
 Ambulatory Polysomnography (Psg) Systems Market | 2026-2036
Ambulatory Polysomnography (Psg) Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Ambulatory Polysomnography (Psg) Systems Market Outlook
Market Context with Strategic Players
Homecare settings is hardening as the dominant demand vertical for ambulatory PSG systems, displacing traditional hospital-based sleep studies. ResMed Inc. leverages its respiratory therapy installed base to cross-sell home diagnostic platforms. Nihon Kohden Corporation anchors its position through specialized neurology channel relationships in Asia-Pacific markets. SOMNOmedics GmbH differentiates via compact, European-manufactured device portfolios optimized for decentralized care workflows.
Technical Definition and Structural Segments
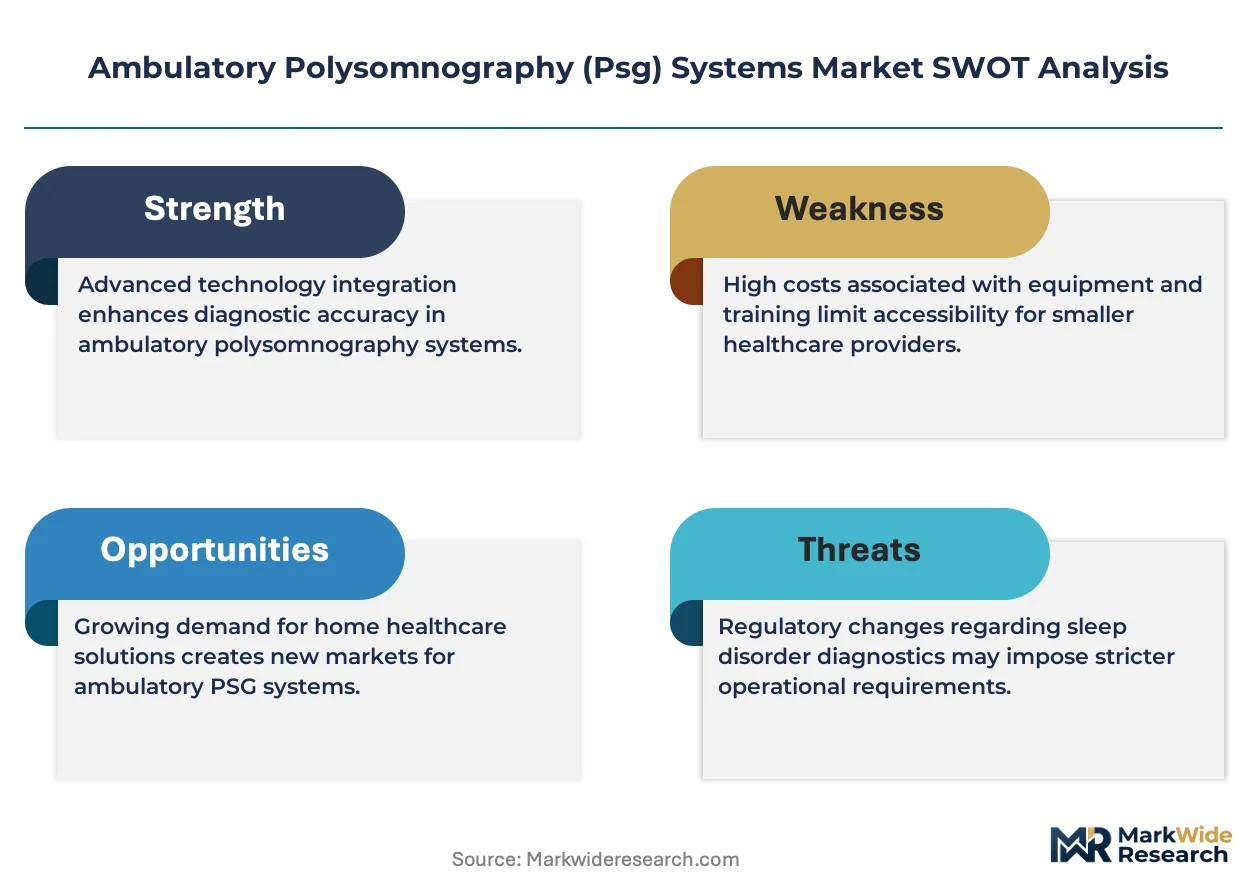
Ambulatory polysomnography systems comprise portable multi-channel physiological recorders capturing electroencephalography, electrooculography, electromyography, respiratory effort, airflow, and oxygen saturation data during natural sleep environments outside clinical facilities. These systems enable diagnosis of sleep-disordered breathing, narcolepsy, and periodic limb movement disorders while eliminating facility-based observation costs. Portable PSG devices command the largest revenue pool due to clinical-grade signal fidelity, though wearable sleep monitors represent the fastest-expanding category as consumer-grade sensors approach medical accuracy thresholds. Home sleep testing devices occupy a mature, reimbursement-dependent segment where margin compression from commoditized airflow-oximetry configurations pressures manufacturers toward cloud-based platform differentiation.
Regulatory Frame and Forward-Looking Close
The FDA governs 510(k) clearance pathways for ambulatory PSG hardware and software-as-medical-device platforms, while the EU MDR imposes strengthened clinical evidence requirements on wearable diagnostic claims in European markets. HIPAA compliance obligations shape cloud-based data architecture investments, as sleep study recordings constitute protected health information requiring encrypted transmission and storage protocols. Stakeholders must monitor evolving FDA guidance on artificial intelligence-enabled sleep staging algorithms, as regulatory positioning around automated scoring will determine competitive access to integrated diagnostic workflows.
Market Dynamics
The migration of sleep diagnostics from hospital sleep centers to decentralized home environments is compressing traditional facility-based revenue models while expanding addressable patient populations through lower-cost access points.
Growth Catalysts
- Homecare reimbursement frameworks:Medicare and private payers in the United States have expanded coverage for unattended home sleep testing, eliminating prior authorization barriers that previously channeled patients toward in-lab studies.
- Wearable sensor miniaturization:Advances in dry electrode technology and MEMS accelerometers enable clinical-grade signal acquisition without technician application, reducing per-test labor costs.
- Cloud-native diagnostic platforms:HIPAA-compliant data pipelines allow sleep medicine practices to scale interpretation capacity across state lines without physical infrastructure expansion.
Market Restraints
- Semiconductor supply concentration:Discrete analog front-end chips for biopotential amplification rely on concentrated fabrication capacity in Taiwan, creating vulnerability to geopolitical disruption.
- EU MDR clinical evidence requirements:Strengthened post-market surveillance obligations for Class IIa wearable diagnostics extend certification timelines and inflate regulatory consulting expenditure.
- Consumer-grade substitution:Apple Watch and Oura Ring photoplethysmography algorithms are capturing pre-diagnostic screening demand, compressing entry-level medical device pricing.
Strategic Opportunities
- Pediatric sleep diagnostics:Underpenetrated assessment of childhood obstructive sleep apnea presents white space as school-based screening programs expand in Australia and Canada.
- Artificial intelligence-enabled scoring:FDA breakthrough device designation pathways for automated sleep staging algorithms offer first-mover positioning in integrated diagnostic workflows.
- Direct-to-employer channels:Self-insured corporations in Germany and the United Kingdom are contracting directly with diagnostic platform vendors to reduce downstream cardiovascular disease costs.
Industry Challenges
- Electroencephalography technologist scarcity:Registered polysomnographic technologist certification programs produce insufficient graduates to support hybrid home-lab service models.
- Legacy health record integration:Ambulatory PSG data formats lack standardized interoperability with Epic and Cerner deployments, forcing costly custom interface development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ambulatory Polysomnography (Psg) Systems Market |
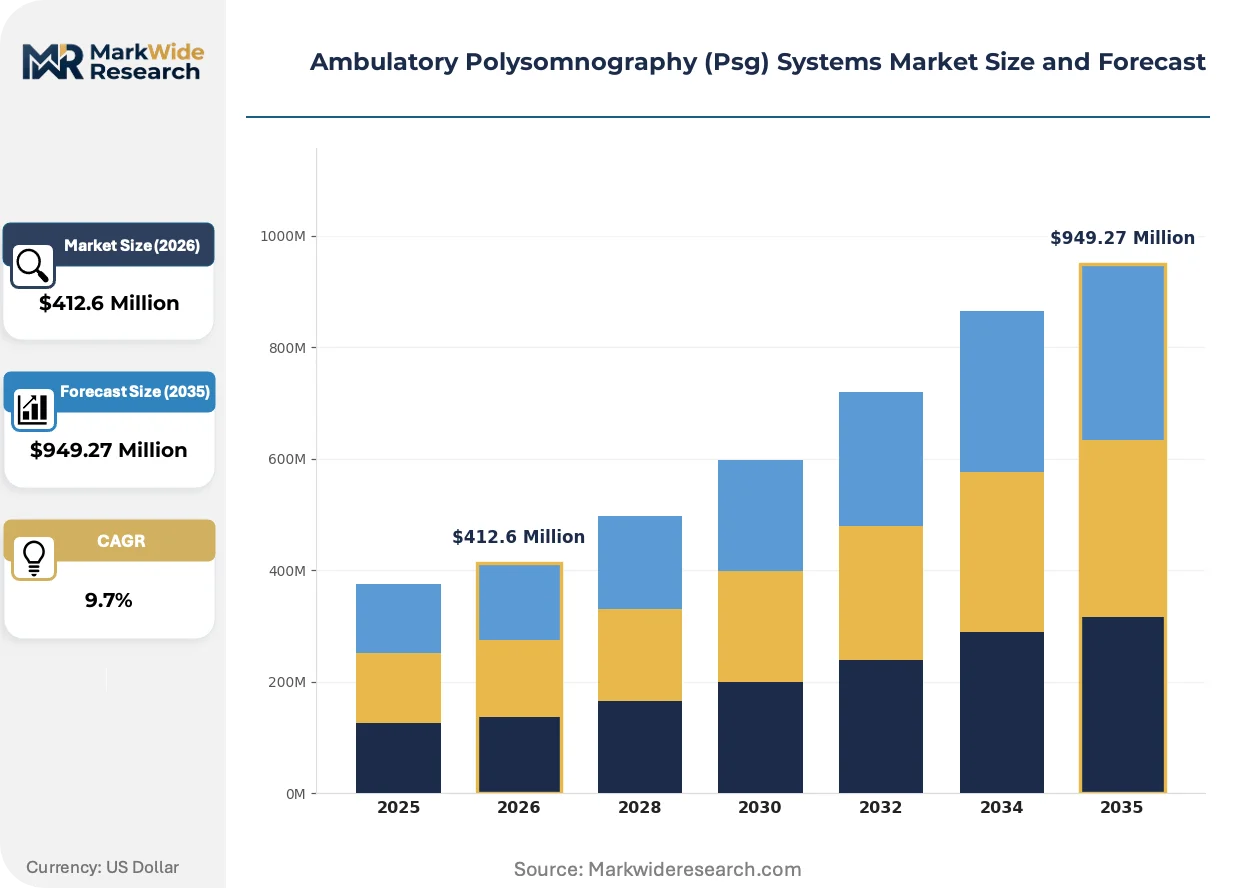
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $949.27 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable PSG Devices, Home Sleep Testing Devices, Wearable Sleep Monitors, Mobile Sleep Applications End User: Homecare Settings, Hospitals, Sleep Clinics, Research Institutions Technology: Wi-Fi Enabled Systems, Bluetooth Connected Devices, Cloud-Based Platforms, Traditional Monitoring Devices Application: Sleep Apnea Diagnosis, Sleep Quality Assessment, Polysomnographic Studies, Research and Development |
| Companies Covered | Koninklijke Philips N.V., Natus Medical Incorporated, ResMed Inc., Nihon Kohden Corporation, Compumedics Limited, SOMNOmedics GmbH, Cadwell Industries Inc., Nox Medical, Neurosoft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ambulatory Polysomnography (Psg) Systems Market Strategic Shifts
Signal processing architectures and regulatory frameworks for software-as-medical-device platforms are converging to enable autonomous diagnostic workflows that reduce specialist interpretation burden.
Dry capacitive electrode arrays are absorbing the function of traditional gel-based gold cup electrodes for electroencephalography acquisition. Sleep medicine practices in the United States and Germany are adopting these configurations for unsupervised home deployments. The technology is absorbing technician labor costs while introducing motion artifact trade-offs that algorithmic filtering must address.
The FDA's evolving guidance on predetermined change control plans for machine learning-enabled devices is reshaping product development roadmaps. Manufacturers must now prospectively define algorithm modification boundaries to maintain 510(k) clearance validity. Wearable sleep monitor developers with cloud-update architectures face the steepest compliance adaptation requirements.
Hospital systems are consolidating sleep medicine referrals through captive home diagnostic platforms rather than dispersing across independent sleep centers. This channel concentration in the United States is displacing traditional durable medical equipment supplier relationships. Integrated delivery networks in California and Texas now require direct platform contracting for employed physician groups.
Ambulatory Polysomnography (Psg) Systems Market Segmentation
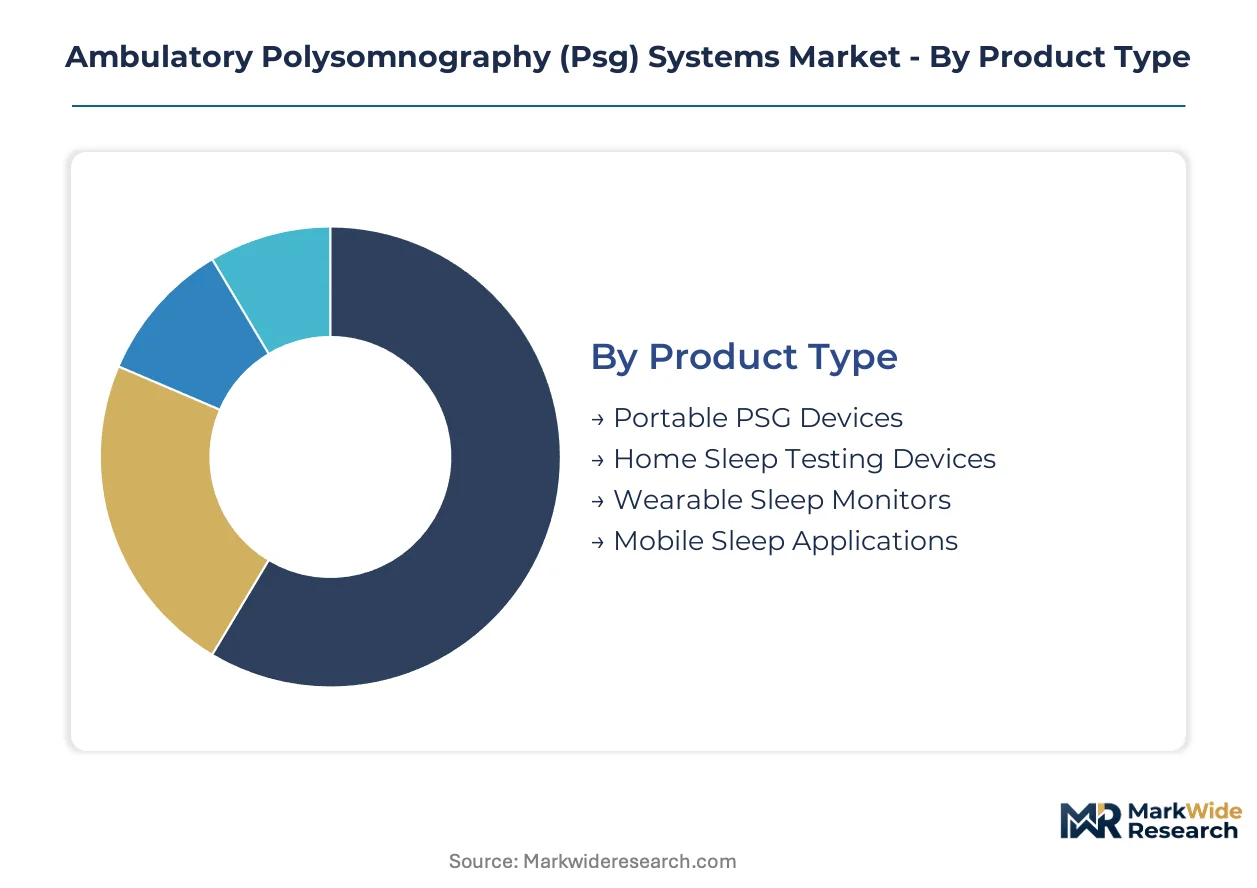
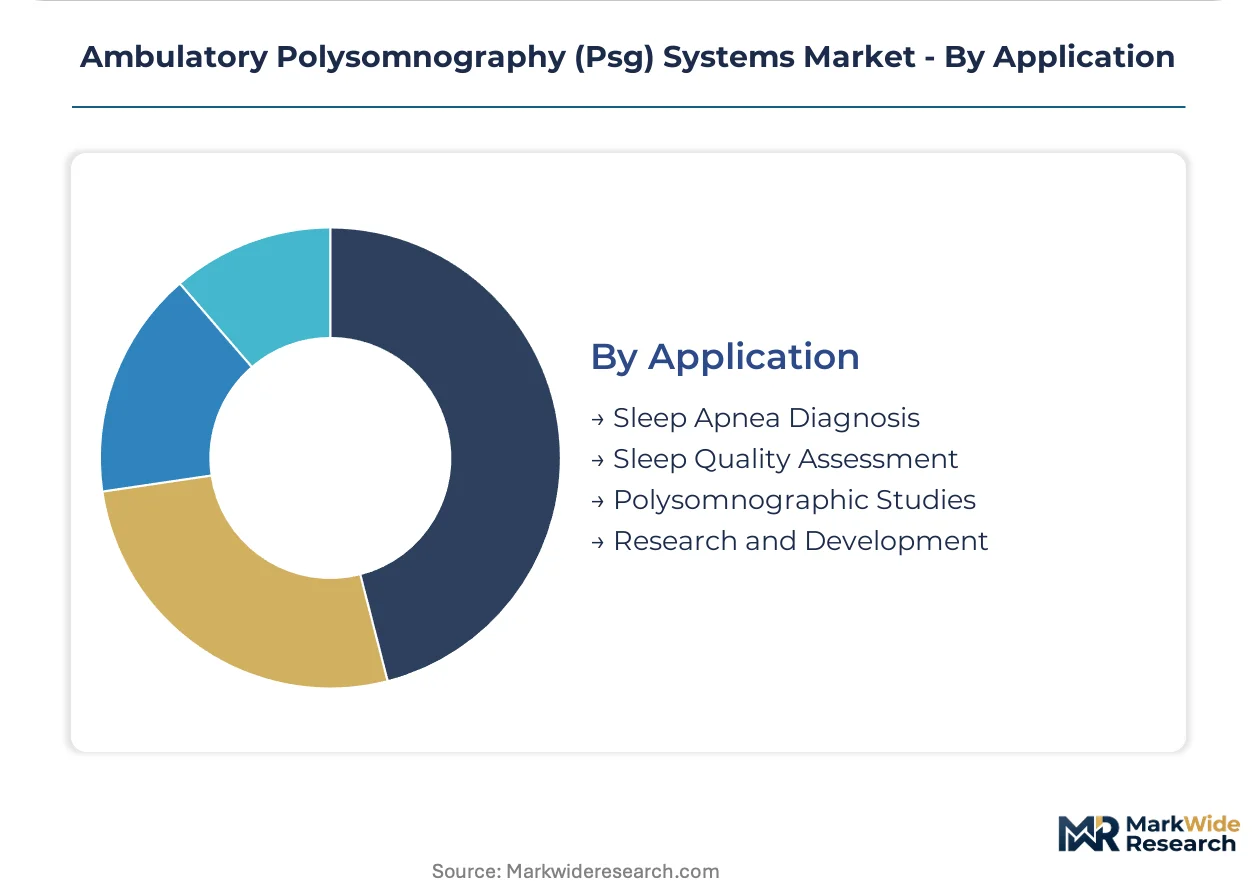
Ambulatory PSG systems fragment across four structural dimensions that shape procurement patterns and margin architecture. Product type determines reimbursement eligibility and signal fidelity requirements. End-user concentration dictates service model complexity and regulatory exposure.
Product Type:
Buyers prioritize signal fidelity against total cost of ownership when selecting device categories.
- Portable PSG Devices:Multi-channel physiological recorders capturing EEG, EOG, EMG, respiratory effort, and oximetry with clinical-grade precision. Demand concentrates in United States sleep medicine practices seeking Medicare-compliant home testing alternatives to in-lab polysomnography. Reimbursement codes for unattended studies drive volume.
- Wearable Sleep Monitors:Wrist-worn or headband-integrated sensors utilizing photoplethysmography and accelerometry for sleep staging. Adoption accelerates in Germany and United Kingdom direct-to-employer wellness programs seeking cardiovascular risk stratification. Sensor miniaturization approaches medical accuracy thresholds.
- Home Sleep Testing Devices:Simplified airflow-oximetry configurations for obstructive sleep apnea screening. United States homecare suppliers dominate procurement through capitated contracts with integrated delivery networks.
- Mobile Sleep Applications:Smartphone-based sleep tracking using accelerometer and microphone inputs. Consumer wellness segment in South Korea and Japan absorbs volume despite limited diagnostic validity.
Portable PSG devices lead on scale; wearable sleep monitors lead on momentum.
End User:
Service delivery location determines regulatory burden and labor cost structure.
- Homecare Settings:Patient-administered testing environments eliminating facility overhead. United States Medicare reimbursement expansion and private payer prior authorization elimination channel volume here. Cloud-based interpretation platforms enable cross-state scaling without physical infrastructure.
- Sleep Clinics:Specialized diagnostic centers combining home testing with specialist consultation. Germany's statutory health insurance system reimburses hybrid models at premium rates. Technologist scarcity constrains throughput expansion.
- Hospitals:Inpatient and outpatient sleep laboratories within acute care systems. United States integrated delivery networks in California and Texas consolidate referrals through captive platforms.
- Research Institutions:Academic medical centers and pharmaceutical trials requiring raw signal access. NIH-funded sleep research programs in Massachusetts and Maryland specify open-format data export.
Homecare settings capture volume expansion; sleep clinics retain margin premiums.
Technology:
Connectivity architecture shapes data security investment and update velocity.
- Cloud-Based Platforms:HIPAA-compliant data pipelines enabling centralized scoring and longitudinal analytics. United States multi-site sleep practices adopt these to offset registered polysomnographic technologist shortages.
- Wi-Fi Enabled Systems:Real-time data transmission for attended home studies. Germany's Federal Office for Information Security (BSI) cybersecurity requirements shape vendor certification.
- Bluetooth Connected Devices:Local wireless pairing to patient smartphones for store-and-forward workflows. Lower power consumption suits multi-night studies in Japan's aging population.
- Traditional Monitoring Devices:Offline recording with physical data retrieval. Mature installed base in France's hospital sleep laboratories resists migration.
Cloud-based platforms gain share fastest; traditional monitoring devices defend legacy installed base.
Application:
Clinical indication determines sensor configuration and reimbursement pathway.
- Sleep Apnea Diagnosis:Airflow, respiratory effort, and oxygen saturation monitoring for obstructive and central events. United States Medicare home sleep testing coverage expansion drives procedural volume.
- Sleep Quality Assessment:Comprehensive sleep architecture analysis including REM latency and sleep efficiency. Wellness programs in United Kingdom financial services sector contract directly for population screening.
- Polysomnographic Studies:Full multi-channel recording for narcolepsy, periodic limb movement disorder, and parasomnia evaluation. Academic medical centers in Canada maintain demand for complex case characterization.
- Research and Development:Customizable channel configurations and raw data export for pharmaceutical trials. CROs in Switzerland specify these for central nervous system drug development.
Sleep apnea diagnosis anchors revenue; sleep quality assessment climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage between FDA clearance timelines and EU MDR clinical evidence requirements is redirecting product development investment toward jurisdictions with faster market access. Manufacturers calibrate launch sequencing to exploit reimbursement expansion in homecare-heavy markets while navigating semiconductor supply vulnerabilities concentrated in East Asian fabrication.
United States
Medicare's elimination of prior authorization barriers for unattended home sleep testing has accelerated ambulatory PSG deployment across integrated delivery networks. The FDA's 510(k) pathway for wearable diagnostic devices enables faster commercialization than European alternatives. Sleep medicine practices in California and Texas consolidate referrals through captive cloud-based platforms, displacing traditional durable medical equipment supplier relationships.
Germany
Statutory health insurance reimbursement for hybrid home-clinic sleep diagnostic models sustains premium pricing for multi-channel portable systems. The Federal Office for Information Security enforces stringent cybersecurity certification for Wi-Fi enabled medical devices, shaping vendor selection criteria. Medical technology clusters in Baden-Württemberg and Bavaria host specialized neurology channel relationships that anchor European market penetration for compact device portfolios.
Japan
Aging demographics and multi-night study protocols favor Bluetooth-connected devices with lower power consumption for longitudinal sleep monitoring. The Ministry of Economy, Trade and Industry promotes digital health adoption through regulatory sandbox programs for AI-enabled diagnostic algorithms. Tokyo-based sleep research institutions drive demand for raw signal export capabilities in pharmaceutical trial applications.
United Kingdom
Direct-to-employer contracting by self-insured financial services corporations creates alternative procurement channels bypassing traditional NHS referral pathways. The Medicines and Healthcare products Regulatory Agency aligns post-Brexit device regulation with FDA convergence trends to accelerate market entry. London and Southeast England wellness program administrators specify cardiovascular risk stratification through wearable sleep monitors for population-level screening.
Australia
School-based childhood obstructive sleep apnea screening programs in New South Wales and Victoria generate underpenetrated demand for pediatric-configured ambulatory systems. The Therapeutic Goods Administration maintains streamlined approval pathways for devices with prior FDA or European CE marking. Academic medical centers in Melbourne and Sydney specify open-format data export for NIH-aligned sleep research collaborations.
Ambulatory Polysomnography (Psg) Systems Market Competitive Environment
Strategic partnerships between diagnostic platform vendors and cloud infrastructure providers dominate the current landscape as manufacturers race to offset registered polysomnographic technologist scarcity. The vendor base concentrates around three tiers: diversified medical device conglomerates with respiratory therapy installed bases, specialized neurology-focused equipment manufacturers with regional channel depth, and compact-device specialists optimized for decentralized care workflows. Competitive positioning hinges on FDA breakthrough device designation pursuit for AI-enabled scoring algorithms and direct contracting with integrated delivery networks to bypass traditional supplier intermediaries.
Within the diversified conglomerate tier, Koninklijke Philips N.V. and ResMed Inc. exemplify scale-driven platform strategies leveraging cross-category respiratory therapy relationships to anchor home diagnostic market share. Among specialized manufacturers, Nihon Kohden Corporation occupies a position reflecting deep Asia-Pacific neurology channel penetration, while SOMNOmedics GmbH represents the compact-device archetype with European manufacturing credentials optimized for decentralized deployment. Natus Medical Incorporated and Compumedics Limited sit within the research-institution-focused segment where raw signal fidelity and customizable channel configurations determine procurement decisions.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| Natus Medical Incorporated |
| ResMed Inc. |
| Nihon Kohden Corporation |
| Compumedics Limited |
| SOMNOmedics GmbH |
| Cadwell Industries Inc. |
| Nox Medical |
| Neurosoft |
| Others |
Value Chain & Pricing Dynamics
Integrated delivery networks in the United States operate on direct-to-manufacturer contracting models that compress traditional distributor markups while elevating cloud-platform subscription pricing for multi-site sleep practices.
Pricing Analysis
Distributor margin layers have thinned as hospital systems consolidate procurement through captive platforms, shifting revenue toward SaaS-tiered scoring subscriptions. Price differentiation hinges on FDA 510(k) clearance tier and cloud-interpretation bundling. Cost compression in entry-level home sleep testing devices intensifies as consumer-grade wearables encroach diagnostic screening. Research institutions demonstrate lowest price sensitivity due to raw signal fidelity requirements.
Supply Chain Analysis
Regional distribution centers in Germany and the United States maintain hub-and-spoke patterns for portable PSG device fulfillment, with final assembly drawing from Taiwan-sourced analog front-end chips and Japanese MEMS accelerometers. Discrete semiconductor fabrication concentrates in East Asian foundries, creating single-source vulnerability for biopotential amplification components. Distribution runs through specialized neurology equipment distributors in European markets and direct-platform contracting in North American integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Medicare's elimination of prior authorization barriers for unattended home sleep testing compounds regulatory tailwinds into sustained demand expansion for ambulatory diagnostic platforms.
For Market Incumbents: Cement platform stickiness through AI-enabled scoring algorithm FDA breakthrough device pursuit, insulating against consumer-grade wearable substitution. Deepen backward integration into dry electrode manufacturing to offset semiconductor supply concentration. Lock integrated delivery networks into exclusive cloud-interpretation contracts. For New Entrants and Emerging Players: Cloud infrastructure providers represent the most viable channel partnership path for rapid scale. Pediatric sleep diagnostics in Australia and Canada offer penetrable white space with school-based screening program expansion. Target direct-to-employer wellness contracts in United Kingdom financial services as bypass to saturated reimbursement channels. For Investors and Strategic Acquirers: Respiratory therapy conglomerates are the most active acquirer in this space, seeking home diagnostic platform adjacencies. Five-to-ten year viability rests on automated sleep staging algorithm differentiation rather than hardware commoditization. Watch FDA guidance evolution on predetermined change control plans for machine learning-enabled devices as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Automated sleep staging algorithms gain competitive access to integrated diagnostic workflows ahead of 510(k) clearance timelines. |
| Cloud-Native Platform Integration | HIPAA-compliant data pipelines enable sleep practices to scale interpretation capacity across state lines without physical infrastructure. |
| Direct-to-Employer Contracting | Self-insured corporations in Germany and United Kingdom reduce downstream cardiovascular costs through population sleep screening. |
| Pediatric Configuration Development | School-based childhood obstructive sleep apnea screening in Australia generates underpenetrated demand for specialized ambulatory systems. |
| Dry Electrode Manufacturing Integration | In-house production of capacitive electrode arrays absorbs technician labor costs while reducing gel-based consumable dependency. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with sleep medicine physicians, biomedical engineers, GPO contracts managers, and cloud platform technical leads with secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EU MDR clinical evidence repositories. Bottom-up device shipment modeling and top-down healthcare expenditure triangulation anchored value estimates.
Segment-weighting across product type, end user, technology, and application dimensions shaped the analytical framework across the projection horizon. Portable PSG, wearable sleep monitor, home sleep testing, and mobile application categories were modeled against homecare, sleep clinic, hospital, and research institution demand. CAGRs derived from installed base expansion rates and reimbursement policy trajectory, with semiconductor supply constraints and AI regulatory evolution as specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA guidance evolution on machine learning-enabled devices and EU MDR post-market surveillance enforcement. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Portable Ultrasound Equipment Market
Medical Devices
Next Generation Infusion Pump Market
Medical Devices
Europe Surgical Microscopes Market
Medical Devices
Reusable Medical Battery Market
Medical Devices
High Tibial Osteotomy (HTO) Plates Market
Medical Devices
ePTFE Vascular Prosthesis Market
Medical Devices
US Nebulizer Market
Medical Devices
Cardiac Catheters and Guidewires Market
Medical Devices
Medical Devices Reimbursement Market
Medical Devices
Asia-Pacific Interventional Cardiology and Peripheral Vascular Devices Market
Medical Devices
Global Mechanical Ventilators Market
Medical Devices
Joint Reconstruction Devices Market
Medical Devices
Sphincterotomes Market
Medical Devices
Heart Failure POC and LOC Devices Market
Medical Devices
Soft Tissue Market
Medical Devices
Spinal Trauma Devices Market