
 Die Attach Equipment Market | 2026-2036
Die Attach Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Die Attach Equipment Market Analysis
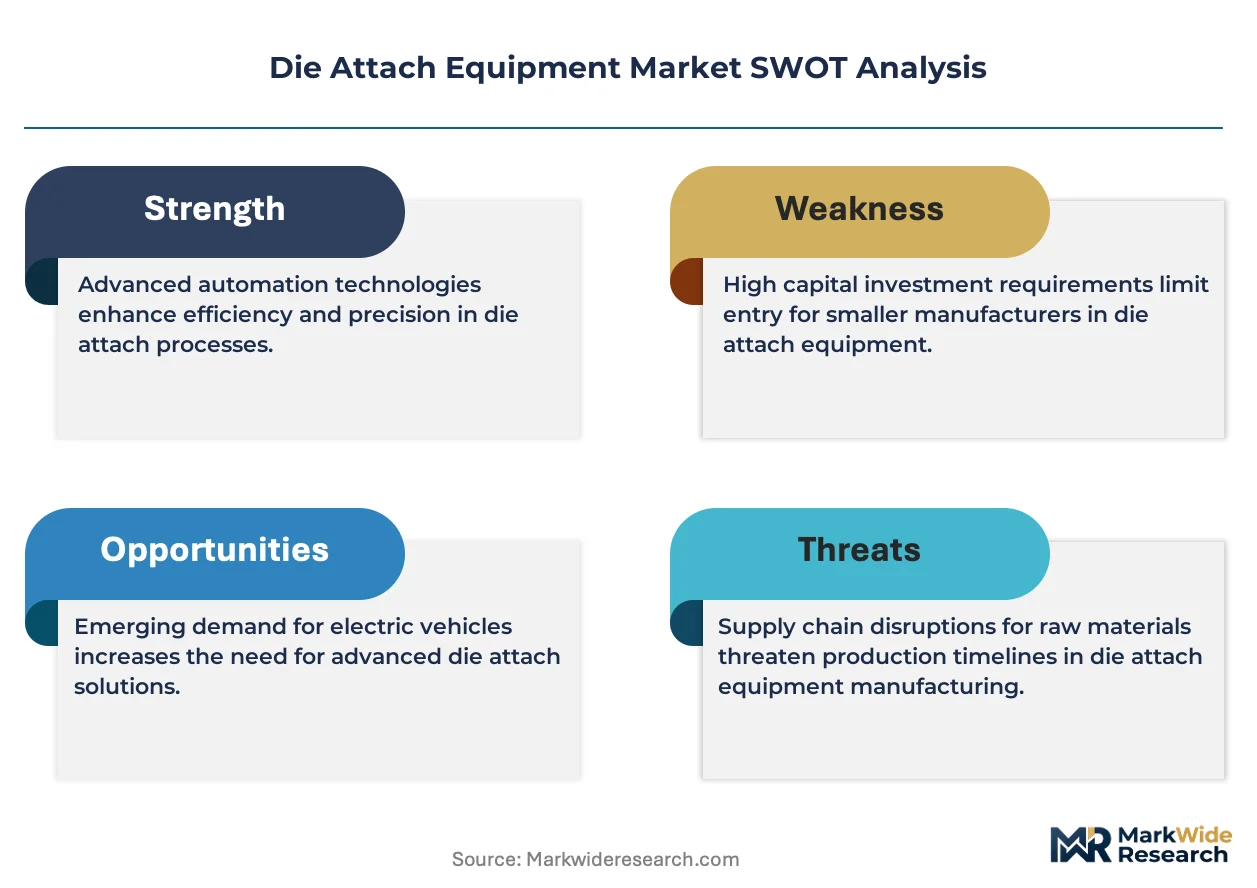
Packaging engineer shortages across advanced semiconductor hubs is reorganizing how equipment vendors allocate technical support resources. ASM Pacific Technology Limited leverages its Greater China service density to sustain installation throughput. Kulicke & Soffa Industries anchors North American automotive electronics programs through localized application engineering. BE Semiconductor Industries N.V. competes on flip-chip throughput metrics that differentiate its high-volume bonder portfolio.
Die attach equipment comprises precision bonding systems that join semiconductor dies to substrates using force, heat, and specialized adhesives, with placement accuracy typically below ten microns. These systems enable electrical interconnect and thermal management in packaged integrated circuits for consumer, automotive, and industrial end products. Automatic attach equipment commands the largest installed base due to throughput requirements in memory and logic packaging, while flip chip attach represents the fastest-growing technology segment driven by 2.5D and 3D integration roadmaps. Thermal compression bonding carries premium margin pools as advanced node adoption requires sub-five-micron placement precision with simultaneous heat and pressure control.
China's MIIT enforces GB standards on equipment energy efficiency that filter procurement specifications for domestic packaging houses. The EU F-Gas Regulation and REACH compliance requirements restrict adhesive chemistries and refrigerant-based cooling systems in European-bound equipment lines. Semiconductor manufacturers must reconcile these divergent regulatory frameworks when standardizing global factory footprints. Stakeholders should monitor how impending EU AI Act supply chain disclosure rules extend traceability requirements into capital equipment purchasing decisions.
Market Dynamics
Semiconductor packaging roadmaps are compressing die attach cycle times while simultaneously demanding sub-micron placement precision, forcing equipment vendors to reconcile throughput and accuracy in single-platform architectures.
Growth Catalysts
- Automotive electronics qualification:Tier-1 suppliers in Germany and Japan are mandating AEC-Q100-compliant attach systems for power module production, pulling high-force bonders into EV inverter lines.
- EU F-Gas Regulation phase-down:The refrigerant cooling ban is accelerating equipment retrofits across European packaging houses, creating replacement demand for thermal management-integrated bonders.
- Hybrid bonding integration:3D NAND and logic stacking roadmaps are embedding die attach equipment into hybrid bonding process flows, extending tool utilization into backside processing.
Market Restraints
- Gold wire cost volatility:Precious metal price swings compress margin predictability for ball-attach equipment operators serving memory packaging.
- East Asian supply concentration:Precision motion control components and high-vacuum subsystems concentrate among Taiwanese and Japanese component suppliers, exposing lead time vulnerability.
- REACH adhesive restrictions:ECHA substance candidate list expansions are disqualifying legacy conductive epoxies from European-bound equipment configurations.
Strategic Opportunities
- India PLI scheme for semiconductors:The Ministry of Electronics and Information Technology incentive structure is attracting OSAT greenfield investments, creating attach equipment installation pipelines.
- Photonics packaging emergence:Silicon photonics transceiver assembly is adopting flip-chip attach for optical engine integration, opening non-traditional end-use demand.
- AI Act supply chain disclosure:The EU's impending traceability mandates will favor equipment vendors with embedded process data logging and blockchain-ready quality systems.
Industry Challenges
- Packaging engineer scarcity:Advanced packaging hubs in Taiwan and South Korea face acute shortages of process integration specialists capable of debugging multi-parameter attach recipes.
- Legacy tool interoperability:Factory automation upgrades require die attach equipment to communicate with 20-year-old MES architectures through custom protocol bridges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Die Attach Equipment Market |
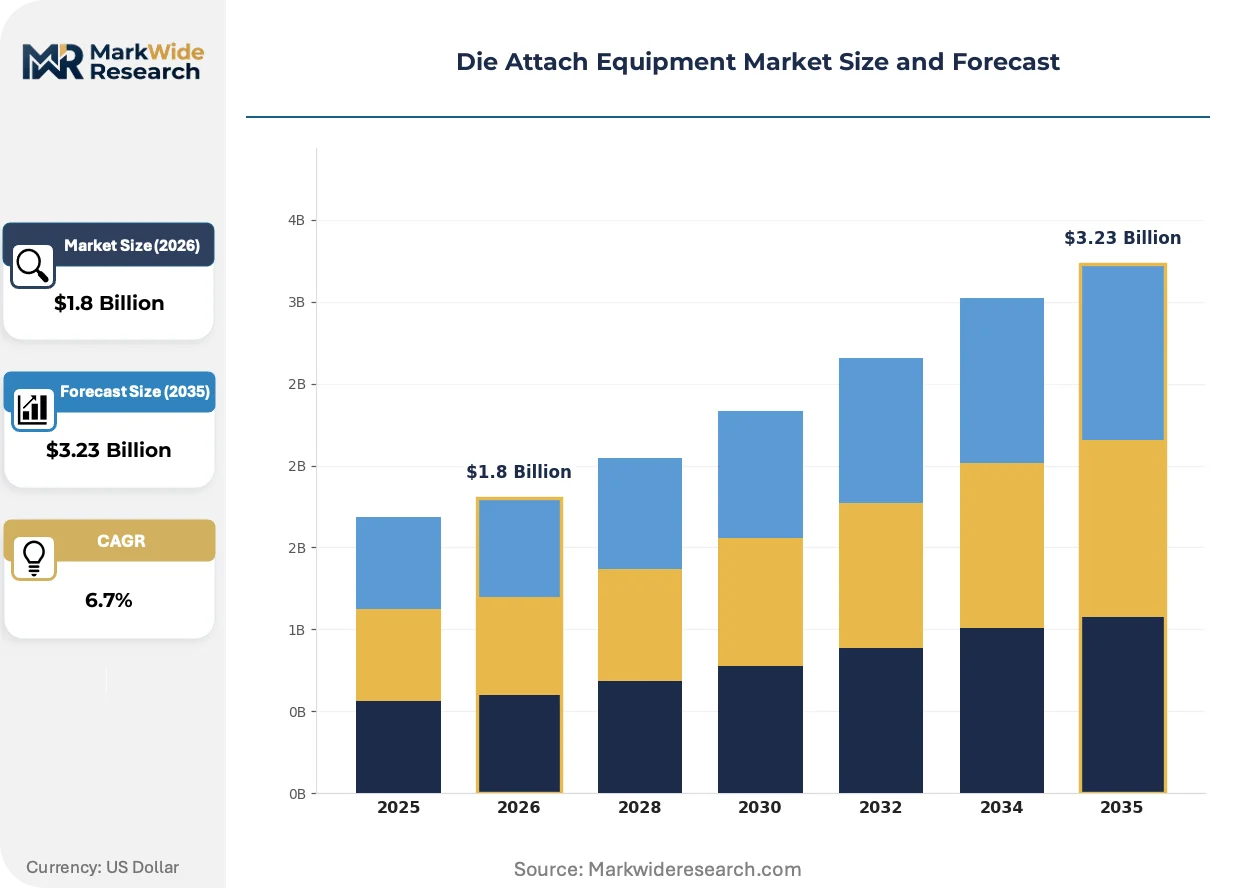
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Attach, Automatic Attach, Semi-Automatic Attach, Flip Chip Attach Technology: Thermal Compression, Ultrasonic, Adhesive Bonding, Laser End User: Semiconductor Manufacturers, Electronics Assemblers, Research Laboratories, Automotive Suppliers Application: Consumer Electronics, Automotive Electronics, Industrial Equipment, Medical Devices |
| Companies Covered | ASM Pacific Technology Limited, BE Semiconductor Industries N.V., Kulicke & Soffa Industries, Palomar Technologies, Shinkawa Ltd., MicroAssembly Technologies, Ltd., Fasford Technology Co. Ltd., Dr. Tresky AG, Inseto UK Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Die Attach Equipment Market Emerging Trajectories
Thermal compression bonding architectures are fragmenting into modular subsystems, enabling packaging houses to upgrade placement precision without full platform replacement. Equipment vendors are embedding machine vision and real-time force feedback into standard configurations.
Thermal compression bonding is decomposing the traditional separation between die attach and reflow processes in advanced packaging flows. Memory manufacturers in South Korea are adopting integrated heat-pressure units for HBM stack assembly. This convergence is compressing cleanroom footprint requirements while elevating capital intensity per square meter.
China's MIIT GB standards on equipment energy efficiency are filtering into domestic procurement specifications, compelling foreign vendors to redesign power electronics and thermal subsystems. Packaging houses in Suzhou and Wuxi now require compliance documentation for grid-connected equipment. European and Japanese suppliers are responding with localized engineering centers to accelerate certification timelines.
After-sales service contracts are unbundling from equipment purchases as OSATs seek hourly-rate technical support rather than bundled maintenance packages. This shift is visible most acutely among Taiwanese packaging houses managing multi-vendor install bases. Equipment vendors are restructuring field engineering organizations into standalone profit centers with dedicated P&L accountability.
Die Attach Equipment Market Segmentation
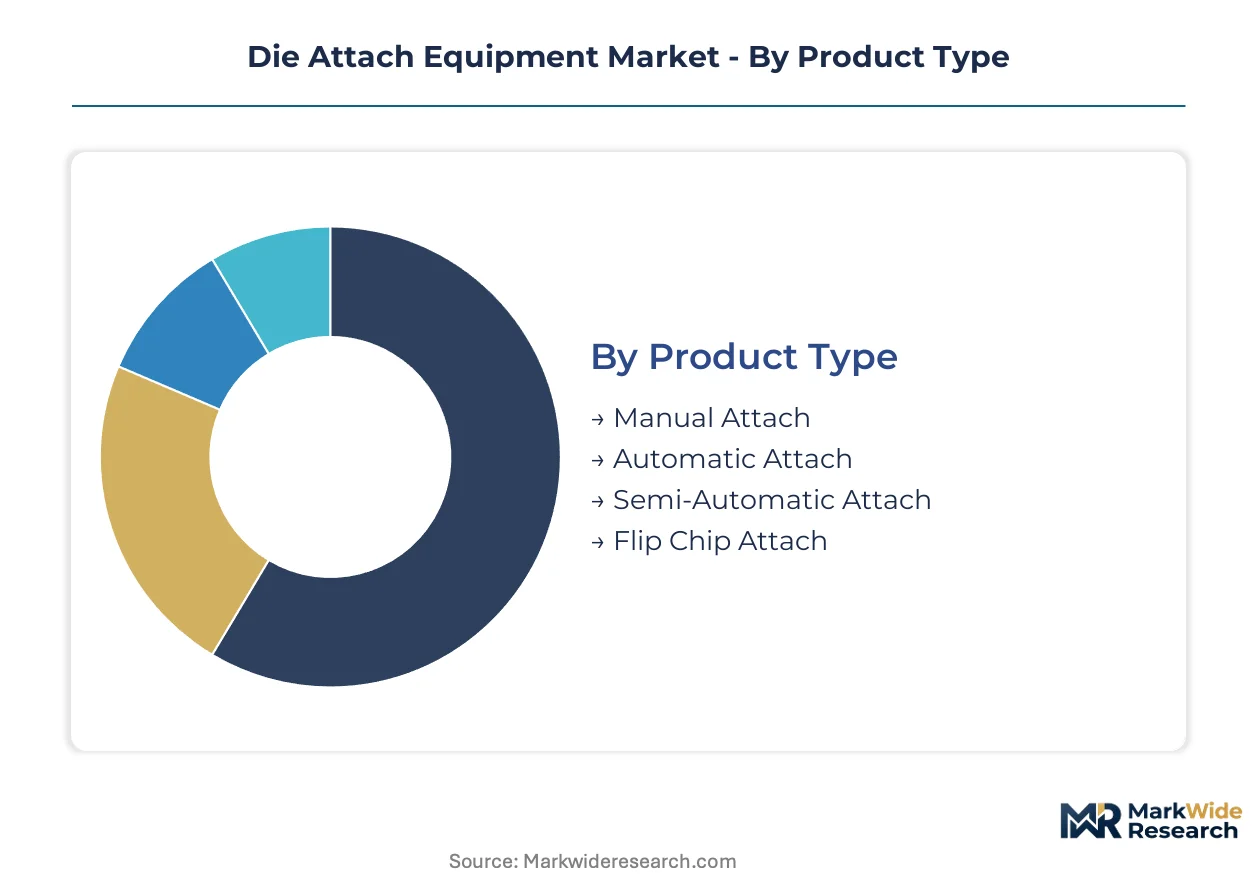
Die attach equipment segmentation reveals how packaging houses balance throughput requirements against placement precision mandates. Equipment vendors configure product portfolios around these trade-offs, with technology choices increasingly dictated by 2.5D and 3D integration roadmaps rather than legacy packaging formats.
Product Type:
Automatic attach systems face substitution pressure from semi-automatic units in low-volume automotive qualification lines, while flip chip architectures displace wire bond equipment in memory stacking applications.
- Automatic Attach:High-throughput systems deploy multi-head gantries and vision-guided placement for memory and logic packaging at sub-ten-micron accuracy. Demand concentrates in Taiwanese OSATs serving Apple and NVIDIA supply chains, driven by HBM2E and HBM3 stack assembly requirements.
- Flip Chip Attach:These systems enable solder bump or copper pillar interconnect for advanced node processors and baseband chips. South Korean memory manufacturers anchor procurement volumes for 3D NAND string stacking, with thermal compression variants gaining traction in logic-to-logic bonding.
- Manual Attach:Benchtop units serve research prototyping and legacy discrete component assembly with operator-controlled force and temperature parameters. Aerospace and defense contractors in the US maintain limited install bases for radiation-hardened device qualification.
- Semi-Automatic Attach:Hybrid systems combine automated die presentation with operator-initiated bonding cycles. European automotive Tier-1s favor these configurations for power module pilot lines where recipe flexibility outweighs throughput targets.
Automatic attach anchors the volume base while flip chip attach gains share at the steepest rate.
Technology:
Cost tier differentiation separates thermal compression platforms from adhesive bonding systems, with ultrasonic and laser technologies occupying intermediate price-performance positions.
- Thermal Compression:Simultaneous heat and force application achieves sub-five-micron placement for hybrid bonding and advanced fan-out packaging. South Korean HBM manufacturers drive capacity expansion, though tool cost and footprint requirements restrict adoption beyond leading-edge memory houses.
- Adhesive Bonding:Conductive epoxies and non-conductive pastes enable die attach without solder reflow, preserving thermal budget for temperature-sensitive substrates. Chinese OSATs in Jiangsu province concentrate procurement for image sensor and MEMS packaging where cost sensitivity dominates.
- Ultrasonic:High-frequency mechanical vibration creates metallurgical bonds without bulk heating, suited for copper-to-copper interconnect in power electronics. Japanese automotive suppliers specify these systems for inverter module production.
- Laser:Selective heating enables localized bond formation with minimal thermal diffusion into adjacent components. German industrial equipment manufacturers pilot these systems for photonics packaging where adhesive outgassing risks contaminate optical paths.
Adhesive bonding commands the broadest install base while thermal compression climbs the fastest.
End User:
Customer type segmentation tracks how procurement authority shifts from integrated device manufacturers to outsourced assembly houses as packaging strategies fragment.
- Semiconductor Manufacturers:IDMs and foundries with captive packaging operations specify equipment for internal roadmaps, prioritizing recipe confidentiality and cycle time optimization. Intel and TSMC anchor North American and Taiwanese procurement respectively.
- Electronics Assemblers:OSATs and contract manufacturers configure multi-vendor install bases to service diverse customer portfolios. These buyers unbundle service contracts and demand hourly-rate technical support rather than bundled maintenance.
- Automotive Suppliers:Tier-1 power module producers in Germany and Japan mandate AEC-Q100-compliant systems with documented traceability for EV inverter lines. Bosch and Denso anchor European and Japanese demand.
- Research Laboratories:University and national lab facilities acquire refurbished or entry-level systems for process development and student training. US Department of Energy labs maintain limited attach capability for wide-bandgap device research.
Electronics assemblers anchor the volume base while automotive suppliers expand procurement fastest.
Application:
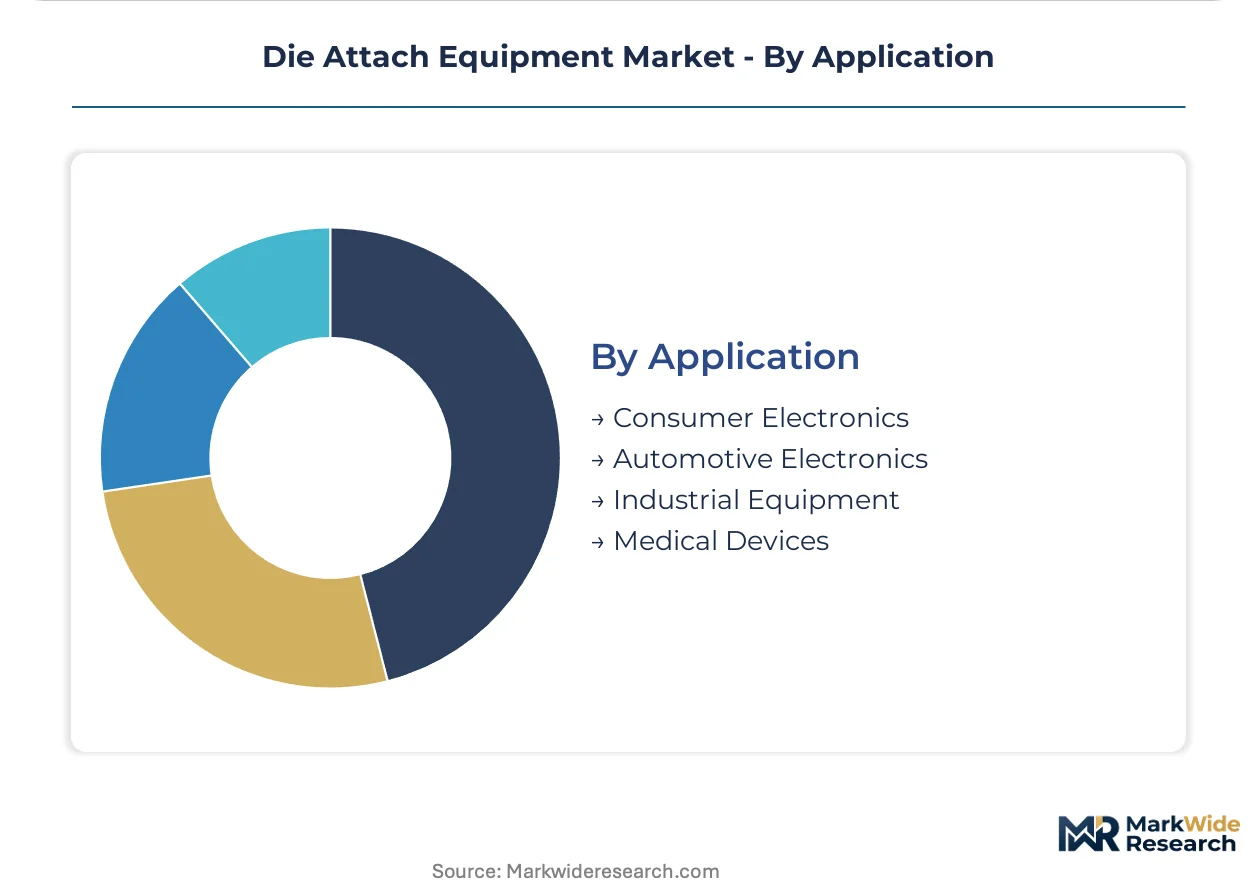
Application segmentation reflects how end-market qualification requirements reshape equipment specifications, with automotive electronics imposing the most stringent reliability standards.
- Consumer Electronics:Smartphone and wearable packaging demands high-throughput flip chip and fan-out configurations. Chinese OSATs in Shenzhen and Dongguan concentrate capacity for Android ecosystem suppliers.
- Automotive Electronics:Power module, radar sensor, and battery management system packaging require high-force bonders with extended temperature cycling validation. German and Japanese Tier-1s drive specification tightening for EV traction inverter applications.
- Industrial Equipment:Motor drives, programmable logic controllers, and power supplies utilize wire bond and adhesive attach with extended service life requirements. European industrial automation vendors anchor demand.
- Medical Devices:Implantable and diagnostic equipment packaging prioritizes biocompatibility and hermetic sealing over throughput. US and Swiss medical device manufacturers specify specialized configurations with extended qualification documentation.
Consumer electronics anchors the volume base while automotive electronics gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT dual carbon goals and GB energy efficiency standards are reshaping procurement specifications for die attach equipment across East Asian packaging hubs. Taiwan and South Korea anchor advanced memory and logic packaging demand, while Germany and Japan drive automotive electronics qualification requirements.
Taiwan
TSMC and ASE Group anchor captive and OSAT packaging capacity for Apple and NVIDIA supply chains. The National Development Council semiconductor initiative subsidizes advanced packaging equipment purchases in Hsinchu and Taichung Science Parks. Kaohsiung's emerging packaging cluster concentrates flip-chip attach installations for HBM2E and HBM3 memory stacking.
South Korea
Samsung Electronics and SK Hynix drive thermal compression bonding capacity expansion for 3D NAND string stacking and logic-to-logic bonding. The Ministry of Trade, Industry and Energy K-Semiconductor Belt program funds equipment localization in Pyeongtaek and Icheon. Yongin's packaging corridor concentrates hybrid bonding process flow integration.
China
Jiangsu province OSATs in Suzhou and Wuxi concentrate adhesive bonding procurement for image sensor and MEMS packaging where cost sensitivity dominates. MIIT GB standards on equipment energy efficiency filter into domestic procurement specifications with compliance documentation now required for grid-connected equipment. Foreign vendors maintain localized engineering centers in Shanghai to accelerate certification timelines.
Germany
Bosch and Infineon mandate AEC-Q100-compliant attach systems with documented traceability for EV traction inverter power module production. The EU F-Gas Regulation refrigerant cooling ban accelerates equipment retrofits across European packaging houses. Saxony's semiconductor cluster in Dresden concentrates thermal management-integrated bonder replacement demand.
Japan
Denso and Renesas specify high-force bonders with extended temperature cycling validation for radar sensor and battery management system packaging. METI's semiconductor and digital industry strategy supports equipment investment in Kyushu's silicon island. Hiroshima's automotive electronics corridor anchors power module pilot line configurations.
Die Attach Equipment Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in die attach equipment supply. The upper tier combines precision motion control capabilities with global service networks spanning installation and recipe optimization. Mid-tier specialists compete on flip-chip throughput metrics or regional proximity to packaging clusters. Competitive moves concentrate on M&A for precision component access and strategic partnerships with adhesive chemistry suppliers.
Within the integrated tier, ASM Pacific Technology Limited and BE Semiconductor Industries N.V. exemplify equipment vendors with dense Greater China service networks and high-volume bonder portfolios respectively. Kulicke & Soffa Industries occupies a position among North American-anchored suppliers with localized application engineering for automotive electronics programs. These three entities represent the archetype of vendors restructuring field engineering organizations into standalone profit centers with dedicated P&L accountability.
| Leading Market Players |
|---|
| ASM Pacific Technology Limited |
| BE Semiconductor Industries N.V. |
| Kulicke & Soffa Industries |
| Palomar Technologies |
| Shinkawa Ltd. |
| MicroAssembly Technologies, Ltd. |
| Fasford Technology Co. Ltd. |
| Dr. Tresky AG |
| Inseto UK Ltd. |
| Others |
Supply Flow & Price Mechanics
EU F-Gas Regulation refrigerant cooling restrictions simultaneously gate equipment qualification for European-bound lines and stratify price tiers between thermal management-integrated bonders and legacy cooling architectures. This regulatory overlay compresses margin pools for non-compliant vendors while rewarding certified suppliers with pricing power in German and Japanese automotive electronics programs.
Pricing Analysis
East Asian packaging houses command lower equipment unit costs than European automotive Tier-1s due to volume scale and reduced certification documentation requirements. Pricing stratifies across thermal compression premium tiers, adhesive bonding standard tiers, and manual attach economy tiers, with certification grade and after-sales service bundling as primary differentiation drivers. Cost compression in the standard tier is intensifying because Chinese OSATs in Jiangsu province prioritize capital efficiency over precision specifications. Semiconductor manufacturers remain least price-sensitive given recipe confidentiality requirements, while research laboratories exhibit highest sensitivity with refurbished system preference.
Supply Chain Analysis
Precision motion control subsystems and high-vacuum components carry eighteen-to-twenty-four month order backlogs, constraining equipment vendor delivery commitments. Supply concentrates in Taiwan, Japan, and Germany for linear motors, granite bases, and force sensors, with raw material dependencies spanning rare-earth magnets, high-purity ceramics, and specialized aluminum alloys. Single-source vulnerability from Japanese high-vacuum pump suppliers exposes lead time disruption risk. Distribution runs through direct sales teams for IDM accounts and authorized distributors serving OSAT multi-vendor install bases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat structure where regulatory entrenchment in EU F-Gas and China MIIT certification requirements locks in incumbent positions. Switching costs between attach equipment vendors compound this moat through recipe revalidation timelines.
For Market Incumbents: Consolidate precision component supply through backward integration into high-vacuum subsystem production or captive supply agreements with Taiwanese linear motor specialists. Expand application engineering headcount in Suzhou and Dresden to compress certification timelines for MIIT GB standards and EU F-Gas compliance. Defend against emerging Chinese equipment vendors by embedding blockchain-ready process data logging ahead of EU AI Act traceability mandates.
For New Entrants and Emerging Players: Anchor in Indian OSAT greenfield investments under the Ministry of Electronics and Information Technology PLI scheme, where incumbent service density remains lowest. Target photonics packaging pilot lines in German industrial equipment corridors as the most penetrable application white-space. Pursue hourly-rate technical support contracts rather than bundled maintenance to match Taiwanese buyer preferences.
For Investors and Strategic Acquirers: EU AI Act supply chain disclosure rules reshape the acquisition landscape toward equipment vendors with embedded quality systems and regulatory documentation capabilities. Long-term viability over the next decade hinges on hybrid bonding process flow integration. Prioritize acquisition targets with thermal compression bonding IP and established automotive electronics qualification track records. Watch for MIIT GB standard enforcement acceleration as the signal indicating certification-timeline arbitrage opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vacuum Subsystems | Captive supply of high-vacuum pumps from Japanese specialists reduces lead time exposure for HBM equipment lines. |
| Localized Engineering Center Expansion | Shanghai and Dresden facilities accelerate MIIT GB and EU F-Gas certification timelines for foreign vendors. |
| Blockchain-Ready Quality System Deployment | Embedded process data logging positions vendors for EU AI Act supply chain disclosure compliance. |
| Photonics Packaging Pilot Line Partnership | German industrial equipment manufacturers pilot laser attach systems for silicon photonics transceiver assembly. |
| Hourly-Rate Service Contract Unbundling | Taiwanese OSAT procurement patterns favor standalone technical support over bundled maintenance packages. |
Methodological Framework
A standing panel of packaging process engineers, OSAT procurement directors, automotive Tier-1 supplier quality managers, and equipment vendor field service heads provided ongoing calibration across the study. Primary interviews with these stakeholders combined with secondary validation against SEMI equipment market data, customs import records for precision motion components, and SEC filings from listed semiconductor equipment vendors. Bottom-up equipment shipment tallies triangulated against top-down packaging capacity expansion announcements.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions spanning attach technology type, end-user category, application vertical, and regional regulatory cluster. CAGRs derived from equipment shipment trajectories and packaging capacity buildout pipelines incorporated HBM stack assembly intensity, EV inverter power module qualification requirements, and photonics packaging adoption curves as industry-specific inputs.
Material uncertainties — geopolitical disruption to precision component trade flows, regulatory acceleration in China energy efficiency enforcement, and hybrid bonding technology substitution rates — sit outside the modeled envelope. Forecasts reflect documented assumptions about packaging roadmaps and equipment replacement cycles. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Vacuum Ovens Market
Semiconductor Equipment
Africa Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
Acid Filling and Leveling Machine Market
Semiconductor Equipment
Pulsed Laser Deposition Systems Market
Semiconductor Equipment
Semiconductor Photolithography Equipment Market
Semiconductor Equipment
Electrostatic Chucks Market
Semiconductor Equipment
Global Microelectronics Cleaning Equipment Market
Semiconductor Equipment
Die Bonder Machinery Market
Semiconductor Equipment
Semiconductor Process and Control Equipment Market
Semiconductor Equipment
Semiconductor Capital Equipment Market
Semiconductor Equipment
Single Wafer Wet Cleaning Equipment Market
Semiconductor Equipment
Global Semiconductor Thermal Evaporators Market
Semiconductor Equipment
Focused Ion Beam Market
Semiconductor Equipment
Automatic Flip Chip Bonders Market
Semiconductor Equipment
Semiconductor POD Cleaner Market
Semiconductor Equipment
Global Photoresist Market