
 Solar-Grade Polysilicon Market | 2026-2036
Solar-Grade Polysilicon Market Size, Share, and Industry Trends Forecast 2026-2036
Solar-Grade Polysilicon Market Insights
Chinese polysilicon capacity expansion is realigning global supply geography. Tongwei Co., Ltd leverages its integrated n-type monocrystalline chain to dominate high-efficiency cell feedstock. GCL Technology Holdings Ltd. anchors its position through massive Siemens-process scale in Xuzhou and Baotou. Wacker Chemie AG navigates European energy costs by specializing in ultra-high-purity grades for premium wafer customers.
Solar-grade polysilicon is hyper-pure silicon metal refined to 99.9999999% purity through trichlorosilane deposition, serving as the foundational ingot material for crystalline photovoltaic wafers. The Siemens Process still occupies the bulk of merchant supply, though Fluidized Bed Reactor technology is concentrating investment as producers seek lower electricity intensity per kilogram. Monocrystalline feedstock leads product type value capture, while wafer manufacturing absorbs the dominant share of application-directed volume. The technology mix is displacing older multicrystalline routes as cell efficiency standards tighten across downstream tiers.
China's MIIT enforces GB standards for polysilicon energy consumption per unit, while the EU's CBAM and F-Gas Regulation shape import competitiveness for non-European producers. EPA permitting in the United States and India's BIS quality mandates are fragmenting compliance requirements for multinational suppliers. Stakeholders must track how carbon-border adjustments and domestic content incentives in major demand markets reshape sourcing calculus for new capacity commitments.
Market Dynamics
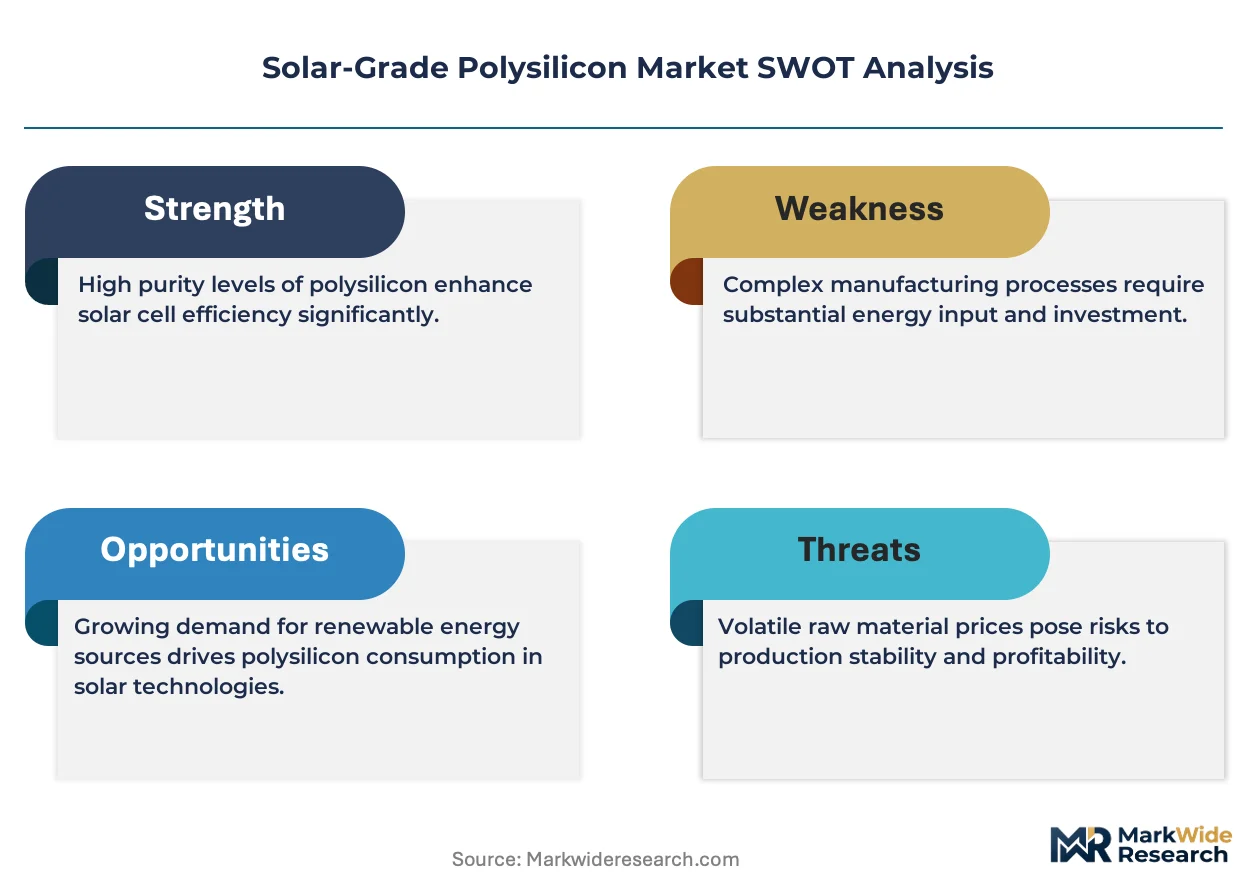
Fluidized Bed Reactor technology is compressing electricity intensity per kilogram, forcing Siemens-process incumbents to defend margin position through scale or purity specialization. This technological bifurcation is redrawing competitive boundaries between merchant suppliers and integrated wafer producers.
Growth Catalysts
- China's dual carbon goals:Beijing's 2030 carbon peak mandate accelerates renewable buildout, concentrating polysilicon demand in Xinjiang and Inner Mongolia where coal-to-solar conversion clusters near captive power.
- EU CBAM phase-in:The Carbon Border Adjustment Mechanism imposes embodied-carbon reporting on imported solar-grade feedstock, advantaging European producers with verified low-carbon production routes.
- N-type monocrystalline migration:Cell efficiency standards above 25 percent are pulling high-purity 9N+ feedstock requirements through the wafer tier, tightening quality spreads between merchant grades.
Market Restraints
- Xinjiang supply concentration:Over 40 percent of global merchant capacity sits in a single Chinese province exposed to forced-labor due diligence and US UFLPA detention risk.
- Industrial silicon price volatility:Metallurgical-grade silicon feedstock swings with ferroalloy demand and Chinese power rationing, transmitting cost instability to polysilicon contract pricing.
- Siemens process electricity intensity:Conventional trichlorosilane deposition consumes 50-60 kWh per kilogram, creating stranded asset risk where grid carbon intensity rises or renewable power access is constrained.
Strategic Opportunities
- US domestic content incentives:The Inflation Reduction Act's 45X manufacturing credit and domestic content bonus create first-mover returns for greenfield polysilicon-to-wafer complexes in low-cost power states.
- Semiconductor-grade crossover:11N+ purity capability opens adjacent demand from silicon wafer foundries serving power electronics and automotive chips, diversifying revenue beyond solar.
- India PLI scheme:New Delhi's production-linked incentive for solar module manufacturing is pulling integrated polysilicon commitments to Rajasthan and Gujarat where land and solar irradiance support captive renewable power.
Industry Challenges
- Trichlorosilane handling certification:Pyrophoric chemical safety protocols and EPA Risk Management Plan compliance extend commissioning timelines for new US facilities by 18-24 months.
- FBR-to-Siemens process integration:Blending fluidized bed granular polysilicon with conventional rod material in Czochralski crucibles requires crucible lining modifications and pull-rate recalibration that slow yield ramp.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar-Grade Polysilicon Market |
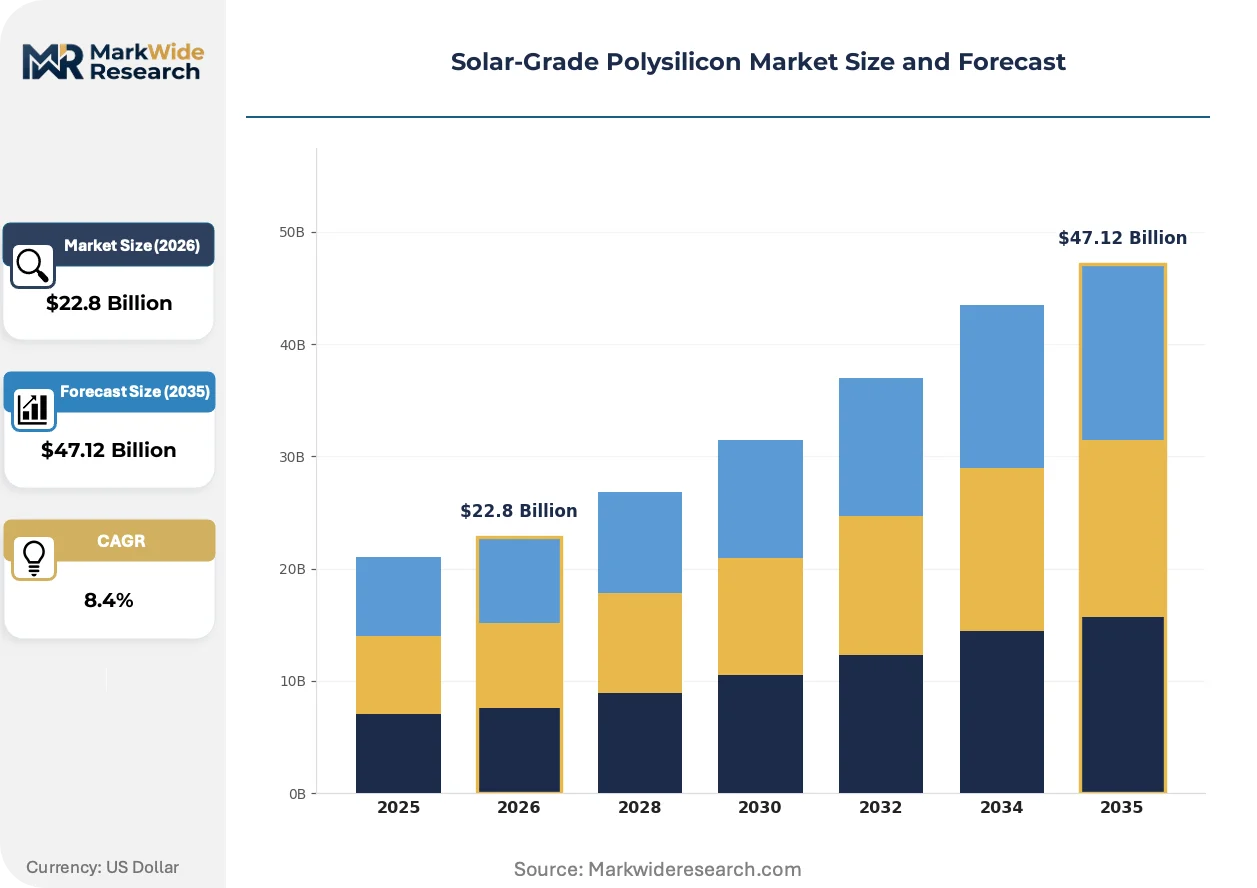
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $47.12 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monocrystalline, Multicrystalline, Amorphous, Others Application: Photovoltaic Cells, Solar Panels, Wafer Manufacturing, Others Technology: Siemens Process, Fluidized Bed Reactor, Czochralski Process, Others End User: Utilities, Residential, Commercial, Industrial |
| Companies Covered | Tongwei Co., Ltd, GCL Technology Holdings Ltd., Daqo New Energy Corp., Xinte Energy Co., Ltd, Wacker Chemie AG, OCI Company Ltd., Hemlock Semiconductor Operations LLC, REC Silicon ASA, Asia Silicon (Qinghai) Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar-Grade Polysilicon Market Trends and Innovations
Technology substitution and regulatory carbon accounting are compressing the viable process set for merchant producers, while downstream consolidation is concentrating buyer power among a handful of integrated wafer-cell-module conglomerates.
Fluidized Bed Reactor technology is consolidating investment flows as producers seek electricity intensity below 30 kWh per kilogram. GCL-Poly and REC Silicon are expanding FBR capacity in low-cost power jurisdictions. This technology is compressing the cost floor for solar-grade feedstock, forcing Siemens-only producers to specialize in semiconductor-grade purity or exit.
The EU F-Gas Regulation is tightening reporting requirements for fluorinated greenhouse gases used in polysilicon etching and cleaning steps. German and Norwegian producers are accelerating abatement technology deployment to maintain import competitiveness into the European market. Premium wafer customers are now requiring F-Gas emission disclosures in supplier scorecards.
Buyer consolidation among integrated cell-module producers is compressing contract structures from multi-year take-or-pay to quarterly price renegotiation with volume flexibility clauses. Tongwei and Longi are internalizing polysilicon supply through backward integration, reducing merchant market liquidity. This concentration is most visible in China where the top five buyers now absorb over 60 percent of domestic spot volume.
Solar-Grade Polysilicon Market Segmentation
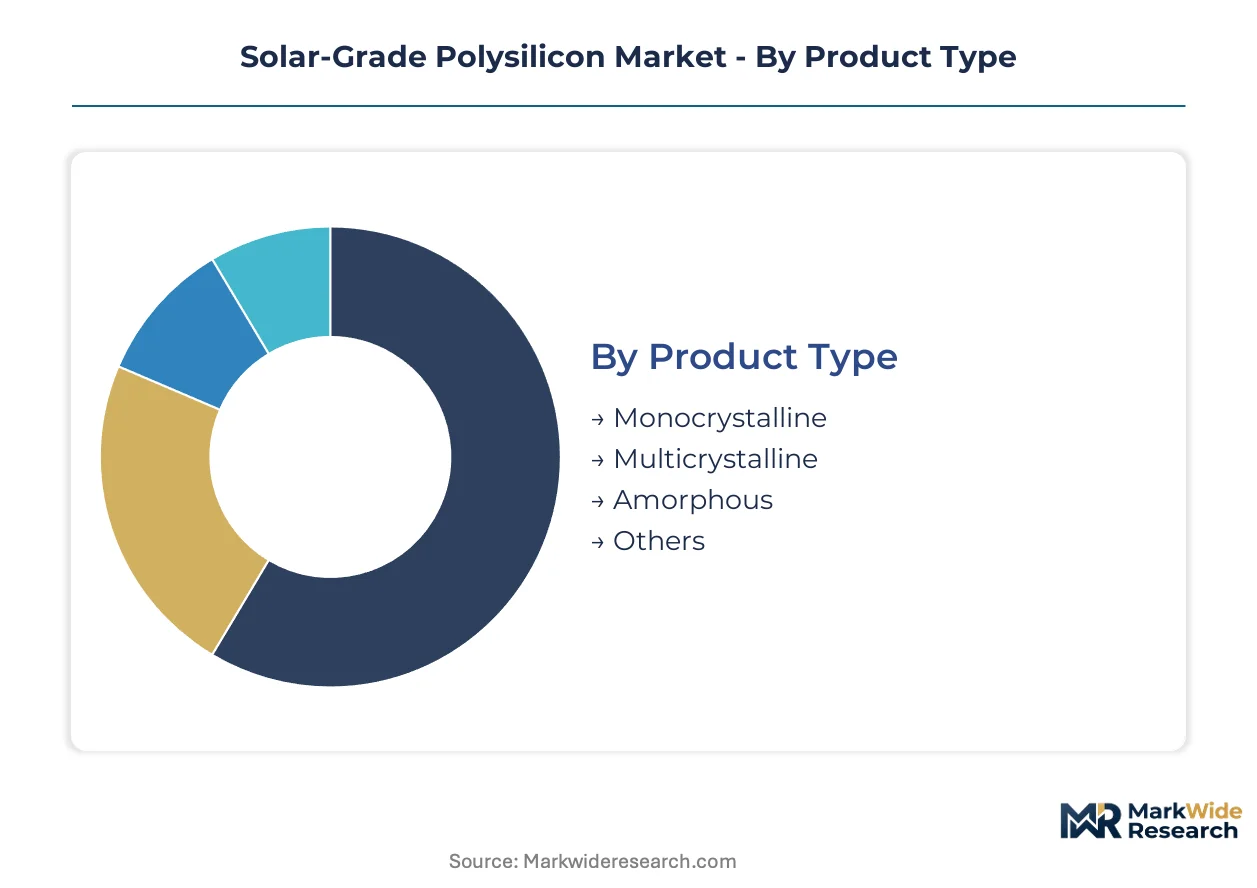
Polysilicon segmentation reveals how purity grades, manufacturing routes, and downstream integration patterns determine margin capture across the solar value chain. Each dimension carries distinct implications for capital intensity, energy consumption, and regulatory exposure.
Product Type:
Supply concentration in high-purity grades is compressing margins for legacy multicrystalline producers unable to meet n-type monocrystalline specifications.
- Monocrystalline:9N+ purity silicon refined for single-crystal ingot pulling via Czochralski growth. Demand concentrates in Tongwei and Longi wafer fabs across Sichuan and Yunnan provinces where hydropower supports low-carbon production claims for EU CBAM compliance.
- Multicrystalline:Directional solidification produces lower-purity blocks for conventional p-type cells. Xinjiang producers still operate multicrystalline furnaces for domestic Chinese distributed solar, though capacity is retiring fastest as PERC cell lines upgrade to TOPCon.
- Amorphous:Thin-film silicon deposition for heterojunction and tandem cell architectures.
- Others:Emerging kerfless wafer feedstocks and direct wafer technologies.
Monocrystalline absorbs the bulk of installed capacity; amorphous is expanding most quickly as heterojunction cell lines scale in Anhui and Jiangsu provinces.
Application:
Cost tier differentiation separates merchant-grade spot sales from captive supply chains internalized by integrated wafer-cell-module conglomerates.
- Photovoltaic Cells:High-purity feedstock for PERC, TOPCon, and heterojunction cell architectures. Demand clusters in Anhui, Jiangsu, and Zhejiang where JA Solar, Trina Solar, and JinkoSolar operate gigawatt-scale cell fabs with backward-integrated polysilicon offtake.
- Solar Panels:Module assembly consumes lower-grade polysilicon from merchant suppliers for standard p-type panels targeting utility-scale procurement in India and Brazil.
- Wafer Manufacturing:Czochralski pulling and diamond wire slicing transform polysilicon into monocrystalline wafers. Xinjiang's integrated polysilicon-to-wafer complexes near coal-chemical power sources dominate this application, though UFLPA detention risk is diverting US-bound supply to Inner Mongolia.
- Others:Research quantities and specialty semiconductor crossover applications.
Wafer manufacturing absorbs the bulk of installed capacity; photovoltaic cells are gaining share fastest as cell efficiency standards tighten.
Technology:
Volume concentration in Siemens-process capacity is creating stranded asset exposure where electricity costs rise or carbon-border adjustments tighten.
- Siemens Process:Trichlorosilane chemical vapor deposition onto heated silicon rods remains the dominant merchant technology. Xuzhou and Baotou host the largest Siemens clusters, though 50-60 kWh/kg electricity intensity disadvantages these assets against FBR competition.
- Fluidized Bed Reactor:Granular polysilicon production via silane decomposition in fluidized beds achieves sub-30 kWh/kg electricity consumption. GCL-Poly's Xuzhou FBR expansion and REC Silicon's Moses Lake facility anchor this technology's geographic spread.
- Czochralski Process:Single-crystal ingot growth from polysilicon feedstock, not a polysilicon production method itself but a downstream shaping technology.
- Others:Emerging metallurgical and electrochemical refinement routes.
Siemens Process absorbs the bulk of installed capacity; Fluidized Bed Reactor is climbing the fastest as producers secure low-cost renewable power offtake.
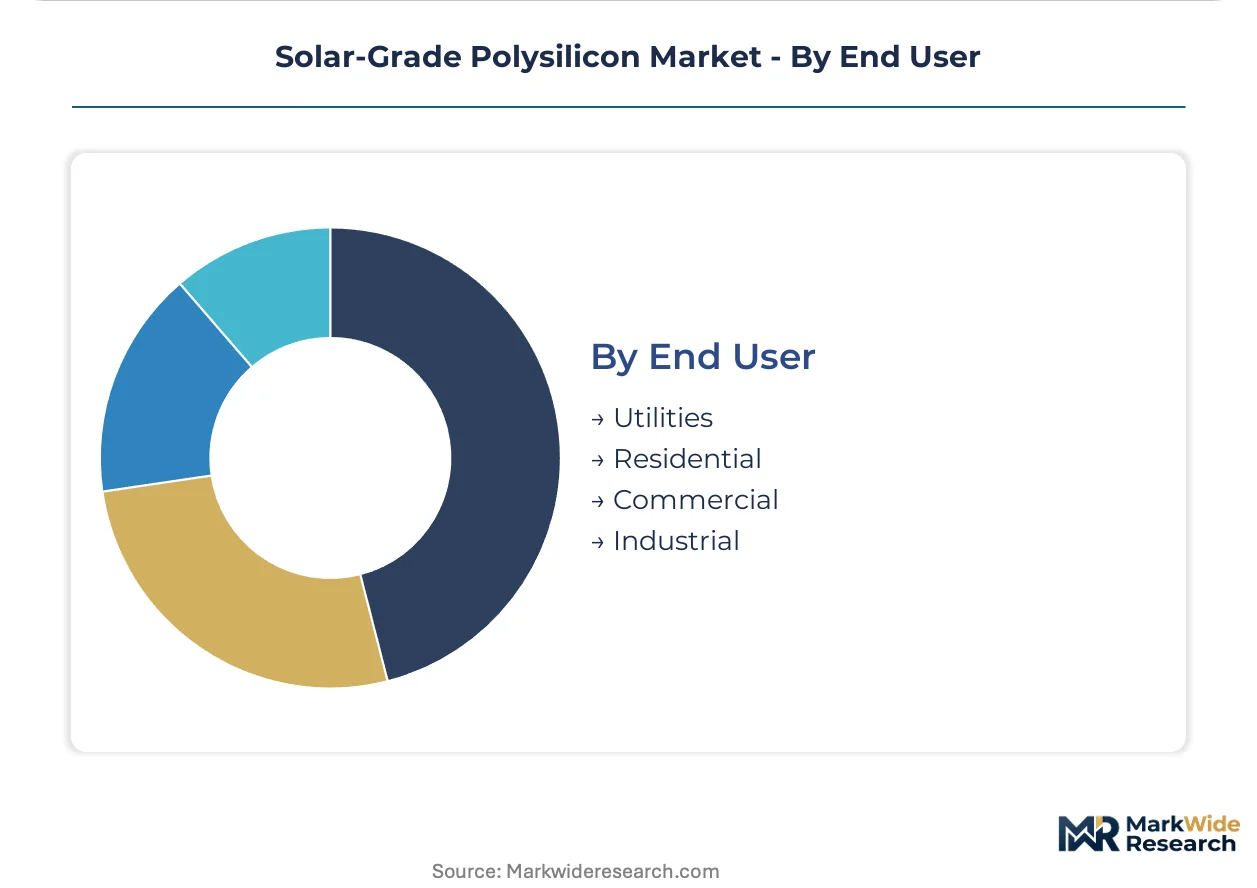
End User:
Customer type fragmentation separates price-tolerant utility procurement from margin-sensitive residential and commercial segments.
- Utilities:Gigawatt-scale solar farm developers procure polysilicon through long-term wafer supply agreements. State Power Investment Corporation and China Three Gorges Renewables anchor demand for high-purity feedstock in Xinjiang and Qinghai desert solar bases.
- Residential:Rooftop solar installers in Germany, Australia, and the US Northeast source panels with polysilicon from non-Xinjiang supply chains to satisfy due diligence requirements.
- Commercial:Corporate power purchase agreements drive demand for low-carbon-verified polysilicon in European and US markets.
- Industrial:Captive solar for manufacturing facilities with 24/7 load profiles.
Utilities absorb the bulk of installed capacity; residential is expanding most quickly as distributed solar accelerates in high-electricity-price jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Xinjiang's coal-chemical basins anchor the world's densest polysilicon production clusters, yet regulatory pressure is redispersing capacity across multiple jurisdictions seeking low-carbon power arbitrage.
China
Inner Mongolia's Baotou and Xuzhou host integrated Siemens-process complexes serving Tongwei and Longi wafer fabs. MIIT enforces GB energy-consumption standards per kilogram of output. Xinjiang's merchant supply dominance faces US UFLPA detention risk, diverting export-bound volume to Yunnan's hydropower corridors.
Germany
Burghausen-based Wacker Chemie AG specializes in ultra-high-purity grades for premium European wafer customers. ECHA REACH compliance and EU F-Gas Regulation reporting requirements shape import competitiveness. The country's chemical process engineering heritage supports FBR technology development alongside conventional deposition routes.
United States
Washington State's Moses Lake facility anchors domestic granular polysilicon production for semiconductor and solar crossover demand. EPA Risk Management Plan permitting for trichlorosilane handling extends commissioning timelines. IRA 45X manufacturing credits are pulling greenfield investment toward low-cost power states.
Norway
REC Silicon's Fjord-based operations leverage hydropower for sub-30 kWh/kg electricity intensity. The country's renewable power surplus attracts producers seeking CBAM-compliant supply chains for EU market access. Elkem and other metallurgical-grade silicon producers cluster near coastal smelters.
India
Rajasthan and Gujarat host emerging polysilicon-to-module complexes under PLI scheme incentives. BIS quality mandates fragment compliance requirements for multinational suppliers. Land and solar irradiance support captive renewable power for new integrated facilities.
Solar-Grade Polysilicon Market Competitive Landscape
Global majors compete with regional champions across purity grades and power-cost jurisdictions. The vendor base concentrates among integrated conglomerates and merchant specialists, with technology licensing reshaping competitive boundaries. Two archetypes dominate: backward-integrated wafer producers capturing captive supply chains, and purity-specialized merchant suppliers serving premium tier customers. Capacity expansion and strategic partnerships constitute the dominant competitive moves.
Within the integrated conglomerate tier, Tongwei Co., Ltd and GCL Technology Holdings Ltd. occupy positions exemplifying scale-driven vertical control over polysilicon-to-cell value chains. Wacker Chemie AG represents the specialized merchant archetype, anchoring European premium-grade supply. These three entities illustrate how geographic power-cost arbitrage and purity-grade specialization bifurcate competitive positioning.
| Leading Market Players |
|---|
| Tongwei Co., Ltd |
| GCL Technology Holdings Ltd. |
| Daqo New Energy Corp. |
| Xinte Energy Co., Ltd |
| Wacker Chemie AG |
| OCI Company Ltd. |
| Hemlock Semiconductor Operations LLC |
| REC Silicon ASA |
| Asia Silicon (Qinghai) Co., Ltd |
| Others |
Pricing and Supply Chain Analysis
Metallurgical-grade silicon price indices on the Shanghai Metals Market cascade through polysilicon contract tiers, compressing margins for Siemens-process producers while hydropower-backed Yunnan supply commands premium spreads under EU CBAM scrutiny.
Pricing Analysis
Warranty-backed carbon-intensity certifications bundle with long-term offtake contracts, separating unbundled spot sales from premium tier structures. Three-tier pricing stratification across 11N+ semiconductor crossover, 9N+ monocrystalline, and legacy multicrystalline grades reflects purity differentiation and power-source verification. Cost compression in standard-grade segments intensifies as Tongwei and Longi internalize captive supply. Residential rooftop installers in Germany and Australia exhibit highest price sensitivity, while utility-scale developers in Qinghai desert solar bases prioritize supply security over unit economics.
Supply Chain Analysis
REACH-compliant carbon accounting and UFLPA due diligence documentation gate entry into premium supply tiers, fragmenting procurement pathways. Production concentrates in China, Norway, and the United States, with Xinjiang's merchant dominance facing diversion to Inner Mongolia and Yunnan. The supply chain draws from metallurgical-grade silicon, trichlorosilane precursors, and high-purity hydrogen feedstocks. Single-province concentration in Xinjiang creates forced-labor detention risk for US-bound shipments. Distribution runs through integrated polysilicon-to-wafer complexes and merchant spot markets serving non-integrated cell fabs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance narrative where EU CBAM embodied-carbon reporting and US UFLPA due diligence erect barrier-to-entry moats for producers with verified low-carbon power offtake and documented supply chain transparency.
For Market Incumbents: Anchor market position through backward integration into Yunnan and Qinghai hydropower corridors, securing CBAM-compliant production claims. Defend against FBR technology substitution by specializing in 11N+ semiconductor-grade purity or scaling Siemens-process units below 45 kWh/kg through captive renewable power. Certification investment in F-Gas abatement technology preserves European market access as ECHA reporting requirements tighten. For New Entrants and Emerging Players: US-based module assemblers seeking non-Xinjiang supply chains represent the most penetrable buyer archetype, with IRA 45X manufacturing credits supporting greenfield FBR development in Washington State or low-cost power jurisdictions. Rajasthan and Gujarat polysilicon-to-module complexes under India's PLI scheme offer secondary white-space entry. A qualification-first go-to-market angle emphasizing UFLPA-compliant documentation and carbon-intensity verification unlocks premium procurement channels. For Investors and Strategic Acquirers: Distressed-cycle entries favor FBR-technology specialists with secured renewable power offtake in Norway or the Pacific Northwest, where sub-30 kWh/kg electricity intensity aligns with long-term CBAM advantage. Acquisition targets include merchant-grade producers with purity-upgrade potential toward semiconductor crossover applications. Monitor EU CBAM phase-in enforcement and US Customs UFLPA detention rates as inflection indicators for supply chain preference shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hydropower Corridors | Yunnan and Qinghai captive renewable offtake secures EU CBAM-compliant production claims for premium wafer customers. |
| FBR Technology Scale-Up | Sub-30 kWh/kg electricity consumption compresses cost floor against Siemens-process incumbents in high-grid-carbon jurisdictions. |
| Semiconductor-Grade Purity Crossover | 11N+ capability diversifies revenue beyond solar into silicon wafer foundries serving automotive chip demand. |
| UFLPA-Compliant Supply Chain Documentation | Forced-labor due diligence transparency unlocks US utility procurement and residential rooftop installer channels. |
| F-Gas Abatement Technology Deployment | ECHA reporting compliance preserves European import competitiveness as EU F-Gas Regulation tightens disclosure requirements. |
Research Methodology
Independent corroboration across polysilicon plant managers, wafer fab procurement leads, EPC contractors in utility-scale solar development, and trichlorosilane chemical safety officers underwrites the qualitative findings in this study. Primary interviews with downstream cell fab engineers and integrated conglomerate supply chain directors combined with secondary validation from MIIT energy-consumption disclosures, EIA power sector data, EU CBAM implementation guidance, and SEC filings from listed polysilicon producers. Bottom-up capacity-by-facility aggregation and top-down demand-model triangulation anchored volume estimates.
Rate-of-change decomposition across technology substitution curves, regulatory phase-in schedules, and power-cost arbitrage movements structured the analytical framework. Segmentation dimensions modeled include purity grade tier, manufacturing process route, downstream integration level, and regional regulatory cluster. CAGRs derived from installed capacity buildout schedules and wafer demand projections across the analysis window. Industry-specific forecast inputs incorporated MIIT GB standard enforcement timelines and EU CBAM carbon-border adjustment implementation.
Revisions become necessary when forced-labor due diligence enforcement intensifies, FBR technology cost curves steepen, or renewable power offtake availability shifts in key production basins. Forecasts reflect documented assumptions regarding technology adoption rates, regulatory implementation pacing, and feedstock price stability. A model refresh is warranted upon material change in EU CBAM carbon-intensity threshold calibration or US UFLPA entity list expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Asia-Pacific Semiconductor Materials Market
Semiconductor Material
Titanium Diboride Market
Semiconductor Material
Fullerene Market
Semiconductor Material
Gallium Market
Semiconductor Material
Synthetic Sapphire Market
Semiconductor Material
Quartz Crucible Market
Semiconductor Material
Niobium Hydride Market
Semiconductor Material
Silicon Carbide (Sic) Coating Market
Semiconductor Material
Chromium Oxide Market
Semiconductor Material
Quartz Market
Semiconductor Material
Asia-Pacific Silicone Market
Semiconductor Material
Global Gallium Nitride Market
Semiconductor Material
Electronic Ceramics Market
Semiconductor Material
Hafnium Market
Semiconductor Material
Vietnam Semiconductor Materials Market
Semiconductor Material
Rhenium Market