
 Tungsten Market | 2026-2036
Tungsten Market Size, Share, and Industry Trends Forecast 2026-2036
Tungsten Market Analysis
Aerospace and defense end-use demand is broadening as commercial aviation fleet renewal accelerates and hypersonic weapons programs multiply. China Minmetals Corporation leverages its captive concentrate mines to dominate upstream supply. H.C. Starck sustains European downstream refining capacity despite energy cost pressures. Kennametal Inc. specializes in cemented carbide tool systems for precision machining applications.
Tungsten is a refractory metal with the highest melting point of all elements at 3,422 degrees Celsius, typically extracted from wolframite and scheelite ores through acid leaching and reduction processes, then formed into carbides, alloys, and pure metal products for cutting tools, radiation shielding, and high-temperature components. Tungsten powder commands the largest volume share as the feedstock for cemented carbide production, while tungsten wire represents the fastest-growing product type driven by semiconductor thermal management and LED filament demand. Aerospace application leads value generation due to stringent certification requirements and long-term supply agreements, whereas electronics application is accelerating fastest from chip packaging and heat sink adoption.
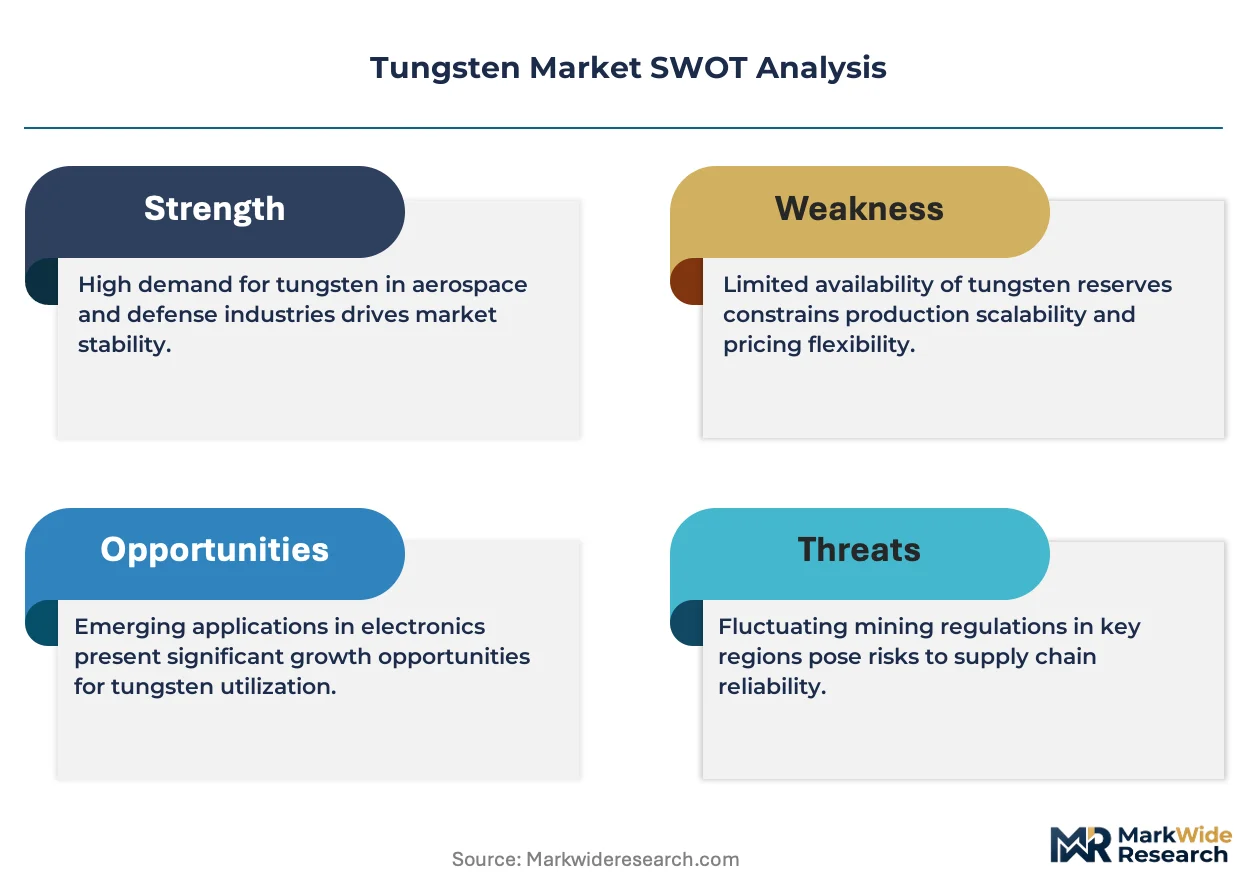
China's MEE enforces stricter tailings and emissions standards on domestic concentrate producers, tightening global raw material availability. REACH in Europe mandates full substance registration for tungsten compounds imported above one tonne annually, raising compliance costs for non-EU suppliers. ISO 9001 and aerospace-specific AS9100 certifications govern market access for defense and aviation suppliers. Stakeholders must monitor concentrate export license fluctuations from China and evaluate alternative African and Vietnamese mine development timelines to secure supply chain resilience.
Market Dynamics
China's concentrate export licensing regime and MEE tailings standards are compressing raw material availability while aerospace OEMs scramble for qualified tungsten alloy suppliers under AS9100 certification pressure.
Growth Catalysts
- Hypersonic weapons programs:Defense contractors in the US and Europe are expanding superalloy procurement for thermal protection systems requiring tungsten's 3,422°C melting point.
- REACH substance registration:European carbide tool makers face compliance costs that favor established refiners with existing dossiers, consolidating downstream value capture.
- Semiconductor thermal management:Tungsten-copper composites are displacing traditional heat spreaders in advanced packaging for high-power chips.
Market Restraints
- Concentrate supply concentration:China controls roughly 80% of global mine output, creating single-point vulnerability for non-Chinese downstream processors.
- Energy cost differentials:European APT smelters face 40-60% higher electricity costs than Chinese integrated operations, eroding refining margins.
- Molybdenum substitution in steels:Tool steel formulations are reducing tungsten content where performance specifications permit lower-cost alternatives.
Strategic Opportunities
- Vietnamese mine development:Nui Phao and emerging projects offer non-Chinese concentrate sources for supply chain diversification.
- EU Green Deal critical raw materials list:Tungsten's designation triggers strategic stockpiling mandates and domestic processing subsidies.
- Additive manufacturing feedstock:Spherical tungsten powder for laser powder bed fusion opens precision component markets beyond subtractive machining.
Industry Challenges
- AS9100 certification timelines:Aerospace suppliers face 12-18 month audit cycles to qualify new material sources for turbine blade contracts.
- Refractory metal welding expertise:Fabricators with tungsten inert gas capabilities for thick-section components remain concentrated in Germany and the US.
- Legacy furnace infrastructure:Hydrogen reduction furnaces for tungsten powder production require capital replacement that few independent processors can finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tungsten Market |
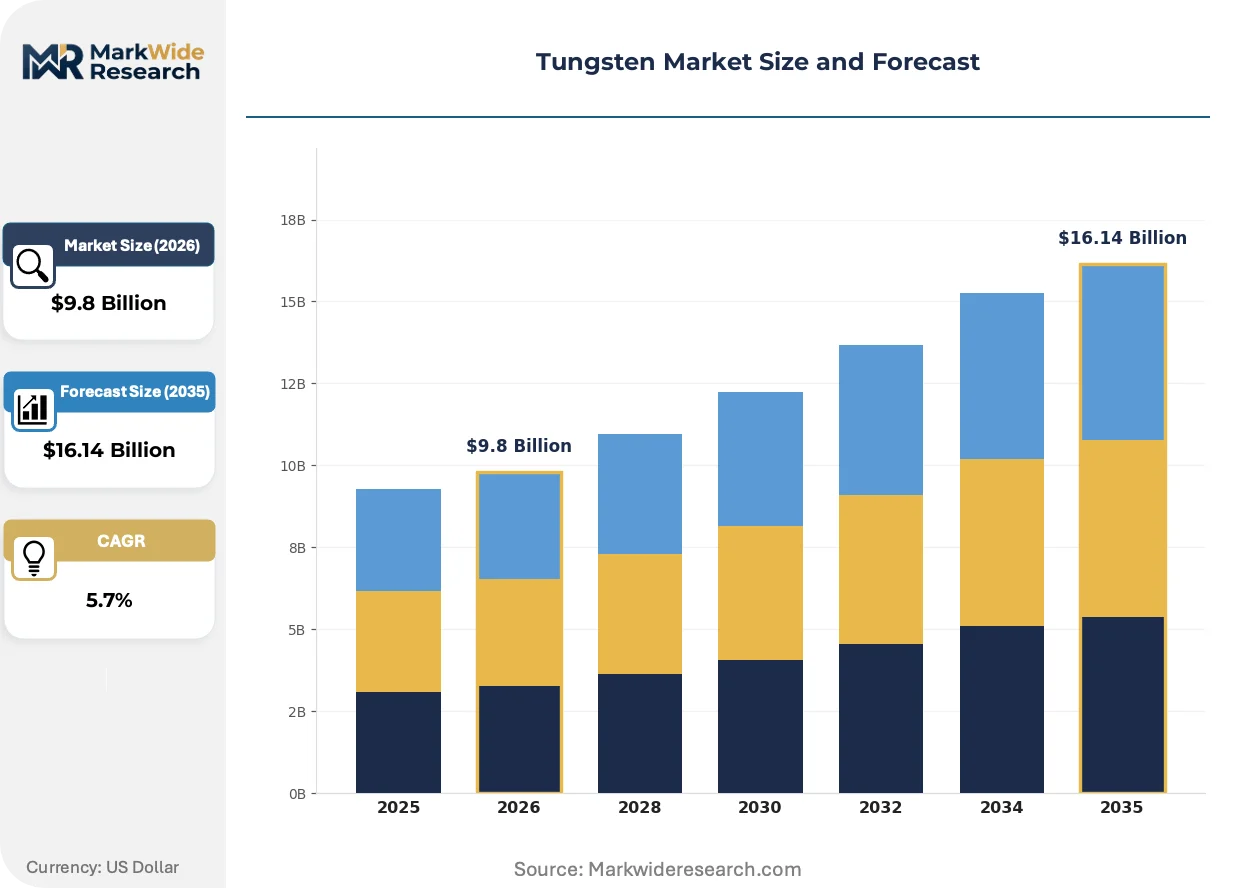
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $16.14 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tungsten Rods, Tungsten Bars, Tungsten Powder, Tungsten Wire Application: Aerospace, Defense, Electronics, Mining End User: Manufacturers, OEMs, Research Institutions, Industrial Users Form: Sintered, Machined, Cast, Coated |
| Companies Covered | China Minmetals Corporation, Xiamen Tungsten Co. Ltd., China Tungsten & Hightech Materials Co. Ltd., H.C. Starck, Chongyi Zhangyuan Tungsten Co. Ltd., Kennametal Inc., Sandvik AB, Guangdong Xianglu Tungsten Co. Ltd., Buffalo Tungsten Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tungsten Market Emerging Trajectories
Material science breakthroughs and regulatory recalibration are compressing traditional supply hierarchies while end-users demand traceable, low-carbon tungsten for Scope 3 reporting.
Near-net-shape spark plasma sintering is rewriting powder metallurgy economics for complex carbide geometries. Medical device manufacturers in Switzerland and Germany are adopting the process for surgical instrument blanks, eliminating 30-40% of finish machining operations and compressing lead times from weeks to days.
REACH Annex XVII restrictions on cobalt compounds are forcing reformulation of traditional WC-Co cemented carbides. Cutting tool producers are testing nickel and iron binder alternatives, with the most advanced trials occurring at Stuttgart-area research institutes serving automotive suppliers.
Buyers are consolidating qualified supplier lists and demanding cradle-to-gate carbon footprints. German automotive tier-1s now require tungsten carbide inserts with documented concentrate origin and energy-intensity metrics, displacing spot-market procurement and favoring vertically integrated producers with mine-to-tool traceability systems.
Tungsten Market Segmentation
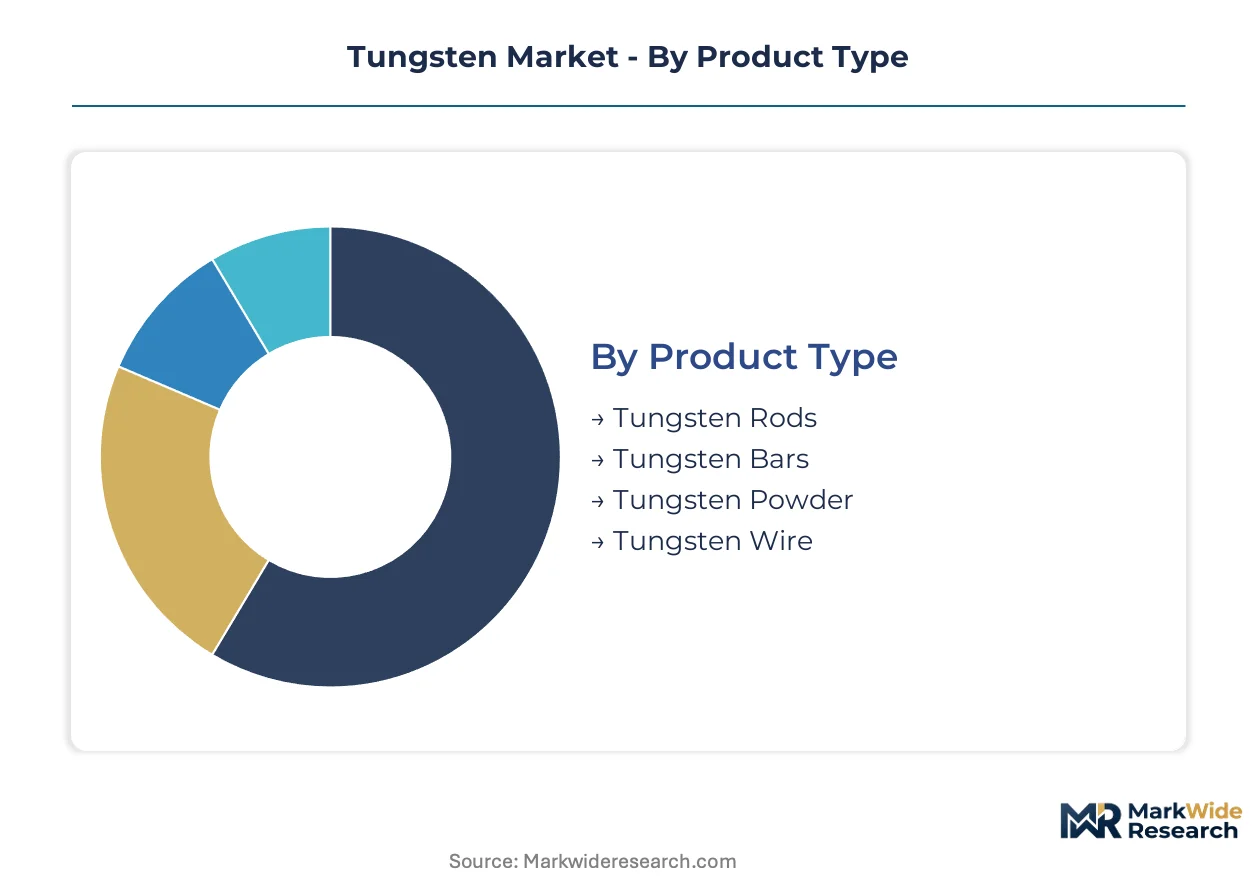
Product form and processing route determine pricing tiers and customer qualification requirements in tungsten supply chains. Aerospace and electronics end-users impose divergent purity and certification standards that reshape procurement patterns across each segment.
Product Type:
Material specification and downstream conversion complexity define the competitive landscape across product categories.
- Tungsten Powder:Reduced from ammonium paratungstate in hydrogen furnaces, this feedstock grades from 0.5 to 50 microns depending on carbide or metallurgical end-use. Cemented carbide producers in Germany's Stuttgart cluster consume the largest volumes for cutting tool matrices.
- Tungsten Wire:Drawn from sintered rods through diamond dies to diameters below 25 microns, this product serves semiconductor thermal management and LED filament applications. Wire demand is climbing fastest from chip packaging adoption in Taiwan and South Korea.
- Tungsten Rods:Pressed and sintered billets for electrical discharge machining electrodes and radiation shielding components.
- Tungsten Bars:Heavy alloy blanks for kinetic energy penetrators and counterbalance weights in aerospace applications.
Tungsten powder leads on scale; tungsten wire leads on momentum.
Application:
End-use performance requirements and regulatory certification intensity create distinct margin profiles across demand sectors.
- Aerospace:Superalloy additions and turbine blade coatings require 99.95%+ purity with full AS9100 traceability. Jet engine OEMs in the US and France lock in multi-year supply agreements to secure qualified material.
- Electronics:Heat spreaders, package substrates, and sputtering targets demand controlled grain structure and low oxygen content. Semiconductor fabricators are displacing molybdenum with tungsten-copper composites for thermal management.
- Defense:Armor-piercing penetrators and hypersonic thermal protection systems drive demand for heavy alloys with nickel-iron binders.
- Mining:Drill bit inserts and wear parts consume cemented carbide with cobalt matrices, though REACH cobalt restrictions are forcing binder reformulation.
Aerospace leads on scale; electronics leads on momentum.
End User:
Procurement sophistication and technical specification authority vary sharply across customer categories.
- OEMs:Original equipment manufacturers in aviation and semiconductor equipment set material specifications and audit supplier quality systems directly.
- Manufacturers:Tier suppliers convert semi-finished tungsten into components, bearing inventory risk and certification maintenance costs.
- Industrial Users:Maintenance and repair operations purchase cutting tools and wear parts through distributor channels with limited technical engagement.
- Research Institutions:Universities and national laboratories source small-batch high-purity material for fusion energy and medical isotope projects.
OEMs lead on scale; research institutions lead on momentum.
Form:
Processing stage determines value capture position and capital intensity requirements.
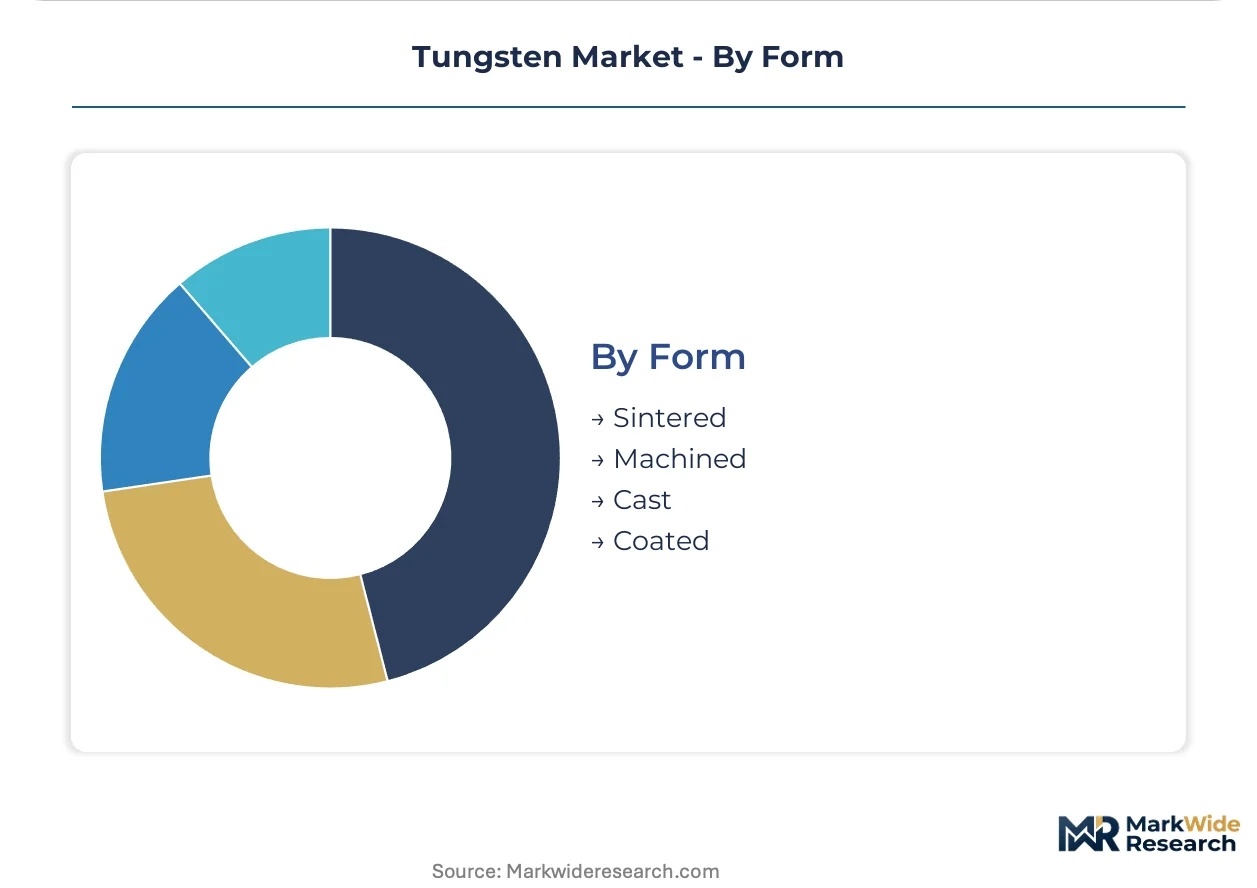
- Sintered:Hydrogen-fired compacts at 80-95% theoretical density serve as feedstock for subsequent machining or direct use in wear applications.
- Machined:Precision-ground components for ion implantation sources and X-ray targets command premium pricing for dimensional tolerances.
- Cast:Limited to specialized alloys where near-net shapes reduce material waste in heavy section parts.
- Coated:Chemical vapor deposition and physical vapor deposition layers extend tool life in extreme cutting conditions.
Sintered forms lead on scale; machined forms lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart's precision tooling cluster anchors global tungsten demand, with German carbide insert makers supplying automotive and medical device OEMs across three continents. Aerospace turbine blade procurement is accelerating from US and French jet engine manufacturers. Electronics fabricators in Taiwan and South Korea are displacing traditional heat spreaders with tungsten-copper composites.
China
Concentrate mining controls roughly four-fifths of global raw material output, with MEE tailings standards and dual carbon goals tightening permit availability. Export licensing regimes now fluctuate quarterly, forcing non-Chinese APT processors to maintain buffer inventories. Xiamen and Ganzhou house the dominant upstream refining complexes serving domestic carbide producers.
Germany
Stuttgart-Essen precision tooling corridor consumes the largest European volumes of tungsten powder for cemented carbide matrices. REACH substance registration mandates favor established refiners with existing dossiers, raising barriers for non-EU suppliers. H.C. Starck maintains downstream refining capacity despite 40-60% energy cost premiums over Asian integrated operations.
United States
Hypersonic weapons programs and commercial aviation fleet renewal are expanding superalloy procurement for thermal protection systems. FAA certification pressure and AS9100 audit cycles create 12-18 month qualification timelines for new material sources. Buffalo Tungsten Inc. and Pennsylvania-based processors serve defense contractors with heavy alloy requirements.
Vietnam
Nui Phao and emerging mine projects offer non-Chinese concentrate sources for supply chain diversification. The country's geology favors wolframite deposits with lower sulfur content than typical Chinese ore bodies. Thai Nguyen province is attracting APT smelter investment from Japanese trading houses seeking upstream control.
South Korea
Semiconductor thermal management demand is climbing fastest from chip packaging adoption in Suwon and Pyeongtaek clusters. Tungsten wire for LED filaments and sputtering targets commands premium pricing from display panel manufacturers. The national industrial policy designates refractory metals as strategic materials eligible for stockpiling subsidies.
Tungsten Market Vendor Landscape
Capacity expansion dominates the current landscape as Chinese state-owned enterprises consolidate mine-to-metal control and European processors defend margin position against energy cost differentials. The vendor base stratifies into three tiers: integrated miners with captive concentrate supply, specialized refiners with REACH dossiers and aerospace certifications, and regional fabricators serving spot-market tool steel demand. Strategic archetypes include upstream-integrated Chinese SOEs, certification-heavy European specialists, and technology-licensed Asian powder producers. M&A activity concentrates on Vietnamese and African mine assets, while portfolio diversification moves target spherical powder for additive manufacturing feedstock.
Among Chinese state-backed miners, China Minmetals Corporation and Xiamen Tungsten Co. Ltd. exemplify the upstream-integrated archetype with captive concentrate supply chains. H.C. Starck occupies a position representing European certification-heavy specialists, sustaining downstream refining despite continental energy cost pressures. Kennametal Inc. anchors the tool-systems tier, converting semi-finished tungsten into precision machining solutions for automotive and aerospace OEMs with stringent AS9100 requirements.
| Leading Market Players |
|---|
| China Minmetals Corporation |
| Xiamen Tungsten Co. Ltd. |
| China Tungsten & Hightech Materials Co. Ltd. |
| H.C. Starck |
| Chongyi Zhangyuan Tungsten Co. Ltd. |
| Kennametal Inc. |
| Sandvik AB |
| Guangdong Xianglu Tungsten Co. Ltd. |
| Buffalo Tungsten Inc. |
| Others |
Supply Flow & Price Mechanics
Energy differentials between Chinese hydrogen reduction furnaces and European APT smelters cascade through three pricing tiers, with Stuttgart carbide producers absorbing 40-60% cost premiums that concentrate buyers now demand to offset through long-term offtake discounts.
Pricing Analysis
Distributor margins on cemented carbide inserts compress as German automotive tier-1s consolidate qualified supplier lists and negotiate direct mill relationships. Pricing stratifies across premium, standard, and economy tiers based on AS9100 certification status and documented concentrate origin. Cost compression in standard-grade powder stems from Chinese integrated producers leveraging captive mine supply. Research institutions exhibit highest price sensitivity due to small-batch procurement volumes, while aerospace OEMs prioritize qualification security over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from jet engine manufacturers in France and the US mandate qualified secondary suppliers for tungsten heavy alloys, forcing inventory buffers at Buffalo Tungsten and H.C. Starck despite working capital strain. Concentrate supply draws from China, Vietnam, and emerging African projects. Ammonium paratungstate, hydrogen gas, and cobalt binder compounds constitute critical input dependencies. Single-source vulnerability concentrates in Chinese export licensing fluctuations. Distribution runs through direct OEM contracts for aerospace grades and distributor networks for industrial maintenance tooling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tungsten functions as a stable compounder anchored by irreplaceable thermal properties in jet engine superalloys, with fleet renewal cycles and hypersonic weapons programs generating decade-long demand visibility.
For Market Incumbents: Extend certification maintenance investments to lock in AS9100-qualified supplier status against emerging Vietnamese concentrate processors. Add spherical powder capacity for additive manufacturing feedstock to capture precision component markets beyond subtractive machining. Deepen upstream control through offtake agreements with Nui Phao and comparable non-Chinese mine developments.
For New Entrants and Emerging Players: Begin with medical device manufacturers in Switzerland and Germany adopting near-net-shape spark plasma sintering for surgical instrument blanks. Target semiconductor thermal management applications in South Korea's Suwon cluster where tungsten-copper composites displace legacy heat spreaders. Pursue toll-processing arrangements with established refiners lacking REACH dossiers.
For Investors and Strategic Acquirers: Roll-up economics work for European certification-heavy specialists because REACH substance registration barriers and AS9100 audit cycles prevent rapid new entrant scaling. Five-to-ten year viability rests on aerospace superalloy demand inelasticity and electronics thermal management acceleration. Monitor Chinese MEE tailings permit issuance as inflection indicator for concentrate export volume shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Concentrate Supply | Captive wolframite access from Vietnamese deposits insulates against Chinese export licensing volatility. |
| Spherical Powder Capacity Addition | Laser powder bed fusion feedstock opens aerospace precision component markets beyond traditional machining. |
| REACH Dossier Expansion | Existing cobalt compound registrations gain defensive value as Annex XVII restrictions force binder reformulation. |
| Long-term Aerospace Supply Agreement | Multi-year offtake contracts with Safran or GE Aviation lock in qualified supplier status against new entrants. |
| Joint Venture with Semiconductor Fabricator | Co-development of tungsten-copper composite heat spreaders accelerates displacement of molybdenum in advanced packaging. |
Methodological Framework
Bottom-up cemented carbide consumption modeling reconciled against top-down concentrate production tracking forms the analytical core of this study. Primary interviews with plant managers at Stuttgart-area tool manufacturers, procurement leads at German automotive tier-1s, and technical R&D directors at aerospace superalloy foundries combined with secondary validation from customs trade data, SEC filings of listed tungsten processors, ECHA REACH registration databases, and national mineral production statistics. Triangulation across these sources calibrated volume and value estimates.
Historical trendline analysis of ammonium paratungstate pricing, cemented carbide insert shipments, and aerospace engine delivery patterns informed projection frameworks across the analysis window. Segmentation dimensions encompassed product form, application sector, end-user category, and processing stage. CAGRs derived from regression against macro industrial production indices and end-use demand drivers including commercial aviation fleet renewal rates and semiconductor capital expenditure cycles.
Several conditions sit outside the modeled scope, including unannounced Chinese mining permit revocations, breakthrough molybdenum substitution in high-performance steels, and disruptive additive manufacturing technology shifts. Forecasts reflect documented assumptions regarding concentrate export license continuity and energy cost differential persistence. Deviation in Chinese environmental enforcement intensity or REACH cobalt restriction timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Semiconductor Grade Neon Gas Market
Semiconductor Material
Asia Pacific Graphene Market
Semiconductor Material
Monocrystalline Silicone Market
Semiconductor Material
PP Capacitor Films Market
Semiconductor Material
5G Substrate Materials Market
Semiconductor Material
Synthetic Sapphire Market
Semiconductor Material
Global Polybutylene Terephthalate (PBT) Market
Semiconductor Material
Silicon Dioxide Market
Semiconductor Material
Yttrium Oxide Market
Semiconductor Material
Glass Wafer Market
Semiconductor Material
Quartz Market
Semiconductor Material
Indium Gallium Zinc Oxide Market
Semiconductor Material
Chromium Oxide Market
Semiconductor Material
Asia-Pacific Transparent Conductive Films Market
Semiconductor Material
Electronic-Grade Polysilicon Market
Semiconductor Material
Big Size Synthetic Diamond Market