
 Distribution Voltage Regulator Market | 2026-2036
Distribution Voltage Regulator Market Size, Share, and Industry Trends Forecast 2026-2036
Distribution Voltage Regulator Market Outlook
Utility-grade specification tiers is reorganizing competitive dynamics in the Distribution Voltage Regulator Market. ABB Ltd. leverages its electromechanical heritage to dominate pole-mounted installations across European utilities. Siemens AG anchors its position through deep R&D investment in smart grid integration protocols. Schneider Electric differentiates via end-to-end digital energy management platforms that bundle regulators with analytics software.
A distribution voltage regulator is an electromechanical or solid-state device that maintains consistent voltage levels on medium-voltage distribution feeders, typically operating across 2.4 kV to 34.5 kV ranges with ±10% correction bandwidth. Its primary function is to compensate for voltage drop across long feeder lines, ensuring that industrial motors, commercial HVAC systems, and residential appliances receive power within acceptable tolerance bands. Static and digital type segments are capturing margin pools as utilities phase out legacy servo mechanisms in favor of faster-response electronic control systems. Smart technology installations are expanding fastest where grid operators deploy voltage-var optimization schemes, while electromechanical units retain residual demand in cost-sensitive emerging markets with simpler network topologies.
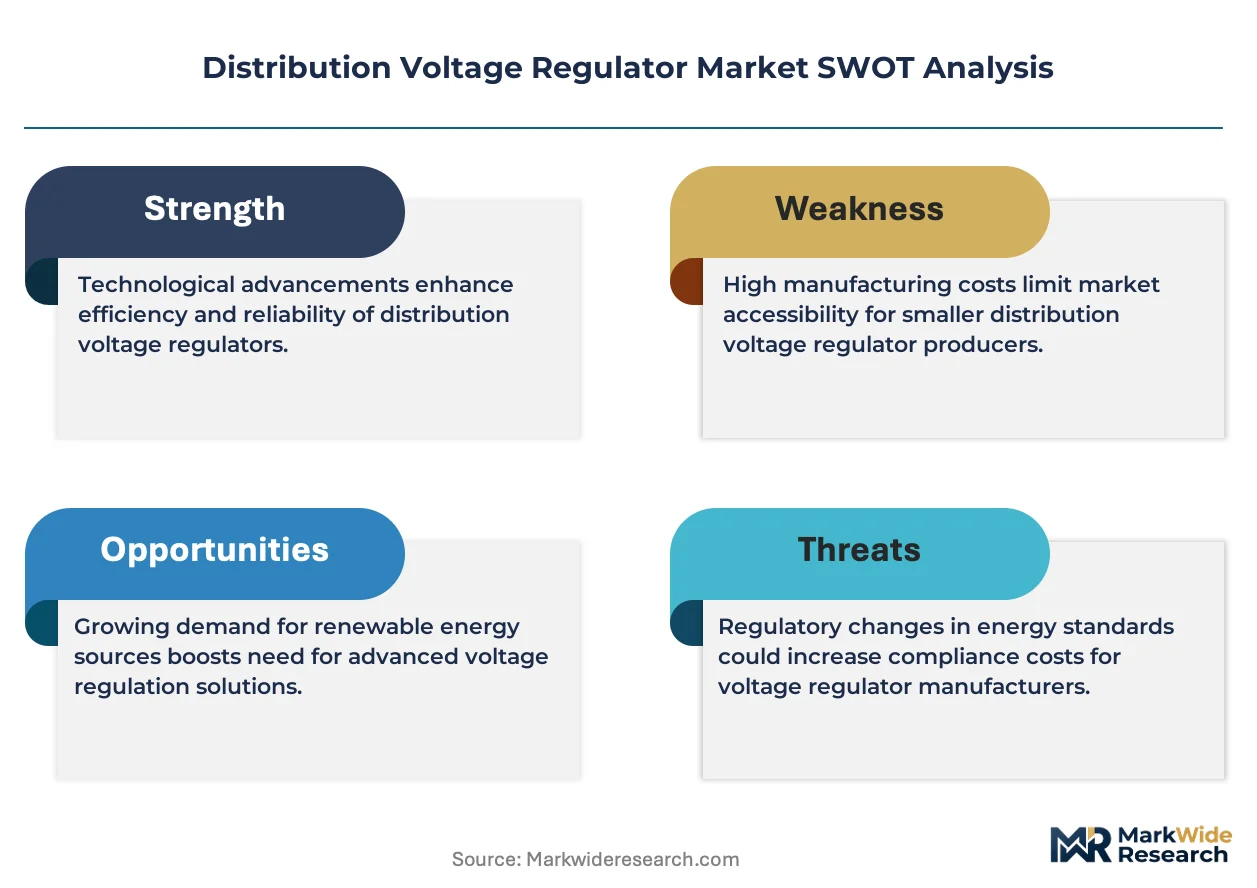
IEEE 1547 interconnection standards in the United States, IEC 60076 loading guides in Europe, and BIS IS 2026 specifications in India collectively dictate insulation classes, efficiency thresholds, and testing protocols that determine product market access. Compliance with these frameworks forces manufacturers to maintain parallel certification portfolios, adding fixed cost burdens that favor scaled producers with dedicated regulatory affairs teams. Stakeholders must monitor how evolving FERC Order 2222 implementation in the United States and EU Green Deal efficiency mandates reshape the economic viability of hybrid versus fully electronic regulator architectures.
Market Dynamics
Utility grid modernization mandates and the phase-out of electromechanical servo mechanisms are compressing replacement cycles across distribution networks, forcing capital allocation toward solid-state and hybrid voltage regulation architectures.
Growth Catalysts
- FERC Order 2222 Implementation:US utilities accelerate procurement of smart regulators capable of bidirectional power flow coordination with distributed energy resources.
- Industrial Motor Protection:Manufacturing facilities in Germany and India demand tighter voltage tolerance bands to prevent damage to precision automation equipment.
- Silicon Carbide Power Electronics:Faster switching speeds in static regulators enable sub-cycle voltage correction for solar-rich feeders.
Market Restraints
- Copper and Grain-Oriented Steel Volatility:Core material price swings compress margins for electromechanical unit producers.
- Chinese Supply Concentration:Dependency on PRC-based magnetic core suppliers exposes procurement teams to logistics disruptions.
- IEC 60076 Certification Burden:Parallel testing protocols for European market entry add fixed costs that disadvantage smaller manufacturers.
Strategic Opportunities
- Rural Electrification in India:Village-level microgrids create demand for compact pole-mounted regulators with remote monitoring capabilities.
- Voltage-Var Optimization Convergence:Integration of capacitor bank controllers with digital regulators opens bundled analytics revenue streams.
- EU Green Deal Efficiency Mandates:Tiered loss-reduction targets incentivize replacement of 1980s-era electromechanical installations.
Industry Challenges
- Legacy SCADA Integration:Digital regulators must interface with decades-old utility communication protocols.
- Field Technician Shortage:Utilities struggle to hire personnel trained in both power electronics and traditional transformer maintenance.
- Multi-Standard Certification Timelines:Simultaneous IEEE 1547 and IEC compliance testing extends product launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Distribution Voltage Regulator Market |
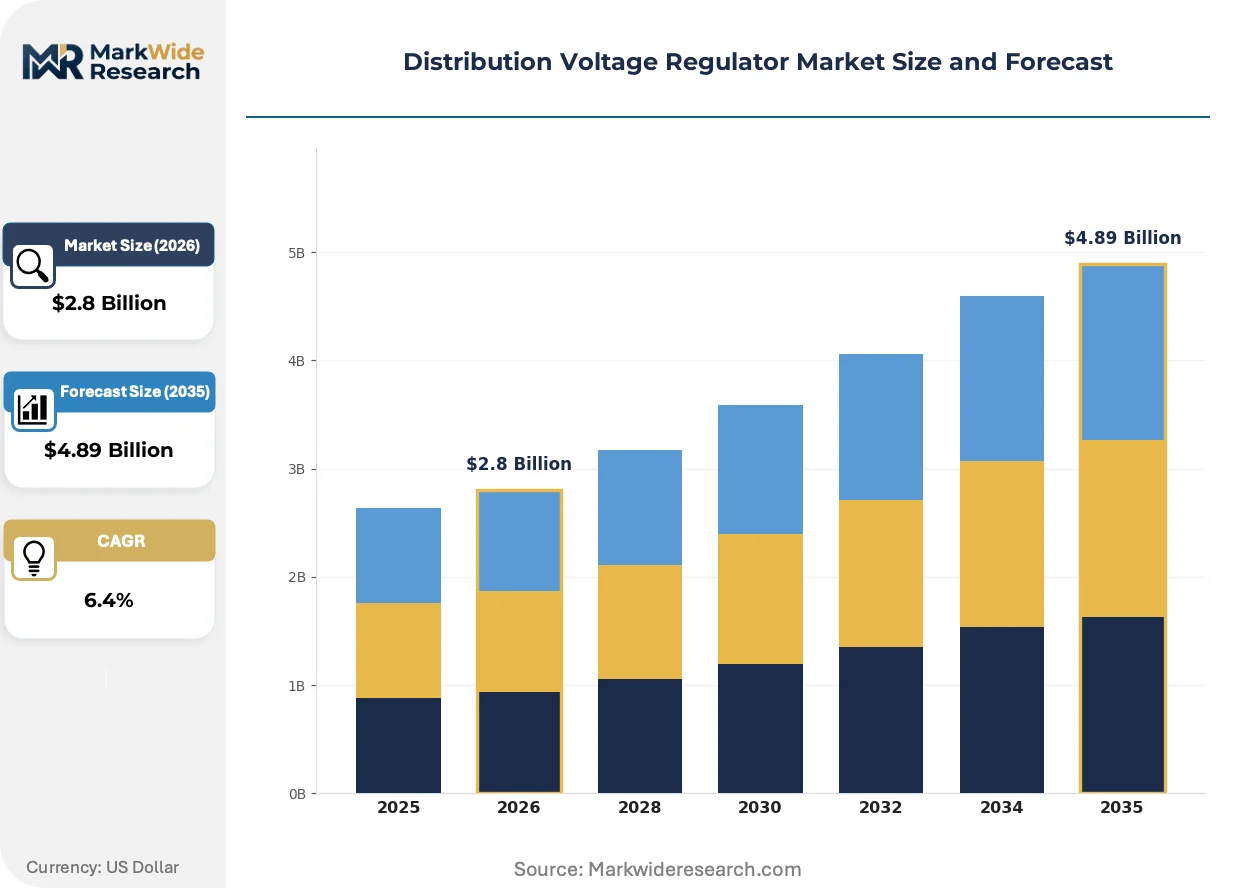
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Servo, Static, Digital, Line Interactive Application: Industrial, Commercial, Residential, Utility Technology: Electromechanical, Electronic, Hybrid, Smart Installation: Pole Mounted, Ground Mounted, Indoor, Outdoor |
| Companies Covered | Schneider Electric, Belotti Variatori SRL, ABB Ltd., S&C Electric Company, Daihen Corporation, Eaton Corporation, Siemens AG, Maschinenfabrik Reinhausen GmbH, General Electric Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Distribution Voltage Regulator Market Strategic Shifts
Digital control architectures and wide-bandgap semiconductors are compressing response times while expanding telemetry capabilities, enabling predictive maintenance models that reshape utility O&M economics.
Solid-state voltage regulators employing silicon carbide MOSFETs are supplanting mechanical tap-changers in urban distribution feeders. Grid operators in California and Texas deploy these units to manage rapid voltage fluctuations from rooftop solar penetration. The technology is supplanting traditional 32-step mechanical designs with continuous 0.5% resolution correction.
EU Green Deal efficiency mandates are tightening no-load loss thresholds for distribution equipment. Manufacturers must redesign core laminations and cooling systems to meet 2027 benchmarks. German and French utilities now specify premium-tier regulators with 20% lower losses than IEC 60076 minimums.
Performance-based service agreements are displacing traditional equipment-plus-installation contracts. US cooperatives and municipal utilities in the Midwest now procure voltage regulation as a guaranteed power-quality outcome. This model concentrates risk with manufacturers while accelerating adoption of remote-diagnostic platforms.
Distribution Voltage Regulator Market Segmentation
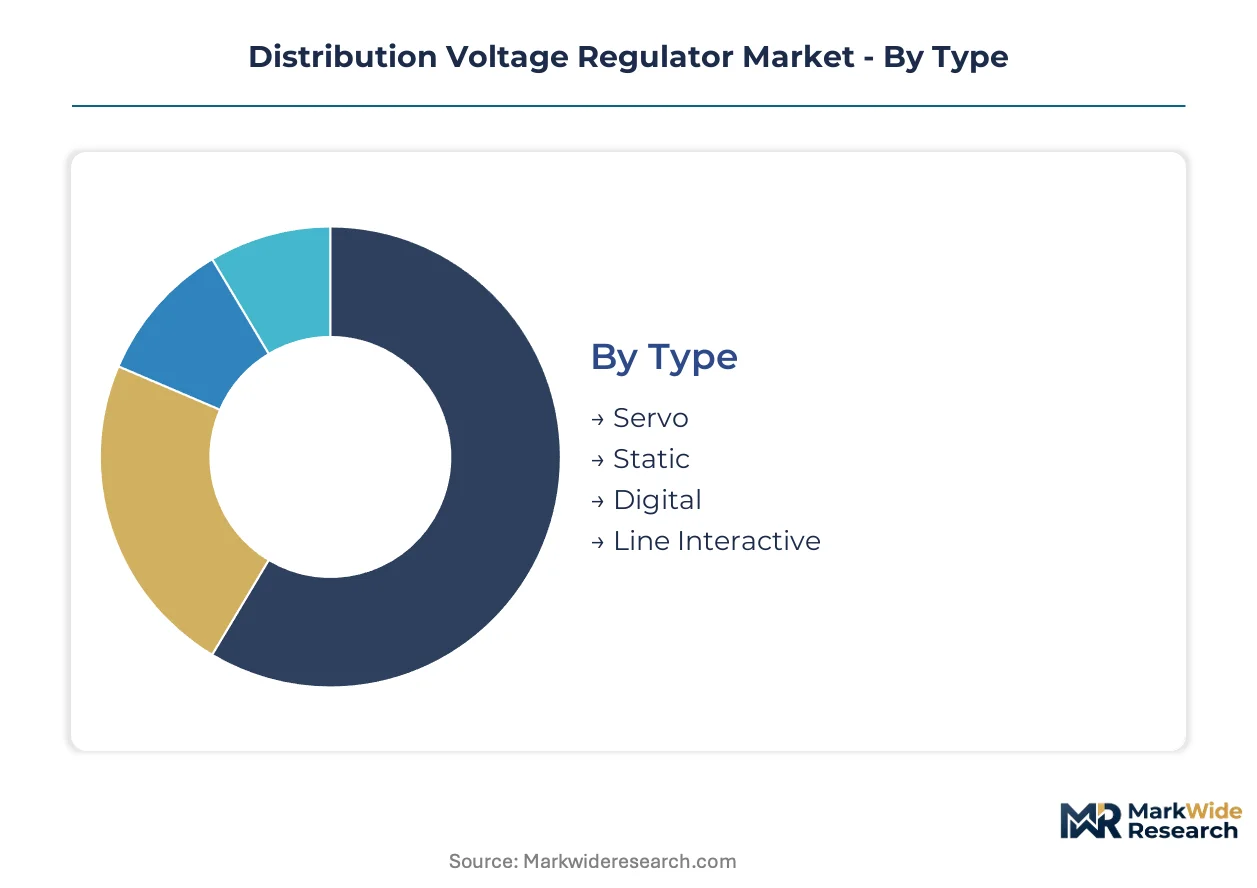
Voltage regulator procurement channels diverge sharply by segment, with utilities favoring electromechanical units through direct OEM contracts while commercial integrators source static and digital variants via electrical distributors. Understanding these channel dynamics reveals where margin pools concentrate and which technology transitions will reshape competitive positioning.
Type:
Servo regulators flow through traditional utility procurement channels, static and digital units concentrate in commercial electrical distribution, while line interactive models serve residential markets through contractor networks.
- Servo:Mechanical tap-changing mechanisms using motor-driven brush assemblies achieve ±10% voltage correction across 32 discrete steps. US rural cooperatives in Nebraska and Kansas specify these units for long feeder lines serving agricultural loads where replacement part availability outweighs efficiency concerns.
- Static:Silicon carbide MOSFET arrays enable continuous voltage regulation without moving parts, achieving sub-cycle response times below 4 milliseconds. California utilities deploy these for solar-rich feeders in the Central Valley where rapid voltage fluctuations from cloud transients demand electronic speed.
- Digital:Microprocessor-controlled architectures with embedded communication protocols support remote configuration and predictive diagnostics. These units are penetrating municipal utility fleets in Texas and Florida seeking SCADA integration without proprietary gateway hardware.
- Line Interactive:Buck-boost transformer designs with battery backup capability protect sensitive residential electronics. These units move through electrical contractor channels in hurricane-prone Gulf Coast states where power quality events exceed 100 annually.
Servo regulators dominate installed base. Static units are where expansion concentrates.
Application:
Cost tier stratification separates premium utility-grade specifications from standard commercial offerings and economy residential units.
- Industrial:Precision manufacturing facilities in Germany's Baden-Württemberg region demand ±1% voltage tolerance bands to protect CNC machining centers and semiconductor fabrication equipment. Siemens and ABB supply these markets with IEC 60076-compliant units featuring enhanced insulation systems.
- Commercial:Data centers and hospital complexes in India's Maharashtra and Karnataka states require uninterrupted voltage regulation for critical loads. These installations favor hybrid electromechanical-electronic architectures that combine mechanical reliability with electronic response speed.
- Residential:Single-phase pole-mounted regulators protect rural distribution feeders serving dispersed housing clusters. Chinese manufacturers supply these cost-sensitive markets through regional electrical distributors in provinces with ongoing grid extension programs.
- Utility:Transmission and distribution operators in France and Italy deploy three-phase regulators with integrated capacitor bank controllers for voltage-var optimization schemes. These premium-tier installations specify 20% lower no-load losses than IEC minimums.
Utility applications command highest unit values. Industrial segments are climbing the fastest.
Technology:
Volume concentration favors mature electromechanical production while customer type differentiation separates smart grid adopters from legacy maintenance organizations.
- Electromechanical:Conventional servo-driven tap changers with oil-immersed contacts remain the default specification for emerging market utilities in India and Southeast Asia. These units offer field-serviceable components that align with local technician capabilities.
- Electronic:Fully solid-state designs eliminate mechanical wear components, reducing maintenance intervals from annual to decadal cycles. Texas and Arizona utilities specify these for desert installations where airborne contaminants accelerate contact degradation in mechanical units.
- Hybrid:Combined electromechanical coarse regulation with electronic fine trimming balances cost and performance. German distribution network operators in Bavaria favor this architecture for medium-voltage feeders with mixed industrial-residential loading.
- Smart:Embedded sensors and edge computing enable autonomous voltage optimization and predictive maintenance algorithms. These units are penetrating California and New York markets where FERC Order 2222 mandates DER coordination capabilities.
Electromechanical technology holds largest installed base. Smart technology is gaining share fastest.
Installation:
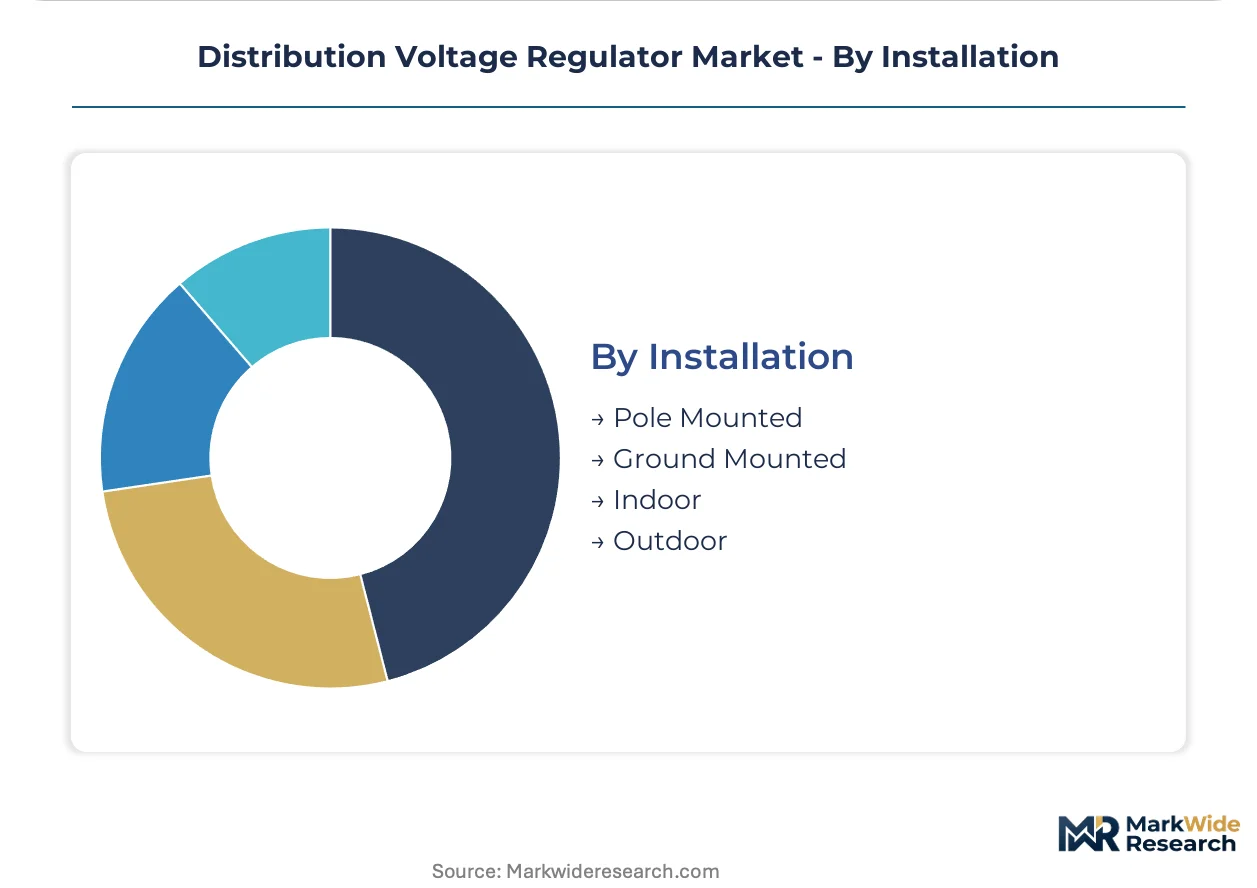
Geography determines mounting configuration, with pole-mounted units concentrating in suburban and rural feeders while ground-mounted and indoor installations cluster in dense urban infrastructure.
- Pole Mounted:Single-phase regulators suspended from distribution structures dominate US Midwest and Southern rural electrification. These units require compact form factors below 500 kg to accommodate standard utility pole load ratings.
- Ground Mounted:Pad-mounted three-phase installations serve commercial and light industrial loads in suburban Germany and France. These configurations facilitate maintenance access and thermal management in climates with seasonal temperature swings.
- Indoor:Enclosed installations protect regulators in controlled environments such as Indian urban substations and European underground distribution vaults. These specifications emphasize fire safety and reduced noise emissions.
- Outdoor:Weatherproof enclosures with IP54 minimum ratings withstand direct exposure in coastal and desert environments. Gulf Coast utilities in Florida and Louisiana specify these with enhanced corrosion protection for salt-laden atmospheres.
Pole-mounted configurations dominate installed base. Ground-mounted installations are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturers export pole-mounted regulators to rural electrification programs across Southeast Asia and Africa, while German and US suppliers dominate premium-tier utility contracts in Europe and North America. Trade corridors reflect technology stratification: solid-state units flow from East Asia to solar-rich markets, electromechanical heritage products move within regional blocs.
United States
FERC Order 2222 implementation accelerates smart regulator procurement for distributed energy resource coordination. IEEE 1547 interconnection standards mandate bidirectional power flow capabilities in California and Texas. California utilities in the Central Valley deploy silicon carbide-based static regulators to manage rapid voltage fluctuations from high rooftop solar penetration.
Germany
EU Green Deal efficiency mandates tighten no-load loss thresholds for distribution equipment replacements. IEC 60076 loading guides dictate insulation classes and testing protocols for medium-voltage network operators. Bavarian distribution network operators favor hybrid electromechanical-electronic architectures for mixed industrial-residential feeders.
China
National grid extension programs drive volume demand for cost-sensitive electromechanical pole-mounted units. MIIT efficiency standards and GB certification requirements shape product specifications for domestic procurement. Yangtze River Delta manufacturers supply compact single-phase regulators to provincial utilities in western provinces with ongoing rural electrification.
India
Village-level microgrid deployments create demand for remote-monitoring-capable pole-mounted regulators. BIS IS 2026 specifications govern insulation systems and efficiency testing for distribution transformers and associated equipment. Maharashtra and Karnataka data centers specify hybrid architectures combining mechanical reliability with electronic response speed for critical load protection.
Distribution Voltage Regulator Market Competitive Environment
Listed leaders compete with private specialists across technology tiering, with publicly traded electrical conglomerates facing focused private manufacturers in heritage electromechanical segments. Market structure consolidates around three archetypes: diversified industrial conglomerates with utility-scale project capabilities, specialized voltage control equipment manufacturers with deep regional roots, and emerging solid-state power electronics firms. Dominant competitive moves include strategic partnerships for smart grid software integration and geographic expansion through local manufacturing joint ventures.
Within the diversified conglomerate tier, Schneider Electric and Siemens AG exemplify platform-scale competitors bundling regulators with broader energy management portfolios. ABB Ltd. occupies a distinctive position bridging electromechanical heritage with digital transition roadmaps. Among specialized manufacturers, Maschinenfabrik Reinhausen GmbH and Belotti Variatori SRL represent focused European heritage in tap-changer and voltage control specialization.
| Leading Market Players |
|---|
| Schneider Electric |
| Belotti Variatori SRL |
| ABB Ltd. |
| S&C Electric Company |
| Daihen Corporation |
| Eaton Corporation |
| Siemens AG |
| Maschinenfabrik Reinhausen GmbH |
| General Electric Company |
| Others |
Value Chain & Pricing Dynamics
Silicon carbide MOSFET substitution for silicon IGBTs in static regulator designs simultaneously shifts procurement geography toward East Asian wafer foundries and compresses pricing premiums for electromechanical heritage units. This material transition rewards manufacturers with captive semiconductor sourcing while squeezing margins for legacy servo-mechanical producers dependent on copper and grain-oriented electrical steel.
Pricing Analysis
The technology-generation pricing gap separates premium smart regulators with embedded DER coordination capabilities from standard digital units and economy electromechanical designs. Three-tier pricing structure across premium, standard, and economy levels reflects certification burden divergence, with IEC 60076 and IEEE 1547 compliance adding fixed costs that scale producers absorb more efficiently. Pricing pressure stems from Chinese export competition in pole-mounted segments, particularly affecting Indian and Southeast Asian procurement. Commercial integrators sourcing through electrical distributors exhibit highest price sensitivity, while utility direct procurement prioritizes lifecycle cost and grid integration over upfront capital expenditure.
Supply Chain Analysis
The Yangtze River Delta concentration of magnetic core lamination production creates single-source vulnerability for electromechanical regulator manufacturers worldwide. Supply chains draw from China for grain-oriented electrical steel and silicon steel, Germany for precision tap-changer components, and Japan for high-grade insulating materials. Distribution runs through utility direct procurement channels for large-scale deployments and electrical distributors for commercial and residential segments. Tariff exposure on Chinese steel imports threatens margin stability for European and North American producers without alternative sourcing arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Distribution Voltage Regulator Market is approaching a platform-economics inflection as FERC Order 2222 and EU Green Deal mandates force interoperability between voltage regulation hardware and distributed energy resource management systems. This shift rewards ecosystem orchestrators over component specialists.
For Market Incumbents: Secure backward integration into silicon carbide power module production to defend margin position against emerging solid-state specialists. Incumbent electromechanical producers must accelerate hybrid architecture roadmaps before fully electronic competitors capture utility smart grid procurement. Channel control through exclusive service agreements with rural cooperatives provides defensive moats against price-aggressive Chinese exporters in the pole-mounted segment.
For New Entrants and Emerging Players: Certification fast-track partnerships with German TÜV or US UL laboratories enable rapid IEEE 1547 and IEC 60076 compliance for mid-size manufacturers lacking in-house regulatory affairs teams. White-space opportunity concentrates in Indian village-level microgrids and African rural electrification programs where remote-monitoring-capable pole-mounted units face limited competition. A software-first go-to-market bundling voltage regulation hardware with predictive analytics platforms bypasses entrenched electromechanical supply relationships.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed European tap-changer specialists holding heritage electromechanical expertise but lacking digital transition roadmaps. Long-term viability in this market hinges on smart grid software integration capabilities rather than manufacturing scale alone. The signal to watch is utility procurement contract migration toward performance-based service agreements with guaranteed power-quality outcomes, which concentrates risk with manufacturers and favors capitalized platforms over equipment-only vendors.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Power Module Integration | Enables sub-cycle voltage correction for solar-rich feeders in California and Texas utilities. |
| Smart Grid Software Platform Partnership | Links voltage regulators with DER management systems for FERC Order 2222 compliance. |
| Hybrid Electromechanical-Electronic Architecture Launch | Balances mechanical reliability with electronic response speed for German industrial-residential feeders. |
| Rural Electrification Distribution Agreement | Captures Indian village microgrid demand through regional electrical contractor networks. |
| EU Green Deal Efficiency Certification Program | Positions premium-tier regulators with 20% lower losses than IEC 60076 minimums for French and Italian utilities. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of utility procurement databases, FERC interconnection filings, and IEC certification registries. Primary interviews engaged utility planning officers, distribution network operators, electrical distributor category managers, and power electronics procurement leads at OEM manufacturers. Secondary validation incorporated EIA grid infrastructure data, EU Green Deal implementation tracking, and customs trade records for transformer and regulator components. Bottom-up unit shipment estimates triangulated against top-down utility capital expenditure disclosures.
Segmentation dimensions modeled include regulator type, application tier, technology generation, and installation configuration across the projection horizon. The analytical framework incorporated voltage-var optimization adoption curves, DER penetration rates by feeder type, and regulatory compliance timelines without year-specific assumptions. CAGRs derived from utility replacement cycle compression analysis and technology substitution elasticity estimates. Forecast inputs included copper and grain-oriented steel price volatility scenarios and smart grid interoperability standard evolution.
Decision-makers should treat outputs as directional under assumptions of continued FERC Order 2222 implementation and EU Green Deal efficiency mandate adherence; material deviation in regulatory enforcement or commodity price trajectories would warrant model refresh. Practitioners should keep alternative scenarios live as distributed energy resource penetration rates and utility procurement contract structures evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Hybrid Inverters Market
Power Systems
Medium Voltage Drives Market
Power Systems
Harmonic Generators Market
Power Systems
Space DC-DC Converters Market
Power Systems
Battery Equalizer Market
Power Systems
Telecom Power Systems Market
Power Systems
Global Fault Current Limiter Market
Power Systems
Asia Pacific Solid State Transformers Market
Power Systems
Global Rectifier Market
Power Systems
Three-Phase String Inverter Market
Power Systems
Low Voltage DC Circuit Breaker Market
Power Systems
Liquid Cooling Systems Market
Power Systems
Global Power Discrete and Modules Market
Power Systems
Shunt Capacitor Market
Power Systems
Module-Level Power Electronics (MLPE) Market
Power Systems
Europe Micro Inverter Market