
 Carrier Router Switch Market | 2026-2036
Carrier Router Switch Market Size, Share, and Industry Trends Forecast 2026-2036
Carrier Router Switch Market Outlook
Cloud service providers and hyperscale data center operators are reorganizing capital allocation toward programmable routing fabrics, displacing traditional enterprise-led buying cycles. Cisco Systems, Inc. leverages extensive ASIC design capabilities to sustain margin advantages in high-throughput platforms. Huawei Technologies Co., Ltd. anchors substantial manufacturing scale across integrated silicon-to-system operations. Juniper Networks, Inc. differentiates through specialized carrier-grade operating systems optimized for MPLS and segment routing deployments.
A carrier router switch is a high-performance packet-forwarding device engineered for terabit-scale throughput, sub-microsecond latency, and five-nines reliability in telecommunications networks; it employs custom ASICs, deep packet buffers, and redundant fabric architectures to sustain traffic engineering across multi-tenant infrastructures. The product type dimension shows high-end routers capturing concentrated R&D investment while combo devices gain traction at network edges where space and power constraints dominate. Technology segmentation reveals SDN-enabled platforms expanding fastest as carriers virtualize control planes, though MPLS retains entrenched positions in incumbent backbone estates.
The Federal Communications Commission shapes US market access through spectrum coordination and network reliability mandates, while the European Telecommunications Standards Institute enforces interoperability frameworks that constrain proprietary lock-in across EU member states. China's Ministry of Industry and Information Technology governs domestic equipment certification through GB standards and indigenous innovation directives. Stakeholders must weigh sovereign technology requirements against supply chain concentration risks when calibrating long-term platform commitments.
Market Dynamics
The carrier router switch market is experiencing fundamental restructuring as software-defined networking architectures displace purpose-built hardware procurement models. Telecom operators now prioritize programmable forwarding planes over fixed-function ASICs, compressing traditional refresh cycles and redistributing value toward software stacks and orchestration layers.
Growth Catalysts
- 5G Backhaul Requirements:Telecom operators in China are deploying multi-terabit edge nodes to support ultra-reliable low-latency communications. Massive MIMO densification mandates router upgrades at thousands of cell sites.
- Segment Routing Deployment:MPLS-SR and SRv6 protocols are simplifying traffic engineering across multi-tenant infrastructures. Carriers in Germany and Japan are standardizing on these source-routing mechanisms for backbone modernization.
- Edge Computing Workloads:Hyperscale data center operators are extending compute fabrics to metropolitan edge locations. This distributed architecture requires high-throughput switching at points of presence previously served by lower-capacity equipment.
Market Restraints
- Custom ASIC Concentration:Advanced packet-processing silicon depends on a limited foundry base concentrated in Taiwan. Geopolitical friction threatens supply continuity for terabit-scale forwarding engines.
- Copper and Substrate Costs:High-performance PCBs and thermal interface materials face input cost volatility. Router chassis manufacturing absorbs these fluctuations with limited pricing power.
- Proprietary Protocol Lock-in:Incumbent MPLS estates create technical friction against SDN migration. Carriers face stranded asset risk when transitioning control planes to open standards.
Strategic Opportunities
- Rural Broadband Subsidies:The US Infrastructure Investment and Jobs Act allocates capital for unserved connectivity. Equipment vendors can capture router-switch demand from tier-three carriers building middle-mile networks.
- AI/ML Traffic Patterns:GPU cluster interconnects are creating new demand for lossless Ethernet fabrics. Cloud operators are adopting carrier-grade switches for training workload backbones.
- India's BharatNet Expansion:The country's national optical fiber network requires aggregation routers at gram panchayat level. Domestic manufacturing incentives under PLI schemes favor local assembly partnerships.
Industry Challenges
- Control Plane Software Talent:Vendors face acute shortages of engineers proficient in P4 programming and SONiC customization. Compensation inflation for these specialized skills compresses R&D margins.
- Interoperability Certification Delays:Multi-vendor deployments require extensive testing against ETSI NFV frameworks. Extended validation cycles postpone revenue recognition for new platform introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carrier Router Switch Market |
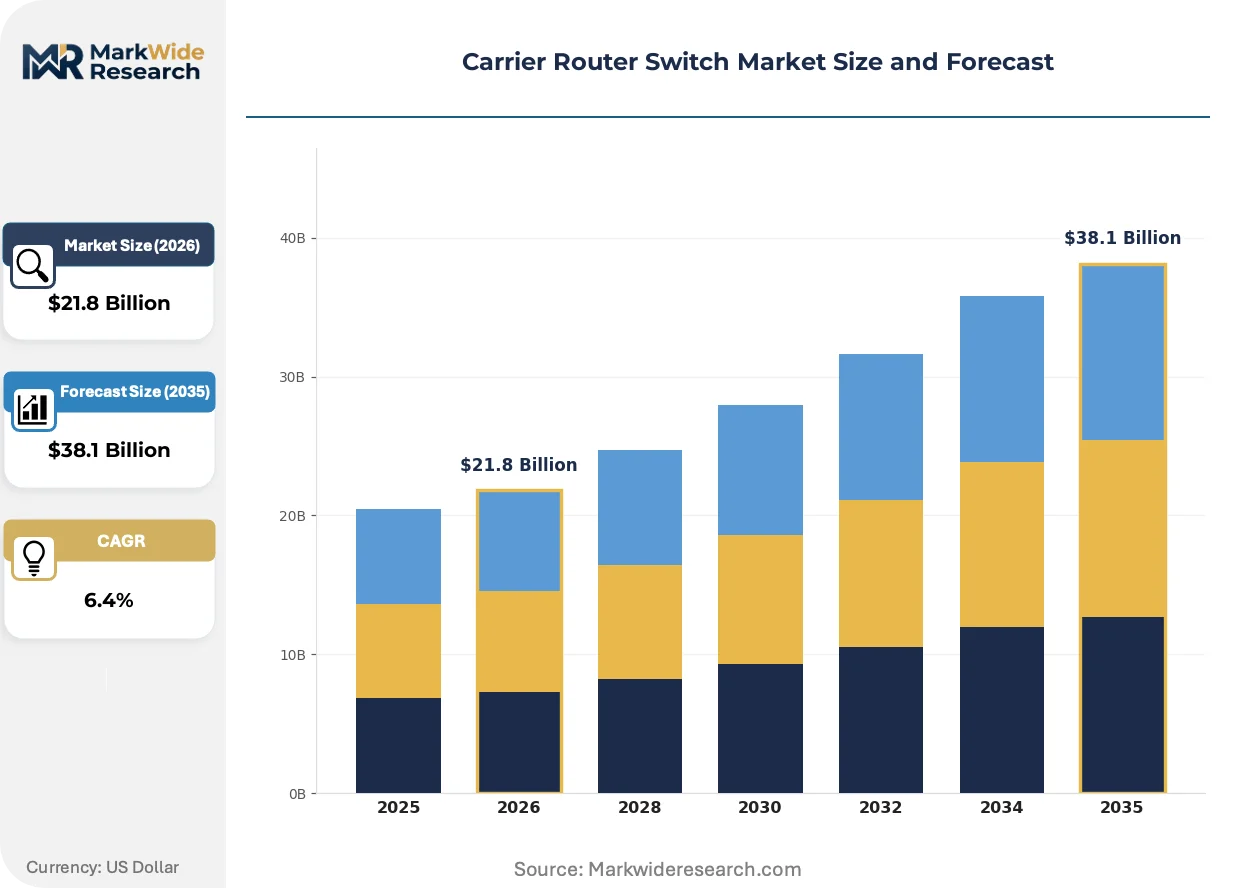
| Market Size in 2026 | $21.8 Billion |
| Market Size in 2035 | $38.1 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Router, Switch, Combo Device, High-End Router Technology: MPLS, Ethernet, IP, SDN End User: Telecom Operators, ISPs, Enterprises, Public Sector Application: Data Center, WAN, Cloud Networking, Network Virtualization |
| Companies Covered | Cisco Systems, Inc., Huawei Technologies Co., Ltd., Juniper Networks, Inc., Hewlett Packard Enterprise Company, Arista Networks, Inc., Extreme Networks, Inc., Dell Technologies, Inc., ADTRAN, Inc., Telefonaktiebolaget LM Ericsson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carrier Router Switch Market Strategic Shifts
Silicon photonics and co-packaged optics are redefining power-density constraints in high-throughput routing platforms. These physical-layer advances are enabling new form factors that challenge traditional chassis architectures.
Merchant silicon is bifurcating the high-end router market into programmable white-box platforms and vertically integrated systems. Cloud operators are adopting Broadcom and Intel Tofino-based designs for spine-leaf fabrics. This technology shift is compressing margins for traditional chassis vendors while expanding the addressable market for disaggregated software.
The European Union's CSRD mandates granular disclosure of embedded emissions in network infrastructure procurement. Equipment vendors must now provide lifecycle carbon accounting for router-switch deployments. German and French carriers are incorporating these sustainability metrics into tender evaluation criteria, favoring suppliers with circular design programs.
Hyperscale self-build programs are displacing traditional OEM channels for data center interconnect applications. Amazon Web Services and Microsoft are developing internal switching platforms through direct foundry relationships. This buyer behavior shift is most visible in the United States, where cloud capital expenditure now exceeds telecom equipment spending for high-throughput switching categories.
Carrier Router Switch Market Segmentation
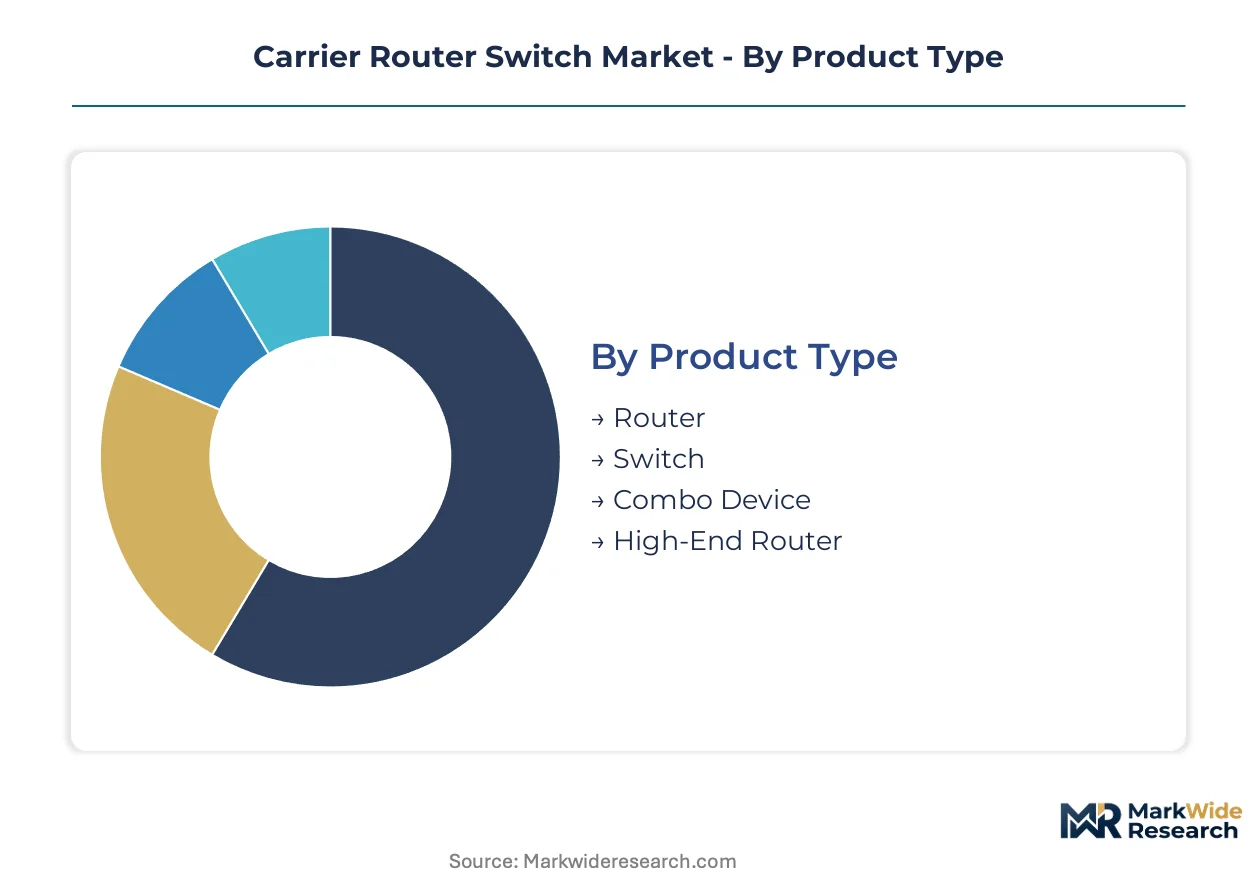
Carrier router switch procurement diverges sharply across deployment contexts, with software-defined alternatives threatening fixed-function hardware in several categories. Understanding substitution dynamics within each dimension clarifies where incumbent vendors retain pricing power versus where merchant silicon disrupts established architectures.
Product Type:
High-end routers face the most acute substitution pressure as programmable white-box platforms displace purpose-built chassis in hyperscale data centers.
- High-End Router:These systems integrate custom ASICs with terabit-scale forwarding capacity and redundant fabric architectures for five-nines reliability. Demand concentrates among tier-one carriers in China executing backbone modernization programs, though hyperscale self-build programs erode traditional OEM attachment rates.
- Combo Device:Integrated router-switch platforms combine Layer 2 switching with Layer 3 routing in space-constrained form factors. Edge computing deployments in metropolitan points of presence drive procurement, where power density constraints favor consolidated functionality over discrete appliances.
- Router:Standalone routing platforms handle inter-domain traffic engineering across autonomous system boundaries.
- Switch:High-throughput switching fabrics interconnect server clusters and storage arrays within data center environments.
High-end routers anchor the volume base while combo devices gain share at the steepest rate.
Technology:
Cost tier differentiation separates legacy protocol estates from emerging programmable control planes, with carriers weighing stranded asset risk against operational flexibility.
- SDN:Software-defined networking separates control plane intelligence from forwarding hardware, enabling centralized traffic engineering through open APIs. North American cloud operators and European telecom carriers prioritize these platforms for multi-tenant infrastructure automation, though interoperability certification delays extend procurement cycles.
- MPLS:Multi-Protocol Label Switching retains entrenched positions in incumbent backbone networks where traffic engineering policies depend on established label distribution protocols. German and Japanese carriers standardize on MPLS-SR and SRv6 extensions for source-routing simplification, preserving investment in operational expertise.
- Ethernet:Carrier-grade Ethernet switches provide cost-optimized connectivity for access aggregation and enterprise edge applications.
- IP:Native IP routing platforms handle best-effort traffic without label-switching overhead in less latency-sensitive network segments.
MPLS retains the largest installed base while SDN platforms climb the fastest among new deployments.
End User:
Customer type determines procurement sophistication, with volume concentration shifting from enterprise IT departments toward infrastructure engineering teams at cloud operators.
- Telecom Operators:National carriers and mobile network operators deploy carrier router switches across backbone, metro, and access tiers to support 5G backhaul and subscriber aggregation. China's domestic carriers execute multi-year network modernization programs under MIIT indigenous innovation directives, creating concentrated demand for high-throughput platforms.
- Hyperscale Data Center Operators:Cloud service providers reorganize capital allocation toward programmable routing fabrics, displacing traditional enterprise-led buying cycles with direct foundry relationships and internal switching platform development.
- ISPs:Internet service providers aggregate residential and business traffic at regional points of presence.
- Enterprises:Large corporations operate private WANs interconnecting geographically distributed facilities.
- Public Sector:Government networks prioritize sovereign technology requirements and supply chain security certifications.
Telecom operators anchor the volume base while hyperscale data center operators expand procurement fastest.
Application:
Deployment context dictates performance requirements, with latency-sensitive workloads commanding premium pricing against bulk transport applications.
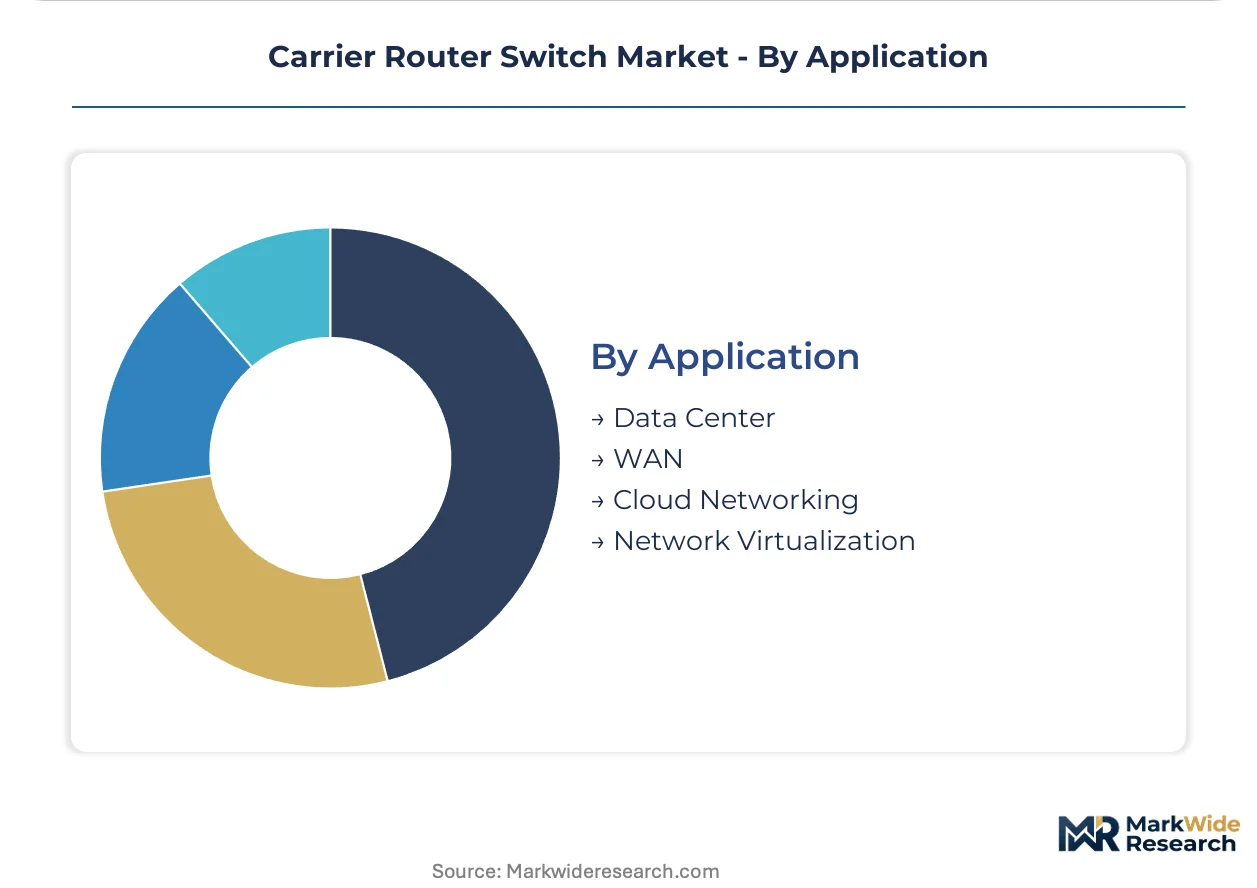
- Data Center:Spine-leaf architectures interconnect server clusters with lossless Ethernet fabrics optimized for AI/ML training workloads. GPU cluster interconnects create new demand for carrier-grade switches as cloud operators extend compute fabrics to metropolitan edge locations.
- WAN:Wide area network applications span inter-city backbones and international submarine cable landing points where sub-microsecond latency matters less than terabit-scale throughput and operational reliability.
- Cloud Networking:Virtualized network functions run on commodity hardware with software-defined control planes.
- Network Virtualization:Overlay technologies abstract physical infrastructure into logical network segments for multi-tenant isolation.
WAN applications anchor the volume base while data center deployments gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The submarine cable landing stations at Shantou and Qingdao anchor Asia-Pacific's interconnection density, while terrestrial fiber corridors across the Rhine-Ruhr and Po Valley regions sustain European backbone capacity. These infrastructure assets concentrate equipment procurement among carriers modernizing for 5G backhaul and edge computing workloads.
United States
Hyperscale data center operators in Northern Virginia and Dallas-Fort Worth drive programmable routing fabric procurement. The FCC enforces network reliability mandates through spectrum coordination frameworks. Cloud capital expenditure now exceeds telecom equipment spending for high-throughput switching categories.
China
Domestic carriers execute multi-year modernization programs under MIIT indigenous innovation directives. GB standards govern equipment certification for terabit-scale platforms. The Yangtze River Delta cluster concentrates manufacturing scale across integrated silicon-to-system operations.
Germany
Deutsche Telekom and regional carriers standardize on MPLS-SR and SRv6 protocols for backbone simplification. ETSI interoperability frameworks constrain proprietary lock-in across EU member states. The Munich-Stuttgart corridor hosts specialized engineering teams for segment routing deployments.
Japan
NTT and KDDI deploy multi-terabit edge nodes to support ultra-reliable low-latency communications for Massive MIMO densification. METI industrial policy promotes domestic equipment sourcing for critical network infrastructure. The Tokyo-Osaka corridor concentrates R&D investment in carrier-grade operating systems.
India
BharatNet expansion requires aggregation routers at gram panchayat level for national optical fiber network buildout. PLI schemes incentivize local assembly partnerships for equipment vendors. The Bengaluru-Hyderabad corridor attracts hyperscale data center investments driving edge switching demand.
Carrier Router Switch Market Competitive Environment
Concentration sits with vertically integrated systems houses and merchant silicon adopters competing for diverging procurement streams. Tier-one carriers favor custom ASIC platforms with five-nines reliability guarantees. Cloud operators prioritize programmable white-box designs with open API ecosystems. Strategic moves center on foundry partnerships for terabit-scale silicon and software stack acquisitions for orchestration layer control.
Within the integrated systems tier, Cisco Systems, Inc. and Huawei Technologies Co., Ltd. exemplify divergent geographic positioning strategies, with the former leveraging extensive ASIC design capabilities and the latter anchoring manufacturing scale across captive silicon-to-system operations. Juniper Networks, Inc. occupies a specialist position among carriers optimizing for MPLS and segment routing operational expertise. Merchant silicon disruptors including Arista Networks, Inc. represent the programmable fabric archetype gaining traction among hyperscale operators reorganizing capital allocation toward disaggregated architectures.
| Leading Market Players |
|---|
| Cisco Systems, Inc. |
| Huawei Technologies Co., Ltd. |
| Juniper Networks, Inc. |
| Hewlett Packard Enterprise Company |
| Arista Networks, Inc. |
| Extreme Networks, Inc. |
| Dell Technologies, Inc. |
| ADTRAN, Inc. |
| Telefonaktiebolaget LM Ericsson |
| Others |
Value Chain & Pricing Dynamics
GB standards and MIIT indigenous innovation directives gate equipment certification for terabit-scale platforms, simultaneously constraining supplier qualification and enabling price differentiation between domestic and import-dependent procurement streams. Tier-one carriers in China pay premiums for compliant platforms while international vendors absorb certification overhead to access concentrated demand.
Pricing Analysis
Volume-discount tiering structures separate enterprise procurement from hyperscale direct negotiations, with cloud operators extracting steeper concessions through captive silicon development. Three-tier pricing structure across premium, standard, and economy levels reflects reliability-grade differentiation, with five-nines platforms commanding substantial premiums over four-nines alternatives. Cost compression in mid-range chassis is intensifying because merchant silicon alternatives erode proprietary ASIC margins. Hyperscale data center operators exhibit lowest price sensitivity due to internal platform development options, while tier-three rural broadband carriers face acute budget constraints.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication for advanced packet-processing silicon, while China concentrates PCB substrate and chassis assembly operations. Custom ASIC production draws from TSMC foundry capacity, high-performance organic substrates, and specialized thermal interface materials. Single-source vulnerability in leading-edge node access threatens supply continuity for terabit-scale forwarding engines. Distribution runs through direct OEM relationships with tier-one carriers, supplemented by systems integrator channels for mid-market deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-defined networking architectures are disrupting procurement patterns faster than vendor R&D cycles can adapt, compressing traditional refresh timelines and redistributing value toward orchestration software stacks.
For Market Incumbents: Compound ASIC design capabilities with software stack acquisitions to defend against programmable white-box substitution. Secure foundry partnerships for advanced node access to maintain five-nines reliability differentiation. Capture rural broadband subsidy flows through tier-three carrier channel programs before merchant silicon alternatives penetrate middle-mile deployments.
For New Entrants and Emerging Players: Lead with SONiC-based disaggregated platforms targeting hyperscale data center interconnect applications where incumbent attachment rates are weakest. India's BharatNet aggregation router tier offers penetrable white-space with PLI-compliant local assembly partnerships. Pursue cloud operator proof-of-concept engagements to establish forwarding plane credibility before carrier certification cycles.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed merchant silicon specialists possessing P4 programming talent pools but limited carrier relationships. Five-to-ten year viability hinges on control plane software monetization rather than hardware margin capture. Watch for ETSI NFV interoperability certification acceleration as signal of enterprise adoption inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| ASIC-Foundry Partnership Expansion | Secures advanced node access for Cisco and Huawei against supply concentration risks. |
| SONiC Distribution Platform Acquisition | Accelerates merchant silicon adoption among cloud operators disaggregating from chassis vendors. |
| India PLI Manufacturing Localization | Captures BharatNet router demand through domestic assembly partnerships qualifying for subsidies. |
| Segment Routing Software Stack Investment | Strengthens Juniper's position as Deutsche Telekom standardizes on SRv6 protocols. |
| Silicon Photonics Co-Packaging Development | Enables Arista to challenge chassis vendors in high-density data center spine applications. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with carrier network architects, hyperscale infrastructure engineers, and optical systems procurement leads; and secondary validation against SEC 10-K filings, hyperscaler capex disclosures, and ETSI NFV framework documentation. Bottom-up equipment shipment modeling triangulated against top-down carrier capital expenditure projections across the analysis window.
Across the projection horizon, the analytical framework modeled segmentation across product type, technology protocol, end-user archetype, and application deployment context. CAGRs derived from historical shipment trajectories adjusted for 5G backhaul deployment schedules and SDN migration curves. Forecast inputs incorporated foundry capacity constraints, spectrum allocation timelines, and rural broadband subsidy program disbursement patterns.
The analysis sits within stated boundaries; outcomes outside sustained carrier capital expenditure levels or unimpeded foundry access would require recalibration. Forecasts reflect documented assumptions regarding interoperability certification timelines and merchant silicon adoption rates. Recalibration cycles align with material shifts in MIIT equipment certification directives and hyperscale self-build program announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
Timer Switch Socket Market
Switches
Proximity Switches Market
Switches
Japan Reed Sensors Switches Market
Switches
Differential Pressure Switches Market
Switches
Cross Point Switch Market
Switches
Fusible Switches Market
Switches
Middle-East and Africa Low Voltage Switchgear Market
Switches
Saudi Arabia Switchgear Market
Switches
India Switchgear Market
Switches
Global Light Control Switches Market
Switches
United States X by Wire Systems Market
Switches
Reed Switches Sensors Market
Switches
Canada Switch Gear Market
Switches
Zero Speed Switch Market
Switches
Tactile Switch Keyboard Market
Switches
DC Circuit Breaker Market