
 Diatomite Market | 2026-2036
Diatomite Market Size, Share, and Industry Trends Forecast 2026-2036
Diatomite Market Analysis
Modular packaging of diatomite filter aids by performance tier is realigning procurement patterns among mid-sized beverage processors. EP Minerals leverages its Nevada mining complex to sustain vertical integration from ore extraction to finished filter media. Imerys anchors European supply through specialized calcination facilities in France and Spain. Showa Chemical Industry Co., Ltd competes on precision grading for pharmaceutical applications, where consistency specifications exceed standard industrial thresholds.
Diatomite consists of fossilized remains of diatoms, siliceous microalgae with porous skeletal structures yielding high surface area and low bulk density, typically processed through calcination or flux calcination to enhance permeability and mechanical strength for filtration, absorption, and lightweight aggregate applications. Filter aid products dominate value generation due to irreplaceable performance in clarifying beer, wine, and edible oils, while food grade material commands premium positioning through FDA and EFSA compliance burdens that limit supplier pools. Industrial grade supply serves construction and agriculture with thinner margins, though volume throughput sustains operational scale for integrated producers.
EPA standards under the Safe Drinking Water Act and OSHA permissible exposure limits shape product formulation and workplace handling protocols for U.S.-based operations, while REACH registration requirements in Europe restrict non-compliant imports and elevate documentation costs for market participants. China's GB standards and evolving MEE environmental enforcement are tightening emission controls on calcination facilities, pressuring smaller domestic refiners toward consolidation or technology upgrades. Stakeholders must monitor regulatory divergence between jurisdictions as compliance fragmentation threatens to segment supply chains into incompatible regional specifications.
Market Dynamics
REACH registration requirements and EPA purity standards are compressing supplier pools while calcination capacity concentrates among integrated producers with captive ore reserves.
Growth Catalysts
- Filtration demand from craft breweries:Small-batch beer producers are abandoning synthetic filter aids for natural diatomite clarifying agents to meet clean-label positioning requirements.
- REACH compliance burdens:European chemical registration documentation costs are eliminating marginal importers and consolidating volume among established refiners with dedicated regulatory affairs functions.
- Flux calcination technology:Advanced high-temperature processing is yielding engineered permeability grades that command premium positioning in pharmaceutical and biotechnology separations.
Market Restraints
- Energy input cost volatility:Natural gas prices directly determine calcination economics, squeezing margin structures for producers without long-term fuel hedging arrangements.
- Nevada supply concentration:EP Minerals controls the dominant share of North American ore reserves, creating single-source vulnerability for regional filter aid consumers.
- Cellulose filter aid substitution:Modified cellulose alternatives are capturing share in low-temperature liquid filtration applications where permeability requirements are less stringent.
Strategic Opportunities
- India water treatment infrastructure:Municipal scale-up under the Jal Jeevan Mission is creating first-time specification demand for potable water filtration media.
- Carbon capture sorbent applications:Surface-modified diatomite is demonstrating capture efficiency in post-combustion gas treatment pilots at coal-fired power stations.
- Direct-to-processor e-procurement platforms:Digital marketplaces are collapsing distributor layers and enabling mid-sized beverage processors to source certified filter aids without wholesale intermediaries.
Industry Challenges
- Calcination emissions compliance:China's MEE enforcement is requiring particulate capture retrofits that strain capital reserves of family-owned refining operations.
- Food-grade certification timelines:FDA and EFSA dual compliance documentation extends new product qualification cycles to eighteen months, freezing formulation agility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diatomite Market |
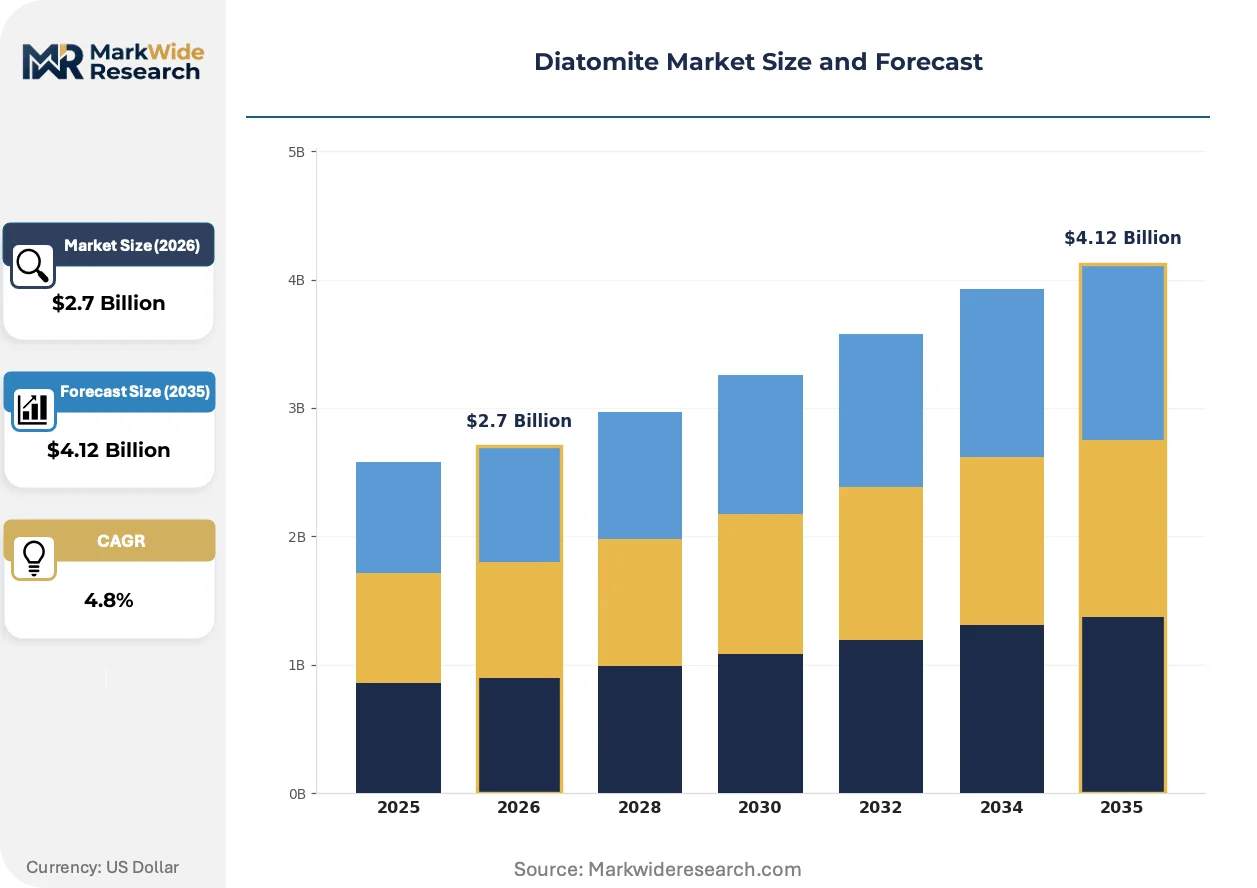
| Market Size in 2026 | $2.7 Billion |
| Market Size in 2035 | $4.12 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Industrial Grade, Filter Aid, Absorbent Application: Construction, Agriculture, Filtration, Chemical End User: Food & Beverage, Pharmaceuticals, Cosmetics, Paints Distribution Channel: Direct Sales, Online Retail, Wholesale, Distributors |
| Companies Covered | EP Minerals, Imerys, Showa Chemical Industry Co., Ltd, Dicalite Management Group, Calgon Carbon Corporation, Diatomit CJSC, Jilin Yuan Tong Mineral Co., Ltd., U.S. Silica Holdings Inc., Qingdao Best Diatomite Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diatomite Market Emerging Trajectories
Process intensification in filtration engineering and regulatory digitization are compressing product development cycles while reshaping how buyers evaluate performance specifications.
Surface functionalization chemistry is rewriting the competitive map for high-value separations. Silane-treated diatomite delivers targeted hydrophobicity for non-aqueous filtration in edible oil refining. Specialty chemical divisions at integrated miners are capturing this segment from generic filter aid distributors. The technology is rewriting margin structures by decoupling pricing from raw ore commodity indices.
REACH Article 33 disclosure obligations are forcing supply chain transparency down to mine origin. Downstream formulators must now document diatomite provenance through calcination batch records. Food and cosmetic applications face the steepest compliance cost escalation as ECHA enforcement tightens. European buyers are consolidating supplier panels to reduce audit burden.
Performance-based procurement contracts are displacing traditional volume commitments in beverage filtration. Mid-sized juice processors now specify turbidity reduction outcomes rather than filter aid tonnage. Technical service teams from refiners are embedding at customer sites to optimize dosing protocols. This shift is most advanced in Germany and the Netherlands where processor consolidation has concentrated buying power.
Diatomite Market Segmentation
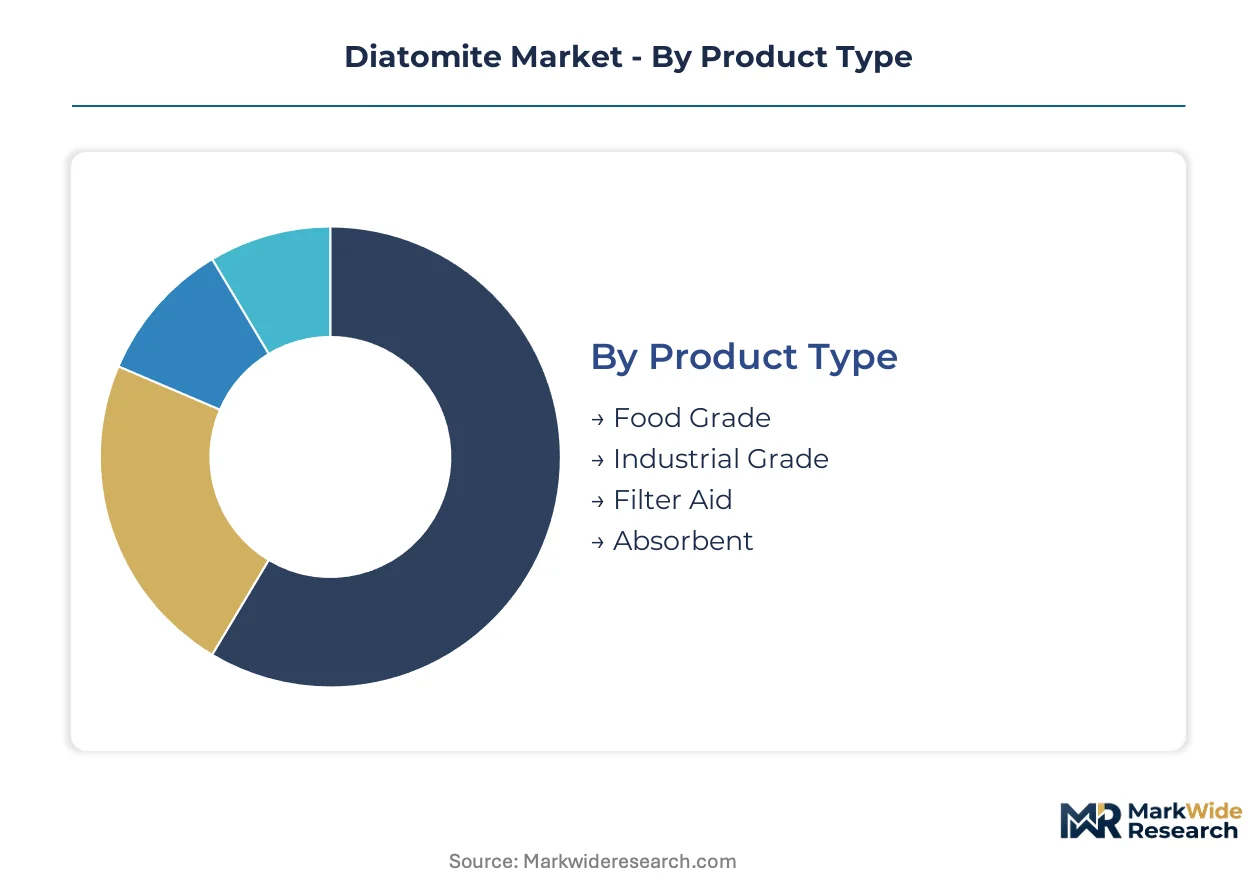
Product differentiation across purity grades and processing intensity determines pricing power and regulatory burden for diatomite suppliers. Segmentation clarity enables buyers to match filtration performance requirements with appropriate certification tiers while optimizing total cost of ownership.
Product Type:
Upgrade cycles from industrial to food-grade specifications are accelerating as processors face dual FDA-EFSA compliance audits and clean-label marketing pressures.
- Food Grade:Refined through controlled calcination to meet FDA 21 CFR 182.90 and EFSA purity thresholds for direct food contact. Breweries in Germany and edible oil refiners in Spain absorb premium pricing to secure batch consistency documentation required by ECHA Article 33 disclosure obligations.
- Filter Aid:Engineered permeability grades processed via flux calcination deliver precise particle size distributions for pharmaceutical biotechnology separations. Demand concentrates at multi-site beverage processors in the Netherlands specifying turbidity reduction outcomes rather than tonnage commitments.
- Industrial Grade:Lower-purity material serves construction lightweight aggregate and agricultural carrier applications with thinner margins sustained by volume throughput.
- Absorbent:High-porosity grades capture spills and moisture in industrial settings where regulatory compliance requirements remain minimal.
Filter Aid sits at the top of the volume ranking, with Food Grade climbing the fastest.
Application:
Cost tier stratification separates high-margin precision filtration from commodity construction and agricultural volume plays.
- Filtration:Clarifying beer, wine, edible oils, and pharmaceuticals demands irreplaceable diatomite performance characteristics. Craft breweries across the United States abandon synthetic alternatives to meet clean-label positioning requirements while absorbing technical service embedding from refiners.
- Construction:Lightweight aggregate applications in concrete and plasterboard exploit low bulk density properties. China's municipal infrastructure scale-up under evolving MEE emission controls pressures domestic calcination capacity toward consolidation.
- Agriculture:Carrier applications for pesticides and fertilizers leverage high surface area for controlled release formulations.
- Chemical:Catalyst supports and specialty chemical processing utilize surface-modified grades for targeted reactivity.
Filtration commands the steepest expansion trajectory, with Construction holding the largest installed base.
End User:
Customer type diversity spans regulated life sciences sectors with eighteen-month qualification cycles versus fast-moving consumer goods with compressed procurement timelines.
- Food & Beverage:Juice processors and breweries specify natural clarifying agents to replace synthetic filter aids. Mid-sized processors in Germany leverage direct-to-processor e-procurement platforms to collapse distributor layers.
- Pharmaceuticals:Consistency specifications exceed standard industrial thresholds, requiring precision grading and exhaustive documentation. Showa Chemical Industry captures this segment through dedicated pharmaceutical-grade production lines.
- Cosmetics:Exfoliant and absorbent applications face escalating REACH compliance burdens for provenance documentation.
- Paints:Flatting agent applications exploit diatomite's controlled particle morphology for matte finish coatings.
Food & Beverage dominates current volume, with Pharmaceuticals gaining share fastest.
Distribution Channel:
Supply concentration among integrated producers with captive ore reserves is compressing intermediary layers and reshaping procurement patterns.
- Direct Sales:Integrated miners EP Minerals and Imerys serve large-volume processors through technical service teams embedded at customer sites. Performance-based contracts specify outcomes rather than tonnage.
- Distributors:Regional wholesalers maintain inventory positions for mid-sized processors lacking volume to justify direct refiner relationships.
- Online Retail:Digital marketplaces enable certified filter aid sourcing without wholesale intermediaries, advancing fastest among mid-sized beverage processors.
- Wholesale:Traditional bulk purchasing arrangements persist in construction and agricultural segments where specification requirements remain undifferentiated.
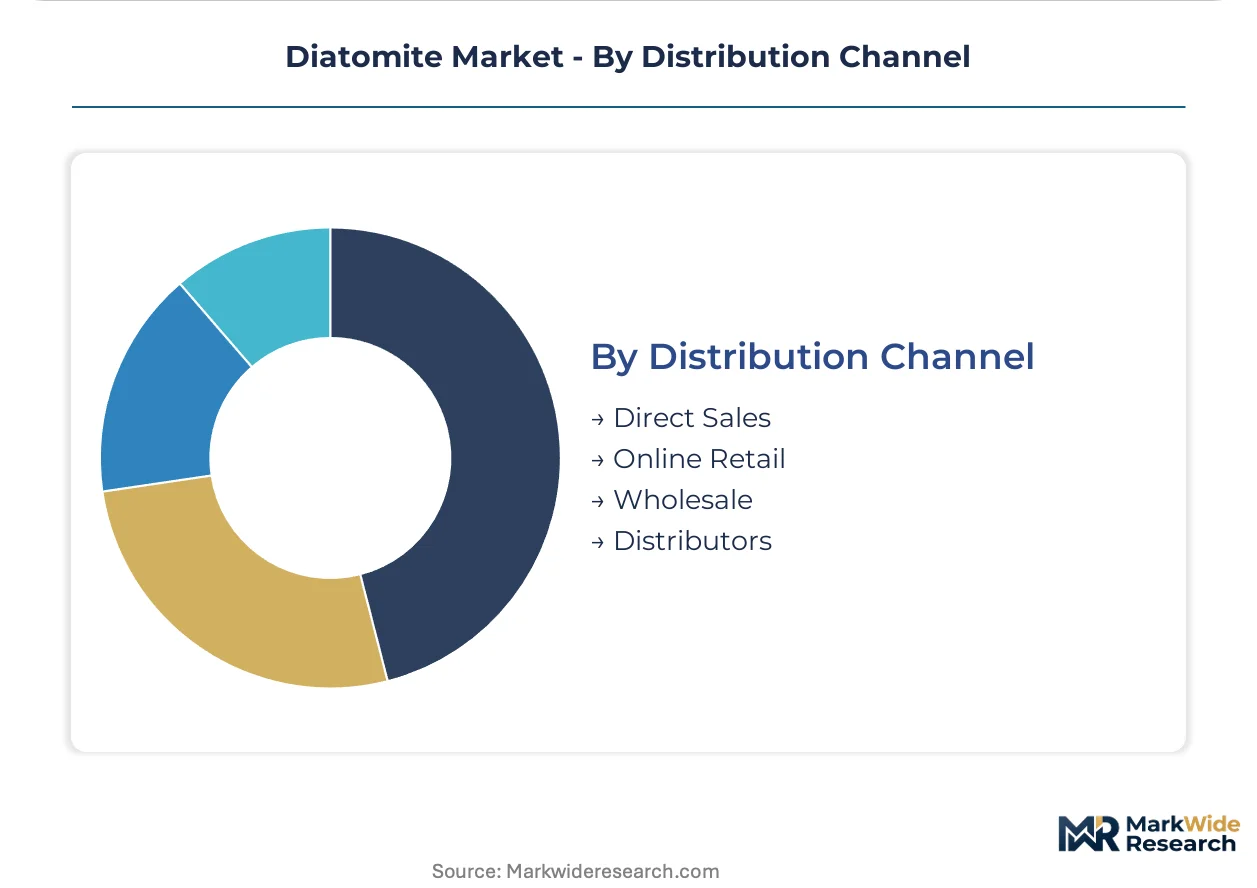
Direct Sales anchors the channel mix, with Online Retail expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diatomite mining and processing first achieved industrial scale in the United States during the early twentieth century, with Nevada deposits supplying filtration media to West Coast food processors. European calcination capabilities developed subsequently in France and Spain, while Chinese domestic production expanded rapidly after 2000 to serve construction and water treatment demand.
United States
Nevada's Lassen County hosts the dominant North American ore reserves, with EP Minerals operating integrated extraction and calcination facilities that supply breweries across California and the Pacific Northwest. EPA standards under the Safe Drinking Water Act govern filter-grade purity for potable water applications. Technical service teams from refiners embed directly at beverage processing sites in Portland and Seattle to optimize dosing protocols.
China
Domestic producers in Jilin and Shandong provinces are scaling capacity to serve municipal water treatment infrastructure and lightweight aggregate demand from construction markets. MEE environmental enforcement is tightening emission controls on calcination facilities, pressuring smaller refiners toward consolidation. Qingdao-based operations concentrate on export-grade filter aid production for Southeast Asian beverage processors.
Germany
Bavarian and Rhineland beverage clusters drive specification demand for food-grade diatomite, with mid-sized juice processors leveraging direct-to-processor e-procurement platforms. REACH Article 33 disclosure obligations force supply chain transparency down to mine origin, elevating documentation costs. Frankfurt-area technical service hubs support turbidity reduction outcome contracts rather than traditional tonnage commitments.
Japan
Showa Chemical Industry anchors pharmaceutical-grade production from dedicated facilities serving biotechnology separations with consistency specifications exceeding standard industrial thresholds. METI industrial standards shape product formulation for domestic life sciences applications. Osaka-Kobe chemical processing corridors concentrate precision grading capacity for high-value separations.
France
Imerys operates specialized calcination facilities in southern France supplying filter media to edible oil refiners in Spain and Italy. EFSA purity thresholds for direct food contact limit supplier pools and sustain premium positioning. Provence-Alpes-Côte d'Azur industrial zones host surface functionalization chemistry operations for hydrophobic grades targeting non-aqueous filtration.
Diatomite Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification tiers, with food-grade and pharmaceutical-grade specialists capturing pricing power that industrial-grade suppliers cannot match. The market structure concentrates calcination capacity among integrated producers with captive ore reserves, compressing supplier pools as REACH and EPA compliance burdens eliminate marginal participants. Two strategic archetypes dominate: vertically integrated miners controlling extraction through finished media production, and specialized refiners focusing on precision grading for regulated life sciences applications. Competitive moves center on capacity consolidation through acquisition of distressed calcination assets and technology licensing for flux calcination processes that yield engineered permeability grades.
Among the named participants, EP Minerals and Imerys occupy positions as integrated archetypes with mining-to-media control, while Showa Chemical Industry exemplifies the precision-grading specialist model. EP Minerals represents North American vertical integration anchored in Nevada ore reserves. Imerys sits within the European supply anchor position through French and Spanish calcination infrastructure. Showa Chemical Industry occupies the pharmaceutical-grade tier where consistency documentation requirements create defensive moats against commodity competition.
| Leading Market Players |
|---|
| EP Minerals |
| Imerys |
| Showa Chemical Industry Co., Ltd |
| Dicalite Management Group |
| Calgon Carbon Corporation |
| Diatomit CJSC |
| Jilin Yuan Tong Mineral Co., Ltd. |
| U.S. Silica Holdings Inc. |
| Qingdao Best Diatomite Co. Ltd. |
| Others |
Supply Flow & Price Mechanics
Food-grade certification against industrial-grade commodity positioning creates a bifurcation that manifests in both margin structures and procurement channel configurations. Premium-tier filter aid buyers in Germany and the United States absorb technical service embedding costs to secure batch consistency documentation required by ECHA Article 33 and FDA 21 CFR 182.90, while construction-grade purchasers in China negotiate spot tonnage through wholesale intermediaries with minimal provenance requirements.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels anchors the diatomite market, with food-grade and pharmaceutical-grade certifications commanding substantial premiums over industrial aggregate applications. Price differentiation rests on purity thresholds and regulatory documentation depth, with REACH-registered material from Imerys and EP Minerals sustaining margin separation from unregistered imports. Cost compression in standard-grade construction supply is intensifying because Chinese MEE emission controls are forcing calcination retrofits onto family-owned refiners. Mid-sized beverage processors in the Netherlands exhibit lowest price sensitivity due to outcome-based turbidity reduction contracts, while agricultural carrier buyers in India remain most cost-conscious.
Supply Chain Analysis
Returns and refurbishment flows are negligible in diatomite supply chains given the consumable nature of filtration media and construction aggregate applications. Geographic supply concentrates in the United States, China, and France, with Nevada's Lassen County ore reserves feeding North American demand through EP Minerals' integrated operations. Raw material dependencies center on diatomaceous earth deposits, natural gas for calcination energy input, and sodium carbonate for flux-calcination processing. Single-source vulnerability characterizes North American supply, as EP Minerals controls dominant ore reserves in Nevada. Distribution runs through direct sales relationships for large-volume processors, with e-procurement platforms collapsing distributor layers for mid-sized buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The diatomite market reads as a late-cycle quality story, justified by craft breweries and juice processors abandoning synthetic filter aids for natural clarifying agents to meet clean-label positioning requirements.
For Market Incumbents: Anticipate cellulose substitution pressure in low-temperature liquid filtration by securing flux-calcination technology licensing and embedding technical service teams at beverage processing sites. Defensive consolidation moves should target distressed calcination assets in China where MEE enforcement is pressuring family-owned refiners, while certification investment in dual FDA-EFSA compliance creates moats against unregistered imports. For New Entrants and Emerging Players: Mid-sized Indian municipal water treatment authorities under the Jal Jeevan Mission represent an underserved buyer archetype with first-time specification demand for potable water filtration media. Carbon capture sorbent pilots at coal-fired power stations offer a second white-space target, with surface-modified diatomite demonstrating capture efficiency in post-combustion gas treatment. A go-to-market angle through direct-to-processor e-procurement platforms collapses distributor layers and enables certified sourcing without wholesale intermediaries. For Investors and Strategic Acquirers: Consolidation pressure builds where calcination capacity concentrates among integrated producers with captive ore reserves, compressing supplier pools as REACH and EPA compliance burdens eliminate marginal participants. Long-term viability favors vertically integrated miners controlling extraction through finished media production over standalone refiners lacking ore security. Acquisition target archetypes include distressed Chinese calcination assets facing MEE retrofit requirements and European specialty chemical divisions with surface functionalization chemistry capabilities. The signal to watch is carbon capture sorbent application scale-up, which would rerate high-porosity engineered grades beyond traditional filtration end-uses.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ore Reserves | EP Minerals' Nevada mining complex secures captive supply against single-source vulnerability for North American buyers. |
| Flux Calcination Technology Licensing | Engineered permeability grades command pharmaceutical and biotechnology separation premiums beyond commodity filter aid pricing. |
| Surface Functionalization Chemistry Investment | Silane-treated hydrophobic grades from Provence-Alpes-Côte d'Azur facilities capture non-aqueous edible oil refining demand. |
| Direct-to-Processor E-Procurement Platform Launch | Digital marketplaces collapse distributor layers for mid-sized German juice processors specifying turbidity outcomes. |
| Dual FDA-EFSA Certification Program | Eighteen-month qualification cycles freeze formulation agility but sustain premium positioning through limited supplier pools. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant managers at integrated mining operations, procurement leads at multi-site beverage processors, technical R&D directors at specialty chemical divisions, and distribution channel partners across European filter media markets. Secondary validation drew from customs and trade data, SEC 10-K filings from U.S. Silica Holdings and Calgon Carbon Corporation, Cefic chemical industry reports, and EPA Safe Drinking Water Act regulatory filings. Bottom-up tonnage estimates by application segment were triangulated against top-down market value reconstructions.
Comparable-period anchoring established historical reference baselines across the projection horizon, with analytical frameworks modeling segmentation dimensions including grade tier, end-use industry, calcination processing intensity, and regional production hub. CAGRs were derived through regression analysis of volume trends against macroeconomic indicators and regulatory enforcement intensity. Industry-specific forecast inputs incorporated natural gas price volatility assumptions affecting calcination economics and MEE emission control compliance timelines shaping Chinese capacity rationalization.
Inputs from plant managers and procurement leads were available through the study window; gaps in real-time calcination capacity utilization data from Chinese family-owned refiners introduce uncertainty bands around near-term supply projections. Forecasts reflect assumptions regarding regulatory enforcement continuity and substitution elasticity between diatomite and cellulose filter aids. Practitioners should monitor carbon capture sorbent pilot scale-up and REACH Article 33 disclosure enforcement intensity for early signals of demand inflection and supply chain transparency cost escalation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Yttria-Stabilized Zirconia (YSZ) Market
Ceramics
Advanced Ceramics Market
Ceramics
Global Alumina Trihydrate Market
Ceramics
Heat-Resistant Ceramic Tableware Market
Ceramics
Glass Ceramics Market
Ceramics
Clay Market
Ceramics
White Fused Alumina Market
Ceramics
Automotive Ceramics Market
Ceramics
Optical Ceramics Market
Ceramics
Ceramic Sanitary Ware Market
Ceramics
Ceramic Armor Materials Market
Ceramics
Strontium Carbonate Market
Ceramics
Fly Ash and Ceramic Microsphere Market
Ceramics
Titanates Market
Ceramics
Quartz Powder Market
Ceramics
Low Density Ceramic Proppant Market