
 Automotive Ceramics Market | 2026-2036
Automotive Ceramics Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Ceramics Market Analysis
Software-defined thermal management and predictive maintenance subscriptions for ceramic components is shifting how suppliers monetize long-term vehicle relationships. CeramTec leverages its European manufacturing footprint to anchor supply contracts with premium German OEMs. KYOCERA Corporation competes through deep specialization in piezoelectric ceramics for precision engine applications. NGK Spark Plug sustains its position via dominant control over ceramic substrate production for exhaust aftertreatment systems.
Automotive ceramics encompass oxide, non-oxide, and composite ceramic materials engineered to withstand thermal shock above 1,000°C, corrosive exhaust environments, and mechanical stress in powertrain assemblies. These materials function primarily as thermal barriers, wear-resistant surfaces, and electrical insulators that enable higher combustion efficiencies and extended component lifespans. Ceramic brake discs within the product type dimension command premium positioning due to extreme heat dissipation requirements in performance and commercial vehicles. Advanced ceramics technology leads structural growth as silicon carbide and alumina formulations displace metal alloys in electrified powertrains. The OEM end user channel concentrates margin pools through multi-year platform contracts, while aftermarket providers occupy fragmented, price-sensitive replacement demand.
EPA tailpipe standards, Euro 7 emissions frameworks, and China's GB standards collectively mandate ceramic material upgrades for catalytic converters, diesel particulate filters, and thermal barrier coatings. NHTSA braking performance requirements and ECE R90 regulations further specify ceramic composition thresholds for friction materials in commercial and passenger applications. Stakeholders must monitor regulatory divergence between emissions-focused jurisdictions and safety-centric markets to align R&D portfolios with divergent certification pathways.
Market Dynamics
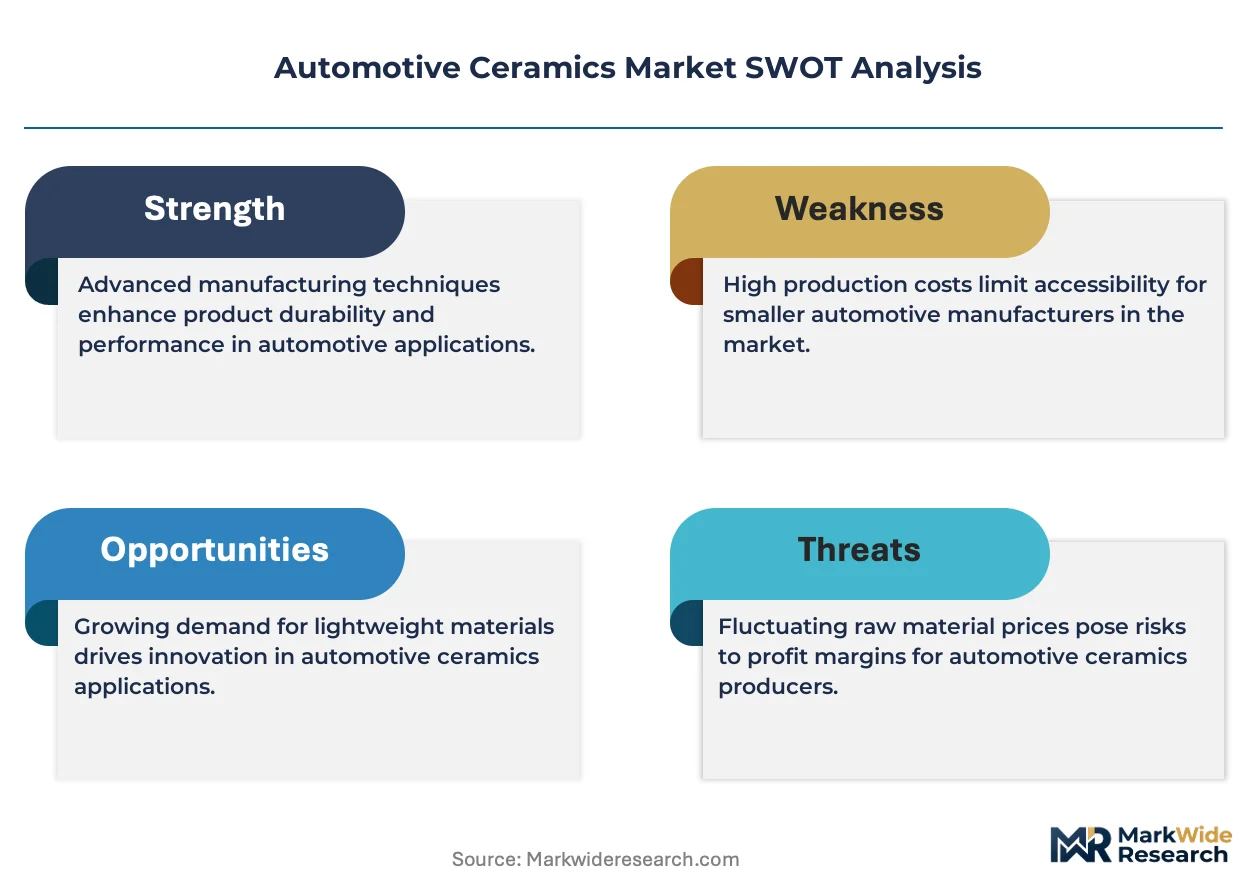
EPA tailpipe standards and Euro 7 emissions rules are forcing ceramic material upgrades across catalytic converters, diesel particulate filters, and thermal barrier coatings, compressing supplier development timelines while opening multi-year platform contracts for compliant formulations.
Growth Catalysts
- Emissions Rule Stringency:Euro 7 frameworks mandate higher-performance ceramic substrates in exhaust aftertreatment systems, pulling demand for silicon carbide and alumina formulations that withstand thermal shock above 1,000°C.
- German Manufacturing Clusters:Precision ceramics production concentrated in Stuttgart and Munich anchors supply contracts with domestic premium OEMs, creating captive demand pools for brake disc and engine component suppliers.
- Electrified Powertrain Penetration:Battery electric and hybrid architectures require ceramic thermal barriers and electrical insulators that metal alloys cannot provide, expanding addressable component sets per vehicle platform.
Market Restraints
- Raw Material Concentration:High-purity alumina and silicon carbide feedstocks concentrate among limited specialty chemical suppliers, exposing processors to input cost volatility and qualification delays.
- Energy-Intensive Sintering:Ceramic component production requires sustained furnace temperatures exceeding 1,600°C, locking in elevated energy costs that compress margins when electricity prices spike.
- Substitution by Advanced Metals:Powder metallurgy and superalloy formulations in lower-temperature engine zones compete for share in cost-sensitive vehicle segments, capping ceramic penetration in economy-class platforms.
Strategic Opportunities
- Software-Defined Thermal Management:Predictive maintenance subscriptions for ceramic brake and engine components enable recurring revenue streams that extend supplier monetization beyond initial hardware sales.
- India Vehicle Production Expansion:Domestic OEM assembly growth under the PLI scheme creates demand for ceramic catalytic substrates and sensors in a market where local ceramic processing capacity remains underdeveloped.
- Solid-State Battery Integration:Ceramic electrolyte and separator technologies converge with next-generation battery architectures, opening new application categories outside traditional powertrain ceramics.
Industry Challenges
- Specialized Ceramics Engineering Talent:The intersection of materials science and automotive powertrain engineering creates a shallow labor pool, extending recruitment timelines for R&D and manufacturing roles.
- Multi-Jurisdiction Certification Complexity:Divergent EPA, ECE R90, and GB standard testing protocols force redundant validation cycles that delay product launches by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Ceramics Market |
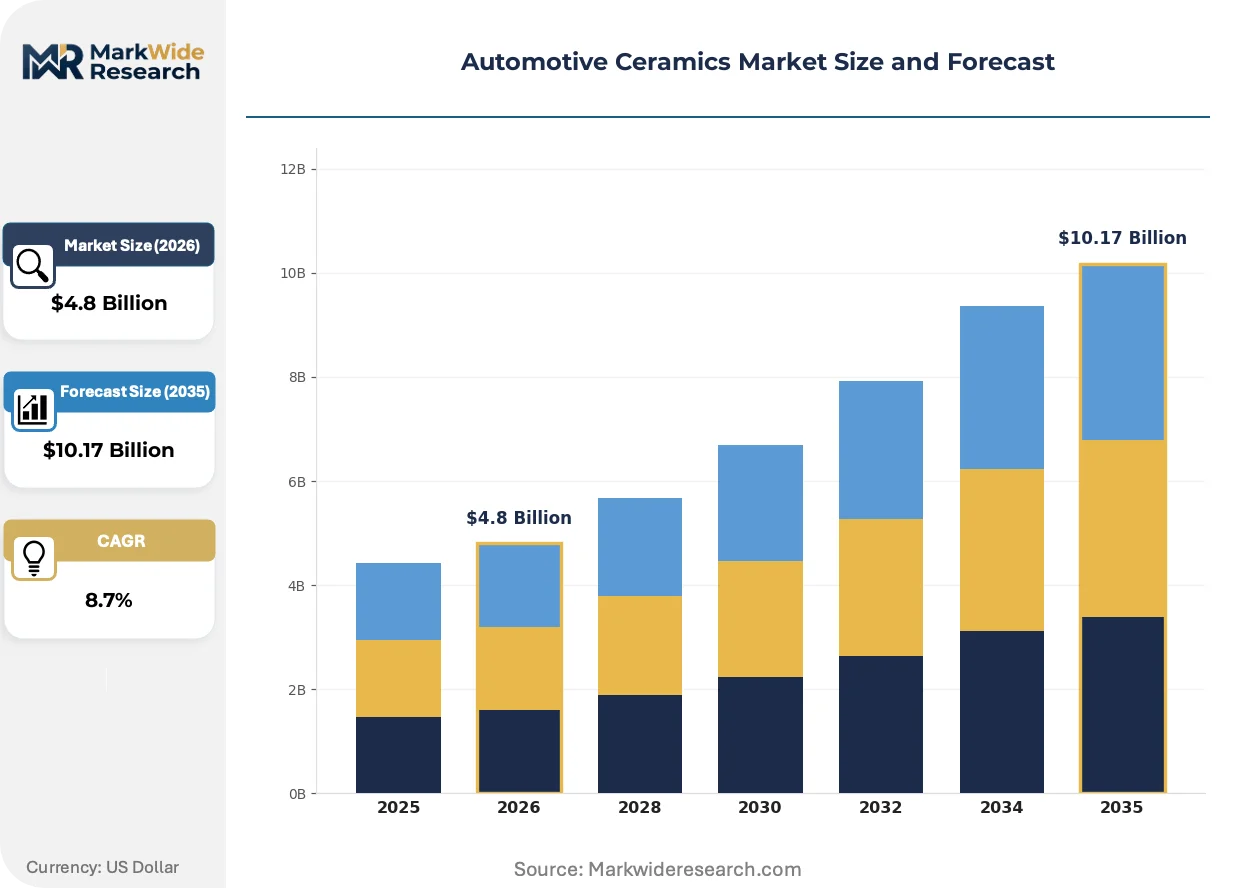
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ceramic Brake Discs, Engine Components, Exhaust Components, Insulators Application: Braking Systems, Engine Systems, Thermal Barriers, Electrical Insulation Technology: Advanced Ceramics, Traditional Ceramics, Composite Ceramics, Bio-Ceramics End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | CeramTec, KYOCERA Corporation, NGK Spark Plug, CoorsTek, Corning Incorporated, Morgan Advanced Materials, IBIDEN, Saint-Gobain Ceramics, Ceradyne, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Ceramics Market Emerging Trajectories
Digitalization of component lifecycle management and convergence of ceramics with electrified architectures are restructuring how suppliers capture value and how OEMs specify material systems.
Additive manufacturing of ceramic matrix composites is automating the production of geometrically complex thermal barrier components that conventional pressing and sintering cannot achieve. Tier-1 suppliers in Germany and Japan are piloting these processes for next-generation turbine housings and brake disc cores. The technology is automating quality consistency and lead time compression in made-to-order ceramic fabrication.
REACH substance restrictions and the EU Green Deal's embodied carbon reporting requirements are forcing reformulation of ceramic binders and sintering aids. Manufacturers must document supply chain emissions and eliminate legacy flux materials that fail Substance of Very High Concern thresholds. The catalytic converter segment faces the steepest compliance burden as substrate producers requalify entire material sets.
Direct supplier-OEM platform contracting is displacing traditional tiered purchasing structures for critical ceramic components. Brake disc and thermal management system makers now negotiate multi-year sole-source agreements that bundle hardware, predictive analytics, and replacement scheduling. This pattern concentrates most visibly in the United States where EPA durability requirements extend component liability windows and favor integrated supplier relationships.
Automotive Ceramics Market Segmentation
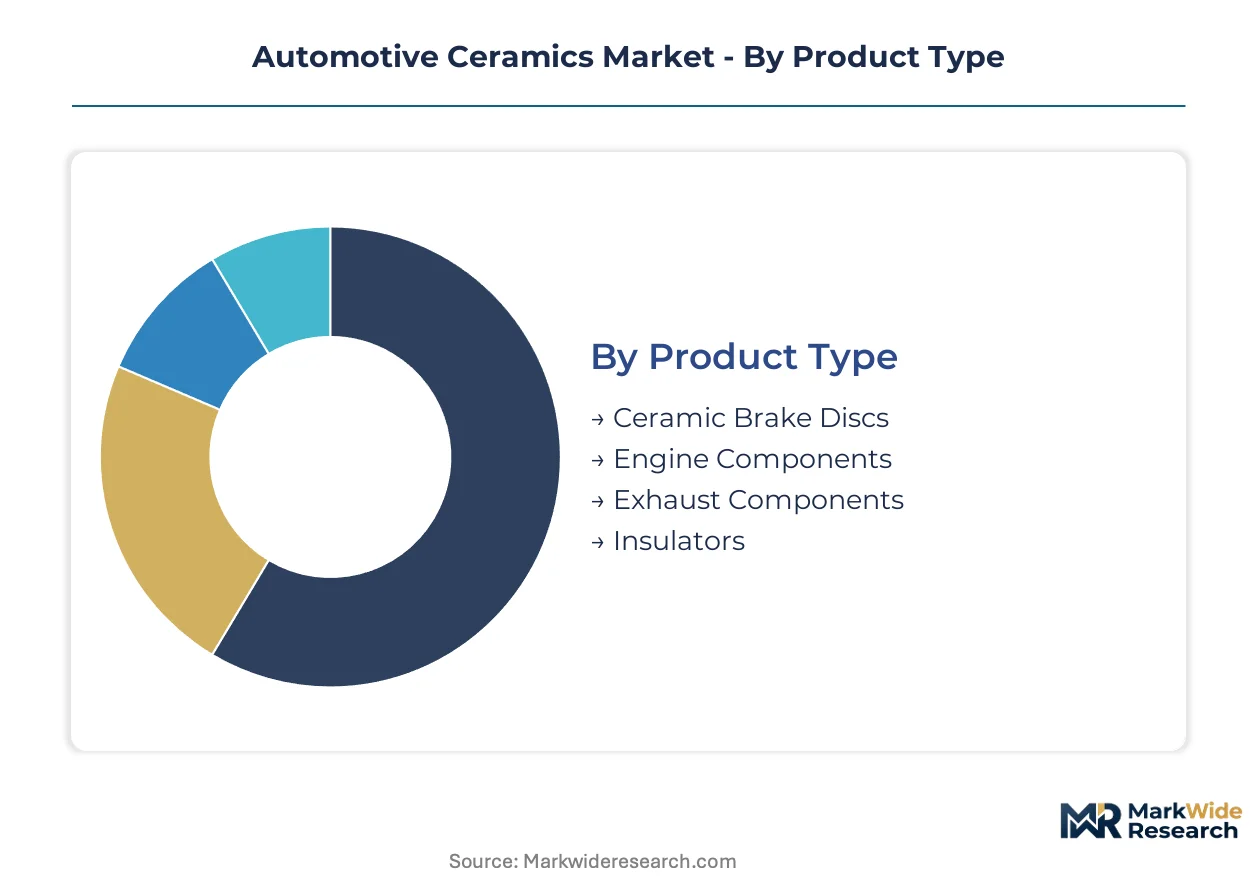
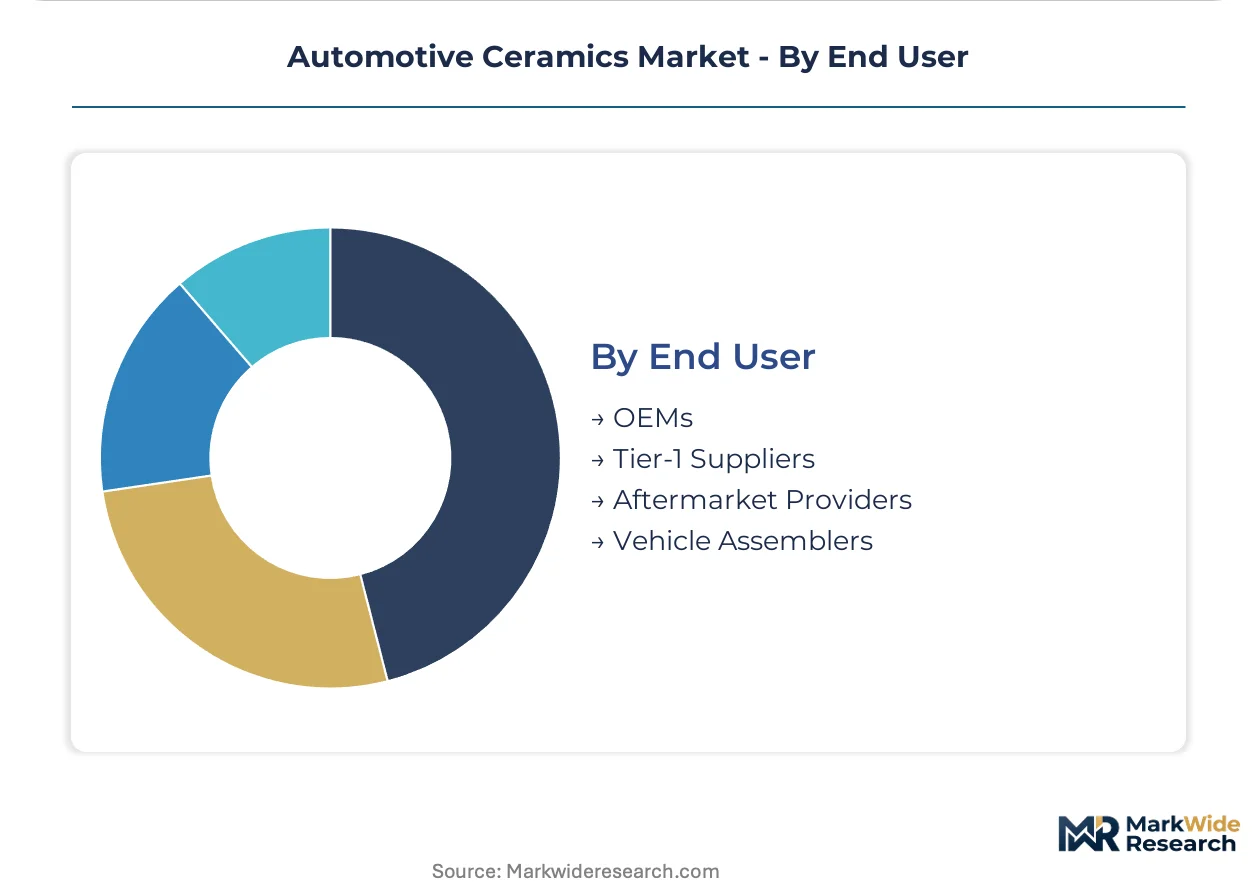
Automotive ceramics segmentation reflects divergent thermal, mechanical, and electrical performance requirements across powertrain architectures. Material selection and channel strategy vary sharply by component function and regulatory exposure, creating distinct margin pools within each dimension.
Product Type:
Specification intensity separates segments by operating temperature thresholds and wear resistance demands.
- Ceramic Brake Discs:Silicon carbide and carbon-ceramic matrix composites withstand sustained temperatures exceeding 1,000°C during high-performance braking events. German premium OEMs in Stuttgart and Munich anchor procurement for performance and commercial vehicle platforms where NHTSA braking performance requirements mandate thermal durability.
- Engine Components:Thermal barrier coatings and valve train ceramics enable higher combustion efficiencies in downsized turbocharged engines. Japanese precision manufacturing clusters in Aichi Prefecture concentrate demand for alumina-zirconia formulations that reduce heat rejection and extend component lifespans under Euro 7 thermal stress requirements.
- Exhaust Components:Cordierite and silicon carbide substrates form catalytic converter and diesel particulate filter cores mandated by EPA tailpipe standards.
- Insulators:Alumina and steatite compositions isolate high-voltage systems in hybrid and electric powertrains.
Ceramic brake discs lead on scale; engine components lead on momentum.
Application:
Functional role in vehicle energy management determines material specification and contract duration.
- Braking Systems:Friction materials and disc substrates must satisfy ECE R90 regulations for commercial vehicle certification. Japanese and German OEMs specify carbon-ceramic formulations for weight reduction in electric vehicle platforms where regenerative braking extends conventional friction component intervals.
- Engine Systems:Piston crowns, cylinder liners, and turbocharger housings employ ceramic coatings to manage thermal loads. Detroit-based powertrain engineering centers drive specification for thermal spray barrier coatings that enable higher compression ratios without metallurgical failure.
- Thermal Barriers:Exhaust manifold and turbine housing insulation reduces underhood temperatures and enables lightweight aluminum adjacent components.
- Electrical Insulation:Battery pack separators, busbar housings, and inverter substrates require dielectric ceramics with breakdown resistance above 15 kV/mm.
Braking systems command the largest contract values; electrical insulation is climbing the fastest as electrification accelerates.
Technology:
Processing complexity and raw material purity create tiered performance and cost structures.
- Advanced Ceramics:Silicon carbide, silicon nitride, and transformation-toughened zirconia achieve properties unobtainable in conventional ceramics. German specialty manufacturers in Bavaria lead production of pressureless-sintered silicon carbide for exhaust substrates and electric drivetrain thermal management.
- Traditional Ceramics:Alumina, steatite, and cordierite serve cost-sensitive applications with moderate thermal and mechanical demands. Japanese producers in Nagoya maintain scale advantages in alumina insulators for ignition systems and sensor housings.
- Composite Ceramics:Ceramic matrix composites with carbon or silicon carbide fiber reinforcement enable complex geometries via additive manufacturing.
- Bio-Ceramics:Hydroxyapatite and bioglass formulations serve niche medical-automotive crossover applications in racing safety equipment.
Advanced ceramics dominate revenue concentration; composite ceramics show steepest expansion trajectory from technology maturation.
End User:
Procurement authority and liability exposure shape supplier relationship structures and pricing mechanisms.
- OEMs:Volkswagen, Toyota, and Ford negotiate multi-year platform contracts that bundle hardware, predictive analytics, and replacement scheduling. Direct supplier-OEM contracting concentrates in the United States where EPA durability requirements extend component liability windows and favor integrated relationships over tiered purchasing.
- Tier-1 Suppliers:Bosch, Denso, and Continental specify ceramics for subsystem integration into braking, exhaust, and thermal management modules. These intermediaries aggregate demand across multiple OEM platforms and manage qualification burden for specialized ceramic formulations.
- Aftermarket Providers:Fragmented distributors and service networks occupy replacement demand for wear components, competing primarily on price and availability rather than technical specification.
- Vehicle Assemblers:Contract manufacturers and emerging electric vehicle specialists procure ceramics through specification delegation to tier-1 partners.
OEMs lead on contract scale; tier-1 suppliers lead on specification influence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping where automotive ceramics production locates, with manufacturers migrating toward jurisdictions offering streamlined certification pathways and concentrated OEM demand pools.
United States
EPA tailpipe standards and NHTSA braking performance requirements drive specification intensity for ceramic substrates and friction materials. Detroit-based powertrain engineering centers anchor procurement for thermal barrier coatings in commercial vehicle platforms. Domestic OEMs negotiate multi-year sole-source agreements that bundle hardware with predictive maintenance subscriptions.
Germany
Precision ceramics manufacturing clusters in Stuttgart and Munich serve premium OEM assembly operations with silicon carbide brake discs and exhaust substrates. Euro 7 emissions frameworks mandate higher-performance formulations that withstand thermal shock above 1,000°C. KBA certification protocols create entry barriers that favor established Bavarian specialty producers.
Japan
Aichi Prefecture and Nagoya-based manufacturing networks concentrate demand for alumina-zirconia engine components and piezoelectric ceramics. METI industrial policy supports domestic supply chain resilience for critical automotive materials. Japanese OEMs specify ceramic thermal management systems for hybrid and battery electric platforms where regenerative braking extends component intervals.
China
GB standards for emissions and vehicle safety create parallel certification requirements that domestic ceramic processors must satisfy. Yangtze River Delta manufacturing bases supply catalytic converter substrates for both domestic OEMs and export markets. MIIT technology roadmaps prioritize silicon carbide and alumina formulations in electrified powertrain development.
India
PLI scheme incentives for domestic vehicle assembly are pulling demand for ceramic catalytic substrates and sensors. Local ceramic processing capacity remains underdeveloped relative to accelerating OEM platform launches. Maharashtra and Gujarat industrial corridors are emerging as procurement hubs where tier-1 suppliers aggregate demand across multiple vehicle segments.
Automotive Ceramics Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated positions in exhaust substrates contrasting fragmented competition in aftermarket brake components. Three archetypes dominate: integrated material-science conglomerates with captive ceramics divisions, pure-play automotive ceramic specialists, and diversified industrial ceramic houses serving multiple end-markets. Capacity expansion and direct supplier-OEM platform contracting represent the dominant competitive vectors, displacing traditional tiered purchasing structures.
Among European precision ceramic specialists, CeramTec GmbH and Saint-Gobain Ceramics occupy positions anchored by proximity to German OEM engineering centers. KYOCERA Corporation exemplifies the integrated conglomerate archetype, leveraging deep specialization across piezoelectric and structural ceramic formulations. These three entities represent distinct strategic postures: regional supply chain anchoring, materials science breadth, and vertical integration into automotive-specific component systems.
| Leading Market Players |
|---|
| CeramTec |
| KYOCERA Corporation |
| NGK Spark Plug |
| CoorsTek |
| Corning Incorporated |
| Morgan Advanced Materials |
| IBIDEN |
| Saint-Gobain Ceramics |
| Ceradyne |
| Others |
Supply Flow & Price Mechanics
Premium German OEM procurement offices in Stuttgart and Munich command contract-based long-term offtake agreements that bundle ceramic brake discs and thermal management hardware with predictive maintenance subscriptions. This buyer concentration anchors pricing power with suppliers who qualify through KBA certification protocols, while tier-1 intermediaries aggregate volume across multiple platforms to extract standard-tier pricing.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for cordierite and silicon carbide exhaust substrates. Three-tier pricing structure across premium, standard, and economy levels separates carbon-ceramic brake discs certified to ECE R90 from alumina insulators for ignition systems and commodity cordierite catalytic converter cores. Price differentiation hinges on thermal shock resistance certification above 1,000°C and volume scale commitments. Margins are tightening due to energy-intensive sintering costs; aftermarket distributors exhibit highest price sensitivity while OEM sole-source contracts show lowest.
Supply Chain Analysis
Multi-jurisdiction certification complexity gates supply chain participation, with KBA protocols in Germany, EPA durability requirements in the United States, and GB standards in China creating redundant qualification cycles. Geographic supply concentrates in Germany, Japan, and the United States where precision ceramics clusters feed domestic vehicle assembly. Raw material dependencies draw from high-purity alumina refiners, silicon carbide specialty chemical suppliers, and rare earth stabilizer processors. Single-source vulnerability runs through limited silicon carbide feedstock qualification. Distribution runs through tier-1 subsystem integrators who manage OEM platform contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive ceramics function as a stable compounder anchored by regulatory mandates for emissions compliance and thermal durability that sustain replacement demand across vehicle lifecycles.
For Market Incumbents: Anchor multi-year platform contracts with predictive maintenance bundling to lock in OEM switching costs against emerging additive manufacturing specialists. Defend position by deepening backward integration into high-purity alumina and silicon carbide feedstocks, reducing exposure to specialty chemical supplier concentration. Prioritize certification investment for Euro 7 and EPA tailpipe standard compliance to maintain KBA and regulatory qualification barriers. For New Entrants and Emerging Players: The gap between premium carbon-ceramic brake discs and economy-class alumina insulators creates entry space for mid-tier silicon nitride formulations in hybrid thermal management systems. Target India's PLI scheme vehicle production expansion where local ceramic processing capacity lags accelerating OEM platform launches. Pursue joint development agreements with tier-1 subsystem integrators to bypass direct OEM qualification timelines. For Investors and Strategic Acquirers: Tier-1 automotive subsystem integrators are the most active acquirer in this space, seeking captive ceramic supply for electrified powertrain thermal management. Five-to-ten year viability rests on solid-state battery ceramic electrolyte convergence and software-defined vehicle component lifecycle monetization. Signal to watch: direct supplier-OEM platform contracting displacement of tiered purchasing structures in the United States and Germany.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstocks | Captive supply of high-purity alumina reduces silicon carbide supplier concentration risk. |
| Software-Defined Thermal Management Launch | Predictive maintenance subscriptions for ceramic brake components extend monetization beyond hardware sales. |
| Euro 7 Certification Investment | KBA qualification for silicon carbide substrates above 1,000°C thermal shock anchors German OEM supply. |
| India PLI Scheme Manufacturing Footprint | Maharashtra and Gujarat capacity addresses domestic ceramic processing gaps under vehicle assembly incentives. |
| Solid-State Battery Ceramic Electrolyte Partnership | Next-generation battery separator technology opens application categories outside traditional powertrain ceramics. |
Methodological Framework
Bottom-up OEM procurement modeling reconciled against top-down precision ceramics production tracking forms the analytical core. Primary interviews with tier-1 supplier procurement directors, OEM platform engineers, aftermarket distribution heads, and thermal management R&D leads combine with secondary validation from vehicle production databases, IHS Markit registration data, EPA certification filings, and KBA type-approval records. Triangulation across these sources anchors volume and value estimates.
Historical trendline analysis of ceramic content per vehicle by propulsion architecture informs the projection framework. Segmentation dimensions span product type, application function, technology tier, and end-user channel across the analysis window. CAGRs derive from regression against regulatory mandate implementation schedules and electrified powertrain penetration curves. Industry-specific inputs include Euro 7 thermal stress requirements and NHTSA braking performance thresholds.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery ceramic electrolyte integration would alter the outlook. Forecasts reflect assumptions regarding EPA and Euro 7 enforcement timelines, silicon carbide feedstock qualification rates, and OEM direct contracting preferences. A model refresh is warranted upon material change in emissions rule stringency or solid-state battery commercialization velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
GCC Ceramic Tiles and Sanitary Ware Market
Ceramics
Ceramic Sanitary Ware Market
Ceramics
Cordierite Market
Ceramics
East Africa Ceramic Tiles Market
Ceramics
Taiwan Ceramic Tiles Market
Ceramics
Wollastonite Market
Ceramics
Vaterite Market
Ceramics
South Korea Ceramic Tiles Market
Ceramics
Calcium Aluminosilicate Market
Ceramics
Ceramic Injection Molding Market
Ceramics
Activated Alumina Market
Ceramics
UAE Ceramic Tiles Market
Ceramics
2N High Purity Alumina Market
Ceramics
North America Ceramic Coatings Market
Ceramics
Calcite Market
Ceramics
Advanced Sintering Technologies Market