
 Flatting Agents Market | 2026-2036
Flatting Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Flatting Agents Market Foresight
Specialized silica synthesis expertise is collapsing across Western Europe, forcing coating formulators to rely on a shrinking pool of qualified suppliers. Evonik Industries AG leverages its integrated precipitated silica network to secure raw material continuity for automotive flatting grades. PPG Industries anchors North American supply through captive technical service teams that co-develop matte finishes with OEM specification engineers. Huntsman Corporation differentiates via urethane-based flatting agents that serve industrial maintenance coatings requiring chemical resistance.
Flatting agents are finely dispersed inorganic or organic particles, typically silica or synthetic wax with particle sizes between 2 and 15 micrometers, that scatter incident light at coating surfaces to reduce gloss readings. Manufacturers engineer these additives through precipitation, gelation, or controlled grinding to achieve targeted Hegman fineness and consistent matting efficiency across solventborne and waterborne vehicles. Waterborne formulations now lead volume as architectural and automotive OEM buyers enforce low-VOC compliance, while radiation-cured systems represent the fastest-expanding margin pool due to their premium positioning in furniture and flooring applications. Urethane-based agents sustain above-average pricing power in marine and protective coatings where durability specifications resist commoditization.
The EPA enforces VOC content limits under 40 CFR Part 59 that directly constrain solventborne flatting agent selection in US architectural coatings. ECHA administers REACH registration requirements that burden imported silica additives with extensive toxicity dossiers, reshaping supplier qualification timelines for European paint manufacturers. China's MEE implements dual carbon targets that pressure domestic coating plants to shift from solventborne to powder and waterborne systems, altering regional flatting agent specification patterns. Stakeholders must monitor regulatory divergence across these jurisdictions to anticipate reformulation cycles and qualify alternative matting technologies before specification lock-in.
Market Dynamics
Automotive OEMs are consolidating matte-finish specifications across interior trim programs, forcing coating formulators to secure silica supply chains capable of delivering consistent Hegman fineness at industrial scale.
Growth Catalysts
- REACH VOC limits:ECHA's tightening thresholds on solventborne coatings are accelerating waterborne flatting agent adoption across European architectural and industrial maintenance segments.
- Automotive interior matting:Low-gloss finishes for dashboard and door panel applications are expanding procurement volumes from tier-one coating suppliers serving German and US assembly plants.
- Radiation-cured furniture coatings:UV-curable systems incorporating synthetic wax flatting agents are capturing premium positioning in North American and European flooring applications.
Market Restraints
- Precipitated silica supply concentration:Western European synthesis expertise has contracted to a handful of qualified suppliers, creating raw material continuity risks for specialty coating formulators.
- Energy-intensive production:Thermal processing of gel silicas requires sustained natural gas or electricity inputs, exposing margin structures to regional energy price volatility.
- Polyurethane dispersion substitution:Self-matting urethane resins are displacing separate flatting agent additions in select marine and protective coating formulations.
Strategic Opportunities
- China's dual carbon targets:MEE enforcement is pressuring domestic coating plants toward powder and waterborne systems, opening specification windows for low-VOC flatting technologies.
- Marine coating durability premium:Urethane-based flatting agents command above-commodity pricing in shipyard maintenance programs where chemical resistance specifications resist standardization.
- Digital color matching integration:Co-development partnerships between additive suppliers and OEM specification engineers are collapsing traditional technical service timelines.
Industry Challenges
- Silica particle engineering talent:Specialized expertise in controlled precipitation and gelation processes is aging out of Western European chemical workforces without adequate replacement pipelines.
- REACH dossier burden:ECHA registration requirements for imported silica additives are extending supplier qualification timelines by 18-24 months, freezing specification decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flatting Agents Market |
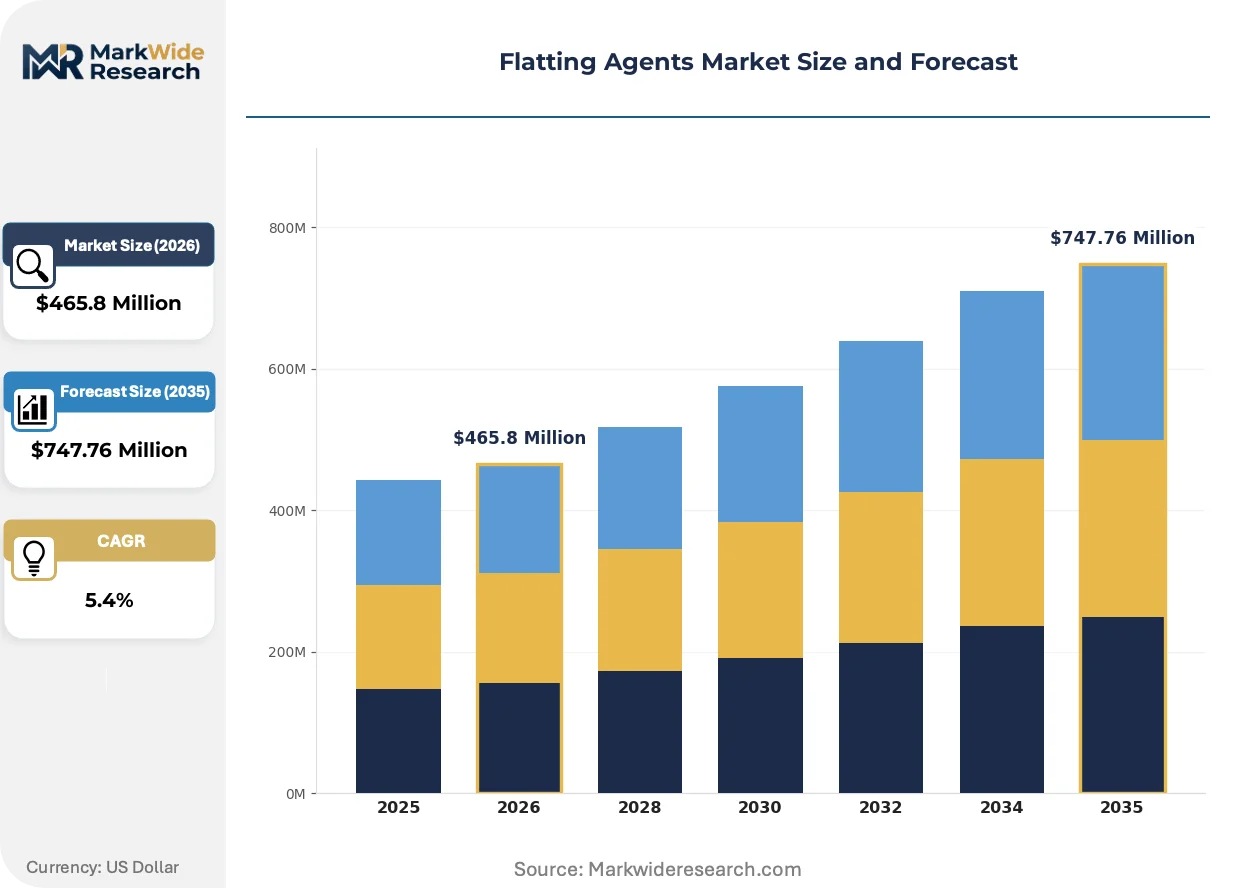
| Market Size in 2026 | $465.8 Million |
| Market Size in 2035 | $747.76 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alkylated Flatting Agents, Modified Silicone, Acrylate-Based Agents, Urethane-Based Agents, Others Application: Architectural Coatings, Automotive Finishes, Industrial Coatings, Protective Coatings, Marine Finishes End User: Paint Manufacturers, Automotive OEMs, Furniture Producers, Industrial Equipment Makers, Construction Firms Formulation Type: Waterborne, Solventborne, Powder Coatings, Radiation Cured, UV Curable |
| Companies Covered | Evonik Industries AG, PPG Industries, Huntsman Corporation, J.M. Huber Corporation, BYK Additives & Instruments, Baltimore Innovations, W. R. Grace & Co., Imerys, PQ Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flatting Agents Market Shifts & Advancements
Reformulation cycles are compressing as regulatory deadlines and OEM sustainability mandates force simultaneous transitions across solventborne, waterborne, and radiation-cured coating platforms.
Surface-treated precipitated silicas with controlled porosity profiles are displacing conventional ground silica in high-performance automotive clearcoats. Tier-one coating suppliers serving German and US assembly plants are qualifying these grades for interior trim programs where gloss readings below 10 GU at 60° are mandatory. The shift is compressing demand for legacy diatomaceous earth flatting agents in premium automotive segments.
EPA enforcement of 40 CFR Part 59 VOC content limits is constraining solventborne flatting agent selection in US architectural coatings. The regulation forces formulators to pre-qualify waterborne alternatives before specification lock-in at national retail chains. Southern and Midwestern US coating manufacturing clusters are absorbing the highest compliance costs due to legacy solventborne infrastructure.
Furniture and flooring OEMs are unbundling after-sales technical service from raw material procurement contracts. Buyers now source flatting agents through distributor channels while retaining direct relationships with specification engineers for color matching support. This bifurcation is most visible in Italian and Polish furniture manufacturing districts where coating consumption concentrates among mid-sized finishers.
Flatting Agents Market Segmentation
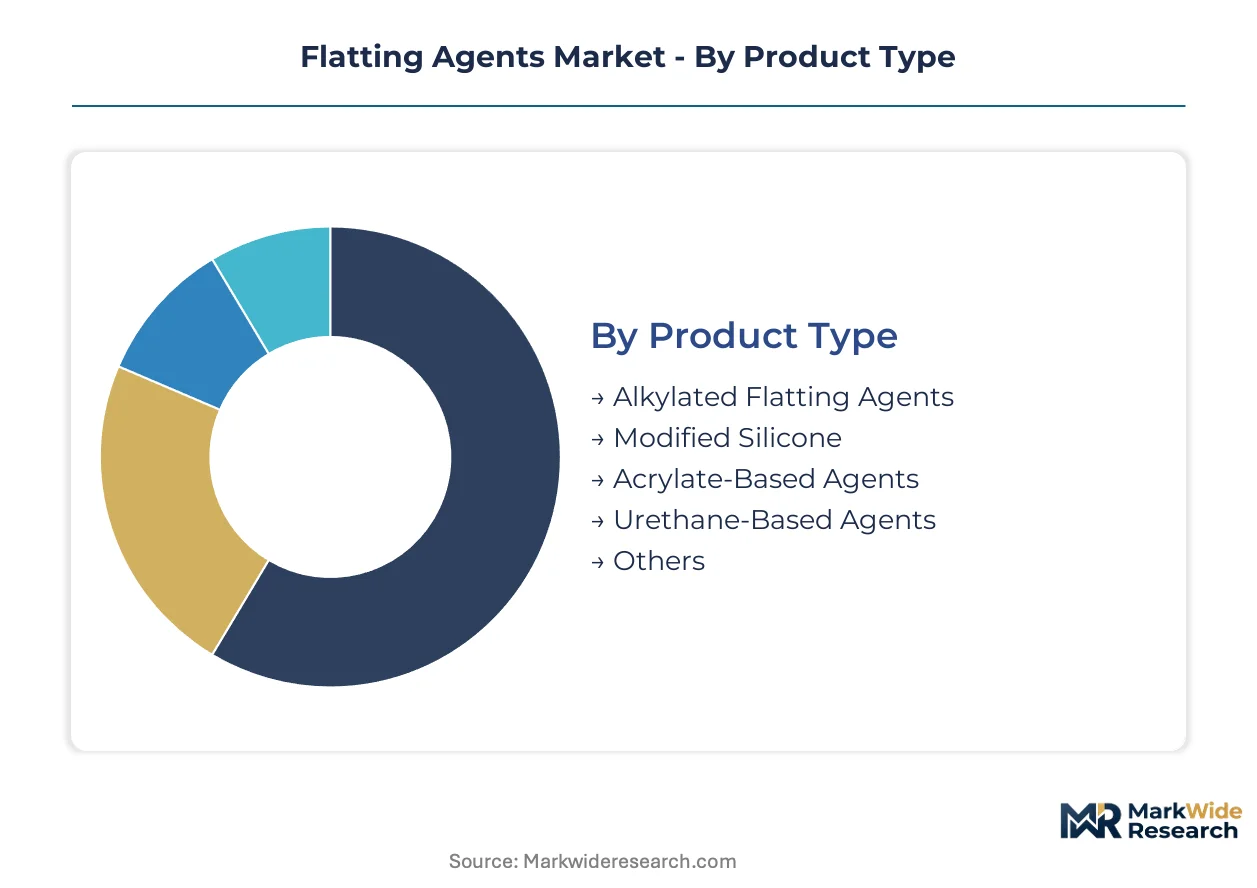
Flatting agent procurement channels diverge sharply by formulation chemistry and end-use specification intensity. Coating formulators route commodity silica grades through distributor networks while reserving direct supplier relationships for automotive OEM qualification programs.
Product Type:
Channel economics favor synthetic flatting agents through technical service partnerships, while mineral-derived grades flow through bulk chemical distributors serving regional paint manufacturers.
- Alkylated Flatting Agents:Surface-modified silica particles with controlled hydrophobicity enable dispersion stability in high-solids solventborne systems. Demand concentrates in German automotive clearcoat formulations where OEM gloss specifications below 10 GU at 60° mandate consistent Hegman fineness.
- Urethane-Based Agents:Polyurethane-structured particles deliver chemical resistance in marine and protective coatings. Expansion concentrates in shipyard maintenance programs across Hamburg and Rotterdam where durability specifications resist commoditization.
- Modified Silicone:Siloxane-treated silicas reduce surface tension defects in waterborne architectural coatings.
- Acrylate-Based Agents:Cross-linked polymer microspheres serve radiation-cured furniture finishes requiring scratch resistance.
- Others:Synthetic wax and organic polymer flatting agents address niche flooring applications.
Alkylated flatting agents dominate installed base. Urethane-based agents are where expansion concentrates.
Application:
Specification authority varies by end-use — automotive OEMs retain direct supplier relationships while construction coatings route through national retail chains.
- Automotive Finishes:Interior trim programs for dashboards and door panels require sub-10 GU gloss readings. German and US assembly plants are consolidating matte-finish specifications, forcing tier-one coating suppliers to secure silica supply chains capable of industrial-scale Hegman consistency.
- Architectural Coatings:Waterborne interior wall paints drive volume procurement through distributor channels. EPA enforcement of 40 CFR Part 59 VOC limits across Southern and Midwestern US manufacturing clusters is accelerating pre-qualification of compliant flatting alternatives.
- Industrial Coatings:Machinery and equipment finishes prioritize cost efficiency over premium matting performance.
- Protective Coatings:Infrastructure and pipeline applications demand chemical resistance in harsh environments.
- Marine Finishes:Shipyard maintenance programs specify urethane-based agents for saltwater durability.
Architectural coatings dominate installed base. Automotive finishes are gaining share fastest.
End User:
Procurement scale and technical service requirements separate large-volume coating manufacturers from specification-driven OEMs.
- Paint Manufacturers:National and regional coating producers purchase flatting agents through bulk chemical distributors. REACH registration burdens on imported silica additives are extending supplier qualification timelines by 18-24 months, freezing specification decisions at European paint plants.
- Automotive OEMs:Volkswagen, BMW, and Ford specification engineers co-develop matte finishes directly with additive suppliers. This bypasses traditional distributor channels and collapses technical service timelines through digital color matching integration.
- Furniture Producers:Italian and Polish manufacturing districts source through unbundled channels — raw materials via distributors, color matching through retained specification engineers.
- Industrial Equipment Makers:Agricultural and construction machinery finishers prioritize cost-competitive matting solutions.
- Construction Firms:Project-based procurement of architectural coatings limits long-term supplier commitments.
Paint manufacturers dominate installed base. Automotive OEMs are where expansion concentrates.
Formulation Type:
Regulatory enforcement patterns are fragmenting procurement channels by chemistry platform.
- Waterborne:Silica and synthetic wax flatting agents disperse in aqueous vehicles with surfactant stabilization. China's MEE dual carbon targets are pressuring domestic coating plants toward waterborne systems, opening specification windows for low-VOC flatting technologies.
- Radiation Cured:UV-curable systems incorporating synthetic wax flatting agents capture premium positioning in North American and European flooring applications. These formulations command above-commodity pricing due to instant cure and low-energy processing.
- Solventborne:Legacy high-VOC systems face constrained selection under EPA and REACH thresholds.
- Powder Coatings:Dry-blend silica additives serve industrial applications requiring zero-VOC compliance.
- UV Curable:Furniture and flooring OEMs specify these systems for scratch-resistant matte finishes.
Solventborne formulations dominate installed base. Radiation-cured systems are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA's REACH enforcement anchors European flatting agent procurement, while EPA regulations and China's MEE dual carbon targets fragment specification patterns across three continents. Automotive OEMs in Germany and the United States drive premium-grade demand, with waterborne reformulation accelerating in all major manufacturing clusters.
Germany
Automotive interior trim programs at Volkswagen and BMW consolidate matte-finish specifications below 10 GU. ECHA's tightening VOC thresholds force coating formulators toward waterborne silica systems. The Stuttgart-Munich corridor hosts the densest concentration of tier-one automotive coating suppliers in Europe.
United States
Southern and Midwestern manufacturing clusters absorb EPA 40 CFR Part 59 compliance costs for architectural coatings. Ford specification engineers co-develop matte finishes directly with additive suppliers, bypassing distributor channels. Detroit-area assembly plants anchor North American demand for industrial-scale Hegman consistency.
China
MEE dual carbon targets pressure domestic coating plants toward powder and waterborne systems. The Yangtze River Delta and Pearl River Delta manufacturing bases lead specification shifts away from solventborne flatting agents. Shanghai-based formulators pre-qualify low-VOC alternatives ahead of enforcement deadlines.
Japan
METI industrial standards guide radiation-cured furniture coating adoption in Kansai manufacturing districts. UV-curable systems with synthetic wax flatting agents capture premium positioning in flooring applications. Osaka-area finishers prioritize scratch-resistant matte technologies for export markets.
India
BIS certification requirements reshape supplier qualification timelines for imported silica additives. Maharashtra and Gujarat paint manufacturers expand waterborne capacity to serve domestic architectural demand. Mumbai-based coating plants negotiate extended payment terms amid raw material cost volatility.
Flatting Agents Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated precipitated silica specialists commanding premium positioning while mineral processors compete on volume. The vendor base separates into three strategic tiers: captive raw material integrators, formulation-technology licensors, and regional distributor-dependent suppliers. Consolidation pressures concentrate around automotive OEM qualification programs, where specification lock-in creates defensive moats. Competitive moves center on backward integration into silica synthesis and co-development partnerships with OEM specification engineers.
Among Germany-based chemical conglomerates, Evonik Industries AG occupies the integrated silica synthesis archetype, while BYK Additives & Instruments exemplifies the formulation-technology specialist model. PPG Industries anchors North American supply through captive technical service capabilities. These three companies represent distinct competitive positions: raw material security, application expertise, and direct OEM channel control.
| Leading Market Players |
|---|
| Evonik Industries AG |
| PPG Industries |
| Huntsman Corporation |
| J.M. Huber Corporation |
| BYK Additives & Instruments |
| Baltimore Innovations |
| W. R. Grace & Co. |
| Imerys |
| PQ Corporation |
| Others |
Supply & Pricing Matrix
Industrial-scale precipitated silica capacity utilization above 85 percent in Western Europe compresses supply availability and establishes firm price floors for automotive-grade flatting agents. German coating formulators absorb premium pricing for consistent Hegman fineness while Southern US architectural buyers face cost compression from EPA compliance investments.
Pricing Analysis
Western European alkylated silica grades trade 15-25 percent above North American equivalents due to ECHA REACH registration burdens on imports. Pricing stratifies across premium, standard, and economy tiers keyed to automotive OEM qualification status, ISO certification level, and after-sales technical service bundling. Cost compression in architectural segments is intensifying as waterborne reformulation absorbs R&D overhead. Paint manufacturers purchasing through distributor channels exhibit highest price sensitivity; automotive OEMs co-developing specifications directly with additive suppliers show lowest sensitivity.
Supply Chain Analysis
Strategic stockpiling of precipitated silica precursors dominates German and US automotive coating clusters, while just-in-time inventory governs architectural distributor channels. Supply concentrates in Germany, China, and the United States for synthetic silica synthesis, with Malaysia and Brazil hosting secondary grinding operations. Raw material flows draw from sodium silicate feedstock, sulfuric acid precipitation reagents, and specialized surfactant surface treatments. Single-source vulnerability concentrates around Western European precipitation expertise. Distribution runs through bulk chemical distributors for commodity grades and direct supplier relationships for automotive qualification programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized expertise in controlled silica precipitation is aging out of European chemical workforces faster than training pipelines replenish, compressing the qualified supplier pool and amplifying pricing power for incumbent integrated producers.
For Market Incumbents: Shield specification lock-in at German and US automotive OEMs through captive technical service teams that co-develop matte finishes with platform engineers. Deepen backward integration into sodium silicate feedstock production to secure margin structures against energy price volatility. Prioritize certification investment for ECHA REACH dossier completeness to extend qualification timeline advantages over import-dependent competitors. For New Entrants and Emerging Players: Anchor in China's Yangtze River Delta waterborne reformulation wave, where MEE dual carbon targets are displacing solventborne legacy capacity fastest. Target mid-sized Italian and Polish furniture finishers with unbundled procurement models—raw materials via distributors, color matching through retained specification engineers. Pursue co-development partnerships with regional coating formulators lacking in-house silica engineering capabilities. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated precipitated silica producers serving automotive OEM direct channels; these archetypes command durable pricing power through specification lock-in. Over the medium-term horizon, prioritize acquisition targets with captive synthesis capacity and active REACH registration portfolios. Monitor ECHA enforcement intensity as the inflection signal for supplier consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silica Synthesis | Evonik's captive precipitated silica network secures raw material continuity for automotive flatting grades. |
| Co-Development Partnership with OEM Engineers | PPG's direct collaboration with Ford specification teams collapses traditional technical service timelines. |
| Waterborne Formulation Qualification | BYK's surface-modified silica systems capture EPA 40 CFR Part 59 compliance-driven specification shifts. |
| Radiation-Cured System Expansion | Synthetic wax flatting agents in UV-curable flooring coatings command premium positioning in North American markets. |
| REACH Dossier Investment | Complete ECHA registration portfolios extend supplier qualification timelines by 18-24 months against import competition. |
Research Methodology
A spread of perspectives from automotive OEM specification engineers, tier-one coating formulators, precipitated silica plant managers, and bulk chemical distributors converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with downstream procurement leads and technical R&D directors at German, US, and Chinese manufacturing facilities. Secondary validation drew from ECHA REACH registration databases, EPA 40 CFR enforcement disclosures, SEC 10-K filings from listed chemical conglomerates, and trade flow data from customs authorities. Bottom-up volume estimates triangulated against top-down market sizing from coating consumption models.
Segmentation dimensions modeled include product chemistry platform, end-use application intensity, formulation type, and regional regulatory cluster across the projection horizon. CAGRs derive from regression analysis of historical coating production indices and forward-looking OEM specification roadmaps. Industry-specific forecast inputs incorporate automotive interior trim program ramp schedules and waterborne reformulation penetration curves by geography.
Decision-makers should treat outputs as directional under stable ECHA enforcement intensity and sustained automotive matte-finish specification consolidation; material deviation in regulatory timelines or OEM platform cancellations would warrant model refresh. Practitioners should keep alternative scenarios live as China's MEE dual carbon enforcement pace and Western European silica synthesis capacity retirement schedules evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Benzenoid Market
Chemicals
Global Diphenylmethane Diisocyanate Market
Chemicals
Trimethylamine Market
Chemicals
Calcium Borate Market
Chemicals
Allyl Chloride Market
Chemicals
Chemical Distribution Market
Chemicals
Africa Mining Chemicals Market
Chemicals
Iscotrizinol Market
Chemicals
Ruthenium Tetroxide Market
Chemicals
Anticoagulant Rodenticides Market
Chemicals
Global Butanediol Market
Chemicals
Ferric Oxide Market
Chemicals
Non PVC Plasticizers Market
Chemicals
Cummene Derivatives Market
Chemicals
Menadione Market
Chemicals
Para Cresol Market