
 Low Density Ceramic Proppant Market | 2026-2036
Low Density Ceramic Proppant Market Size, Share, and Industry Trends Forecast 2026-2036
Low Density Ceramic Proppant Market Intelligence
North American kiln capacity is hardening as domestic producers race to meet proppant specifications for longer laterals and higher closure stresses. CARBO Ceramics Inc. leverages its vertically integrated bauxite-to-kiln infrastructure to control raw material quality across its manufacturing footprint. Covia Holdings LLC anchors its position through extensive mine reserves and multi-modal logistics networks serving the Permian and Appalachian basins. JSC Borovichi Refractories Plant competes on cost-efficient alumina-based formulations tailored to Eastern European and Central Asian well conditions.
Low density ceramic proppant consists of sintered bauxite or kaolin-based spheres engineered with bulk densities below 2.65 g/cm³ and crush resistance ratings typically exceeding 5,000 psi closure stress, functioning to maintain fracture aperture and enable hydrocarbon flowback in hydraulically stimulated reservoirs. Synthetic proppant formulations dominate premium pricing tiers due to their engineered uniformity and predictable performance under extreme downhole temperatures, while resin-coated variants capture growing share in flowback-sensitive applications where proppant embedment and fines generation threaten well productivity. Hydraulic fracturing applications command the largest volume allocation across the value chain, though construction sector testing of ceramic aggregates for high-performance concrete represents an adjacent demand channel with distinct specification requirements.
EPA emissions regulations and OSHA silica exposure limits are tightening operational standards across the proppant supply chain, compelling manufacturers to invest in dust suppression systems and closed-loop material handling. The EU REACH framework and associated chemical registration requirements constrain import pathways for non-European producers seeking to serve North Sea and European shale prospects. Stakeholders must monitor evolving state-level proppant sourcing mandates in Texas and New Mexico, where local content preferences could reshape procurement patterns without warning.
Market Dynamics
Longer horizontal laterals and higher stage counts in unconventional shale development are compressing the economics of proppant logistics, forcing operators to prioritize lightweight ceramic systems that reduce trucking intensity and enable faster pump schedules.
Growth Catalysts
- EPA emissions standards:Stricter diesel combustion limits for hydraulic fracturing fleets are accelerating operator preference for low-density ceramic proppant that cuts transport volumes and associated greenhouse gas intensity.
- Permian Basin well intensity:Proppant loading per stage continues climbing in West Texas and southeastern New Mexico, concentrating demand for high-conductivity lightweight formulations that maintain fracture aperture under elevated closure stress.
- Resin-coating technology:Advanced surface treatments that reduce proppant embedment and fines generation are capturing expanded share in flowback-sensitive completions where well productivity protection drives specification upgrades.
Market Restraints
- Bauxite supply concentration:Raw material sourcing for alumina-based ceramic proppant depends heavily on Guinean and Australian mine outputs, exposing manufacturers to geopolitical disruption and maritime freight volatility.
- Natural sand substitution:Northern White and regional Brady sand deposits continue pressuring ceramic volumes in shallow, low-stress basins where crush resistance requirements remain below ceramic thresholds.
- Kiln capacity constraints:Domestic North American sintering infrastructure faces hardening bottlenecks as producers race to qualify production for longer laterals and higher closure stress ratings.
Strategic Opportunities
- Construction sector testing:High-performance concrete applications represent an adjacent demand channel with distinct specification requirements, enabling manufacturers to diversify revenue beyond oilfield cyclicality.
- EU REACH framework alignment:Chemical registration compliance creates a structural barrier for non-European producers, offering first-mover advantage to registrants seeking North Sea and European shale prospect supply contracts.
- Closed-loop material handling:Dust suppression system integration addresses tightening OSHA silica exposure limits while differentiating suppliers in procurement evaluations where environmental, health, and safety metrics carry expanding weight.
Industry Challenges
- Refractory ceramics engineering talent:Specialized expertise in sintered bauxite formulation and kiln process control remains scarce, constraining rapid capacity expansion and quality consistency at scale.
- State-level sourcing mandates:Evolving local content preferences in Texas and New Mexico threaten to reshape procurement patterns without warning, requiring agile supply chain reconfiguration capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Density Ceramic Proppant Market |
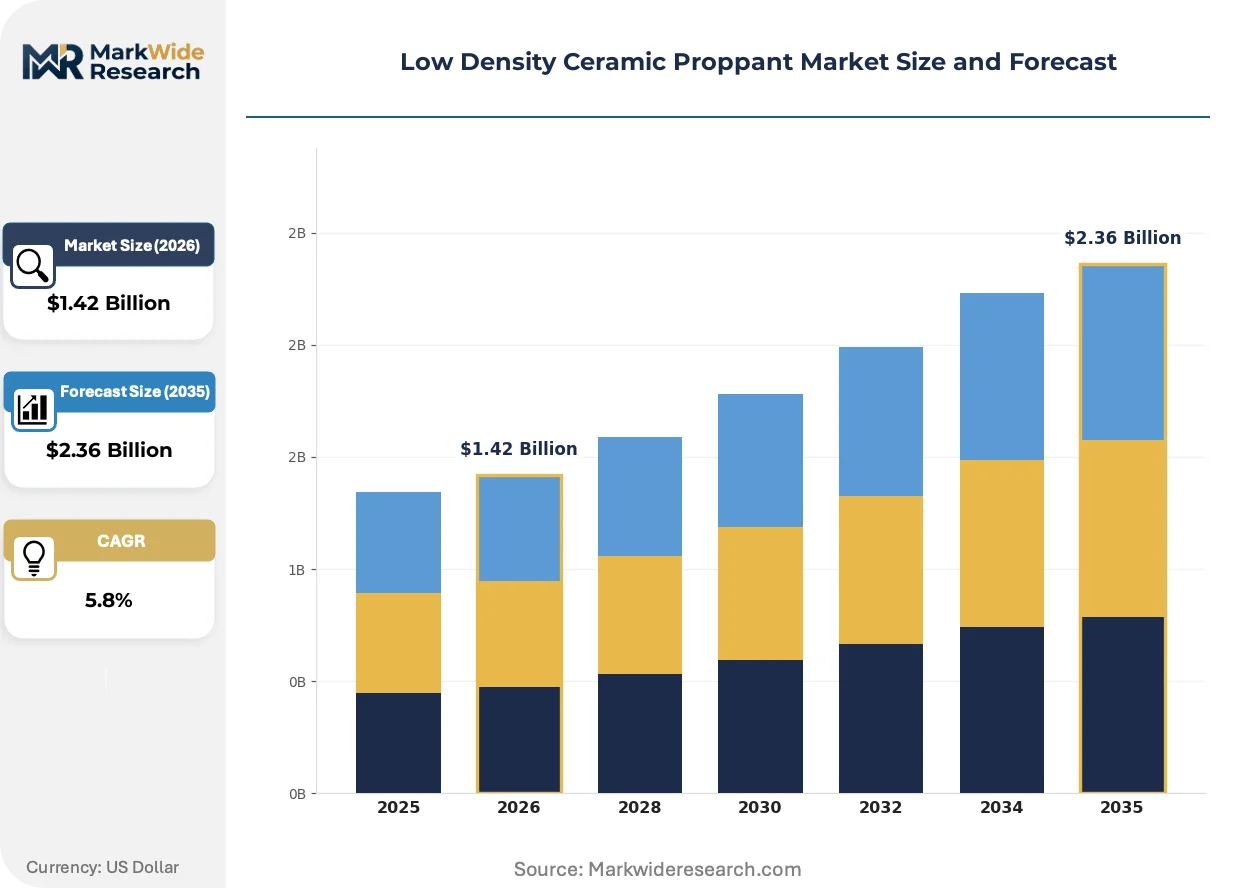
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.36 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Synthetic, Resin-Coated, Others Application: Hydraulic Fracturing, Construction, Oil Extraction, Mining End User: Oil & Gas, Construction Companies, Mining Firms, Energy Sector Distribution Channel: Direct Sales, Distributors, Online Retail, Export |
| Companies Covered | Badger Mining Corp., Mineracao Curimbaba, CARBO Ceramics Inc., CC, Fores, Fineway Ceramics, Covia Holdings LLC, JSC Borovichi Refractories Plant, Imerys SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Density Ceramic Proppant Market Strategic Shifts & Innovations
Engineered proppant systems are converging with digital fracture design platforms, creating specification feedback loops that compress development cycles and reward materials science innovation with faster field validation.
Ultralight ceramic formulations with bulk densities approaching 2.50 g/cm³ are electrifying operator interest in deep Permian and Appalachian completions where reduced hydrostatic loading extends effective lateral reach. Majors and large independents are qualifying these materials for 15,000-foot-plus true vertical depth applications previously dominated by intermediate-density alternatives. The technology is electrifying competitive positioning by enabling single-source proppant strategies across variable stress regimes.
OSHA silica exposure limits are tightening operational standards across the proppant supply chain, compelling manufacturers to invest in pneumatic conveying upgrades and enclosed loadout infrastructure. The industrial consequence is capital reallocation from capacity expansion toward environmental, health, and safety compliance. Mid-tier suppliers serving the Marcellus and Utica basins are most affected, responding with third-party dust control service contracts and real-time air monitoring deployments.
Integrated proppant service contracts that bundle material supply with last-mile logistics and on-site handling are displacing traditional spot purchasing in the most active North American shale basins. Disintermediation of regional distributors is accelerating as operators consolidate vendor bases and demand outcome guarantees on conductivity performance. This pattern is most visible in the Delaware Basin sub-region of the Permian, where supermajors have compressed approved supplier lists to single-digit counts.
Low Density Ceramic Proppant Market Segmentation
Segmentation in low density ceramic proppant reveals how capital deployment, technical specifications, and procurement patterns diverge across the value chain. Understanding these fault lines helps suppliers align kiln investments, coating capabilities, and logistics infrastructure with where margins concentrate.
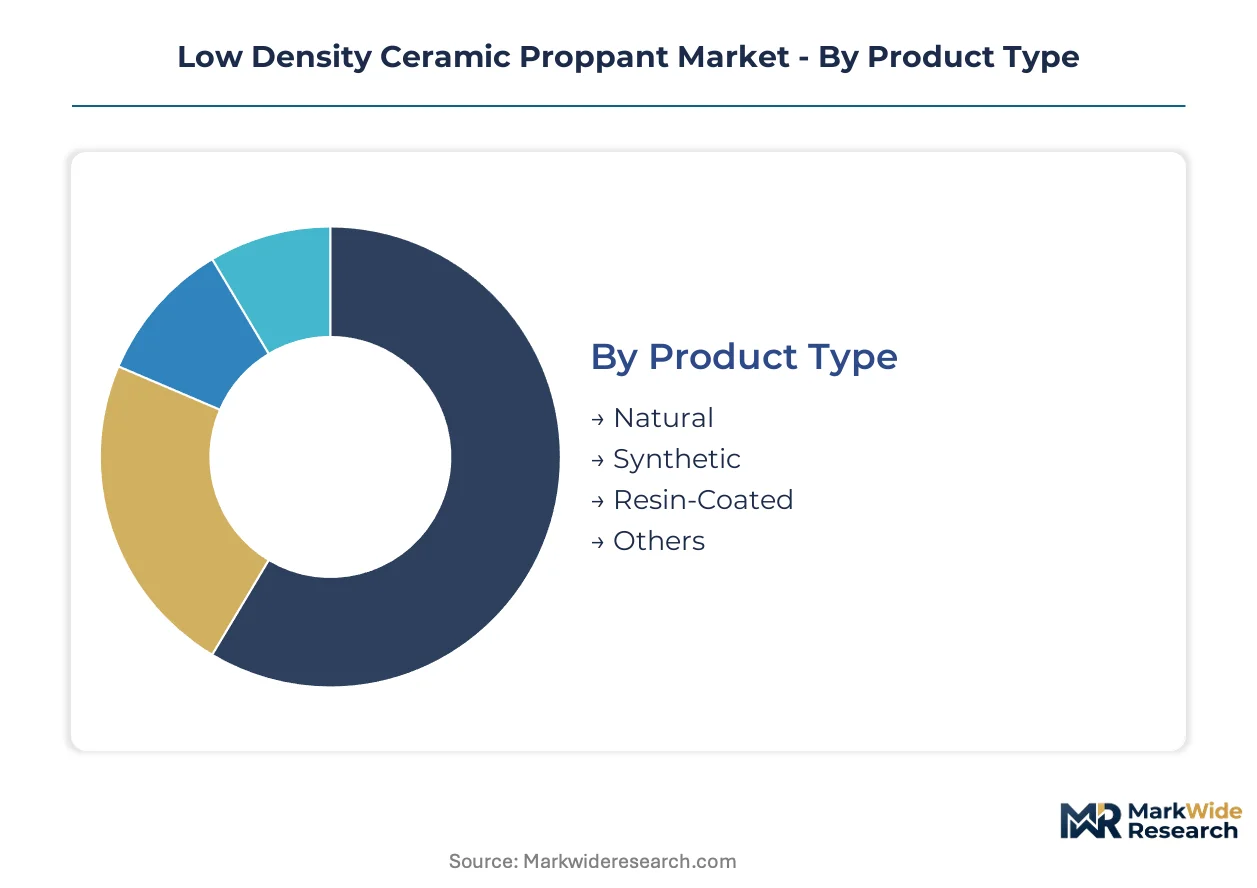
Product Type:
Capital intensity varies sharply across formulation approaches, with synthetic sintering requiring the heaviest upfront kiln and quality-control infrastructure.
- Natural:Derived from mined bauxite or kaolin clays processed through rotary kiln sintering without chemical modification. Demand clusters in shallow Permian and Appalachian wells where intermediate crush resistance satisfies operator economics without premium pricing.
- Synthetic:Engineered from chemically refined alumina feedstocks with precisely controlled sphericity and bulk density below 2.50 g/cm³. West Texas supermajors are qualifying these formulations for 15,000-foot true vertical depth applications where hydrostatic loading reduction extends lateral reach.
- Resin-Coated:Surface-treated ceramic substrates reduce proppant embedment and fines generation in flowback-sensitive completions.
- Others:Emerging nano-modified and composite formulations targeting ultra-high closure stress regimes.
Most installed capacity flows through Natural. Expansion is steepest in Synthetic.
Application:
Volume concentration and margin structure diverge meaningfully between cyclical oilfield demand and adjacent industrial channels.
- Hydraulic Fracturing:Dominates tonnage as proppant maintains fracture conductivity in stimulated shale reservoirs. Delaware Basin operators are pushing per-stage loading past 3,000 pounds per foot, concentrating procurement through integrated service contracts that bundle material with last-mile logistics.
- Construction:High-performance concrete testing represents a non-cyclical demand channel with distinct ASTM specification requirements. European infrastructure projects are piloting ceramic aggregates for abrasion-resistant highway surfaces and marine structures.
- Oil Extraction:Conventional reservoir applications including gravel packing and sand control in mature fields.
- Mining:Heap leaching and mineral processing applications utilizing ceramic media for chemical resistance.
Procurement concentration tilts toward Hydraulic Fracturing. Construction is climbing fastest as a diversification hedge.
End User:
Customer scale and technical sophistication determine specification stringency and contract structure across the buyer base.
- Oil & Gas:Majors and large independents drive premium-tier demand with closed-loop material handling requirements and real-time conductivity guarantees. ESG scorecards now weight dust suppression and transport emissions alongside unit pricing in vendor selection.
- Construction Companies:Project-based procurement with batch consistency requirements and certified recycled content preferences in EU public tenders.
- Mining Firms:Volume buyers prioritizing chemical inertness and wear resistance over sphericity tolerances.
- Energy Sector:Geothermal and compressed air energy storage applications with emerging thermal cycling specifications.
Contract value concentrates with Oil & Gas. Construction Companies are gaining procurement sophistication fastest.
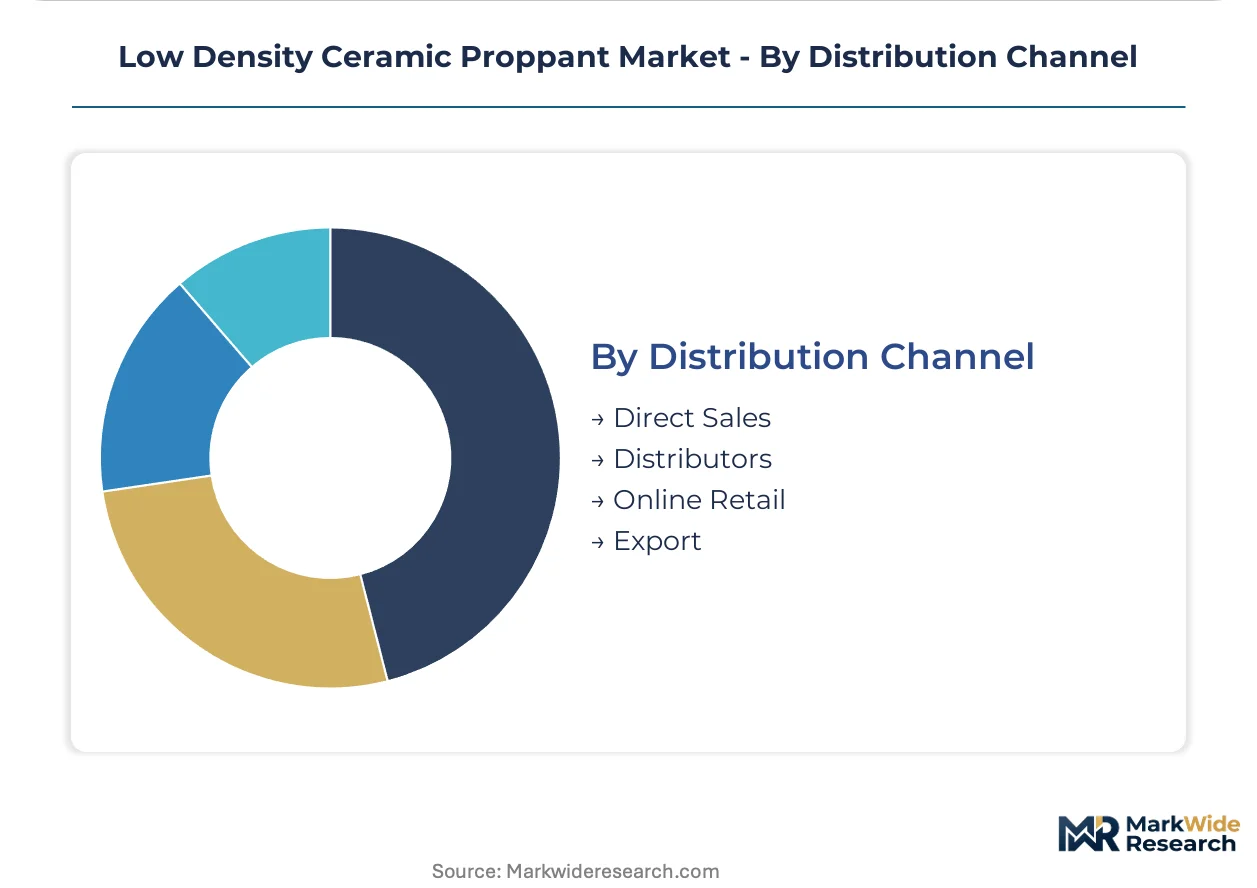
Distribution Channel:
Channel economics reflect the tension between inventory risk, logistics control, and customer intimacy in a weight-intensive product category.
- Direct Sales:Kiln operators with captive mine-to-wellhead logistics bypass intermediaries in the Permian and Marcellus basins. Supermajors have compressed approved supplier lists to single-digit counts, disintermediating regional distributors.
- Distributors:Regional inventory holders serving smaller independents with fragmented demand and irregular scheduling.
- Online Retail:Limited to specialty formulations and sample procurement for laboratory qualification.
- Export:Maritime bulk shipments to Middle East and North Sea prospects with REACH registration requirements creating structural barriers for non-European entrants.
Volume flows predominantly through Direct Sales. Export is expanding most quickly as North American kiln capacity hardens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping kiln investment geography as EPA emissions enforcement in the United States widens the cost-of-compliance gap against jurisdictions with looser silica handling standards. Manufacturers are migrating sintering capacity toward states with streamlined permitting while maintaining raw material ties to bauxite-exporting nations.
United States
Permian Basin operators in West Texas and southeastern New Mexico are pushing per-stage proppant loading past 3,000 pounds per foot. EPA emissions standards for hydraulic fracturing fleets are accelerating preference for low-density ceramic systems that cut transport volumes and diesel combustion intensity. Midland-Odessa anchors domestic demand concentration with supermajors compressing approved supplier lists to single-digit counts.
China
Domestic shale development in Sichuan and Xinjiang basins is absorbing rising volumes of lightweight ceramic proppant for deeper horizontal wells. The country's national environmental regulator has tightened industrial emissions standards for ceramics manufacturing, forcing kiln upgrades and dust suppression investments. Zhengzhou and Zibo industrial clusters host the majority of sintering capacity serving both oilfield and construction sector demand.
Russia
Eastern Siberian and Volga-Ural basin operators are qualifying low-density formulations for high-closure-stress reservoirs previously dominated by intermediate-density alternatives. Domestic content requirements in strategic mineral processing are constraining import pathways for non-Russian producers. Borovichi in Novgorod Oblast anchors refractory ceramics manufacturing with legacy expertise in alumina-based formulations.
Brazil
Pre-salt carbonate reservoir development is driving specification upgrades toward crush-resistant lightweight proppant for high-pressure completions. The country's national petroleum regulator has issued updated technical standards for hydraulic fracturing materials in offshore environments. Minas Gerais state concentrates bauxite mining and initial processing capacity serving both domestic and export markets.
Saudi Arabia
Unconventional gas development in the Jafurah Basin is creating new demand for high-conductivity proppant systems in tight sandstone reservoirs. The national oil company's localization mandates are requiring foreign suppliers to establish domestic manufacturing or joint venture structures. Eastern Province industrial zones near Jubail are attracting kiln investment to serve regional oilfield services demand.
Low Density Ceramic Proppant Market Key Industry Players
North American producers anchor one tier; Eastern European and Chinese specialists hold differentiated positions in cost-sensitive and state-contract channels. The vendor base organizes around three strategic archetypes: vertically integrated mine-to-kiln operators, regional logistics-heavy distributors, and technology-focused synthetic formulation specialists. Capacity expansion and backward integration into bauxite sourcing represent the dominant competitive moves as kiln bottlenecks harden.
Among North American fabricators, CARBO Ceramics Inc. and Covia Holdings LLC exemplify the integrated archetype with captive raw material positions and multi-basin logistics networks. JSC Borovichi Refractories Plant occupies a position within the cost-efficient formulation tier, leveraging legacy refractory expertise to serve Eastern European and Central Asian well conditions. These three anchors illustrate how geographic origin and corporate structure map to distinct competitive positioning in a market where qualification timelines and transport economics determine contract viability.
| Leading Market Players |
|---|
| Badger Mining Corp. |
| Mineracao Curimbaba |
| CARBO Ceramics Inc. |
| CC |
| Fores |
| Fineway Ceramics |
| Covia Holdings LLC |
| JSC Borovichi Refractories Plant |
| Imerys SA |
| Others |
Cost & Logistics Intelligence
Captive bauxite-to-kiln infrastructure anchors both supply security and pricing power for North American producers serving Permian Basin operators. This backward integration shields qualified suppliers from Guinean and Australian maritime freight volatility while enabling contract premiums for crush-resistant formulations.
Pricing Analysis
Distributor margins compress under integrated service contracts that bundle material with last-mile logistics. Three-tier pricing structure across premium synthetic, standard natural, and economy resin-coated levels stratifies by closure stress rating and sphericity tolerance. Pricing pressure stems from Northern White sand substitution in shallow Appalachian wells where ceramic crush resistance exceeds operational requirements. Small independents exhibit highest price sensitivity, while supermajors prioritize conductivity guarantees over unit cost.
Supply Chain Analysis
Bauxite supply rests on Guinean mine outputs and Australian alumina refineries, with maritime bulk routes feeding kiln clusters in Texas and Zhengzhou. Sintered sphere production draws from rotary kiln capacity concentrated in Odessa-Midland, Zibo industrial zones, and Borovichi refractory corridors. Single-source vulnerability runs through Strait of Malacca chokepoints for Asian-bound feedstocks. Distribution runs through direct sales channels bypassing regional inventory holders as operator consolidation compresses approved supplier lists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Low density ceramic proppant has matured into a late-cycle quality story as Permian operators push per-stage loading past 3,000 pounds per foot and demand 15,000-foot true vertical depth qualification for ultralight formulations.
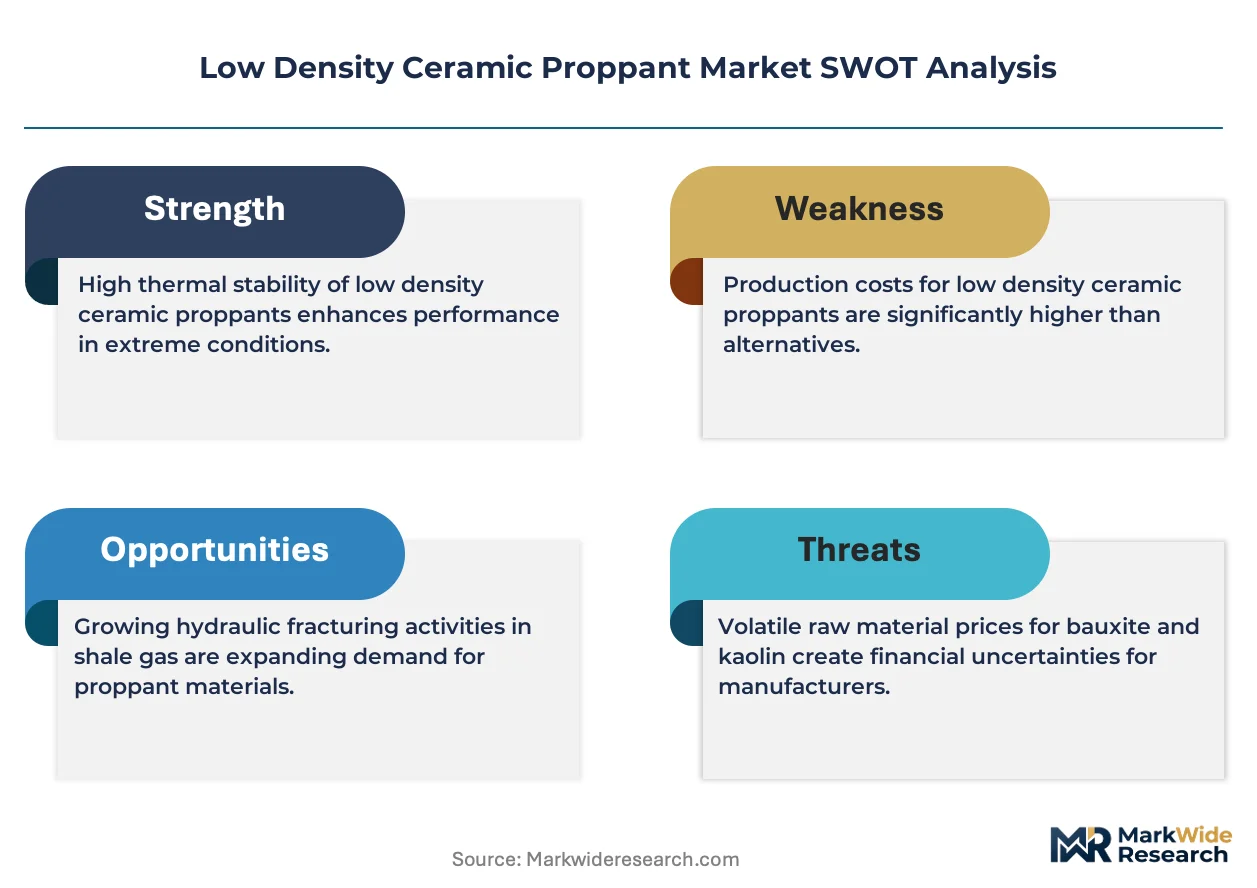
For Market Incumbents: Acquire captive bauxite reserves or long-term offtake agreements to secure feedstock against Guinean supply disruption. Expand kiln capacity in Texas or New Mexico ahead of state-level local content mandates that could disqualify non-domestic supply. Natural sand substitution in shallow basins and kiln bottlenecks threatening qualification timelines represent immediate threats to volume retention. For New Entrants and Emerging Players: Launch via construction sector ceramic aggregate contracts for high-performance concrete applications in European infrastructure projects. Target EU REACH-compliant channels where chemical registration barriers protect first-mover registrants from non-European competition. Dust suppression system integration offers differentiation in procurement evaluations where OSHA silica limits tighten. For Investors and Strategic Acquirers: Consolidation pressure builds where kiln capacity hardens against qualification timelines for longer laterals and higher closure stress ratings. Five-to-ten year viability favors vertically integrated mine-to-wellhead operators with multi-basin logistics networks over regional distributors facing disintermediation. Watch EPA emissions enforcement intensity as the trigger for accelerated lightweight ceramic adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bauxite Reserves | Captive Guinean or Australian mine positions secure feedstock against maritime freight volatility and geopolitical disruption. |
| Kiln Capacity Expansion in Texas | Odessa-Midland proximity reduces last-mile logistics costs for Permian Basin operators pushing higher stage counts. |
| EU REACH Registration Compliance | Chemical registration creates structural barriers for non-European producers seeking North Sea shale prospect contracts. |
| Closed-Loop Dust Suppression Deployment | OSHA silica handling compliance differentiates suppliers in ESG-weighted procurement evaluations. |
| Construction Sector Aggregate Qualification | ASTM-certified ceramic aggregates for high-performance concrete diversify revenue beyond oilfield cyclicality. |
Research Approach
Direct dialogue with kiln operations managers, Permian Basin procurement directors, hydraulic fracturing engineers, and EHS compliance officers grounded qualitative assessment in operational reality. Secondary validation drew from EPA emissions filings, EIA drilling productivity reports, SEC 10-K disclosures by listed proppant producers, and customs trade data on bauxite import volumes. Bottom-up well completion counts and top-down kiln capacity estimates were triangulated to anchor volume projections.
Bottom-up modeling tracked proppant loading per stage across Delaware and Midland Basin sub-regions, while top-down analysis calibrated total addressable market against North American horizontal rig counts. Segmentation by product type, application, end user, and distribution channel structured the analytical framework across the projection horizon. Crush resistance ratings, bulk density thresholds, and closure stress qualification timelines served as industry-specific forecast inputs alongside regulatory enforcement patterns.
Several conditions sit outside the modeled scope, including abrupt Guinean export restrictions, breakthrough natural sand treatment technologies, and unilateral state-level local content mandates. Forecasts reflect assumptions about EPA emissions enforcement continuity and OSHA silica rule stability. A small set of named triggers warrants ongoing watch: kiln qualification delays for 15,000-foot applications, REACH registration timeline shifts, and supermajor supplier list compression rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
North America Barium Carbonate Market
Ceramics
Ceramics Packaging Market
Ceramics
Vaterite Market
Ceramics
Relaxor Ferroelectric Ceramics Market
Ceramics
USA and Canada Alumina Market
Ceramics
China Ceramic Tiles Market
Ceramics
Boiler Refractory Material Market
Ceramics
Ceramic Frit Glass Market
Ceramics
Low Temperature Co-Fired Ceramic (LTCC) Market
Ceramics
East Africa Ceramic Tiles Market
Ceramics
Ceramic Sanitary Ware Market
Ceramics
Dielectric Ceramics Market
Ceramics
Glazed Ceramic Tile Market
Ceramics
Refractories Market
Ceramics
Tetramethyl Orthosilicate Market
Ceramics
Wollastonite Market