
 Diatomite Mining Market | 2026-2036
Diatomite Mining Market Size, Share, and Industry Trends Forecast 2026-2036
Diatomite Mining Market Insights
Market Context
The diatomite mining sector is restructuring around a widening split between premium calcined grades for pharmaceutical filtration and commodity raw diatomite for industrial absorbents. Imerys leverages its integrated processing network across Nevada and California to dominate high-purity filter aid supply. EP Minerals sustains a leading position in absorbent applications through control of deposits in Oregon and Washington. Showa Chemical Industry Co., Ltd. anchors Asian supply chains with specialized calcination technology for Asian water treatment markets.
Technical Foundation and Segment Dynamics
Diatomite consists of fossilized siliceous skeletons of diatoms, yielding a porous structure with bulk densities of 128–320 kg/m³ and high surface area ideal for filtration and absorption. Calcined diatomite commands premium positioning due to thermal processing that raises silica purity above 90% for stringent beverage and pharmaceutical filtration. Raw diatomite competes on volume in agricultural insecticide and rubber filler applications where lower processing costs offset performance trade-offs. Water treatment end users concentrate procurement on filter aid performance, while petroleum refiners prioritize absorbent capacity for spill response.
Regulatory Environment and Outlook
The EPA enforces Maximum Contaminant Level Goals under the Safe Drinking Water Act that directly expand demand for diatomite filtration media in municipal systems. OSHA regulates respirable crystalline silica exposure in mining operations, shaping extraction technology investments and workplace compliance costs. The EU REACH framework restricts certain diatomite processing additives, altering export specifications for producers serving European chemical processing customers. Stakeholders must monitor evolving drinking water quality mandates and silica exposure thresholds to align capacity planning with compliance-driven demand shifts.
Market Dynamics
The diatomite mining sector is consolidating around calcination capacity proximity to western US deposits, as thermal processing economics and EPA particulate standards reshape competitive boundaries between integrated producers and toll-processors.
Growth Catalysts
- Safe Drinking Water Act amendments:EPA Maximum Contaminant Level Goals are mandating finer filtration media in municipal water systems, directly expanding specification-grade diatomite procurement volumes.
- Petroleum spill response infrastructure:US Coast Guard and state environmental agencies are stockpiling absorbent-grade diatomite for rapid deployment protocols across coastal and inland waterway jurisdictions.
- Silica purity thresholds:Beverage and pharmaceutical end-users are tightening incoming material specifications above 90% SiO₂, calcined diatomite toward premium processing investments.
Market Restraints
- Natural gas price volatility:Calcination operations require sustained thermal energy input, and gas price spikes compress margins for Nevada and California processing facilities.
- Deposit geographic concentration:Commercial-grade diatomite reserves cluster in Oregon, Washington, Nevada and California, creating supply vulnerability to regional drought or seismic disruption.
- Perlite and cellulose substitution:Lower-cost filter aids are capturing volume in non-critical industrial applications where performance trade-offs are acceptable.
Strategic Opportunities
- Lithium extraction brine filtration:Nevada's lithium triangle operations are testing diatomite pre-filtration for battery-grade salt recovery, opening a new high-specification demand vertical.
- EU REACH additive compliance:Reformulation of processing aids to meet European chemical registration requirements is creating first-mover advantage for US exporters with certified clean production lines.
- Precision agriculture expansion:Organic farming jurisdictions in the Pacific Northwest are expanding mechanical insecticide registrations for food-grade diatomaceous earth soil applications.
Industry Challenges
- Respirable silica compliance:OSHA enforcement of crystalline silica exposure limits in mining and milling operations is requiring capital-intensive dust suppression and worker monitoring systems.
- Calciner capacity lead times:Rotary kiln fabrication and permitting timelines extend 18-24 months, constraining rapid response to demand spikes in filtration-grade material.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diatomite Mining Market |
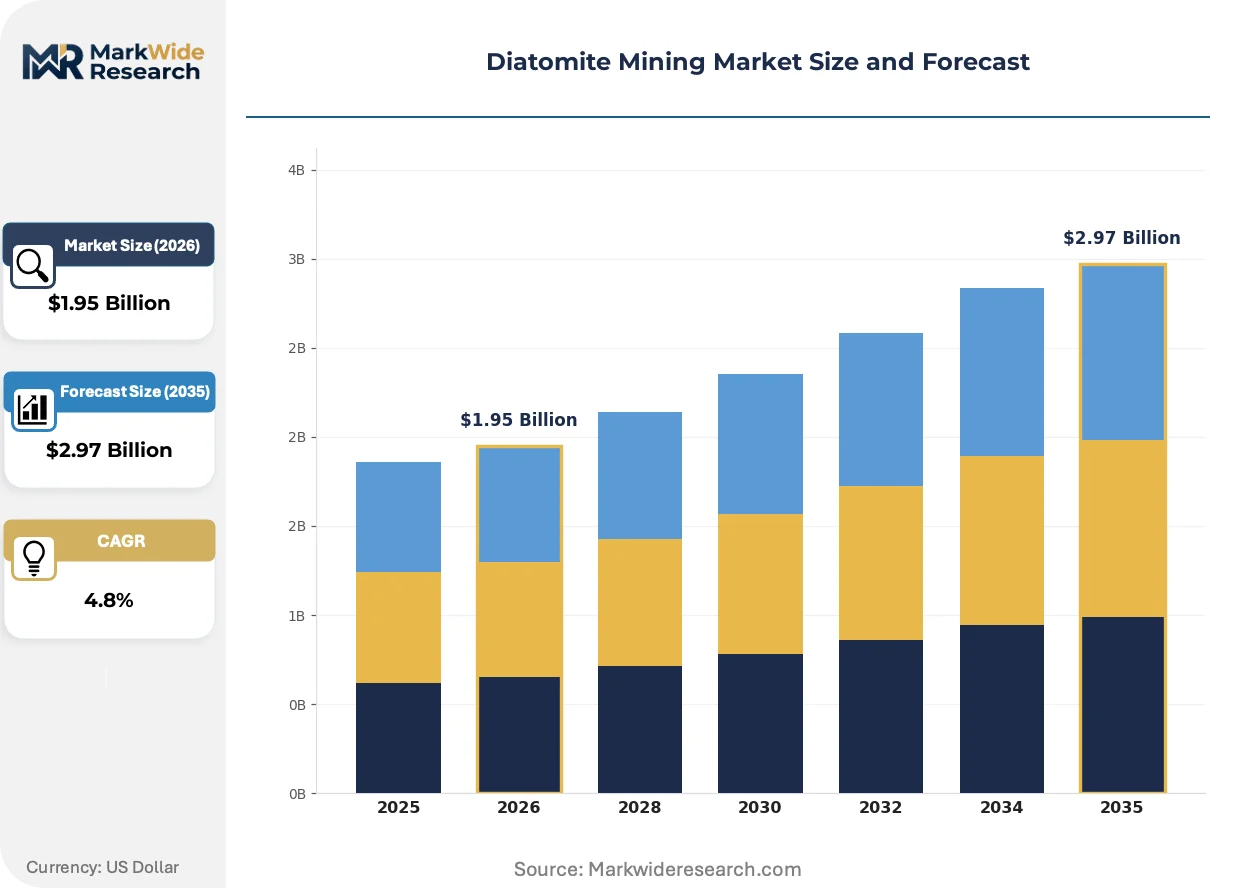
| Market Size in 2026 | $1.95 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Calcined Diatomite, Raw Diatomite, Filter Aids, Absorbents, Others Application: Filtration, Filler, Absorbent, Refractory Material, Catalyst Carrier, Insecticide End User Industry: Water Treatment, Paints, Rubber Manufacturing, Chemical Processing, Agriculture, Petroleum Mining Method: Open-pit Mining, Quarrying, Underground Mining, Hydraulic Mining |
| Companies Covered | Imerys, EP Minerals, Showa Chemical Industry Co., Ltd, Dicalite Management Group, LLC, Diatomit CJSC, Jilin Yuantong Mineral Co., Ltd., Calgon Carbon Corporation, CECA Chemical, Grefco Minerals, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diatomite Mining Market Trends and Innovations
Processing technology and regulatory chemistry are converging to split the diatomite market into traceable premium grades and commodity absorbents, with digital quality verification emerging as a competitive differentiator.
Flash calcination systems with real-time temperature control are rewriting the economics of high-purity filter aid production. Beverage bottlers in California and pharmaceutical manufacturers in New Jersey are qualifying these thermally processed grades at accelerated rates. The technology is compressing the historical premium gap between imported European filter aids and domestically produced material.
EPA's proposed revisions to Lead and Copper Rule corrosion control requirements are expanding municipal specification for diatomite in drinking water pre-filtration. Water utilities in Arizona and Colorado are upgrading intake systems to meet anticipated turbidity thresholds. The rulemaking is forcing procurement departments toward certified performance documentation rather than commodity sourcing.
Consolidated municipal purchasing cooperatives are displacing individual utility procurement contracts across the western United States. Regional water authorities in Utah and Idaho are aggregating filter aid volumes to secure calcined grade pricing previously reserved for large industrial accounts. This concentration is most visible in the Intermountain West where infrastructure bond funding is synchronizing upgrade timelines.
Diatomite Mining Market Segmentation
Diatomite mining segmentation reflects divergent processing economics and regulatory compliance pathways. Thermal treatment intensity separates premium filtration grades from commodity absorbents, while end-use specifications dictate purity thresholds and certification requirements across supply tiers.
Product Type:
Integration depth varies sharply—calcined grades embed into pharmaceutical and beverage filtration systems as certified performance components, while raw diatomite serves standalone agricultural and industrial absorbent applications without downstream thermal processing.
- Calcined Diatomite:Thermal processing at 800-1,200°C drives silica purity above 90% and creates controlled pore structures for beverage and pharmaceutical filtration. Nevada processing facilities supply California bottlers under FDA food-contact regulations.
- Raw Diatomite:Unprocessed fossilized diatom skeletons retain natural porosity for agricultural insecticide carriers and industrial spill absorbents. Oregon deposits supply Pacific Northwest organic farming jurisdictions expanding mechanical pest control registrations.
- Filter Aids:Sized and classified diatomite grades optimize cake permeability in municipal water treatment pre-coat systems.
- Absorbents:Lower-density grades capture petroleum spills and chemical leaks under US Coast Guard stockpiling protocols.
- Others:Specialized flux-calcined variants serve cement and insulation applications requiring intermediate thermal treatment.
Calcined diatomite leads volumes today; raw diatomite is gaining share fastest in organic agriculture verticals.
Application:
Cost tier stratification separates specification-driven filtration from price-sensitive filler applications, with performance premiums widening between certified drinking water grades and industrial commodity uses.
- Filtration:Municipal water treatment systems deploy diatomite pre-coat filtration to meet EPA turbidity standards under Safe Drinking Water Act amendments. Arizona and Colorado utilities are upgrading intake infrastructure with specification-grade material.
- Filler:Rubber manufacturing and paint formulations incorporate raw diatomite as low-cost extender pigments and viscosity modifiers where performance trade-offs against precipitated silica are economically acceptable.
- Absorbent:Petroleum refiners and spill response contractors prioritize bulk absorbent capacity over purity for rapid deployment protocols.
- Refractory Material:High-alumina diatomite blends insulate kilns and furnaces in ceramic manufacturing.
- Catalyst Carrier:Controlled pore-size calcined grades support petrochemical process catalysts.
- Insecticide:Food-grade diatomaceous earth abrades insect exoskeletons in organic crop protection.
Filtration commands the highest value per ton; insecticide applications are climbing fastest amid organic farming expansion.
End User Industry:
Customer type concentration shapes procurement patterns—consolidated municipal cooperatives negotiate calcined grade contracts while fragmented agricultural buyers purchase raw diatomite through distributor networks.
- Water Treatment:Regional purchasing cooperatives in Utah and Idaho aggregate municipal volumes to secure pricing previously reserved for large industrial accounts. Intermountain West infrastructure bond funding is synchronizing upgrade timelines.
- Paints:Architectural coating manufacturers substitute diatomite for higher-cost rheology modifiers in volume interior formulations.
- Rubber Manufacturing:Tire and industrial rubber producers use raw diatomite as non-reinforcing filler to reduce compound costs.
- Chemical Processing:Petrochemical refiners specify absorbent-grade material for process spill containment and wastewater treatment.
- Agriculture:Pacific Northwest organic jurisdictions are expanding mechanical insecticide registrations for soil-applied diatomaceous earth.
- Petroleum:Coastal and inland waterway spill response stockpiles require rapid-deployment absorbent capacity under state environmental agency protocols.
Water treatment leads procurement volumes; agriculture is expanding most quickly behind organic certification growth.
Mining Method:
Deposit geometry and overburden depth determine extraction technology selection, with surface methods dominating western US reserves and underground techniques reserved for deeper, higher-purity seams.
- Open-pit Mining:Bulk extraction of near-surface diatomite deposits in Nevada and California feeds integrated calcination facilities with minimal overburden removal costs.
- Quarrying:Selective bench mining in Oregon and Washington targets discrete high-purity lenses for filter aid production.
- Underground Mining:Limited application for deep, consistent seams where surface disturbance restrictions or overburden economics favor shaft access.
- Hydraulic Mining:Slurry extraction of unconsolidated lakebed deposits where water availability and permitting allow.
Open-pit mining dominates current output; quarrying is gaining operational share for premium-grade deposit access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled mining engineers and process technicians cluster around Nevada's diatomite belt, anchoring North American production expertise in a tight geographic radius.
United States
Municipal water utilities in Arizona and Colorado are upgrading intake infrastructure to meet anticipated EPA turbidity thresholds under Safe Drinking Water Act amendments. Nevada and California host integrated calcination facilities supplying beverage bottlers under FDA food-contact regulations. EP Minerals controls deposits across Oregon and Washington for absorbent applications.
China
Jilin Province mineral processors are expanding output for domestic filtration and agricultural insecticide markets. The country's national environmental regulator enforces tightening industrial wastewater standards that expand specification-grade diatomite procurement. Shandong Peninsula chemical clusters are qualifying local filter aid grades for petrochemical catalyst carriers.
Japan
Specialized calcination technology developers in Osaka and Nagoya serve Asian water treatment markets with high-purity filter aids. METI industrial standards guide silica purity certification for pharmaceutical end-users. Showa Chemical Industry anchors regional supply chains from Chubu region processing facilities.
France
CECA Chemical operations near Provence supply filtration media for European beverage and chemical processing under ECHA REACH framework compliance. The EU Green Deal carbon border adjustments are reshaping import specifications for US exporters. Auvergne-Rhône-Alpes industrial corridors concentrate specialty mineral processing expertise.
Brazil
Agricultural insecticide formulators in São Paulo and Minas Gerais are expanding mechanical pest control registrations for organic farming jurisdictions. ANVISA regulates food-grade diatomaceous earth safety in soil applications. Southeast industrial zones are testing local deposit viability for import substitution.
Diatomite Mining Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a bifurcated structure where integrated calcination networks face toll-processing specialists. The sector consolidates around western US deposit proximity, with thermal processing economics and EPA particulate standards reshaping competitive boundaries. Two strategic archetypes dominate: vertically integrated miners with captive kilns, and regional deposit holders selling raw ore to third-party processors. Capacity expansion and portfolio diversification toward lithium extraction brine filtration represent the dominant competitive moves.
Among France-based chemical specialists, CECA Chemical exemplifies the integrated European filtration grade supplier archetype. Nevada and California operations anchor North American supply, with Imerys representing the scale-driven integrated producer model and EP Minerals occupying the regional deposit specialist position. Chinese mineral processors including Jilin Yuantong Mineral sit within the expanding domestic supply tier serving Asia-Pacific agricultural and industrial markets.
| Leading Market Players |
|---|
| Imerys |
| EP Minerals |
| Showa Chemical Industry Co., Ltd |
| Dicalite Management Group, LLC |
| Diatomit CJSC |
| Jilin Yuantong Mineral Co., Ltd. |
| Calgon Carbon Corporation |
| CECA Chemical |
| Grefco Minerals, Inc. |
| Others |
Pricing and Supply Chain Analysis
Skilled mining engineers and process technicians cluster around Nevada's diatomite belt, anchoring North American production expertise in a tight geographic radius. Labor-cost differentials between integrated calcination facilities and toll-processing operations drive pricing-tier spreads, with captive kiln operations commanding premium positioning over third-party thermal service arrangements.
Pricing Analysis
The bundled-vs-unbundled service split separates integrated producers from toll-dependent processors. Contract-based long-term offtake dominates municipal water treatment procurement, while spot transactions govern agricultural absorbent volumes. Price differentiation rests on calcination certification grade and volume scale, with FDA food-contact tiers commanding substantial premiums over industrial specifications. Cost compression in raw diatomite grades is intensifying because perlite substitution erodes commodity filter aid margins. Agricultural buyers exhibit highest price sensitivity, whereas pharmaceutical formulators prioritize performance documentation over unit economics.
Supply Chain Analysis
Natural gas supply rests on pipeline infrastructure concentrated in the western United States, creating thermal processing cost differentials against regions dependent on volatile spot markets. Diatomite extraction draws from Nevada, Oregon, and Washington deposits, with rotary kiln fabrication anchored in domestic heavy equipment manufacturing. Single-source vulnerability characterizes calciner capacity, where 18-24 month fabrication lead times constrain rapid demand response. Distribution runs through consolidated municipal purchasing cooperatives in the Intermountain West and distributor networks serving fragmented agricultural buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: Nevada's integrated processing infrastructure offers cost advantages against European producers facing EU Green Deal carbon border adjustments, while EPA drinking water mandates expand specification-grade demand faster than domestic calcination capacity can respond.
For Market Incumbents: To counter natural gas price volatility compressing thermal processing margins, secure long-term supply agreements with pipeline operators and invest in flash calcination technology with real-time temperature control. Backward integration into captive natural gas storage or renewable thermal alternatives reduces exposure to spot market spikes.
For New Entrants and Emerging Players: EPA Safe Drinking Water Act amendments in Arizona and Colorado open a window for specification-grade filter aid supply to municipal cooperatives upgrading intake infrastructure. Target lithium extraction brine filtration in Nevada's lithium triangle, where battery-grade salt recovery operations are testing diatomite pre-filtration protocols with limited qualified suppliers.
For Investors and Strategic Acquirers: Integrated specialty mineral producers are the most active acquirer in this space, seeking calcination capacity adjacent to western US deposits. Over a 5-10 year horizon, assets with certified clean production lines for EU REACH compliance represent prime acquisition targets. Watch EPA Lead and Copper Rule corrosion control revisions as the inflection indicator for municipal specification-grade demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Flash Calcination Technology Deployment | Real-time temperature control compresses premium gaps against European filter aid imports. |
| EU REACH Additive Reformulation | Clean production line certification creates first-mover advantage for US export competitiveness. |
| Lithium Brine Filtration Qualification | Nevada battery-grade salt recovery operations test diatomite pre-filtration specifications. |
| Municipal Cooperative Volume Aggregation | Utah and Idaho regional water authorities secure calcined grade pricing previously reserved for industrial accounts. |
| Respirable Silica Compliance Investment | OSHA enforcement drives capital-intensive dust suppression and worker monitoring system deployment. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement included mining operations managers, municipal water utility procurement directors, filtration equipment OEM technical specialists, and agricultural distributor sales heads. Secondary validation drew from EPA enforcement databases, USGS mineral commodity summaries, state environmental agency stockpiling protocols, and SEC filings of publicly traded specialty mineral producers. Bottom-up deposit capacity modeling and top-down end-use demand estimation were triangulated against trade flow data.
Segment-weighting approaches applied differential growth assumptions across calcined grades, raw diatomite, and filter aid specifications. The analytical framework modeled product type, application intensity, end-user industry concentration, and mining method economics across the projection horizon. CAGRs were derived from historical volume trajectories adjusted for regulatory demand inflections and capacity expansion timelines. Forecast inputs incorporated natural gas price scenario modeling and municipal infrastructure bond issuance patterns.
Revisions become necessary when EPA turbidity standard amendments accelerate, natural gas price volatility disrupts calcination economics, or lithium extraction brine filtration adoption scales beyond current pilot phases. Forecasts reflect documented assumptions about regulatory enforcement intensity and thermal processing technology diffusion rates. A small set of named triggers warrants ongoing watch: OSHA silica exposure threshold adjustments, EU carbon border adjustment implementation timing, and Nevada lithium triangle production ramp schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Minerals
Europe Frac Sand Market
Industrial Minerals
Chelated Minerals Market
Industrial Minerals
Global Cristobalite Market
Industrial Minerals
Mineral Enrichment Ingredients Market
Industrial Minerals
Global Feed Minerals Market
Industrial Minerals
Inorganic Salts Market
Industrial Minerals
Limestone Market
Industrial Minerals
Pyrophyllite Market
Industrial Minerals
Anhydrite Market
Industrial Minerals
Mineral Adsorbent Market
Industrial Minerals
Aluminium Potassium Sulphate Market
Industrial Minerals
Global Graphite Market
Industrial Minerals
Mediterranean Sea Salt Micro-Mineral Complexes Market
Industrial Minerals
North America Silica Sand Market
Industrial Minerals
China Feed Minerals Market
Industrial Minerals
Potassium Schoenite Market