
 Fly Ash and Ceramic Microsphere Market | 2026-2036
Fly Ash and Ceramic Microsphere Market Size, Share, and Industry Trends Forecast 2026-2036
Fly Ash and Ceramic Microsphere Market Analysis
Construction procurement is collapsing toward oil and gas buyers as shale drilling rebounds and well cementing specifications tighten. 3M Company leverages its materials science portfolio to dominate aerospace-grade hollow microsphere supply. Cenosphere India Pvt. Ltd. anchors South Asian demand through captive fly ash sourcing from thermal power corridors. Boral Limited competes across Australian and North American construction channels with integrated quarry-to-delivery logistics.
Fly ash and ceramic microspheres are alumino-silicate or glass-ceramic spheres formed during coal combustion or manufactured via spray pyrolysis, typically measuring 10–300 microns with bulk densities below 0.7 g/cm³ for hollow variants; they function primarily as lightweight fillers, thermal insulators, and rheology modifiers in cementitious systems. Hollow microspheres command premium positioning in aerospace and deepwater oilfield applications where compressive strength-to-weight ratios determine specification compliance. Fly ash supply concentrates around power plant proximity, creating margin pools for processors with rail-advantaged beneficiation facilities.
EPA coal ash disposal rules under the Resource Conservation and Recovery Act shape fly ash availability and pricing for microsphere recovery operations. ASTM C618 and EN 450-1 standards govern pozzolanic performance in concrete applications, directly filtering market access for unbeneficiated material. Stakeholders must track EPA enforcement patterns and ASTM specification revisions to anticipate feedstock cost shifts and qualification barriers.
Market Dynamics
EPA coal ash disposal rules under the Resource Conservation and Recovery Act are compressing fly ash availability while oilfield cementing specifications tighten, forcing processors to secure rail-advantaged beneficiation positions or lose margin to integrated power plant operators.
Growth Catalysts
- Lightweight concrete specifications:ASTM C618 and EN 450-1 pozzolanic standards are tightening qualification thresholds, filtering out unbeneficiated material and concentrating volume with certified processors.
- Deepwater oilfield demand:Shale drilling rebounds in the Permian and Bakken formations are accelerating well cementing procurement for hollow microspheres with compressive strength-to-weight ratios above 10,000 psi.
- Aerospace thermal insulation:Hollow ceramic microspheres are displacing traditional syntactic foam in satellite and unmanned aerial vehicle structures where mass reduction determines payload economics.
Market Restraints
- Feedstock concentration risk:Quality fly ash supply clusters within 150 kilometers of coal-fired generation corridors in China, India, and the United States, exposing processors to rail cost volatility and utility contract renegotiation.
- Spray pyrolysis energy intensity:Manufactured ceramic microsphere production requires sustained furnace temperatures above 1,200°C, anchoring unit economics to natural gas pricing and carbon border adjustment exposure.
- Silica fume substitution:Elkem Microsilica and similar densified silica fume products are capturing specification share in high-performance concrete where ultra-low permeability overrides density targets.
Strategic Opportunities
- Beneficiation technology convergence:Electrostatic separation and froth flotation integration is unlocking cenospheres from ponded ash deposits previously classified as waste, expanding recoverable reserves in the United States and Poland.
- India PLI scheme alignment:Domestic manufacturing incentives for construction materials are creating tariff-advantaged supply positions for microsphere processors with captive thermal power partnerships.
- Carbon capture utilization:Mineralization pathways using fly ash as a feedstock for concrete CO₂ sequestration are attracting offtake commitments from cement majors seeking Scope 3 reductions.
Industry Challenges
- ASTM C618 certification timelines:New source qualification requires 18-24 months of pozzolanic activity index testing, freezing out opportunistic traders and demanding sustained capital commitment.
- Beneficiation equipment lead times:Dense medium separators and air classifiers face 12-16 month delivery backlogs from German and Chinese OEMs, throttling capacity expansion for qualified processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fly Ash and Ceramic Microsphere Market |
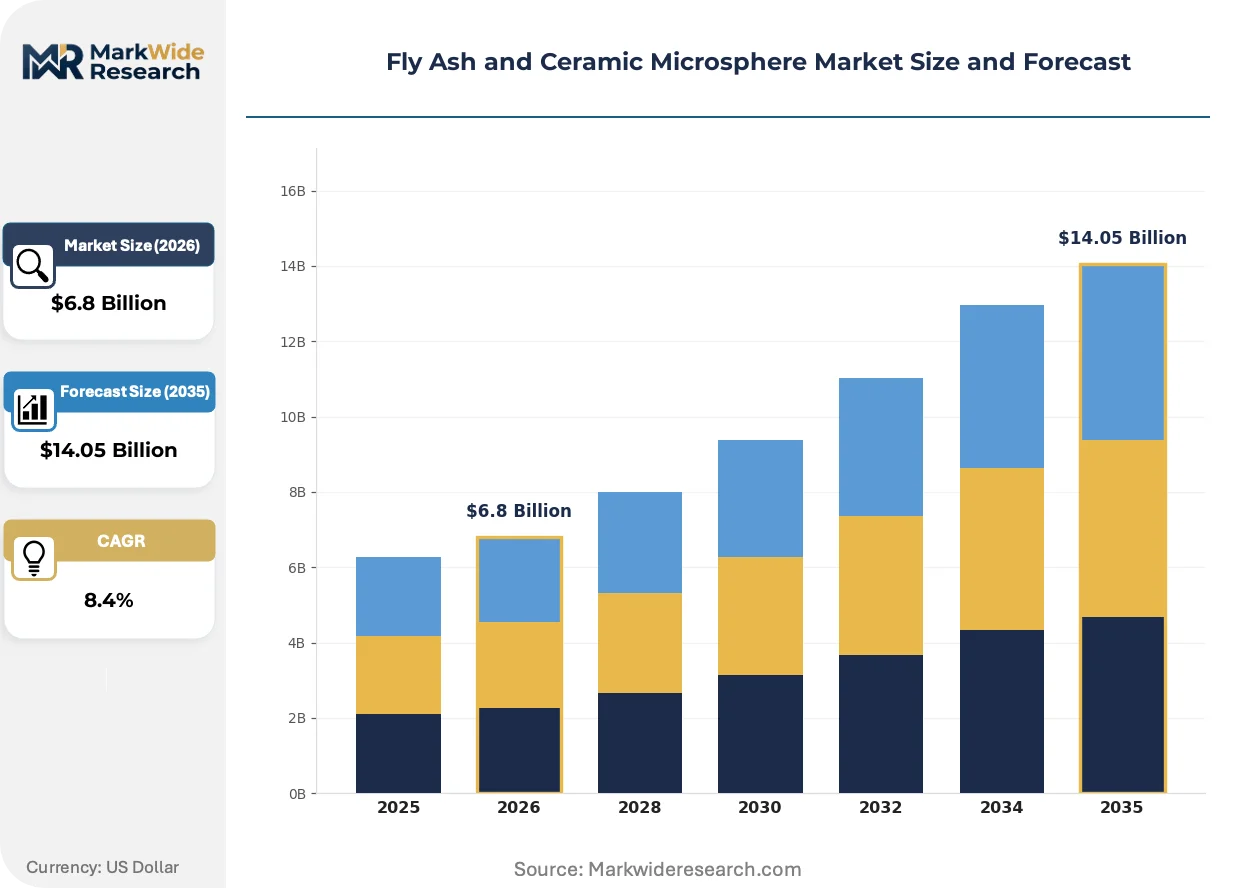
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fly Ash, Hollow Microspheres, Solid Microspheres, Expanded Microspheres End User: Construction, Aerospace, Automotive, Oil & Gas Application: Lightweight Concrete, Insulation Materials, Fillers, Coatings Form: Powder, Granule, Sphere, Composite |
| Companies Covered | Shijiazhuang Horse Building Materials, 3M Company, Cenosphere India Pvt. Ltd., Reslab, CenoStar, Boral Limited, Ashtech India Pvt. Ltd., Omya, Zhengzhou Hollowlite Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fly Ash and Ceramic Microsphere Market Emerging Trajectories
Process intensification and specification fragmentation are compressing traditional supply hierarchies while regulatory enforcement patterns and buyer procurement models force simultaneous adaptation across technology, compliance, and commercial functions.
Spray pyrolysis manufacturing is fragmenting the hollow microsphere supply base by enabling tailored alumino-silicate compositions outside coal combustion byproduct constraints. Aerospace contractors and deepwater oilfield service firms are qualifying these engineered spheres for applications where batch consistency exceeds cost sensitivity. The technology is fragmenting procurement patterns by creating dual-source strategies that bypass traditional power plant dependency.
EPA enforcement of the 2015 Coal Ash Rule is accelerating pond closure timelines and forcing utilities to accelerate beneficiation partnerships or face remediation liability. Beneficiation processors with rail-advantaged positions are securing long-term offtake agreements as utilities seek to monetize stranded ash inventories. Construction-grade microsphere supply in the United States is consolidating around processors with established ASTM C618 qualification protocols.
Buyer consolidation among ready-mix concrete majors is compressing supplier rosters and demanding volume-commitment pricing structures that favor integrated processors over traders. LafargeHolcim, HeidelbergCement, and Cemex procurement teams are consolidating microsphere sourcing through direct utility partnerships or captive beneficiation investments. This concentration is most visible in the United States and Germany where construction material specification uniformity enables single-source qualification at regional scale.
Fly Ash and Ceramic Microsphere Market Segmentation
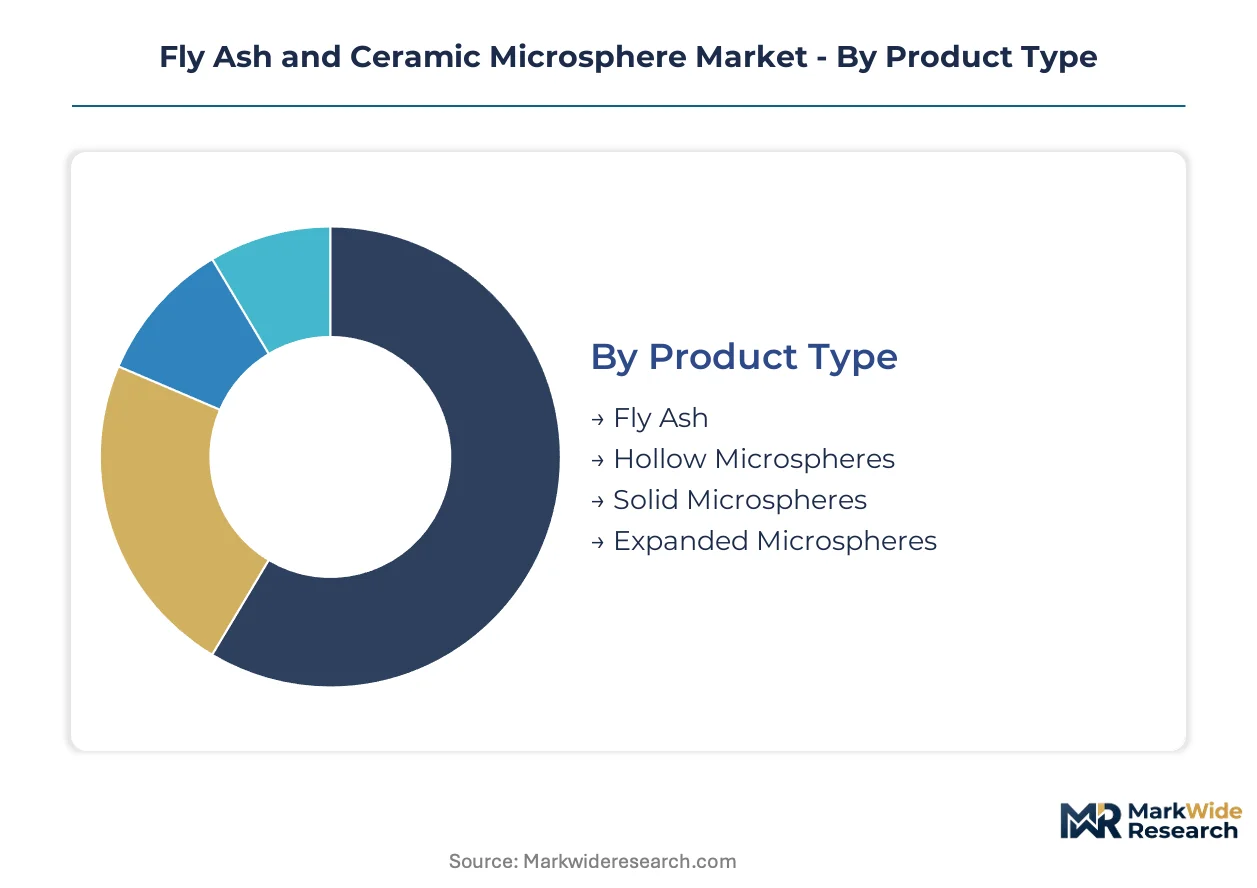
Segmentation in the fly ash and ceramic microsphere market reveals divergent margin structures across product types and end-use verticals. Specification intensity varies dramatically between construction-grade bulk supply and aerospace-qualified engineered materials.
Product Type:
Hollow microspheres command the widest margin spreads due to compressive strength-to-weight performance premiums in oilfield and aerospace applications.
- Fly Ash:Coal combustion byproduct cenospheres and precipitator fines serve as pozzolanic extenders in cementitious systems. ASTM C618 qualification requirements in the United States and EN 450-1 compliance in Europe filter unbeneficiated material, concentrating procurement with rail-advantaged processors near Ohio River and Yangtze River power corridors.
- Hollow Microspheres:Alumino-silicate spheres with bulk densities below 0.7 g/cm³ function as lightweight fillers and thermal insulators. Deepwater well cementing specifications above 10,000 psi compressive strength in the Gulf of Mexico and North Sea anchor demand, while satellite manufacturers in California and Bavaria qualify engineered variants for mass-critical payloads.
- Solid Microspheres:Glass-ceramic or alumina-based dense spheres provide grinding media and reflective bead applications.
- Expanded Microspheres:Thermoplastic shell-encapsulated gas spheres serve as blowing agents and density reducers in polymer systems.
Fly Ash holds installed capacity. Hollow Microspheres is rotating up the share rankings.
End User:
Customer concentration patterns split between specification-driven aerospace procurement and volume-driven construction sourcing.
- Construction:Ready-mix concrete producers and precast manufacturers absorb the majority of construction-grade cenospheres. LafargeHolcim, HeidelbergCement, and Cemex procurement consolidation in the United States and Germany compresses supplier rosters toward direct utility partnerships or captive beneficiation investments.
- Aerospace:Prime contractors and Tier 1 structures suppliers qualify hollow ceramic microspheres for thermal protection systems and syntactic foam cores. 3M Company and specialty engineered materials suppliers dominate qualification protocols for satellite bus manufacturers in California and unmanned aerial vehicle producers in Israel.
- Automotive:Underbody coatings and lightweight structural composites drive demand for density-modifying fillers.
- Oil & Gas:Well cementing slurry specifications for deepwater and unconventional drilling anchor premium hollow microsphere procurement.
Construction commands volume scale. Aerospace is climbing the fastest on value per kilogram metrics.
Application:
Application-driven pricing stratification separates commodity construction fill from performance-specified insulation and coating systems.
- Lightweight Concrete:Cenospheres and processed fly ash reduce dead load in high-rise and infrastructure concrete. China's Three Gorges Dam region and India's National Capital Region thermal power corridors supply beneficiated material for domestic megaproject consumption.
- Insulation Materials:Hollow microspheres displace traditional syntactic foam in cryogenic and high-temperature applications. LNG tank insulation specifications in Qatar and Singapore anchor demand for thermal conductivity below 0.05 W/m·K.
- Fillers:Density reduction and viscosity modification across polymer and resin systems.
- Coatings:Reflective and thermal barrier applications in industrial and automotive finishes.
Lightweight Concrete maintains volume leadership. Insulation Materials is gaining share fastest on energy infrastructure buildout.
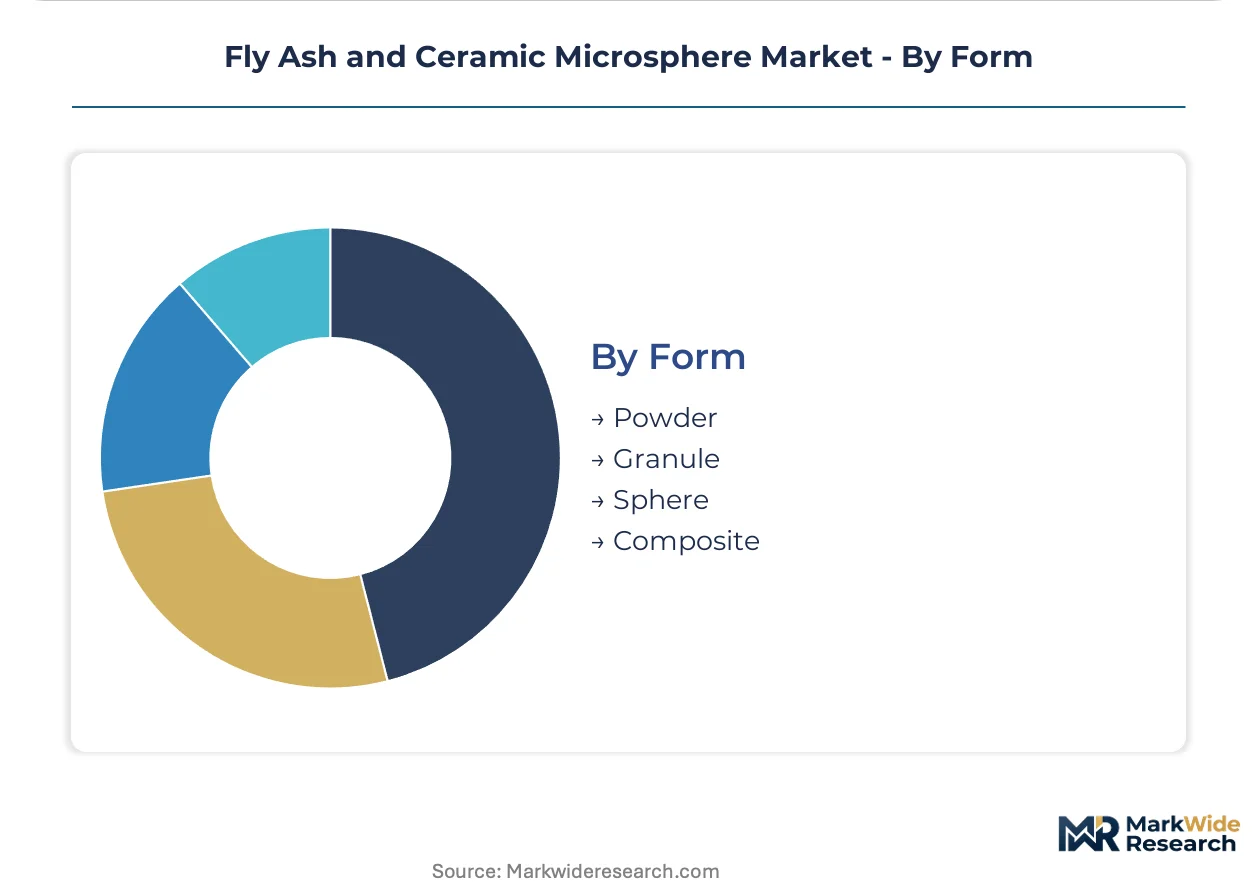
Form:
Physical form determines handling economics and downstream processing integration requirements.
- Powder:Fine-ground fly ash and pulverized microspheres integrate directly into dry-mix mortars and cement blends. Pneumatic conveying infrastructure at German and Chinese cement terminals favors bulk powder procurement.
- Granule:Agglomerated microspheres for controlled release and handling stability.
- Sphere:Intact hollow or solid spheres preserve compressive strength and thermal performance for specification-critical applications.
- Composite:Pre-compounded microsphere-resin systems for direct molding and casting.
Powder dominates logistics infrastructure. Sphere forms are expanding most quickly on specification premium capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Quality fly ash supply clusters within 150 kilometers of coal-fired generation corridors in China, India, and the United States. Rail-advantaged beneficiation facilities near these thermal power centers capture margin pools as EPA enforcement accelerates pond closure timelines.
United States
Deepwater well cementing specifications above 10,000 psi compressive strength anchor hollow microsphere procurement from Gulf of Mexico drilling operations. EPA enforcement of the 2015 Coal Ash Rule forces utilities to accelerate beneficiation partnerships or face remediation liability. Ohio River power corridor processors with established ASTM C618 qualification protocols secure long-term offtake agreements as stranded ash inventories monetize.
China
Lightweight concrete specifications for high-rise infrastructure and megaproject construction drive cenospheres consumption through domestic supply chains. GB standards and MEE environmental compliance requirements filter unbeneficiated material toward certified processors. Yangtze River Delta thermal power corridors supply beneficiated material for Three Gorges Dam region consumption and coastal manufacturing clusters.
India
National Capital Region thermal power corridors and Gujarat captive generation facilities feed construction-grade microsphere demand for infrastructure buildout. PLI scheme domestic manufacturing incentives create tariff-advantaged supply positions for processors with captive thermal power partnerships. Maharashtra and Telangana cement majors consolidate sourcing through direct utility partnerships or captive beneficiation investments.
Germany
Ready-mix concrete procurement consolidation by HeidelbergCement and regional majors compresses supplier rosters toward integrated processors. EN 450-1 pozzolanic compliance requirements and EU Green Deal carbon reduction targets shape qualification barriers. Ruhr industrial corridor and Bavarian cement terminals favor bulk powder procurement through pneumatic conveying infrastructure.
Australia
Integrated quarry-to-delivery logistics networks serve construction channels across eastern seaboard infrastructure projects. State-level environmental regulations governing coal ash reuse create compliance frameworks for beneficiation operations. New South Wales and Queensland power corridor processors leverage rail access to capture volume commitments from regional concrete producers.
Fly Ash and Ceramic Microsphere Market Vendor Landscape
Concentration sits with diversified materials conglomerates and regional beneficiation specialists who control rail-advantaged feedstock access. The market structure tiers between premium hollow microsphere suppliers serving aerospace and deepwater oilfield specifications, and construction-grade processors competing on ASTM C618 qualification and logistics efficiency. Three archetypes dominate: integrated power plant operators with captive beneficiation assets, independent processors with rail-served terminal networks, and engineered materials specialists manufacturing via spray pyrolysis. Competitive moves center on securing long-term utility offtake agreements and expanding ASTM qualification protocols to new source regions.
Among Asia-Pacific beneficiation specialists, Cenosphere India Pvt. Ltd. and Zhengzhou Hollowlite Materials exemplify regional feedstock control strategies. 3M Company occupies a position on the premium-tier vector representing engineered materials capabilities. Boral Limited anchors integrated logistics positioning across Australian and North American construction channels. These named entities illustrate archetype differentiation rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Shijiazhuang Horse Building Materials |
| 3M Company |
| Cenosphere India Pvt. Ltd. |
| Reslab |
| CenoStar |
| Boral Limited |
| Ashtech India Pvt. Ltd. |
| Omya |
| Zhengzhou Hollowlite Materials |
| Others |
Supply Flow & Price Mechanics
Beneficiation scale economies at rail-served terminals in Ohio River and Yangtze River corridors compress unit costs below threshold levels for unqualified traders, concentrating margin capture with ASTM C618-certified processors while anchoring price floors to utility contract renegotiation cycles. This scale-driven consolidation simultaneously shapes procurement patterns among ready-mix concrete majors and hollow microsphere buyers in deepwater oilfield applications.
Pricing Analysis
Volume-discount tiering structures separate aerospace-qualified hollow microspheres from construction-grade cenospheres and unbeneficiated fly ash. Pricing stratifies across premium, standard, and economy tiers based on compressive strength certification and ASTM C618 qualification status. Cost compression in construction-grade supply is intensifying because silica fume substitution captures high-performance concrete specifications. Ready-mix concrete producers exhibit highest price sensitivity, while aerospace contractors prioritize batch consistency over unit cost.
Supply Chain Analysis
Strategic stockpile preferences dominate construction-grade procurement, with ready-mix concrete majors securing 18-24 month offtake agreements to buffer ASTM C618 certification timelines. Supply concentrates in China, India, and the United States around thermal power corridors within 150 kilometers of coal-fired generation. Feedstock draws from coal combustion residuals, natural gas for spray pyrolysis, and rail logistics capacity. Single-source vulnerability stems from utility contract concentration. Distribution runs through rail-served beneficiation terminals to pneumatic conveying infrastructure at cement terminals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fly ash beneficiation is approaching a platform-economics inflection as ASTM C618 qualification protocols create interoperability barriers that lock in certified processors and lock out opportunistic traders, similar to API specifications in oilfield services.
For Market Incumbents: Compound rail-advantaged terminal networks through captive utility partnerships in Ohio River and Yangtze River corridors before pond closure timelines accelerate. Deepen ASTM C618 qualification protocols to new source regions as a defensive moat against spray pyrolysis entrants. Prioritize backward integration into power plant beneficiation assets to secure feedstock control as EPA enforcement tightens disposal economics. For New Entrants and Emerging Players: Post-qualification technical service gaps in ASTM C618 compliance documentation present white-space opportunities for digital certification platforms serving mid-sized ready-mix concrete producers. Target India's PLI scheme-aligned processors in Maharashtra and Telangana thermal power corridors where domestic manufacturing incentives reduce tariff exposure. Deploy beneficiation-as-a-service models to utilities facing remediation liability without captive processing capability. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors rail-served beneficiation specialists with established qualification protocols over spray pyrolysis manufacturing given feedstock cost advantages and regulatory moats. Five-to-ten year viability hinges on carbon capture utilization pathways monetizing fly ash mineralization for concrete CO₂ sequestration. Monitor EPA enforcement patterns as inflection indicator for stranded ash inventory monetization velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Power Plant Beneficiation | Secures captive fly ash feedstock from Ohio River utility partners facing EPA pond closure mandates. |
| ASTM C618 Qualification Expansion | Unlocks construction-grade procurement from LafargeHolcim and HeidelbergCement regional consolidation. |
| Spray Pyrolysis Capacity Buildout | Captures aerospace and deepwell oilfield specifications where batch consistency exceeds coal byproduct constraints. |
| Carbon Capture Utilization Partnership | Attracts cement major offtake commitments for Scope 3 reduction through fly ash mineralization pathways. |
| Rail-Served Terminal Network Extension | Compresses logistics costs below threshold for unqualified traders in Yangtze River and Three Gorges corridors. |
Methodological Framework
The analysis maps hollow microsphere, fly ash, and solid microsphere sub-sectors, each validated through beneficiation plant managers, ready-mix concrete procurement leads, aerospace materials qualification engineers, and oilfield cementing specialists. Primary interviews combined with secondary validation from EPA enforcement records, ASTM specification revisions, customs and trade data, and SEC filings from construction materials conglomerates. Bottom-up capacity and volume modeling triangulated against top-down end-use consumption estimates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, end-use vertical, application function, and physical form. CAGRs derived from historical trajectory analysis and demand elasticity coefficients. Industry-specific forecast inputs incorporate EPA coal ash disposal rule enforcement intensity and shale drilling activity patterns in Permian and Bakken formations.
Underlying assumptions cover ASTM C618 certification timeline stability, natural gas pricing for spray pyrolysis energy intensity, and rail logistics cost trajectories, with deviation risk concentrated in silica fume substitution rates and carbon border adjustment implementation. Revision becomes warranted when EPA enforcement patterns cross thresholds that accelerate utility pond closure timelines beyond modeled beneficiation partnership formation rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Taiwan Ceramic Tiles Market
Ceramics
Medical Ceramics Market
Ceramics
Carbon-Ceramic Discs Market
Ceramics
Glass Ceramics Market
Ceramics
Colloidal Alumina Market
Ceramics
South Korea Ceramic Sanitaryware Market
Ceramics
Ceramic Pigments Market
Ceramics
Wollastonite Market
Ceramics
Global Alumina Trihydrate Market
Ceramics
Relaxor Ferroelectric Ceramics Market
Ceramics
Nano Ceramic Coatings Market
Ceramics
Global Wollastonite Powder Market
Ceramics
Refractories Market
Ceramics
Ceramic Lining Market
Ceramics
Heat-Resistant Ceramic Tableware Market
Ceramics
High Temperature Ceramics Market