
 Europe Diatomite Market | 2026-2036
Europe Diatomite Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Diatomite Market Insights
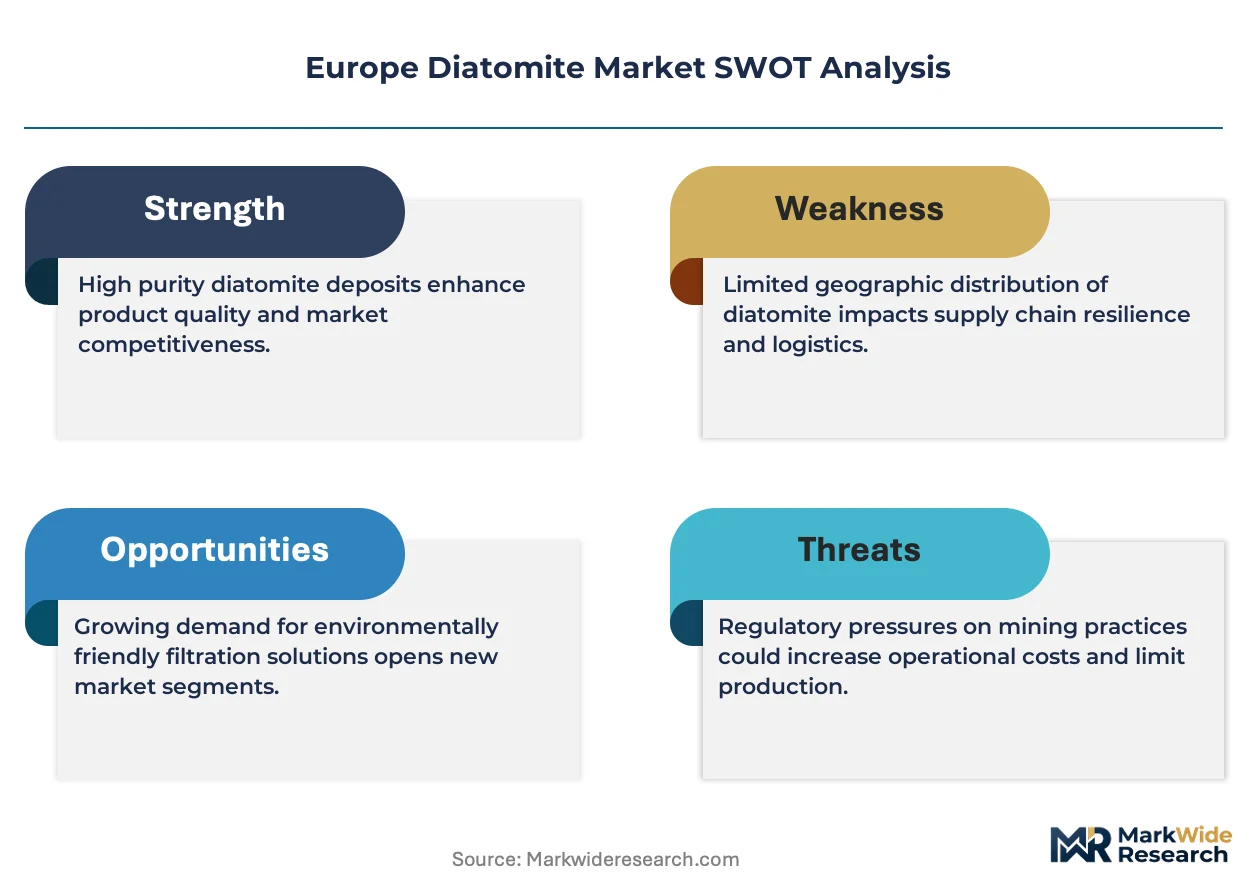
The gap between premium filtration-grade diatomite and commodity construction filler is broadening across European supply chains. Imerys S.A. leverages its vertically integrated mining and processing footprint to dominate high-purity calcined grades for pharmaceutical and food applications. EP Minerals sustains competitive positioning through specialized absorption products serving environmental remediation contracts.
Diatomite consists of fossilized remains of diatoms with high porosity, silica content exceeding 80 percent, and particle sizes ranging from 10 to 200 micrometers, making it valuable for filtration, absorption, and lightweight aggregate applications. Calcined diatomite leads product type demand due to its superior permeability and structural stability in high-temperature filtration systems. Filtration applications command the strongest margin pools as beverage and pharmaceutical processors prioritize purity certification under evolving EU standards.
REACH registration requirements and the EU Green Deal carbon accounting framework are reshaping extraction permits and processing energy disclosures across member states. ECHA substance evaluation protocols now require detailed toxicological profiles for diatomaceous earth used in food contact materials. Stakeholders must monitor pending revisions to F-Gas Regulation and industrial emissions directives that could redirect demand toward activated diatomite alternatives in climate-controlled filtration systems.
Market Dynamics
REACH substance evaluation protocols and the EU Green Deal carbon accounting framework are tightening extraction permits and processing disclosures across member states. Filtration-grade producers face escalating compliance costs while commodity-grade operators confront margin compression from energy disclosure mandates.
Growth Catalysts
- Beverage filtration mandates:Beer and wine processors across Germany, France, and Italy are upgrading to calcined diatomite systems to meet EFSA purity certification for food contact materials.
- REACH registration depth:Detailed toxicological profiling requirements for diatomaceous earth in pharmaceutical applications are locking in incumbent suppliers with established dossiers.
- Refractory cluster concentration:Steel and glass manufacturers in Northern Italy and the Ruhr Valley are expanding high-temperature filtration capacity using flux-calcined grades.
Market Restraints
- Energy cost volatility:Natural gas price spikes in Germany and the Netherlands are compressing margins for calcination-intensive production of high-permeability filtration grades.
- Substitute filtration media:Activated carbon and ceramic membrane systems are capturing share in pharmaceutical pre-filtration applications where thermal regeneration is prioritized.
- Deposit depletion gradients:Spanish and Greek mining concessions face declining ore quality, forcing processors to blend stocks or absorb higher beneficiation costs.
Strategic Opportunities
- Environmental remediation absorption:Spill response contractors in France and Belgium are specifying engineered diatomite for hydrocarbon containment under tightened MEE-equivalent discharge protocols.
- CSRD-aligned carbon disclosure:Scope 3 reporting requirements are creating first-mover advantage for operators with verified low-carbon calcination processes using renewable thermal energy.
- Biopharma single-use filtration:Cell culture media producers in Switzerland and southern Germany are testing diatomite depth filtration as a cost alternative to multi-layer synthetic cartridges.
Industry Challenges
- Specialized mineral processing talent:Retiring engineers with expertise in diatomite calcination kinetics and particle size engineering are thinning the technical workforce across Spanish and Italian operations.
- Legacy equipment retrofit timelines:Pre-2010 rotary kilns in Eastern European facilities require multimillion-euro upgrades to meet F-Gas Regulation leak detection and industrial emissions directive standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Diatomite Market |
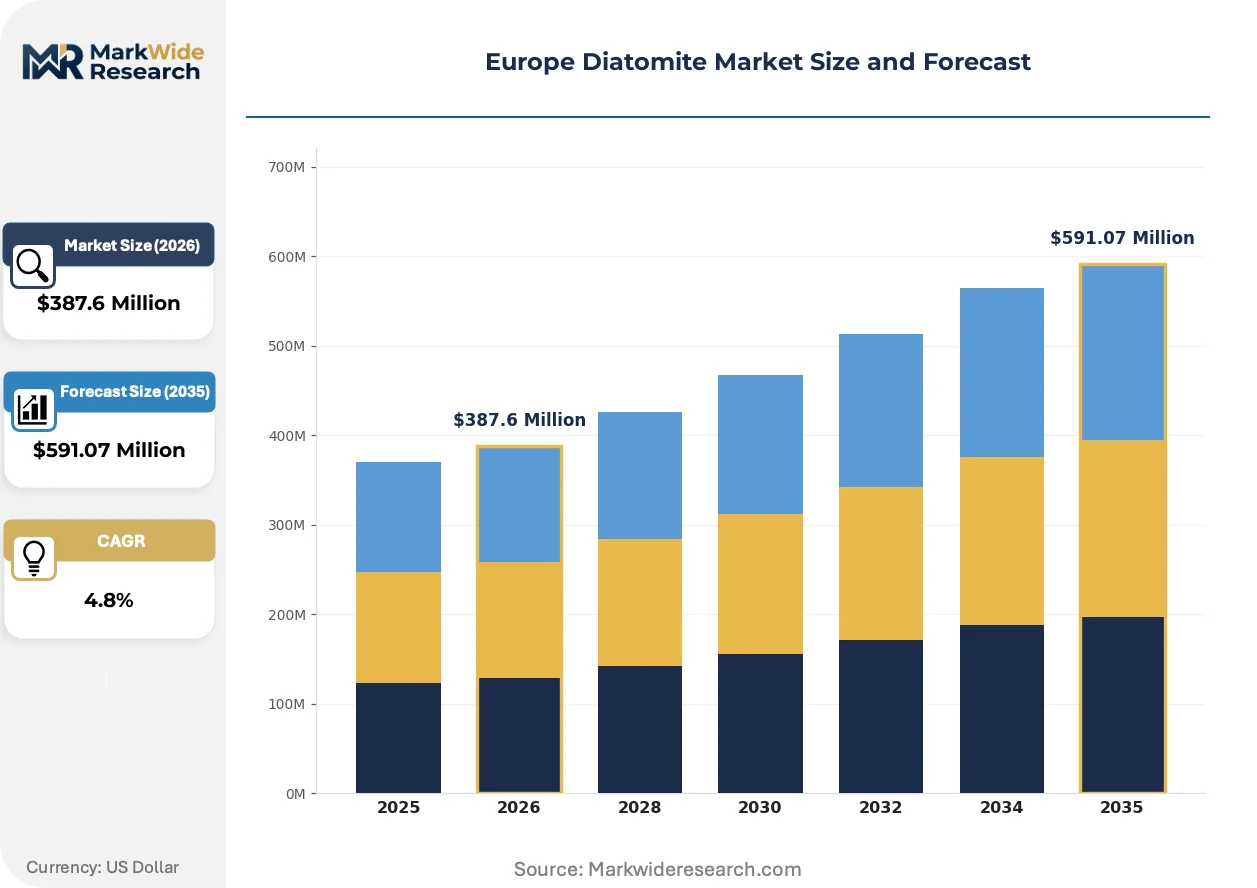
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $591.07 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Uncalcined Diatomite, Calcined Diatomite, Diatomaceous Earth, Activated Diatomite Application: Filtration, Absorption, Construction, Agriculture End User: Food & Beverage, Pharmaceuticals, Paints & Coatings, Environmental Distribution Channel: Online, Direct Sales, Distributors, Retail |
| Companies Covered | Imerys S.A., EP Minerals, Dicalite Management Group, Damolin, Diatomit CJSC, Decalite Europe, Showa Chemical Industry, Calgon Carbon Corporation, CECA, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Diatomite Market Trends and Innovations
Processing automation and regulatory disclosure technologies are compressing production cycles while expanding addressable application sets. These shifts favor capital-rich operators capable of integrating digital traceability with thermal processing control.
Advanced calcination control systems using real-time thermal imaging and automated kiln atmosphere adjustment are automating quality consistency for pharmaceutical-grade diatomite. Belgian and Dutch filtration media specialists are deploying these systems to reduce batch rejection rates. The technology is automating labor-intensive quality assurance steps that previously required manual sieve analysis and permeability testing.
ECHA substance evaluation protocols now mandate updated toxicological profiles for diatomaceous earth in food contact applications. Industrial mineral processors must submit revised registration dossiers or face market access restrictions. High-purity calcined grade suppliers in Germany and France are accelerating dossier preparation to maintain supply continuity to beverage and pharmaceutical customers.
Consolidated procurement by multinational beverage groups is compressing supplier lists and extending contract durations. Procurement teams at major brewing and soft drink operations are requiring multi-year supply agreements with embedded carbon accounting. This pattern is most pronounced in Germany, where three large beverage cooperatives now manage diatomite sourcing through centralized technical purchasing functions.
Europe Diatomite Market Segmentation
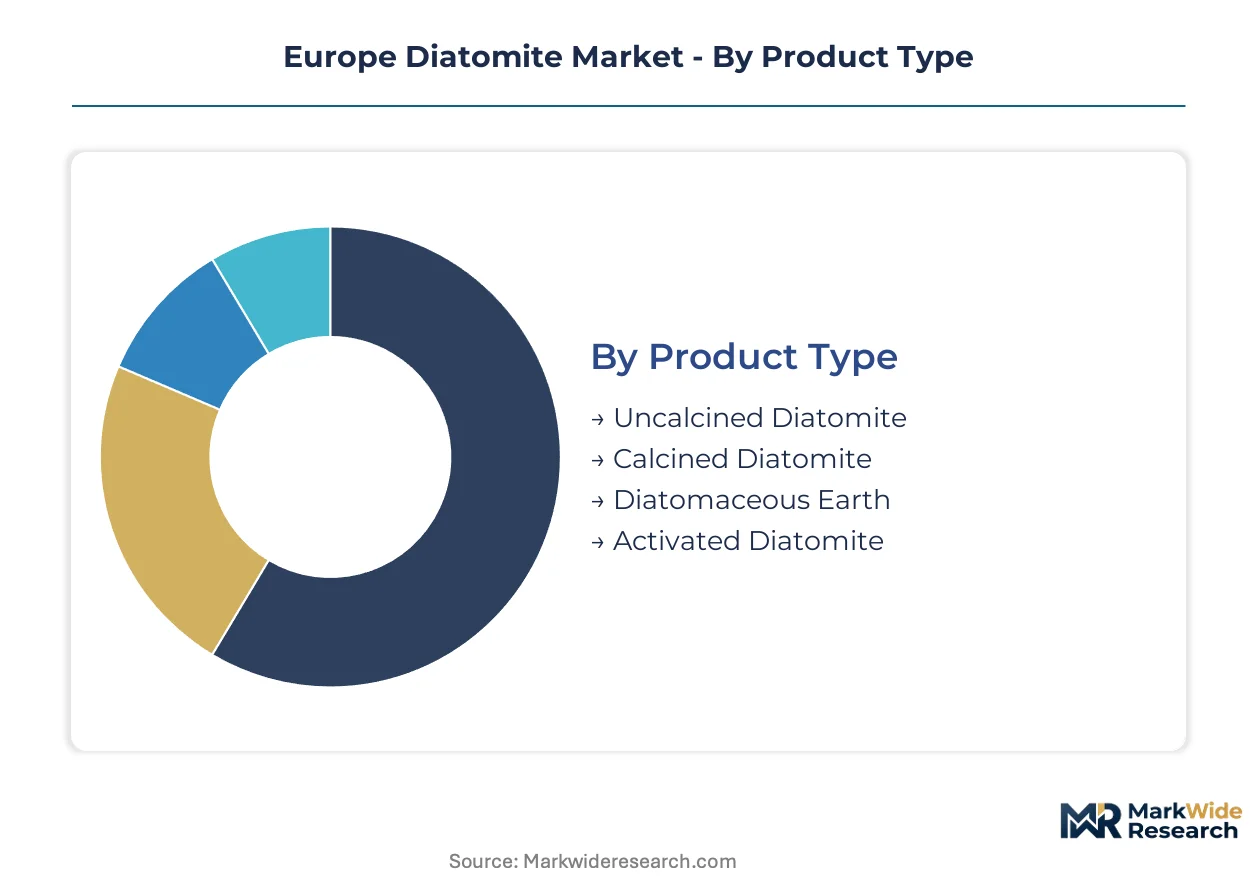
European diatomite procurement patterns diverge sharply between high-purity calcined grades for regulated industries and commodity uncalcined material for construction fill. Understanding these segment boundaries reveals where compliance investments concentrate versus where price competition dominates.
Product Type:
Upgrade cycles favor thermal-processed grades as beverage and pharmaceutical processors replace legacy filtration media with EFSA-certified alternatives.
- Calcined Diatomite:Thermal treatment at 800-1000°C drives off organic content and increases permeability. German and French beverage cooperatives specify flux-calcined grades for beer clarification under tightened food contact material protocols.
- Uncalcined Diatomite:Natural sedimentary ore retains higher moisture and lower permeability. Spanish construction aggregate producers blend uncalcined material into lightweight concrete for thermal insulation applications.
- Diatomaceous Earth:Raw fossilized diatom frustules serve agricultural pest control and animal feed supplement markets across Italy and Greece.
- Activated Diatomite:Surface-modified grades engineered for hydrocarbon absorption. Belgian spill response contractors specify activated variants under tightened MEE-equivalent discharge regulations.
Volume placements concentrate in Calcined Diatomite; the faster expansion belongs to Activated Diatomite.
Application:
Margin stratification tracks regulatory intensity, with filtration commanding certification premiums while construction competes on delivered cost per ton.
- Filtration:Depth filtration for beverages, pharmaceuticals, and swimming pools demands controlled particle size distributions. Ruhr Valley steel plants deploy flux-calcined grades for molten metal filtration in refractory linings.
- Absorption:Spill containment and pet litter applications exploit high porosity and chemical inertness. French environmental contractors source engineered absorption media for industrial hydrocarbon recovery.
- Construction:Lightweight aggregate and pozzolanic additive functions in concrete and plasterboard. Greek processors supply uncalcined material to Mediterranean insulation board manufacturers.
- Agriculture:Soil amendment and insecticidal dusting leverage abrasive silica structure. Italian olive oil producers apply diatomaceous earth as mechanical pest control in organic certification regimes.
Revenue concentration sits with Filtration; Absorption gains share fastest among climate remediation procurement.
End User:
Customer sophistication determines specification stringency, with pharmaceutical and food contact applications imposing toxicological dossier requirements that commodity buyers bypass.
- Food & Beverage:Beer, wine, and soft drink processors require EFSA-compliant purity certification. Centralized technical purchasing at German brewing cooperatives now mandates embedded carbon accounting in multi-year supply agreements.
- Pharmaceuticals:Cell culture media and API filtration demand validated low-endotoxin grades. Swiss biopharma manufacturers test diatomite depth filtration against synthetic cartridge alternatives.
- Paints & Coatings:Matting agent and rheology modifier functions in architectural finishes. French and Italian coatings formulators specify controlled particle sizes for flatting efficiency.
- Environmental:Remediation contractors and wastewater treatment operators specify absorption capacity per unit cost. Belgian industrial spill response procurement favors engineered diatomite under tightened discharge protocols.
Contract duration extends longest in Food & Beverage; Environmental represents the steepest expansion trajectory.
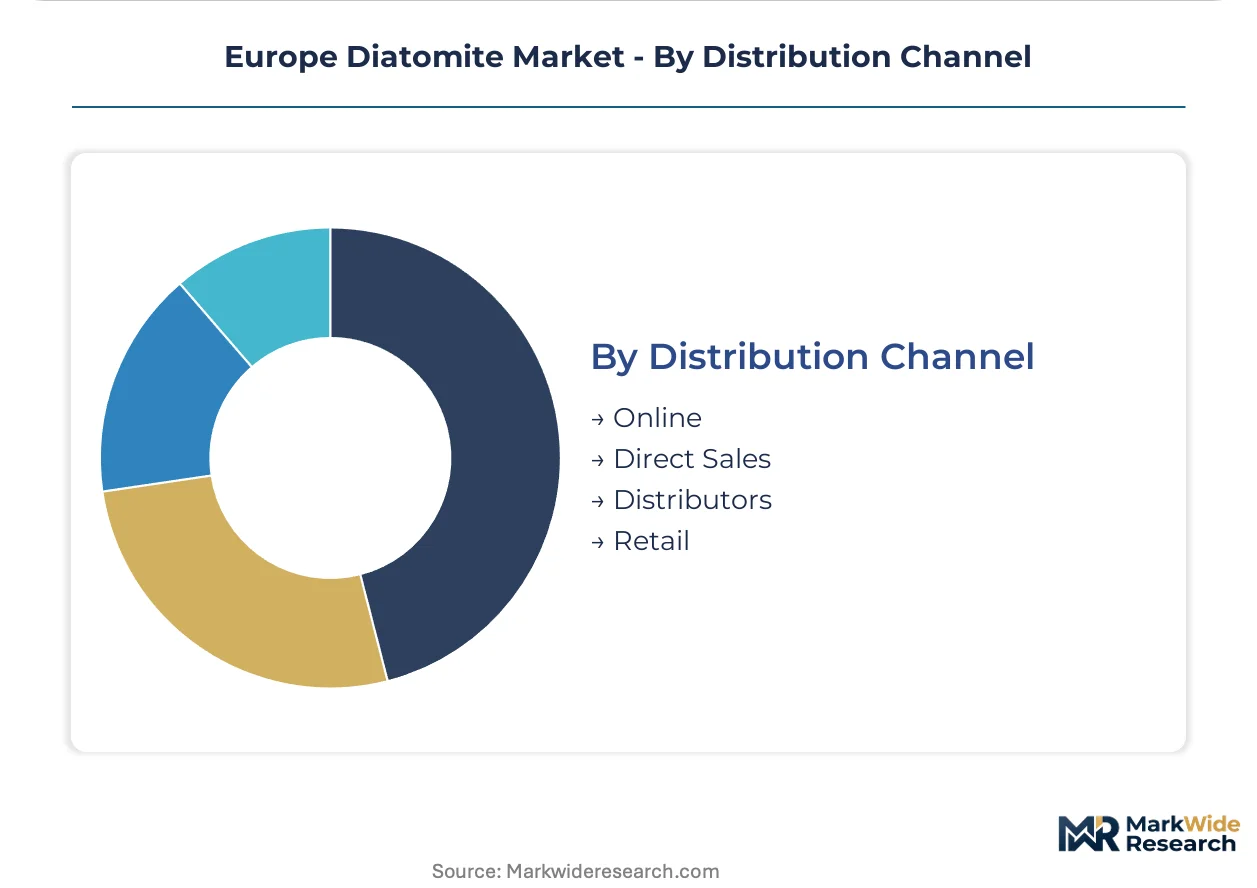
Distribution Channel:
Channel selection reflects order scale and technical service intensity, with bulk filtration grades moving direct while specialty absorption products flow through technical distributors.
- Direct Sales:Long-term supply agreements with multinational beverage and pharmaceutical manufacturers. German calcined grade producers maintain dedicated technical account teams for EFSA dossier support.
- Distributors:Regional mineral specialists stock construction and agricultural grades for fragmented SME buyers. Italian distributors serve terrazzo and plasterboard manufacturers with blended uncalcined material.
- Online:Agricultural pest control and pet litter products reach hobby farmers through specialty chemical e-commerce. Greek processors list bulk uncalcined grades on B2B platforms for Mediterranean buyers.
- Retail:Small-package garden and pool filtration products through building supply chains. French garden centers stock diatomaceous earth insecticide under organic certification labels.
Transaction value concentrates in Direct Sales; Online climbs fastest among agricultural and small-industrial procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ruhr Valley industrial corridor anchors European diatomite procurement through its dense concentration of steel filtration and refractory manufacturing. German beverage cooperatives and pharmaceutical clusters in the region drive specification-grade demand under tightened EU regulatory frameworks. Cross-border supply chains link calcination facilities to processing plants across the Low Countries and Northern France.
Germany
Brewing cooperatives in Bavaria and North Rhine-Westphalia specify flux-calcined grades for beer clarification systems. EFSA purity certification requirements under REACH substance evaluation protocols lock in incumbent suppliers with established toxicological dossiers. The Ruhr Valley steel cluster deploys high-temperature filtration media for molten metal processing in refractory linings.
France
Environmental remediation contractors in the Hauts-de-France region engineer diatomite for hydrocarbon spill containment under tightened discharge protocols. The EU Green Deal carbon accounting framework mandates energy disclosure for mineral processing operations. Champagne wine producers in the Grand Est region upgrade filtration infrastructure to meet evolving food contact material standards.
Italy
Steel and glass manufacturers in Lombardy and Veneto expand high-temperature filtration capacity using specialized calcined grades. Retiring engineers with diatomite calcination expertise thin the technical workforce across Northern Italian operations. Olive oil producers in Tuscany apply diatomaceous earth for mechanical pest control under organic certification regimes.
Spain
Construction aggregate producers blend uncalcined diatomite into lightweight concrete for thermal insulation applications across Mediterranean markets. Mining concessions in Andalusia face declining ore quality, forcing processors to absorb higher beneficiation costs. Pre-2010 rotary kilns in Eastern Spanish facilities require multimillion-euro upgrades to meet industrial emissions directive standards.
Belgium
Spill response contractors specify activated diatomite variants for industrial hydrocarbon recovery under MEE-equivalent discharge regulations. Advanced calcination control systems using real-time thermal imaging automate quality consistency for pharmaceutical-grade production. Dutch-Belgian filtration media specialists deploy these technologies to reduce batch rejection rates in cross-border supply chains.
Europe Diatomite Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification-grade and energy-disclosure dimensions. The vendor base stratifies between capital-rich operators with integrated mining-processing footprints and regional specialists serving construction and agricultural segments. Three archetypes dominate: vertically integrated multinationals controlling high-purity calcination assets, regional absorption-media specialists, and uncalcined commodity traders. Competitive moves concentrate on dossier preparation for REACH registration continuity and renewable thermal energy sourcing for carbon disclosure alignment.
Within the integrated multinational tier, Imerys S.A. and EP Minerals occupy positions exemplifying scale-driven calcination expertise and specialized absorption product development respectively. Dicalite Management Group represents the mid-tier specialist archetype with processing flexibility across grade categories. These named entities anchor industry-level commentary on how regulatory compliance investments and energy transition requirements reshape competitive positioning across European supply chains.
| Leading Market Players |
|---|
| Imerys S.A. |
| EP Minerals |
| Dicalite Management Group |
| Damolin |
| Diatomit CJSC |
| Decalite Europe |
| Showa Chemical Industry |
| Calgon Carbon Corporation |
| CECA |
| Others |
Pricing and Supply Chain Analysis
Backward integration into mining concessions anchors supply security for calcined grade producers while locking in pricing power against commodity competitors. German and French operators with captive ore reserves command premium positioning as EFSA certification requirements intensify buyer dependency on established dossier holders.
Pricing Analysis
Yield-based pricing anchors filtration-grade contracts, with beverage processors paying per clarified hectoliter rather than per ton delivered. Pricing stratifies across EFSA-certified premium, industrial-standard, and uncalcined economy tiers based on permeability certification and carbon disclosure depth. Cost compression in commodity construction grades is intensifying because Spanish processors absorb higher beneficiation costs from declining Andalusian ore quality. Environmental contractors show least price sensitivity due to MEE-equivalent discharge compliance mandates, while Mediterranean insulation board manufacturers negotiate aggressively on uncalcined volume.
Supply Chain Analysis
Single-source vulnerability sits with German calcination capacity serving Ruhr Valley steel filtration and Bavarian brewing cooperatives. Mining concessions in Spain, Greece, and Italy feed raw material streams, while natural gas supply from the Netherlands and Norway rests beneath thermal processing economics. Regulatory restriction through REACH substance evaluation protocols threatens market access for non-compliant importers. Distribution runs through direct technical account teams for pharmaceutical and food contact grades, with regional mineral distributors handling construction and agricultural fragmentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Calcination kiln capacity scarcity props pricing power as retiring engineering expertise thins operational expansion options across Southern Europe. Supply constraints favor incumbents with established thermal processing assets and certified low-carbon energy sourcing.
For Market Incumbents: Lock in multi-year supply agreements with embedded carbon accounting before CSRD disclosure mandates harden buyer procurement criteria. Secure renewable thermal energy offtake to defend margin position against natural gas volatility, and accelerate REACH dossier updates to exclude emerging activated carbon substitutes from pharmaceutical pre-filtration specifications. For New Entrants and Emerging Players: Belgian spill response contractors represent an underserved buyer archetype with MEE-equivalent discharge protocols driving specification-grade absorption demand. Target Portuguese and Eastern European mining concessions with unexploited reserves for uncalcined construction supply, and enter through technical distributor partnerships rather than direct sales infrastructure. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated industrial mineral groups seeking EFSA-certified filtration assets. Five-to-ten year viability hinges on renewable calcination technology deployment and carbon disclosure verification capabilities. Watch for F-Gas Regulation enforcement tightening as the inflection signal for activated diatomite substitution acceleration in climate-controlled systems.| Strategic Initiative | Industry Significance |
|---|---|
| Renewable Thermal Energy Sourcing | CSRD-aligned carbon disclosure creates first-mover advantage for verified low-carbon calcination operators. |
| REACH Dossier Acceleration | ECHA substance evaluation protocols lock in supply continuity for beverage and pharmaceutical customers. |
| Advanced Calcination Control Systems | Real-time thermal imaging automation reduces batch rejection rates for Belgian and Dutch filtration specialists. |
| Environmental Remediation Product Engineering | Surface-modified activated grades capture hydrocarbon containment contracts under tightened discharge regulations. |
| Technical Account Team Expansion | Dedicated EFSA dossier support deepens incumbent relationships with centralized German brewing cooperatives. |
Research Methodology
Trade statistics from Eurostat, industrial mineral association publications, and ECHA registration databases formed the secondary backbone for supply and regulatory mapping. Primary interviews with calcination plant managers, beverage procurement leads at German cooperatives, environmental remediation contractors in France and Belgium, and filtration media distributors across the Low Countries anchored demand-side validation. Bottom-up and top-down triangulation cross-checked volume estimates against customs data and production capacity disclosures.
Bottom-up modeling aggregated segment-level demand across filtration, absorption, construction, and agriculture applications, while top-down analysis calibrated against macroeconomic mineral processing indicators. Segmentation dimensions included product type tier, end-use industry, purity certification level, and regional regulatory cluster. CAGRs were derived from trend extrapolation moderated by capacity constraint assumptions and energy cost trajectory scenarios. Forecast inputs incorporated REACH enforcement timelines and F-Gas Regulation revision schedules.
Revisions become necessary when EFSA purity standards tighten beyond current calcination capabilities or when renewable energy cost curves disrupt carbon disclosure competitive positioning. Forecasts reflect assumptions about regulatory enforcement consistency and mining concession renewal patterns. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Minerals
Bentonite Market
Industrial Minerals
Europe Limestone Market
Industrial Minerals
Solar Salt Market
Industrial Minerals
Feldspathic Minerals Market
Industrial Minerals
Global Epsom Salt Market
Industrial Minerals
Dolomite Mining Market
Industrial Minerals
Boron Minerals and Chemicals Market
Industrial Minerals
North America Silica Sand Market
Industrial Minerals
Nepheline Syenite Market
Industrial Minerals
Mineral Adsorbent Market
Industrial Minerals
Seaweed Derived Minerals Market
Industrial Minerals
North America Limestone Market
Industrial Minerals
Diatomite Mining Market
Industrial Minerals
Mediterranean Sea Salt Micro-Mineral Complexes Market
Industrial Minerals
Limestone Market
Industrial Minerals
Global Graphite Market