
 Global Alumina Trihydrate Market | 2026-2036
Global Alumina Trihydrate Market Size, Share, and Industry Trends Forecast 2026-2036
Global Alumina Trihydrate Market Foresight
Technical service agreements for flame retardant formulation support is expanding what producers sell beyond commodity powder. Huber Engineered Materials leverages its technical service network to anchor premium positioning in North America. Nabaltec AG sustains competitive differentiation through specialized coated alumina grades for polymer systems. Hindalco Industries Limited dominates bauxite-to-ATH integration across its Indian manufacturing footprint.
Alumina trihydrate is aluminum hydroxide with the chemical formula Al(OH)3, typically produced via the Bayer process from bauxite ore and characterized by its decomposition at 180-220°C to release water vapor for flame suppression. The compound functions primarily as a halogen-free flame retardant filler and smoke suppressant across polymer and rubber matrices. Standard grade ATH commands the largest volume share in flame retardant applications where cost sensitivity prevails, while specialty grade variants capture margin pools in high-performance electrical equipment and automotive cable sheathing. Coated alumina is gaining traction in polyolefin systems requiring improved compatibility and processing stability.
The EPA regulates ATH under the Toxic Substances Control Act for manufacturing and import thresholds, while REACH in Europe mandates registration and restricts hazardous substance content in finished goods. OSHA workplace exposure limits for respirable alumina dust shape handling protocols and packaging specifications across US production facilities. China's MEE enforces emissions standards on Bayer process refineries that influence regional supply availability. Stakeholders must monitor evolving fire safety codes in construction materials and the pace of substitution from halogenated alternatives to halogen-free systems.
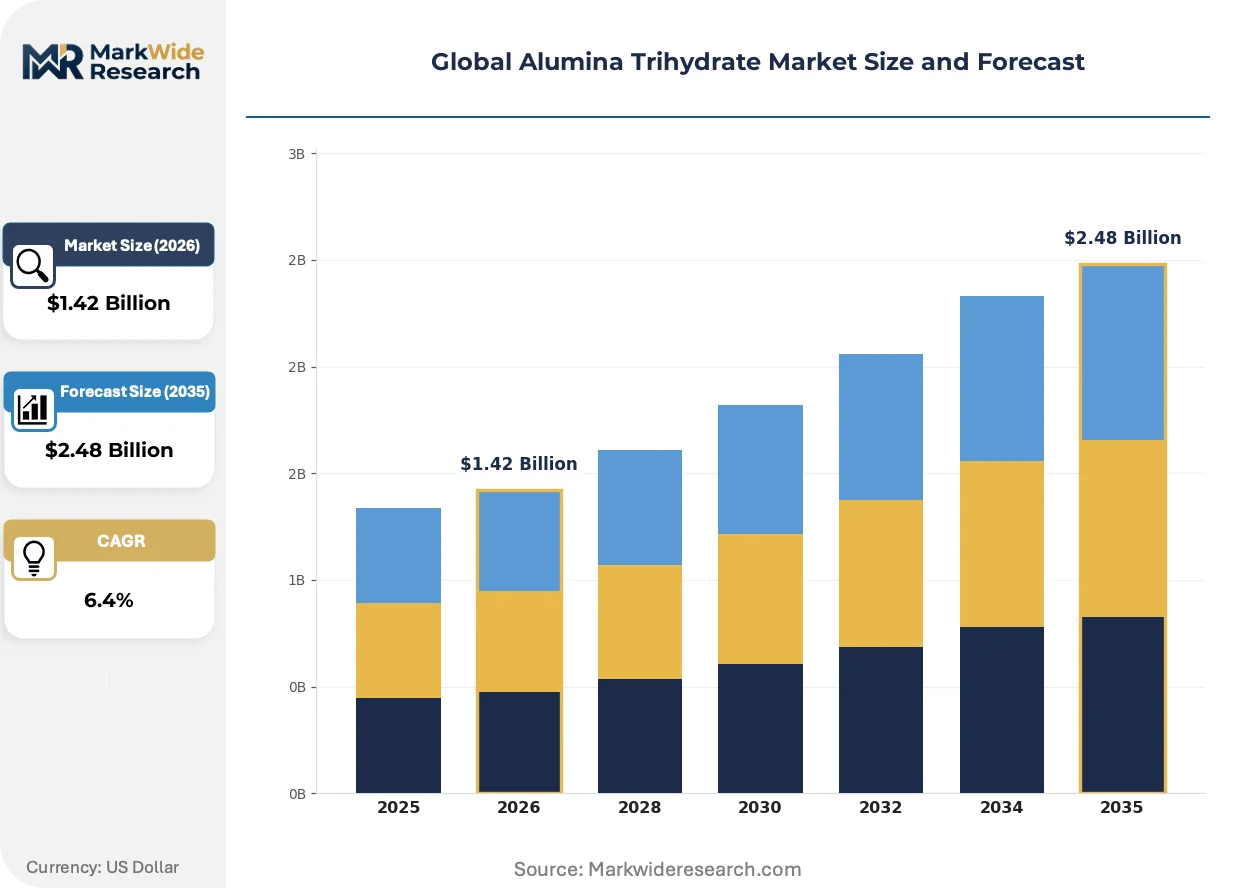
Market Dynamics
Halogen-free flame retardant mandates are restructuring procurement specifications across electrical equipment and construction materials, forcing reformulation of polymer compounds and rewiring supplier-buyer relationships around ATH compatibility testing.
Growth Catalysts
- REACH and RoHS compliance deadlines:European electrical equipment manufacturers face mandatory phase-outs of brominated flame retardants by 2026, redirecting specification sheets toward ATH-filled polyolefins in cable sheathing and connector housings.
- China's construction surge:Provincial infrastructure targets in Guangdong and Jiangsu are absorbing record volumes of flame-retardant aluminum composite panels for high-rise facades and transit systems.
- Electric vehicle battery enclosures:Thermal runaway protection requirements are embedding ATH-loaded thermoplastic composites into pack housings and module separators.
Market Restraints
- Bauxite supply concentration:Guinean and Australian ore deposits dominate feedstock availability, exposing ATH producers to geopolitical disruptions and shipping corridor bottlenecks.
- Processing energy intensity:Bayer process refineries consume 8-12 GJ per tonne of alumina, making European and North American operations vulnerable to natural gas price spikes.
- Magnesium hydroxide substitution:Competing halogen-free fillers with higher decomposition temperatures are capturing share in polyamide and high-temperature polymer systems.
Strategic Opportunities
- India's PLI scheme for specialty chemicals:Domestic manufacturing incentives are attracting greenfield ATH capacity to serve electrical component exports and local automotive wiring harness production.
- Coated ATH for recycled polyolefins:Surface-treated grades that maintain dispersion stability in post-consumer resin streams are opening circular economy supply contracts.
- 5G infrastructure buildouts:Low-smoke zero-halogen cable specifications for base stations and data centers are creating specification pull for ultra-fine precipitated ATH grades.
Industry Challenges
- Formulation chemistry expertise:Compounders lack technicians trained in ATH-polymer interface engineering, slowing customer adoption and increasing technical service costs.
- REACH registration timelines:New coated ATH variants require 18-24 month dossier preparation and substance evaluation periods before legal placement on the EU market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Alumina Trihydrate Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.48 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Grade, Calcined Grade, Coated Alumina, Specialty Grade Application: Flame Retardant, Filler in Plastics, Paper Manufacturing, Paints and Coatings, Adhesives & Sealants End User Industry: Electrical Equipment, Construction Materials, Packaging, Consumer Goods, Automotive Suppliers Packaging Type: FIBC Bags, Paper Bags, Bulk Containers, Plastic Bags |
| Companies Covered | Huber Engineered Materials, Nabaltec AG, Hindalco Industries Limited, Almatis GmbH, Sumitomo Chemical Co., Ltd., Alcoa Corporation, Aluminum Corporation of China Limited, Sibelco, R.J. Marshall Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Alumina Trihydrate Market Shifts & Advancements
Surface modification chemistry and particle engineering are redefining ATH performance ceilings, enabling penetration into polymer systems previously closed to mineral fillers due to mechanical property degradation.
Nano-precipitated ATH with controlled particle size distribution below 1 micron is overtaking conventional ground grades in thin-wall electrical connectors and fiber-optic cable jackets. Japanese automotive wiring suppliers have adopted these grades for 0.3mm wall thickness specifications. The technology is overtaking legacy precipitation methods in premium applications where tensile retention and elongation at break determine qualification.
REACH Annex XIV authorization requirements for halogenated flame retardants are tightening substitution deadlines across European E&E sectors. Compounders must reformulate entire product lines or surrender market access. German cable manufacturers are accelerating ATH qualification programs to maintain CE marking compliance for infrastructure tenders.
Specification-driven procurement is consolidating buying power among tier-1 electrical equipment OEMs who now mandate pre-approved compound formulations rather than raw material purchasing. This disintermediates independent distributors and locks ATH volumes into multi-year supply agreements with qualified compounders. The shift is most visible in China's state-grid procurement where centralized tendering favors pre-certified material packages.
Global Alumina Trihydrate Market Segmentation
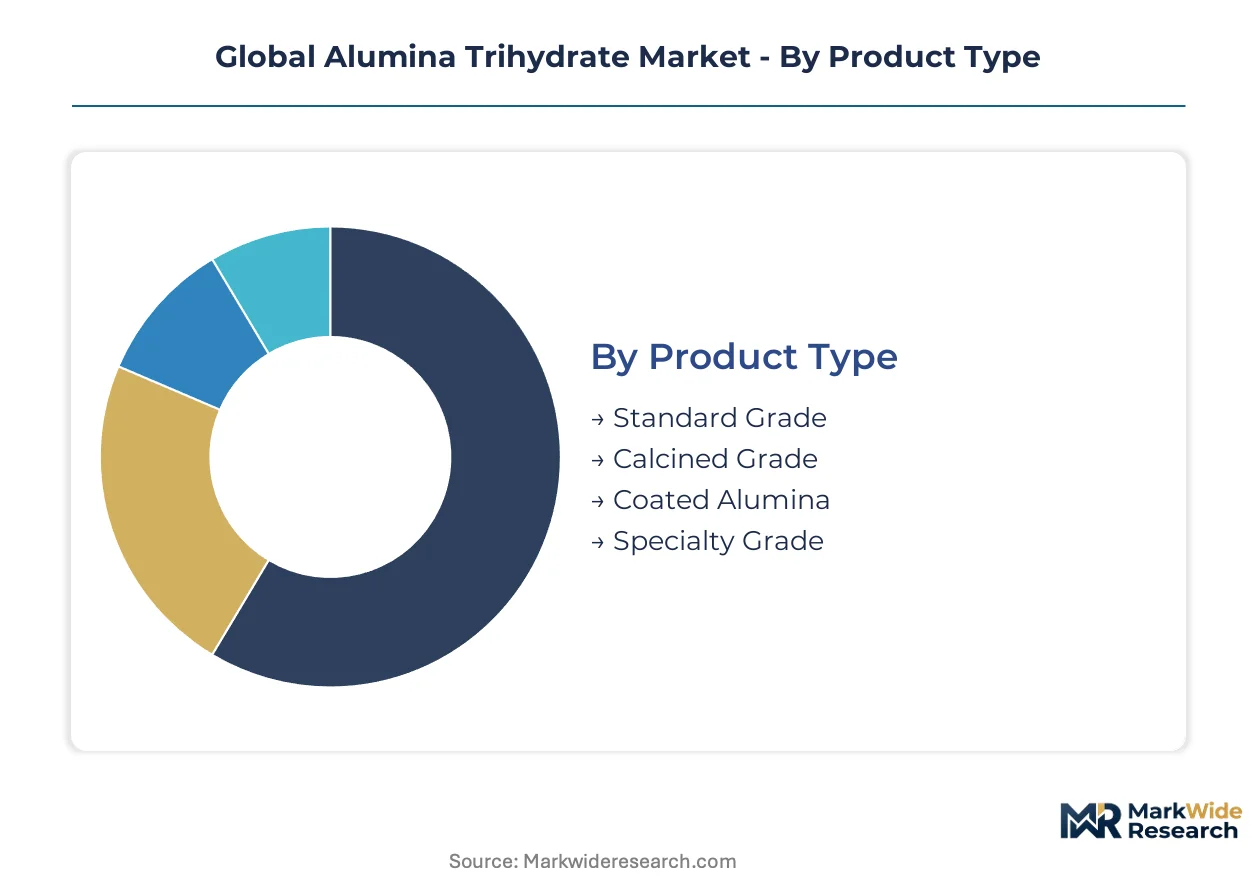
ATH segmentation reveals how certification burdens and performance specifications fragment procurement across electrical, construction, and automotive supply chains. Product grades carry distinct REACH registration obligations, while application segments face divergent fire safety code enforcement.
Product Type:
REACH Annex XIV authorization timelines vary sharply across grades, with coated and specialty variants requiring extended dossier preparation compared to standard formulations.
- Standard Grade:Unmodified precipitated ATH with particle sizes typically ranging 1-10 microns serves cost-sensitive polyolefin compounding. Construction materials manufacturers in China absorb the largest volumes for aluminum composite panel production facing GB standard fire ratings.
- Coated Alumina:Surface-treated with silane or fatty acid modifiers to enhance polymer matrix compatibility and hydrophobicity. Automotive wiring harness suppliers in Germany specify these grades for PA6 and PP compounds under LV 112-1 cable standards requiring improved dispersion stability.
- Calcined Grade:Thermally processed to remove structural water, yielding transition alumina phases for ceramic and catalyst applications rather than flame retardant use.
- Specialty Grade:Ultra-fine precipitated variants below 1 micron with tight particle distribution for thin-wall electrical connectors and fiber-optic cables.
Standard Grade sits at the top of the volume ranking, with Coated Alumina climbing the fastest.
Application:
Cost tier stratification separates specification-driven electrical applications from commodity construction and paper uses.
- Flame Retardant:ATH decomposes endothermically at 180-220°C to release water vapor, diluting combustible gases in polymer matrices. Electrical equipment OEMs in the European Union specify halogen-free formulations under RoHS Article 4(1) restrictions on brominated compounds.
- Filler in Plastics:Functions as a reinforcing extender in PVC, PP, and PE systems where mechanical property retention must balance loading levels. Packaging converters in India leverage ATH for cost reduction in rigid containers under BIS IS 10146 standards.
- Paper Manufacturing:Coating pigment and filler for glossy paper grades, though facing displacement from precipitated calcium carbonate in graphic paper applications.
- Paints and Coatings:Functional filler providing opacity and flame resistance in intumescent architectural coatings.
- Adhesives & Sealants:Viscosity modifier and fire-retardant additive in construction sealants meeting ASTM E84 smoke development limits.
Flame Retardant commands the dominant revenue share, with Filler in Plastics expanding most quickly.
End User Industry:
Customer type concentration clusters procurement power among tier-1 electrical and automotive compounders who mandate pre-approved formulations.
- Electrical Equipment:Cable manufacturers, connector producers, and enclosure fabricators drive specification-grade ATH demand. China's State Grid centralized tendering requires pre-certified halogen-free compounds for infrastructure projects.
- Construction Materials:Aluminum composite panel and insulation board producers absorb commodity volumes. Guangdong and Jiangsu provincial targets for high-rise fire safety are redirecting specification sheets toward ATH-filled facade systems.
- Automotive Suppliers:Wiring harness and battery enclosure manufacturers specify coated grades for thermal runaway protection in electric vehicle pack housings.
- Packaging:Rigid container and film producers use ATH as a cost-effective filler with incidental flame retardancy for warehouse storage compliance.
- Consumer Goods:Appliance housings and electronics enclosures requiring UL 94 V-0 ratings at reduced formulation cost versus engineered halogenated alternatives.
Electrical Equipment maintains the steepest expansion trajectory, with Automotive Suppliers gaining share fastest.
Packaging Type:
Supply chain configuration determines handling protocols, with OSHA respirable dust limits shaping bulk versus bagged distribution.
- FIBC Bags:Flexible intermediate bulk containers of 500-2000 kg capacity serve compounders with dedicated pneumatic conveying systems. North American electrical cable plants favor FIBC for high-volume, low-touch material flow.
- Paper Bags:Multi-wall kraft constructions of 25-50 kg for smaller compounders lacking bulk handling infrastructure. European distributors stock paper-bagged specialty grades for just-in-time delivery to mid-tier wire producers.
- Bulk Containers:Tank trucks and railcars for captive refinery-to-compounder transfers, minimizing packaging cost and dust exposure.
- Plastic Bags:PE-lined woven polypropylene for moisture-sensitive coated grades requiring humidity protection during ocean freight.
FIBC Bags dominate tonnage movements, with Bulk Containers climbing fastest among integrated supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China absorbs more ATH tonnage than Germany and the United States combined, yet regulatory tightening in Europe is redirecting specification-grade demand toward premium coated variants faster than volume growth alone suggests.
China
Provincial infrastructure targets in Guangdong and Jiangsu are driving record consumption of flame-retardant aluminum composite panels for high-rise transit systems. The Ministry of Ecology and Environment enforces emissions standards on Bayer process refineries that constrain regional supply availability. Qingdao and Zhengzhou host integrated bauxite-to-ATH manufacturing clusters serving domestic cable compounders.
Germany
Automotive wiring harness manufacturers specify coated ATH grades for PA6 and PP compounds under LV 112-1 cable standards. REACH Annex XIV authorization deadlines for halogenated flame retardants are accelerating reformulation programs across electrical equipment OEMs. The Rhine-Ruhr industrial corridor concentrates compounding capacity for export-oriented cable producers.
United States
Electrical cable plants in the Southeast and Midwest favor FIBC bulk handling systems for high-volume ATH procurement. EPA oversight under the Toxic Substances Control Act shapes manufacturing and import thresholds for mineral fillers. Huber Engineered Materials leverages its technical service network to anchor premium positioning across North American polymer compounders.
India
The Production-Linked Incentive scheme for specialty chemicals is attracting greenfield ATH capacity to serve automotive wiring harness exports. Bureau of Indian Standards IS 10146 regulations govern rigid container applications where ATH functions as a cost-reducing filler. Hindalco Industries Limited dominates bauxite-to-ATH integration across manufacturing footprints in Odisha and Maharashtra.
Japan
Automotive wiring suppliers have adopted nano-precipitated ATH grades below 1 micron for 0.3mm wall thickness specifications in electric vehicle battery enclosures. METI industrial standards guide halogen-free material qualification for infrastructure tenders. The Chubu region around Nagoya hosts precision compounding facilities serving tier-1 automotive OEMs.
Global Alumina Trihydrate Market Competitive Landscape
Top-tier vendors anchor integrated bauxite-to-specialty-grade production, while mid-scale compounders and regional distributors occupy fragmented downstream positions. The vendor base stratifies across three archetypes: integrated mining-chemical conglomerates with captive bauxite supply, specialty coated-grade formulators with technical service networks, and commodity precipitated-ATH producers competing on volume scale. Dominant competitive moves include backward integration into bauxite mining assets and geographic expansion through technical service agreements rather than greenfield capacity alone.
Among integrated mining-chemical conglomerates, Hindalco Industries Limited and Aluminum Corporation of China Limited exemplify the bauxite-captive archetype with in-house refinery control. Nabaltec AG occupies a position within the specialty-coated tier, representing European formulators who compete on polymer compatibility expertise rather than raw material access. Huber Engineered Materials anchors the North American premium service model, illustrating how technical support networks lock compounders into multi-year supply relationships.
| Leading Market Players |
|---|
| Huber Engineered Materials |
| Nabaltec AG |
| Hindalco Industries Limited |
| Almatis GmbH |
| Sumitomo Chemical Co., Ltd. |
| Alcoa Corporation |
| Aluminum Corporation of China Limited |
| Sibelco |
| R.J. Marshall Company |
| Others |
Supply & Pricing Matrix
China's dual carbon goals for Bayer process emissions are gating qualified supply and premium-tier pricing access, as refineries failing MEE standards face capacity constraints that redirect procurement toward certified producers commanding coated-grade premiums.
Pricing Analysis
Capacity additions in India are reshaping price floors for standard-grade ATH while specialty coated variants maintain premium-mid-economy pricing differentiation. Price differentiation rests on REACH registration status and silane surface treatment depth, with unregistered commodity grades facing cost compression from magnesium hydroxide substitution. Compounders in China's State Grid tendering system show least price sensitivity due to pre-certified formulation mandates, while Indian packaging converters absorb maximum cost pressure.
Supply Chain Analysis
REACH and RoHS qualification timelines are gating supply chain participation, with dossier preparation periods filtering out non-specialized distributors. Geographic supply concentrates in China, India, and Germany, drawing from Guinean and Australian bauxite feedstocks. Raw material dependencies center on caustic soda, natural gas for calcination energy, and silane coupling agents for surface modification. Single-source vulnerability runs through Guinean ore export corridors. Distribution runs through integrated refinery-to-compounder bulk transfers and FIBC bagged shipments to electrical cable plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where REACH Annex XIV authorization deadlines for halogenated flame retardants are restructuring procurement specifications and redirecting formulation demand toward ATH-qualified suppliers.
For Market Incumbents: To counter magnesium hydroxide substitution in high-temperature polymer systems, deepen captive bauxite supply through Australian or Guinean mining assets and accelerate nano-precipitated ATH R&D for thin-wall electrical connector specifications. Certification investment in REACH-registered coated grades locks compounders into multi-year supply agreements.
For New Entrants and Emerging Players: The price-point gap between premium Japanese nano-precipitated grades and Chinese standard powder opens white-space targeting of India's PLI-subsidized specialty chemical parks and recycled polyolefin compounding for circular economy contracts. A technical service partnership model with German automotive wiring suppliers bypasses greenfield refinery capital intensity.
For Investors and Strategic Acquirers: Valuations sit cheapest among commodity precipitated-ATH producers lacking downstream coating capabilities. Long-term viability across the analysis window favors integrated bauxite-to-specialty-grade conglomerates with captive ore supply. The signal to watch is China's MEE enforcement intensity on Bayer process emissions, which would accelerate consolidation toward certified producers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bauxite Mining | Captive Guinean or Australian ore supply insulates against shipping corridor disruptions and price volatility. |
| REACH-Registered Coated Grade Development | Silane-treated variants command premium positioning in German automotive wiring harness specifications. |
| Technical Service Network Expansion | Polymer compatibility expertise locks North American compounders into multi-year supply relationships. |
| Nano-Precipitated Capacity Buildout | Sub-micron particle grades penetrate Japanese electric vehicle battery enclosure applications. |
| Recycled Polyolefin Formulation Partnerships | Surface-treated ATH maintains dispersion stability in post-consumer resin streams for circular economy contracts. |
Research Methodology
Multiple input streams — primary interviews with Bayer process plant managers, polymer compounding R&D directors, and electrical cable procurement leads; secondary validation through customs trade data, SEC filings of integrated aluminum producers, and ECHA registration databases; plus ACC and Cefic industry reports — were reconciled through bottom-up and top-down triangulation.
Historical volume trajectories were cross-referenced against expert panel assessments of halogen-free substitution rates and electric vehicle battery enclosure adoption curves across the projection horizon. Segmentation dimensions modeled include product grade tier, end-use industry, packaging format, and regional production hub. CAGRs were derived from iterative convergence of demand-side build-ups and supply-side capacity constraints, with specific inputs from China's provincial infrastructure targets and REACH authorization timelines.
Caveats apply where bauxite supply disruptions, natural gas price spikes, or magnesium hydroxide formulation breakthroughs could materially shift the outlook. A model refresh is warranted upon material change in China's MEE enforcement posture or European halogenated flame retardant substitution deadlines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Global Barium Carbonate Market
Ceramics
Porous Ceramic Market
Ceramics
Engineering Ceramics Market
Ceramics
Fly Ash and Ceramic Microsphere Market
Ceramics
Graphite Crucibles Market
Ceramics
UAE Ceramic Tiles Market
Ceramics
North America Activated Alumina Market
Ceramics
Glass Ceramics Market
Ceramics
Zirconium Dioxide Market
Ceramics
Active Calcium Silicate Market
Ceramics
GCC Ceramic Tiles and Sanitary Ware Market
Ceramics
2N High Purity Alumina Market
Ceramics
United States Ceramic Tiles Market
Ceramics
Feldspar and Nepheline Syenite Market
Ceramics
Global Ceramic Tube Market
Ceramics
Aluminium Nitride Market