
 Optical Ceramics Market | 2026-2036
Optical Ceramics Market Size, Share, and Industry Trends Forecast 2026-2036
Optical Ceramics Market Intelligence
Project-specific financing tied to long-term defense and aerospace contracts is fragmenting the competitive landscape for high-performance materials. CoorsTek leverages its extensive manufacturing scale to serve large-volume industrial accounts. Surmet Corporation differentiates through its specialization in advanced transparent armor materials. Saint-Gobain sustains its market position by offering a diverse portfolio that includes both glass and ceramic optical components.
Optical ceramics are polycrystalline materials engineered through processes like sintering to achieve high transparency and durability. These materials offer superior mechanical strength and thermal resistance compared to traditional optical glass, making them suitable for harsh environments. Sapphire and Alumina represent mature product segments, while advanced materials like Spinel are gaining traction. The defense and aerospace end-user industries constitute the largest source of demand, particularly for infrared windows and transparent armor applications.
Adherence to military specifications from the United States Department of Defense is mandatory for transparent armor applications. In Europe, material qualification for aerospace components is governed by stringent aviation safety agency standards. These regulations dictate material performance and testing protocols, creating high barriers to entry. Future competitiveness hinges on a manufacturer's ability to scale production of next-generation materials while navigating these complex qualification processes.
Market Dynamics
The market's structural tension arises from the defense sector's demand for advanced materials like Spinel, which requires significant capital investment in new sintering technologies, versus the long, costly qualification cycles that delay return on that investment.
Growth Catalysts
- Sintering Innovations:Advancements in sintering and hot pressing techniques are enhancing the optical transparency and mechanical durability of ceramic materials, expanding their viability for demanding applications.
- Defense Modernization:Heightened geopolitical tensions drive government spending on advanced military systems in the United States and Europe, specifically for transparent armor and sensor windows on vehicles and aircraft.
- Infrared System Demand:The proliferation of infrared (IR) sensors and guidance systems in both defense and industrial automation creates a need for durable IR-transparent windows and domes made from optical ceramics.
Market Restraints
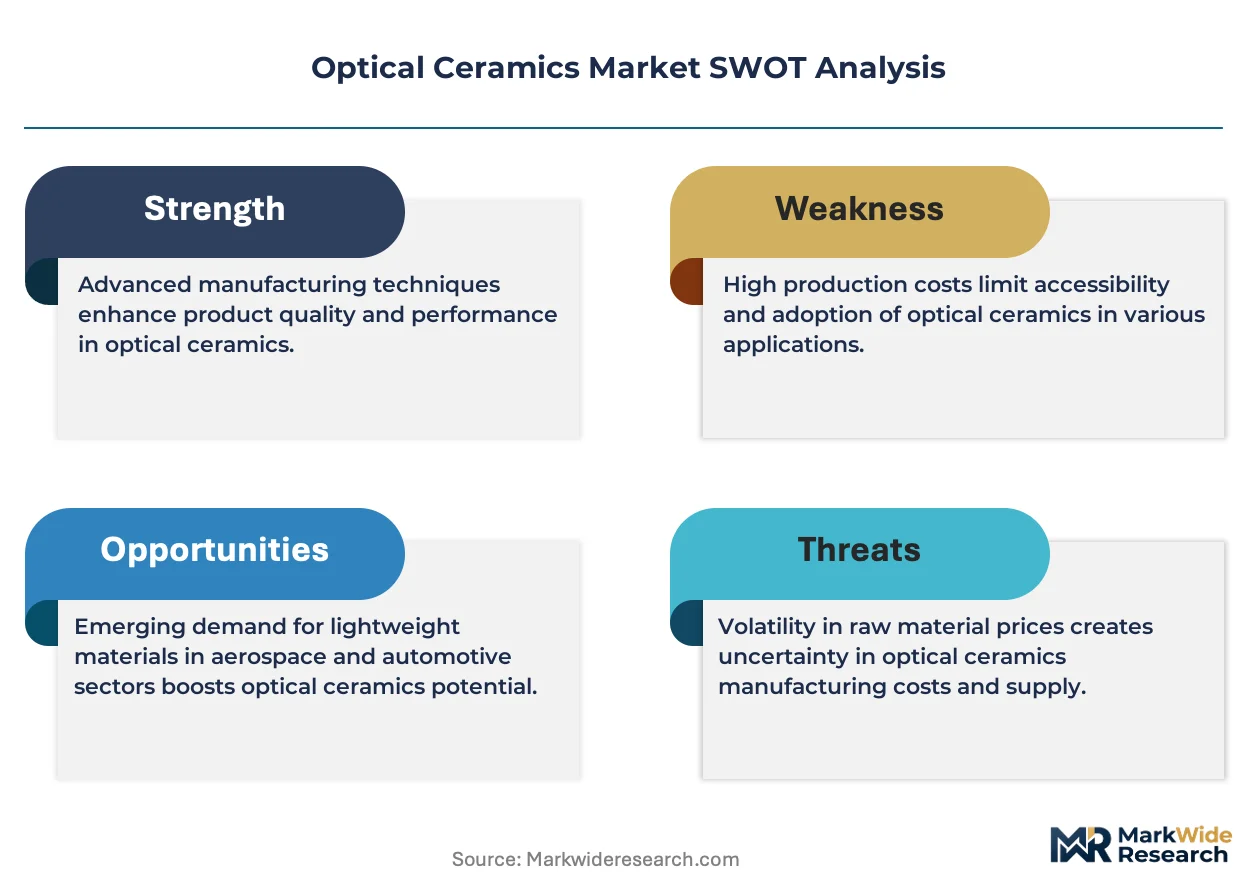
- High Production Costs:The manufacturing of optical ceramics involves energy-intensive processes and high-purity raw materials, resulting in component costs that are substantially higher than those for traditional optical glass.
- Manufacturing Complexity:Achieving consistent, defect-free optical quality across large-area ceramic components remains a significant technical hurdle, limiting scalability for applications like large armored vehicle windows.
- Stringent Qualification:Material qualification for aerospace applications under European aviation safety agencies or for armor under US military specifications is a multi-year, high-cost process that creates a major barrier to entry.
Strategic Opportunities
- Spinel Commercialization:Scaling the production of transparent polycrystalline spinel offers a significant opportunity, as it provides superior optical and mechanical properties compared to mature materials for next-generation armor.
- Semiconductor Equipment:The semiconductor fabrication industry presents an opportunity for ceramic components in plasma etch chambers and lithography systems, where high purity and thermal stability are critical.
- Medical Device Applications:There is an emerging opportunity for biocompatible optical ceramics in endoscopic devices and surgical tools, where durability and sterilization resistance are key requirements.
Industry Challenges
- Production Scalability:A primary operational challenge is transitioning new material formulations from laboratory-scale development to repeatable, high-volume manufacturing while maintaining strict quality and performance specifications.
- Complex Qualification Pathways:Navigating the disparate material testing protocols and certification requirements between US Department of Defense contracts and European aerospace standards complicates market access for suppliers.
- Specialized Talent Scarcity:The industry faces a shortage of materials scientists and process engineers with specific expertise in advanced ceramic sintering, powder processing, and optical finishing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optical Ceramics Market |
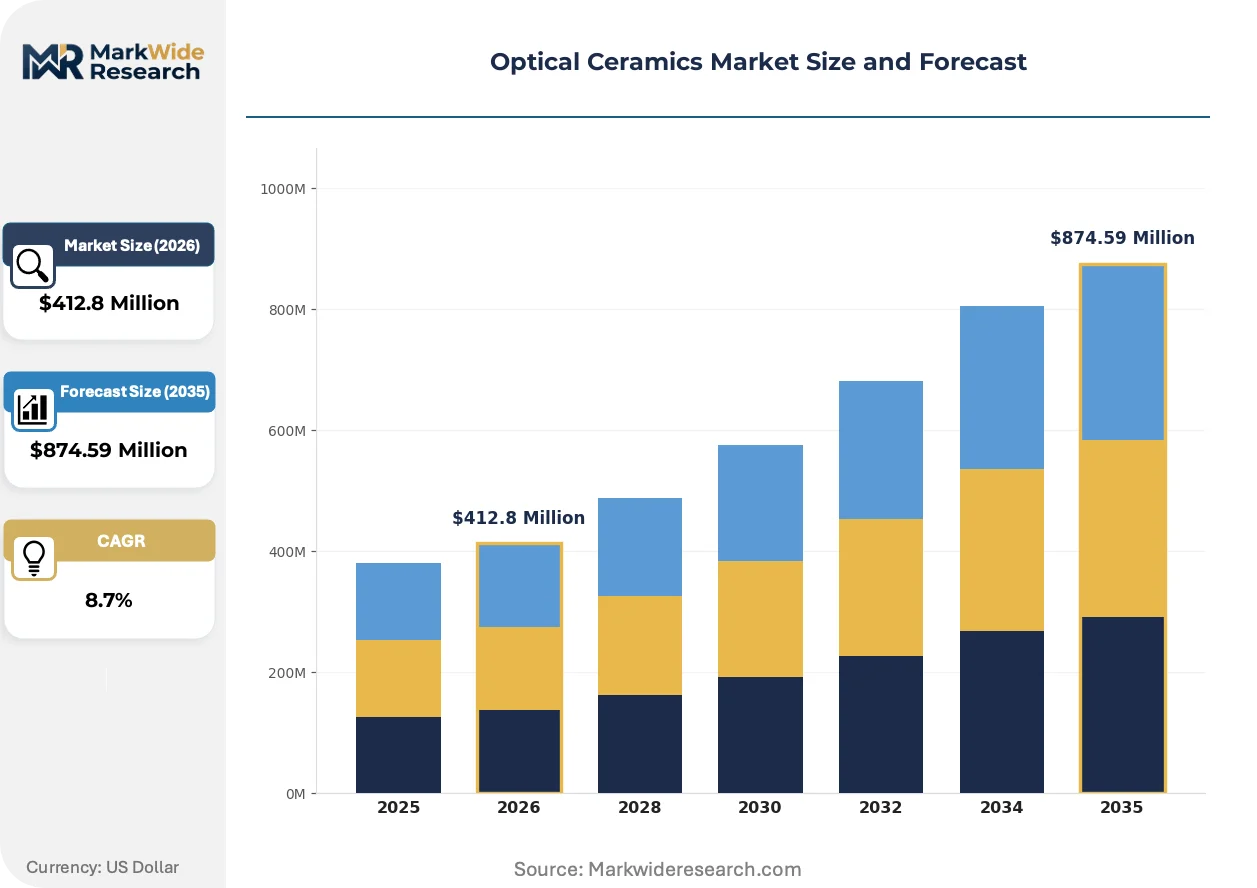
| Market Size in 2026 | $412.8 Million |
| Market Size in 2035 | $874.59 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alumina, Yttria, Spinel, Sapphire, Zirconia, Boron Nitride Application: Laser Optics, Infrared Windows, Transparent Armor, High-Performance Lenses, Sensor Components, Optical Filters Manufacturing Process: Hot Pressing, Sintering, Chemical Vapor Deposition, Sol-Gel, Tape Casting, Reaction Bonding End User Industry: Defense, Electronics, Telecommunications, Aerospace, Scientific Research, Consumer Electronics |
| Companies Covered | CoorsTek, CeramTec, Schott AG, Surmet Corporation, CeraNova, Kyocera, Saint-Gobain, Konoshima Chemicals, American Elements, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optical Ceramics Market Strategic Shifts & Innovations
Material science is advancing faster than the qualification and adoption cycles of the primary end-use markets. This creates a pipeline of next-generation materials, like advanced Spinel, awaiting integration into long-term defense and aerospace programs.
Advanced hot isostatic pressing (HIP) enables the fabrication of optical ceramics with near-theoretical density and minimal light-scattering defects. Aerospace and defense prime contractors are specifying HIP-processed components for critical infrared window and dome applications. This capability is collapsing the historical performance trade-offs between optical clarity and mechanical toughness, allowing for more durable sensor systems in harsh environments.
European Union regulations, including REACH, place increasing scrutiny on the chemical substances used in manufacturing processes, impacting raw material selection for ceramic producers. This forces manufacturers to document their supply chains and seek compliant precursor materials, potentially altering cost structures and sourcing strategies. The aerospace components segment is most affected, requiring extensive re-qualification if material inputs are changed.
A clear shift in buying behavior is evident as prime contractors move away from component-level purchasing toward acquiring integrated optical assemblies. This disrupts the traditional model of selling raw ceramic blanks, forcing material suppliers to either develop downstream finishing and assembly capabilities or partner with specialized integrators. This trend is most visible within the North American defense supply chain for sophisticated sensor and targeting pods.
Optical Ceramics Market Segmentation
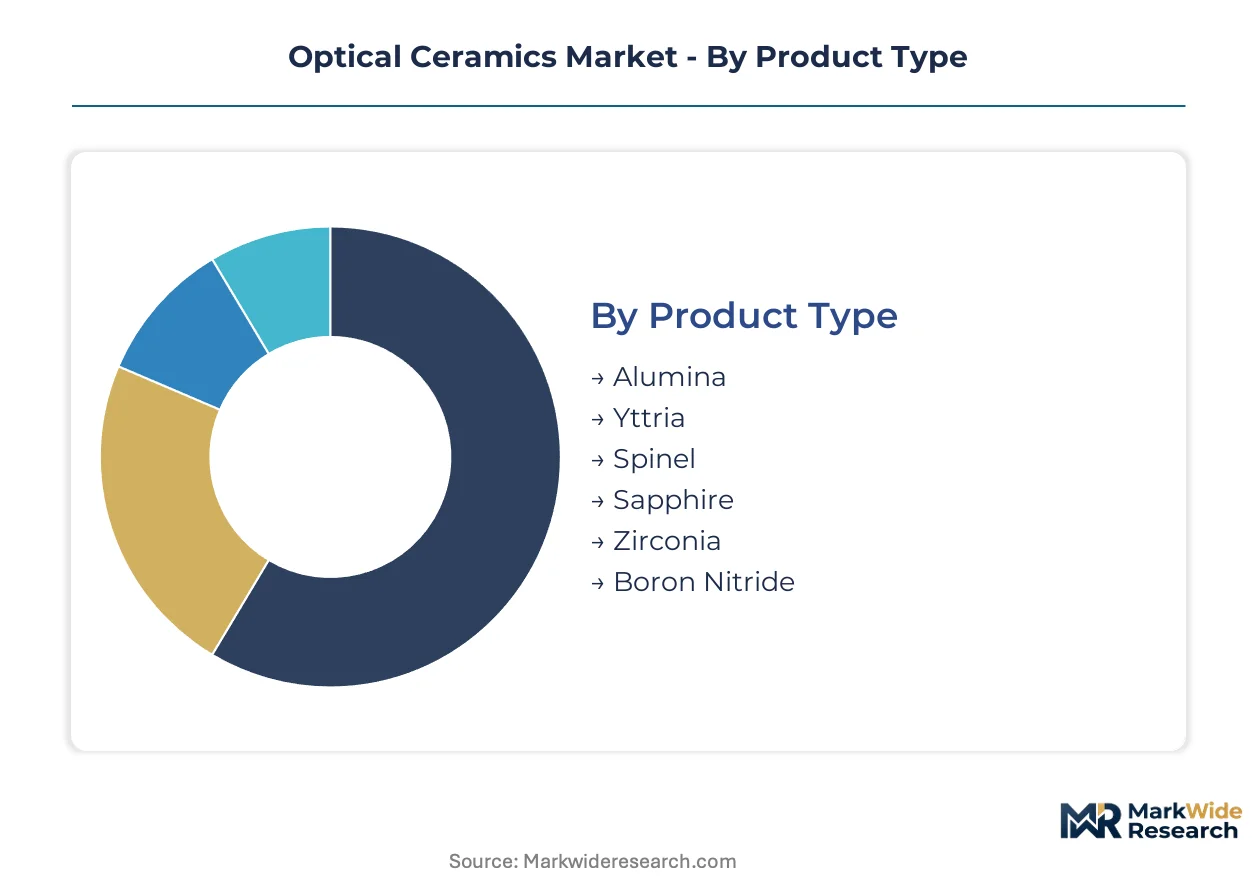
Market segmentation provides a detailed lens into the diverse material compositions, application areas, production methods, and end-user industries shaping the optical ceramics landscape. Understanding these distinct segments helps manufacturers align product development with specific market demands and regulatory requirements.
Product Type:
The product type spectrum ranges from established materials with broad industrial utility to advanced ceramics engineered for extreme performance applications.
- Spinel:Transparent polycrystalline spinel offers superior optical clarity and mechanical strength, making it ideal for next-generation transparent armor systems. Demand for spinel concentrates in defense applications, particularly for advanced vehicle and aircraft protection.
- Sapphire:Single-crystal sapphire provides exceptional hardness and broad spectral transparency, crucial for high-performance optical windows and domes. The aerospace industry utilizes sapphire extensively for infrared sensor protection in extreme environments.
- Alumina:Polycrystalline alumina ceramics offer a cost-effective solution for less demanding optical components and structural applications.
- Yttria:Yttria ceramics are emerging for high-temperature optical components and specialty laser applications due to their thermal stability.
- Zirconia:Zirconia exhibits high fracture toughness, finding use in durable optical components and wear-resistant parts.
- Boron Nitride:Hexagonal boron nitride is valued for its high thermal conductivity and electrical insulation in specialized optical systems.
Established volume favors Alumina; emerging adoption favors Spinel.
Application:
Applications span from mature optical systems requiring basic durability to cutting-edge defense platforms demanding extreme environmental resistance.
- Transparent Armor:Optical ceramics provide ballistic protection and clear visibility for military vehicles and aircraft, replacing traditional glass. The United States Department of Defense specifies stringent performance for these critical transparent armor systems.
- Infrared Windows:These components allow infrared radiation to pass through while protecting sensitive sensors in harsh environments. Aerospace and defense prime contractors specify infrared windows for advanced targeting and surveillance systems.
- Laser Optics:Optical ceramics function as lenses, mirrors, and windows in high-power laser systems, resisting thermal shock.
- High-Performance Lenses:These lenses offer superior optical properties and durability for specialized imaging and sensing equipment.
- Sensor Components:Ceramics protect and enhance the performance of various optical sensors in industrial and military settings.
- Optical Filters:Ceramic optical filters provide precise wavelength selection for specific light transmission requirements.
Long-standing demand concentrates in Infrared Windows; Transparent Armor is expanding most quickly.
Manufacturing Process:
Manufacturing processes exhibit varying levels of capital intensity and technical complexity, influencing supply chain concentration.
- Sintering:This process compacts ceramic powders using heat without melting, creating dense, transparent optical ceramics. Innovations in sintering techniques are enhancing material properties and manufacturing scalability.
- Hot Pressing:Combining high temperature and pressure during densification, hot pressing produces optical ceramics with superior mechanical properties and minimal defects. Aerospace and defense prime contractors specify hot-pressed components for critical applications.
- Chemical Vapor Deposition:CVD involves depositing thin films of ceramic materials from gaseous precursors, used for specialized coatings.
- Sol-Gel:The sol-gel method creates high-purity ceramic materials at lower temperatures, suitable for optical coatings and fibers.
- Tape Casting:This process forms thin, flexible ceramic sheets for multilayer components and specialized electronic packaging.
- Reaction Bonding:Reaction bonding forms ceramic materials through chemical reactions between precursors, often used for complex shapes.
Volume production relies on Sintering; advanced material development increasingly leverages Hot Pressing.
End User Industry:
End-user industries range from highly regulated sectors with stringent performance requirements to commercial markets prioritizing cost-effectiveness and scalability.
- Defense:The defense sector utilizes optical ceramics for transparent armor, infrared windows, and sensor protection in harsh military environments. Heightened geopolitical tensions drive government spending on advanced military systems in the United States and Europe.
- Aerospace:Aerospace applications demand lightweight, durable optical ceramics for aircraft windows, sensor domes, and thermal management components. Material qualification for aerospace components is governed by stringent European aviation safety agency standards.
- Electronics:Optical ceramics find use in semiconductor equipment and specialized electronic devices requiring high purity and thermal stability.
- Telecommunications:These materials are used in fiber optic components and high-bandwidth communication systems.
- Scientific Research:Research institutions employ optical ceramics for advanced instrumentation and experimental setups.
- Consumer Electronics:Emerging applications include durable screens and camera lenses for high-end consumer devices.
Demand from Defense drives significant market volume; Aerospace applications command premium pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global optical ceramics market exhibits a complex export-import balance, with advanced material production concentrating in a few key nations. High-performance optical ceramics, crucial for defense and aerospace, often originate from countries possessing specialized manufacturing capabilities. This dynamic influences material availability and strategic partnerships across international supply chains.
United States
Defense modernization drives demand for transparent armor and infrared windows in the United States. Adherence to US military specifications from the Department of Defense is mandatory for transparent armor applications. Silicon Valley and aerospace hubs like Southern California host significant research and development for advanced optical components.
Germany
European aerospace programs and industrial automation applications require durable optical ceramics in Germany. Material qualification for aerospace components is governed by stringent European aviation safety agency standards. The Fraunhofer Institutes in Dresden and Aachen contribute significantly to material science innovations for ceramic production.
Japan
High-performance lenses and semiconductor equipment drive demand for advanced optical ceramics in Japan. METI promotes research and development in advanced materials, influencing industry standards for ceramic components. Tokyo and Osaka house specialized manufacturers and research centers focusing on precision optical ceramics.
China
Domestic defense modernization and expanding electronics manufacturing fuel demand for optical ceramics within China. MIIT policies support local production of high-tech materials, including advanced ceramics. Research institutions in Shanghai and Shenzhen are developing new sintering techniques for scalable ceramic manufacturing.
France
European defense contracts and specialized laser systems require robust optical ceramic components from France. European Union REACH regulations impact raw material selection for ceramic producers within the country. Aerospace clusters around Toulouse and Paris host companies integrating optical ceramics into advanced systems.
Optical Ceramics Market Key Industry Players
On the supply side, the industry is structurally tiered, with a mix of large-scale material producers and highly specialized component fabricators. Project-specific financing tied to long-term defense and aerospace contracts fragments the competitive landscape for high-performance optical ceramics. Strategic archetypes include diversified material conglomerates, advanced transparent armor specialists, and large-volume industrial suppliers focusing on specific end-use applications. Companies primarily engage in capacity expansion for next-generation materials and strategic partnerships with prime contractors for integrated optical assemblies.
Specialists in advanced transparent armor materials, such as Surmet Corporation, exemplify innovation-driven differentiation within niche segments demanding superior performance. Diversified material suppliers like Saint-Gobain sustain market position by offering a broad portfolio encompassing both traditional glass and advanced ceramic optical components. CoorsTek, leveraging its extensive manufacturing scale, occupies the segment serving large-volume industrial accounts, particularly where consistent supply and cost-effectiveness are critical. These entities represent distinct strategic approaches to capturing value across the varied demands of the optical ceramics market.
| Leading Market Players |
|---|
| CoorsTek |
| CeramTec |
| Schott AG |
| Surmet Corporation |
| CeraNova |
| Kyocera |
| Saint-Gobain |
| Konoshima Chemicals |
| American Elements |
Cost & Logistics Intelligence
Under-capacity in advanced sintering facilities drives both supplier investment and premium pricing for next-generation optical ceramics. This dynamic shapes material availability and influences long-term contract negotiations with prime contractors.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake agreements for specialized optical ceramics. Price differentiation stems from material purity grade, stringent military specification certifications, and component customization levels. Pricing softness in mature segments reflects increasing competition for established alumina and sapphire components. Defense sector buyers exhibit lower price sensitivity due to performance requirements, contrasting with commercial electronics manufacturers prioritizing cost-effectiveness.
Supply Chain Analysis
Specialized ceramic fabricators hold significant contract-manufacturing capacity, particularly in Japan, Germany, and the United States. The supply chain draws from high-purity raw materials like aluminum oxide, yttrium oxide, and magnesium oxide. Single-source vulnerability for advanced spinel precursors represents a structural risk, impacting material lead times. Distribution primarily moves through direct sales channels to aerospace and defense prime contractors, often involving integrated optical assembly partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The optical ceramics market is experiencing a cyclical recovery, driven by heightened geopolitical tensions and subsequent defense modernization spending. This resurgence creates opportunities across the value chain.
For Market Incumbents: Harden core capabilities in advanced sintering techniques to maintain a performance edge. Integrate vertically into downstream finishing and assembly to capture more value per component. Counter the threat of new material entrants by investing in next-generation material R&D, specifically for Spinel. Focus on securing long-term supply agreements with prime contractors.
For New Entrants and Emerging Players: Establish a beachhead in niche applications requiring high thermal stability, such as semiconductor equipment. Target underpenetrated commercial segments where cost-effective alumina solutions are viable. A go-to-market angle focusing on rapid prototyping and flexible production for specialized components will attract smaller OEMs. Pursue strategic partnerships with integrators for complex optical assemblies.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap specialists with proprietary sintering technologies and established military qualifications. The long-term viability of this market rests on sustained defense and aerospace spending over the next 5-10 years. An acquisition target archetype involves companies with strong IP in next-generation materials like Spinel. The signal to watch is successful commercialization of large-area transparent armor.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Spinel Production | Scaling output of advanced Spinel materials addresses defense sector demand for superior transparent armor. |
| Strategic Partnerships with System Integrators | Collaborating with integrators ensures material suppliers participate in the shift toward integrated optical assemblies. |
| Investment in Hot Isostatic Pressing (HIP) R&D | Advancing HIP techniques enhances material density and optical clarity for critical aerospace components. |
| Certification Pathway Acceleration for New Materials | Expediting qualification processes reduces time-to-market for innovative optical ceramics in regulated applications. |
| Backward Integration into High-Purity Raw Material Sourcing | Securing control over precursor materials mitigates supply chain risks and ensures consistent quality. |
Research Approach
Two parallel data streams informed the analysis: primary stakeholder interviews and secondary validation of market intelligence. The study incorporated insights from materials scientists, defense procurement officers, aerospace engineers, and specialized ceramic manufacturers. Secondary data sources included military specifications, aviation safety agency reports, and technical publications. This approach enabled robust bottom-up and top-down triangulation of market figures.
The forecast inputs considered macroeconomic indicators, technological advancements in sintering, and evolving defense spending patterns. The analytical framework modeled market segmentation by product type, application, manufacturing process, end-user industry, and regional regulatory compliance. Compound annual growth rates were derived through historical trend analysis and projected demand curves across the analysis window.
Sensitivities concentrate around shifts in defense budgets, raw material price volatility, and slower-than-anticipated qualification cycles. Forecasts reflect assumptions regarding technological adoption and regulatory stability. Quarterly review of defense procurement contracts and material science breakthroughs is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Advanced Ceramics Market
Ceramics
Philippines Ceramic Tiles Market
Ceramics
High Purity Mullite Powder Market
Ceramics
Global Alumina Market
Ceramics
Earthenware Market
Ceramics
Thermal Spray Powder Market
Ceramics
Ceramic Armor Materials Market
Ceramics
Ceramic Proppant Market
Ceramics
Lithium Zirconate Market
Ceramics
Asia-Pacific Ceramic Coatings Market
Ceramics
Clay Market
Ceramics
East Africa Ceramic Tiles Market
Ceramics
Ceramic Frit Market
Ceramics
Quartz Powder Market
Ceramics
China Ceramic Market
Ceramics
Industrial Ceramics Market