
 Slow and Controlled Release Pesticides Market | 2026-2036
Slow and Controlled Release Pesticides Market Size, Share, and Industry Trends Forecast 2026-2036
Slow and Controlled Release Pesticides Market Outlook
Consolidation among North American row-crop cooperatives is expanding the addressable market for volume-formulation suppliers. BASF SE leverages polymer encapsulation expertise to sustain long-term supply agreements with integrated grain handlers. Syngenta Crop Protection AG anchors its position through biological evaluation networks that validate field persistence claims across diverse soil chemistries. FMC Corporation differentiates via precision-coating technologies that reduce active ingredient loading without sacrificing efficacy windows.
Slow and controlled release pesticides are crop protection products engineered with polymer matrices, lipid barriers, or inorganic shell structures that modulate active ingredient diffusion rates over weeks to months, typically achieving 30-90 day release profiles depending on environmental moisture and temperature regimes. Their primary purpose is to maintain therapeutic pest control concentrations while minimizing leaching, volatilization, and non-target exposure. Microencapsulated formulations command the deepest margin pools due to patent-protected wall chemistry and application-specific customization, whereas biodegradable carriers represent the fastest-expanding category as registrants anticipate EU Green Deal biomonitoring requirements. Granule applications dominate volume in broad-acre cereals, though nanoformulations are gaining trial adoption in high-value horticulture where foliar penetration timing is critical.
EPA residue chemistry reviews under FIFRA are lengthening registration timelines for conventional actives, indirectly favoring controlled-release formats that demonstrate reduced environmental metabolite loads. REACH compliance in Europe and China's GB standard revisions for agricultural chemical migration are converging on stricter ecotoxicological endpoints that legacy formulations struggle to satisfy. Stakeholders must monitor how Brazil's ANVISA aligns its toxicological re-evaluation calendar with OECD test guideline updates, as this synchronization will determine which encapsulation platforms secure multi-jurisdictional approval efficiency.
Market Dynamics
Polymer encapsulation chemistry is bifurcating the competitive landscape between patent-protected microencapsulation specialists and biodegradable carrier innovators racing to meet EU Green Deal biomonitoring deadlines.
Growth Catalysts
- EPA residue chemistry reviews:Extended FIFRA registration timelines for conventional actives are redirecting development budgets toward controlled-release formats that demonstrate reduced environmental metabolite loads.
- Brazil's Cerrado soybean belt:Large-scale no-till operations require season-long pest control without repeat applications, concentrating procurement of season-extended formulations.
- EU Green Deal Farm to Fork strategy:Tightening active ingredient approval thresholds are accelerating reformulation investments toward biodegradable carrier systems that anticipate biomonitoring requirements.
Market Restraints
- Specialty polymer supply concentration:Wall-formulation chemistries rely on concentrated North American and German specialty chemical suppliers, creating input vulnerability.
- REACH compliance costs:European ecotoxicological endpoint requirements demand extensive dossier preparation that smaller registrants cannot absorb.
- Technical release-profile variability:Soil moisture and temperature fluctuations across microclimates create inconsistent field performance that undermines grower confidence.
Strategic Opportunities
- California specialty crop premiumization:Central Valley growers expanding procurement of microencapsulated formulations to meet residue limits present a high-margin demand pocket.
- Biological-encapsulation convergence:Combining microbial actives with controlled-release matrices opens new efficacy windows against pesticide-resistant pest populations.
- Direct-to-cooperative distribution:Consolidating North American row-crop cooperatives create channel openings for volume-formulation suppliers to bypass traditional distribution tiers.
Industry Challenges
- Formulation chemist scarcity:The specialized skill set combining polymer science with agrochemical stability testing is concentrated among retiring cohorts at legacy registrants.
- Multi-jurisdictional approval synchronization:Brazil's ANVISA toxicological re-evaluation calendar misalignment with OECD test guideline updates creates redundant study requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Slow and Controlled Release Pesticides Market |
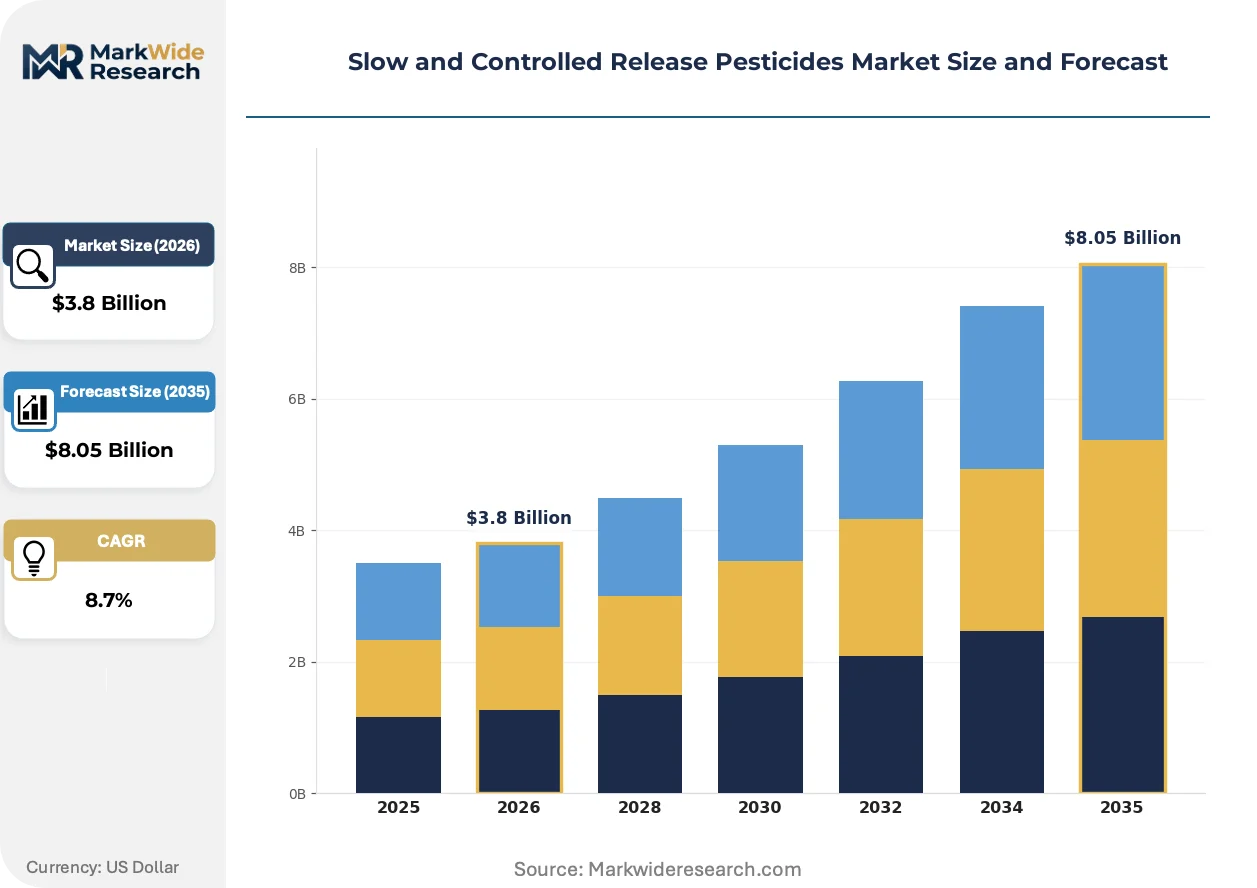
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granules, Pellets, Coated Fertilizers, Microencapsulated Formulations End Use Industry: Agriculture, Horticulture, Turf Management, Forestry Distribution Channel: Online, Offline, Retail, Wholesale Formulation Technology: Polymer-based, Biodegradable, Nanoformulations, Inorganic Compounds |
| Companies Covered | Corteva Agriscience, DuPont de Nemours, Inc., BASF SE, Sumitomo Chemical Co. Ltd., ADAMA Agricultural Solutions Ltd., Bayer AG, FMC Corporation, The Dow Chemical Company, Syngenta Crop Protection AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Slow and Controlled Release Pesticides Market Strategic Shifts
Active ingredient stabilization through advanced barrier technologies is compressing the gap between laboratory release profiles and variable field performance, reshaping how registrants validate commercial claims.
Chitosan-lignin composite shells are integrating enzymatic biodegradation triggers with moisture-activated diffusion mechanisms. Specialty vegetable growers in Spain's Almería greenhouse cluster are piloting these formulations for precision-timed thrips control. The technology is integrating biological and synthetic chemistry disciplines that previously operated in siloed R&D functions.
REACH authorization amendments under the EU Green Deal are restricting persistent organic pollutant thresholds in agricultural chemical metabolites. Registrants must now submit extended environmental fate studies for encapsulated actives that demonstrate soil residue dissipation within 120 days. Microencapsulated pyrethroid formulations face the steepest compliance burden, driving accelerated biodegradable carrier substitution in European cereal applications.
Buyer concentration among integrated grain handlers is compressing formulation procurement cycles from annual tenders to multi-season supply agreements. Large cooperatives in Iowa and Illinois are consolidating purchasing through preferred supplier frameworks that demand validated field persistence data across diverse soil chemistries. This concentration is most visible in corn-soybean rotation systems where input standardization reduces operational complexity.
Slow and Controlled Release Pesticides Market Segmentation
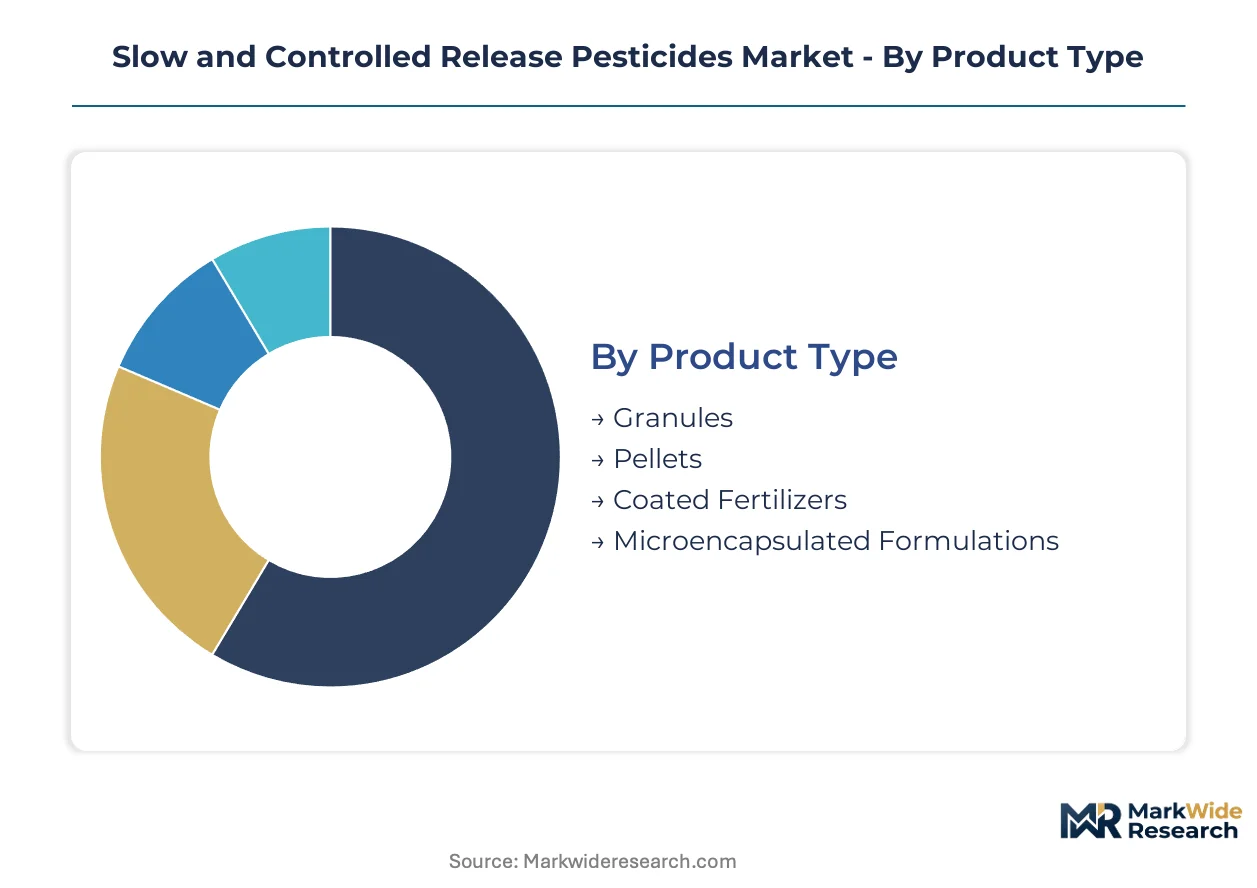
Segmentation in slow and controlled release pesticides reveals divergent margin structures across formulation technologies. Product type and end-use combinations determine whether suppliers capture commodity volume or premium pricing.
Product Type:
Volume concentrates in granular applications for broad-acre cereals, while microencapsulated formats command the deepest margin pools through patent-protected wall chemistry.
- Microencapsulated Formulations:Polymer shell structures modulate active ingredient diffusion over 30-90 day windows. California specialty crop growers in the Central Valley are expanding procurement to meet EPA residue limits for export markets.
- Granules:Inorganic or clay-based matrices deliver bulk active loading for soil incorporation. Brazil's Cerrado soybean belt concentrates demand for season-long pest control without repeat applications in no-till systems.
- Pellets:Compressed formulations with controlled dissolution rates suit precision planting equipment.
- Coated Fertilizers:Active ingredient integration with nutrient delivery systems targets high-value horticulture.
Today's leader: Microencapsulated Formulations. Tomorrow's challenger: Granules.
End Use Industry:
Agriculture dominates volume throughput, though horticulture applications generate superior per-hectare formulation revenue.
- Agriculture:Row-crop systems in Iowa and Illinois consolidate procurement through cooperative frameworks demanding validated field persistence data across diverse soil chemistries.
- Horticulture:Greenhouse clusters in Spain's Almería pilot chitosan-lignin composite shells for precision-timed thrips control, integrating enzymatic biodegradation triggers.
- Turf Management:Golf course and sports field maintenance requires uniform release profiles across variable microclimates.
- Forestry:Extended protection windows match multi-year pest cycles in plantation systems.
Agriculture anchors current volume. Horticulture climbs the fastest on per-unit value.
Distribution Channel:
Channel selection determines whether suppliers access consolidated cooperative purchasing or fragmented retail decision-making.
- Wholesale:Integrated grain handlers compress procurement cycles from annual tenders to multi-season supply agreements, favoring volume-formulation suppliers with validated persistence claims.
- Offline:Traditional agricultural retailers maintain relationships with legacy registrants for technical support.
- Online:Direct-to-farm platforms emerge for specialty formulation trials.
- Retail:Small-holder access points concentrate in developing agricultural economies.
Wholesale consolidates share. Online platforms represent the fastest-expanding access route.
Formulation Technology:
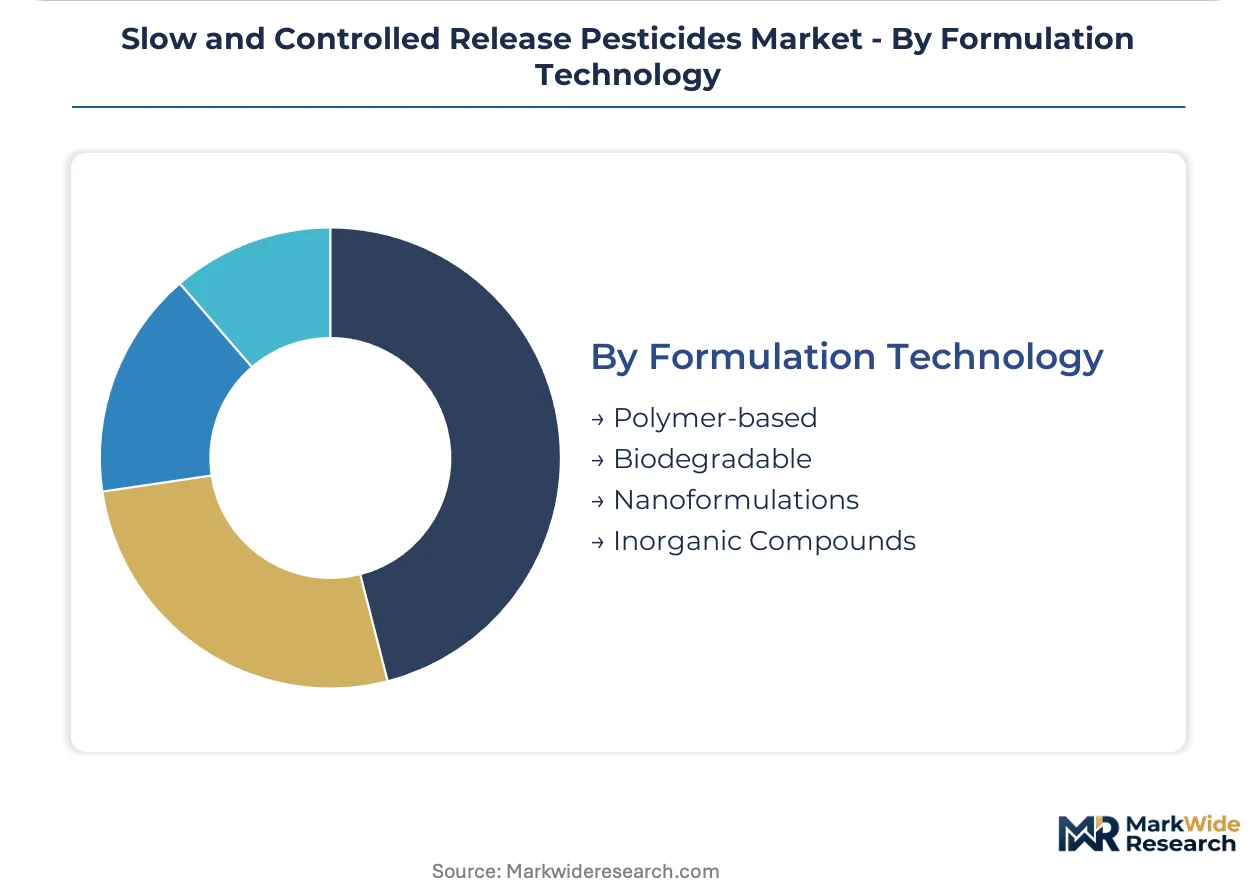
Technology selection increasingly reflects regulatory anticipation rather than purely technical performance.
- Biodegradable:Carrier systems incorporating chitosan, lignin, or starch matrices anticipate EU Green Deal biomonitoring requirements and REACH authorization amendments restricting persistent organic pollutant thresholds.
- Polymer-based:Patent-protected encapsulation chemistries sustain long-term supply relationships with major registrants.
- Nanoformulations:Sub-micron delivery systems gain trial adoption in high-value horticulture where foliar penetration timing is critical.
- Inorganic Compounds:Clay and mineral matrices serve cost-sensitive broad-acre applications.
Polymer-based systems defend current position. Biodegradable formats gain share fastest on regulatory alignment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation chemists with polymer science expertise concentrate in Germany's industrial Rhine corridor and California's agricultural technology corridor. Their specialized knowledge anchors regional competitive advantages in encapsulation platform development. These talent clusters shape where registrants locate R&D facilities and field validation networks.
United States
EPA residue chemistry reviews under FIFRA are extending registration timelines for conventional actives, redirecting development budgets toward controlled-release formats that demonstrate reduced environmental metabolite loads. California's Central Valley specialty crop growers are expanding procurement of microencapsulated formulations to meet residue limits for export markets. Iowa and Illinois row-crop cooperatives are consolidating purchasing through preferred supplier frameworks demanding validated field persistence data.
Germany
REACH compliance costs and authorization amendments restricting persistent organic pollutant thresholds are accelerating reformulation investments toward biodegradable carrier systems. ECHA's tightening ecotoxicological endpoint requirements demand extensive dossier preparation that favors registrants with established polymer encapsulation expertise. Specialty chemical suppliers in the Rhine-Neckar metropolitan region provide concentrated inputs for wall-formulation chemistries.
Brazil
Large-scale no-till operations in the Cerrado soybean belt require season-long pest control without repeat applications, concentrating procurement of season-extended formulations. ANVISA's toxicological re-evaluation calendar alignment with OECD test guideline updates will determine which encapsulation platforms secure multi-jurisdictional approval efficiency. Mato Grosso's integrated grain handlers are compressing procurement cycles from annual tenders to multi-season supply agreements.
China
GB standard revisions for agricultural chemical migration are converging on stricter ecotoxicological endpoints that legacy formulations struggle to satisfy. The country's national chemical regulator is tightening active ingredient approval thresholds for conventional pesticides. Yangtze River Delta manufacturing clusters are scaling production of biodegradable carrier matrices incorporating chitosan and lignin composites.
Spain
EU Green Deal Farm to Fork strategy biomonitoring requirements are driving trial adoption of enzymatic biodegradation triggers in greenhouse applications. Almería's protected horticulture cluster is piloting chitosan-lignin composite shells for precision-timed thrips control. EFSA's extended environmental fate study requirements for encapsulated actives are reshaping how registrants validate commercial claims in Mediterranean growing conditions.
Slow and Controlled Release Pesticides Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across encapsulation technology tiers. The vendor base organizes around three strategic archetypes: integrated agrochemical majors with captive polymer science divisions, independent formulation technology licensors, and regional contract manufacturers serving specific growing conditions. Dominant competitive moves include backward integration into specialty polymer supply and multi-season supply agreement anchoring with consolidating cooperative buyers.
Within the integrated major tier, BASF SE and Syngenta Crop Protection AG exemplify divergent strategic positioning around encapsulation platform development. FMC Corporation occupies a distinct position among North American registrants emphasizing precision-coating technologies. Sumitomo Chemical Co. Ltd. represents the Asia-Pacific-based archetype with polymer science capabilities anchored in Japanese industrial chemistry traditions. These company structures reflect how geographic origin and corporate heritage shape competitive approach in a market where regulatory anticipation increasingly determines technology selection.
| Leading Market Players |
|---|
| Corteva Agriscience |
| DuPont de Nemours, Inc. |
| BASF SE |
| Sumitomo Chemical Co. Ltd. |
| ADAMA Agricultural Solutions Ltd. |
| Bayer AG |
| FMC Corporation |
| The Dow Chemical Company |
| Syngenta Crop Protection AG |
| Others |
Value Chain & Pricing Dynamics
Polymer formulation chemists concentrate in Germany's Rhine-Neckar corridor and California's agricultural technology belt, creating labor-cost differentials that widen pricing spreads between premium microencapsulated formulations and commodity granule applications. Their specialized expertise in wall-chemistry design anchors tiered pricing structures that separate patent-protected specialty formats from biodegradable carrier alternatives.
Pricing Analysis
Bundled technical service contracts versus unbundled product-only procurement splits the market into divergent pricing architectures. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by certification grade and volume scale, with EPA-compliant residue profiles commanding substantial premiums. Pricing pressure stems from REACH compliance dossier costs compressing margins for mid-tier registrants. Large-scale cooperative buyers in Iowa and Illinois exhibit lowest price sensitivity due to multi-season supply agreement anchoring, while small-holder retailers in developing markets face acute cost compression.
Supply Chain Analysis
Domestic-content mandates in China's Yangtze River Delta manufacturing clusters are reshaping sourcing patterns for chitosan and lignin composite matrices. Specialty polymer inputs draw from concentrated suppliers in Germany and the United States, with active ingredient precursors anchored in Indian and Chinese chemical manufacturing. Single-source vulnerability persists for microencapsulation wall-formulation chemistries. Distribution runs through consolidating North American grain handlers and European cooperative frameworks that compress procurement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The slow and controlled release pesticides market functions as a stable compounder, with regulatory-driven reformulation cycles providing steady replacement demand that sustains pricing power across technology generations.
For Market Incumbents: Cement long-term supply relationships with integrated grain handlers through validated field persistence data across diverse soil chemistries. Deepen backward integration into specialty polymer supply to defend against input concentration risks from Rhine-Neckar suppliers. Biological-encapsulation convergence represents the critical R&D frontier for sustaining differentiation against biodegradable carrier innovators.
For New Entrants and Emerging Players: Direct-to-farm digital platforms offer the most penetrable channel route for bypassing traditional distribution tiers. Target California Central Valley specialty crop growers with precision-timed microencapsulated formulations that command residue-compliant premiums. White-space exists in nanoformulation trials for high-value horticulture where foliar penetration timing drives purchasing decisions.
For Investors and Strategic Acquirers: Integrated agrochemical majors with captive polymer science divisions are the most active acquirers in this space, seeking formulation technology licensors that bridge biological and synthetic chemistry disciplines. The five-to-ten-year viability window favors mid-cap specialists with demonstrated REACH dossier capabilities. Watch Brazil's ANVISA alignment with OECD test guideline updates as the signal for multi-jurisdictional approval efficiency inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Carrier Transition | EU Green Deal biomonitoring requirements are accelerating chitosan-lignin composite shell adoption across European cereal applications. |
| Backward Integration into Specialty Polymers | Captive wall-chemistry production reduces input vulnerability from concentrated Rhine-Neckar suppliers. |
| Multi-Season Supply Agreement Anchoring | Consolidating Iowa and Illinois cooperatives demand validated persistence data that locks out smaller competitors. |
| Biological-Encapsulation Convergence | Microbial active integration with controlled-release matrices opens efficacy windows against resistant pest populations. |
| Direct-to-Cooperative Distribution Bypass | Channel restructuring eliminates traditional retail markups for volume-formulation suppliers in North American row-crop systems. |
Study Parameters
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with formulation R&D directors, regulatory affairs leads at major registrants, procurement managers at integrated grain handlers, and technical sales specialists at agricultural cooperatives combined with secondary validation from EPA FIFRA registration databases, ECHA authorization amendments, ANVISA toxicological re-evaluation calendars, and customs trade data for specialty polymer inputs. Top-down macro indicators and bottom-up segment builds triangulate to final market estimates.
Input-output matrices map active ingredient loading requirements across formulation technology types, end-use applications, and regional regulatory clusters over the projection horizon. Segmentation dimensions include product type, formulation technology, end-use industry, and distribution channel, with CAGRs derived from regression analysis against historical replacement cycles and regulatory reformulation timelines. Soil moisture and temperature regime variability across microclimates serves as a key forecast sensitivity input.
The model assumes a particular technology adoption path; alternative pathways for enzymatic biodegradation trigger integration would alter the outlook for synthetic polymer encapsulation platforms. Forecasts reflect assumptions regarding EPA residue chemistry review timelines, EU Green Deal implementation pacing, and Brazil's OECD guideline synchronization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Formulation Chemicals
Topical Applicators Market
Formulation Chemicals
Global Benzaldehyde Derivatives Market
Formulation Chemicals
Global Chemical Licensing Market
Formulation Chemicals
Foundry Binders Market
Formulation Chemicals
Ammonium Fluoride Solution Market
Formulation Chemicals
Drug Formulation Market
Formulation Chemicals
Global Formulation Development Outsourcing Market
Formulation Chemicals
Anti-Gelling Agent Market
Formulation Chemicals
Gelling Agent Market
Formulation Chemicals
Template Preparation Kits Market
Formulation Chemicals
Sol-Gel Products Market
Formulation Chemicals
Solution Deposition Precursor Market
Formulation Chemicals
Forchlorfenuron Market
Formulation Chemicals
Embossing Powder Market