
 Quartz Powder Market | 2026-2036
Quartz Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Quartz Powder Market Intelligence
Long-term supply contracts for ultra-high-purity feedstock is consolidating procurement leverage among buyers in semiconductor and solar wafer manufacturing. Sibelco leverages its vertically integrated mining-to-refining network across Spruce Pine and Drag deposits to sustain premium-grade output. Imerys S.A. anchors European supply through specialized beneficiation plants in France and Belgium. Jiangsu Pacific Quartz Co., Ltd competes aggressively on cost while extending domestic capacity for solar-grade material.
Quartz powder consists of finely processed crystalline silica derived from crushed and milled quartzite or pegmatite sources, typically achieving SiO₂ content exceeding 99.5% in high-purity grades through acid leaching and thermal treatment. Its primary industrial purpose centers on providing thermal stability, chemical inertness, and precise dimensional control in crucibles, investment molds, and engineered composites. Ground quartz dominates volume flows into construction fillers and foundry applications where cost efficiency outweighs purity thresholds. High-purity grades command disproportionate margin pools from semiconductor crucible and fiber optic preform end users, while specialty grades capture niche value in pharmaceutical and advanced ceramic segments.
EPA silica exposure limits under OSHA's respirable crystalline silica standard constrain dry-processing operations and mandate wet-cutting methods in US facilities. REACH registration requirements and ECHA classification of crystalline silica as carcinogenic shape product liability and export compliance burdens for European producers. China's MEE enforces stricter particulate emissions thresholds under evolving GB standards, forcing domestic refiners toward closed-loop water systems. Stakeholders must monitor divergence between regional purity certifications as semiconductor OEMs tighten supplier qualification protocols without harmonized international standards.
Market Dynamics
Semiconductor foundries in Taiwan and South Korea are consolidating procurement leverage through decade-long supply contracts for crucible-grade feedstock, compressing supplier margins and forcing mid-tier refiners toward solar-grade diversification.
Growth Catalysts
- GB Standards Stringency:China's MEE particulate thresholds under evolving silica emission rules are accelerating closed-loop water system adoption among domestic refiners, creating captive demand for cleaner processing equipment.
- Photovoltaic Wafer Expansion:East Asian electronics corridors are clustering polysilicon ingot production, pulling high-purity quartz consumption into Taiwan and South Korean semiconductor foundries for crucible manufacturing.
- Dual Carbon Goals:China's national decarbonization mandates are redirecting state subsidies toward energy-efficient thermal treatment technologies in quartz beneficiation plants.
Market Restraints
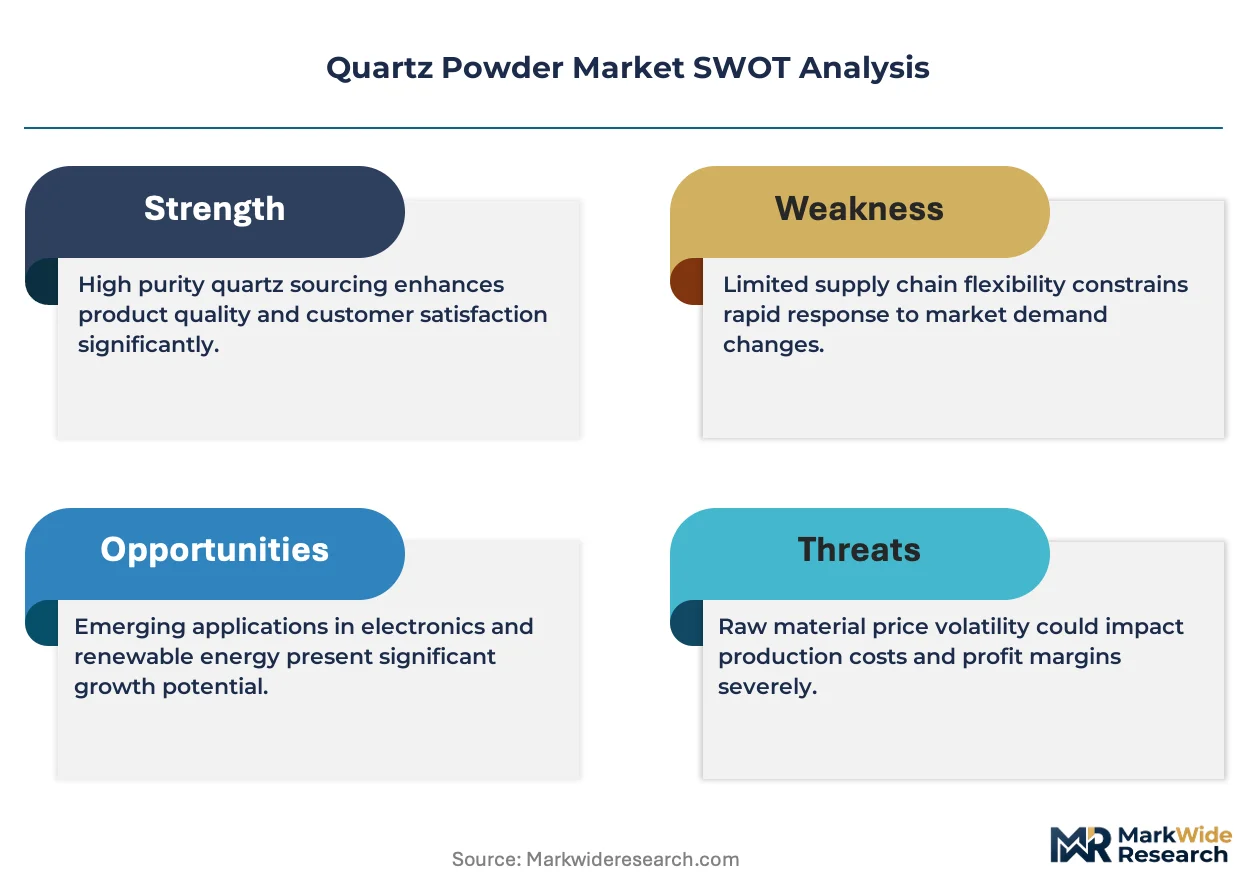
- Input Cost Volatility:Natural gas price swings directly impact thermal treatment costs in acid-leaching refinement, squeezing margin pools for standard-grade producers.
- Supply Concentration Risk:Premium-grade feedstock dependence on Spruce Pine and Drag pegmatite deposits creates geographic chokepoints vulnerable to weather or labor disruptions.
- Substitution Threat:Synthetic fused silica crucibles are capturing share in lower-tier solar applications where purity tolerances permit non-crystalline alternatives.
Strategic Opportunities
- Pharmaceutical Excipient Grade:Untapped demand for USP-grade quartz powder in tablet disintegrants offers margin expansion beyond industrial applications.
- Advanced Ceramic Convergence:Silicon nitride-quartz composite sintering is opening precision thermal management applications in aerospace heat shields.
- EU Green Deal Alignment:REACH-registered low-carbon footprint quartz qualifies for preferential procurement under CSRD-mandated supply chain disclosures.
Industry Challenges
- Crucible Certification Timelines:Semiconductor OEM qualification protocols require 18-24 month validation cycles for new feedstock sources, locking out rapid supplier switching.
- Respirable Silica Compliance:OSHA's crystalline silica standard mandates wet-cutting infrastructure retrofits that strain capital allocation for dry-processing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Quartz Powder Market |
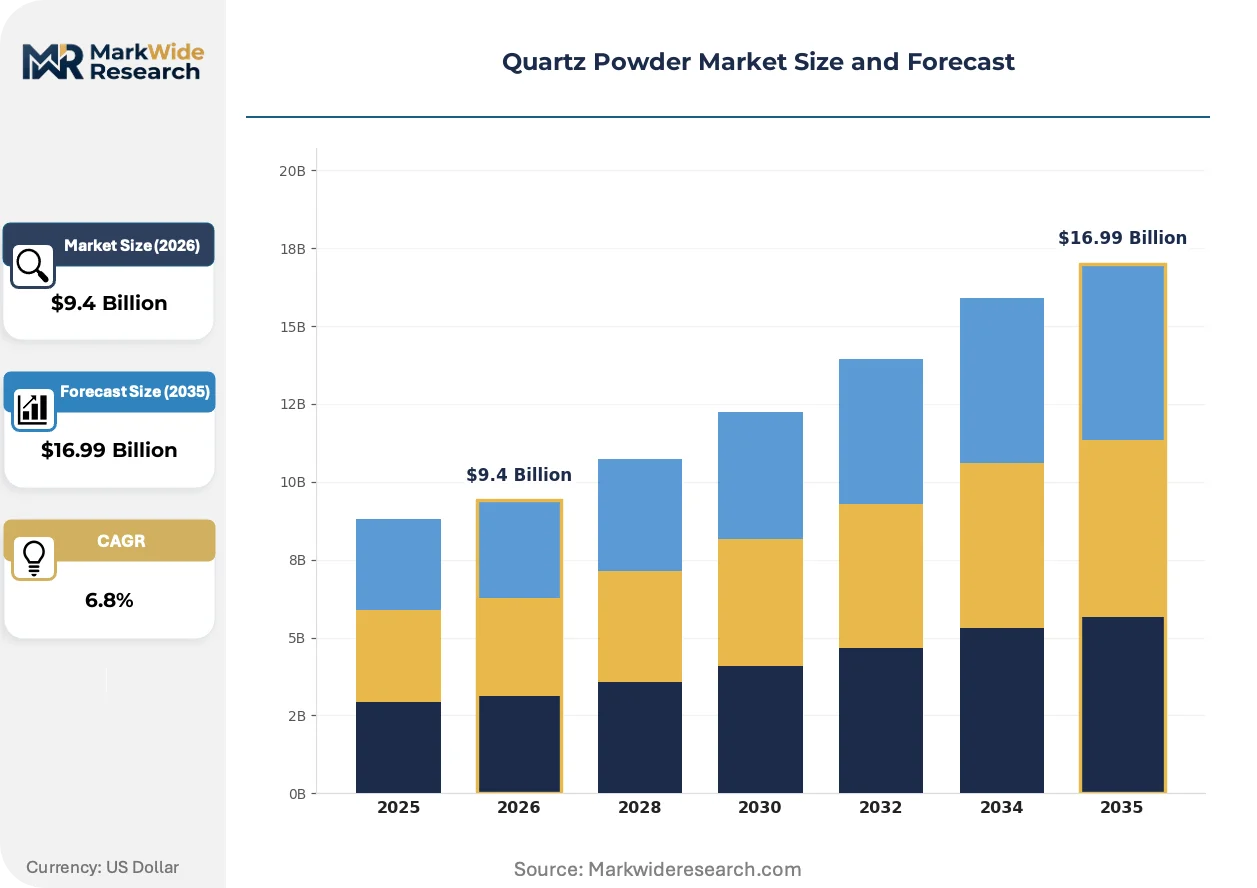
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $16.99 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fused Quartz, Ground Quartz, Mesh Quartz, Silica Sand End User: Construction, Glass Manufacturing, Foundry, Ceramics Application: Abrasives, Fillers, Reinforcements, Chemical Production Quality Grade: High Purity, Low Iron, Medium Purity, Specialty Grades |
| Companies Covered | Imerys S.A., Australian Silica Quartz Group Ltd, Sibelco, Covia Corp., Russian Quartz LLC, The Quartz Corp., Quarzwerke Group, Tanvi Mines & Minerals, Jiangsu Pacific Quartz Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Quartz Powder Market Strategic Shifts & Innovations
Processing automation and regulatory fragmentation are compressing traditional batch-refinement economics while opening premium niches for certified low-impurity supply chains.
AI-driven optical sorting is automating impurity detection in crushed quartzite feedstock. Solar wafer manufacturers in Jiangsu province are adopting these systems at pilot scale. The technology is automating labor-intensive manual inspection, reducing rejection rates in crucible-grade output.
REACH registration requirements and ECHA carcinogenic classification are reshaping product liability frameworks for European quartz powder distributors. Exporters now face mandatory downstream user communication obligations. Specialty-grade producers in Belgium and France are absorbing compliance costs into premium pricing for semiconductor customers.
Long-term offtake agreements are displacing spot-market purchasing among Taiwanese foundry operators. Direct supplier relationships now span five-to-seven year horizons with embedded volume guarantees. This pattern concentrates procurement leverage in East Asian electronics corridors while marginalizing trading intermediaries.
Quartz Powder Market Segmentation
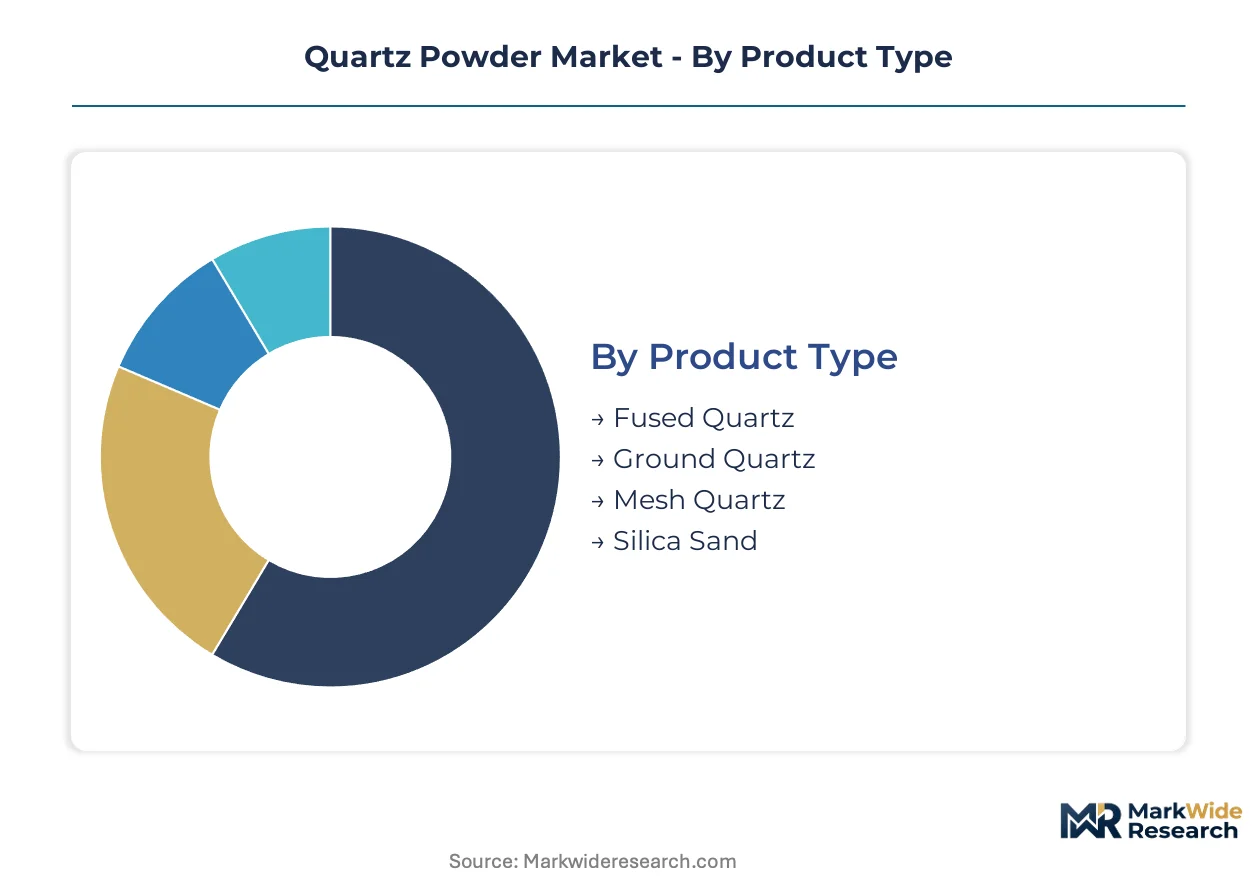
Quartz powder markets fragment across purity thresholds and thermal processing routes that determine crucible compatibility, refractory performance, and regulatory compliance costs. Buyers segment procurement strategies by end-use purity mandates rather than geographic sourcing alone.
Product Type:
Cost tiers separate commodity volume plays from premium thermal stability applications.
- Fused Quartz:Manufactured through electric arc melting of crystalline silica to achieve amorphous structure with near-zero thermal expansion. Semiconductor crucible manufacturers in Taiwan and South Korea specify fused grades for single-crystal silicon ingot production where thermal shock resistance prevents crucible fracture during cooling cycles.
- Ground Quartz:Mechanically milled crystalline silica retaining α-quartz structure, typically achieving 99.0-99.5% SiO₂ content through standard beneficiation. Construction filler and foundry binder applications in China's industrial corridors absorb the bulk of ground quartz volume where cost efficiency dominates procurement criteria.
- Mesh Quartz:Size-classified particulate meeting precise sieve specifications for investment casting molds and precision ceramic pressing.
- Silica Sand:Coarse-grained quartz aggregate for glass tank furnace linings and hydraulic fracturing proppants where purity requirements permit higher alumina and titania content.
Volume sits with Ground Quartz; growth tilts toward Fused Quartz.
End User:
Application maturity determines margin capture and contract duration.
- Construction:Concrete additive and engineered stone filler applications consuming standard-grade material under ASTM C618 specifications. China's infrastructure stimulus and India's smart city programs are pulling mesh-sized material into polymer-modified cement formulations where silica fume replacement drives specification shifts.
- Glass Manufacturing:Container, flat, and specialty glass producers specifying iron content below 0.03% for optical clarity. Low-iron deposits in Brazil and Madagascar supply float glass furnaces where GB standards on particulate emissions constrain domestic Chinese sourcing.
- Foundry:Mold and core binder systems utilizing rounded grain morphology for permeability control in ferrous casting.
- Ceramics:Whiteware, refractory, and advanced ceramic sintering applications where thermal expansion matching determines grade selection.
Long-term contracting dominates Glass Manufacturing; spot purchasing persists in Construction.
Application:
Performance requirements stratify pricing across functional additives versus structural reinforcements.
- Abrasives:Hardness-driven applications in stone cutting, sandblasting, and grinding wheel manufacture where friability and grain angularity determine cutting efficiency. OSHA's respirable crystalline silica standard is forcing wet-abrasive system adoption in US fabrication shops, redirecting demand toward coated abrasives with encapsulated grain.
- Fillers:Extender applications in paints, plastics, and rubber compounding where particle size distribution controls viscosity and tensile properties. Automotive lightweighting in Germany and Japan is expanding precipitated silica substitution in tire tread formulations, compressing natural quartz filler margins.
- Reinforcements:Fiber-reinforced polymer composite applications requiring surface-treated quartz for matrix adhesion.
- Chemical Production:Silane and silicon metal feedstock for semiconductor precursor manufacturing.
Fillers command volume share; Chemical Production exhibits steepest expansion trajectory.
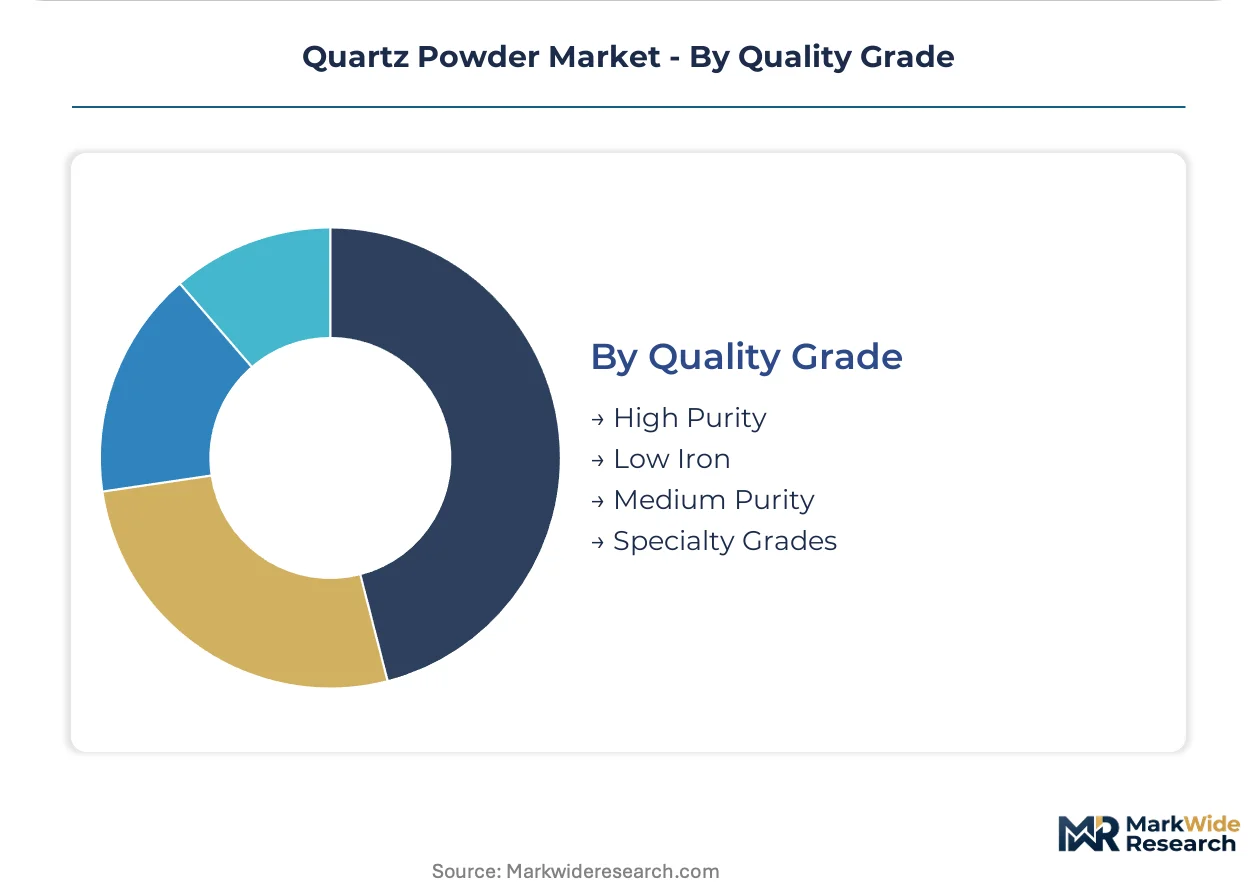
Quality Grade:
Impurity thresholds create supply scarcity and pricing power concentration.
- High Purity:SiO₂ content exceeding 99.995% with controlled alkali and transition metal levels, achieved through acid leaching, chlorination, and thermal treatment of Spruce Pine pegmatite. Taiwan Semiconductor Manufacturing and Samsung Foundry qualify only three global sources for crucible-grade feedstock, locking in decade-long offtake agreements with embedded volume escalators.
- Low Iron:Ferric oxide content below 0.01% for optical and solar glass applications where color neutrality is mandatory. Brazil's Minas Gerais deposits and Madagascar's Ankazobe region supply European solar glass manufacturers under REACH-registered supply chains qualifying for EU Green Deal procurement preferences.
- Medium Purity:Standard industrial grades for construction and foundry applications with 99.0-99.5% SiO₂ content.
- Specialty Grades:Pharmaceutical excipient, semiconductor packaging, and aerospace ceramic specifications with customized particle morphology and surface chemistry.
Medium Purity anchors volume; Specialty Grades capture margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hsinchu Science Park anchors high-purity quartz consumption through Taiwan Semiconductor Manufacturing's crucible supply chains. Taiwanese foundry operators lock in decade-long feedstock contracts with Spruce Pine-derived sources. South Korean memory fabricators in Pyeongtaek and Yongin mirror this procurement consolidation.
United States
Spruce Pine, North Carolina hosts the world's only ultra-high-purity pegmatite mining complex supplying semiconductor crucible manufacturers. EPA respirable crystalline silica enforcement under OSHA standards constrains dry-processing expansion in Appalachian refining corridors. Sibelco's vertically integrated mining-to-refining network across North Carolina and Drag, Nevada deposits sustains premium-grade output for domestic and export markets.
China
Jiangsu province's photovoltaic wafer manufacturers in Lianyungang and Xuzhou pull solar-grade quartz consumption into East Asian electronics corridors. MEE particulate emissions thresholds under evolving GB standards force domestic refiners toward closed-loop water systems and cleaner thermal treatment technologies. State subsidies under dual carbon goals redirect capital toward energy-efficient beneficiation plants in Shandong and Henan provinces.
Germany
Automotive lightweighting programs in Stuttgart and Munich expand precipitated silica substitution in tire tread formulations, compressing natural quartz filler margins. REACH registration requirements and ECHA carcinogenic classification reshape product liability frameworks for distributors serving Central European glass manufacturers. Quarzwerke Group's specialized beneficiation operations in North Rhine-Westphalia anchor regional supply for construction and foundry applications.
South Korea
Samsung Foundry and SK Hynix consolidate procurement leverage through multi-year supply contracts for crucible-grade feedstock in Yongin and Icheon semiconductor clusters. MFDS pharmaceutical-grade certification protocols create compliance barriers for excipient market entry. Pyeongtaek's memory fabrication expansion pulls high-purity quartz consumption away from spot-market purchasing toward direct supplier relationships.
France
Imerys S.A.'s specialized beneficiation plants in Brittany and Provence supply REACH-registered low-iron grades for European solar glass manufacturers. ANSM pharmaceutical excipient standards and EU Green Deal procurement preferences qualify certified low-carbon footprint quartz for preferential sourcing. The Auvergne-Rhône-Alpes ceramics corridor consumes mesh-classified material for precision investment casting molds serving aerospace supply chains.
Quartz Powder Market Key Industry Players
Capital-heavy producers compete with asset-light traders across tiered purity segments. The vendor base stratifies between integrated miners with captive pegmatite deposits and regional processors dependent on third-party feedstock. Three archetypes dominate: Spruce Pine-anchored premium-grade specialists, Chinese solar-grade volume players, and European REACH-registered distributors serving pharmaceutical niches. Competitive moves concentrate on backward integration into mining assets and geographic expansion toward East Asian electronics corridors.
Among integrated mining specialists, Sibelco and The Quartz Corp. exemplify the premium-grade archetype through control over Spruce Pine and Drag deposit access. Jiangsu Pacific Quartz Co., Ltd. occupies a position within the solar-grade volume tier, competing aggressively on cost while extending domestic capacity. Imerys S.A. and Quarzwerke Group anchor European supply through specialized beneficiation infrastructure and REACH-registered distribution networks serving construction and foundry segments.
| Leading Market Players |
|---|
| Imerys S.A. |
| Australian Silica Quartz Group Ltd |
| Sibelco |
| Covia Corp. |
| Russian Quartz LLC |
| The Quartz Corp. |
| Quarzwerke Group |
| Tanvi Mines & Minerals |
| Jiangsu Pacific Quartz Co., Ltd |
| Others |
Cost & Logistics Intelligence
High-purity crucible-grade certification against commodity construction-grade output creates a bifurcated pricing architecture that simultaneously concentrates supply chain leverage among Spruce Pine-anchored specialists and fragments procurement across dispersed regional processors serving cost-sensitive filler applications.
Pricing Analysis
Margin tightening in solar-grade material reflects decade-long offtake compression by Taiwanese and South Korean foundry operators locking in volume guarantees. Contract-based long-term offtake dominates semiconductor feedstock, while spot purchasing persists in construction fillers. Price differentiation hinges on GB standard compliance costs and thermal treatment energy intensity. Solar wafer manufacturers exhibit acute price sensitivity; semiconductor OEMs prioritize certification stability over unit cost.
Supply Chain Analysis
Reverse-logistics flows for crucible recycling and spent thermal treatment media remain underdeveloped, constraining circularity economics. Supply concentrates in the United States, China, and Brazil. Feedstock draws from Spruce Pine pegmatite, Jiangsu province quartzite, and Minas Gerais low-iron deposits. Single-source vulnerability around North Carolina ultra-high-purity ore creates geographic chokepoint exposure. Distribution runs through direct supplier relationships in East Asian electronics corridors and regional distributors in European construction markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OSHA respirable crystalline silica enforcement functions as a cost-of-compliance moat, elevating capital barriers for dry-processing expansions while advantaging wet-cutting infrastructure incumbents with amortized retrofit costs.
For Market Incumbents: To counter synthetic fused silica substitution in lower-tier solar applications, Sibelco and The Quartz Corp. should deepen backward integration into Drag deposit capacity expansion while accelerating pharmaceutical-grade certification investments to capture USP-grade excipient premiums beyond industrial commoditization. For New Entrants and Emerging Players: Direct-to-foundry digital procurement platforms offer white-space entry around spot-market disintermediation in Chinese solar-grade supply chains and REACH-registered pharmaceutical distribution networks serving European tablet manufacturers seeking qualified excipient sources. For Investors and Strategic Acquirers: Re-rating potential sits with integrated mining-to-refining specialists given tightening semiconductor OEM qualification protocols and multi-year contract visibility. Long-term viability favors Spruce Pine-anchored assets with captive pegmatite access. Monitor MFDS and ANSM pharmaceutical certification timelines as inflection indicators for excipient-grade margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mining Assets | Spruce Pine deposit control secures crucible-grade feedstock scarcity pricing for semiconductor OEMs. |
| Pharmaceutical-Grade Certification Investment | USP-grade qualification opens tablet disintegrant margins beyond construction filler commoditization. |
| Closed-Loop Water System Adoption | GB standards compliance enables continued operating permits in Jiangsu and Shandong refining corridors. |
| Long-Term Supply Agreement Structuring | Five-to-seven year offtake terms with Taiwanese foundries lock in volume visibility against spot volatility. |
| AI-Driven Optical Sorting Deployment | Pilot-scale automation in Jiangsu province reduces crucible-grade rejection rates and labor inspection costs. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving quartz refinery plant managers, semiconductor foundry procurement leads, solar wafer manufacturing technical directors, and REACH-registered distribution channel partners. SEC 10-K disclosures, MEE emissions filings, and OECD trade statistics provided triangulation against bottom-up capacity estimates and top-down demand modeling across purity grades and end-use applications.
Segment-level granularity modeled purity thresholds, thermal processing routes, end-use industry concentrations, and regional regulatory clusters throughout the forecast period. CAGRs derived from trend extrapolation of foundry expansion timelines, photovoltaic wafer capacity additions, and construction stimulus trajectories. Forecast inputs incorporated acid-leaching energy cost curves, crucible replacement rates in single-crystal silicon ingot production, and evolving GB particulate emission compliance timelines.
The model holds under sustained semiconductor capital expenditure and Chinese dual carbon policy continuity; deviation in natural gas price volatility or Spruce Pine labor disruptions would shift supply availability assumptions. Practitioners should monitor OSHA enforcement intensity and synthetic fused silica cost curves for early signals of substitution acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Ceramic Substrate Market
Ceramics
Thermal Spray Powder Market
Ceramics
North America Ceramic Coatings Market
Ceramics
Mullite Market
Ceramics
Ceramic Tiles Market
Ceramics
High Purity Mullite Powder Market
Ceramics
Ceramic Pigments Market
Ceramics
Ceramic Frit Market
Ceramics
Taiwan Ceramic Tiles Market
Ceramics
Technical Ceramics Market
Ceramics
Engineering Ceramics Market
Ceramics
Wollastonite Market
Ceramics
Asia-Pacific Kaolin Market
Ceramics
Germany Ceramic Tiles Market
Ceramics
Ceramic Kilns Market
Ceramics
Ceramics Packaging Market