
 Advanced Ceramics Market | 2026-2036
Advanced Ceramics Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced Ceramics Market Analysis
ISO 13356 certification for surgical implant-grade zirconia is reorganizing supplier hierarchies in medical ceramics. KYOCERA Corporation leverages its vertically integrated alumina substrate production to dominate Japanese electronics supply chains. CeramTec GmbH anchors European medical device procurement through specialized bio-implant manufacturing capabilities. Morgan Advanced Materials competes in high-temperature structural ceramics for aerospace turbine applications across multiple continents.
Advanced ceramics are inorganic, non-metallic materials formed from refined oxides, nitrides, or carbides and densified through sintering above 1,400°C to achieve hardness exceeding 1,500 HV and thermal stability beyond 1,200°C. These properties enable load-bearing applications where metals fail, including turbine blades, electronic substrates, and joint replacements. Alumina commands the largest volume share due to mature supply chains and cost-effective processing, while silicon carbide attracts the fastest investment as electric vehicle power electronics demand higher thermal conductivity substrates. Structural components generate the deepest margin pools because qualification cycles lock in long-term aerospace and defense contracts.
FDA 510(k) pathways govern bio-implant market access in the United States, while REACH restricts hazardous precursor chemicals in European manufacturing. Japan's METI promotes domestic silicon nitride production through industrial technology grants. EASA airworthiness directives increasingly specify ceramic matrix composites for next-generation engine hot sections. Stakeholders must monitor evolving qualification standards and regional subsidy programs to secure position in high-margin medical and aerospace segments.
Market Dynamics
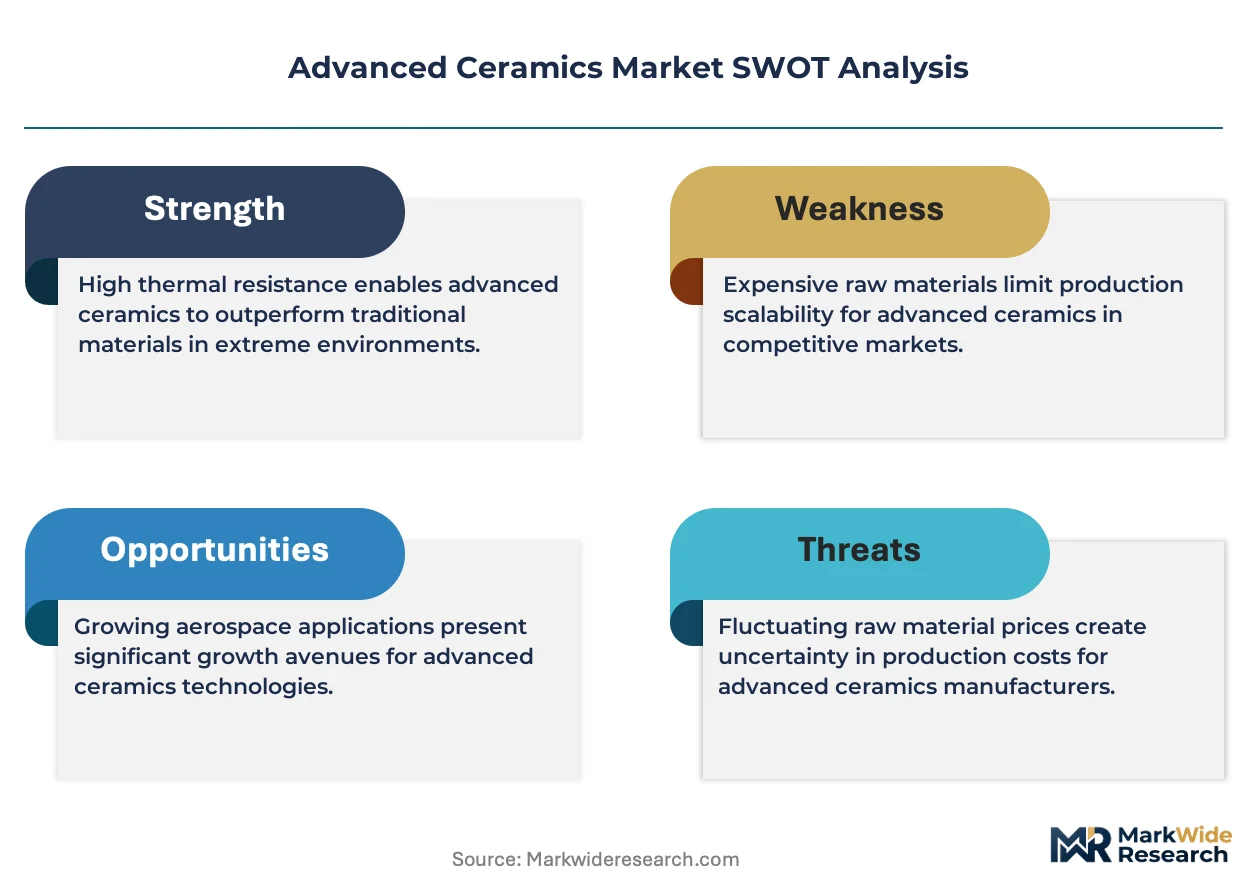
Silicon carbide substrate qualification cycles are compressing procurement timelines as electric vehicle power electronics manufacturers bypass traditional alumina supply chains for thermal management solutions.
Growth Catalysts
- EASA airworthiness directives:European engine manufacturers now specify ceramic matrix composites for hot-section components, locking in multi-year aerospace contracts.
- Semiconductor capital equipment:Japanese industrial ceramics clusters supply precision components for lithography and deposition systems serving global chip fabrication expansion.
- METI industrial technology grants:Japanese domestic silicon nitride production receives targeted subsidy support for next-generation turbine applications.
Market Restraints
- Yttria supply concentration:Rare-earth stabilizer sourcing concentrates in Chinese processing facilities, exposing zirconia implant manufacturers to input volatility.
- REACH precursor restrictions:European chemical registration requirements limit hazardous raw material availability for traditional oxide ceramic processing routes.
- Silicon nitride machining costs:Diamond grinding requirements for turbine blade finishing add manufacturing overhead that constrains price competitiveness against superalloys.
Strategic Opportunities
- FDA 510(k) pathway optimization:Streamlined bio-implant approvals create white space for surgical-grade zirconia hip and dental components in United States medical device markets.
- Solid-state battery ceramic electrolytes:Lithium-conducting oxide and sulfide ceramics enable next-generation energy storage architectures beyond lithium-ion liquid electrolyte limits.
- Direct OEM contracting:Aerospace engine manufacturers are consolidating supplier relationships, bypassing distributors for long-term structural ceramic procurement agreements.
Industry Challenges
- ISO 13356 certification timelines:Medical-grade zirconia qualification cycles extend months beyond standard industrial ceramic approvals, compressing product launch windows.
- Sintering furnace capacity constraints:High-temperature densification equipment requires capital deployment exceeding standard materials processing infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced Ceramics Market |
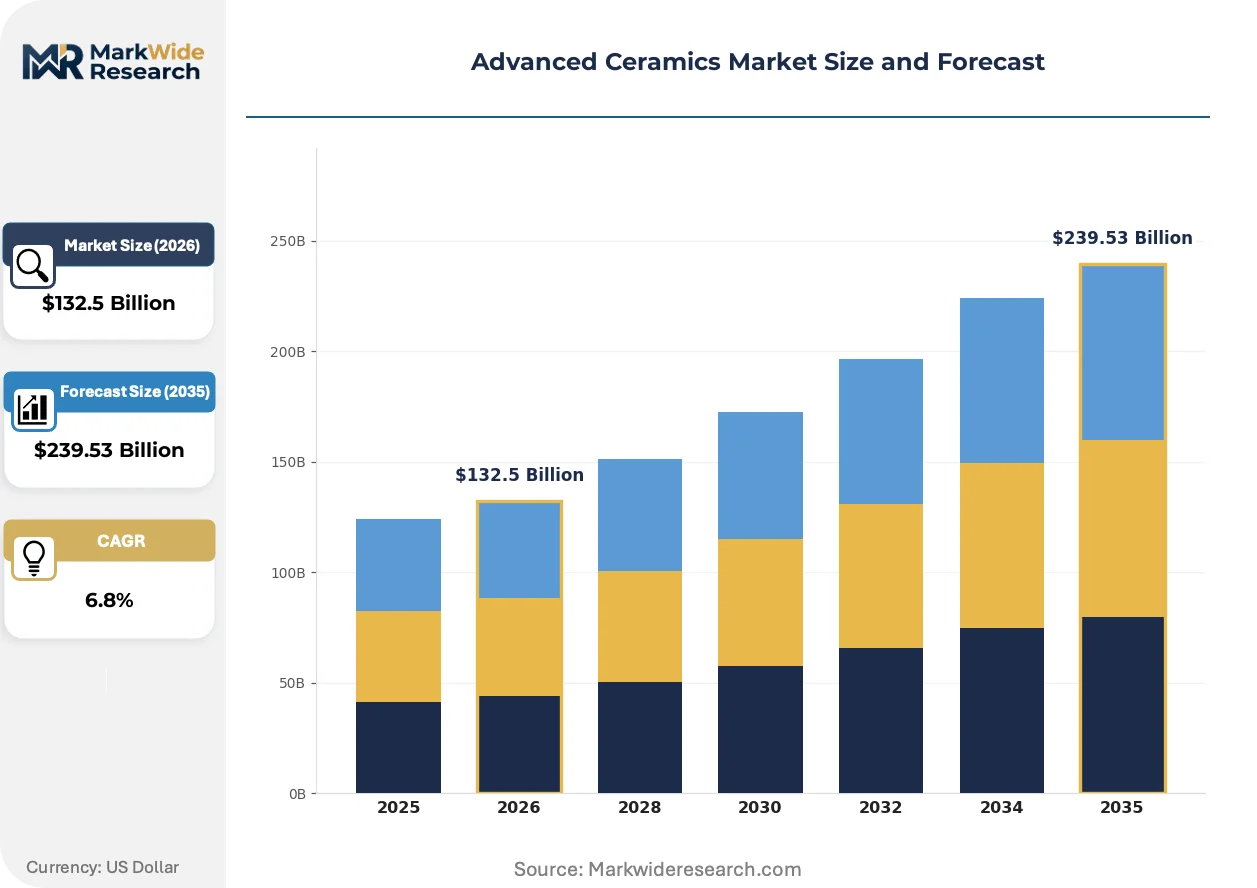
| Market Size in 2026 | $132.5 Billion |
| Market Size in 2035 | $239.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Alumina, Zirconia, Silicon Nitride, Silicon Carbide End Use Industry: Aerospace, Electronics, Medical Devices, Energy Manufacturing Process: Hot Pressing, Slip Casting, 3D Printing, Sintering Application: Structural Components, Insulators, Cutting Tools, Bio-implants |
| Companies Covered | KYOCERA Corporation, CeramTec GmbH, CoorsTek Inc., Morgan Advanced Materials, Saint-Gobain, 3M, AGC Inc., MARUWA Co., Ltd., Murata Manufacturing Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced Ceramics Market Emerging Trajectories
Additive manufacturing of technical ceramics is collapsing prototyping-to-production timelines while enabling geometric complexity impossible with conventional pressing and machining methods.
Silicon carbide power substrates are decomposing the thermal management hierarchy in electric vehicle inverters. Automotive Tier-1 suppliers are qualifying these components for volume production. Traditional alumina-DBC (direct bond copper) architectures are losing share as silicon carbide enables higher switching frequencies and reduced cooling system mass.
REACH authorization requirements are forcing reformulation of zirconia precursor chemistries across European manufacturing. Biomedical implant producers face extended substance evaluation timelines. German and French ceramic processors are accelerating yttria-stabilized zirconia supply chain audits to maintain market access.
Specification-driven procurement now dominates aerospace and medical segments, displacing price-centric sourcing. Buyers consolidate vendor lists around certified suppliers with vertical substrate production. Japanese electronics manufacturers and German engine OEMs exemplify this concentration, locking in multi-year agreements with qualified ceramic component specialists.
Advanced Ceramics Market Segmentation
Advanced ceramics procurement splits across four critical dimensions. Material chemistry determines thermal and mechanical performance ceilings. End-use qualification requirements lock in supplier relationships for decades. Manufacturing process selection constrains geometric complexity and unit economics. Application-specific certification gates control market access.
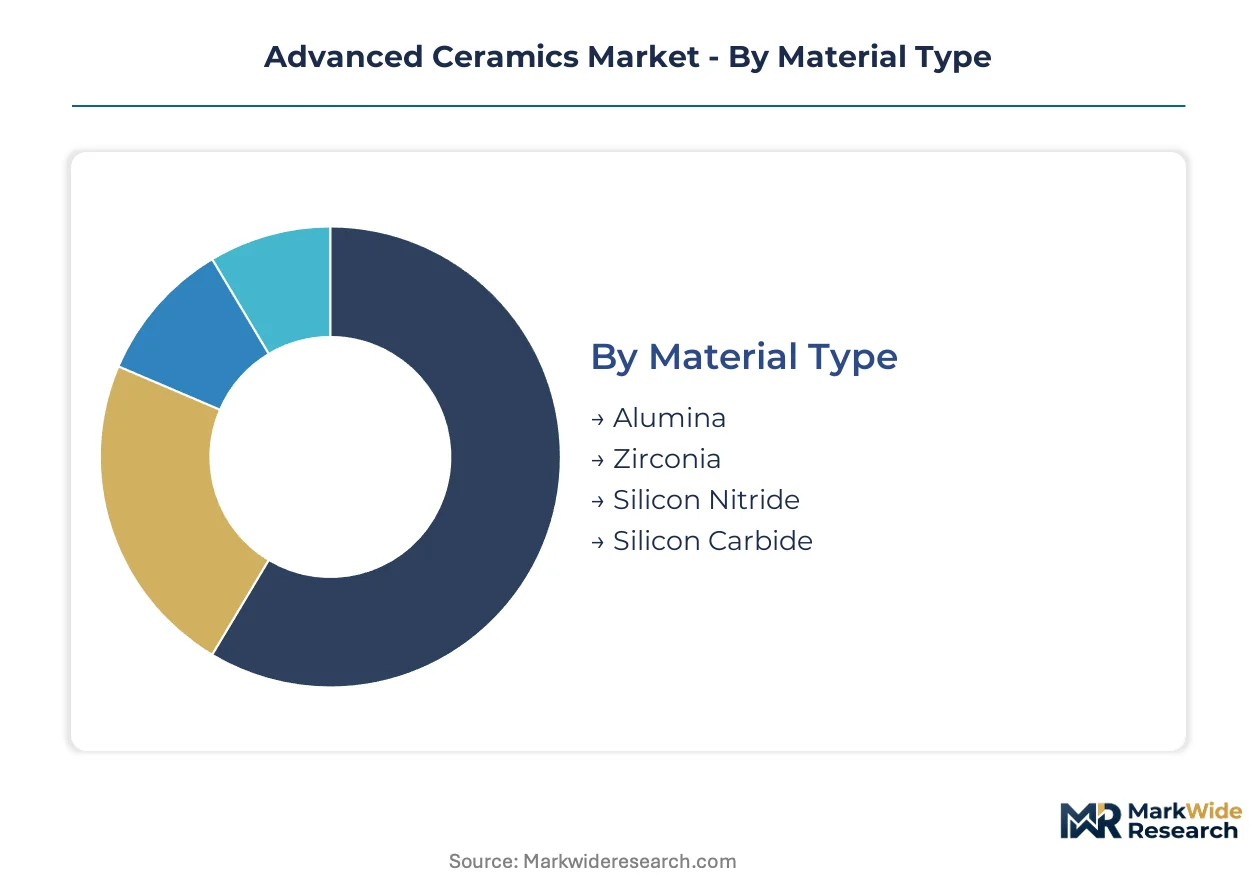
Material Type:
REACH authorization tiers and FDA implant-grade pathways differentiate material commercialization timelines and margin structures.
- Alumina:Aluminum oxide ceramics achieve hardness exceeding 1,500 HV through sintering above 1,400°C. Electronics substrate demand in Japanese industrial clusters consumes the largest volume share, though price compression from mature supply chains limits margin expansion.
- Zirconia:Yttria-stabilized tetragonal polycrystals deliver fracture toughness unmatched by other oxide ceramics. ISO 13356 certification requirements for surgical implants in European and United States markets extend qualification timelines, creating supplier stickiness and premium pricing power for certified manufacturers.
- Silicon Nitride:Covalent-bonded nitride ceramics withstand thermal shock beyond 1,200°C. EASA airworthiness directives for next-generation turbine components are accelerating German and Japanese aerospace procurement.
- Silicon Carbide:Wide-bandgap semiconductor substrates enable power electronics thermal conductivity above 400 W/mK. Automotive inverter qualification is compressing traditional procurement timelines as electric vehicle manufacturers bypass alumina supply chains.
Established volume favors alumina; emerging adoption favors silicon carbide.
End Use Industry:
Customer concentration and contract duration separate margin profiles across verticals.
- Aerospace:Ceramic matrix composites specified in EASA engine hot-section directives command multi-year procurement agreements. German and Japanese turbine manufacturers consolidate supplier lists around qualified structural ceramic specialists.
- Electronics:Japanese precision ceramics clusters supply lithography and deposition components to global semiconductor capital equipment makers. KYOCERA's vertically integrated alumina substrate production anchors domestic supply chain dominance.
- Medical Devices:FDA 510(k) pathways and ISO 13356 surgical implant standards govern bio-ceramic market access. German processors face REACH precursor restrictions while auditing yttria supply chains.
- Energy:Solid-state battery ceramic electrolytes and nuclear fuel cladding applications demand radiation-resistant microstructures. METI industrial technology grants support Japanese domestic silicon nitride development for next-generation energy systems.
Defense-linked aerospace contracts deliver longest duration; medical qualification barriers deliver deepest margins.
Manufacturing Process:
Capital intensity and geometric capability distinguish competitive positioning.
- Hot Pressing:Uniaxial pressure sintering achieves full density in silicon nitride turbine blades. Diamond grinding requirements for finishing add manufacturing overhead that constrains price competitiveness against superalloys.
- Slip Casting:Colloidal suspension forming enables complex hollow geometries in alumina insulators. Japanese electronics manufacturers specify slip-cast substrates for high-voltage applications.
- 3D Printing:Binder jetting and stereolithography of technical ceramics collapse prototyping-to-production timelines. Geometric complexity impossible with conventional pressing now reaches bio-implant and aerospace component qualification.
- Sintering:Conventional pressureless densification remains volume leader for standard alumina and zirconia grades. Furnace capacity constraints require capital deployment exceeding standard materials processing infrastructure.
Conventional sintering holds cost advantage; additive manufacturing captures complexity premium.
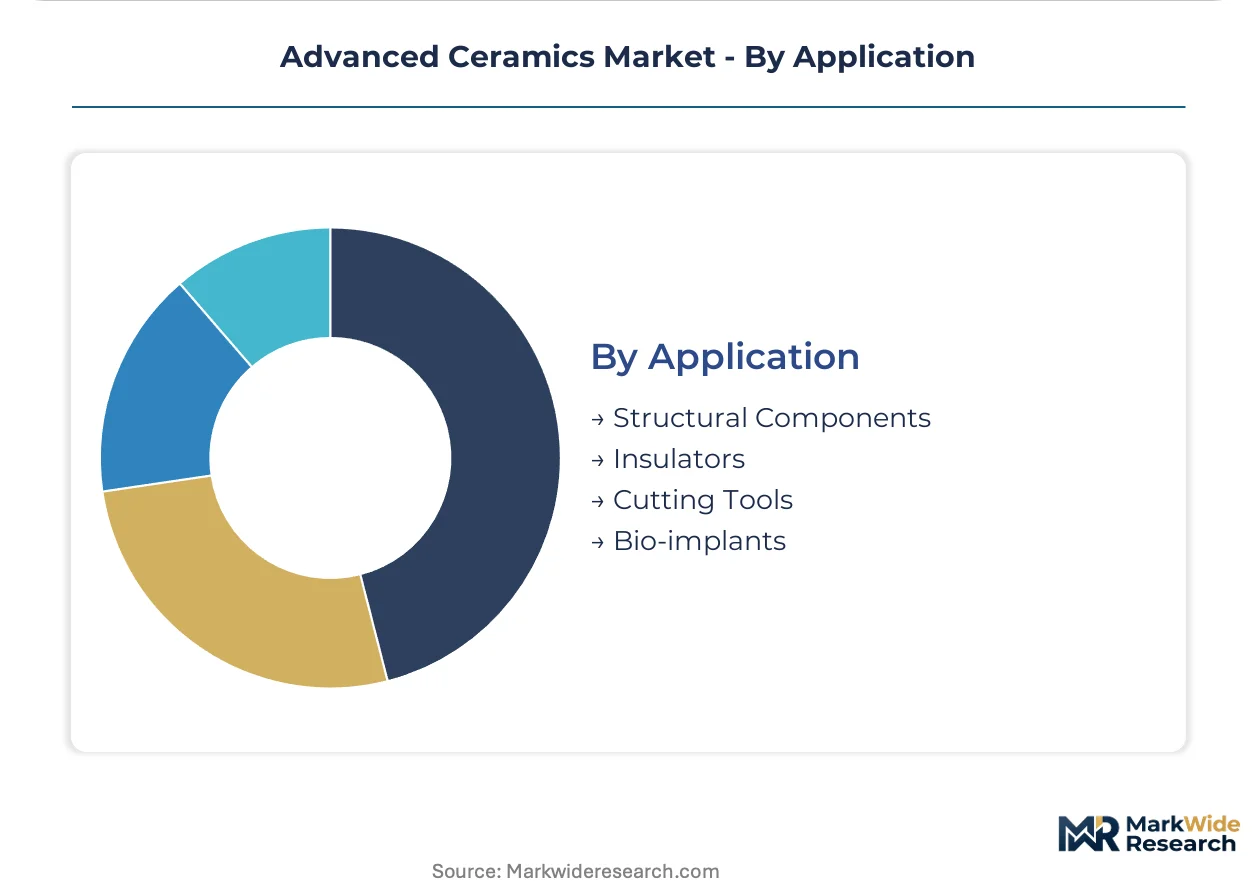
Application:
Performance requirements and replacement frequency set pricing architecture.
- Structural Components:Load-bearing ceramics in aerospace turbines and armor systems require flaw-free microstructures. EASA directives increasingly specify ceramic matrix composites for engine hot sections, locking in qualified suppliers.
- Insulators:High-voltage alumina substrates and spark plug bodies leverage mature oxide ceramic supply chains. Electronics miniaturization trends are compressing insulator dimensions while maintaining dielectric strength requirements.
- Cutting Tools:Silicon nitride and alumina-toughened zirconia inserts machine hardened steels at speeds exceeding carbide. Metalworking demand concentrates in German and Japanese precision manufacturing clusters.
- Bio-implants:Yttria-stabilized zirconia hip and dental components require ISO 13356 certification and FDA 510(k) clearance. Extended substance evaluation timelines under REACH force European manufacturers toward supply chain audits.
Structural aerospace contracts anchor long-term revenue; bio-implant certification barriers defend margin pools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
METI industrial technology grants and EASA airworthiness directives are redirecting advanced ceramics procurement toward certified suppliers in Germany and Japan. National subsidy programs and emissions regulations now determine where silicon nitride turbine components and medical-grade zirconia concentrate.
Germany
EASA engine hot-section specifications drive demand for ceramic matrix composites in aerospace manufacturing. REACH authorization requirements restrict hazardous precursor chemicals for zirconia processing. The Baden-Württemberg precision ceramics cluster anchors European medical device supply chains through specialized bio-implant fabrication.
Japan
Domestic silicon nitride production receives METI grants for next-generation turbine applications. PMDA and JIS standards govern surgical implant-grade material qualification. The Nagoya industrial ceramics corridor supplies precision components to semiconductor capital equipment makers serving global chip fabrication expansion.
United States
FDA 510(k) pathways govern bio-implant market access for surgical-grade zirconia hip and dental components. EPA and OSHA regulations shape manufacturing facility compliance for high-temperature sintering operations. California and Texas host aerospace defense contractors qualifying structural ceramics for turbine applications.
China
MIIT promotes domestic silicon carbide substrate capacity for electric vehicle power electronics. GB standards and dual carbon goals redirect manufacturing toward energy-efficient densification processes. The Yangtze River Delta concentrates alumina substrate production for consumer electronics supply chains.
South Korea
MFDS regulates medical ceramic implant approvals while national semiconductor subsidies expand precision ceramics demand. The Seoul Capital Area anchors electronics substrate manufacturing serving display and memory chip fabrication. Busan-Ulsan industrial complexes process technical ceramics for automotive and marine applications.
Advanced Ceramics Market Vendor Landscape
Player mix skews toward vertically integrated industrial conglomerates with captive raw material processing and specialized ceramic component specialists serving single end-use verticals. Market structure concentrates around three archetypes: diversified materials conglomerates with multi-continent manufacturing footprints, regional precision ceramics specialists with deep customer relationships in electronics or medical devices, and captive aerospace suppliers integrated into engine OEM supply chains. Competitive moves center on qualification-driven customer lock-in through ISO 13356 and EASA certification, plus capacity expansion in silicon carbide substrate fabrication.
Among Japan-based fabricators, KYOCERA Corporation and MARUWA Co., Ltd. exemplify the vertically integrated electronics substrate archetype, while CeramTec GmbH represents European medical device specialization. Morgan Advanced Materials occupies a position bridging aerospace structural ceramics across multiple continents. These three anchors illustrate how geographic clustering around regulatory hubs and end-use demand centers determines competitive positioning.
| Leading Market Players |
|---|
| KYOCERA Corporation |
| CeramTec GmbH |
| CoorsTek Inc. |
| Morgan Advanced Materials |
| Saint-Gobain |
| 3M |
| AGC Inc. |
| MARUWA Co., Ltd. |
| Murata Manufacturing Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts with aerospace engine OEMs lock in silicon nitride turbine component supply while anchoring price visibility through raw material indexation clauses tied to yttria and rare-earth stabilizer markets.
Pricing Analysis
Cost-plus contracts with yttria price indexation dominate structural ceramic procurement for aerospace and medical implant tiers. Price differentiation rests on ISO 13356 certification grade and EASA airworthiness qualification status, with certified bio-implant zirconia commanding substantial premiums over industrial grades. Cost compression in standard alumina substrates is intensifying because Japanese electronics manufacturers are consolidating vendor lists around vertically integrated suppliers. Medical device OEMs exhibit lowest price sensitivity due to decade-long qualification lock-in, while automotive power electronics buyers drive hardest bargaining on silicon carbide substrate volumes.
Supply Chain Analysis
Inbound logistics costs through Shanghai-Ningbo and Busan container corridors expose zirconia precursor importers to port congestion volatility during peak semiconductor equipment shipping seasons. Raw material supply concentrates in Chinese yttria processing facilities, Japanese silicon nitride powder synthesis operations, and German precision finishing equipment manufacturing. The supply chain draws from rare-earth stabilizer feedstock, high-purity oxide powders, and diamond abrasive consumables. Single-source vulnerability in yttria supply chains threatens European medical implant producers under REACH substance evaluation timelines. Distribution runs through qualified supplier networks with direct OEM contracting displacing traditional distributor channels in aerospace and medical segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified sintering furnace capacity and EASA-certified machining capabilities represent the scarcest assets in this market, with qualification timelines creating defensive moats that outlast capital deployment cycles.
For Market Incumbents: Consolidate around captive silicon nitride powder production and in-house diamond grinding capacity to defend margin pools against emerging Asian substrate specialists. Lock in multi-year aerospace offtake agreements before EASA engine specifications finalize supplier lists. Prioritize METI grant-aligned capacity expansion in Japanese industrial ceramics corridors. For New Entrants and Emerging Players: Differentiate on additive manufacturing qualification for geometrically complex bio-implant geometries that bypass traditional pressing equipment barriers. Target FDA 510(k) pathway optimization for surgical-grade zirconia hip components where incumbent qualification backlogs create white space. Pursue direct hospital system partnerships rather than distributor-dependent go-to-market models. For Investors and Strategic Acquirers: The market sits at a certification-intensification phase that favors vertically integrated specialists with captive raw material processing and established OEM relationships. Five-to-ten year viability favors acquirees with ISO 13356 and EASA dual qualifications rather than commodity alumina substrate producers. Watch silicon carbide substrate qualification velocity at automotive Tier-1 suppliers as the inflection signal for power electronics ceramic demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Yttria Supply | Secures rare-earth stabilizer access for European medical implant manufacturers facing REACH restrictions. |
| EASA Airworthiness Qualification | Locks in multi-year turbine component contracts with German and Japanese engine OEMs. |
| Silicon Carbide Substrate Scale-Up | Captures automotive inverter demand as electric vehicle manufacturers bypass alumina supply chains. |
| Additive Manufacturing Certification | Enables geometric complexity premiums in bio-implant and aerospace component markets. |
| Direct OEM Contracting Transition | Displaces distributor margins in aerospace and medical device procurement channels. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with ceramic component procurement managers, sintering furnace operations directors, and biomedical engineering leads at hospital purchasing committees; and secondary validation through EASA airworthiness directives, FDA 510(k) clearance databases, METI industrial technology grant disclosures, and REACH authorization timelines. Primary fieldwork centered on Japanese industrial ceramics clusters in Nagoya, German precision ceramics corridors in Baden-Württemberg, and US aerospace defense contractors in California and Texas. Bottom-up demand modeling triangulated against top-down market sizing across material chemistry, end-use vertical, and manufacturing process dimensions.
Across the projection horizon, the analytical framework modeled volume and value trajectories through segmentation by material type, end-use industry, manufacturing process, and application, with additional granularity on certification status tiers. CAGRs emerged from regression analysis of historical qualification cycle compression, subsidy program uptake rates, and substitution elasticity between ceramic and superalloy turbine components. Industry-specific forecast inputs included silicon carbide substrate adoption curves in automotive power electronics and ISO 13356 certification pipeline velocity for surgical implant-grade zirconia.
The analysis sits within stated boundaries; outcomes outside sustained EASA emissions regulation tightening, METI grant continuity, and REACH authorization timeline stability would require recalibration. Forecasts reflect documented assumptions on qualification cycle durations, rare-earth supply chain configurations, and electric vehicle power electronics architecture transitions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Global Ceramic Balls Market
Ceramics
Titanates Market
Ceramics
Ceramic Injection Molding Market
Ceramics
Europe Ceramic Tiles Market
Ceramics
Ceramics Market
Ceramics
Barium Carbonate Powder Market
Ceramics
Calcium Silicate Boards Market
Ceramics
Advanced Structural Ceramics Market
Ceramics
China Ceramic Tiles Market
Ceramics
Potassium Feldspar Market
Ceramics
Hot-Pressed Aluminum Titanate Ceramics Market
Ceramics
Boiler Refractory Material Market
Ceramics
China Ceramic Market
Ceramics
Ceramic Sanitary Ware Market
Ceramics
North America Barium Carbonate Market
Ceramics
Dielectric Ceramics Market