
 Dialysis Equipment Market | 2026-2036
Dialysis Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Dialysis Equipment Market Intelligence
Synthetic polysulfone membranes are replacing older cellulose-based materials in dialyzers, as the industry is pivoting toward improved biocompatibility and clearance efficiency. Fresenius Medical Care leverages its extensive network of dialysis centers to drive equipment sales. Baxter International specializes in peritoneal dialysis systems for the home care setting. Nipro Corporation differentiates through its manufacturing scale in essential disposables like dialyzers and blood tubing sets.
Dialysis equipment comprises systems and consumables designed to remove uremic toxins and excess fluid from the blood. These devices, such as hemodialysis machines, operate by circulating blood through a filter, or dialyzer, with specific membrane surface areas and ultrafiltration coefficients. Hemodialysis machines and dialyzers for use in dedicated dialysis centers form the core of the market. However, the fastest expansion is observed in the home care providers segment, which relies on peritoneal dialysis systems and emerging portable technologies.
Regulatory frameworks, including pre-market approval from the US FDA and CE marking under Europe's Medical Device Regulation, govern market access. China's NMPA similarly enforces strict quality and safety standards for all dialysis equipment. Manufacturers must now navigate evolving reimbursement models that incentivize home-based therapies and outcome-based care over traditional in-center treatment volumes.
Market Dynamics
The decentralization of care delivery is the central force shaping the dialysis equipment market. This structural shift, driven by patient preference and enabled by portable technology, is moving treatment from dedicated centers to home-based settings, reconfiguring supply chains and service models.
Growth Catalysts
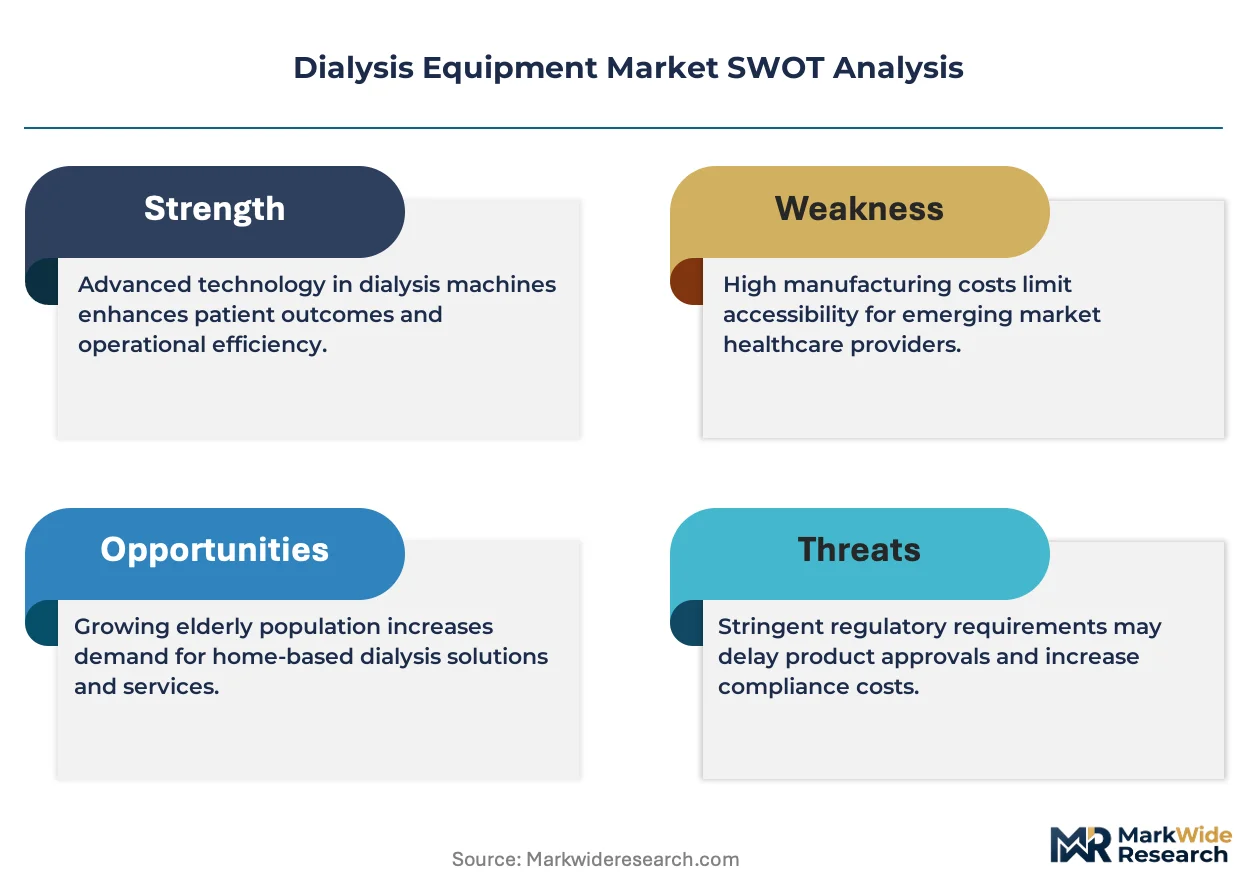
- Reimbursement Incentives:Evolving payment models in the United States that favor home-based therapies are creating a direct financial incentive for providers to adopt peritoneal dialysis and portable hemodialysis systems, accelerating the shift away from in-center treatments.
- Advanced Materials:The adoption of synthetic polysulfone and other advanced polymer membranes in dialyzers improves biocompatibility and clearance efficiency, driving replacement cycles and offering superior clinical outcomes compared to older cellulose-based materials.
- Demographic Pressures:Countries with significant aging populations and high chronic kidney disease prevalence, such as Japan and Germany, exhibit concentrated and sustained demand for dialysis equipment, anchoring the market's core volume.
Market Restraints
- High Capital Costs:The establishment of new dialysis centers requires substantial capital investment in hemodialysis machines, water treatment systems, and infrastructure, acting as a barrier to entry for new providers and limiting expansion in capital-constrained regions.
- Stringent Regulatory Hurdles:Gaining market access requires navigating complex and lengthy approval processes across multiple jurisdictions, including pre-market approval from the US FDA, CE marking under Europe's MDR, and NMPA standards in China.
- Clinical Limitations of Home Therapy:Peritoneal dialysis is not clinically suitable for all patient profiles, and complications such as peritonitis can limit its adoption, restraining the complete transition to home-based care for the entire end-stage renal disease population.
Strategic Opportunities
- Underpenetrated Markets:Developing economies like India and Brazil, with rising healthcare expenditures and large, underserved patient populations, represent significant expansion opportunities for both hemodialysis and peritoneal dialysis equipment manufacturers.
- Technology Convergence:Integrating wearable biosensors with portable dialysis machines creates an opportunity to develop closed-loop systems that offer real-time monitoring and automated therapy adjustments, enhancing safety and efficacy for home patients.
- Sorptive and Regenerative Dialysis:The development of sorbent-based technologies that regenerate small volumes of dialysate opens avenues for truly wearable or implantable artificial kidneys, representing a transformative long-term opportunity beyond current device formats.
Industry Challenges
- Specialized Workforce Shortages:A global shortage of trained nephrologists, dialysis nurses, and biomedical technicians creates a bottleneck for both expanding in-center capacity and providing the necessary clinical support for a growing home dialysis patient base.
- Consumables Supply Chain Complexity:The shift to home care requires a robust, direct-to-patient logistics network capable of reliably delivering bulky and sterile consumables like dialysate bags and tubing sets, posing a significant operational challenge.
- Interoperability with Health IT:Ensuring seamless integration of new home dialysis devices with diverse hospital Electronic Health Record systems is a critical challenge for data management, remote patient monitoring, and clinical workflow coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dialysis Equipment Market |
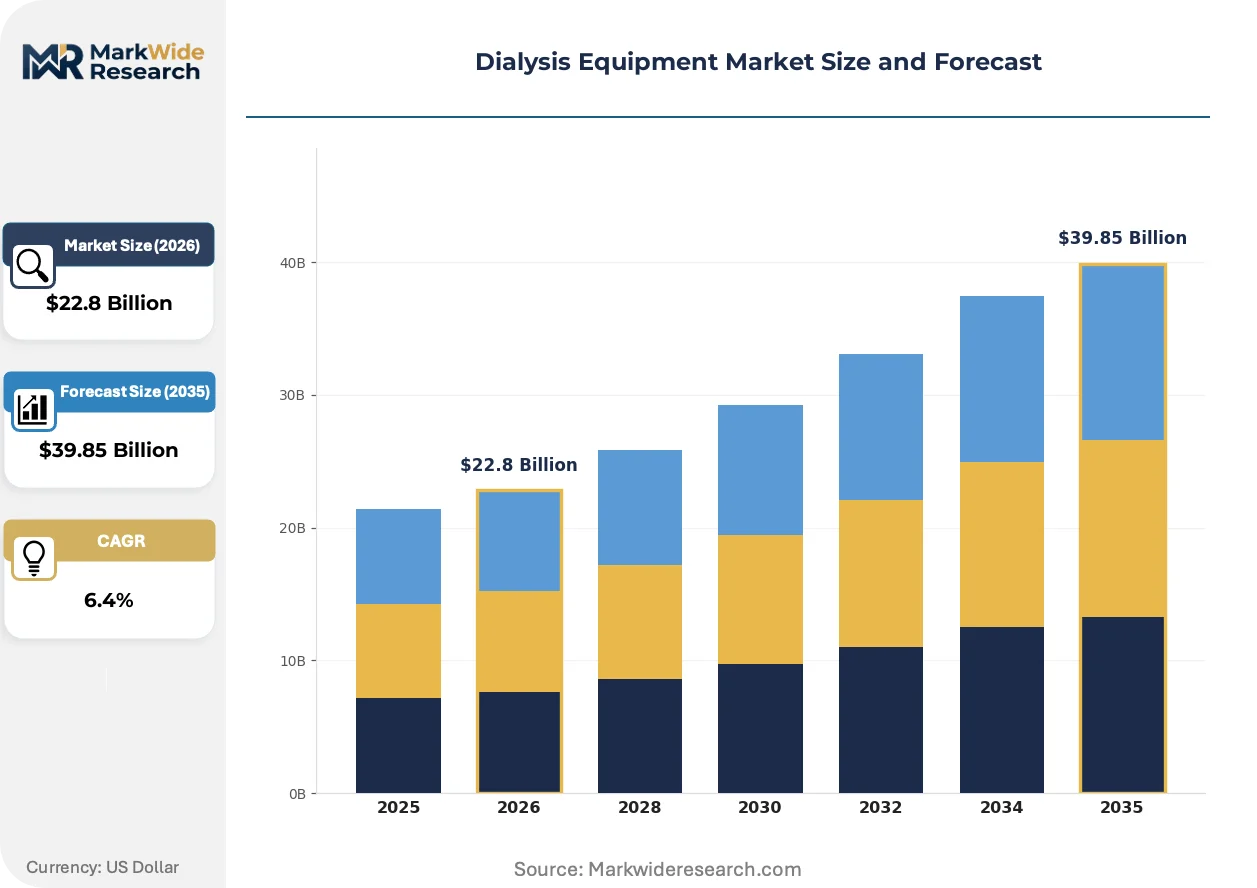
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $39.85 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hemodialysis Machines, Peritoneal Dialysis Systems, Dialyzers, Blood Tubing Sets, Dialysis Concentrates Technology: High-Flux, Low-Flux, Portable, Wearable, Continuous Renal Replacement Therapy Application: Chronic Kidney Disease, Acute Kidney Injury, End-Stage Renal Disease, Pediatric Dialysis End User: Dialysis Centers, Nephrology Clinics, Home Care Providers, Specialty Hospitals |
| Companies Covered | Fresenius Medical Care, Baxter International, Nipro Corporation, B. Braun Melsungen, Nikkiso Co., Ltd., Asahi Kasei Corporation, DaVita Inc., Medtronic plc, Toray Medical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dialysis Equipment Market Strategic Shifts & Innovations
The market's evolution is defined by a pivot from centralized, high-volume treatment models. This change favors patient-centric technologies that support remote care delivery and data-driven personalization, altering the value proposition for equipment manufacturers.
Smart dialyzers with embedded sensors provide real-time data on solute clearance and membrane performance. Home care providers and advanced dialysis centers adopt these to enhance treatment efficacy. This intelligent component technology is converging with telehealth platforms, enabling remote nephrologist intervention and personalized therapy adjustments.
Europe's Medical Device Regulation (MDR) requires more extensive clinical evidence and rigorous post-market surveillance. This regulatory shift extends timelines and increases costs for achieving and maintaining CE marking for dialysis equipment. The consumables segment is heavily impacted, forcing recertification of entire dialyzer portfolios, including both legacy and modern synthetic models.
A shift from fee-for-service purchasing to value-based procurement is accelerating among large dialysis organizations. These models prioritize total cost of ownership and patient outcomes over upfront machine costs, disrupting traditional sales cycles. This trend is most prominent in the United States, driven by reimbursement reforms linking payments to quality metrics.
Dialysis Equipment Market Segmentation
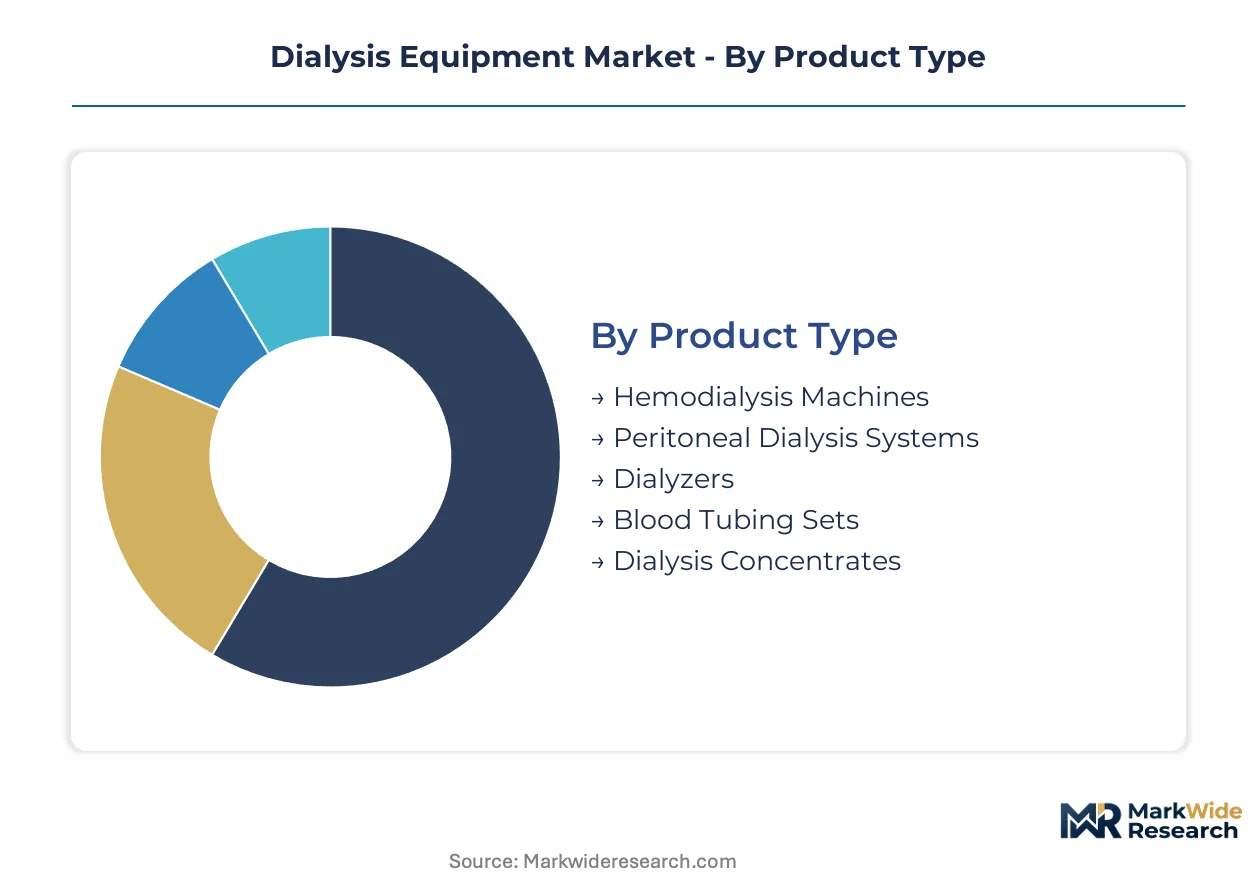
The dialysis equipment market segmentation provides a granular view of product types, technologies, applications, and end-user environments. Understanding these distinct segments helps manufacturers align product development with evolving clinical needs and shifts in care delivery models. This detailed breakdown highlights areas of concentrated demand and emerging growth trajectories.
Product Type:
The technical specifications of dialysis equipment differentiate product types based on their operational mechanism and component roles.
- Hemodialysis Machines:These complex systems circulate a patient's blood through an external dialyzer to remove waste products and excess fluid. Demand remains high in established dialysis centers, driven by a large patient volume and the need for precise fluid and electrolyte management.
- Peritoneal Dialysis Systems:Facilitate home-based therapy by utilizing the patient's peritoneal membrane as a natural filter for waste removal. These systems are gaining traction due to patient preference for remote treatment and evolving reimbursement models that incentivize home care.
- Dialyzers:Contain semi-permeable membranes, increasingly made from synthetic polysulfone, which are crucial for efficient toxin and fluid removal from the blood.
- Blood Tubing Sets:Sterile, disposable conduits connect the patient's vascular access to the dialyzer and the hemodialysis machine during treatment.
- Dialysis Concentrates:These solutions contain electrolytes and buffers, mixed with purified water to create the dialysate used in both hemodialysis and peritoneal dialysis.
Mature deployment sits with Hemodialysis Machines. Newer deployment is concentrated in Peritoneal Dialysis Systems.
Technology:
Market differentiation by technology reflects the specific clinical needs and treatment settings where the devices are employed.
- Portable:These compact, lighter dialysis systems are designed for easier transport and use outside traditional clinical settings. Patient demand for remote care and the ability to travel drive adoption of these innovative systems.
- High-Flux:Dialyzers featuring larger pore sizes enable more efficient removal of middle-molecule uremic toxins from the blood. These are widely used in standard hemodialysis for improved patient outcomes.
- Low-Flux:Older generation dialyzers with smaller pore sizes primarily remove smaller solutes and excess fluid, still used in some clinical contexts.
- Wearable:Emerging, ultra-compact dialysis devices designed for continuous, ambulatory use, still largely in developmental stages for future applications.
- Continuous Renal Replacement Therapy:Specialized, slow-rate dialysis used in critical care settings for hemodynamically unstable patients with acute kidney injury.
Portable technologies are gaining share fastest, while High-Flux systems maintain a strong established base.
Application:
Segmentation by application delineates the specific patient populations and disease states addressed by dialysis interventions.
- Chronic Kidney Disease:This segment represents the largest patient cohort requiring long-term dialysis to manage progressive kidney function decline. High prevalence in aging populations anchors sustained demand for equipment.
- End-Stage Renal Disease:The terminal stage of kidney failure, necessitating permanent renal replacement therapy, either dialysis or transplantation. This segment drives core market volumes for both hemodialysis and peritoneal dialysis.
- Acute Kidney Injury:Characterized by a sudden loss of kidney function, often requiring temporary dialysis support in critical care settings.
- Pediatric Dialysis:Specialized equipment and treatment protocols adapted for younger patients, addressing unique physiological and psychological needs.
The largest volume of procedures targets Chronic Kidney Disease, while Acute Kidney Injury requires specialized, short-term interventions.
End User:
The end-user landscape reflects the diverse settings where dialysis services are delivered, influencing equipment design and distribution.
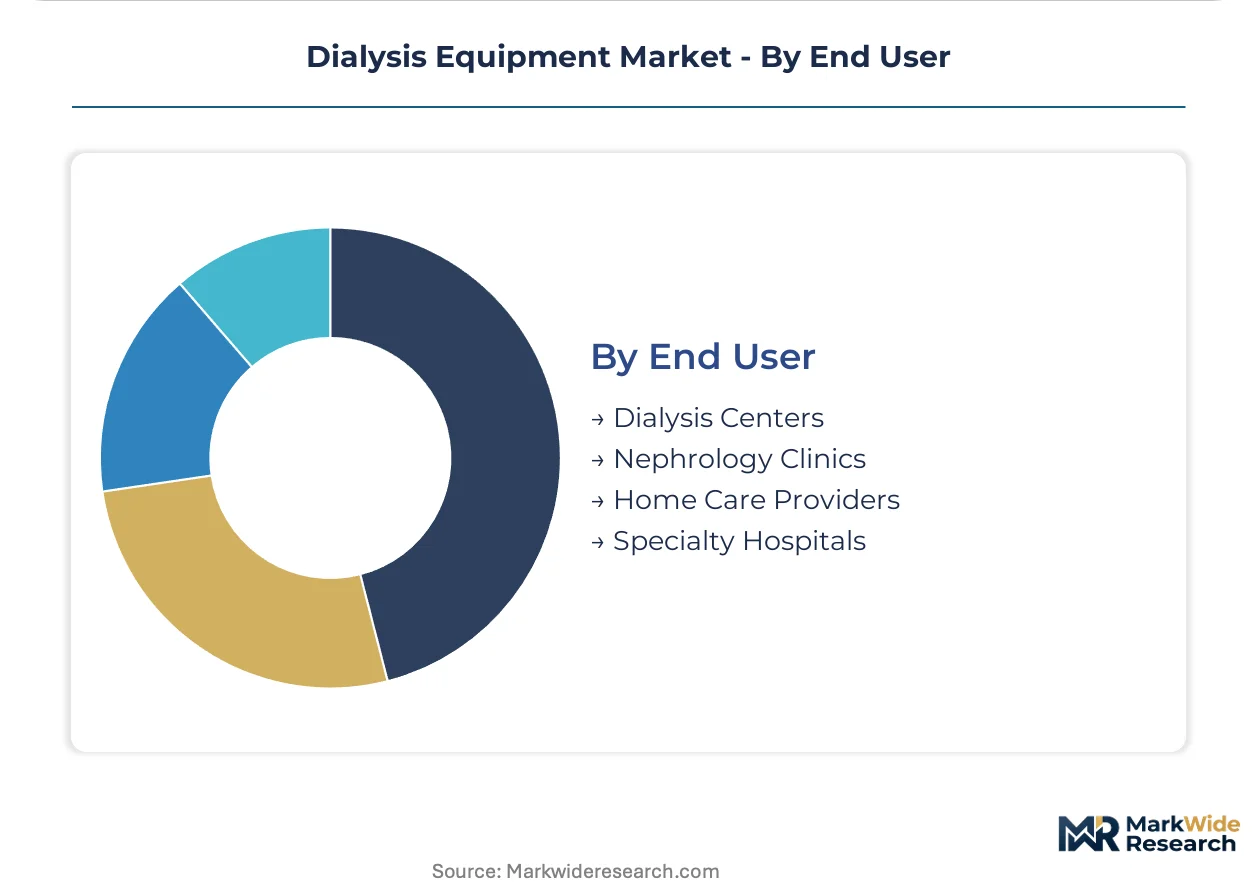
- Home Care Providers:This segment encompasses patients receiving dialysis in their residences, supported by remote monitoring and logistical supply chains. Patient preference for remote treatment and reimbursement incentives are accelerating growth here.
- Dialysis Centers:Dedicated facilities offering in-center hemodialysis treatments, often with extensive infrastructure for water purification and patient supervision. These centers form the traditional backbone of dialysis care delivery.
- Nephrology Clinics:Outpatient facilities providing diagnostic, therapeutic, and follow-up care for kidney patients, sometimes offering limited in-office dialysis.
- Specialty Hospitals:Institutions with specialized departments that manage complex kidney conditions, including critical care dialysis and pre/post-transplant management.
Traditional care delivery is centered in Dialysis Centers, with significant expansion observed in Home Care Providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Advanced medical technology hubs, particularly in countries with robust healthcare infrastructure, drive significant innovation and demand for dialysis equipment. These regions often benefit from concentrated R&D efforts and specialized manufacturing capabilities. This focus ensures continuous advancements in patient care and device efficacy.
United States
United States demand for dialysis equipment is shaped by evolving reimbursement models that prioritize home-based care. The US FDA's stringent pre-market approval process ensures device safety and efficacy. In Boston's medical device cluster, significant research focuses on developing next-generation portable and wearable dialysis technologies.
Germany
Germany exhibits sustained demand for dialysis equipment due to its significant elderly population and high chronic kidney disease rates. CE marking under Europe's Medical Device Regulation (MDR) ensures compliance for all devices. In Munich, specialized manufacturers focus on high-precision hemodialysis machines and advanced dialyzer membranes.
Japan
Japan's rapidly aging demographic profile creates a substantial patient base for long-term dialysis equipment. The PMDA enforces strict quality and safety standards for all medical devices entering the market. In Tokyo, advanced medical equipment companies actively develop innovative dialyzers and compact home dialysis systems.
China
China's expanding healthcare infrastructure and large patient population drive significant demand for dialysis equipment. The NMPA enforces strict quality and safety standards for all medical devices, including dialysis systems. Shanghai and Beijing serve as key centers for domestic medical device manufacturing and nephrology R&D.
India
India presents significant expansion opportunities due to its large, underserved patient population and rising healthcare expenditures. The CDSCO regulates medical devices, ensuring product quality and market access for dialysis equipment. Bengaluru and Hyderabad are emerging hubs for medical technology development and manufacturing.
Dialysis Equipment Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments within the dialysis equipment market. The landscape exhibits a tiered structure, with established global players dominating core hemodialysis systems and disposables. Smaller, agile firms often focus on niche segments like portable technologies or advanced membrane materials. Competitive moves frequently involve strategic partnerships to expand geographic reach and portfolio diversification into advanced home care solutions, alongside targeted M&A activities.
Within the established global player archetype, Fresenius Medical Care and Baxter International represent significant market presence. Fresenius Medical Care, a German-based entity, leverages its extensive network of dialysis centers, anchoring a traditional care delivery model. Baxter International, an Inc.-suffixed company, occupies a strong position in peritoneal dialysis systems, particularly for the home care setting. Nipro Corporation, a Co., Ltd.-suffixed firm, differentiates through its manufacturing scale in essential disposables like dialyzers and blood tubing sets, serving a broad customer base globally. These companies collectively influence innovation and supply chain dynamics.
| Leading Market Players |
|---|
| Fresenius Medical Care |
| Baxter International |
| Nipro Corporation |
| B. Braun Melsungen |
| Nikkiso Co., Ltd. |
| Asahi Kasei Corporation |
| DaVita Inc. |
| Medtronic plc |
| Toray Medical Co., Ltd. |
Cost & Logistics Intelligence
Evolving reimbursement models in the United States, incentivizing home-based care, are forcing equipment manufacturers to reconfigure supply chains and adjust pricing strategies. This structural shift favors direct-to-patient logistics and value-based procurement.
Pricing Analysis
Lead-time-driven pricing structures often command a premium for rapid delivery of critical consumables, while spot inventory may see discounts for standard items. Contract-based long-term offtake agreements dominate the core hemodialysis equipment segment. Price differentiation stems from certification levels, particularly US FDA approval, and after-sales service bundles. Pricing softness affects older generation low-flux dialyzers due to advanced material adoption, with home care providers being most price-sensitive regarding system costs.
Supply Chain Analysis
Dual-sourcing requirements for critical components are increasingly mandated by large dialysis organizations to mitigate supply disruptions. Geographic supply concentration for essential disposables centers on China, Japan, and Germany. The supply chain relies on specialized polymers for advanced membranes and sterile packaging materials. Logistics chokepoints, especially for bulky dialysate bags, present a structural risk. Distribution runs through direct-to-clinic models and specialized home delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dialysis equipment market is ripe for consolidation, as evolving reimbursement models and stringent regulatory hurdles force smaller, less capitalized players out. This structural shift concentrates market power among established global entities.
For Market Incumbents: Hedge against the decentralization of care by investing in portable and wearable dialysis system R&D. Diversify distribution channels to support direct-to-patient logistics for home care consumables, countering the margin pressure from value-based procurement. Expand manufacturing capabilities for synthetic polysulfone membranes to maintain a technological edge against emerging material science firms. Acquire smaller technology firms specializing in remote monitoring and telehealth integration.
For New Entrants and Emerging Players: Launch via strategic partnerships with home care providers to penetrate the rapidly expanding remote treatment segment. Target underpenetrated developing economies like India and Brazil with cost-effective peritoneal dialysis systems. Focus on niche technology convergence areas, such as integrating AI with biosensors for automated therapy adjustments. A go-to-market angle emphasizing ease of use and patient quality of life will resonate with end-users.
For Investors and Strategic Acquirers: The window for entry favors strategic acquirers seeking long-term growth in the home-based care and advanced materials segments. Identify mid-sized technology firms with strong intellectual property in sorbent-based dialysis or integrated biosensor platforms. These targets offer significant potential over a five-to-ten year horizon as the market shifts. A signal to watch is the widespread regulatory approval of novel wearable dialysis devices.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Home Dialysis Portfolio | Captures market share in the fastest-growing segment driven by patient preference for remote treatment. |
| Invest in Advanced Membrane R&D | Improves clearance efficiency and biocompatibility, offering superior clinical outcomes for chronic kidney disease patients. |
| Develop Integrated Telehealth Platforms | Enables remote nephrologist intervention and personalized therapy adjustments, enhancing safety for home patients. |
| Secure Supply Chains for Disposables | Mitigates risks from logistics chokepoints and ensures reliable delivery of sterile consumables to home care providers. |
| Pursue M&A in Portable Technologies | Accelerates entry into the emerging portable and wearable dialysis market, addressing demand for remote treatment. |
Research Approach
Independent corroboration across industry reports, company financial statements, and regulatory filings underwrites the qualitative findings. Primary interviews with nephrologists, hospital purchasing committees, and biomedical engineers provided direct market insights. Secondary data from US FDA approvals, CE marking databases, and customs trade statistics validated market sizing. This approach ensures robust bottom-up and top-down triangulation.
Rate-of-change decomposition analyzes historical growth drivers and projects future trends across the analysis window. Segmentation dimensions modeled include product type, technology, application, and end-user environment, alongside regional adoption patterns. CAGRs were derived by projecting volume and value growth based on patient population dynamics and technology penetration. Key inputs include chronic kidney disease prevalence rates and home care adoption incentives.
The model assumes a particular technology adoption path; alternative pathways for sorbent-based dialysis would alter the outlook. Forecasts reflect assumptions regarding reimbursement policy stability and material supply chain continuity. Deviation in regulatory approval timelines or patient preference shifts would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Clinical Microscopes Market
Medical Equipment
Medical Suction Units Market
Medical Equipment
Brazil Massage Equipment Market
Medical Equipment
MRI Transport Market
Medical Equipment
Global Cardiopulmonary Stress Testing Systems Market
Medical Equipment
Nuclear Medicine Equipment Market
Medical Equipment
Medical Vending Machines Market
Medical Equipment
Global Latex Medical Gloves Market
Medical Equipment
Embedded Disinfection Cabinet Market
Medical Equipment
Urodynamic Equipment Market
Medical Equipment
Global Intraoperative Radiation Therapy Market
Medical Equipment
Medical Physics Market
Medical Equipment
Medical Computer Carts Market
Medical Equipment
Global Medical Refrigerators Market
Medical Equipment
Autopsy Saw Market
Medical Equipment
New-Born Screening Equipment Market