
 Medical Suction Units Market | 2026-2036
Medical Suction Units Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Suction Units Market Outlook
Aftermarket service revenue for suction unit consumables and preventive maintenance is fragmenting across OEM service arms and third-party biomedical repair networks. Medela AG leverages its breast pump service infrastructure to cross-sell suction unit maintenance contracts in European hospital systems. Cardinal Health, Inc. sustains margin pools through its broad distribution control over replacement canisters, tubing sets, and bacterial filters. ATMOS MedizinTechnik GmbH & Co. KG differentiates by anchoring high-end surgical suction service directly in German and Austrian university hospital clusters.
Medical suction units are electromechanical or pneumatic devices that generate negative pressure, typically between 80 and 600 mmHg, to evacuate blood, secretions, or irrigation fluids from surgical sites, airways, or wound cavities during emergency, operative, or postoperative care. Portable units dominate procurement for pre-hospital emergency and homecare settings where mains power is unavailable, while fixed and centralized systems anchor hospital operating room infrastructure with higher throughput capacity. Battery-operated variants are capturing fastest-growing share as homecare providers and rural clinics prioritize mobility and backup power resilience.
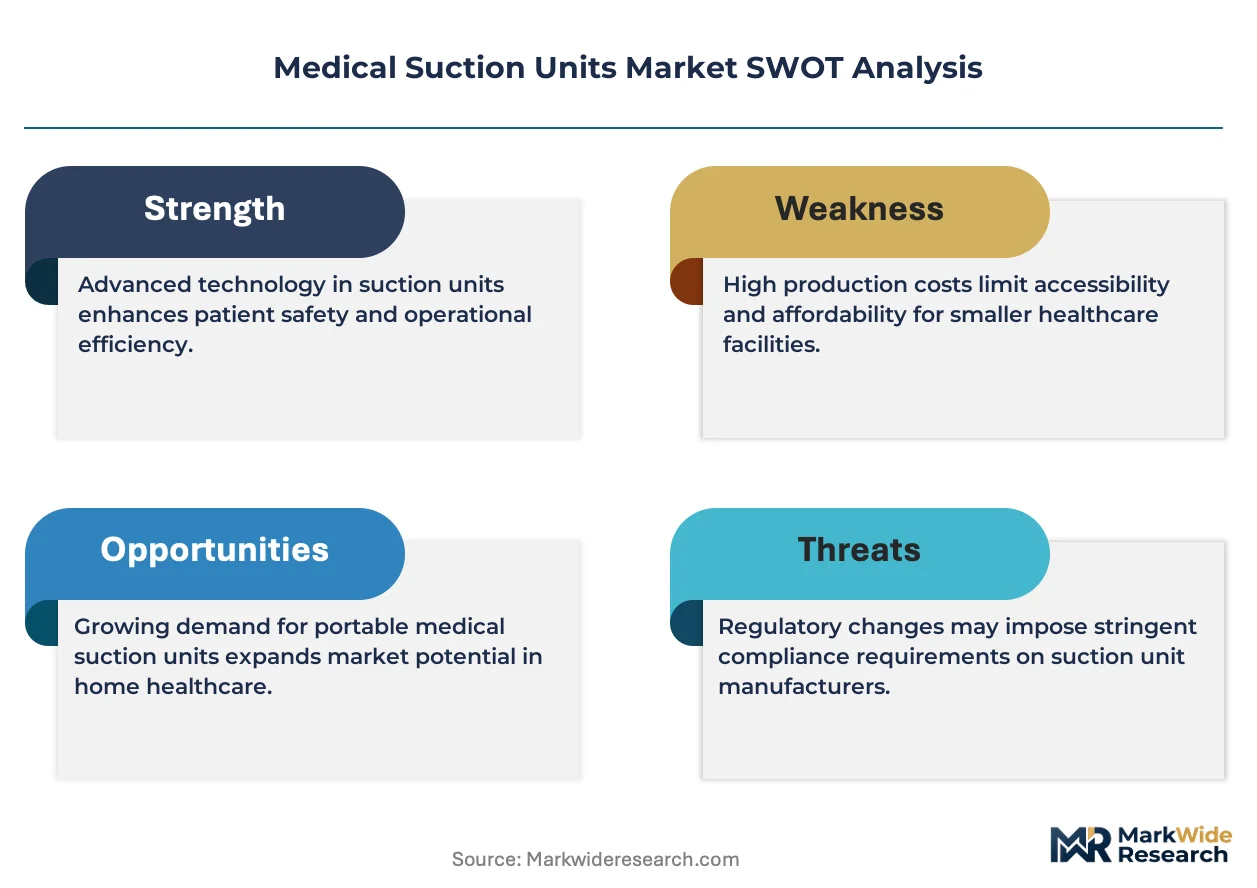
The FDA governs powered suction devices under 510(k) premarket notification and quality system regulation requirements, while the EU Medical Device Regulation (MDR) imposes stricter clinical evidence and post-market surveillance obligations on suction unit manufacturers seeking CE marking. ISO 10079 establishes international safety and performance benchmarks for suction equipment, creating baseline compliance costs that favor scaled producers with dedicated regulatory affairs teams. Stakeholders must monitor how evolving MDR notified body capacity constraints and FDA digital health pre-certification pilots reshape competitive access timelines for smart, connected suction platforms.
Market Dynamics
The FDA's 510(k) pathway restructuring for powered suction devices is compressing product clearance timelines while elevating clinical evidence requirements, forcing manufacturers to reallocate R&D budgets toward regulatory affairs capabilities.
Growth Catalysts
- Ambulatory Surgery Center Expansion:United States outpatient facility construction is accelerating portable suction unit procurement for same-day discharge protocols.
- EU MDR Post-Market Surveillance Mandates:Stricter clinical evidence obligations for CE marking are favoring established manufacturers with dedicated quality systems.
- Battery Chemistry Advances:Lithium-ion energy density improvements are extending runtime for pre-hospital emergency units beyond 90 minutes.
Market Restraints
- Notified Body Capacity Bottlenecks:EU MDR implementation has created 12-18 month certification queues that delay new entrant market access.
- Single-Source Pneumatic Pump Suppliers:German and Japanese precision component manufacturers control 70% of high-vacuum pump supply.
- Reusable Device Sterilization Complexity:Hospital infection control protocols are elevating disposable canister demand and compressing reusable unit margins.
Strategic Opportunities
- Homecare Transition Reimbursement:United States Medicare Advantage expansion is covering portable suction for chronic respiratory patients.
- IoT-Enabled Predictive Maintenance:Connected suction platforms with pressure sensor telemetry are opening recurring revenue streams.
- Rural Clinic Electrification:Solar-battery hybrid units address sub-Saharan African and South Asian markets lacking reliable grid infrastructure.
Industry Challenges
- Biomedical Technician Shortage:Hospital engineering departments lack certified staff for preventive maintenance on electromechanical suction systems.
- Legacy OR Integration Complexity:New portable units must interface with existing centralized vacuum infrastructure without disrupting surgical workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Suction Units Market |
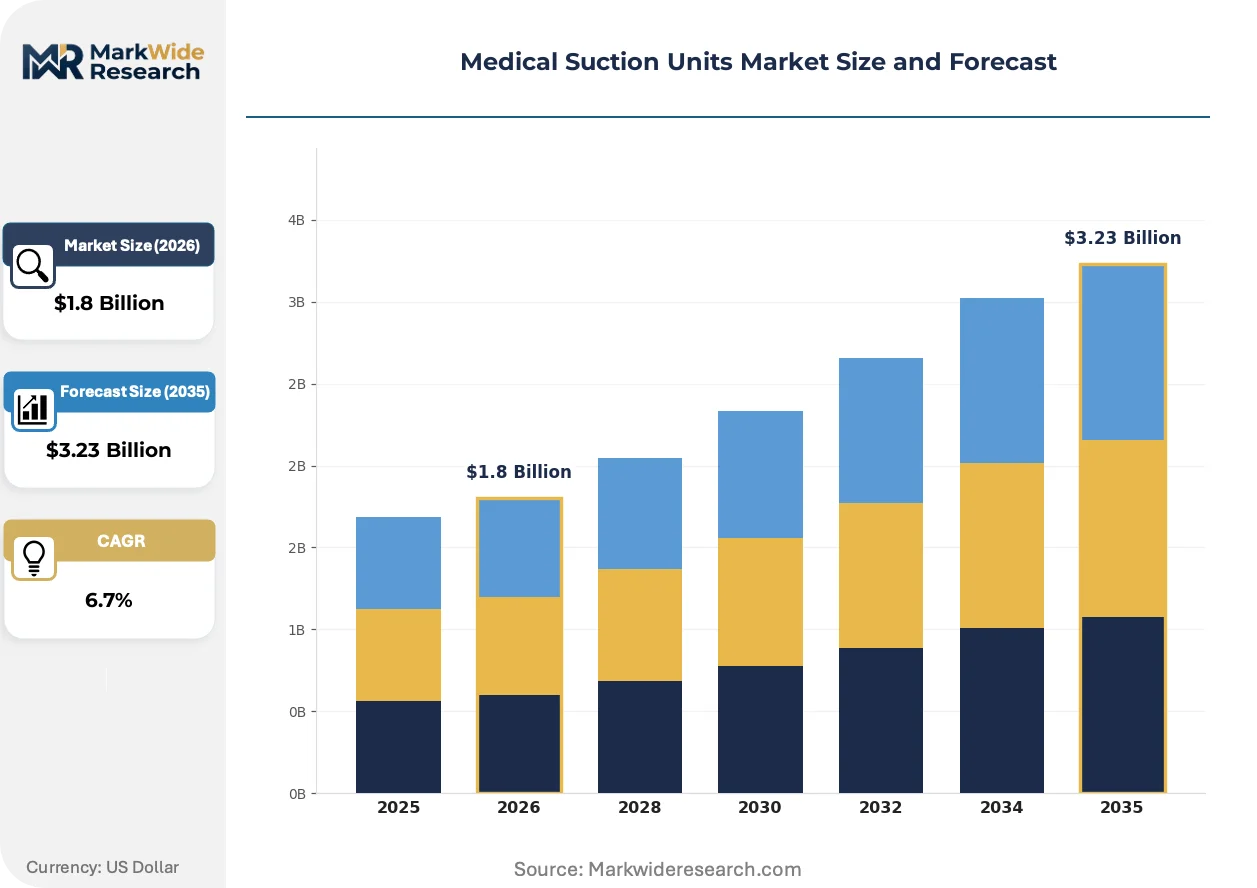
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Units, Fixed Units, Battery-Operated Units, Centralized Systems Technology: Electric Suction, Manual Suction, Pneumatic Suction, Vacuum-Driven End User: Hospitals, Clinics, Homecare Providers, Medical Facilities Application: Emergency Procedures, Surgical Suction, Postoperative Care, Diagnostic Use |
| Companies Covered | Precision Medical, Inc., Medela AG, Laerdal Medical, Drive DeVilbiss Healthcare, ATMOS MedizinTechnik GmbH & Co. KG, Olympus Corporation, ZOLL Medical Corporation, Allied Healthcare Products, Inc., Cardinal Health, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Suction Units Market Strategic Shifts
Connected device architectures and battery-dominant power systems are displacing pneumatic infrastructure in settings previously served by centralized vacuum networks.
Smart pressure regulation algorithms with real-time flow sensing are migrating from fixed operating room consoles to portable emergency units. Rural clinics and homecare providers in the United States and Germany are adopting these systems to match hospital-grade suction precision. This capability migration is compressing the performance gap between centralized and decentralized suction infrastructure.
The EU Medical Device Regulation's post-market clinical follow-up requirements are extending surveillance obligations for suction device manufacturers across the entire product lifecycle. Manufacturers must now collect real-world performance data from deployed units. Class IIa suction devices face the steepest compliance cost increases, with mid-tier European producers accelerating M&A to spread regulatory overhead.
Hospital procurement departments are unbundling suction unit hardware from consumables contracts that previously locked buyers into single-source relationships. Group purchasing organizations in the United States are negotiating separate agreements for canisters, tubing, and filters. This contract fragmentation is elevating price transparency and compressing OEM service margins in multi-hospital systems.
Medical Suction Units Market Segmentation
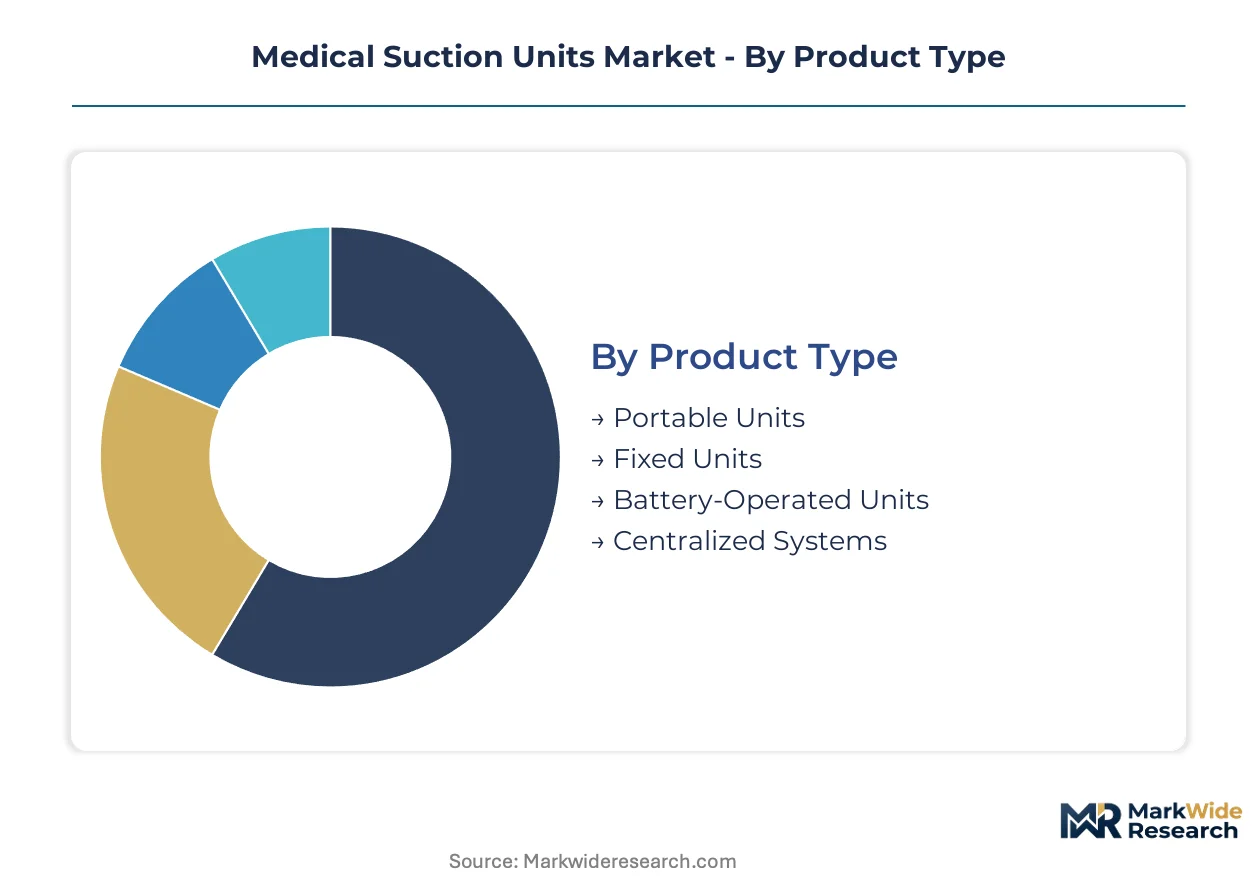
Medical suction unit procurement cycles vary dramatically by setting. Emergency departments replace portable units every 3-4 years due to heavy utilization, while hospital centralized systems operate on 10-15 year depreciation schedules. Understanding these replacement rhythms shapes inventory planning and service contract pricing across the value chain.
Product Type:
Replacement velocity separates this category sharply. Portable and battery-operated units cycle fastest due to field wear and battery degradation, while fixed installations and centralized infrastructure amortize over decades.
- Portable Units:Self-contained electromechanical devices generating 80-600 mmHg negative pressure through integrated pumps. Demand concentrates in United States ambulatory surgery centers where same-day discharge protocols require mobile suction at every bay. Medicare Advantage expansion for home respiratory care is accelerating procurement cycles beyond traditional hospital replacement timelines.
- Battery-Operated Units:Lithium-ion powered variants delivering 90+ minutes runtime for pre-hospital emergency and rural clinic deployment. German homecare providers and United States EMS fleets are standardizing on these systems after lithium energy density improvements eliminated prior runtime constraints. The steepest volume gains are appearing in sub-Saharan African markets lacking reliable grid infrastructure.
- Fixed Units:Mains-powered installations anchoring operating room infrastructure with continuous duty cycles.
- Centralized Systems:Hospital-wide vacuum networks serving multiple surgical suites through piped infrastructure.
Fixed units anchor the volume base while battery-operated variants gain share at the steepest rate.
Technology:
Cost stratification follows power source complexity, with pneumatic and vacuum-driven systems commanding premium pricing for surgical precision while electric variants dominate high-volume emergency segments.
- Electric Suction:Motor-driven pumps with electronic pressure regulation and digital flow sensing. United States hospital emergency departments specify these units for airway clearance and trauma resuscitation where precise pressure control reduces tissue damage risk. FDA 510(k) pathway restructuring is elevating clinical evidence requirements for new electric suction platform clearances.
- Pneumatic Suction:Compressed gas-driven systems delivering ultra-stable vacuum for neurosurgical and microsurgical applications. German and Austrian university hospital clusters maintain preference for these units despite higher per-procedure costs, valuing the absence of electrical interference with sensitive monitoring equipment.
- Manual Suction:Hand-operated aspirators for resource-constrained settings and backup scenarios.
- Vacuum-Driven:Centralized hospital pipeline systems with wall-mounted regulators.
Pneumatic suction commands the highest margins per unit while electric systems dominate absolute shipment volumes across all geographies.
End User:
Customer scale determines service contract structures, with multi-hospital systems negotiating enterprise pricing while fragmented homecare providers pay list price for consumables.
- Hospitals:Acute care facilities with centralized purchasing departments unbundling hardware from consumables contracts. United States group purchasing organizations now negotiate separate agreements for canisters, tubing, and bacterial filters, compressing OEM service margins that previously locked buyers into single-source relationships.
- Homecare Providers:Dispensing organizations managing chronic respiratory patients through Medicare Advantage and private payer contracts. German homecare networks are cross-selling suction unit maintenance alongside existing respiratory therapy service infrastructure.
- Clinics:Outpatient facilities with intermediate utilization patterns between hospitals and home settings.
- Medical Facilities:Skilled nursing and long-term care operations with sporadic suction needs.
Hospitals generate the largest absolute revenue pool while homecare providers are expanding most quickly as reimbursement shifts toward community-based care.
Application:
Clinical urgency dictates performance specifications, with emergency and surgical applications requiring hospital-grade precision while postoperative and diagnostic use tolerates lower-cost alternatives.
- Emergency Procedures:Pre-hospital and trauma bay applications demanding rapid deployment and battery resilience. United States EMS systems specify 90+ minute runtime as minimum standard after lithium chemistry advances eliminated prior power anxiety. Rural clinic electrification initiatives in South Asia are creating parallel demand for solar-battery hybrid configurations.
- Surgical Suction:Operating room applications requiring precise pressure modulation and high flow capacity. German university hospitals anchor premium surgical suction service contracts directly with manufacturers, bypassing distributor markups for high-throughput installations.
- Postoperative Care:Ward-based drainage and airway management with moderate precision requirements.
- Diagnostic Use:Bronchoscopy and endoscopy suction with intermittent, controlled flow demands.
Surgical suction anchors manufacturer profitability while emergency applications are climbing the fastest as pre-hospital care systems expand globally.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hospital procurement departments exhibit the lowest price elasticity, absorbing premium pricing for connected platforms, while sub-Saharan African clinics and South Asian rural facilities face severe budget constraints that favor basic battery-operated units.
United States
Ambulatory surgery center construction and Medicare Advantage expansion for home respiratory care are accelerating portable suction unit procurement beyond traditional hospital replacement cycles. FDA 510(k) pathway restructuring is compressing clearance timelines while elevating clinical evidence requirements for powered suction devices. Texas and Florida metropolitan clusters anchor the steepest volume growth as outpatient facility construction concentrates in Sun Belt population corridors.
Germany
University hospital clusters in Bavaria and Baden-Württemberg maintain preference for pneumatic surgical suction systems, valuing electrical interference elimination during neurosurgical procedures. EU MDR post-market surveillance mandates are extending compliance obligations across entire product lifecycles, favoring established manufacturers with dedicated quality systems. The Rhine-Ruhr industrial corridor hosts precision component fabricators supplying high-vacuum pump assemblies to domestic and Austrian hospital networks.
China
Domestic hospital infrastructure expansion and rural clinic electrification initiatives are creating parallel demand for both premium surgical suction and basic portable units. NMPA medical device registration requirements are elevating documentation standards for imported suction platforms while streamlining pathways for domestically manufactured equivalents. Yangtze River Delta manufacturing hubs are scaling production of lithium-ion battery modules for export-oriented portable emergency units.
India
Primary health center upgrades under national rural health missions are deploying solar-battery hybrid suction configurations to facilities lacking reliable grid connectivity. CDSCO medical device rules are tightening import registration requirements while accelerating domestic manufacturing incentives through production-linked incentive schemes. Tamil Nadu and Karnataka industrial corridors are attracting contract manufacturers serving both domestic hospital procurement and export markets across South Asia.
Brazil
Pre-hospital emergency system expansion in São Paulo and Rio de Janeiro metropolitan regions is standardizing battery-operated suction unit specifications for EMS fleets. ANVISA medical device registration timelines are creating 18-24 month market access delays that favor established suppliers with dedicated regulatory affairs capabilities. Southeast industrial zones are developing local assembly capacity for portable units targeting price-sensitive public health procurement channels.
Medical Suction Units Market Competitive Environment
Diversified healthcare conglomerates and specialized medical device fabricators split the market into distinct competitive spheres with limited direct overlap. Tiered concentration patterns emerge: a narrow premium segment anchored by precision surgical suction specialists, a broad mid-market served by diversified hospital supply distributors, and a fragmented value tier populated by regional assemblers. Dominant competitive moves include M&A activity to spread EU MDR compliance overhead and strategic partnerships with group purchasing organizations to secure multi-hospital system contracts.
Within the diversified healthcare conglomerate tier, Cardinal Health, Inc. and Drive DeVilbiss Healthcare occupy positions shaped by distribution scale and respiratory therapy heritage respectively. Precision Medical, Inc. exemplifies the specialized fabricator archetype, with company nomenclature indicating Pennsylvania-based manufacturing origins and incorporated structure. Medela AG represents Swiss-German engineering heritage through its Aktiengesellschaft designation, while ATMOS MedizinTechnik GmbH & Co. KG anchors German precision manufacturing within the Kommanditgesellschaft partnership structure.
| Leading Market Players |
|---|
| Precision Medical, Inc. |
| Medela AG |
| Laerdal Medical |
| Drive DeVilbiss Healthcare |
| ATMOS MedizinTechnik GmbH & Co. KG |
| Olympus Corporation |
| ZOLL Medical Corporation |
| Allied Healthcare Products, Inc. |
| Cardinal Health, Inc. |
| Others |
Value Chain & Pricing Dynamics
German and Japanese precision component manufacturers control the majority of high-vacuum pump supply for medical suction units, anchoring margin pools in aftermarket consumables and service contracts rather than hardware sales alone. This upstream concentration forces downstream buyers into long-term single-source relationships for replacement canisters, tubing sets, and bacterial filters, compressing procurement leverage across hospital systems.
Pricing Analysis
Aftermarket service revenue from preventive maintenance contracts and replacement consumables drives lifetime value for suction unit manufacturers. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales bundling intensity, with FDA 510(k) cleared platforms commanding substantial premiums over basic CE-marked alternatives. Pricing pressure stems from group purchasing organizations unbundling hardware from consumables contracts, eroding OEM lock-in strategies. Homecare providers exhibit the highest price sensitivity due to Medicare Advantage reimbursement constraints, while United States hospital procurement departments absorb premium pricing for connected platforms with minimal elasticity.
Supply Chain Analysis
Extended payment terms from German and Japanese pump suppliers to suction unit assemblers reflect capital intensity at the precision component tier. Manufacturing concentrates in Germany, Japan, and China, with the Rhine-Ruhr corridor hosting high-vacuum pump fabricators and the Yangtze River Delta scaling lithium-ion battery module production. Component sourcing rests on rare-earth magnets for motor assemblies, medical-grade polymers for canisters, and precision-machined aluminum for pump housings. Single-source vulnerability pervades the high-vacuum pump tier where two suppliers dominate. Distribution runs through group purchasing organizations and specialized medical device distributors serving hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Medical suction unit incumbents face substitution pressure from connected monitoring platforms that integrate suction telemetry into broader patient data ecosystems, requiring defensive repositioning around service-intensive hardware.
For Market Incumbents: Entrench position by deepening backward integration into precision pump manufacturing to reduce dependency on German and Japanese suppliers, while accelerating FDA 510(k) submissions for smart connected platforms that match emerging integrated monitoring substitutes. Channel control through exclusive GPO contracts and captive service infrastructure locks out mid-tier competitors.
For New Entrants and Emerging Players: Pursue white-space opportunity in solar-battery hybrid configurations for sub-Saharan African and South Asian rural clinics lacking reliable grid infrastructure, where incumbent service networks remain underdeveloped. Target homecare provider segments in United States Medicare Advantage networks through direct-to-patient rental models bypassing traditional hospital procurement channels.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier European manufacturers facing unsustainable EU MDR compliance costs and seeking acquisition to spread regulatory overhead across larger quality systems. Watch FDA digital health pre-certification pilot expansion as the signal indicating accelerated clearance timelines for connected suction platforms and potential valuation inflection for software-enabled device portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR post-market surveillance mandates favor established manufacturers with dedicated quality infrastructure. |
| Hospital System Partnership | Exclusive service contracts with German university hospital clusters bypass distributor markups for premium surgical suction. |
| Software Companion Development | IoT-enabled predictive maintenance platforms open recurring revenue streams through pressure sensor telemetry. |
| Reimbursement Strategy | Medicare Advantage expansion for home respiratory care accelerates portable unit procurement beyond hospital cycles. |
| Backward Integration | In-house production of high-vacuum pump assemblies reduces dependency on concentrated German and Japanese suppliers. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital biomedical engineers, ambulatory surgery center procurement managers, homecare provider operations directors, and group purchasing organization contract specialists. Secondary validation drew from FDA 510(k) premarket notification databases, EU MDR notified body certification records, hospital procurement contract filings, and CMS Medicare Advantage coverage determinations. Bottom-up unit shipment estimates triangulated against top-down market size calculations across the analysis window.
Calibration against historical replacement cycle data and regulatory approval timelines anchored the analytical framework. Segmentation dimensions modeled include product type, power source technology, end-user setting, and clinical application intensity. CAGRs were derived from regression analysis of shipment volumes against surgical procedure growth and facility construction permits. Forecast inputs incorporated lithium-ion energy density improvement curves and EU MDR notified body capacity constraints.
Macroeconomic conditions sit as an overlay; deviation in hospital capital expenditure cycles, reimbursement policy shifts, or battery raw material costs would shift the trajectory. Forecasts reflect documented assumptions about regulatory pathway timelines and technology substitution rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Chile Radiotherapy Market
Medical Equipment
Fluoroscopy Equipment Market
Medical Equipment
Global Medical Refrigerators Market
Medical Equipment
Bench-Top Dental Autoclaves Market
Medical Equipment
Global Medical Lifting Slings Market
Medical Equipment
Podiatry Equipment Market
Medical Equipment
Global Surgical Table Market
Medical Equipment
Thermal Cycler Market
Medical Equipment
Histology Embedding System Market
Medical Equipment
Water Bath Market
Medical Equipment
Patient Mechanical Lift Handling Equipment Market
Medical Equipment
Urodynamics Equipment and Disposables Market
Medical Equipment
Durable Medical Equipment Market
Medical Equipment
Contact Type Liquid Handling Workstation Market
Medical Equipment
Global Embryo Incubator Market
Medical Equipment
Medical Ultrasonic Baths Market