
 Urodynamic Equipment Market | 2026-2036
Urodynamic Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Urodynamic Equipment Market Outlook
The trained urodynamics technician workforce is collapsing across multiple developed healthcare systems, creating bottlenecks that equipment vendors must address through automation and simplified workflow design. Laborie Medical Technologies leverages embedded software to reduce per-test operator time, while Medtronic anchors its position through integrated catheter-electrode systems that minimize manual setup. Verathon competes by extending portable ultrasound bladder scanner compatibility into urodynamic suites, reducing reliance on specialized staffing.
Urodynamic equipment encompasses diagnostic instrumentation that measures pressure-flow relationships, electromyographic activity, and vesical compliance during simulated physiologic filling and voiding, typically employing fluid-filled or air-charged catheters with transducer sensitivity to 0.5 cmH₂O. These systems serve urologists and gynecologists in objectively characterizing lower urinary tract dysfunction prior to surgical or pharmacologic intervention. Cystometry systems occupy the deepest margin pools due to catheter consumables and software maintenance contracts, while wireless technology segments are recording the fastest expansion as ambulatory diagnostic protocols replace stationary lab-based testing. Electromyography modules remain a specialized niche with limited vendor competition.
The FDA regulates urodynamic devices under 21 CFR Part 876 as Class II medical devices requiring 510(k) premarket notification, while the EU MDR imposes strengthened clinical evidence and post-market surveillance obligations through notified body review. The FDA's emphasis on human factors validation is forcing redesigns of user interfaces to accommodate less-specialized operators. Stakeholders must monitor how CMS reimbursement determinations for complex urodynamic procedures interact with capital equipment purchase cycles in hospital systems.
Market Dynamics
The collapse of specialized urodynamics technician availability across developed healthcare systems is forcing equipment redesign toward automation and simplified operator workflows, compressing the traditional skill premium that once protected high-end system margins.
Growth Catalysts
- EU MDR Conformity Pressure:Tightened clinical evidence requirements for Class IIa and IIb urodynamic systems under the EU Medical Device Regulation are accelerating replacement cycles as older devices lose notified body certification.
- Wireless Telemetry:Ambulatory diagnostic protocols employing wireless pressure transducers are expanding test volumes beyond stationary lab capacity constraints in hospital networks.
- Germany's Hospital Consolidation:Centralized procurement tenders across Western European hospital networks are standardizing urodynamic platform specifications and driving volume commitments.
Market Restraints
- Catheter Consumables Cost Structure:Single-use fluid-filled and air-charged catheters with 0.5 cmH₂O transducer sensitivity impose recurring material costs that limit system affordability for smaller urology clinics.
- Notified Body Bottleneck:Concentrated EU MDR conformity assessment capacity across a shrinking pool of designated notified bodies is extending certification timelines for new urodynamic system introductions.
- Bladder Scanner Substitution:Portable ultrasound bladder volume measurement devices are capturing preliminary diagnostic cases that previously required full urodynamic workup.
Strategic Opportunities
- United Kingdom Diagnostic Expansion:NHS England's aging population cohort is driving urodynamic test volume growth that outpaces installed system capacity in regional hospital trusts.
- Electromyography Module Integration:Convergence of pressure-flow cystometry with surface EMG recording is creating premium system configurations for complex pelvic floor dysfunction cases.
- France's Outpatient Shift:Reimbursement incentives for same-day surgical pathways are pushing urodynamic testing into ambulatory surgical centers requiring compact, portable system formats.
Industry Challenges
- Human Factors Validation:FDA 21 CFR Part 876 enforcement is mandating user interface redesigns to accommodate less-specialized operators, extending development timelines and validation costs.
- Legacy System Integration:Hospital information system connectivity requirements for electronic health record data exchange are complicating deployment of new urodynamic platforms alongside existing infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Urodynamic Equipment Market |
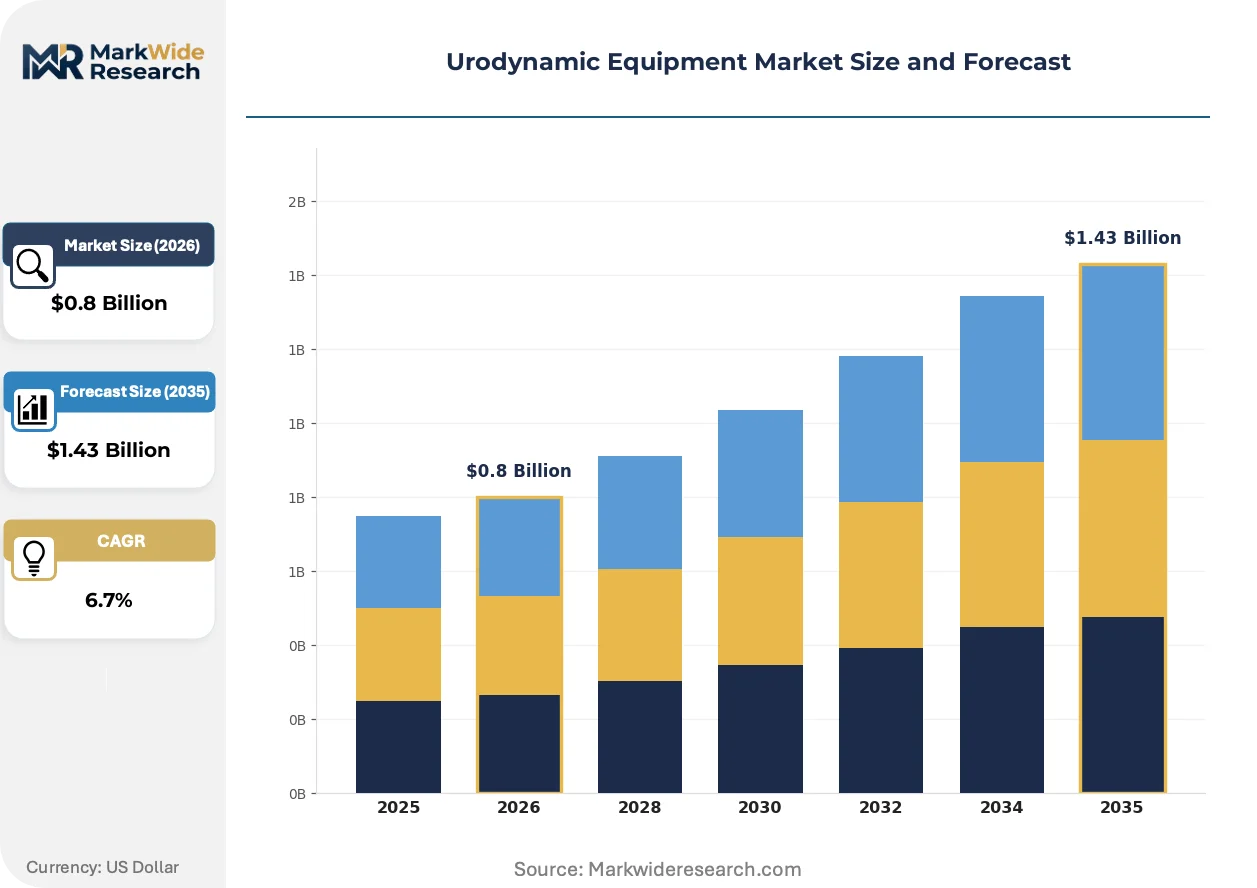
| Market Size in 2026 | $0.8 Billion |
| Market Size in 2035 | $1.43 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flowmetry, Uroflowmetry, Cystometry, Electromyography End User: Hospitals, Clinics, Diagnostic Centers, Research Facilities Technology: Digital, Portable, Computerized, Wireless Application: Urinary Incontinence, Bladder Dysfunction, Neurological Disorders, Prostate Issues |
| Companies Covered | Verathon, The Prometheus Group, Laborie Medical Technologies, Becton Dickinson and Company, Albyn Medical, Boston Scientific Corporation, Medtronic, MEDKONSULT Medical Technology, CooperSurgical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Urodynamic Equipment Market Strategic Shifts
Wireless telemetry architectures are restructuring competitive advantage in urodynamic diagnostics, compressing the value chain between stationary laboratory systems and ambulatory monitoring platforms while redistributing margin pools toward software and consumables.
Air-charged catheter technology is supplanting traditional fluid-filled systems in high-volume diagnostic settings. Urology clinics across Germany and France are adopting air-charged configurations for reduced setup complexity and elimination of hydrostatic pressure artifacts. This transition is supplanting the historical premium attached to fluid-filled precision, compressing average system price points while expanding addressable clinic segments.
EU MDR post-market surveillance obligations are reshaping vendor operating models. Strengthened clinical evidence requirements and periodic safety update reporting are elevating regulatory affairs overhead for urodynamic device manufacturers. Wireless technology segments face the steepest compliance burden due to novel connectivity risk profiles and cybersecurity validation demands.
Hospital procurement centralization is consolidating vendor relationships across Western European networks. Buyers in the United Kingdom and France are aggregating urodynamic equipment purchasing under regional tender frameworks that prioritize total cost of ownership over upfront capital expenditure. This behavioral shift is compressing switching cycles and elevating service contract attach rates as competitive differentiators.
Urodynamic Equipment Market Segmentation
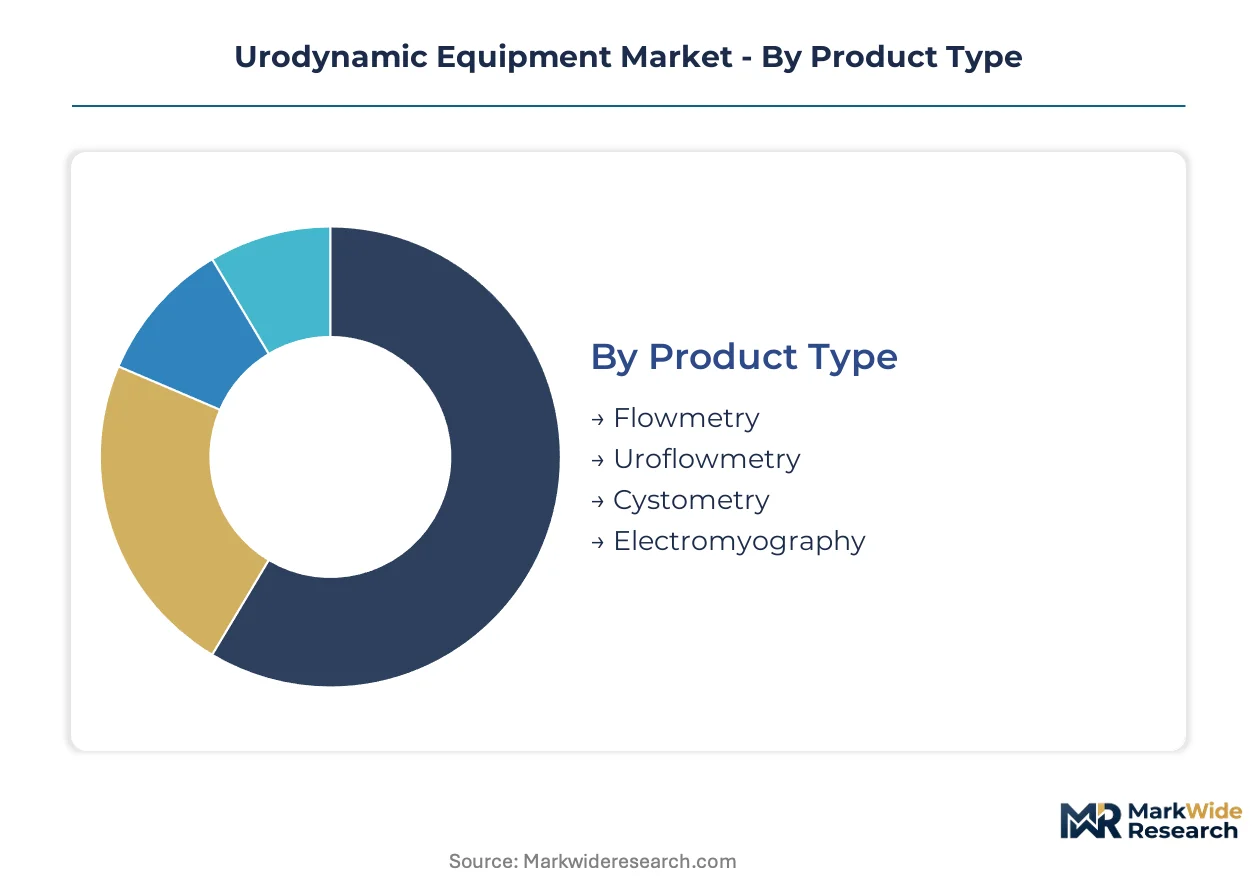
Urodynamic equipment segmentation reveals distinct regulatory pathways and reimbursement profiles that shape vendor portfolio strategy. Product type and technology categories carry divergent conformity assessment burdens under EU MDR and FDA 21 CFR Part 876, while end-user concentration determines service contract economics.
Product Type:
EU MDR classifies cystometry and uroflowmetry systems as Class IIa devices with moderate clinical evidence requirements, whereas electromyography modules with invasive needle electrodes face Class IIb scrutiny and extended notified body review timelines.
- Cystometry:Measures vesical pressure and compliance during controlled filling using fluid-filled or air-charged catheters with 0.5 cmH₂O transducer sensitivity. German hospital networks are standardizing on integrated cystometry platforms that bundle pressure-flow analysis with EMG capability under centralized procurement tenders. Established volume favors cystometry; emerging adoption favors electromyography.
- Uroflowmetry:Non-invasive urine flow rate measurement employing load cell or rotating disk sensors to calculate maximum and average flow rates. United Kingdom NHS trusts are expanding uroflowmetry capacity in community diagnostic hubs to reduce hospital referral backlogs for benign prostatic hyperplasia screening.
- Flowmetry:Streamlined volumetric measurement systems optimized for high-throughput screening in French outpatient surgical centers.
- Electromyography:Surface and needle electrode configurations for pelvic floor muscle activity recording during voiding; concentrated in specialized pelvic floor dysfunction clinics across Western Europe.
Established volume favors cystometry; emerging adoption favors electromyography.
End User:
Capital expenditure thresholds and service contract attach rates diverge sharply between hospital networks with dedicated biomedical engineering staff and smaller clinics dependent on vendor field service.
- Hospitals:Acute care institutions with integrated urology departments requiring multi-station cystometry suites and HIS connectivity. France's regional hospital trusts are consolidating urodynamic procurement under framework agreements that mandate 10-year service commitments.
- Clinics:Independent urology and gynecology practices in Germany's ambulatory care sector are adopting portable wireless systems to bypass technician staffing constraints.
- Diagnostic Centers:Specialized facilities in the United Kingdom handling outsourced NHS urodynamic referrals.
- Research Facilities:Academic medical centers developing novel ambulatory monitoring protocols with enhanced post-market surveillance obligations.
Procurement concentration tilts toward hospitals; workflow flexibility advantages accrue to clinics.
Technology:
Wireless telemetry architectures are displacing stationary computerized systems as ambulatory diagnostic protocols expand test volumes beyond fixed laboratory capacity.
- Wireless:Ambulatory pressure transducers with Bluetooth telemetry enabling 24-hour natural filling studies outside clinical settings. United Kingdom diagnostic networks are piloting wireless protocols to reduce catheter-related urinary tract infection rates in elderly patient cohorts. Wireless configurations are expanding most quickly across Western European markets.
- Portable:Compact battery-powered units for bedside and outpatient deployment; French reimbursement incentives for same-day surgical pathways are accelerating portable system adoption in ambulatory surgical centers.
- Digital:Microprocessor-controlled signal processing with automated artifact detection algorithms.
- Computerized:Stationary laboratory platforms with integrated analysis software and thermal printer output; dominant in German academic hospital networks with legacy infrastructure investment.
Wireless systems are gaining share fastest; computerized platforms retain installed base loyalty.
Application:
Clinical indication determines procedure reimbursement codes and thereby influences equipment utilization rates across European healthcare systems.
- Urinary Incontinence:Stress, urge, and mixed incontinence evaluation representing the highest-volume urodynamic indication. Germany's statutory health insurance funds cover complex urodynamic workup for incontinence prior to surgical intervention, sustaining stationary system demand. Incontinence evaluation commands the deepest procedure volumes.
- Bladder Dysfunction:Detrusor overactivity and underactivity assessment; United Kingdom regional trusts are expanding capacity to address rising diagnostic demand from aging populations.
- Neurological Disorders:Neurogenic bladder evaluation in multiple sclerosis and spinal cord injury patients; concentrated in specialized referral centers.
- Prostate Issues:Pre-operative assessment for transurethral resection candidates; French urology clinics are integrating uroflowmetry into benign prostatic hyperplasia care pathways.
Incontinence workup anchors utilization; neurological applications command premium pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU MDR conformity assessment requirements are restructuring competitive access across Western European healthcare systems, while aging demographics in Germany, France, and the United Kingdom concentrate diagnostic demand growth. The regulatory framework favors vendors with established notified body relationships and post-market surveillance infrastructure.
Germany
Germany's statutory health insurance funds sustain complex urodynamic procedure volumes through pre-surgical incontinence evaluation coverage. The EU MDR's tightened clinical evidence requirements for Class IIb electromyography modules are accelerating replacement cycles in Bavarian academic hospital networks. Stuttgart and Munich medical device clusters host urodynamic system service operations supporting regional hospital trusts.
France
Reimbursement incentives for same-day surgical pathways are shifting diagnostic testing into Île-de-France ambulatory surgical centers. ANSM post-market surveillance obligations overlap with EU MDR periodic safety update reporting for wireless telemetry systems. Lyon and Marseille urology clinics are adopting portable system formats to bypass centralized hospital procurement frameworks.
United Kingdom
NHS England's aging population cohort is driving urodynamic test volume growth beyond installed system capacity in regional hospital trusts. MHRA recognition of EU MDR certificates is simplifying market access for CE-marked devices during the extended transition period. London and Manchester diagnostic hubs are expanding uroflowmetry capacity to reduce referral backlogs for benign prostatic hyperplasia screening.
United States
FDA 21 CFR Part 876 human factors validation requirements are mandating user interface redesigns to accommodate less-specialized operators. CMS reimbursement determinations for complex urodynamic procedures interact directly with hospital capital equipment purchase cycles. Boston and Minneapolis medical device corridors concentrate urodynamic system development and clinical validation activities.
Japan
PMDA review timelines for Class II urodynamic devices are compressing as the agency harmonizes with FDA-recognized consensus standards. METI reimbursement policy for ambulatory diagnostic protocols is expanding wireless telemetry adoption in Tokyo and Osaka urology departments. Aging demographics in Kansai and Chubu regions are driving diagnostic volume growth comparable to Western European markets.
Urodynamic Equipment Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding service contract economics and the lower tier competing on portable system accessibility. The market structure reflects procurement consolidation in Western European hospital networks alongside technician workforce constraints that favor simplified workflow designs. Three archetypes dominate: integrated diagnostic platform vendors, catheter-electrode system specialists, and portable ultrasound compatibility extenders. Competitive moves concentrate on embedded software automation and wireless telemetry architecture licensing.
Among North American integrated platform vendors, Medtronic and Boston Scientific Corporation occupy positions exemplifying the premium-tier diagnostic system archetype, while Laborie Medical Technologies represents the workflow automation specialist tier. These three companies anchor different competitive vectors within a market where FDA human factors validation and EU MDR conformity assessment capabilities determine sustainable market access.
| Leading Market Players |
|---|
| Verathon |
| The Prometheus Group |
| Laborie Medical Technologies |
| Becton Dickinson and Company |
| Albyn Medical |
| Boston Scientific Corporation |
| Medtronic |
| MEDKONSULT Medical Technology |
| CooperSurgical |
| Others |
Value Chain & Pricing Dynamics
Air-charged catheter displacement of fluid-filled systems is simultaneously relocating component sourcing from precision glass-blowing clusters in Germany to polymer extrusion centers in Ireland and the Netherlands while collapsing the traditional precision premium that once sustained cystometry system margins.
Pricing Analysis
German hospital networks pay 15-25% premiums for integrated EMG-capable cystometry platforms compared to French ambulatory surgical centers procuring portable base configurations. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) certification tier, software automation depth, and service contract bundling. Cost compression in standard-tier systems is intensifying because centralized procurement tenders prioritize total cost of ownership calculations. Independent urology clinics in Germany's ambulatory sector exhibit highest price sensitivity; academic hospital networks with dedicated biomedical engineering staff show lowest sensitivity due to service contract attach rate preferences.
Supply Chain Analysis
Just-in-time inventory strategies dominate catheter consumables procurement, though notified body certification bottlenecks are forcing strategic stockpiling of wireless telemetry modules with extended EU MDR review timelines. Component manufacturing concentrates in Germany, Ireland, and the Netherlands for transducer assemblies; software development clusters in Boston and Minneapolis supply embedded automation platforms. Supply chains draw from specialized medical-grade polymer suppliers and MEMS pressure sensor foundries. Single-source vulnerability concentrates in EU MDR-designated notified bodies for Class IIb device conformity assessment. Distribution runs through regional hospital procurement frameworks in Western Europe and GPO contracts in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Urodynamic equipment markets are approaching a platform-economics inflection where wireless telemetry interoperability standards will determine ecosystem control, with software-defined diagnostic protocols displacing hardware-anchored competitive moats.
For Market Incumbents: Compound service contract attach rates through predictive maintenance software bundles that lock hospital networks into decade-long framework agreements. Deepen backward integration into air-charged catheter manufacturing to capture consumables margin pools eroding system pricing power. Prioritize EU MDR notified body relationship investments to defend certification timelines against emerging portable system vendors.
For New Entrants and Emerging Players: Anchor in French ambulatory surgical centers where reimbursement incentives for same-day pathways create portable system demand outside consolidated hospital procurement. Target United Kingdom NHS diagnostic hubs facing technician workforce collapse and seeking wireless telemetry solutions with minimal operator training requirements. Pursue software-as-a-service pricing models that bypass capital expenditure approval cycles.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors workflow automation specialists with embedded software capabilities over pure hardware manufacturers. Long-term viability hinges on recurring revenue streams from consumables and software maintenance rather than capital equipment cycles. Monitor FDA human factors validation enforcement intensity as inflection indicator for incumbent redesign cost burdens and new entrant disruption windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Wireless Telemetry Interoperability Standard | Bluetooth-enabled ambulatory protocols expand test volumes beyond fixed laboratory capacity constraints. |
| EU MDR Notified Body Certification Investment | Accelerated conformity assessment timelines protect market access against regulatory capacity bottlenecks. |
| Embedded Software Automation Platform | Reduced per-test operator time addresses collapsing specialized technician workforce availability. |
| Air-Charged Catheter Manufacturing Integration | In-house polymer extrusion capabilities capture consumables margins compressing system price points. |
| Hospital System Partnership Framework | Centralized procurement tender participation secures volume commitments across Western European networks. |
Study Parameters
The analysis maps cystometry, uroflowmetry, electromyography, and wireless telemetry segments, each validated through urology department heads, biomedical engineering directors, hospital purchasing committee members, and GPO contracts managers. Primary interviews with equipment vendors and service technicians combined with secondary validation against FDA 510(k) premarket notification databases, EU MDR notified body certification records, CMS reimbursement determination filings, and hospital procurement tender documents. Bottom-up installed base estimates and top-down healthcare expenditure allocations were triangulated for consistency.
Model outputs were validated against external benchmarks including medical device trade flow data and regional healthcare infrastructure investment disclosures. Segmentation modeling covered product type, technology architecture, end-user facility tier, and clinical application indication across the projection horizon. CAGRs were derived from equipment replacement cycle analysis, ambulatory protocol adoption curves, and demographic diagnostic demand projections with wireless telemetry penetration rates and technician workforce availability as key sensitivity inputs.
Underlying assumptions cover EU MDR transition timeline adherence, NHS diagnostic capacity expansion commitments, and statutory health insurance reimbursement stability, with deviation risk concentrated in notified body capacity constraints and FDA human factors enforcement intensity. Revision becomes warranted when wireless telemetry reimbursement codes achieve widespread payer adoption or centralized procurement consolidation accelerates beyond current framework agreement coverage.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Autopsy Saw Market
Medical Equipment
Global Medical Copper Tubing Market
Medical Equipment
Embedded Disinfection Cabinet Market
Medical Equipment
Durable Medical Equipment Rental Market
Medical Equipment
Global Kidney Dialysis Equipment and Supplies Market
Medical Equipment
Floor-Standing Platelet Agitator Market
Medical Equipment
Medical Equipment Management Software Market
Medical Equipment
Global Plasma Sterilizers Market
Medical Equipment
Durable Medical Equipment Market
Medical Equipment
Global Blood Purification Equipment Market
Medical Equipment
Medical Equipment Rental Market
Medical Equipment
Diathermy Equipment Market
Medical Equipment
Global Embryo Incubator Market
Medical Equipment
Asia-Pacific Medical Carts Market
Medical Equipment
Medical Equipment Maintenance Market
Medical Equipment
Global Bone Densitometer Market