
 Veterinary Equipment and Disposables Market | 2026-2036
Veterinary Equipment and Disposables Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Equipment and Disposables Market Intelligence
Equipment leasing and pay-per-use financing is tilting competitive dynamics toward asset-light service providers that can deploy advanced diagnostic platforms without capital-intensive purchases. IDEXX Laboratories leverages its integrated diagnostic ecosystem to sustain recurring revenue streams through consumable lock-in. Midmark Corporation anchors its position through specialized anesthesia and dental equipment designed for high-throughput veterinary clinics. Heska Corporation differentiates via point-of-care diagnostics that reduce reliance on centralized reference laboratories.
Veterinary equipment and disposables encompass instruments, consumables, and monitoring systems engineered for animal patient care, typically manufactured from medical-grade polymers and stainless steel with sterilization compatibility to ISO 11135 ethylene oxide or ISO 17665 steam standards, serving the primary purpose of diagnosis, surgical intervention, and continuous health monitoring across species. Diagnostic instruments and disposables together command the dominant share of product-level revenue, with disposables generating superior margin stability through repeat purchase patterns. Companion animal treatment and livestock care represent the most structurally significant application dimensions, the former expanding fastest as specialty oncology and orthopedic procedures migrate from human medicine into veterinary practice.
The FDA Center for Veterinary Medicine enforces sterility and biocompatibility standards for implantable and invasive devices, while the USDA Animal and Plant Health Inspection Service regulates equipment used in interstate livestock movement and disease surveillance programs. ISO 13485 quality management certification functions as a de facto market access threshold for suppliers targeting institutional procurement channels. Stakeholders must monitor how evolving telemedicine reimbursement policies reshape capital allocation between in-clinic imaging and remote biotelemetry infrastructure.
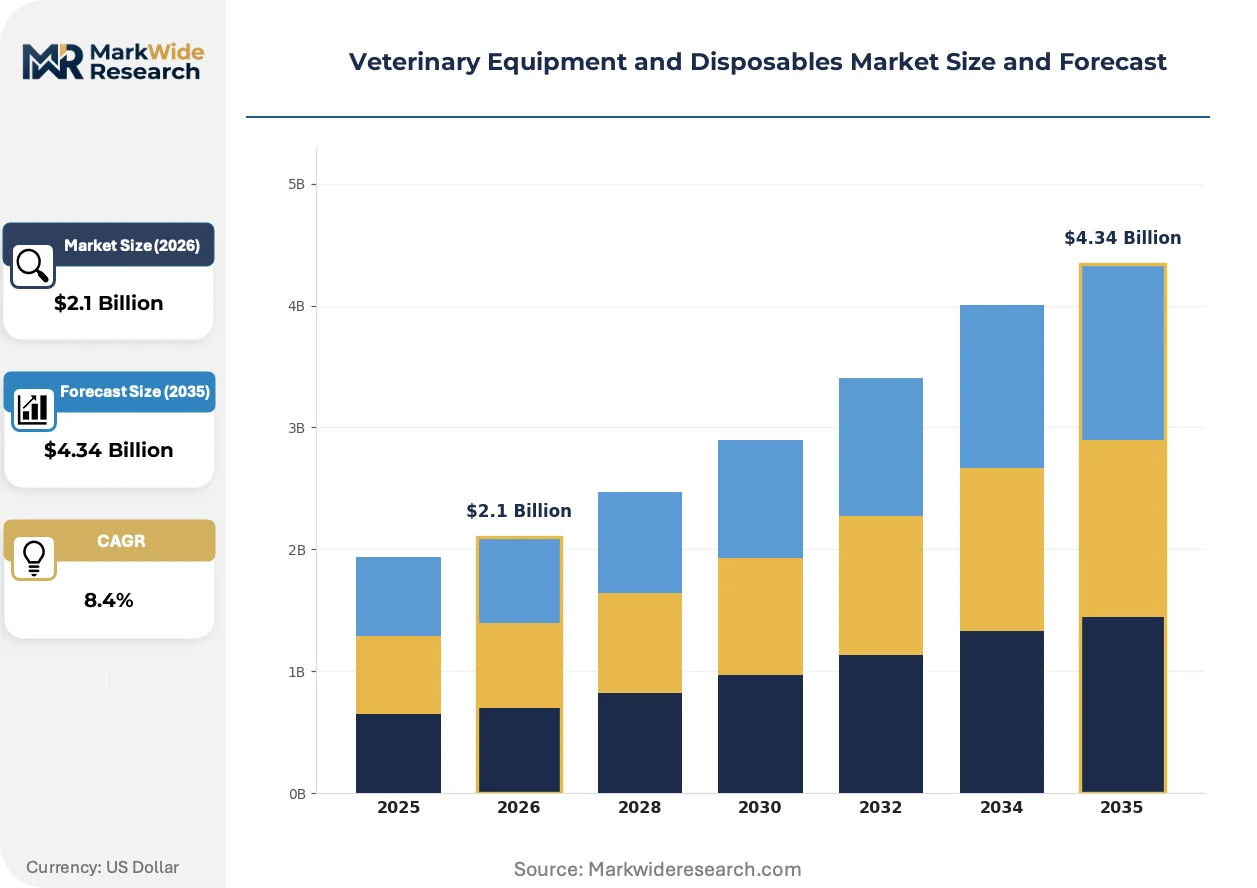
Market Dynamics
Specialty veterinary hospital chains are consolidating procurement power, forcing equipment vendors to abandon traditional distributor networks and build direct service capabilities with embedded financing.
Growth Catalysts
- ISO 13485 Certification Mandates:Institutional buyers now require quality management certification as a baseline procurement filter, elevating compliant suppliers above commodity competitors in the United States and Germany.
- Pet Humanization Trajectory:Companion animal owners increasingly demand oncology and orthopedic procedures previously confined to human medicine, creating pull-through for advanced imaging and surgical platforms.
- Telemedicine Reimbursement Expansion:Evolving veterinary telehealth policies in North America and Western Europe are redirecting capital toward remote biotelemetry infrastructure and cloud-connected monitoring devices.
Market Restraints
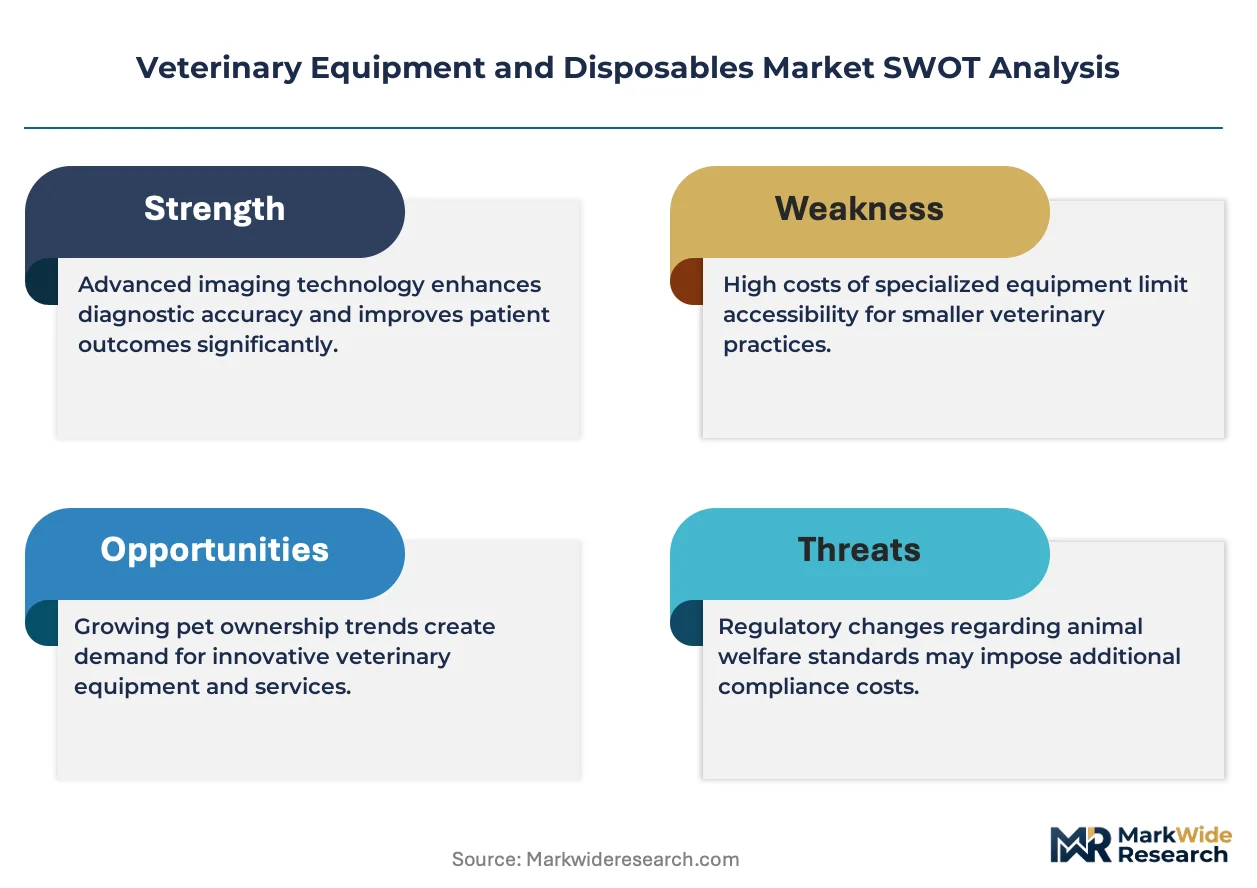
- Medical-Grade Polymer Cost Volatility:Specialized sterilization-compatible resins face petrochemical feedstock price swings that compress disposable margins unpredictably.
- FDA Center for Veterinary Medicine Scrutiny:Intensifying sterility validation requirements for single-use devices extend product development timelines and elevate compliance expenditures.
- Reference Laboratory Concentration:Centralized diagnostic infrastructure in urban corridors limits point-of-care equipment penetration in rural veterinary practices.
Strategic Opportunities
- Rural Practice Underservice:Mobile veterinary units and telemedicine-enabled equipment leasing models remain underdeveloped across the American Midwest and Australian outback regions.
- AI-Assisted Diagnostic Convergence:Machine learning algorithms paired with digital radiography systems enable automated pathology detection without specialist interpretation.
- USDA APHIS Disease Surveillance Programs:Federal livestock monitoring mandates generate recurring demand for portable diagnostic equipment and sample collection disposables.
Industry Challenges
- Veterinary Anesthesiologist Scarcity:Specialized training programs produce insufficient practitioners to operate advanced inhalation systems, constraining equipment utilization rates.
- Legacy Practice Management Integration:New diagnostic platforms require API connectivity with entrenched software ecosystems, complicating deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Equipment and Disposables Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Instruments, Surgical Tools, Monitoring Devices, Disposables, Imaging Equipment Application: Livestock Care, Companion Animal Treatment, Exotic Animal Healthcare, Preventive Medicines, Rehabilitation End User: Veterinary Clinics, Animal Research Facilities, Zoos, Mobile Vet Units, Animal Shelters Technology: Ultrasound, Digital Radiography, Thermal Imaging, Biotelemetry, Laser Surgery |
| Companies Covered | IDEXX Laboratories, Midmark Corporation, Mindray, Heska Corporation, ICU Medical, Medtronic, Covetrus, Zoetis, B. Braun Vet Care, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Equipment and Disposables Market Strategic Shifts & Innovations
Equipment manufacturers are embedding connectivity and service layers into hardware, transforming capital sales into recurring revenue relationships that reshape buyer-vendor dynamics.
Digital radiography is hybridizing with cloud-based image storage and AI-assisted interpretation, enabling general practitioners to perform specialist-grade diagnostics without referral. Small-animal clinics in suburban United States markets are adopting these platforms fastest, compressing the traditional reference laboratory revenue model and redirecting diagnostic spend toward in-house capital equipment.
REACH chemical registration requirements in the European Union are forcing reformulation of polymer compositions used in implantable veterinary devices. Manufacturers serving EU markets must now document full substance toxicity profiles, disproportionately burdening mid-tier disposable suppliers lacking dedicated regulatory affairs capacity.
Consolidated buying groups now dominate equipment acquisition decisions for multi-site veterinary operators, displacing individual practice autonomy in purchasing. These groups negotiate enterprise pricing and standardized equipment fleets, concentrating vendor relationships among suppliers capable of national service coverage. This pattern is most pronounced in the United States, where specialty hospital chains now control a substantial share of diagnostic imaging procurement volume.
Veterinary Equipment and Disposables Market Segmentation
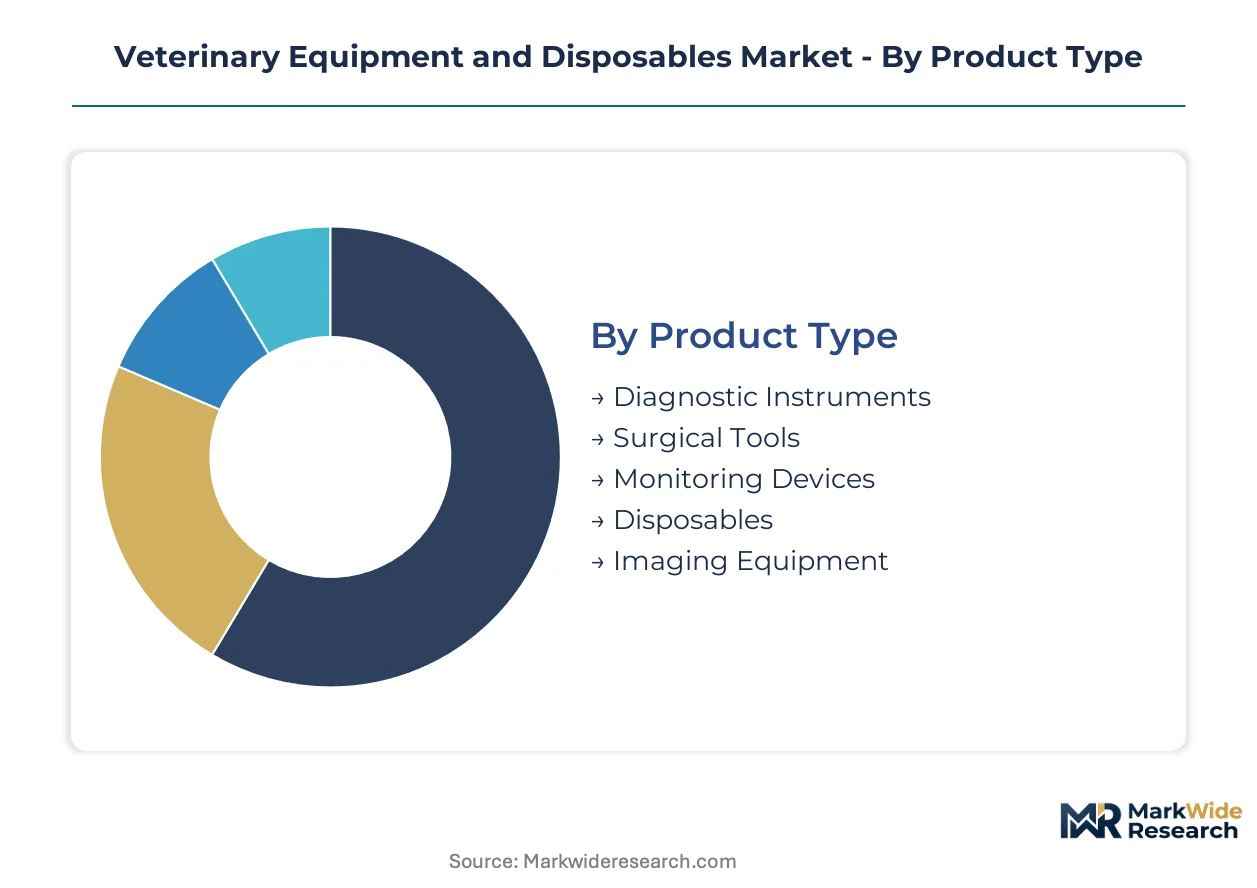
Segmentation in veterinary equipment reveals divergent replacement cycles that reshape inventory planning and capital allocation across practice types. Disposable categories turn over in weeks while imaging platforms depreciate over years, creating distinct financing and service requirements for suppliers.
Product Type:
Disposables rotate through inventory fastest with weekly replenishment cycles, while imaging equipment sits at the opposite extreme with decade-long depreciation schedules.
- Diagnostic Instruments:Blood analyzers, urinalysis systems, and point-of-care testing platforms built around optical sensors and microfluidic cartridges. Demand clusters in suburban United States specialty practices where same-day turnaround expectations eliminate reference laboratory delays.
- Disposables:Single-use syringes, catheters, suture materials, and specimen collection devices manufactured to ISO 11135 ethylene oxide sterilization standards. Hospital chains in Germany and the United States negotiate enterprise pricing for these high-velocity consumables, locking suppliers into multi-year supply agreements.
- Surgical Tools:Scalpels, forceps, retractors, and orthopedic implants forged from medical-grade stainless steel with autoclavable durability.
- Monitoring Devices:Pulse oximeters, capnographs, and multi-parameter anesthesia monitors with cloud connectivity features.
- Imaging Equipment:CT scanners, MRI systems, and C-arm fluoroscopy units requiring dedicated facility infrastructure and specialist interpretation.
Disposables anchors the volume base while diagnostic instruments gains share at the steepest rate.
Application:
Cost tier differentiation separates commodity livestock procedures from premium companion animal interventions that command equipment upgrades.
- Companion Animal Treatment:Oncology protocols, orthopedic surgeries, and dental procedures driving demand for advanced imaging and specialized surgical platforms. Pet humanization trends in the United States, United Kingdom, and Japan push owners toward specialist-grade interventions previously confined to human medicine.
- Livestock Care:Herd health management, reproductive services, and disease surveillance across cattle, swine, and poultry operations. USDA APHIS mandates for interstate movement certification sustain demand for portable diagnostic equipment in the American Midwest and Great Plains regions.
- Exotic Animal Healthcare:Avian, reptile, and small mammal specialty services requiring modified anesthesia systems and miniature surgical instruments.
- Preventive Medicines:Vaccination programs, parasite control, and wellness screening protocols.
- Rehabilitation:Hydrotherapy, therapeutic laser, and orthopedic recovery equipment for post-surgical recovery.
Livestock care anchors the volume base while companion animal treatment expands most quickly.
End User:
Customer type determines procurement sophistication, from centralized buying groups at hospital chains to fragmented purchasing at independent rural practices.
- Veterinary Clinics:Small-animal general practices, specialty referral hospitals, and mixed-animal operations representing the dominant equipment acquisition channel. Consolidated buying groups in the United States now negotiate enterprise pricing for multi-site operators, displacing individual practice autonomy.
- Mobile Vet Units:Ambulatory services delivering field anesthesia, reproductive services, and emergency care to remote livestock operations. Underserved regions across the Australian outback and American Mountain West present structural gaps for equipped mobile providers.
- Animal Research Facilities:University laboratories and pharmaceutical testing sites with specialized anesthesia and monitoring requirements.
- Zoos:Wildlife institutions requiring large-animal imaging platforms and specialized restraint equipment.
- Animal Shelters:Non-profit sterilization and wellness programs operating on constrained capital budgets.
Veterinary clinics anchors the volume base while mobile vet units gains share at the steepest rate.
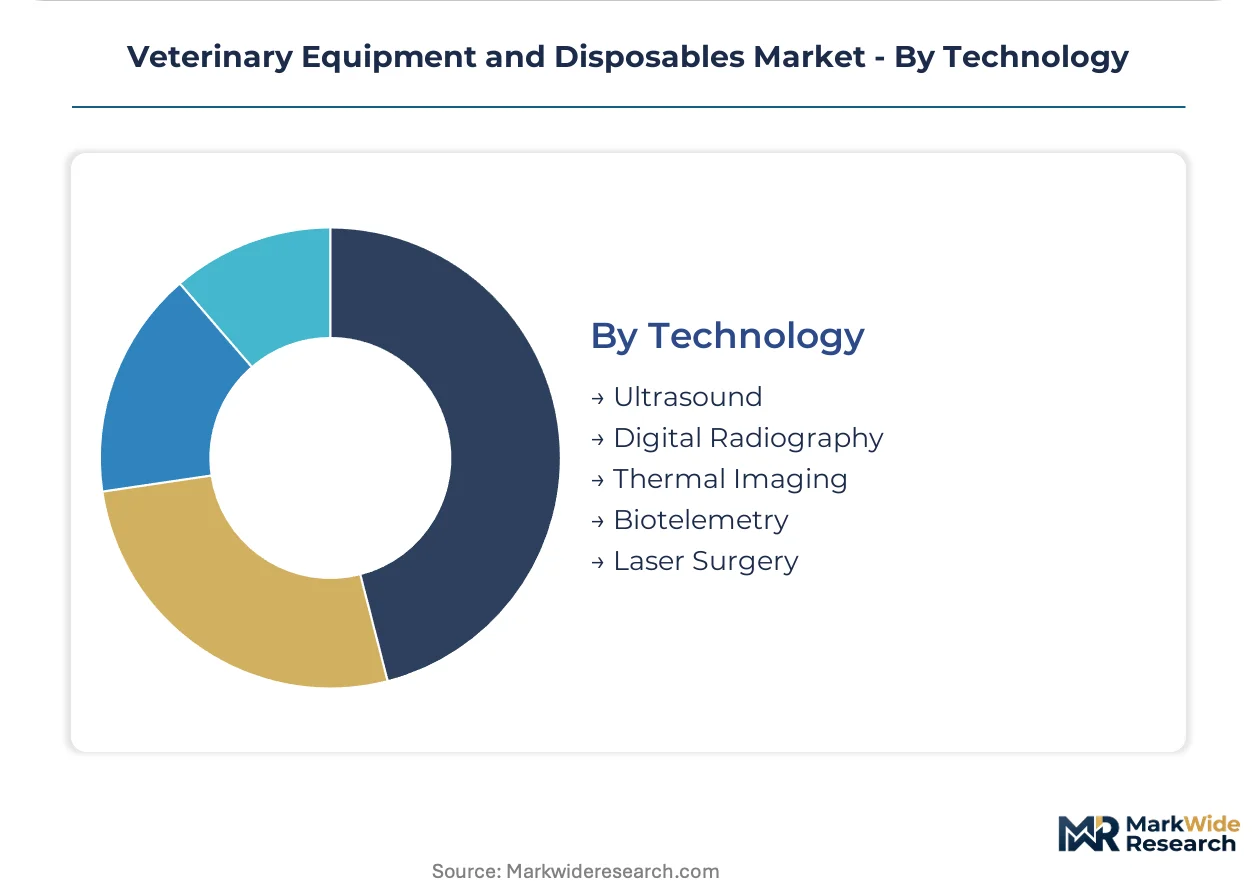
Technology:
Technology maturity separates established modalities with proven reimbursement pathways from emerging platforms requiring clinical validation.
- Digital Radiography:Flat-panel detector systems with DICOM-compliant image storage and teleradiology transmission capabilities. Suburban United States clinics adopt these platforms fastest, compressing traditional reference laboratory revenue models.
- Biotelemetry:Cloud-connected wearable sensors transmitting real-time physiologic data from ambulatory patients. Evolving telemedicine reimbursement policies in North America redirect capital toward remote monitoring infrastructure.
- Ultrasound:Portable and cart-based systems with specialized transducers for abdominal, cardiac, and reproductive imaging.
- Thermal Imaging:Infrared cameras detecting inflammatory patterns and circulatory abnormalities.
- Laser Surgery:CO2 and diode laser platforms for soft-tissue procedures with reduced hemorrhage and post-operative pain.
Digital radiography anchors the volume base while biotelemetry climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
USDA APHIS disease surveillance mandates and the FDA Center for Veterinary Medicine's sterility protocols are redirecting equipment procurement toward compliant suppliers in North America and Western Europe. Germany's REACH chemical registration requirements are forcing polymer reformulation for implantable devices. Japan's PMDA guidelines for animal health devices are tightening quality benchmarks across Asia-Pacific.
United States
Specialty veterinary hospital chains in Texas and Florida are consolidating diagnostic imaging procurement through enterprise buying groups. The FDA Center for Veterinary Medicine enforces ISO 11135 ethylene oxide sterilization standards for invasive disposables. Greater Phoenix and Austin metro clusters host high-throughput companion animal practices driving premium anesthesia platform upgrades.
Germany
REACH compliance costs are filtering mid-tier disposable suppliers from the EU veterinary implant market. ECHA substance toxicity documentation requirements extend product development timelines for polymer-based devices. The Stuttgart and Munich industrial corridors concentrate precision stainless steel surgical instrument manufacturing for export across Central Europe.
Japan
PMDA quality benchmarks for animal health devices are elevating certification barriers for imported diagnostic equipment. METI innovation incentives support domestic development of AI-assisted radiography platforms. Osaka and Nagoya veterinary teaching hospitals anchor demand for advanced orthopedic surgical systems.
Australia
TGA registration requirements for veterinary medical devices align with human health standards, compressing approval pathways for international suppliers. Mobile veterinary units serving Queensland and Western Australia outback regions present structural gaps for portable diagnostic equipment. Sydney and Melbourne specialty practices are adopting cloud-connected monitoring devices fastest.
United Kingdom
Veterinary telemedicine reimbursement expansion under NHS-adjacent frameworks is redirecting capital toward biotelemetry infrastructure. The UK's departure from EU regulatory alignment creates parallel compliance tracks for device manufacturers. London and Southeast England referral hospitals concentrate demand for CT and MRI platforms previously confined to human medicine.
Veterinary Equipment and Disposables Market Key Industry Players
On the supply side, the industry is consolidating around integrated diagnostic ecosystems and specialized equipment manufacturers with embedded financing capabilities. Three archetypes dominate: full-stack diagnostic platforms with consumable lock-in, anesthesia and dental equipment specialists for high-throughput clinics, and point-of-care testing vendors reducing reference laboratory dependence. M&A activity targets regional service networks, while portfolio diversification into cloud-connected monitoring devices accelerates.
Within the integrated diagnostic tier, IDEXX Laboratories and Heska Corporation exemplify platform-centric strategies built around recurring consumable revenue. Midmark Corporation anchors the specialized equipment segment with anesthesia and dental systems designed for consolidated hospital chains. Mindray occupies a position bridging human and veterinary device standards, leveraging manufacturing scale across medical-grade monitoring platforms.
| Leading Market Players |
|---|
| IDEXX Laboratories |
| Midmark Corporation |
| Mindray |
| Heska Corporation |
| ICU Medical |
| Medtronic |
| Covetrus |
| Zoetis |
| B. Braun Vet Care |
| Others |
Cost & Logistics Intelligence
The Stuttgart industrial corridor anchors European precision manufacturing for veterinary surgical instruments, with capacity utilization rates at specialized stainless steel forges directly shaping pricing power for mid-tier disposable suppliers lacking backward integration into medical-grade polymer production.
Pricing Analysis
Certification level (ISO 13485/FDA-grade) creates the primary spread between premium and commodity tiers, with three-tier pricing structure across premium, standard, and economy levels dominating procurement negotiations. Price differentiation rests on ethylene oxide sterilization validation depth and geographic delivery cost to rural practices. Cost compression in standard-tier disposables is intensifying because REACH compliance documentation burdens mid-tier suppliers disproportionately. Independent rural veterinarians exhibit highest price sensitivity, while consolidated hospital chains leverage volume scale for enterprise pricing lock-in.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from German and United States distributors are easing working capital constraints for polymer compounders serving veterinary implant manufacturers. Geographic supply concentration centers on Germany, the United States, and China for medical-grade stainless steel instruments, with South Korea and Japan anchoring electronic component sourcing for monitoring devices. Raw material dependencies draw from petrochemical feedstocks, cobalt-chromium alloys, and optical sensor arrays. Single-source vulnerability in ethylene oxide sterilization services presents structural risk. Distribution runs through specialized veterinary distributors and direct service teams for hospital chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The veterinary equipment sector is crossing into platform-economics territory, with IDEXX Laboratories' consumable-lockin ecosystem demonstrating how interoperability standards reshape competitive moats.
For Market Incumbents: Insulate recurring revenue streams by deepening captive supply of sterilization-compatible polymers and securing ISO 13485 certification moats against commodity competitors. Threat from point-of-care diagnostic entrants demands defensive API integration with entrenched practice management software ecosystems. Priority lever: channel control through embedded financing capabilities that match pay-per-use models offered by asset-light service providers. For New Entrants and Emerging Players: Pursue rural veterinary practice underservice across the American Midwest and Australian outback, where mobile unit equipment leasing remains structurally underdeveloped. The most penetrable segment lies in telemedicine-enabled biotelemetry infrastructure, with cloud-connected monitoring devices capturing diagnostic spend redirected from reference laboratories. Go-to-market angle: AI-assisted radiography interpretation bundled with hardware-as-a-service contracts. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated diagnostic platform owners with consumable recurring revenue over pure-play equipment manufacturers. Long-term viability across the analysis window hinges on cloud connectivity penetration and AI-assisted pathology validation. Acquisition target archetype: regional service networks with FDA Center for Veterinary Medicine compliance infrastructure. Signal to watch: telemedicine reimbursement policy expansion accelerating capital reallocation toward remote monitoring.| Strategic Initiative | Industry Significance |
|---|---|
| Consumable Lock-in Program | IDEXX Laboratories sustains recurring revenue through proprietary microfluidic cartridge ecosystems. |
| Embedded Financing Capability | Midmark Corporation captures hospital chain procurement through pay-per-use anesthesia platform deployment. |
| AI-Assisted Diagnostic Integration | Heska Corporation reduces reference laboratory dependence with automated pathology detection algorithms. |
| REACH Compliance Infrastructure | German manufacturers filter mid-tier competitors via ECHA substance toxicity documentation requirements. |
| Mobile Unit Service Network | Underserved Australian outback regions present structural white space for portable diagnostic equipment leasing. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across veterinary clinics, hospital procurement committees, biomedical engineers at research facilities, and GPO contracts managers. Secondary validation drew from FDA Center for Veterinary Medicine filings, USDA APHIS surveillance program documentation, hospital procurement databases, and ISO certification registries. Bottom-up equipment shipment analysis triangulated against top-down veterinary services expenditure models.
Calibration against historical replacement cycles and sterilization standard evolution anchored the analytical framework across the projection horizon. Segmentation dimensions modeled encompass product type, application, end user, and technology maturity tier. CAGRs derived from weighted average of equipment depreciation schedules and consumable replenishment velocity. Industry-specific inputs included telemedicine reimbursement policy trajectories and specialty hospital chain consolidation rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by asset-light diagnostic platform entrants would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Transseptal Access Systems Market
Medical Devices
Inhaled Corticosteroid Device Market
Medical Devices
Global Suture Anchor Devices Market
Medical Devices
Flow Cytometry Products Market
Medical Devices
Nonablative Laser Resurfacing Devices Market
Medical Devices
US Medical Sector Contract Electronic Manufacturing Market
Medical Devices
Neuromuscular Transmission Monitor Market
Medical Devices
Global Breast Biopsy Devices Market
Medical Devices
Plethysmograph Market
Medical Devices
US Neurothrombectomy Devices Market
Medical Devices
ePTFE Vascular Prosthesis Market
Medical Devices
Automated CPR Devices Market
Medical Devices
Global Cerebrospinal Fluid Drainage Catheter Market
Medical Devices
Global Female Sterilization Devices Market
Medical Devices
Peri-Implantitis Market
Medical Devices
United States Diabetes Devices Market