
 Medical Physics Market | 2026-2036
Medical Physics Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Physics Market Outlook
The shift from outsourced to in-house medical physics staffing is hardening across large hospital systems. LANDAUER sustains its dominance in personnel dosimetry services through extensive accreditation networks. GE Healthcare leverages its imaging installed base to bundle physics support with equipment service contracts. Medical Physics Services LLC anchors its position in the southeastern United States through long-term exclusive agreements with regional oncology networks.
Medical physics applies principles of physics to the prevention, diagnosis, and treatment of disease, encompassing radiation dose calculation algorithms with precision thresholds measured in milligray for therapeutic applications. The discipline ensures safe and effective use of ionizing and non-ionizing radiation in clinical settings, from linear accelerator calibration to magnetic resonance field uniformity verification. Radiation Therapy commands the largest product type segment as proton and heavy-ion centers multiply across North America and Europe. Diagnostic Imaging physics services are expanding fastest within the technology dimension, driven by MRI and CT scanner complexity and artificial intelligence integration into reconstruction protocols. Hospitals represent the dominant end user category, though Research Institutions are capturing disproportionate physics talent as competitive differentiation in grant funding intensifies.
The FDA oversees radiation-emitting product performance standards under 21 CFR Subchapter J, while the Nuclear Regulatory Commission governs radioactive material licensing for medical use, creating dual compliance pathways that shape vendor qualification requirements. ISO 9001 and ISO 13485 quality management certifications function as baseline market access credentials for physics service organizations seeking multi-site health system contracts. Stakeholders must monitor how artificial intelligence-based treatment planning tools redefine the boundary between automated calculation and mandatory physicist oversight.
Market Dynamics
The migration of medical physics services from external vendors to captive hospital departments is restructuring vendor relationships and contract economics across radiation therapy programs.
Growth Catalysts
- Proton Center Expansion:Heavy-ion therapy facilities in the United States, Germany, and Japan are multiplying, each requiring dedicated physics teams for beam commissioning and daily quality assurance protocols.
- FDA Quality System Rule Updates:Tighter 21 CFR Subchapter J enforcement on radiation-emitting devices is compelling hospitals to maintain permanent in-house physics oversight rather than episodic external audits.
- Artificial Intelligence Integration:Machine learning reconstruction algorithms in MRI and CT systems are creating demand for physicists who validate automated image quality against clinical tolerance thresholds.
Market Restraints
- Specialist Labor Scarcity:Board-certified medical physicists concentrate in academic medical centers, leaving community hospitals competing for limited credentialed staff.
- Equipment Cost Concentration:Linear accelerator and proton cyclotron procurement requires capital commitments that only consolidated health systems can absorb, squeezing independent oncology practices from the market.
- Dual Regulatory Burden:Parallel FDA device standards and NRC radioactive material licensing create compliance friction that slows service expansion into new clinical sites.
Strategic Opportunities
- India Diagnostic Imaging:Private hospital chains in Mumbai, Delhi, and Bangalore are installing 3T MRI and spectral CT systems faster than qualified physics support can scale.
- Telephysics Service Models:Remote beam data analysis and treatment planning verification are opening rural and small-market cancer centers to specialist-level physics coverage without relocation costs.
- EU Medical Device Regulation:MDR conformity assessment requirements for software-driven radiation devices are mandating documented physics validation, creating contracted service demand from notified bodies.
Industry Challenges
- Credentialing Timeline Compression:CAMPEP residency slots and ABR certification pathways are failing to match retirement rates among senior therapeutic physicists.
- Legacy System Interoperability:Vendor-specific DICOM-RT formats and proprietary accelerator control systems are fragmenting physics workflow standardization across multi-vendor equipment fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Physics Market |
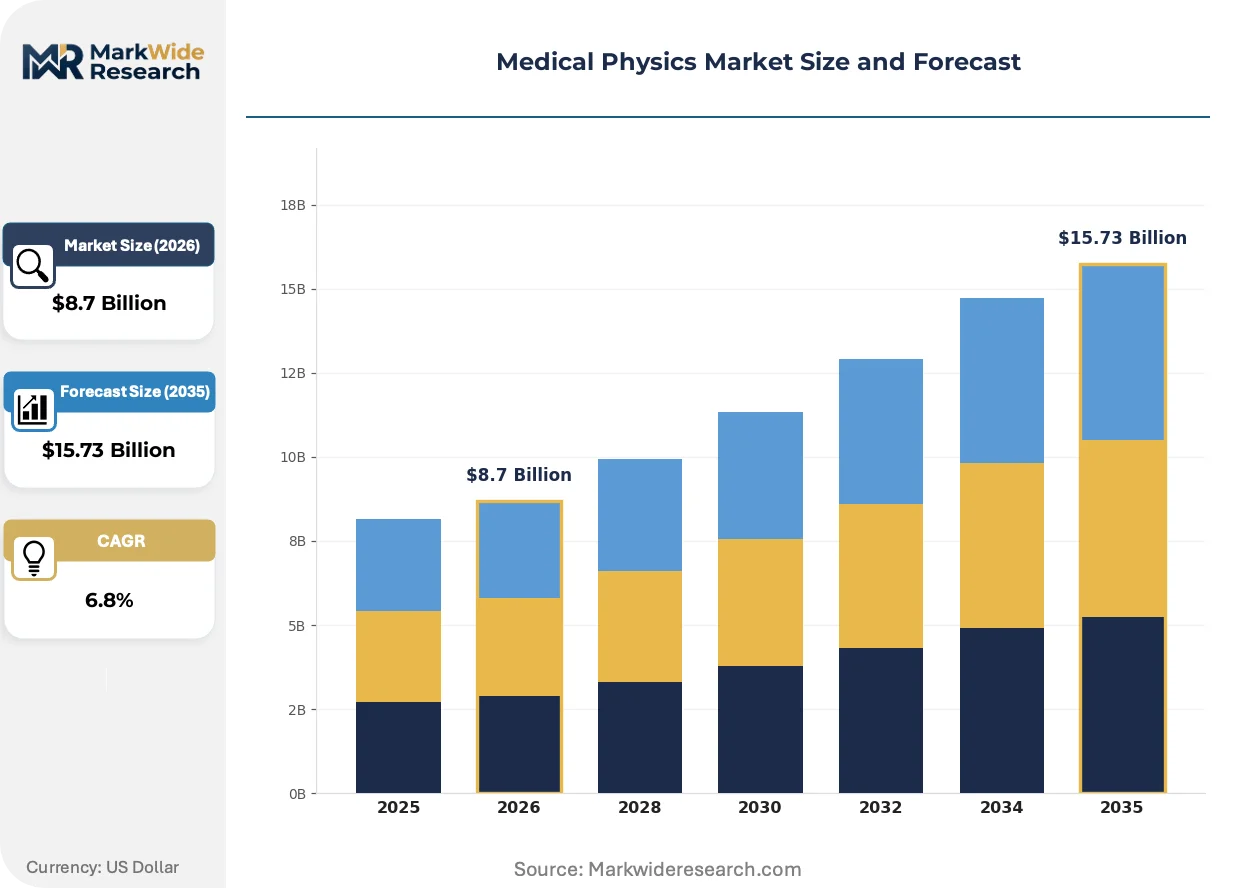
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radiation Therapy, Diagnostic Imaging, Nuclear Medicine, Dosimetry Technology: X-ray, MRI, Ultrasound, PET, CT Application: Patient Care, Research, Quality Assurance, Calibration End User: Hospitals, Clinics, Research Institutions, Academic Facilities |
| Companies Covered | LANDAUER, Medical Physics Services LLC, Krueger-Gilbert Health Physics Inc., GE Healthcare, Radiation Safety & Control Services Inc., Alyzen Medical Physics Services, Upstate Medical Physics Services, Versant Medical Physics Services & Radiation Safety, Alliance Medical Physics Services LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Physics Market Strategic Shifts
Computational methods are displacing manual measurement protocols across dosimetry and quality assurance, compressing physics labor intensity while raising precision requirements.
Monte Carlo dose calculation algorithms are absorbing the verification workload previously handled by ionization chamber measurements in proton and electron beam commissioning. Academic proton centers in the United States and Europe are adopting these tools for patient-specific quality assurance, reducing phantom-based measurement time from hours to minutes. This compression is absorbing junior physicist hours into algorithm validation rather than routine data acquisition.
The EU AI Act's risk classification framework for medical devices is imposing documented validation requirements on machine learning-based treatment planning systems. Physics departments must now maintain algorithm performance monitoring protocols that satisfy both clinical safety and regulatory audit standards. Radiation oncology software vendors in Germany and France are responding by embedding physicist-signed validation reports into their product release cycles.
Hospital procurement departments are unbundling equipment service contracts from physics support agreements that OEMs previously packaged together. Large United States health systems are negotiating separate RFPs for linear accelerator maintenance and clinical physics staffing, driving price transparency. This disaggregation is most visible in the southeastern and midwestern states where consolidated oncology networks command sufficient volume to justify captive physics departments.
Medical Physics Market Segmentation
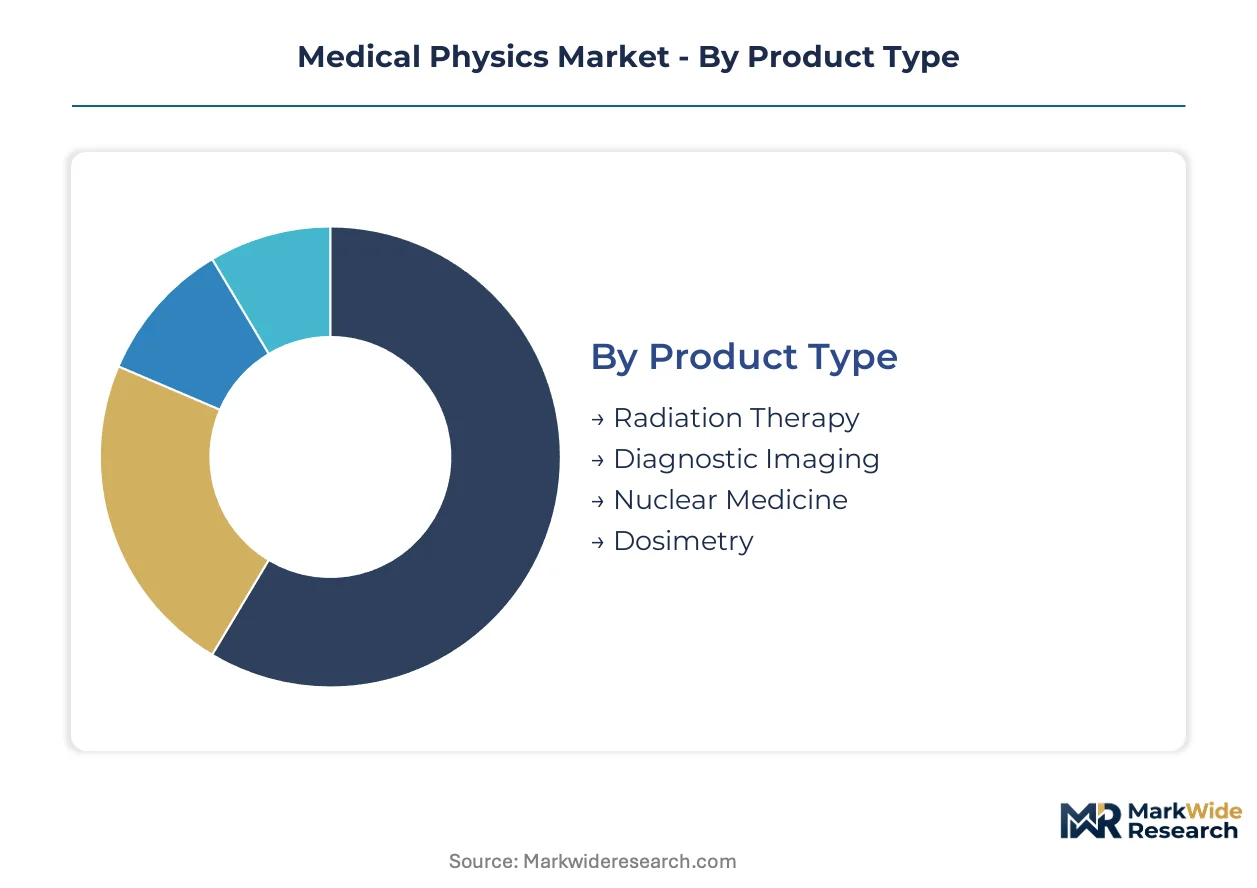
Medical physics services fragment across equipment modalities, institutional settings, and regulatory compliance tiers. Each segment carries distinct physics labor intensity, certification requirements, and vendor concentration patterns that shape contract economics.
Product Type:
Supply concentration in proton beam commissioning and AI-enhanced diagnostic protocols is reshaping which product categories command premium physics staffing.
- Radiation Therapy:Linear accelerator calibration, proton beam modeling, and patient-specific dosimetry verification absorb the majority of board-certified therapeutic physicist hours. United States academic medical centers are building dedicated physics teams for heavy-ion programs, tightening specialist availability for community hospitals.
- Diagnostic Imaging:MRI field uniformity mapping, CT dose optimization algorithms, and spectral imaging reconstruction protocols are climbing the fastest as 3T and 7T systems multiply. India's private hospital chains in Mumbai and Delhi are installing advanced scanners faster than qualified physics support can scale.
- Nuclear Medicine:PET scanner calibration and radiopharmaceutical dose verification require dual FDA and NRC compliance pathways.
- Dosimetry:Personnel monitoring services and phantom-based absorbed dose measurements concentrate in accredited laboratory networks with extensive certification infrastructure.
Today's leader: Radiation Therapy. Tomorrow's challenger: Diagnostic Imaging.
Technology:
Cost tier differentiation separates capital-intensive modalities requiring dedicated physics teams from portable systems with standardized calibration protocols.
- MRI:Superconducting magnet field homogeneity verification, RF coil calibration, and artificial intelligence reconstruction validation demand physicists with specialized magnetic resonance training. European university hospitals are embedding physics oversight into MDR conformity documentation for software-driven sequences.
- CT:Iterative reconstruction algorithm validation, dose modulation protocol optimization, and spectral imaging quality assurance are expanding physics workloads as dual-energy systems proliferate. Germany's notified bodies are mandating physicist-signed validation reports for machine learning-based reconstruction software.
- X-ray:Mammography unit calibration and interventional fluoroscopy dose monitoring follow standardized protocols with lower specialist intensity.
- Ultrasound:Transducer characterization and thermal index verification require less capital equipment but growing attention to AI-enhanced image processing.
- PET:Detector calibration, attenuation correction validation, and quantitative imaging biomarker standardization bridge nuclear medicine and diagnostic imaging physics domains.
Volume concentrates in CT installations. Margin expansion concentrates in MRI and PET physics services.
Application:
Customer type stratification distinguishes between captive hospital physics departments and contracted service vendors serving multi-site networks.
- Patient Care:Direct clinical physics support for treatment planning, image-guided procedures, and real-time dose monitoring absorbs senior physicist capacity in radiation oncology programs. United States health systems are unbundling equipment service contracts from physics staffing agreements, driving price transparency in procurement.
- Quality Assurance:Regulatory audit preparation, accreditation maintenance, and routine equipment performance testing concentrate in outsourced service models for smaller institutions. Telephysics platforms are extending specialist-level QA coverage to rural cancer centers without relocation costs.
- Research:Novel imaging biomarker validation, clinical trial dosimetry, and grant-funded protocol development are capturing disproportionate physics talent as competitive differentiation in academic funding intensifies.
- Calibration:Traceable standard maintenance and inter-institutional measurement harmonization anchor physics service vendor relationships with equipment manufacturers.
Procurement gravity centers on Patient Care. Regulatory pressure is concentrating investment in Quality Assurance.
End User:
Maturity gradients separate integrated academic networks with captive physics departments from community institutions dependent on contracted services.
- Hospitals:Large health systems in the United States are expanding in-house medical physics departments to support precision radiation therapy programs, tightening vendor relationships. The FDA's updated 21 CFR Subchapter J quality management requirements are compelling permanent physics oversight rather than episodic external audits.
- Research Institutions:Grant-funded proton centers and imaging research cores are capturing board-certified physicists through competitive compensation and publication opportunities, draining community hospital recruitment pools.
- Clinics:Independent oncology practices face equipment cost concentration that only consolidated systems can absorb, squeezing market access and physics service affordability.
- Academic Facilities:CAMPEP-accredited residency programs and ABR certification pathways are failing to match retirement rates among senior therapeutic physicists, extending credentialing timelines.
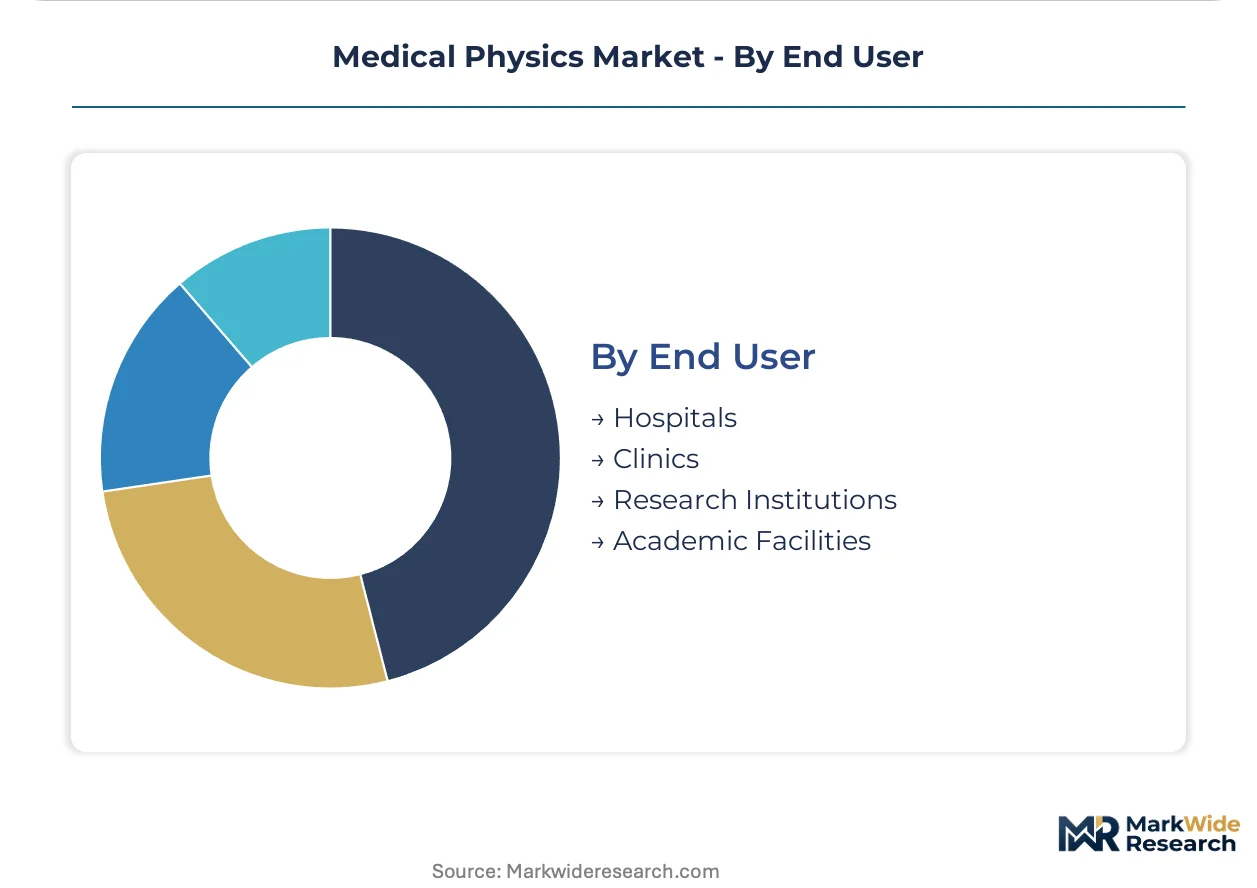
Staffing dominance sits with Hospitals. Talent competition is intensifying with Research Institutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States academic medical centers are expanding proton therapy infrastructure faster than board-certified physicist supply can match, tightening specialist labor markets across radiation oncology programs.
United States
Academic medical centers in Houston, Boston, and Philadelphia are commissioning heavy-ion therapy facilities requiring dedicated physics teams for beam modeling. The FDA enforces 21 CFR Subchapter J quality management standards on radiation-emitting devices, compelling hospitals to maintain permanent in-house physics oversight. The southeastern United States hosts expanding oncology networks negotiating separate procurement contracts for equipment service and clinical physics staffing.
Germany
University hospitals in Heidelberg and Munich are validating Monte Carlo dose algorithms for proton beam quality assurance under EU MDR conformity assessment timelines. Germany's notified bodies mandate physicist-signed validation reports for machine learning-based treatment planning software. The Heidelberg Ion Beam Therapy Center anchors European heavy-ion physics expertise, drawing specialist talent from across the continent.
India
Private hospital chains in Mumbai, Delhi, and Bangalore are installing 3T MRI and spectral CT systems faster than qualified diagnostic imaging physicists can scale. The Central Drugs Standard Control Organization oversees medical device registration while state-level atomic energy regulators govern radiation safety compliance. Maharashtra's private oncology networks are pioneering telephysics service models to extend specialist coverage to tier-two cities.
Japan
Heavy-ion centers in Chiba and Hyogo prefectures require dedicated physics teams for carbon beam commissioning and daily quality assurance protocols. The Ministry of Economy, Trade and Industry coordinates national proton therapy expansion under post-Fukushima radiation safety frameworks. The Chiba-based National Institute of Radiological Sciences anchors Asia-Pacific heavy-ion physics research, training specialists for domestic and regional facilities.
United Kingdom
NHS trusts in London and Manchester are unbundling linear accelerator service contracts from physics staffing agreements to drive procurement transparency. The Medicines and Healthcare products Regulatory Agency enforces UKCA marking requirements on radiation-emitting devices post-Brexit. The Christie NHS Foundation Trust in Manchester maintains one of Europe's largest captive medical physics departments for precision radiation therapy.
Medical Physics Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue AI-enhanced diagnostic validation and remote service delivery models. The vendor base concentrates around three strategic archetypes: legacy dosimetry laboratories with extensive accreditation networks, imaging OEMs bundling physics support with equipment contracts, and regional service specialists holding exclusive long-term agreements. Dominant competitive moves include unbundling of previously packaged service contracts and geographic expansion through telephysics platforms.
Among legacy dosimetry specialists, LANDAUER represents the accredited laboratory archetype with personnel monitoring infrastructure spanning multiple countries. GE Healthcare exemplifies the equipment-anchored service model, leveraging imaging installed base relationships to bundle physics support with maintenance contracts. Medical Physics Services LLC occupies the regional specialist position, securing exclusive long-term agreements with southeastern United States oncology networks.
| Leading Market Players |
|---|
| LANDAUER |
| Medical Physics Services LLC |
| Krueger-Gilbert Health Physics Inc. |
| GE Healthcare |
| Radiation Safety & Control Services Inc. |
| Alyzen Medical Physics Services |
| Upstate Medical Physics Services |
| Versant Medical Physics Services & Radiation Safety |
| Alliance Medical Physics Services LLC |
| Others |
Value Chain & Pricing Dynamics
Superconducting niobium-titanium wire pricing volatility cascades through proton cyclotron construction into three-tier physics service contracting across United States academic medical centers, where equipment-anchored bundles from OEMs command premiums over unbundled staffing arrangements.
Pricing Analysis
Input-cost pass-through from rare-earth magnet materials and specialized detector components intensifies pricing pressure on proton beam commissioning services. Three-tier pricing structure across premium, standard, and economy levels separates CAMPEP-accredited academic teams from regional contract vendors and telephysics platforms. Price differentiation hinges on certification tier and geographic delivery cost, with board-certified therapeutic physicist scarcity pushing premium tier upward. Community hospitals exhibit highest price sensitivity, while research institutions absorbing grant overhead show lowest.
Supply Chain Analysis
Reverse-logistics flows for refurbished linear accelerator components and remanufactured MRI gradient coils concentrate secondary market activity in Germany, Japan, and the United States. Physics service supply draws from superconducting magnet manufacturers, ionization chamber calibration laboratories, and radiation detection sensor foundries. Single-source vulnerability sits with CAMPEP-accredited residency programs failing to match physicist retirement rates. Distribution runs through equipment OEM service networks, regional specialist contractors, and emerging telephysics platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Medical physics services function as a geographic-arbitrage play between United States specialist labor scarcity and India's rapidly scaling diagnostic imaging infrastructure, where regulatory compliance costs diverge by an order of magnitude.
For Market Incumbents: Hedge against physicist talent drain by embedding training pipelines into CAMPEP-accredited residency partnerships and securing exclusive long-term agreements with heavy-ion therapy centers before competitor entry. Backward integration into personnel dosimetry laboratory accreditation networks defends margin position against emerging telephysics platforms.
For New Entrants and Emerging Players: The price-point gap between premium academic physics departments and economy-tier community hospital contracts exceeds viable entry threshold for AI-enhanced diagnostic validation services targeting India's private hospital chains in tier-two cities. White-space concentration sits with remote beam data analysis for rural United States cancer centers and EU MDR conformity documentation for machine learning-based treatment planning software vendors.
For Investors and Strategic Acquirers: Consolidation pressure builds where credentialing timeline compression meets equipment cost concentration squeezing independent oncology practices from addressable market. Long-term viability favors regional service specialists with captive hospital relationships and telephysics platforms with scalable software validation protocols. Signal to watch: FDA enforcement intensity on 21 CFR Subchapter J episodic audit exemptions.
| Strategic Initiative | Industry Significance |
|---|---|
| Telephysics Platform Deployment | Extends specialist-level beam analysis to rural cancer centers without relocation costs. |
| CAMPEP Residency Pipeline Investment | Secures board-certified physicist supply for heavy-ion therapy expansion programs. |
| EU MDR Conformity Documentation Service | Captures mandated physics validation demand from German and French software vendors. |
| Equipment Service Contract Unbundling | Drives procurement transparency for United States health system physics staffing. |
| India Diagnostic Imaging Physics Scale-Up | Addresses qualified physicist shortage in Mumbai and Delhi private hospital chains. |
Study Parameters
Bottom-up hospital procurement modeling reconciled against top-down equipment installed base tracking forms the analytical core of this study. Primary interviews with radiation oncology department heads, hospital purchasing committee members, biomedical engineers, and GPO contracts managers combined with secondary validation from FDA 21 CFR Subchapter J enforcement records, NRC radioactive material licensing databases, CMS Medicare reimbursement data, and hospital procurement system disclosures. Triangulation across stakeholder perspectives and data sources ensures dimensional accuracy.
Historical trendline analysis of linear accelerator and proton center commissioning rates established baseline growth parameters across the projection horizon. Segmentation modeling incorporated product type, technology modality, application purpose, and end-user institutional tier, with regional regulatory framework clusters as an industry-specific dimension. CAGRs derived from equipment replacement cycles, physicist workforce expansion rates, and reimbursement policy trajectories, with Monte Carlo algorithm adoption and AI-enhanced reconstruction validation as forecast inputs.
Caveats apply where FDA quality system rule enforcement intensity or NRC licensing pathway modifications could materially shift the outlook. Practitioners should monitor CAMPEP residency slot expansion and heavy-ion center construction permits for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Global Medical Power Supply Market
Medical Equipment
Medical Carts and Workstations Market
Medical Equipment
North America Nuclear Medicine Equipment Market
Medical Equipment
Birthing Beds Market
Medical Equipment
Air Fluidized Therapy Beds Market
Medical Equipment
Brazil Massage Equipment Market
Medical Equipment
Minor Surgical Lights Market
Medical Equipment
North America Medical Carts Market
Medical Equipment
Medical X-Ray Generators Market
Medical Equipment
Medical Whirlpool Market
Medical Equipment
Water Bath Market
Medical Equipment
Global Platelet Incubator Market
Medical Equipment
Medical Equipment Maintenance Market
Medical Equipment
Global Hospital Equipment and Supplies Market
Medical Equipment
US Biomedical Refrigerators and Freezers Market
Medical Equipment
Urodynamics Equipment and Disposables Market