
 Autopsy Saw Market | 2026-2036
Autopsy Saw Market Size, Share, and Industry Trends Forecast 2026-2036
Autopsy Saw Market Analytics
Forensic laboratories is decoupling from hospital pathology departments as the dominant procurement channel for autopsy saws. Stryker leverages its orthopedic power tool heritage to transfer battery and motor control systems into mortuary applications. Mopec sustains a specialized catalog focused entirely on post-mortem equipment, giving it channel control across North American medical examiner offices. DeSoutter Medical anchors European supply through its surgical power tool manufacturing scale, competing on CE-marked certification depth.
An autopsy saw is a powered or hand-operated cutting instrument designed to section bone and cartilage during post-mortem examinations, typically featuring oscillating or reciprocating blades at speeds between 15,000 and 22,000 oscillations per minute to prevent soft tissue damage. The device serves forensic pathologists, anatomical researchers, and hospital dieners who require precise cranial and thoracic access without aerosolizing biological material. Electric saws dominate installed base value due to sustained torque output in high-throughput forensic settings, while battery-operated units represent the fastest-growing operation mode as facilities prioritize cord-free maneuverability and infection control. Stainless steel blade demand concentrates where regulators mandate autoclave sterilization compatibility, leaving composite material handles as a margin pool for differentiation.
FDA 510(k) clearance requirements and EU MDR Class I device rules shape product development timelines and material traceability obligations for manufacturers selling into the United States and European Union. ISO 13485 quality management certification operates as a de facto market access threshold for contract tenders issued by government forensic services and academic medical centers. Stakeholders must monitor how battery chemistry regulations from ECHA and transport safety rules from IATA reshape cordless product distribution economics.
Market Dynamics
Forensic laboratories are decoupling from hospital pathology departments as the dominant procurement channel for autopsy saws, driven by tightening post-mortem examination protocols and centralized medical examiner system expansion across jurisdictions.
Growth Catalysts
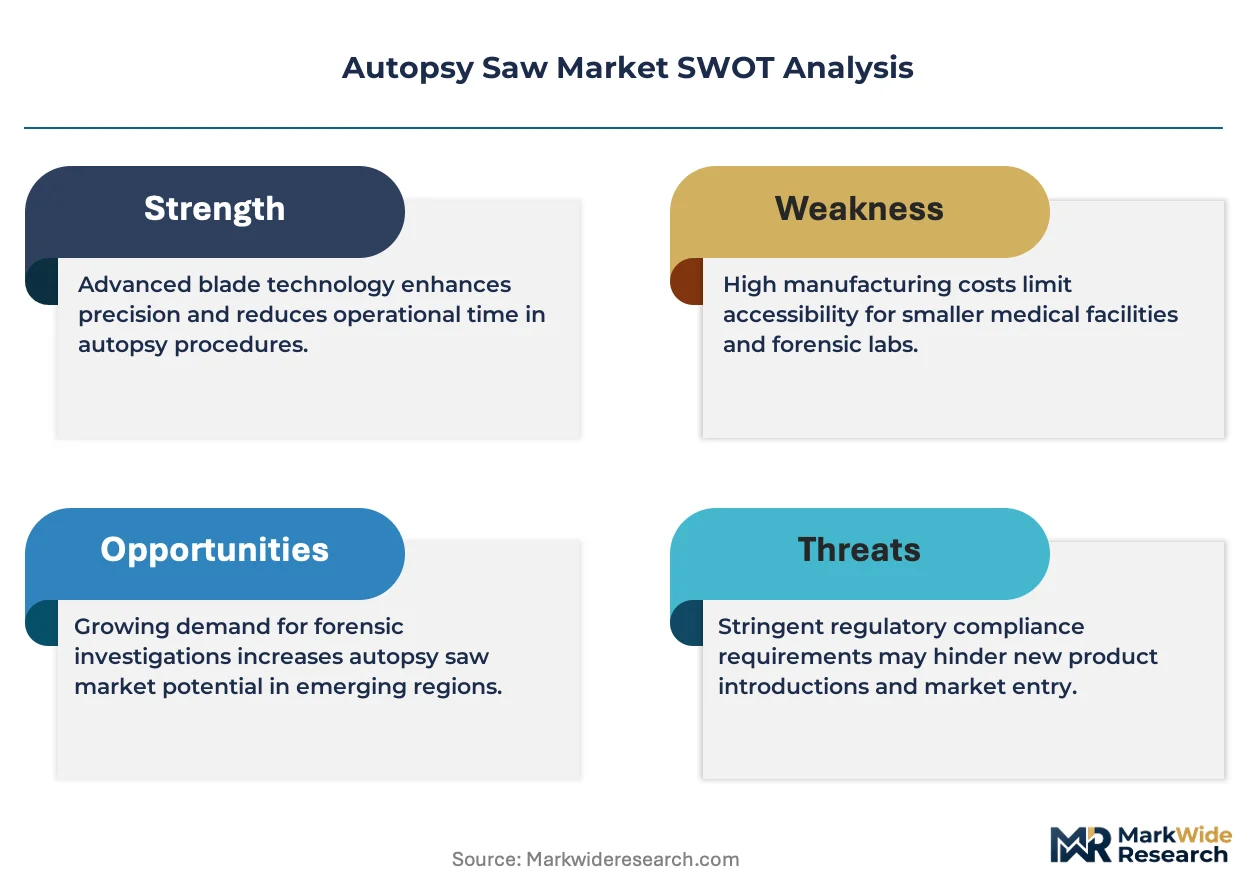
- EU MDR blade mandates:Stainless steel certification requirements under EU MDR Class I device rules are forcing material upgrades across European supply chains, accelerating replacement cycles in forensic laboratories.
- Battery chemistry advancement:Lithium-ion cell density improvements are enabling cordless autopsy saws with sustained torque output, expanding adoption in mobile forensic units and field examination settings.
- Japan's forensic infrastructure:Centralized medical examiner system consolidation in Japan is standardizing procurement specifications and creating volume demand for certified autopsy equipment.
Market Restraints
- Stainless steel supply concentration:Surgical-grade stainless sourcing concentrates in German and Japanese specialty mills, exposing manufacturers to input cost volatility and extended lead times.
- FDA 510(k) timeline friction:FDA clearance requirements for powered surgical instruments extend product development cycles by 12-18 months, compressing returns on R&D investment for device innovators.
- Manual saw substitution:Low-cost oscillating hand saws retain share in resource-constrained pathology departments, particularly in emerging forensic systems with limited capital budgets.
Strategic Opportunities
- Germany's forensic network expansion:Federal-state coordination on medical examiner office modernization is creating tender volume for CE-marked, ISO 13485-certified autopsy equipment suppliers.
- Autoclave-compatible composite handles:Polymer-ceramic hybrid materials that withstand sterilization protocols without thermal degradation offer differentiation in infection-control-sensitive procurement.
- United States federal forensic grants:Department of Justice funding streams for state and local medical examiner systems are channeling capital toward equipment standardization and facility upgrades.
Industry Challenges
- Forensic pathologist workforce gaps:Board-certified practitioner shortages in the United States and Europe are delaying facility commissioning and equipment utilization rates.
- ISO 13485 certification burden:Quality management system implementation costs and audit complexity create barriers for mid-tier manufacturers seeking government contract eligibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autopsy Saw Market |
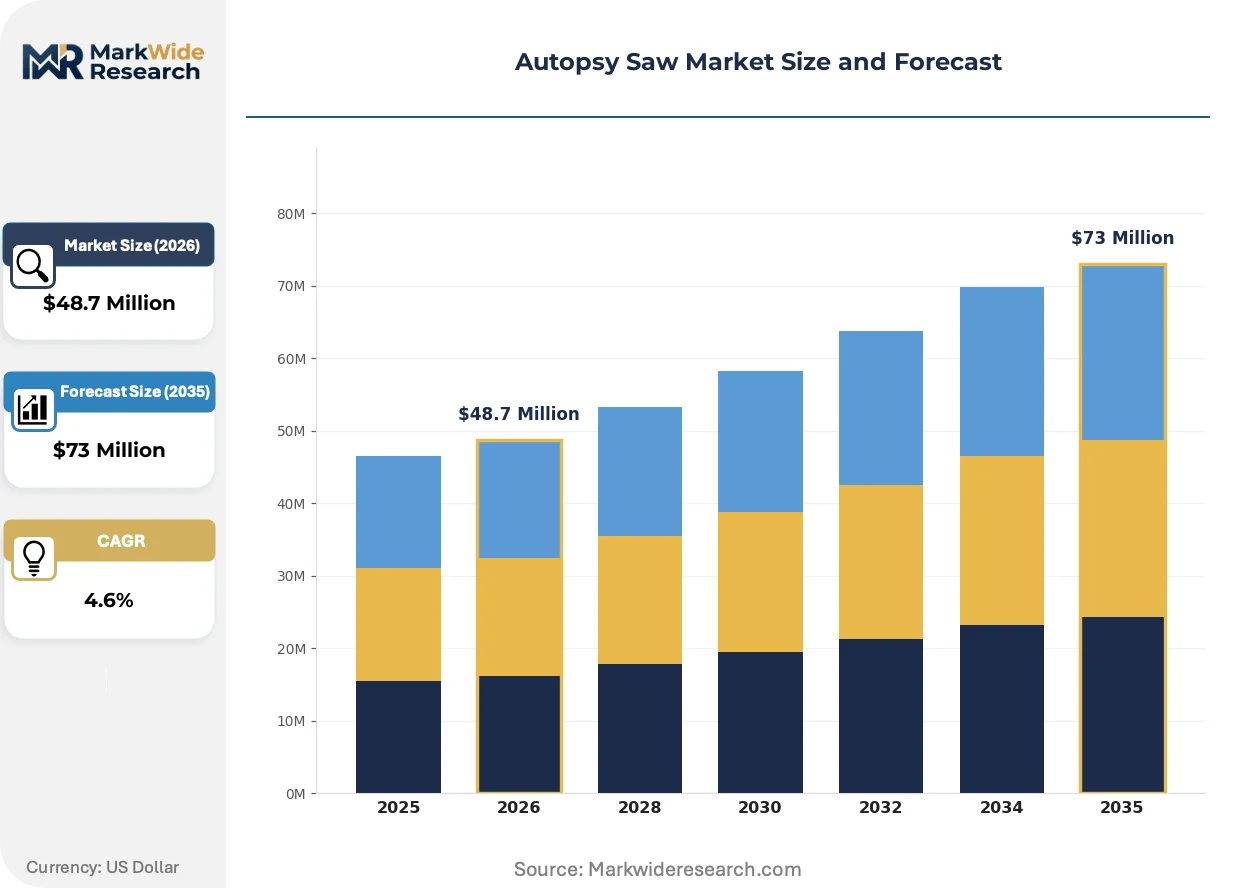
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $73 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Saw, Pneumatic Saw, Manual Saw, Hybrid Saw End User: Forensic Laboratories, Hospitals, Medical Schools, Research Institutions Material: Stainless Steel, Carbon Steel, Plastic, Composite Material Operation Mode: Automated, Semi-Automated, Manual, Battery Operated |
| Companies Covered | Stryker, Medezine, Mopec, TEKNO, Dimeda Instrumente, KUGEL Medical, Thalheimer Khlung, Mortech Manufacturing, DeSoutter Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autopsy Saw Market Evolving Landscape
Active innovation in autopsy saw technology centers on motor control systems, material traceability, and procurement channel restructuring as forensic infrastructure modernizes.
Brushless DC motor controllers with integrated torque feedback are automating blade speed modulation during cranial sectioning, reducing operator skill dependency. High-throughput forensic laboratories in the United States and Germany are adopting these systems to standardize cut quality across rotating diener staff. The technology is automating workforce training compression and enabling facilities to maintain throughput during personnel transitions.
EU MDR Class I device rules now mandate full material traceability for surgical power tools, including batch-level stainless steel certification and supply chain documentation. Manufacturers serving European forensic laboratories must implement quality management systems with supplier audit protocols and component genealogy tracking. Small-to-mid-tier device producers without existing orthopedic surgical tool heritage face compliance cost barriers that favor scaled CE-marked competitors.
Centralized purchasing consortia in the United States are consolidating autopsy equipment procurement under state medical examiner office contracts, displacing hospital pathology department independent buying. These consortia negotiate multi-year supply agreements with ISO 13485-certified vendors, bundling saws with maintenance service and blade replenishment. The shift is most visible in states with unified forensic systems such as Maryland and New Mexico, where standardization reduces per-unit acquisition costs.
Autopsy Saw Market Segmentation
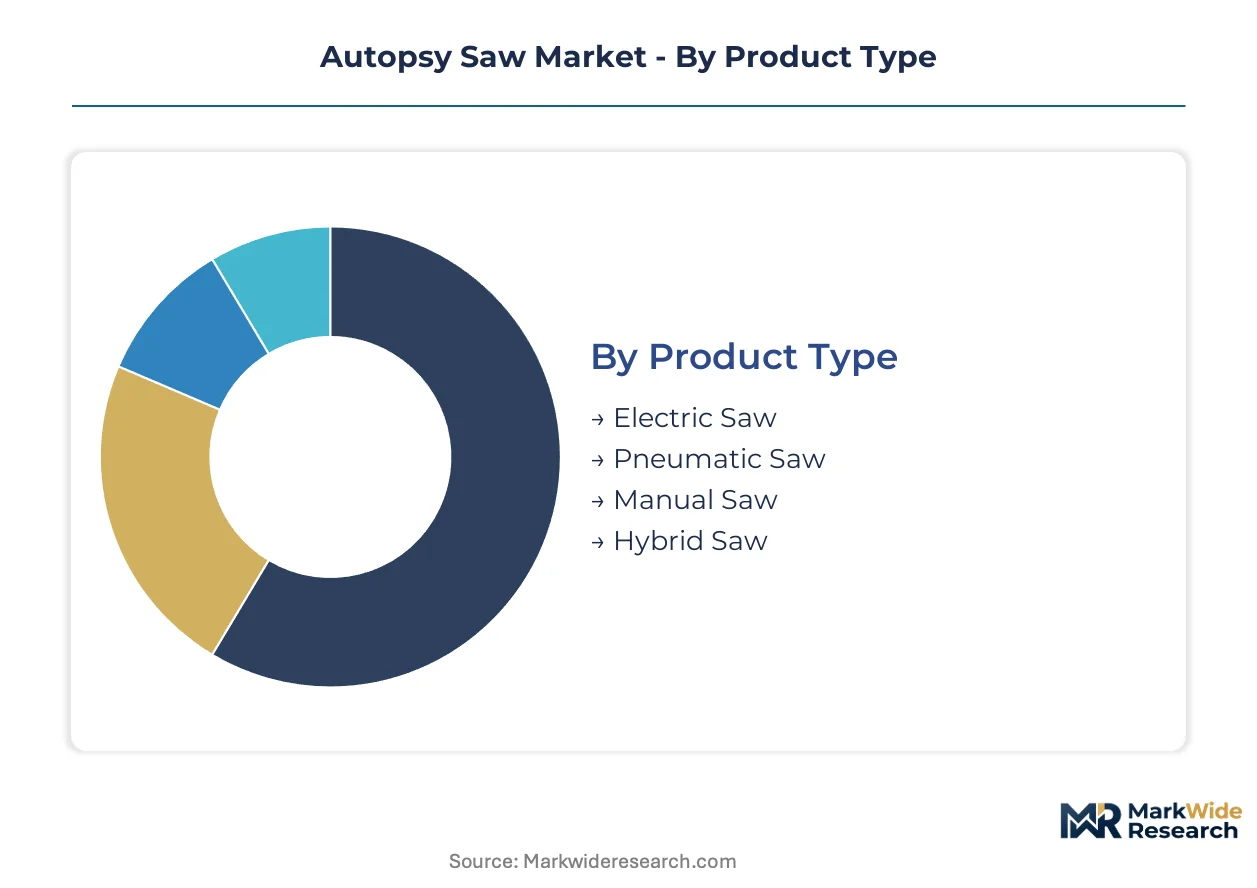
Autopsy saw procurement channels diverge sharply across product categories, with certification requirements and sterilization protocols determining which segments qualify for government forensic tenders versus hospital capital budgets. Material traceability mandates under EU MDR and FDA 510(k) rules create tiered market access that reshapes competitive positioning within each segment category.
Product Type:
Electric saws carry the heaviest certification burden, requiring FDA 510(k) clearance and ISO 13485 quality systems for US forensic laboratory contracts, while pneumatic variants face lighter regulatory scrutiny in jurisdictions with less stringent powered surgical tool classifications.
- Electric Saw:Brushless DC motor systems deliver sustained torque at 15,000-22,000 oscillations per minute for cranial sectioning. Demand concentrates in high-throughput forensic laboratories across the United States and Germany where standardized protocols require consistent cut quality across rotating staff.
- Pneumatic Saw:Compressed air-driven units eliminate electrical spark hazards in volatile environments and reduce motor maintenance cycles. Medical examiner offices in Japan favor these systems for integration with centralized facility infrastructure where compressed air lines are standard.
- Manual Saw:Oscillating hand saws serve resource-constrained pathology departments with minimal capital budgets and no powered tool maintenance capabilities.
- Hybrid Saw:Convertible electric-pneumatic designs address facilities with intermittent power reliability or mixed infrastructure requirements.
Electric saws sit at the top of the volume ranking, with battery-operated configurations climbing the fastest as forensic mobility requirements expand.
End User:
Customer type determines pricing tolerance and contract structure, with government forensic services negotiating multi-year bundled agreements while academic institutions prioritize capital cost minimization over lifecycle service.
- Forensic Laboratories:Centralized medical examiner systems in Maryland, New Mexico, and Japan's consolidated prefectural networks drive standardization mandates and ISO 13485-certified vendor requirements.
- Hospitals:Pathology departments decouple from forensic procurement as separate capital budgets and JCAHO infection control protocols reshape purchasing criteria.
- Medical Schools:Anatomical training programs prioritize cost efficiency and basic sterilization compatibility over advanced motor control features.
- Research Institutions:Specimen processing facilities require specialized blade geometries for non-standard anatomical studies.
Forensic laboratories command the dominant revenue share, with research institutions expanding most quickly as anatomical donation programs proliferate.
Material:
Supply concentration in German and Japanese specialty steel mills creates input cost volatility that segments the market between autoclave-compatible premium tiers and disposable economy alternatives.
- Stainless Steel:Surgical-grade 440C and 17-4 PH alloys withstand repeated autoclave cycles at 134°C without corrosion or edge degradation. EU MDR Class I device rules mandate batch-level material certification, forcing forensic laboratories across Germany and France to specify certified stainless for blade procurement.
- Carbon Steel:Higher hardness ratings enable sharper initial edges but require more frequent replacement due to oxidation susceptibility in humid mortuary environments.
- Plastic:Glass-reinforced polymer handles reduce thermal conductivity and improve grip security during extended procedures.
- Composite Material:Ceramic-polymer hybrids withstand sterilization without thermal degradation, offering differentiation in infection-control-sensitive tenders.
Stainless steel dominates procurement volume, with composite materials gaining share fastest as handle innovation accelerates.
Operation Mode:
Power source selection reflects workforce mobility requirements and facility infrastructure, with cordless systems commanding premium positioning despite battery chemistry regulatory complexity from ECHA and IATA transport rules.
- Automated:Integrated torque feedback systems modulate blade speed during tissue contact, reducing operator skill dependency in high-throughput settings.
- Semi-Automated:Preset speed profiles with manual override capability balance standardization with procedural flexibility.
- Manual:Direct mechanical control without powered assistance serves field examination units and backup redundancy requirements.
- Battery Operated:Lithium-ion cell density improvements enable sustained torque output without cord constraints, expanding adoption in mobile forensic units and temporary morgue facilities.
Automated systems lead installed value, with battery-operated units expanding most quickly as field examination protocols proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers face divergent compliance costs across jurisdictions, with EU MDR certification burdens pushing some procurement toward FDA-cleared US suppliers while Japanese specialty steel sourcing creates input advantages for Asia-Pacific fabricators.
United States
Centralized medical examiner systems in Maryland and New Mexico are consolidating equipment procurement under state-level contracts. DOJ federal forensic grants channel capital toward standardized autopsy equipment. The Southeast forensic corridor spanning Florida and Georgia is expanding regional morgue capacity to handle migration-driven caseload increases.
Germany
Federal-state coordination on medical examiner office modernization is generating tender volume for CE-marked devices. EU MDR Class I device rules mandate batch-level stainless steel certification, forcing blade specification upgrades. The Baden-Württemberg surgical instrument cluster around Tuttlingen supplies precision-manufactured power tool components to mortuary equipment assemblers.
Japan
Prefectural consolidation of forensic services is standardizing procurement specifications across 47 prefectures. METI industrial standards for powered surgical tools create certification alignment with autopsy saw requirements. The Chubu region around Nagoya hosts specialty steel mills producing surgical-grade alloys for blade manufacturers serving domestic and export markets.
United Kingdom
Home Office funding for forensic pathology modernization is replacing aging equipment in regional mortuaries. MHRA device registration requirements parallel EU MDR traceability mandates post-Brexit. The London-Southeast corridor concentrates academic medical centers and forensic science service laboratories driving replacement demand.
France
ANSM medical device oversight enforces sterilization compatibility standards for autopsy equipment in university hospital networks. Ministry of Justice programs are upgrading forensic institute infrastructure in Île-de-France and regional capitals. The Auvergne-Rhône-Alpes medical technology cluster supports component sourcing for powered surgical instrument producers.
Autopsy Saw Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated procurement channels favoring ISO 13485-certified vendors while hospital pathology departments sustain fragmented purchasing. Three archetypes dominate: orthopedic power tool heritage players transferring surgical motor systems, dedicated mortuary equipment specialists controlling forensic channel relationships, and regional surgical instrument fabricators competing on CE-mark certification depth. Competitive moves center on multi-year service bundling and material traceability system implementation to satisfy EU MDR documentation requirements.
Among heritage surgical power tool players, Stryker and DeSoutter Medical occupy positions leveraging orthopedic device manufacturing scale into mortuary applications. Mopec represents the specialized mortuary equipment archetype with catalog focus entirely on post-mortem infrastructure. These three exemplify how certification depth and channel control determine access to centralized forensic procurement contracts.
| Leading Market Players |
|---|
| Stryker |
| Medezine |
| Mopec |
| TEKNO |
| Dimeda Instrumente |
| KUGEL Medical |
| Thalheimer Khlung |
| Mortech Manufacturing |
| DeSoutter Medical |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap surgical instrument fabricators in Germany's Tuttlingen cluster anchor blade production, transmitting stainless steel cost volatility directly into forensic laboratory procurement budgets while maintaining pricing discipline through ISO 13485 certification premiums.
Pricing Analysis
Distributor margins of 18-25% separate OEM pricing from end-user acquisition costs across North American medical examiner systems. Three-tier pricing structure across premium brushless-motor systems, standard electric units, and economy manual saws reflects certification grade and after-sales bundling intensity. Cost compression in economy tiers intensifies because low-cost Asian hand saws capture share in budget-constrained pathology departments. Academic medical schools exhibit highest price sensitivity, while centralized state forensic systems prioritize lifecycle service over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with German and Japanese specialty steel mills supplying surgical-grade 440C and 17-4 PH alloys for autopsy saw blades. Component sourcing draws from China's motor assembly plants, Switzerland's precision bearing manufacturers, and Italy's polymer handle molders. Tariff exposure on Chinese battery cells creates distribution risk for cordless product lines. Distribution runs through medical device distributors serving forensic consortia and direct OEM contracts with hospital purchasing committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The autopsy saw market functions as a stable compounder, with replacement cycles in centralized medical examiner systems generating predictable revenue streams regardless of macroeconomic volatility.
For Market Incumbents: Hedge against manual saw substitution by embedding torque feedback automation into mid-tier electric offerings, compressing the skill gap that protects low-cost alternatives. Secure backward integration into surgical-grade stainless sourcing through long-term offtake agreements with Tuttlingen-area mills, insulating margin pressure from German-Japanese steel supply concentration.
For New Entrants and Emerging Players: EU MDR Class I device rules in Germany and France open a window for CE-marked specialists without orthopedic heritage to capture share in forensic laboratory tenders. Target Japan's prefectural consolidation programs, where standardized procurement specifications reduce incumbent relationship advantages. Lead with autoclave-compatible composite handle differentiation to bypass stainless steel supply bottlenecks.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional surgical instrument fabricators lacking mortuary channel relationships but possessing CE-mark certification infrastructure. Five-to-ten-year viability rests on forensic infrastructure modernization waves in the United States and Japan. Monitor Department of Justice forensic grant disbursement velocity as inflection indicator for North American equipment replacement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | EU MDR compliance unlocks German and French government tender participation. |
| Battery Chemistry Certification | ECHA and IATA alignment enables cordless product distribution across European mobile forensic units. |
| Forensic Consortium Partnership | Multi-year service bundling with Maryland and New Mexico state systems secures replacement revenue. |
| Stainless Steel Supply Agreement | Long-term contracts with Nagoya-area mills reduce input cost volatility for blade manufacturing. |
| Torque Feedback Software Development | Automation features differentiate electric saws against manual substitution in high-throughput laboratories. |
Research Methodology
Direct dialogue with forensic pathologists, medical examiner office procurement directors, biomedical equipment technicians, and GPO contract managers grounded this analysis in operational reality. Secondary validation drew from FDA 510(k) clearance databases, EU MDR notified body documentation, hospital procurement records, and forensic laboratory capital expenditure disclosures. Bottom-up and top-down triangulation reconciled unit shipment estimates with aggregate market value assessments.
Bottom-up modeling segmented volume and value across the projection horizon by product type, end-user institution, material grade, and operation mode. CAGRs derived from historical replacement cycle analysis and procurement budget trajectories in centralized forensic systems. Industry-specific forecast inputs incorporated EU MDR implementation timelines and Department of Justice grant authorization patterns.
Revisions become necessary when battery transport regulations tighten, forensic pathologist workforce shortages delay facility commissioning, or stainless steel supply disruptions extend lead times beyond contractual windows. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Surgical Generators Market
Medical Equipment
US ECG Equipment Market
Medical Equipment
Bench-Top Dental Autoclaves Market
Medical Equipment
Medical Physics Market
Medical Equipment
Podiatry Equipment Market
Medical Equipment
Global Platelet Incubator Market
Medical Equipment
Faecal Extraction System Market
Medical Equipment
Tissue Processing Systems Market
Medical Equipment
Medical Oxygen Gas Cylinder Market
Medical Equipment
Global Intraoperative Radiation Therapy Market
Medical Equipment
Medical Ultrasonic Cleaners Market
Medical Equipment
Embedded Disinfection Cabinet Market
Medical Equipment
Global Blood Purification Equipment Market
Medical Equipment
Ultrasound Equipment Market
Medical Equipment
Global Stereotactic Radiosurgery (Gamma Knife) Market
Medical Equipment
Radiotherapy Motion Management Market