
 Global Cleanroom Disposable Gloves Market | 2026-2036
Global Cleanroom Disposable Gloves Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cleanroom Disposable Gloves Market Foresight
Single-use nitrile formulation chemistry is tilting toward accelerator-free and low-sulfur curing systems that reduce ionic contamination risks in sub-10 nanometer semiconductor nodes. Hartalega Holdings Berhad leverages its centralized Malaysian production complex to sustain cost leadership in nitrile output. Ansell Ltd. differentiates through validated sterile glove portfolios that anchor pharmaceutical and biotechnology contracts across North America and Europe. Kimberly-Clark Corporation controls hospital and diagnostic center channels with bundled cleanroom apparel and wipe programs that extend glove placement.
Cleanroom disposable gloves are single-use hand coverings manufactured from synthetic or natural polymers under ISO-certified conditions, with particle emission limits below specified thresholds and surface resistivity controls to prevent electrostatic discharge damage. Their primary purpose is to prevent human-borne particulate, ionic, and microbial contamination during sensitive manufacturing and testing operations. Nitrile formulations dominate volume shipments due to latex allergy elimination and superior puncture resistance, while neoprene segments command premium positioning in aggressive chemical environments within biotechnology and pharmaceutical applications. Electronics manufacturing applications drive fastest volume expansion as foundry and flat-panel display investments multiply cleanroom square footage across East Asia.
The FDA enforces Quality System Regulation and 510(k) requirements for medical-grade cleanroom gloves, while the EPA tracks solvent emissions from nitrile manufacturing processes, and ISO 14644-1 sets airborne particulate limits that directly dictate glove change-out protocols and material specifications. REACH in Europe restricts phthalate plasticizers and accelerators, compelling reformulation investments that favor suppliers with integrated polymer research capabilities. Stakeholders must monitor how dual carbon goals in China and extended producer responsibility frameworks in the EU reshape material sourcing, end-of-life processing costs, and the competitive viability of domestic versus Southeast Asian manufacturing bases.
Market Dynamics
Wafer fabrication scaling in Taiwan and South Korea is compressing glove change-out protocols while forcing material upgrades from vinyl to accelerator-free nitrile formulations that meet sub-10 nanometer contamination thresholds.
Growth Catalysts
- Semiconductor foundry expansion:Taiwan Semiconductor Manufacturing and Samsung Electronics are multiplying cleanroom square footage for advanced node production, directly amplifying glove procurement volumes for ISO Class 3-5 environments.
- FDA sterile processing guidance:Updated requirements for pharmaceutical aseptic manufacturing are mandating validated sterile glove portfolios, locking in multi-year supply contracts with certified manufacturers.
- Accelerator-free nitrile chemistry:Low-sulfur curing systems eliminate ionic contamination risks, enabling glove qualification for extreme ultraviolet lithography zones where particle control dictates yield.
Market Restraints
- Butadiene feedstock volatility:Nitrile rubber production depends on petrochemical supply chains concentrated in Middle Eastern and Southeast Asian refining complexes, exposing margins to crude price swings.
- Malaysian production concentration:Over half of global nitrile cleanroom glove output originates from Klang Valley manufacturing clusters, creating single-point vulnerability to port congestion or labor disruptions.
- REACH plasticizer restrictions:ECHA regulations on phthalate alternatives compel reformulation investments that disadvantage smaller compounders lacking integrated polymer research facilities.
Strategic Opportunities
- India pharmaceutical manufacturing:CDSCO's alignment with EU GMP standards and PLI scheme incentives for active pharmaceutical ingredient production are germinating cleanroom infrastructure buildouts in Hyderabad and Ahmedabad clusters.
- Biologics single-use systems:Cell and gene therapy manufacturing platforms require neoprene gloves for aggressive chemical compatibility, opening premium positioning beyond semiconductor applications.
- EU extended producer responsibility:France and Germany's packaging waste directives are creating first-mover advantage for suppliers offering closed-loop recycling programs with verified nitrile reprocessing.
Industry Challenges
- Cleanroom technician certification pipelines:ISO 14644 auditor and aseptic technique training programs face 18-month backlogs in the United States and Germany, constraining facility commissioning timelines.
- Dual carbon compliance costs:China's MEE enforcement of energy intensity targets is forcing nitrile manufacturers to retrofit steam recovery systems, compressing working capital for mid-scale producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cleanroom Disposable Gloves Market |
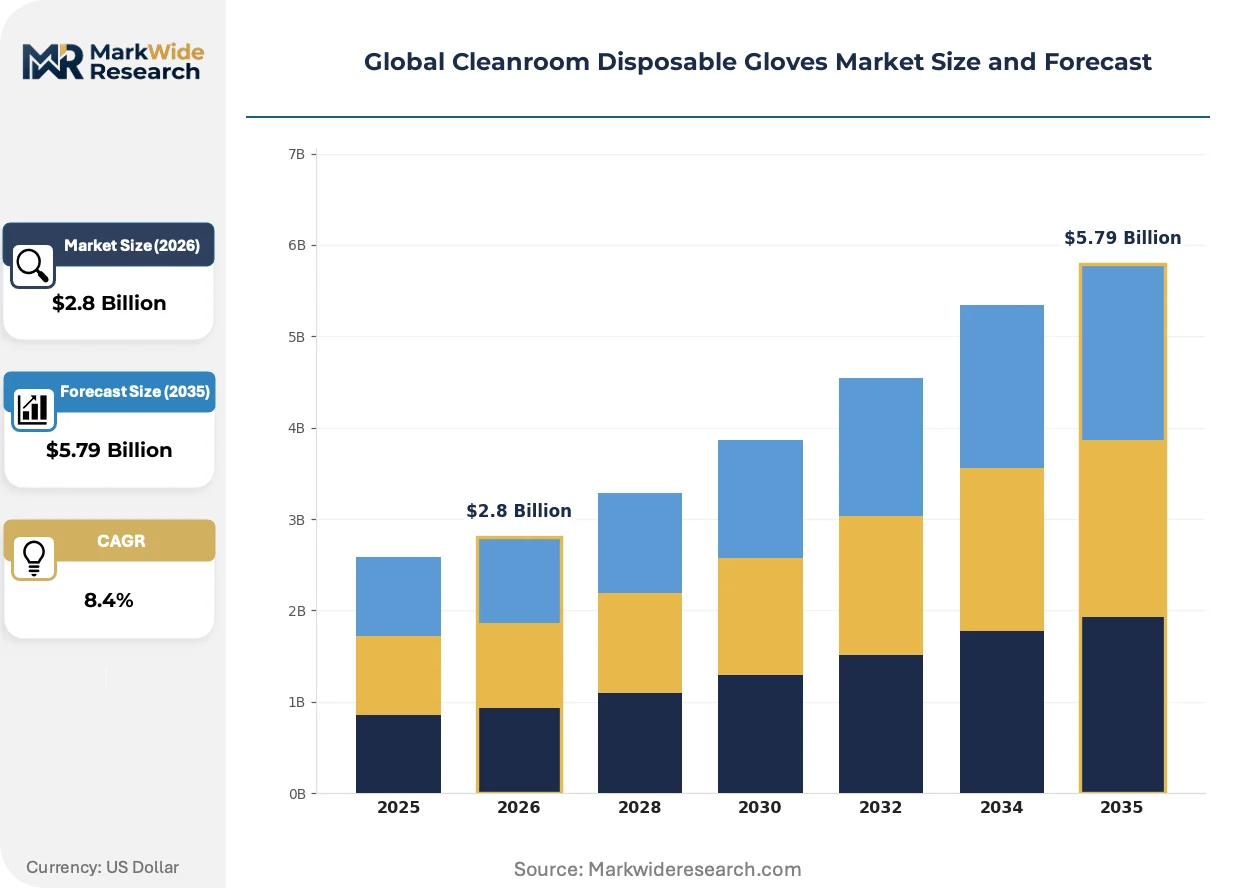
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Nitrile, Latex, Neoprene, Vinyl, Polyethylene Application: Pharmaceutical, Electronics Manufacturing, Biotechnology, Food Processing, Aerospace Assembly End User: Research Laboratories, Semiconductor Plants, Diagnostic Centers, Cleanroom Facilities, Quality Control Labs Packaging Type: Boxes, Cartons, Refill Packs, Bulk Bags, Dispenser Packs |
| Companies Covered | Kimberly-Clark Corporation, Hartalega Holdings Berhad, Ansell Ltd., Medline Industries, Inc., Supermax Corporation Berhad, Top Glove Corporation Bhd, Kossan Rubber Industries Bhd, Dynarex Corporation, Cardinal Health, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cleanroom Disposable Gloves Market Shifts & Advancements
Real-time contamination monitoring systems are digitizing glove integrity verification, compressing the gap between material science advances and quality assurance protocols across electronics and pharmaceutical cleanrooms.
Accelerator-free nitrile compounding is digitizing supply chain traceability requirements. Semiconductor fabs in Hsinchu and Pyeongtaek now mandate lot-level ionic contamination certificates with blockchain-verified chain of custody. This digitizing of specification compliance is displacing commodity glove tenders in favor of qualified supplier programs with multi-year validation cycles.
REACH Annex XVII expansions on thiuram and carbamate accelerators are eliminating conventional sulfur-cured nitrile from pharmaceutical packaging operations. EMA's tightened endotoxin limits for sterile medicinal products are forcing glove manufacturers to validate washing protocols with documented bioburden reduction. European biotechnology clusters in Basel and Leiden are responding by consolidating procurement around suppliers with dedicated pharmaceutical-grade production lines.
Consolidated procurement through group purchasing organizations is compressing distributor margins while amplifying volume concentration among top-tier manufacturers. Hospital systems in the United States and diagnostic laboratory networks in Germany are unbundling glove supply from bundled apparel programs, enabling direct manufacturer contracts with price transparency requirements. This disintermediation is most visible in North American healthcare procurement, where IDN consolidation has reduced qualified vendor lists from twelve to four suppliers per category.
Global Cleanroom Disposable Gloves Market Segmentation
Cleanroom glove procurement patterns diverge sharply across material chemistry and application environment, with semiconductor fabs demanding accelerator-free formulations while pharmaceutical operations prioritize validated sterile portfolios. Understanding segment turnover rates and specification intensity allows suppliers to align production cycles with customer change-out protocols.
Material:
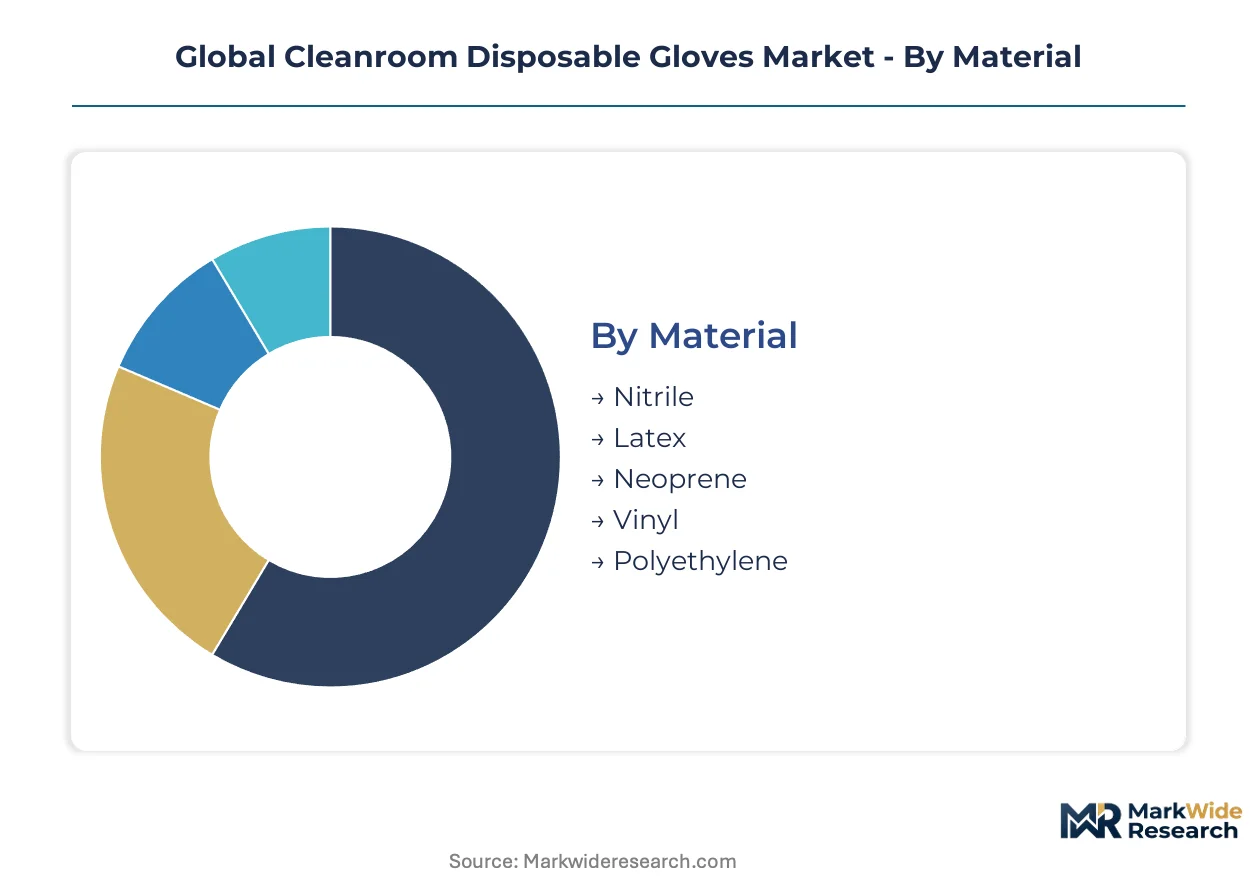
Nitrile formulations turn over fastest in ISO Class 3-5 electronics corridors where particle thresholds tighten with each node shrink, while vinyl persists in lower-grade environments with extended wear cycles. Cost tiers separate medical-grade certified production from industrial commodity streams.
- Nitrile:Accelerator-free and low-sulfur curing systems dominate sub-10 nanometer semiconductor applications, eliminating ionic contamination risks in EUV lithography zones. Taiwan Semiconductor Manufacturing and Samsung Electronics procurement in Hsinchu and Pyeongtaek drives fastest volume expansion for this chemistry.
- Neoprene:Aggressive chemical compatibility positions this synthetic rubber in biotechnology and pharmaceutical operations requiring resistance to solvents and cytotoxic agents. Basel and Leiden biotechnology clusters specify neoprene for cell and gene therapy manufacturing platforms.
- Latex:Natural rubber formulations retain niche positioning in non-allergenic controlled environments with established powder-free processing protocols.
- Vinyl:PVC-based gloves occupy cost-sensitive lower-classification cleanrooms with reduced particle control requirements and extended use durations.
- Polyethylene:Cast film construction serves single-use inspection and packaging tasks where tactile sensitivity is secondary to barrier protection.
Nitrile anchors the volume base while neoprene gains share at the steepest rate.
Application:
Electronics manufacturing commands premium pricing for contamination-critical node production, while food processing operates on compressed margins with standardized specifications. Customer concentration varies from consolidated foundry procurement to fragmented laboratory networks.
- Electronics Manufacturing:Wafer fabrication and flat-panel display production multiply cleanroom square footage across East Asian corridors. Foundry investments in Taiwan and South Korea outpace glove supply localization, forcing material upgrades from vinyl to nitrile.
- Pharmaceutical:Aseptic manufacturing mandates validated sterile glove portfolios with documented bioburden reduction protocols. FDA sterile processing guidance locks in multi-year supply contracts with certified manufacturers across North American and European operations.
- Biotechnology:Cell and gene therapy platforms require neoprene compatibility with aggressive chemical environments.
- Food Processing:HACCP-aligned operations specify standard nitrile for allergen control and color-coded contamination prevention.
- Aerospace Assembly:Satellite and avionics cleanrooms demand ESD-controlled formulations with surface resistivity specifications.
Electronics manufacturing commands the largest procurement volumes while biotechnology applications expand most quickly.
End User:
Semiconductor plants consolidate procurement through direct manufacturer contracts, while diagnostic centers fragment across distributor networks. Volume scale separates captive foundry supply from spot-purchasing laboratory environments.
- Semiconductor Plants:Integrated device manufacturers and pure-play foundries operate ISO Class 3-5 environments with compressed change-out protocols. Procurement concentrates among four qualified suppliers per category following IDN consolidation patterns.
- Research Laboratories:Academic and government facilities balance specification compliance with budget constraints across diverse contamination control needs.
- Diagnostic Centers:Clinical laboratory networks in Germany and the United States unbundle glove supply from bundled apparel programs.
- Cleanroom Facilities:Contract manufacturing organizations serve multiple client specifications with flexible inventory management.
- Quality Control Labs:Analytical and testing operations prioritize tactile sensitivity and chemical resistance for sample handling protocols.
Semiconductor plants anchor procurement concentration while diagnostic centers drive disintermediation trends.
Packaging Type:
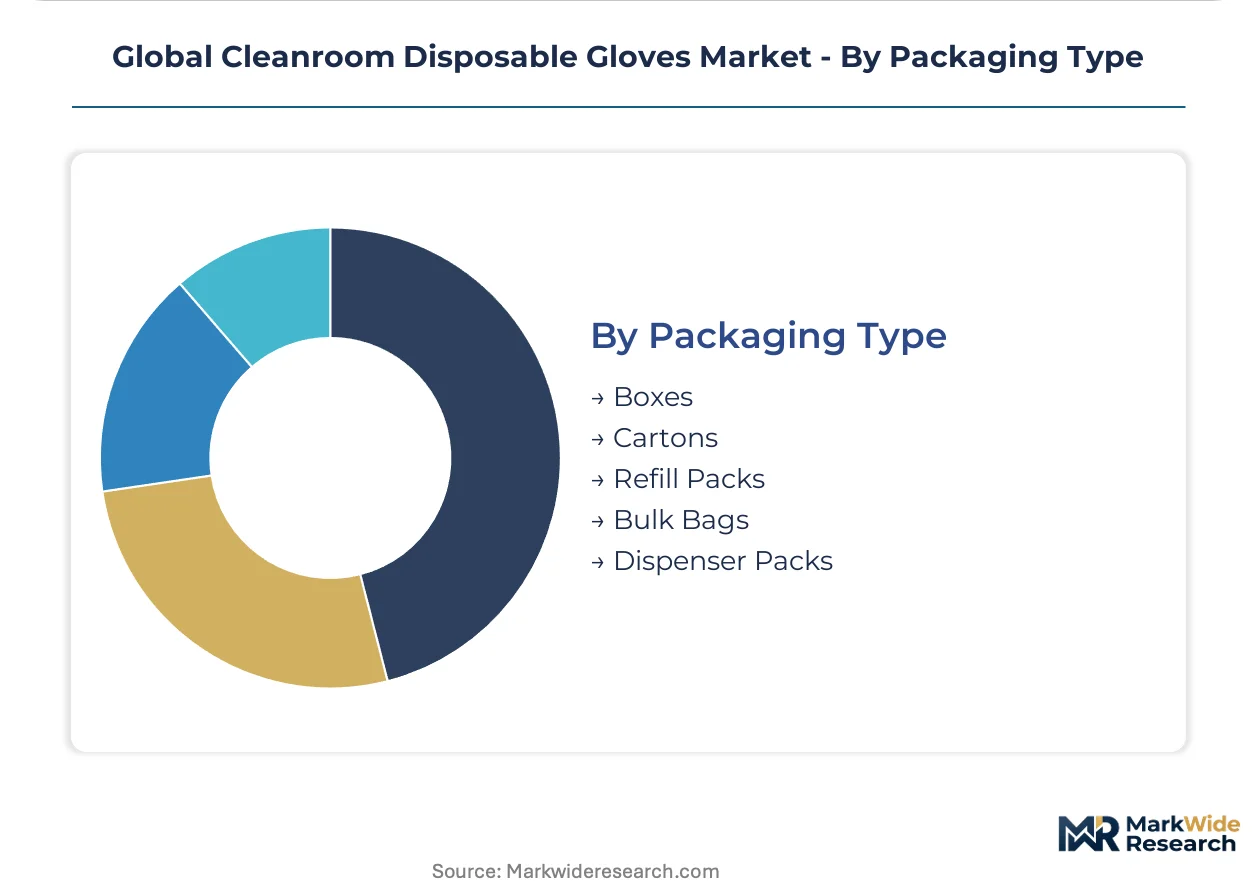
Carton and dispenser pack formats align with automated gowning systems in high-throughput semiconductor corridors, while bulk bags serve centralized sterilization operations. Packaging specification intensity tracks customer scale and integration depth.
- Boxes:Standard unit-of-issue packaging dominates hospital and diagnostic center channels with bundled cleanroom apparel programs.
- Cartons:Intermediate bulk formats balance handling efficiency with inventory rotation requirements.
- Refill Packs:Reduced-waste formats align with EU extended producer responsibility frameworks in France and Germany.
- Bulk Bags:Large-scale supply serves centralized sterilization facilities and automated dispensing systems.
- Dispenser Packs:Individual pair presentation supports aseptic technique compliance in pharmaceutical manufacturing.
Box formats anchor existing infrastructure while refill packs climb the fastest on sustainability mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysian manufacturers supply nitrile formulations to semiconductor fabs in Taiwan and South Korea, creating a concentrated trade corridor that shapes procurement patterns across East Asian electronics corridors. This export dependency exposes end-users to port congestion risks while reinforcing cost advantages for integrated producers.
United States
Hospital systems and diagnostic laboratory networks drive sterile glove procurement through consolidated IDN contracts. FDA Quality System Regulation and 510(k) requirements lock in multi-year supply agreements with validated manufacturers. The Greater Boston biotechnology cluster specifies neoprene compatibility for cell therapy manufacturing platforms.
Germany
EMA tightened endotoxin limits force glove manufacturers to document bioburden reduction protocols for pharmaceutical packaging operations. REACH Annex XVII restrictions on thiuram accelerators eliminate conventional sulfur-cured nitrile from sterile medicinal product lines. The Basel-Leiden corridor consolidates procurement around suppliers with dedicated pharmaceutical-grade production lines.
China
Dual carbon goals enforced by MEE compel nitrile manufacturers to retrofit steam recovery systems, compressing working capital for mid-scale producers. Wafer fabrication investments in the Yangtze River Delta outpace domestic glove supply localization, forcing material upgrades from vinyl to accelerator-free formulations.
South Korea
Samsung Electronics multiplies cleanroom square footage for advanced node production in Pyeongtaek, directly amplifying glove procurement volumes for ISO Class 3-5 environments. MFDS alignment with international GMP standards accelerates sterile processing infrastructure buildouts. The Seoul Capital Area concentrates foundry procurement through direct manufacturer contracts.
India
CDSCO alignment with EU GMP standards and PLI scheme incentives for active pharmaceutical ingredient production germinate cleanroom infrastructure buildouts. Hyderabad and Ahmedabad clusters emerge as procurement growth nodes. The national pharmaceutical regulator mandates documented validation protocols that favor certified suppliers.
Global Cleanroom Disposable Gloves Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered supply relationships. Bundled apparel programs and distributor networks characterize the hospital and diagnostic center segments, while semiconductor fabs consolidate procurement through direct manufacturer contracts. Three archetypes dominate: Malaysian nitrile volume producers, North American sterile portfolio validators, and diversified healthcare conglomerates with integrated distribution. Competitive moves center on capacity expansion in Southeast Asian manufacturing clusters and strategic partnerships for closed-loop recycling programs.
Within the Malaysian volume tier, Hartalega Holdings Berhad exemplifies centralized production complex economics, while Supermax Corporation Berhad and Kossan Rubber Industries Bhd occupy positions shaped by Klang Valley manufacturing concentration. Ansell Ltd. represents the sterile validation archetype through its pharmaceutical and biotechnology contract positioning across North America and Europe. Kimberly-Clark Corporation anchors the channel-control model through bundled cleanroom apparel programs that extend glove placement in hospital systems.
| Leading Market Players |
|---|
| Kimberly-Clark Corporation |
| Hartalega Holdings Berhad |
| Ansell Ltd. |
| Medline Industries, Inc. |
| Supermax Corporation Berhad |
| Top Glove Corporation Bhd |
| Kossan Rubber Industries Bhd |
| Dynarex Corporation |
| Cardinal Health, Inc. |
| Others |
Supply & Pricing Matrix
Malaysian nitrile production clusters in the Klang Valley concentrate feedstock access and compounding expertise, anchoring margin pools with semiconductor fabs in Taiwan and South Korea that pay premiums for accelerator-free formulations with documented ionic contamination certificates.
Pricing Analysis
Sub-10 nanometer node specifications command substantial premiums over legacy vinyl formulations, while pharmaceutical-grade sterile portfolios occupy a mid-tier position between commodity nitrile and next-generation neoprene for cell therapy applications. Price differentiation rests on ISO 14644 certification grade and FDA 510(k) validation status, with validated sterile lines capturing sustained contract premiums. Cost compression in vinyl segments is intensifying as foundry procurement consolidates around four qualified suppliers per category. Diagnostic laboratory networks in Germany and the United States exhibit the highest price sensitivity, unbundling glove supply from bundled apparel programs to force direct manufacturer transparency.
Supply Chain Analysis
Export-control restrictions on advanced lithography equipment to Chinese fabs are reshaping glove demand geography, concentrating procurement with Taiwan Semiconductor Manufacturing and Samsung Electronics while limiting capacity buildouts in the Yangtze River Delta. Manufacturing gravity centers on Malaysia, Thailand, and Indonesia, with butadiene and acrylonitrile monomer feedstocks drawn from Middle Eastern and Southeast Asian petrochemical complexes. Single-source vulnerability to Klang Valley port congestion remains the dominant structural risk. Distribution runs through consolidated group purchasing organizations in North American healthcare and direct manufacturer contracts with East Asian foundries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Accelerator-free nitrile validation services and closed-loop recycling programs are expanding faster than base glove production, creating recurring-revenue layers that decouple supplier economics from commodity volume cycles.
For Market Incumbents: Pre-empt disintermediation by diagnostic laboratory networks through captive sterilization facility partnerships that lock in multi-year validated supply contracts. Accelerate backward integration into acrylonitrile-butadiene rubber compounding to hedge butadiene feedstock volatility. Prioritize blockchain-verified chain-of-custody systems before semiconductor fabs mandate lot-level ionic contamination documentation as a baseline qualification requirement. For New Entrants and Emerging Players: Pursue pharmaceutical-grade neoprene production for Basel and Leiden biotechnology clusters, where aggressive chemical compatibility requirements and limited qualified suppliers create penetrable white space. Target India's Hyderabad and Ahmedabad pharmaceutical corridors, where CDSCO alignment with EU GMP standards is germinating cleanroom infrastructure buildouts without established incumbent relationships. Lead with dedicated pharmaceutical-grade production lines and documented bioburden reduction protocols to differentiate from commodity nitrile suppliers. For Investors and Strategic Acquirers: Capital is best deployed toward Malaysian volume producers with integrated polymer research capabilities that can absorb REACH reformulation costs and capture share from smaller compounders lacking in-house R&D. The five-to-ten year viability window favors suppliers with validated sterile portfolios and closed-loop recycling infrastructure aligned with EU extended producer responsibility frameworks. Watch for MFDS enforcement actions in South Korea as an inflection indicator; accelerated sterile processing mandates would amplify demand for certified manufacturers with existing pharmaceutical-grade production lines.| Strategic Initiative | Industry Significance |
|---|---|
| Accelerator-Free Nitrile Capacity Expansion | TSMC and Samsung procurement in Hsinchu and Pyeongtaek mandates ionic contamination thresholds that eliminate conventional sulfur-cured formulations. |
| Closed-Loop Recycling Program Development | France and Germany's packaging waste directives create first-mover advantage for suppliers with verified nitrile reprocessing capabilities. |
| Pharmaceutical-Grade Production Line Segregation | EMA tightened endotoxin limits force documented bioburden reduction protocols that favor dedicated sterile manufacturing facilities. |
| Blockchain Supply Chain Traceability Implementation | Semiconductor fabs now mandate lot-level certificates with verified chain of custody, displacing commodity tenders for qualified supplier programs. |
| India Cleanroom Infrastructure Partnership | CDSCO alignment with EU GMP standards and PLI scheme incentives germinate procurement growth nodes in Hyderabad and Ahmedabad clusters. |
Research Methodology
A standing panel of cleanroom facility managers, semiconductor procurement leads, pharmaceutical quality assurance directors, and nitrile compounding R&D heads provided ongoing calibration across primary interviews and secondary validation. FDA 510(k) filings, EMA sterile medicinal product guidance documents, ISO 14644-1 particulate classification standards, and customs trade data for acrylonitrile-butadiene rubber derivatives anchored secondary source triangulation. Bottom-up demand modeling across wafer fabrication capacity expansions and top-down supply assessment of Malaysian manufacturing clusters were cross-referenced for convergence.
Scenario bracketing around semiconductor node transition timelines, REACH Annex XVII accelerator restriction implementation, and Chinese dual carbon enforcement intensity shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include material chemistry tier, application environment classification, end-user procurement concentration, and regional regulatory cluster alignment. CAGRs were derived from installed cleanroom square footage growth, change-out protocol compression rates, and validated sterile contract renewal patterns.
Macroeconomic conditions sit as an overlay; deviation in crude oil price trajectories, Malaysian ringgit exchange rate volatility, or East Asian electronics capital expenditure cycles would shift the trajectory. Forecasts reflect assumptions about sustained foundry investment in Taiwan and South Korea, continued REACH enforcement on thiuram accelerators, and stable FDA sterile processing guidance. Material shifts in EU extended producer responsibility implementation scope or sudden Malaysian production disruptions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Global Dialysis Concentrate Market
Medical Supplies
Chlorhexidine Gluconate (CHG) Wipes Market
Medical Supplies
Skin Tac Market
Medical Supplies
Surgical Tapes Market
Medical Supplies
Oral Dosing Cups Market
Medical Supplies
Sequencing Consumables Market
Medical Supplies
Global Hypodermic Needles Market
Medical Supplies
United States Intravenous Solutions Market
Medical Supplies
Europe Insulin Syringe Market
Medical Supplies
France Hospital Supplies Market
Medical Supplies
Endoscope Protective Barrier Covers Market
Medical Supplies
Healthcare Adhesive Tapes Market
Medical Supplies
Urine Meter Trays Market
Medical Supplies
Esophageal Obturator Airway Kits Market
Medical Supplies
Cryoboxes Market
Medical Supplies
Cataract Disposable Products Market