
 Embedded Disinfection Cabinet Market | 2026-2036
Embedded Disinfection Cabinet Market Size, Share, and Industry Trends Forecast 2026-2036
Embedded Disinfection Cabinet Market Insights
Healthcare procurement teams is bifurcating away from traditional standalone sterilizers toward embedded cabinet systems that integrate with existing HVAC and workflow infrastructure. Haier leverages its appliance manufacturing scale to dominate integrated kitchen-to-clinic product lines across Asia. Midea Group anchors its position through captive supply of UV-C lamp assemblies, reducing dependency on third-party component vendors. SIEMENS competes on automation intelligence, embedding IoT-enabled cycle verification that appeals to laboratory end users requiring audit trails.
An embedded disinfection cabinet is a fixed-installation sanitization enclosure engineered with sealed stainless-steel chambers, forced convection heating elements, and UV-C or ozone-based sterilization modules rated for log-5 microbial reduction. These systems serve commercial and institutional environments where continuous throughput of instruments, utensils, or personal items demands validated disinfection without manual intervention between cycles. Wall-mounted configurations lead volume due to space constraints in retrofit healthcare and food service environments, while plasma technology segments capture premium positioning as hospitals seek residue-free alternatives to chemical agents. Integrated units represent the fastest-growing structural category because they displace multiple point-solution devices in new construction projects.
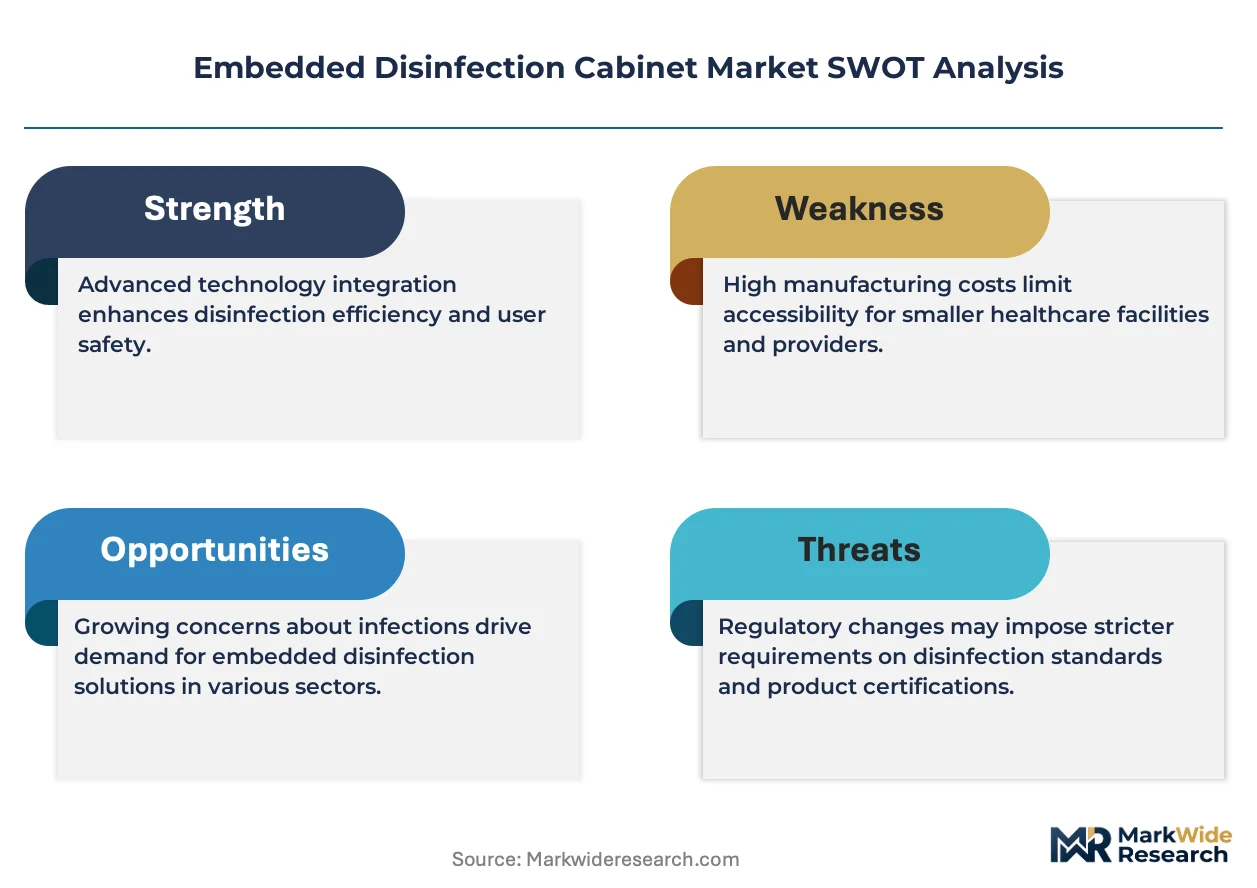
EPA registration requirements for pesticidal device claims and FDA enforcement of 510(k)-exempt sterilization accessories shape product development timelines and marketing language in the United States. EMA-aligned MDR cleanliness standards and REACH substance restrictions on ozone-emitting components govern European market access and material selection. Stakeholders must monitor evolving state-level healthcare facility codes and commercial kitchen sanitation grades, as these sub-national rule sets increasingly specify embedded system performance thresholds that exceed baseline federal requirements.
Market Dynamics
Healthcare infrastructure mandates are forcing rapid displacement of standalone sterilizers by HVAC-integrated cabinet systems that eliminate redundant equipment footprints and manual transfer steps between disinfection cycles.
Growth Catalysts
- EU MDR cleanliness protocols:European hospitals face mandatory validation documentation for surgical instrument sterilization workflows, accelerating replacement of legacy autoclaves with embedded systems offering automated cycle logging.
- Commercial kitchen hygiene mandates:Food service operators in Germany and China must demonstrate continuous surface disinfection compliance, driving wall-mounted cabinet installations in high-throughput prep environments.
- Plasma sterilization modules:Residue-free alternatives to chemical agents are capturing premium positioning in pediatric and ophthalmic surgical suites where ozone sensitivity limits conventional approaches.
Market Restraints
- UV-C lamp supply concentration:Quartz envelope manufacturing clusters in specific Asian manufacturing zones create input cost volatility and extended lead times for cabinet OEMs.
- REACH substance restrictions:ECHA limitations on ozone-emitting components force material redesigns for European market access, extending product development timelines.
- Steam autoclave substitution:Established low-cost sterilization infrastructure in budget-constrained healthcare systems limits embedded cabinet penetration in price-sensitive procurement segments.
Strategic Opportunities
- India hospital infrastructure renewal:Central government health facility modernization programs create first-mover advantages for integrated cabinet suppliers targeting greenfield construction.
- Laboratory audit trail convergence:IoT-enabled cycle verification systems align with ISO 15189 quality management requirements, opening specialized revenue streams in diagnostic lab environments.
- Modular kitchen-to-clinic product lines:Appliance manufacturers leverage existing distribution networks to cross-sell disinfection cabinets through shared channel infrastructure.
Industry Challenges
- 510(k) exemption navigation:FDA enforcement of sterilization accessory classifications creates documentation bottlenecks for manufacturers claiming specific microbial reduction efficacy.
- HVAC integration complexity:Retrofit installations in aging hospital infrastructure require specialized commissioning expertise that strains available field engineering capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Embedded Disinfection Cabinet Market |
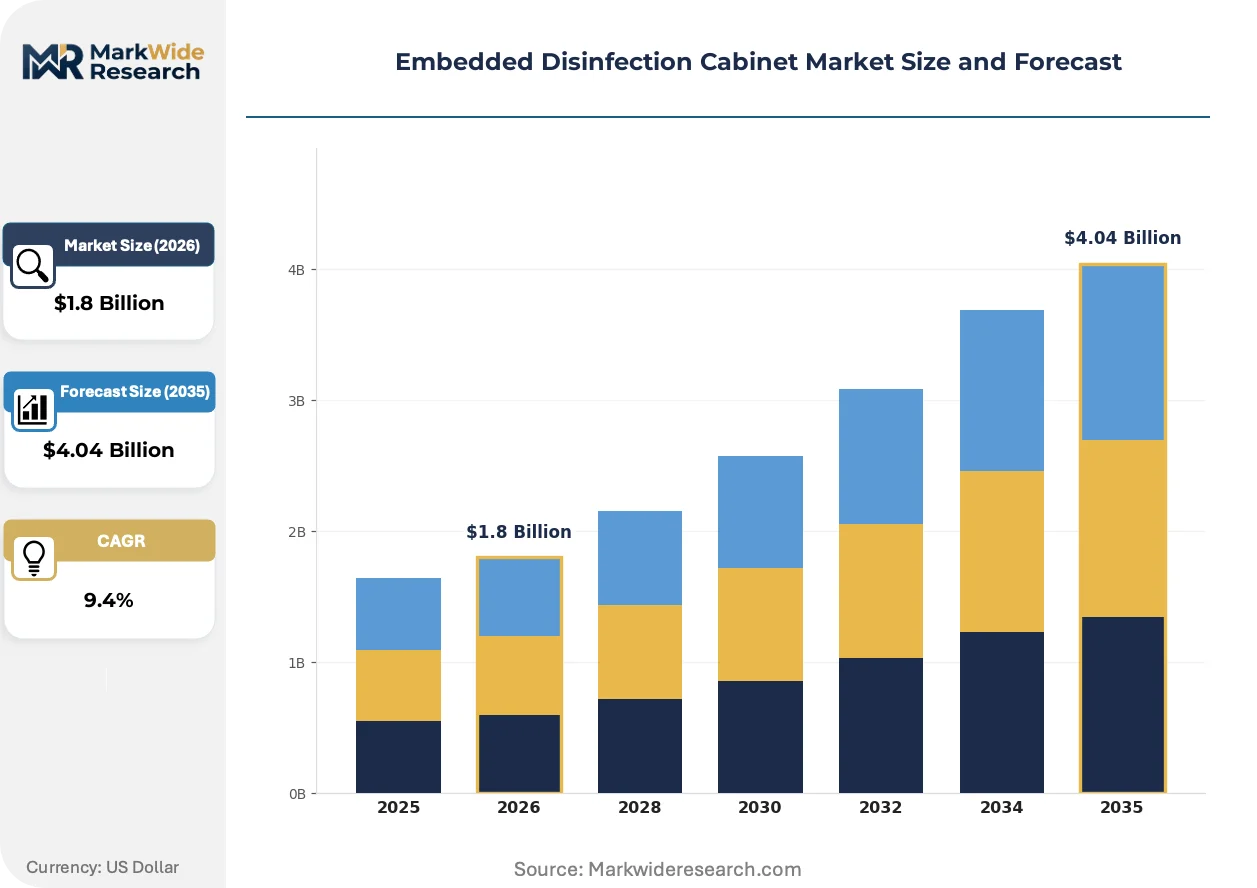
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall-mounted, Countertop, Portable, Integrated Technology: UV-C, Ozone, Chemical, Plasma End User: Healthcare Facilities, Laboratories, Educational Institutions, Restaurants Application: Medical Equipment, Personal Items, Food Services, Surface Sanitization |
| Companies Covered | Haier, Midea Group, SIEMENS, Canbo, MEIKO, Hobart, Vanward, ROBAM, Vatti, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Embedded Disinfection Cabinet Market Trends and Innovations
Embedded disinfection architecture is undergoing rapid functional decomposition as separate heating, UV-C, and ozone modules merge into unified control platforms with predictive maintenance capabilities.
Plasma-based sterilization is decomposing the traditional chemical-agent market by eliminating residue concerns in sensitive surgical environments. Tertiary care hospitals in Japan and South Korea are adopting these systems at accelerated procurement cycles. The technology is compressing competitive differentiation around cycle time and material compatibility rather than basic efficacy claims.
EPA registration requirements for pesticidal device claims are tightening marketing language and efficacy documentation standards in the United States. Manufacturers must submit validated test data for each targeted microorganism class before commercial distribution. Laboratory end users requiring audit trails represent the segment most affected, driving demand for automated data logging features.
Facility managers are consolidating vendor relationships around single-source embedded system providers rather than maintaining separate contracts for sterilizers, storage, and HVAC components. This pattern disrupts traditional medical equipment distributors and favors appliance-scale manufacturers with integrated product portfolios. The shift is most visible in new hospital construction projects across China and Germany where total cost of ownership calculations dominate procurement evaluations.
Embedded Disinfection Cabinet Market Segmentation
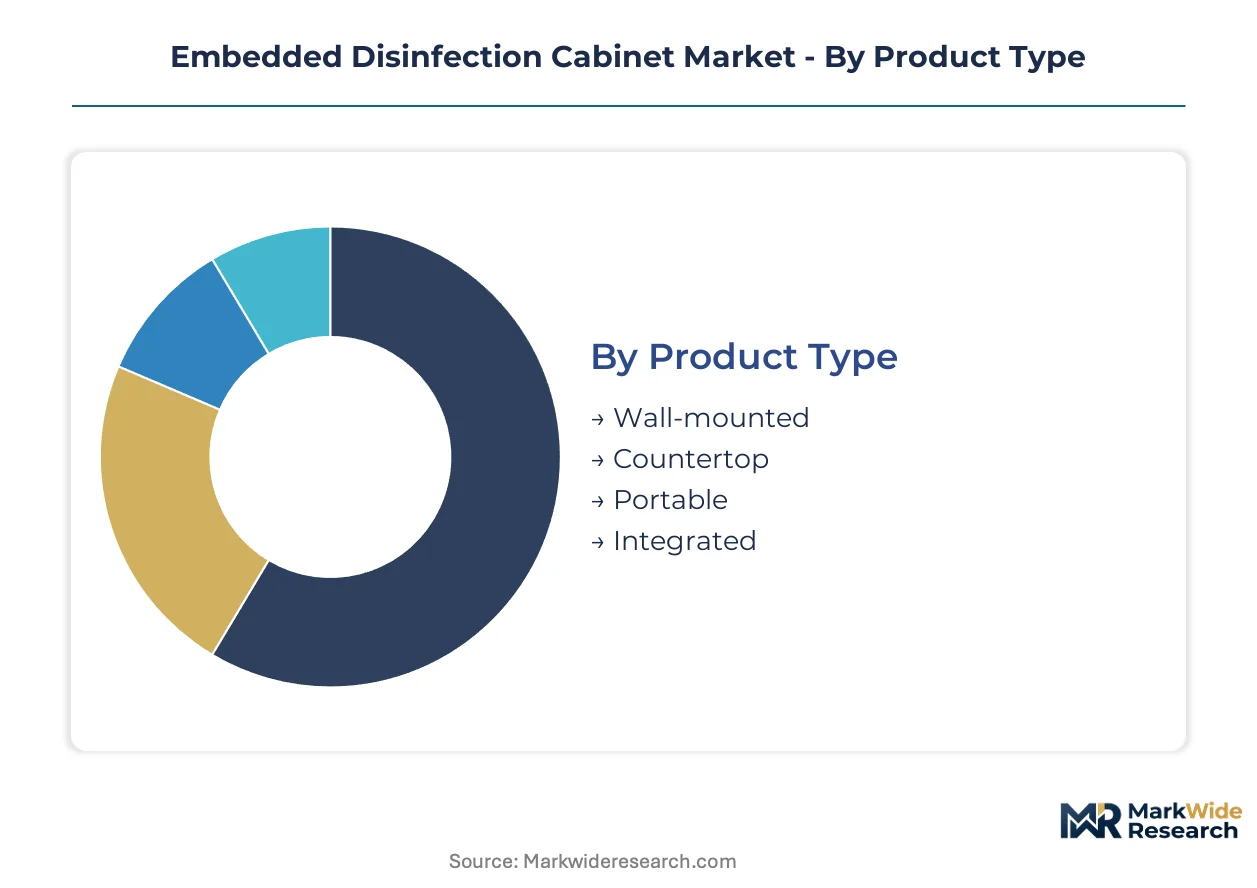
Embedded disinfection cabinets fragment across four distinct category axes, each revealing divergent competitive pressures and substitution vulnerabilities. Procurement patterns vary sharply by installation constraints, sterilization modality, and end-use compliance requirements.
Product Type:
Wall-mounted configurations face the most acute substitution threat from countertop alternatives in retrofit healthcare environments where structural mounting proves cost-prohibitive.
- Wall-mounted:Sealed stainless-steel enclosures affixed to vertical surfaces with forced convection heating and UV-C modules. German hospital infrastructure renewal programs specify these units for surgical instrument workflows where floor space commands premium valuations.
- Countertop:Compact self-contained chambers designed for benchtop placement in laboratory and food service prep zones. China commercial kitchen hygiene mandates accelerate countertop procurement in high-throughput urban restaurant clusters.
- Portable:Mobile units with caster-mounted bases and plug-and-play sterilization modules. Educational institutions deploy these for shared equipment rotation across multipurpose facilities.
- Integrated:Fixed-installation systems engineered into HVAC and building management infrastructure. New hospital construction in India favors integrated units that displace redundant standalone equipment footprints.
Wall-mounted configurations anchor the volume base while integrated units gain share at the steepest rate.
Technology:
Cost tier stratification separates premium plasma systems from commodity UV-C alternatives, with ozone modules occupying a contested middle position facing REACH substance restrictions.
- UV-C:Mercury-vapor or LED-based ultraviolet germicidal irradiation rated for log-5 microbial reduction. FDA 510(k)-exempt sterilization accessories in the United States drive UV-C specification for audit-trail-dependent laboratory environments.
- Ozone:Corona-discharge or UV-generated ozone chambers achieving residue-free sterilization through oxidative decomposition. ECHA REACH limitations on ozone-emitting components force material redesigns for European market access.
- Chemical:Vapor-phase hydrogen peroxide or formaldehyde systems requiring sealed chamber evacuation cycles. Budget-constrained healthcare systems in price-sensitive procurement segments favor chemical approaches for established low-cost infrastructure.
- Plasma:Low-temperature atmospheric plasma modules eliminating residue concerns in sensitive surgical environments. Japanese tertiary care hospitals accelerate plasma adoption for pediatric and ophthalmic suites where ozone sensitivity limits conventional approaches.
UV-C technology anchors the volume base while plasma modules climb the fastest among premium-positioned segments.
End User:
Application-specific compliance burdens concentrate demand among healthcare and laboratory verticals where validation documentation carries regulatory weight.
- Healthcare Facilities:Hospitals, surgical centers, and outpatient clinics requiring validated sterilization workflows for surgical instruments and patient care equipment. EU MDR cleanliness protocols mandate automated cycle logging that embedded cabinets uniquely satisfy.
- Laboratories:Diagnostic and research facilities requiring ISO 15189-aligned quality management with IoT-enabled audit trails. SIEMENS embeds cycle verification intelligence specifically targeting this end-use segment.
- Educational Institutions:Universities and K-12 systems deploying shared equipment disinfection for science laboratories and food service training kitchens.
- Restaurants:Commercial kitchen operators demonstrating continuous surface disinfection compliance under Germany and China hygiene mandates.
Healthcare facilities anchor the volume base while laboratories expand most quickly on diagnostic infrastructure investment.
Application:
Volume concentration in medical equipment sterilization contrasts with emerging demand for personal item sanitization in post-pandemic behavioral patterns.
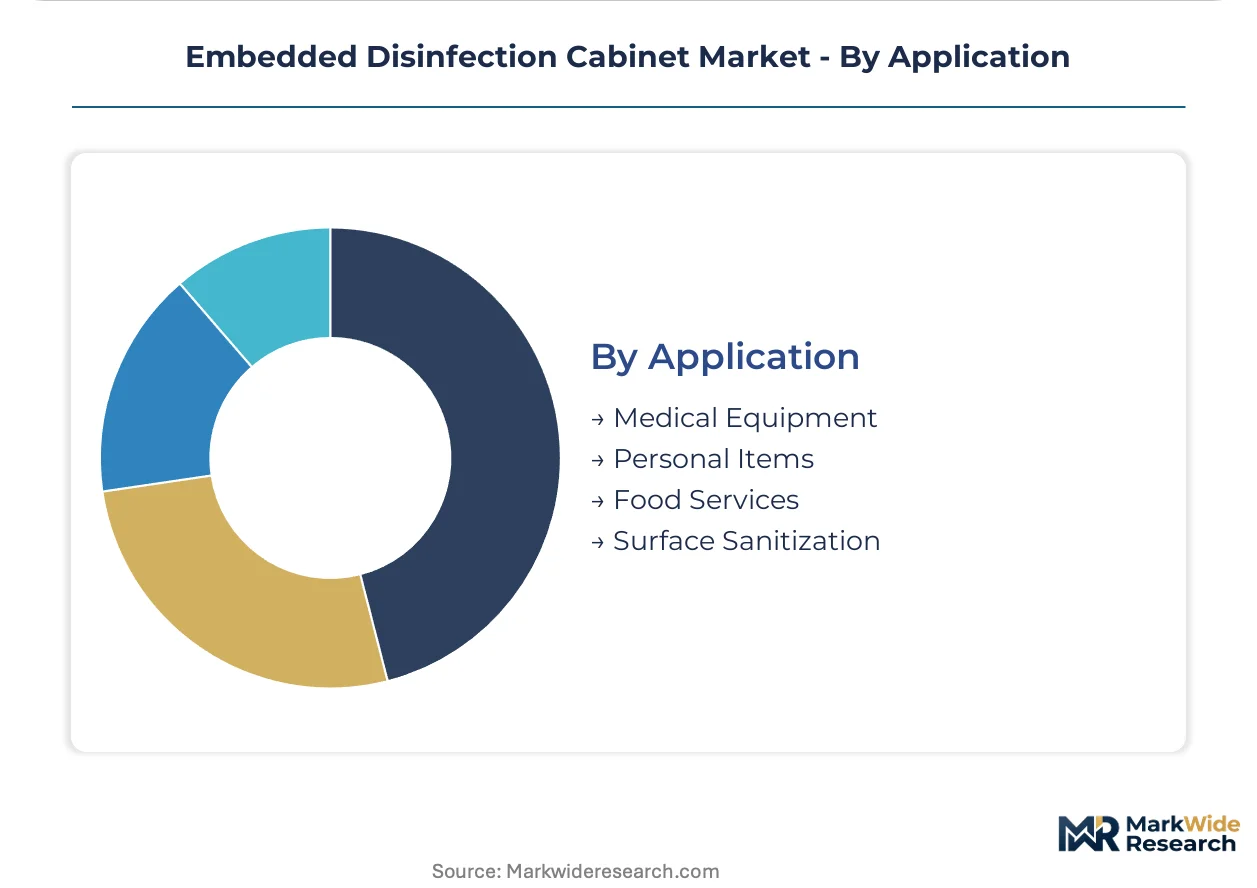
- Medical Equipment:Surgical instruments, endoscopes, and patient care devices requiring validated log-5 microbial reduction. EPA registration requirements for pesticidal device claims shape marketing language and efficacy documentation standards in the United States.
- Personal Items:Smartphones, tablets, and wearable devices sanitized in high-traffic commercial and institutional entryways.
- Food Services:Utensils, prep surfaces, and service ware in commercial kitchen environments. Wall-mounted configurations dominate retrofit installations where space constraints limit equipment footprints.
- Surface Sanitization:Fixed-installation chambers for bulk disinfection of non-instrument items in facility maintenance workflows.
Medical equipment applications anchor the volume base while personal item sanitization demonstrates the steepest expansion trajectory among emerging use cases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput connects German medical equipment supply chains to Asian manufacturing clusters, underwriting Europe's densest concentration of embedded disinfection cabinet procurement.
United States
Hospital infrastructure renewal programs in Texas and Florida accelerate wall-mounted cabinet installations for surgical instrument workflows. FDA enforcement of 510(k)-exempt sterilization accessory classifications shapes product documentation requirements for domestic manufacturers. The Boston-Cambridge medical device corridor concentrates IoT-enabled cycle verification development for laboratory audit trail compliance.
Germany
Commercial kitchen hygiene mandates in Bavaria and North Rhine-Westphalia drive high-throughput wall-mounted configurations for food service operators. EU MDR cleanliness protocols mandate automated cycle logging that embedded systems uniquely satisfy. The Stuttgart industrial cluster anchors precision stainless-steel chamber fabrication for export-oriented OEMs.
China
Central government health facility modernization programs in Jiangsu and Guangdong provinces favor integrated cabinet systems in greenfield hospital construction. NMPA registration requirements for disinfection device claims align with GB standards for microbial reduction validation. The Yangtze River Delta manufacturing belt concentrates UV-C lamp assembly and forced convection heating element production.
India
State-level healthcare infrastructure schemes in Maharashtra and Karnataka create first-mover opportunities for integrated unit suppliers targeting new hospital construction. CDSCO medical device rules govern sterilization equipment import and domestic manufacturing compliance. The Delhi-NCR corridor concentrates procurement decision-making for central government health facility tenders.
Japan
Tertiary care hospitals in Tokyo and Osaka accelerate plasma sterilization module adoption for pediatric and ophthalmic surgical suites. PMDA quality management system requirements shape validation documentation for low-temperature atmospheric plasma systems. The Nagoya manufacturing hub supplies precision control electronics for cycle verification platforms.
Embedded Disinfection Cabinet Market Competitive Landscape
Listed appliance conglomerates compete with private specialists across manufacturing scale and technology integration dimensions. The vendor base stratifies into three tiers: diversified home appliance manufacturers leveraging existing distribution infrastructure, dedicated commercial sterilization equipment fabricators with regulatory specialization, and component suppliers backward integrating into finished cabinet assembly. Consolidation pressure intensifies as facility managers consolidate vendor relationships around single-source embedded system providers. Dominant competitive moves include captive supply of UV-C lamp assemblies and geographic expansion through modular kitchen-to-clinic product line cross-selling.
Within the diversified appliance manufacturer tier, Haier and Midea Group exemplify scale-driven positioning through integrated product portfolios spanning residential and commercial environments. SIEMENS anchors the automation intelligence segment, representing the laboratory and diagnostic end-use specialization archetype with IoT-enabled cycle verification capabilities. These three companies illustrate the competitive divergence between manufacturing scale economies and technology-led differentiation in embedded disinfection cabinet supply.
| Leading Market Players |
|---|
| Haier |
| Midea Group |
| SIEMENS |
| Canbo |
| MEIKO |
| Hobart |
| Vanward |
| ROBAM |
| Vatti |
| Others |
Pricing and Supply Chain Analysis
EPA registration requirements for pesticidal device claims gate both supplier qualification and price differentiation simultaneously, as manufacturers must submit validated test data before commercial distribution while procurement teams weight certification tiers in total cost of ownership calculations.
Pricing Analysis
Volume-discount tiering structures dominate procurement contracts for healthcare facility networks, with three-tier pricing separating plasma-based premium systems from UV-C standard configurations and ozone-based economy alternatives. Price differentiation rests on FDA 510(k) exemption status and EU MDR compliance documentation, with certified audit-trail systems commanding substantial premiums over baseline units. Pricing pressure stems from quartz envelope supply volatility in Asian manufacturing zones, compressing margins for mid-tier OEMs. Budget-constrained healthcare systems in price-sensitive procurement segments exhibit highest price sensitivity, while tertiary care hospitals prioritize performance validation over unit economics.
Supply Chain Analysis
Extended lead times for UV-C lamp assemblies stretch inventory cycles beyond standard procurement horizons, forcing OEMs to hold buffer stocks of critical quartz envelope components. Manufacturing gravity centers on China, Germany, and Japan, with the Yangtze River Delta feeding forced convection heating elements and the Nagoya hub supplying precision control electronics. Raw material dependencies include stainless-steel chamber fabrication, mercury-vapor or LED UV-C sources, and atmospheric plasma generation modules. Single-source vulnerability concentrates in quartz envelope manufacturing clusters, exposing cabinet assemblers to input cost volatility. Distribution runs through medical equipment distributors and appliance-scale channel partners serving hospital construction and commercial kitchen retrofit segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Embedded disinfection cabinet demand is accelerating through a technology inflection as plasma sterilization modules displace chemical-agent alternatives in sensitive surgical environments.
For Market Incumbents: Compound defensive positioning through captive supply of UV-C lamp assemblies and backward integration into quartz envelope sourcing, neutralizing input cost volatility that threatens mid-tier margin structures. Deepen automation intelligence investments in IoT-enabled cycle verification to reinforce laboratory segment differentiation against appliance-scale competitors. Prioritize certification maintenance across EPA, FDA, and EU MDR frameworks as regulatory documentation becomes the primary procurement gate. For New Entrants and Emerging Players: Differentiate on modular kitchen-to-clinic product architecture, leveraging shared channel infrastructure to cross-sell disinfection cabinets through existing appliance distribution networks. Target India's greenfield hospital construction programs, where central government health facility modernization creates first-mover advantages without entrenched incumbent relationships. Pursue plasma technology licensing partnerships with Japanese precision electronics suppliers to shortcut R&D timelines for residue-free sterilization modules. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across integrated HVAC-embedded system manufacturing, favoring asset-light component suppliers over heavy fabrication footprints. Acquisition targets should exhibit regulatory specialization in 510(k) exemption navigation or EU MDR cleanliness protocol validation, creating durable moats against commoditization. Monitor state-level healthcare facility code revisions as early signals of demand inflection, as sub-national rule sets increasingly specify performance thresholds exceeding federal baselines.| Strategic Initiative | Industry Significance |
|---|---|
| Captive UV-C Lamp Supply | Backward integration into quartz envelope manufacturing neutralizes Asian supply zone volatility for OEMs. |
| IoT Cycle Verification Development | SIEMENS embeds audit-trail intelligence aligning with ISO 15189 laboratory quality management requirements. |
| Plasma Technology Licensing | Japanese atmospheric plasma modules eliminate residue concerns in pediatric and ophthalmic surgical suites. |
| Modular Product Line Expansion | Haier leverages appliance manufacturing scale to cross-sell kitchen-to-clinic disinfection cabinets through shared channels. |
| India Greenfield Construction Targeting | Central government health facility programs in Maharashtra and Karnataka create first-mover procurement advantages. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EPA registration databases, EU MDR technical documentation, and NMPA GB standards filings, with hospital procurement managers, biomedical engineers, GPO contracts managers, and commercial kitchen operators providing operational validation. Customs and trade data, SEC 10-K equipment disclosures, and hospital procurement databases supplied volume benchmarks. Bottom-up unit economics triangulated against top-down facility penetration estimates across the analysis window.
Segmentation dimensions modeled include installation configuration, sterilization technology modality, end-use vertical, and application type, with geographic regulatory clusters treated as distinct demand envelopes. CAGRs were derived from installed base replacement cycles and new construction penetration curves, incorporating HVAC integration complexity as a deployment velocity modifier and plasma technology adoption as a premium segment shift variable.
Material uncertainties — tariff exposure on Asian-sourced quartz components, REACH substance restriction expansions, and state-level code revision timing — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and hospital capital expenditure continuity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Medical Filter Market
Medical Equipment
Global Medical Carts Market
Medical Equipment
Medical Whirlpool Market
Medical Equipment
Hemodialysis Equipment Market
Medical Equipment
Cryochambers Market
Medical Equipment
Electric Bed Market
Medical Equipment
Global Laminar Airflow Cabinets Market
Medical Equipment
Global Medical Equipment Cooling Market
Medical Equipment
China Radiotherapy Market
Medical Equipment
Global Medical Refrigerators Market
Medical Equipment
Autoclaves Market
Medical Equipment
Global Ultra Low Temperature Freezers Market
Medical Equipment
Patient Mechanical Lift Handling Equipment Market
Medical Equipment
Global Blood Purification Equipment Market
Medical Equipment
North America Medical Device Reprocessing Market
Medical Equipment
Global Surgical Lights Market