
 Nuclear Medicine Equipment Market | 2026-2036
Nuclear Medicine Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Nuclear Medicine Equipment Market Intelligence
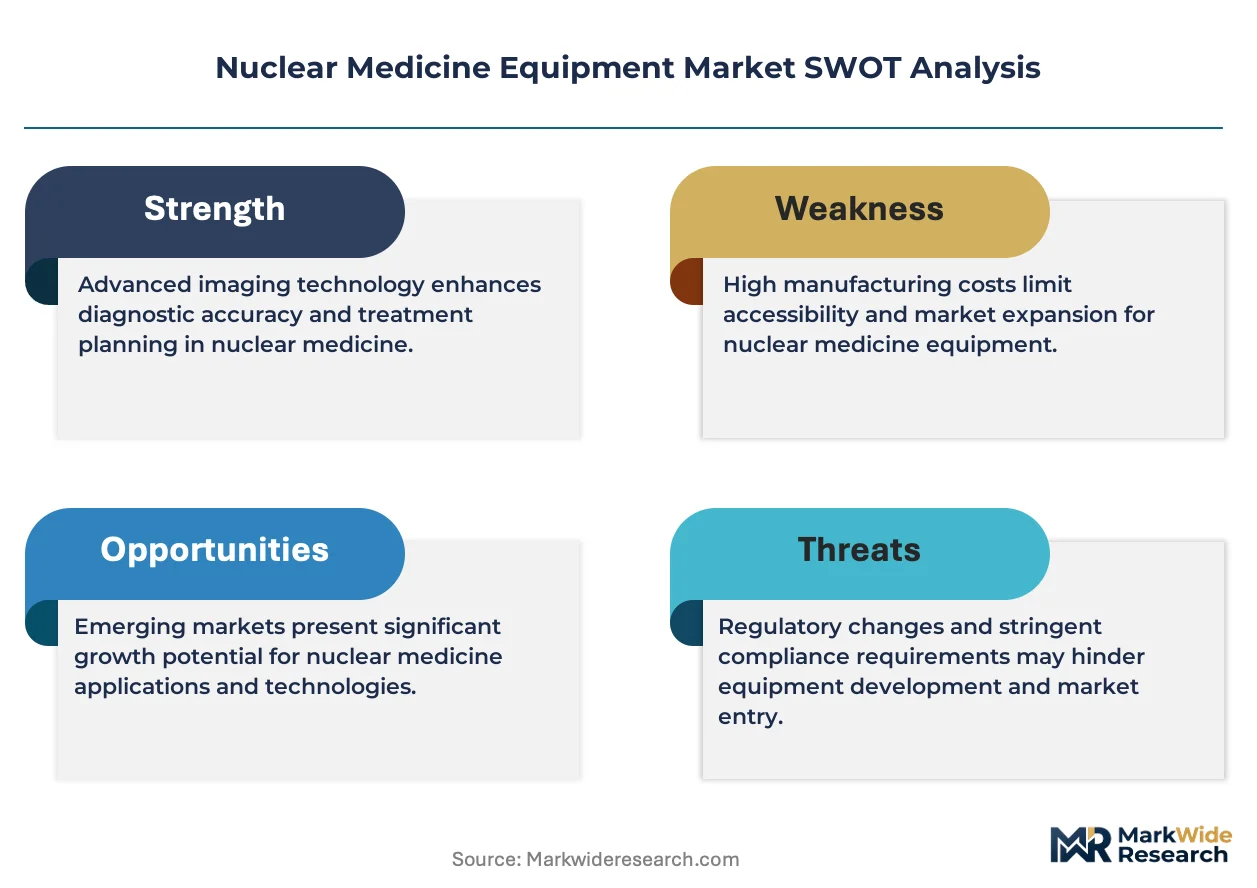
MDR is decoupling equipment certification from legacy quality-management templates, forcing manufacturers to rebuild technical documentation around clinical evidence thresholds. Siemens Healthineers AG sustains European market presence through in-house cyclotron networks that secure isotope supply chains. GE HealthCare leverages AI-embedded reconstruction algorithms to differentiate its PET-MR platforms from conventional scanner portfolios. Koninklijke Philips N.V. anchors its competitive position in hybrid imaging through proprietary digital photon-counting detector architectures.
Nuclear medicine equipment encompasses ionizing-radiation-based diagnostic and therapeutic systems that detect gamma-ray emissions from radiopharmaceuticals administered to patients, with spatial resolution thresholds typically ranging from 4-6 mm for PET and 8-12 mm for SPECT depending on detector material and reconstruction algorithm. These systems serve primarily to localize metabolic activity, perfusion deficits, or receptor density for clinical decision-making in oncology staging, myocardial viability assessment, and neurodegenerative disease characterization. PET scanners command premium pricing and margin pools due to cyclotron-dependent isotope logistics and higher reimbursement for FDG-based oncologic protocols, while SPECT systems retain volume dominance in cardiology departments where Tc-99m availability supports routine stress-rest perfusion imaging. Hybrid imaging combining PET with CT or MR is displacing standalone modalities as the default configuration for new hospital procurement cycles.
FDA 510(k) premarket notification and EMA MDR conformity assessment create divergent compliance burdens that shape regional product launch sequencing and clinical trial investment. EPA radioactive materials licensing and NRC agreement-state oversight constrain site-specific installation timelines, particularly for cyclotron-equipped facilities requiring environmental impact review. Stakeholders must monitor evolving CMS national coverage determinations for theranostic pairings, as reimbursement policy for lutetium-177 PSMA therapy will directly dictate downstream scanner utilization rates and capital replacement cycles.
Market Dynamics
Hybrid imaging configurations are compressing replacement cycles for standalone SPECT and PET systems as hospitals consolidate capital budgets into single-platform investments that deliver both anatomical and functional data streams.
Growth Catalysts
- FDG reimbursement protocols:Medicare coverage for diagnostic radiopharmaceuticals in the United States sustains hospital willingness to invest in cyclotron-equipped PET-CT suites.
- MDR Article 61:Europe's tightened clinical evidence requirements for Class III devices is accelerating documentation standards that improve product differentiation.
- Theranostic expansion:Lutetium-177 PSMA therapy pipelines are driving scanner utilization rates in oncology departments pursuing paired diagnostic-therapeutic workflows.
Market Restraints
- Molybdenum-99 supply fragility:Aging research reactors in Canada and the Netherlands create recurrent Tc-99m shortages that disrupt SPECT procedure scheduling.
- Cyclotron capital intensity:On-site isotope production requires $3-5 million facility investments plus NRC licensing timelines that extend 18-24 months.
- Detector material concentration:Lutetium-yttrium oxyorthosilicate crystal supply chains concentrate among Japanese and Chinese manufacturers, creating input vulnerability.
Strategic Opportunities
- Digital photon-counting transition:Solid-state detector architectures are opening performance gaps that premium-tier vendors can exploit against legacy scintillator-based systems.
- India's tertiary hospital expansion:Government health infrastructure programs in Maharashtra and Tamil Nadu are creating first-time demand for nuclear medicine departments.
- AI-embedded reconstruction:Deep learning algorithms that reduce scan time and radiotracer dose are creating software-layer differentiation above hardware parity.
Industry Challenges
- Qualified medical physicist scarcity:Dosimetry calculation and quality assurance protocols require specialized training pipelines that academic programs have not scaled to match equipment deployment.
- Legacy PACS integration:Hybrid imaging data formats strain hospital IT architectures built around DICOM standards that predate PET-MR multimodal workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nuclear Medicine Equipment Market |
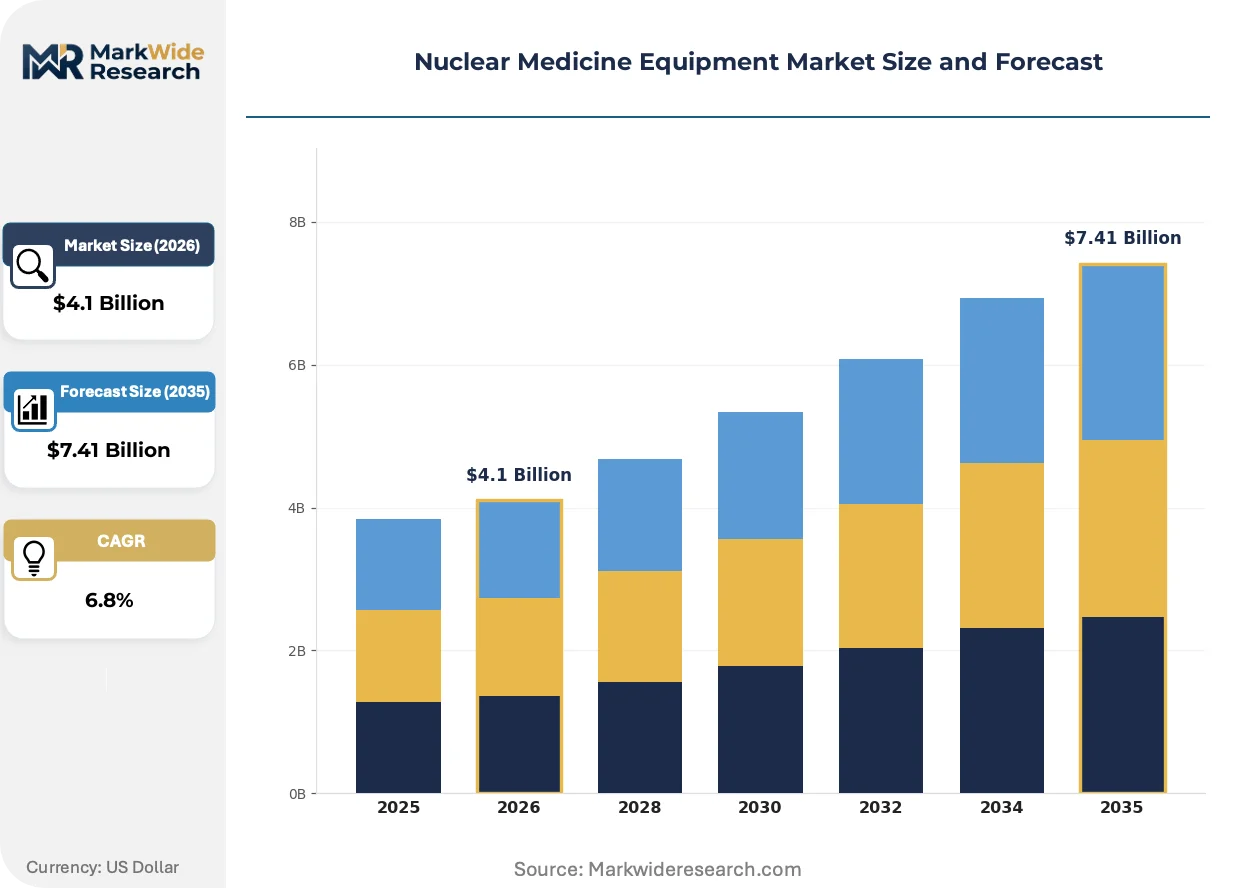
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $7.41 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gamma Cameras, SPECT Systems, PET Scanners, Radiopharmaceutical Generators, Dosimeters Technology: SPECT, PET, Hybrid Imaging, Digital Gamma Cameras, Traditional Analog Systems Application: Cardiology, Oncology, Neurology, Endocrinology, Pulmonology End User: Diagnostic Centers, Research Institutes, Nuclear Pharmacies, Specialized Clinics, Veterinary Facilities |
| Companies Covered | GE HealthCare, Siemens Healthineers AG, Koninklijke Philips N.V., Canon Medical Systems Corporation, Mirion Technologies, Inc., Mediso Ltd., Bracco Imaging S.p.A., Neusoft Corporation, United Imaging Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nuclear Medicine Equipment Market Strategic Shifts & Innovations
Artificial intelligence is embedding at multiple layers of the imaging stack, from acquisition protocols through reconstruction algorithms to clinical decision support, compressing the value chain between raw detector signals and diagnostic reports.
Digital photon-counting detector technology is rewriting sensitivity-resolution tradeoffs that have constrained nuclear medicine for decades. Cadmium-zinc-telluride semiconductors directly convert gamma photons to electrical signals, eliminating light-conversion losses inherent in scintillator-photomultiplier architectures. Tertiary oncology centers in Germany and the United States are piloting these systems for pediatric and repeat-scan populations where dose minimization carries premium value. The technology is rewriting competitive positioning by decoupling image quality from radiotracer volume, threatening incumbent suppliers whose margins depend on isotope throughput.
EMA's MDR transition is fragmenting product launch sequencing between European and North American markets. The regulation's requirement for prospective clinical data on Class III devices is extending conformity assessment timelines by 12-18 months relative to FDA 510(k) pathways. Small-to-mid scale manufacturers without legacy predicate devices are most affected, with several delaying EU market entry to prioritize US commercialization. The divergence is creating a two-speed regulatory environment where product generations reach clinical use in staggered waves.
Hospital procurement departments are consolidating vendor relationships through long-term service contracts that bundle equipment, isotope supply, and maintenance into per-scan pricing models. This shift compresses capital expenditure visibility for manufacturers while transferring cyclotron utilization risk to equipment suppliers. The model is most advanced in US integrated delivery networks and UK National Health Service trusts, where budget predictability outweighs ownership flexibility in purchasing criteria.
Nuclear Medicine Equipment Market Segmentation
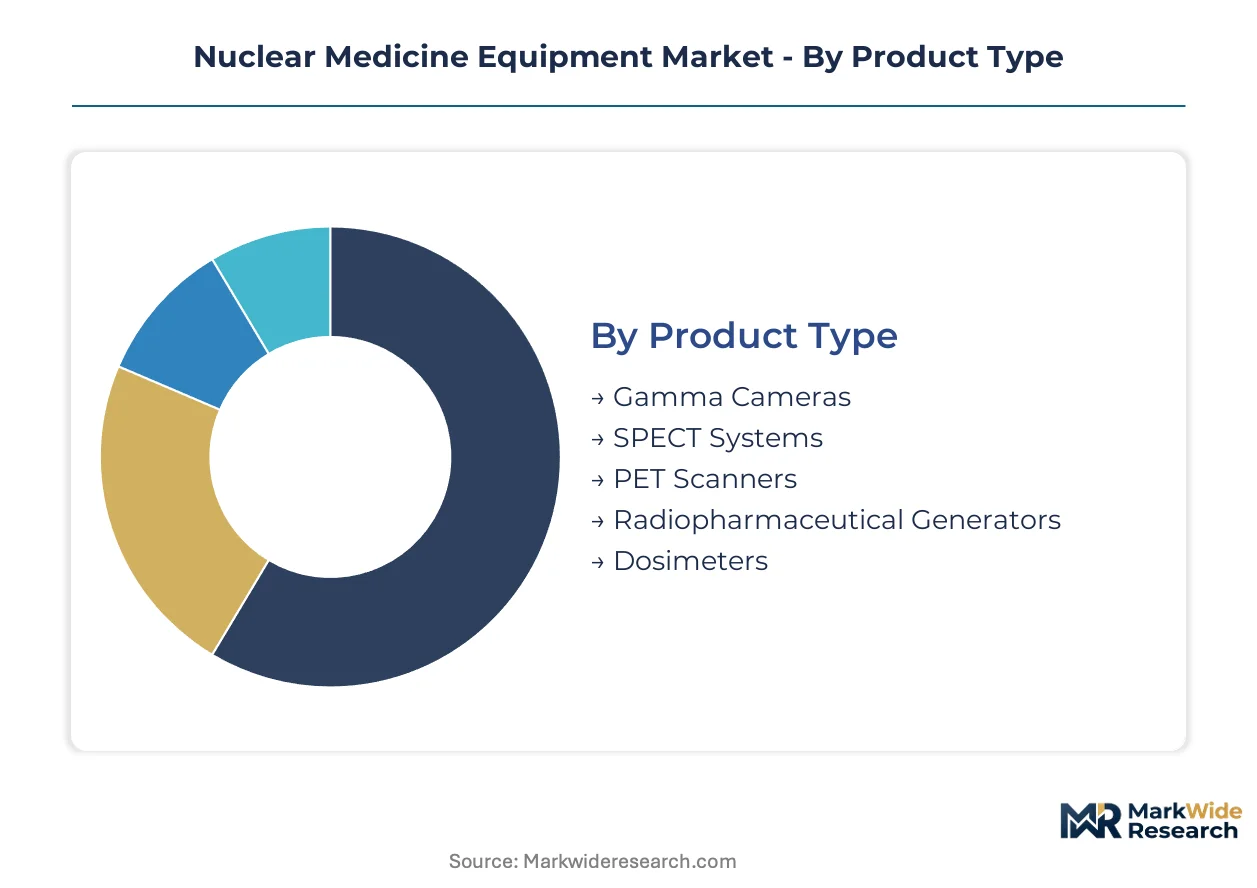
Nuclear medicine equipment segmentation reveals how capital allocation splits between standalone diagnostic platforms and integrated hybrid systems. Product configuration choices directly determine isotope logistics, facility footprint requirements, and reimbursement pathways for hospital procurement teams.
Product Type:
Standalone gamma cameras serve basic functional imaging needs while hybrid architectures embed PET and SPECT within multimodal suites.
- Gamma Cameras:Single-detector and dual-head Anger camera configurations capture planar scintigraphy for thyroid and bone scans. Demand concentrates in community hospitals across India and Brazil where Tc-99m availability supports high-throughput screening programs constrained by capital budgets.
- SPECT Systems:Rotating gamma camera arrays reconstruct three-dimensional perfusion maps with 8-12 mm spatial resolution. Cardiology departments in Germany and Japan deploy these systems for routine myocardial viability assessment where FDG PET access remains limited by cyclotron proximity.
- PET Scanners:Ring-detector geometries detect coincident 511 keV photon pairs from positron-emitting isotopes.
- Radiopharmaceutical Generators:Mo-99/Tc-99m column systems and Sr-82/Rb-82 generators enable on-site isotope elution without cyclotron infrastructure.
- Dosimeters:Ionization chambers and thermoluminescent detectors calibrate administered activities for regulatory compliance.
Volume placements concentrate in SPECT Systems; the faster expansion belongs to PET Scanners.
Technology:
Digital detector architectures are displacing analog signal chains across all modality tiers, rewriting sensitivity benchmarks and dose-minimization protocols.
- SPECT:Conventional Anger camera technology with sodium iodide crystals and photomultiplier tubes dominates installed base maintenance cycles.
- PET:Lutetium oxyorthosilicate block detectors with photomultiplier readout remain the standard configuration for oncologic staging protocols.
- Hybrid Imaging:PET-CT and PET-MR platforms fuse functional and anatomical data streams into single acquisition workflows. Tertiary oncology centers in the United States and Switzerland prioritize these configurations for radiation therapy planning where spatial registration accuracy drives clinical adoption.
- Digital Gamma Cameras:Cadmium-zinc-telluride semiconductor detectors directly convert gamma photons to electrical signals.
- Traditional Analog Systems:Legacy scintillator-photomultiplier architectures persist in cost-sensitive replacement markets.
Revenue pools concentrate in Hybrid Imaging; Digital Gamma Cameras are climbing the fastest as pediatric and repeat-scan populations drive dose-minimization demand.
Application:
Clinical specialization determines isotope selection, with oncology protocols commanding premium reimbursement and cardiology generating procedure volume.
- Cardiology:Stress-rest myocardial perfusion imaging using Tc-99m sestamibi or tetrofosmin tracers dominates SPECT utilization. Community diagnostic centers in the United States schedule these procedures routinely where Medicare reimbursement sustains capital equipment depreciation schedules.
- Oncology:FDG PET-CT staging for lung, lymphoma, and colorectal malignancies drives cyclotron-equipped facility investment. Comprehensive cancer centers in France and South Korea deploy these systems for treatment response monitoring where quantitative SUV metrics guide chemotherapy adjustment.
- Neurology:Amyloid and tau PET tracers characterize neurodegenerative proteinopathy patterns.
- Endocrinology:I-131 whole-body scanning and SPECT-CT localize differentiated thyroid cancer metastases.
- Pulmonology:V/Q scintigraphy evaluates pulmonary embolism perfusion-ventilation mismatch.
Procedure volume concentrates in Cardiology; Neurology applications are gaining share fastest as amyloid-targeting radiotracers expand diagnostic access.
End User:
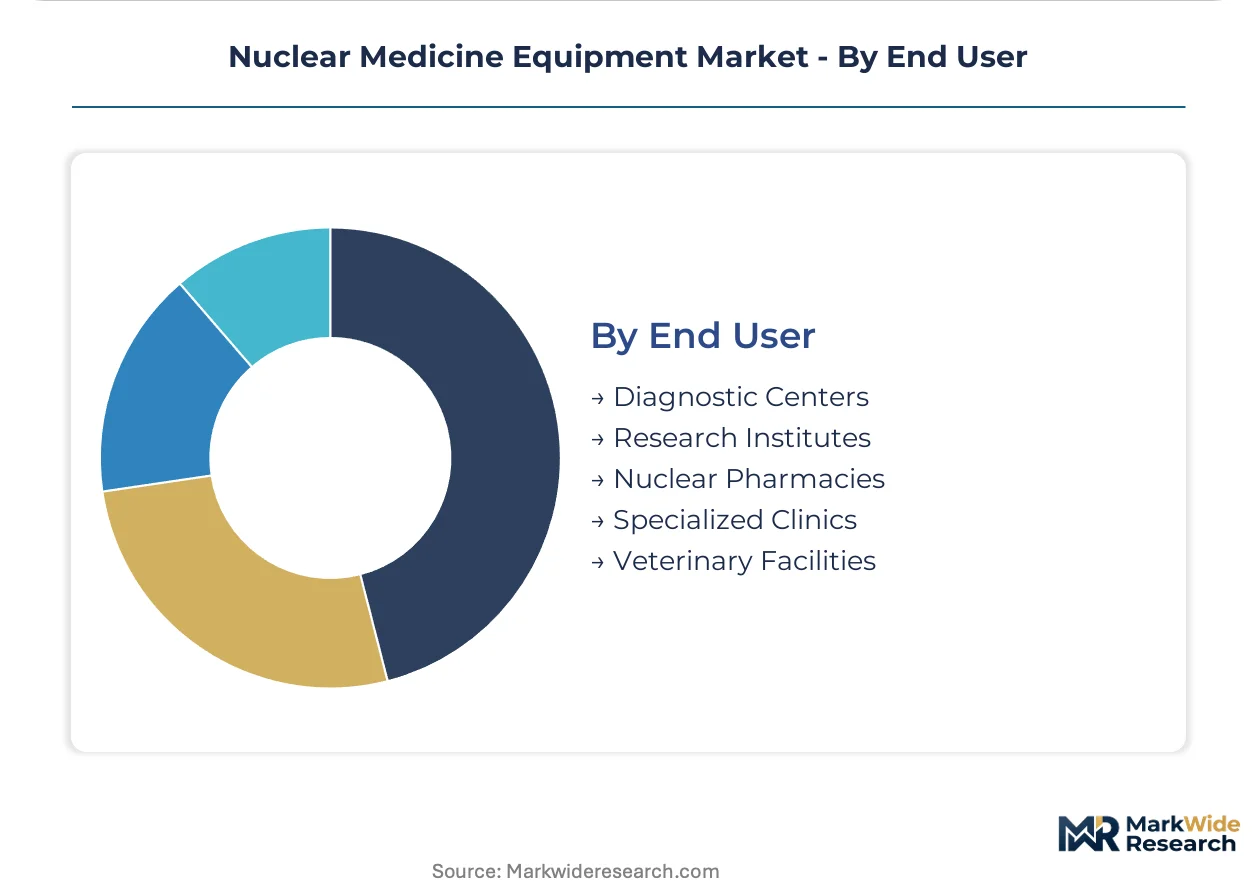
Facility type determines equipment specification, with centralized isotope production favoring high-volume hospital installations over distributed point-of-care deployment.
- Diagnostic Centers:Independent imaging facilities operate SPECT and PET-CT systems on referral networks from community physicians. These centers in Texas and Florida aggregate sufficient procedure volume to justify cyclotron partnerships or generator-based isotope supply.
- Research Institutes:Academic medical centers deploy preclinical PET and SPECT systems for radiotracer development. National laboratories in California and Maryland house micro-PET and autoradiography suites where novel probe validation precedes clinical translation.
- Nuclear Pharmacies:Centralized radiopharmaceutical compounding facilities serve multiple clinical sites through unit-dose distribution.
- Specialized Clinics:Cardiology and oncology focused practices install compact SPECT systems for same-day diagnostic access.
- Veterinary Facilities:Companion animal oncology practices adopt modified human PET-CT systems for tumor staging in canine and feline patients.
Capital deployment concentrates in Diagnostic Centers; Research Institutes show the steepest expansion trajectory as theranostic pipeline development accelerates scanner utilization for probe validation studies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement for hybrid imaging suites concentrates in the United States, where Medicare reimbursement for diagnostic radiopharmaceuticals sustains capital investment cycles. Siemens Healthineers AG maintains cyclotron networks across Germany and Switzerland to secure isotope supply chains for European installations.
United States
Tertiary oncology centers in Texas and Florida are expanding molecular imaging programs for theranostic workflows. FDA's streamlined 510(k) pathway for digital PET systems accelerates product clearance timelines for vendors targeting integrated delivery networks. The Cleveland Clinic and Mayo Clinic anchor high-volume PET-MR utilization in radiation therapy planning protocols.
Germany
Cardiology departments deploy SPECT systems for routine myocardial viability assessment where FDG PET access remains limited by cyclotron proximity. EMA MDR Article 61 tightens clinical evidence requirements for Class III devices, extending conformity assessment timelines. Siemens Healthineers AG operates in-house cyclotron facilities in Erlangen and Forchheim to secure isotope supply chains.
Japan
PMDA regulatory frameworks govern radiopharmaceutical approval timelines for novel amyloid-targeting tracers in neurodegenerative disease characterization. Lutetium-yttrium oxyorthosilicate crystal supply chains concentrate among domestic manufacturers, creating input advantages for detector production. Tokyo and Osaka metropolitan areas host the highest density of PET-CT installations per capita.
India
Government health infrastructure programs in Maharashtra and Tamil Nadu are creating first-time demand for nuclear medicine departments in tertiary hospitals. CDSCO regulates diagnostic radiopharmaceutical imports while domestic production capacity remains limited. Apollo Hospitals and Tata Memorial Centre in Mumbai and Chennai anchor hybrid imaging adoption for oncology staging protocols.
France
ANSM oversees radiopharmaceutical distribution licensing for lutetium-177 PSMA therapy pipelines driving scanner utilization. Comprehensive cancer centers in Paris and Lyon deploy quantitative SUV metrics for treatment response monitoring. Gustave Roussy and Institut Curie represent high-volume theranostic centers with paired diagnostic-therapeutic workflows.
Nuclear Medicine Equipment Market Key Industry Players
United States and German producers anchor the premium-tier equipment segment; Japanese and Chinese specialists hold detector material and component supply positions. The market structure consolidates around three to five integrated imaging conglomerates with cyclotron-equipped service networks, while mid-scale manufacturers concentrate in SPECT system replacements and digital detector upgrades. Archetypes include full-stack hybrid imaging vendors, radiopharmaceutical-integrated equipment suppliers, and solid-state detector technology specialists. Competitive moves center on long-term service contracts bundling equipment and isotope supply into per-scan pricing, plus AI-embedded reconstruction software differentiation above hardware parity.
Among diversified health technology conglomerates, GE HealthCare, Siemens Healthineers AG, and Koninklijke Philips N.V. exemplify the full-stack archetype with cyclotron-networked service capabilities. These entities occupy positions spanning PET-CT, PET-MR, and SPECT modalities with integrated isotope logistics. Canon Medical Systems Corporation and United Imaging Healthcare represent the Asia-Pacific manufacturing tier with cost-optimized platform configurations. Mirion Technologies, Inc. and Mediso Ltd. sit within the specialized detector and dosimetry equipment segment. Bracco Imaging S.p.A. anchors the radiopharmaceutical-integrated archetype with contrast agent and isotope distribution capabilities.
| Leading Market Players |
|---|
| GE HealthCare |
| Siemens Healthineers AG |
| Koninklijke Philips N.V. |
| Canon Medical Systems Corporation |
| Mirion Technologies, Inc. |
| Mediso Ltd. |
| Bracco Imaging S.p.A. |
| Neusoft Corporation |
| United Imaging Healthcare |
| Others |
Cost & Logistics Intelligence
Hospital procurement consolidation into long-term service contracts is forcing manufacturers to absorb cyclotron utilization risk and bundle isotope supply with equipment, compressing upfront capital visibility and shifting margin capture toward per-scan recurring revenue streams.
Pricing Analysis
Volume placements concentrate in SPECT systems where Tc-99m generator supply supports routine cardiology throughput at compressed margin tiers, while PET scanners command premium positioning due to cyclotron-dependent isotope logistics and higher FDG reimbursement rates. Three-tier pricing structure across premium, standard, and economy levels separates digital photon-counting PET-MR configurations from analog SPECT replacements and refurbished gamma camera installations. Pricing pressure stems from integrated delivery networks demanding total-cost-of-ownership transparency across 10-year equipment lifecycles. Community diagnostic centers exhibit highest price sensitivity, whereas comprehensive cancer centers prioritize quantitative SUV metrics and spatial resolution specifications over acquisition cost.
Supply Chain Analysis
Regional distribution centers in Erlangen, Forchheim, and suburban Tokyo coordinate hub-and-spoke isotope logistics that feed cyclotron-equipped installations across European and Asia-Pacific hospital networks. Lutetium-yttrium oxyorthosilicate crystal production concentrates in Japan and China, while molybdenum-99 supply draws from aging research reactors in Canada and the Netherlands. Detector material concentration creates single-source vulnerability for solid-state semiconductor substrates. Distribution runs through centralized radiopharmaceutical compounding facilities that serve multiple clinical sites through unit-dose cold-chain delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital photon-counting detector architectures are displacing legacy scintillator-photomultiplier systems, creating asymmetric upgrade cycles where early adopters capture dose-minimization premiums and late movers face stranded analog inventories.
For Market Incumbents: Acquire solid-state detector technology specialists to secure cadmium-zinc-telluride semiconductor supply chains and eliminate light-conversion efficiency gaps against emerging pure-play digital vendors. Backward integration into in-house cyclotron networks defends isotope margin capture against generator-based competitors. FDA 510(k) pathway acceleration for AI-embedded reconstruction algorithms represents the critical certification lever for integrated delivery network contract renewal. For New Entrants and Emerging Players: Tertiary hospitals in Maharashtra and Tamil Nadu present first-time nuclear medicine department demand with limited incumbent service relationships and price-elastic procurement criteria. Compact SPECT systems for specialized cardiology clinics offer penetrable white-space below full-stack vendor attention. Go-to-market execution should anchor on CDSCO import licensing partnerships with established radiopharmaceutical distributors rather than direct cyclotron infrastructure investment. For Investors and Strategic Acquirers: Re-rating potential sits with digital detector technology specialists given EMA MDR Article 61 compliance timelines that favor predicate-device-rich acquirers over de novo submission pathways. Long-term viability over the extended therapeutic window hinges on theranostic pairing reimbursement expansion beyond diagnostic radiopharmaceuticals into lutetium-177 therapy protocols. Monitor CMS national coverage determinations for PSMA-targeted radioligand therapy as the definitive inflection signal for downstream scanner utilization rates.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Photon-Counting Detector Transition | Cadmium-zinc-telluride semiconductors eliminate light-conversion losses and rewrite sensitivity-resolution tradeoffs for pediatric applications. |
| Long-Term Service Contract Bundling | Per-scan pricing models transfer cyclotron utilization risk from hospitals to equipment vendors in US integrated delivery networks. |
| AI-Embedded Reconstruction Software Development | Deep learning algorithms reduce FDG radiotracer dose and scan time, creating differentiation above hardware parity. |
| Cyclotron Network Geographic Expansion | In-house isotope production facilities in Erlangen and Forchheim secure European supply chains against Mo-99 reactor fragility. |
| Theranostic Pairing Reimbursement Strategy | Lutetium-177 PSMA therapy coverage determinations directly dictate PET-CT scanner replacement cycles in oncology departments. |
Research Approach
Document review covered FDA 510(k) premarket notifications, EMA MDR conformity assessment pathways, and CMS national coverage determinations, complemented by interviews with hospital purchasing committee chairs, biomedical engineering directors, GPO contracts managers, and nuclear medicine department heads. Secondary validation drew from hospital procurement databases, radiopharmaceutical distribution records, and equipment installation registries. Bottom-up procedure volume estimates and top-down capital expenditure patterns were triangulated against manufacturer service contract disclosures.
Market size outputs across the analysis window reflect equipment shipment tracking by modality configuration, isotope supply chain throughput, and replacement cycle timing by installed base vintage. Segmentation modeling incorporated product type, detector technology architecture, clinical application specialty, and end-user facility category. CAGRs were derived from procedure volume elasticity to reimbursement rate changes and capital budget allocation shifts between standalone and hybrid imaging platforms. Forecast inputs included PMDA regulatory timelines for amyloid-targeting tracers and CDSCO diagnostic radiopharmaceutical import licensing patterns.
Revisions become necessary when Mo-99 reactor outages extend beyond scheduled maintenance windows, when MDR Article 61 clinical evidence requirements tighten further, or when CMS theranostic coverage determinations diverge from diagnostic radiopharmaceutical precedent. Forecasts reflect documented assumptions regarding reimbursement stability and isotope supply continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Medical Oxygen Cylinders Market
Medical Equipment
Medical Automation Market
Medical Equipment
Southern Europe and Middle East Medical Robotics Market
Medical Equipment
Brazil Massage Equipment Market
Medical Equipment
Floor-Standing Platelet Agitator Market
Medical Equipment
Proton and Ion Beam Therapy Dosimetry and QA Test Equipment Market
Medical Equipment
Tissue Culture Incubator Market
Medical Equipment
Medical Equipment Calibration Services Market
Medical Equipment
Global Medical Device Reprocessing Market
Medical Equipment
Surgical Lighting System Market
Medical Equipment
US Biomedical Refrigerators and Freezers Market
Medical Equipment
Medical Ultrasonic Cleaners Market
Medical Equipment
Medical Physics Market
Medical Equipment
Global Intraoperative Radiation Therapy Market
Medical Equipment
Global Bone Densitometer Market
Medical Equipment
Global Platelet Incubator Market