
 Brazil Massage Equipment Market | 2026-2036
Brazil Massage Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Massage Equipment Market Insights
Aftermarket service revenue is fragmenting across warranty extensions, replacement part networks, and preventive maintenance subscriptions. Panasonic Holdings Corporation leverages its established electronics service infrastructure to capture recurring income from massage chair owners. Beurer GmbH competes through specialized distributor partnerships that control technical support quality in Brazilian metropolitan areas.
Brazil massage equipment comprises electromechanical and manually operated devices designed for musculoskeletal relaxation, pain relief, and circulation improvement, typically incorporating motors generating percussive or oscillating forces between 1,800 and 3,200 RPM alongside heating elements reaching 40-45°C. These devices serve commercial wellness establishments and residential consumers seeking non-pharmacological therapeutic interventions. Massage chairs dominate value contribution due to high unit prices and extended replacement cycles, while hand-held massagers represent the fastest-expanding product type among home users prioritizing portability and storage efficiency. Electric technology leads installation bases but infrared-equipped models command premium positioning in spa and healthcare facility procurement.
ANVISA regulates massage equipment with therapeutic claims as medical devices, requiring registration certificates that extend market entry timelines for imported products. The Brazilian Association of Technical Standards (ABNT) issues complementary safety and electromagnetic compatibility benchmarks that manufacturers must satisfy for commercial distribution authorization. Stakeholders must monitor pending ANVISA reclassification proposals that could shift borderline wellness products into stricter regulatory tiers, fundamentally altering compliance investment requirements and competitive barriers for new entrants.
Market Dynamics
ANVISA's medical device reclassification proposals are compressing market entry timelines and forcing manufacturers to pre-invest in Brazilian regulatory infrastructure before product launch.
Growth Catalysts
- Wellness tourism concentration:Rio de Janeiro and São Paulo spa operators are upgrading electromechanical equipment to capture medical tourism revenue streams from international visitors.
- ABNT electromagnetic compatibility standards:Harmonized safety benchmarks reduce technical barriers for Asian manufacturers seeking Brazilian distribution authorization.
- Southeast residential demand:São Paulo state households with limited storage space prioritize compact hand-held massagers over full-size massage chairs.
Market Restraints
- Import duty volatility:Brazilian customs classification disputes for massage equipment create landed cost uncertainty for distributors sourcing from Chinese manufacturing clusters.
- ANVISA registration timelines:Therapeutic claim documentation requirements extend product approval cycles to 18-24 months for first-time market entrants.
- Physical therapy substitution:SUS-funded physiotherapy sessions in municipal health centers compete with home-use equipment for chronic pain management budgets.
Strategic Opportunities
- Northeast regional expansion:Recife and Salvador wellness markets remain underpenetrated by premium massage chair distributors focused on Southeast concentration.
- Infrared-heat convergence:Spa procurement teams are specifying combined percussive-infrared systems that command higher per-unit margins than standalone vibration devices.
- Preventive maintenance subscriptions:Commercial operators in São Paulo are unbundling service contracts from equipment sales, creating recurring revenue streams for technical support providers.
Industry Challenges
- Biomedical technician scarcity:ANVISA-authorized repair certification programs graduate fewer technicians than commercial installation bases require for warranty service compliance.
- Legacy inventory obsolescence:Pending electromagnetic compatibility standard updates threaten existing warehouse stock with non-compliance reclassification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Massage Equipment Market |
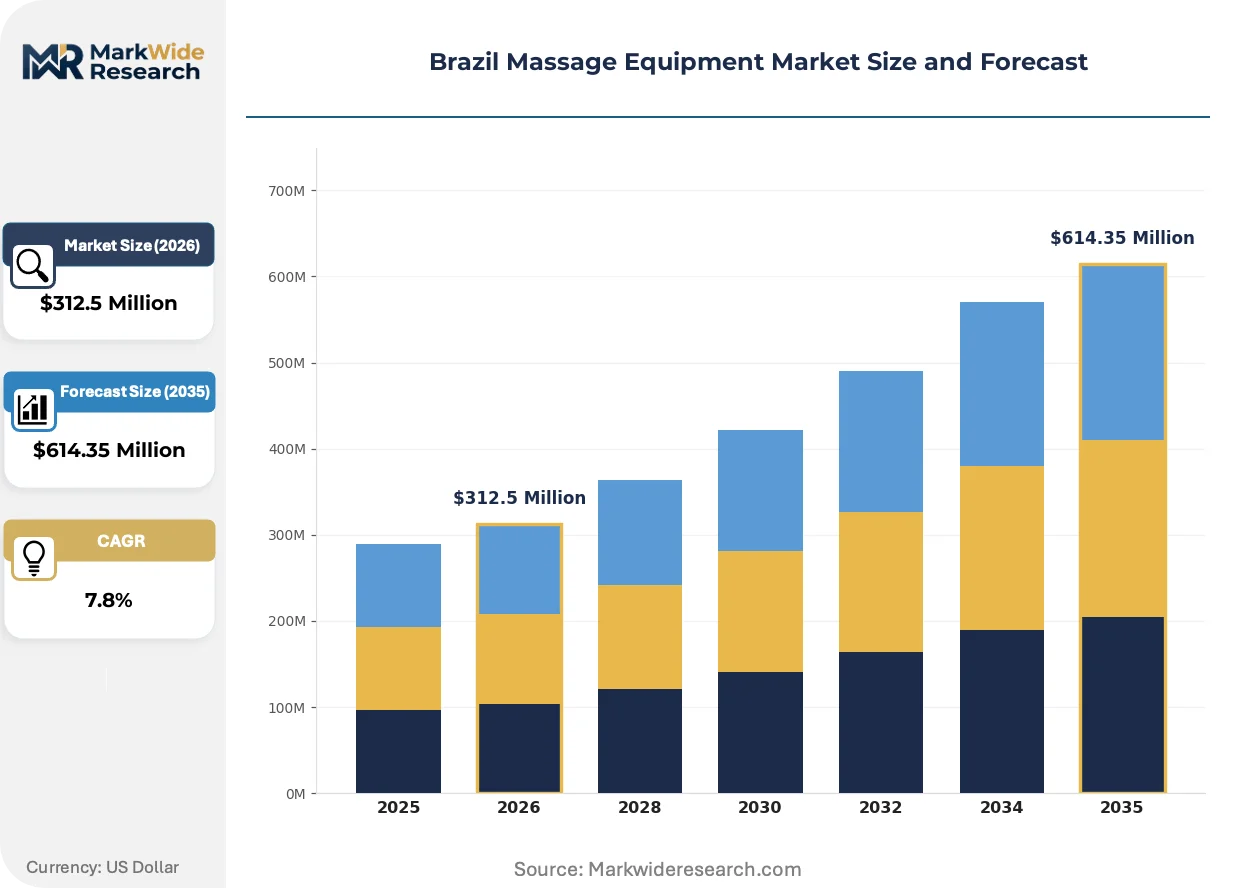
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $614.35 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Massage Chairs, Massage Tables, Hand-Held Massagers, Foot Massagers End User: Fitness Centers, Spas, Home Users, Healthcare Facilities Technology: Electric, Manual, Acupressure, Infrared Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Bodyfriend Inc., Relaxmedic, Panasonic Holdings Corporation, Casada International GmbH, Oster, Beurer GmbH, Plenitude, OMRON Corporation, OSIM International Pte. Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Massage Equipment Market Trends and Innovations
Connected sensor technology and regulatory data requirements are forcing equipment redesign cycles that compress from five-year replacement patterns toward three-year upgrade horizons.
Bluetooth-enabled pressure mapping is digitizing massage chair operation protocols. São Paulo wellness centers are deploying these systems to document treatment consistency for liability protection. The technology is digitizing how spa operators demonstrate service standardization to insurance underwriters and medical tourism accreditation bodies.
ANVISA's proposed medical device reclassification framework is tightening evidentiary requirements for therapeutic claim substantiation. Manufacturers must now generate Brazil-specific clinical data rather than relying on foreign registration certificates. Massage chair importers with existing registration certificates face retroactive compliance audits that could invalidate current product authorizations.
After-sales service unbundling is fragmenting traditional equipment procurement. Brazilian spa operators now negotiate technical support contracts separately from hardware acquisition, favoring distributors with captive service networks over pure trading houses. This pattern concentrates purchasing authority among São Paulo-based procurement teams managing multi-location wellness portfolios.
Brazil Massage Equipment Market Segmentation
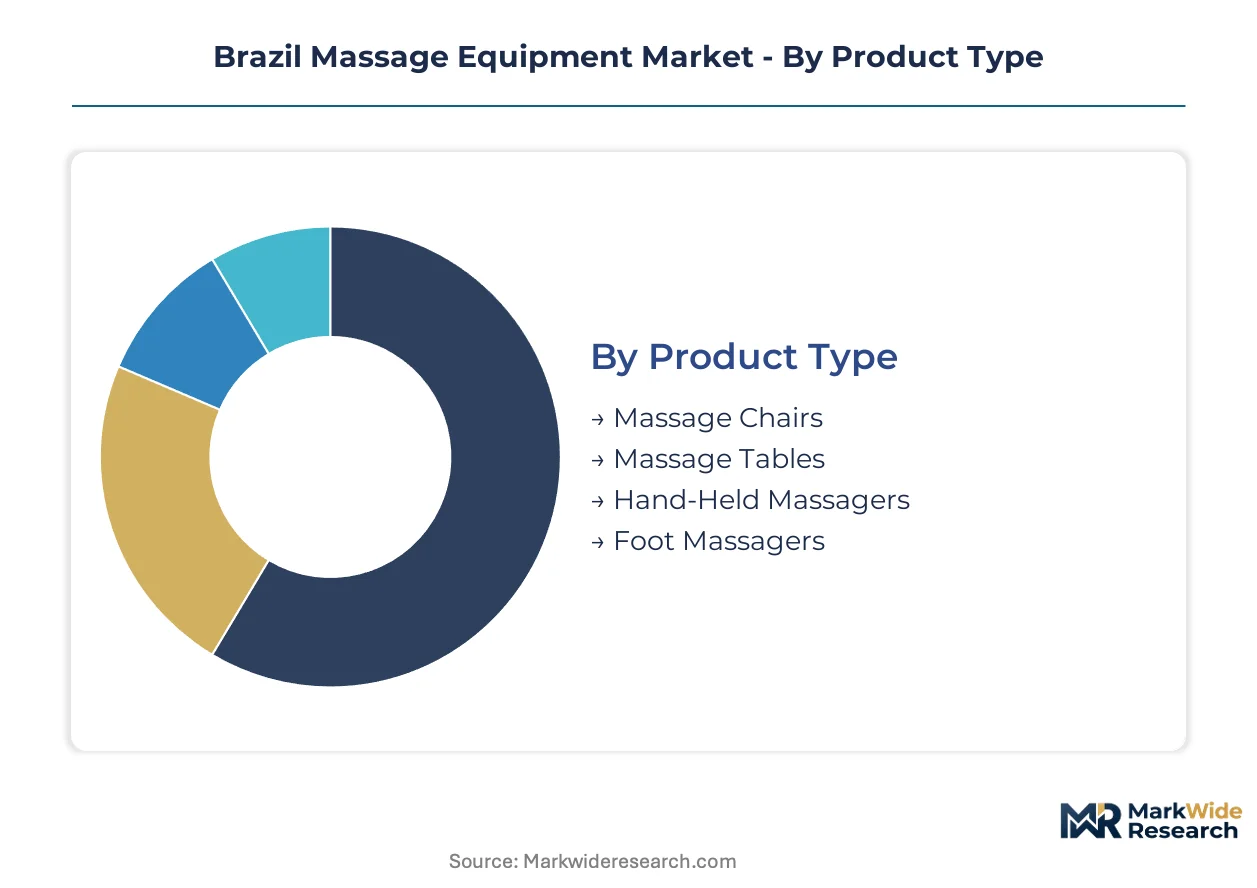
Equipment replacement cycles vary dramatically across Brazil's massage equipment categories, with commercial installations in Rio de Janeiro wellness centers turning over every seven years while compact residential units in São Paulo apartments face obsolescence within three years. Understanding these divergent lifespans helps distributors align inventory financing with actual demand velocity.
Product Type:
Replacement cycles stretch from decade-long investments for institutional furniture to sub-three-year refresh rates for portable electronics, creating fundamentally different cash flow profiles for distributors serving each tier.
- Massage Chairs:Electromechanical systems incorporating 1,800-3,200 RPM motors with integrated heating elements reaching 40-45°C dominate procurement budgets at São Paulo wellness centers. ANVISA medical device registration requirements extend sales cycles to 18-24 months, compressing distributor margins on inventory carrying costs.
- Hand-Held Massagers:Compact percussive devices prioritize storage efficiency for Southeast region households with limited apartment space. Brazilian consumers treat these as disposable wellness accessories rather than durable goods, driving rapid repeat purchase behavior.
- Massage Tables:Stationary and portable frames serve physiotherapy practices in municipal SUS health centers, competing against funded clinical sessions for chronic pain management budgets.
- Foot Massagers:Shiatsu-roller mechanisms with infrared options command premium positioning in spa pedicure service lines, though residential adoption lags behind upper-body alternatives.
Massage chairs anchor the volume base while hand-held massagers gain share at the steepest rate.
End User:
Procurement authority concentrates differently across customer types, with São Paulo-based multi-location wellness portfolios centralizing purchasing decisions while fragmented home users respond to retail channel promotions.
- Spas:Rio de Janeiro and São Paulo operators upgrade electromechanical equipment to capture medical tourism revenue from international visitors. ABNT electromagnetic compatibility compliance has become a non-negotiable specification in tender documents.
- Home Users:Southeast region households prioritize compact electric massagers over full-size chairs, driven by storage constraints in dense urban apartments. Preventive maintenance subscriptions remain underdeveloped for this segment.
- Fitness Centers:Post-workout recovery stations incorporate percussion guns and vibration plates as membership differentiation tools, though equipment utilization rates trail dedicated wellness facilities.
- Healthcare Facilities:SUS-funded physiotherapy departments in municipal health centers deploy massage tables for patient rehabilitation, competing directly with home-use equipment for chronic pain management spending.
Spas anchor the volume base while home users expand most quickly.
Technology:
Margin structures diverge sharply by underlying mechanism, with infrared-equipped systems commanding premium positioning in spa procurement while manual alternatives compete purely on acquisition cost.
- Electric:Motor-driven percussive and oscillating systems dominate installation bases across commercial and residential segments. ANVISA therapeutic claim documentation requirements force manufacturers to generate Brazil-specific clinical data rather than relying on foreign registration certificates.
- Infrared:Heat-integrated systems specify combined percussive-infrared configurations that spa procurement teams favor for higher per-unit margins. Pending ANVISA reclassification proposals threaten retroactive compliance audits for existing product authorizations.
- Manual:Non-powered rollers and pressure tools serve price-sensitive segments with minimal regulatory burden but compressed distributor margins.
- Acupressure:Traditional technique-based devices occupy niche positioning within specialized wellness practices, lacking mainstream retail distribution.
Electric technology anchors the volume base while infrared climbs the fastest.
Distribution Channel:
Service unbundling is fragmenting traditional procurement patterns, with Brazilian spa operators now negotiating technical support contracts separately from hardware acquisition.
- Specialty Stores:São Paulo-based retailers with captive service networks capture commercial wellness procurement, offering ANVISA-authorized repair certification that pure trading houses cannot match. Aftermarket service revenue flows through warranty extensions and preventive maintenance subscriptions.
- Online Retail:E-commerce platforms accelerate hand-held massager turnover among Southeast region home users, though massage chair sales remain constrained by installation and service requirements.
- Direct Sales:Manufacturer representatives target healthcare facility procurement with extended registration documentation support, critical for ANVISA medical device classification compliance.
- Supermarkets:Mass-market retail captures entry-level electric massagers with minimal therapeutic claims, avoiding regulatory complexity that slows specialty channel throughput.
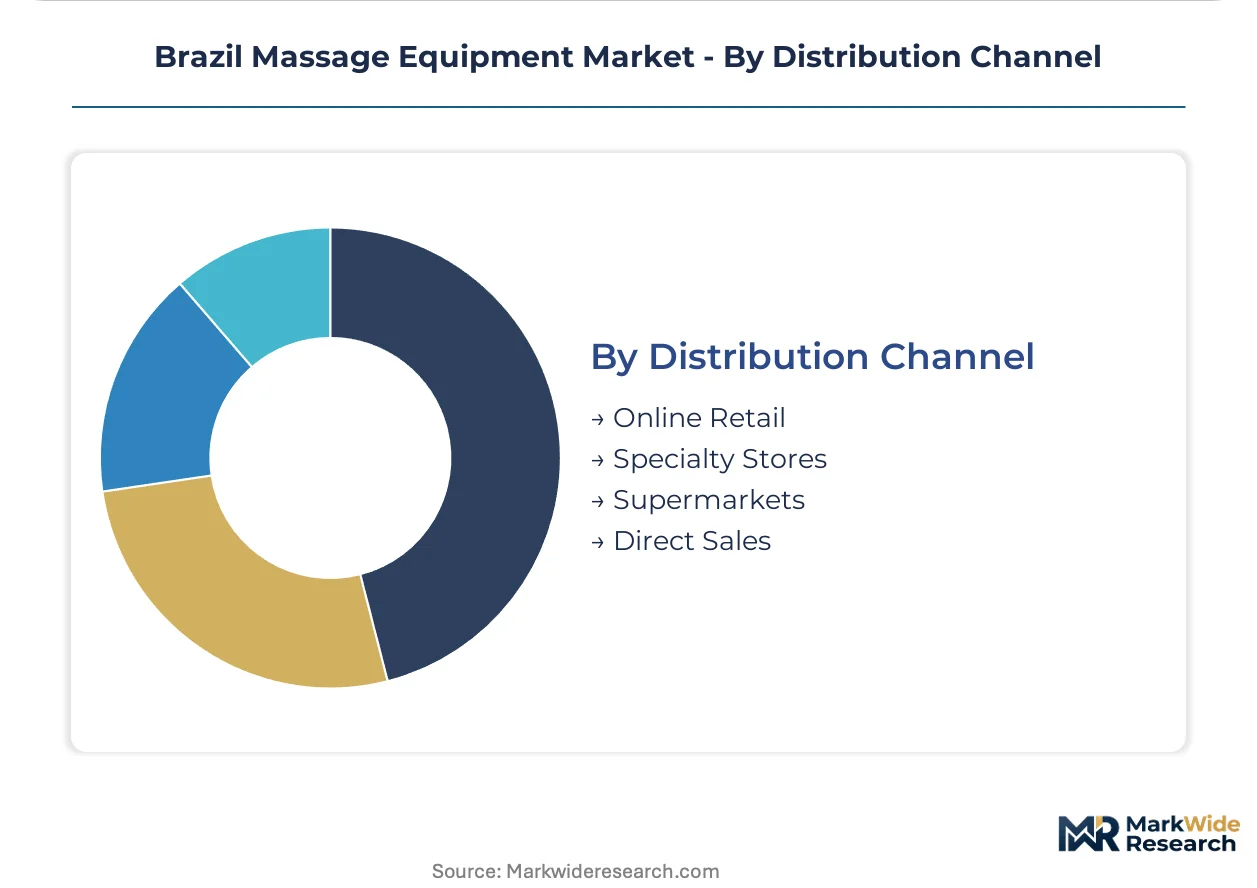
Specialty stores anchor the volume base while online retail expands most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
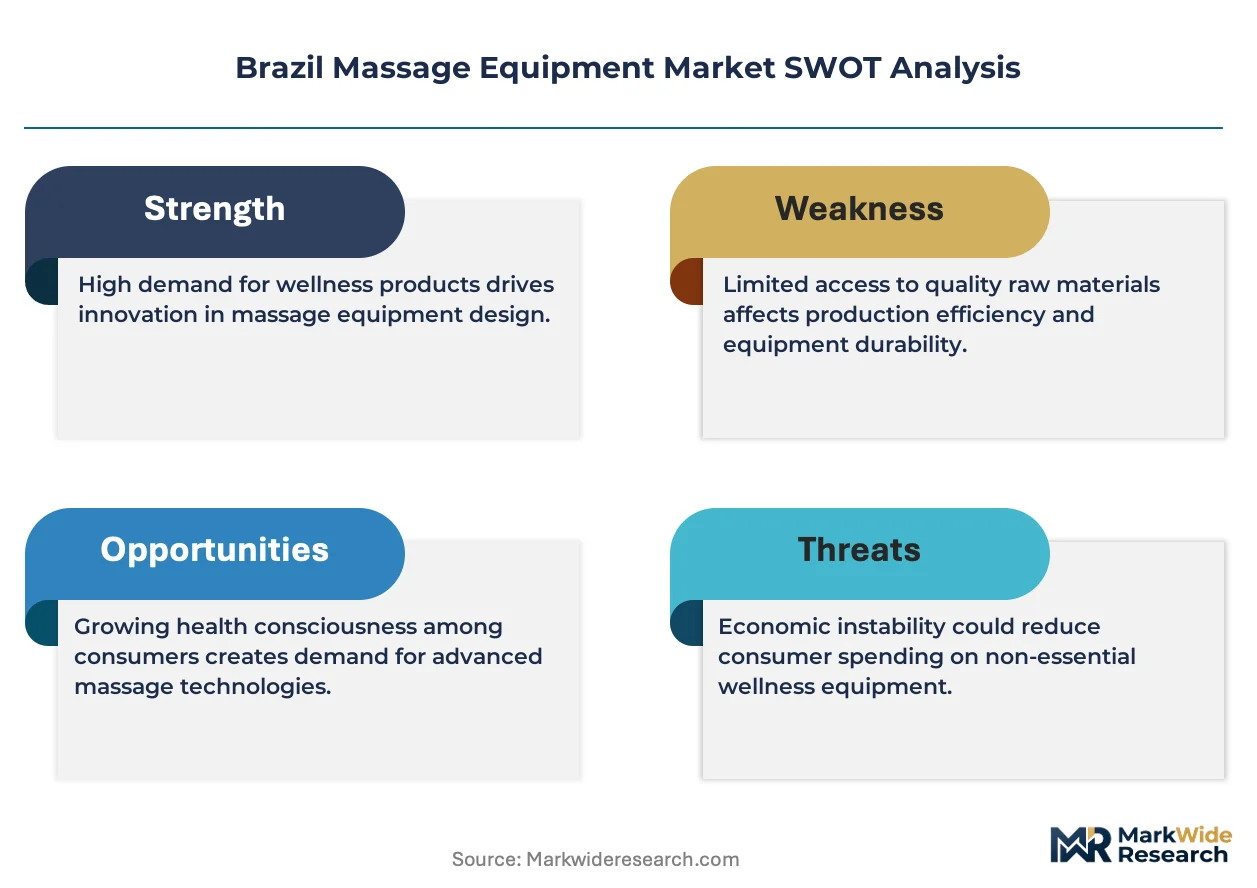
Price elasticity varies sharply across Brazilian sub-regions. Southeast buyers absorb premium massage chair costs for wellness tourism positioning, while Northeast markets demand compact, lower-priced alternatives. ANVISA registration burdens affect all regions uniformly.
São Paulo
Medical tourism revenue drives spa operators toward full-feature electromechanical systems. ANVISA therapeutic claim documentation requirements extend procurement cycles to 18-24 months. São Paulo city wellness centers concentrate multi-location purchasing authority, favoring distributors with captive service networks.
Rio de Janeiro
International visitor traffic pushes beachfront spa operators toward equipment upgrades with ABNT electromagnetic compatibility certification. ANVISA medical device reclassification proposals threaten retroactive compliance audits for existing authorizations. Copacabana and Ipanema wellness clusters specify combined percussive-infrared configurations.
Minas Gerais
Belo Horizonte physiotherapy practices compete with SUS-funded municipal sessions for chronic pain management budgets. The state's national pharmaceutical regulator alignment with federal standards simplifies cross-border equipment sourcing. Contagem industrial suburbs host distributor warehouses serving the broader Southeast.
Bahia
Salvador wellness markets remain underpenetrated by premium massage chair distributors focused on Southeast concentration. Import duty volatility from Chinese manufacturing clusters creates landed cost uncertainty for regional distributors. Historic center spa operators prioritize compact hand-held units due to facility space constraints.
Rio Grande do Sul
Porto Alegre fitness centers deploy post-workout recovery stations as membership differentiation tools. ABNT safety benchmarks reduce technical barriers for Asian manufacturers seeking distribution authorization. The state's southern location creates logistics advantages for Mercosur cross-border equipment flows.
Brazil Massage Equipment Market Competitive Landscape
Capability concentration sits with established electronics conglomerates; scale advantage sits with specialized wellness equipment fabricators. The vendor base stratifies into three tiers: multinational appliance manufacturers with service infrastructure, dedicated massage equipment specialists with clinical positioning, and regional trading houses with price-driven portfolios. Dominant competitive moves include preventive maintenance subscription unbundling and ANVISA-authorized repair certification acquisition.
Among Japanese-based electronics conglomerates, Panasonic Holdings Corporation exemplifies the service-integrated archetype through established technical support networks. German wellness specialists Beurer GmbH and Casada International GmbH occupy positions within the clinical-grade equipment tier, leveraging specialized distributor partnerships for quality control in metropolitan areas. South Korean fabricator Bodyfriend Inc. represents the premium massage chair segment with design-forward positioning.
| Leading Market Players |
|---|
| Bodyfriend Inc. |
| Relaxmedic |
| Panasonic Holdings Corporation |
| Casada International GmbH |
| Oster |
| Beurer GmbH |
| Plenitude |
| OMRON Corporation |
| OSIM International Pte. Ltd. |
| Others |
Pricing and Supply Chain Analysis
Import duty volatility between Brazilian customs and Chinese manufacturing clusters compresses distributor margins while forcing tiered pricing stratification that separates premium ANVISA-registered systems from gray-market alternatives. This tariff exposure determines both the three-tier pricing structure across premium, standard, and economy levels and the geographic concentration of bonded warehouse infrastructure in São Paulo state.
Pricing Analysis
Preventive maintenance subscriptions and extended warranty contracts now drive lifetime value capture for commercial wellness operators. Three-tier pricing structure across premium, standard, and economy levels separates infrared-equipped spa systems from basic electric units and manual alternatives. Cost compression in the mid-market segment is intensifying because ANVISA registration timelines extend inventory carrying costs. Home users in Southeast apartments exhibit highest price sensitivity, while medical tourism-focused spas absorb premium positioning.
Supply Chain Analysis
Tariff exposure between Brazil and China dominates supply chain risk calculus for electromechanical component sourcing. Manufacturing concentrates in China, South Korea, and Taiwan for motor assemblies, heating elements, and sensor modules. Raw material dependencies span copper windings, semiconductor controllers, and infrared emitter substrates. Distribution runs through São Paulo-based specialty retailers with captive service networks rather than pure trading houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Brazilian massage equipment market rewards players who control scarce ANVISA-authorized repair certification capacity, as biomedical technician graduation rates trail commercial installation growth. This capability gap creates durable competitive separation between service-integrated distributors and hardware-only traders.
For Market Incumbents: Build captive technical certification moats through exclusive partnerships with ANVISA-authorized training programs. Panasonic Holdings Corporation exemplifies this archetype through established electronics service infrastructure. Defend against emerging pure-play traders by deepening backward integration into preventive maintenance subscription platforms. Capacity addition in Northeast regional hubs counters Southeast concentration risk. For New Entrants and Emerging Players: Mid-market commercial spas in Recife and Salvador represent the most penetrable entry point given incumbent Southeast fixation. Compact hand-held massagers for dense urban apartments offer lower regulatory barriers than massage chair registration cycles. Partner with São Paulo-based multi-location wellness procurement teams for technical support contract unbundling. For Investors and Strategic Acquirers: The market sits at a regulatory-intensification phase that favors service-integrated distributors over pure hardware traders. Long-term viability across the projection horizon hinges on ANVISA compliance infrastructure rather than product innovation alone. Watch pending electromagnetic compatibility standard updates as inflection indicators for legacy inventory obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA-Authorized Repair Certification | Captive technician pipelines lock in recurring service revenue from São Paulo wellness portfolios. |
| Preventive Maintenance Subscription Unbundling | Separates hardware margins from recurring technical support contracts in commercial procurement. |
| Infrared-Heat Convergence Product Development | Combined percussive-infrared configurations command premium positioning in Copacabana spa tenders. |
| Northeast Regional Distribution Expansion | Recife and Salvador markets remain underpenetrated by Southeast-focused premium chair distributors. |
| Bluetooth-Enabled Pressure Mapping Integration | Digitized treatment protocols satisfy medical tourism accreditation body documentation requirements. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with spa operators, biomedical technicians, ANVISA regulatory consultants, and São Paulo-based procurement managers; and secondary validation through ANVISA registration databases, ABNT electromagnetic compatibility filings, and customs import records. Bottom-up demand modeling across product types and end-user segments triangulated against top-down market sizing from distributor revenue disclosures.
Forecast inputs incorporated replacement cycle velocities by equipment category, ANVISA registration timeline assumptions, and wellness tourism revenue elasticity across the analysis window. Segmentation dimensions spanned product type, end-user archetype, technology mechanism, and distribution channel. CAGRs derived from regression analysis of historical installation base growth correlated with municipal physiotherapy funding and medical tourism visitor volumes.
Practitioners should monitor ANVISA reclassification proposals and electromagnetic compatibility standard updates for early signals of compliance cost shifts. Forecasts reflect assumptions about regulatory stability and import duty classification continuity that operating reality may revise. Continuous validation against distributor inventory carrying costs and technician graduation rates is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Global Hospital Equipment and Supplies Market
Medical Equipment
Cryopreservation Systems Market
Medical Equipment
Medical Ethylene Oxide Sterilization Equipment Market
Medical Equipment
Medical Air Sterilizer Market
Medical Equipment
Nuclear Medicine Equipment Market
Medical Equipment
Global Latex Medical Gloves Market
Medical Equipment
Air Fluidized Therapy Beds Market
Medical Equipment
Global Medical Gas Analyzer Market
Medical Equipment
MRI Transport Market
Medical Equipment
Middle East and Africa Thermal Cyclers Market
Medical Equipment
Hemodialysis Equipment Market
Medical Equipment
Minor Surgical Lights Market
Medical Equipment
New-Born Screening Equipment Market
Medical Equipment
Patient Lifting Equipment Market
Medical Equipment
Urodynamic Equipment Market
Medical Equipment
Global Medical Lighting Technologies Market