
 Tobramycin Eye Drop Market | 2026-2036
Tobramycin Eye Drop Market Size, Share, and Industry Trends Forecast 2026-2036
Tobramycin Eye Drop Market Analytics
Indian generic API production is shifting toward sterile ophthalmic capacity as export qualification requirements tighten. Hikma Pharmaceuticals PLC leverages its vertically integrated sterile manufacturing network to supply regulated markets. Bausch Health Companies Inc. anchors North American distribution through specialty ophthalmology channels. Novartis AG competes on branded formulation science across European hospital tenders.
Tobramycin eye drops constitute an aminoglycoside antibiotic solution typically formulated at 0.3% concentration for topical ocular administration, manufactured under aseptic filling conditions to maintain sterility and prevent particulate contamination. The product targets gram-negative bacterial infections including Pseudomonas aeruginosa in corneal ulcers and post-surgical prophylaxis. Preservative-free single-dose vials command premium positioning in surgical settings where endothelium safety dictates formulation purity. Multidose bottles retain volume leadership in retail pharmacy channels despite growing hospital preference for unit-dose packaging. Ophthalmology clinics represent the fastest-growing end-user segment as ambulatory surgical center volumes expand and same-day discharge protocols proliferate.
The US FDA enforces ophthalmic sterility through Current Good Manufacturing Practice inspections and post-market adverse event surveillance, while the EMA's Annex 1 revision mandates barrier technology upgrades for European sterile facilities. India's CDSCO aligns with PIC/S guidelines for export-oriented ophthalmic manufacturers seeking WHO-prequalification. Stakeholders must monitor regulatory divergence between preservative-free mandates in Western markets and cost-driven multidose tolerance in emerging economies.
Market Dynamics
Preservative-free formulation mandates from the US FDA are compressing multidose bottle economics while surgical volume growth in tertiary eye care centers accelerates unit-dose vial demand. This regulatory-surgical tension is reallocating manufacturing capacity toward aseptic blow-fill-seal lines and single-dose packaging infrastructure.
Growth Catalysts
- Post-operative infection protocols:Tertiary eye care centers in the United States are tightening prophylactic antibiotic regimens after cataract and refractive procedures, expanding tobramycin utilization in same-day discharge settings.
- EMA Annex 1 revision:Barrier technology upgrades mandated for European sterile facilities are disqualifying legacy multidose manufacturers, creating supply vacuum for compliant preservative-free alternatives.
- Ambulatory surgical center expansion:United States outpatient ophthalmology volumes are displacing inpatient procedures, concentrating antibiotic demand in clinic-based procurement channels.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient production clusters in Indian sterile manufacturing zones, creating vulnerability to export qualification delays and regulatory inspection backlogs.
- Preservative-free cost structure:Single-dose vial manufacturing requires aseptic blow-fill-seal equipment with higher per-unit packaging costs than multidose alternatives, compressing margin at price-sensitive accounts.
- Fluoroquinolone substitution:Moxifloxacin and gatifloxacin formulations compete for gram-negative coverage in post-surgical prophylaxis, particularly where Pseudomonas resistance profiles favor broader-spectrum agents.
Strategic Opportunities
- Indian CDSCO export alignment:PIC/S guideline adoption for WHO-prequalified sterile ophthalmic facilities opens regulated market access for compliant API and finished dose manufacturers.
- Combination formulation development:Tobramycin-dexamethasone fixed-dose products address surgical inflammation-infection protocols in single administration, reducing drop burden and improving compliance.
- Hospital pharmacy direct contracting:Bypassing wholesale distribution through integrated delivery network agreements captures formulary placement and volume commitments from United States health systems.
Industry Challenges
- Aseptic fill-finish talent scarcity:Qualified personnel for isolator technology operation and media fill validation are concentrated among legacy parenteral manufacturers, constraining ophthalmic capacity expansion.
- ISO 15378 certification timelines:Primary packaging material qualification for pharmaceutical-grade plastic resins extends supplier onboarding, delaying preservative-free product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tobramycin Eye Drop Market |
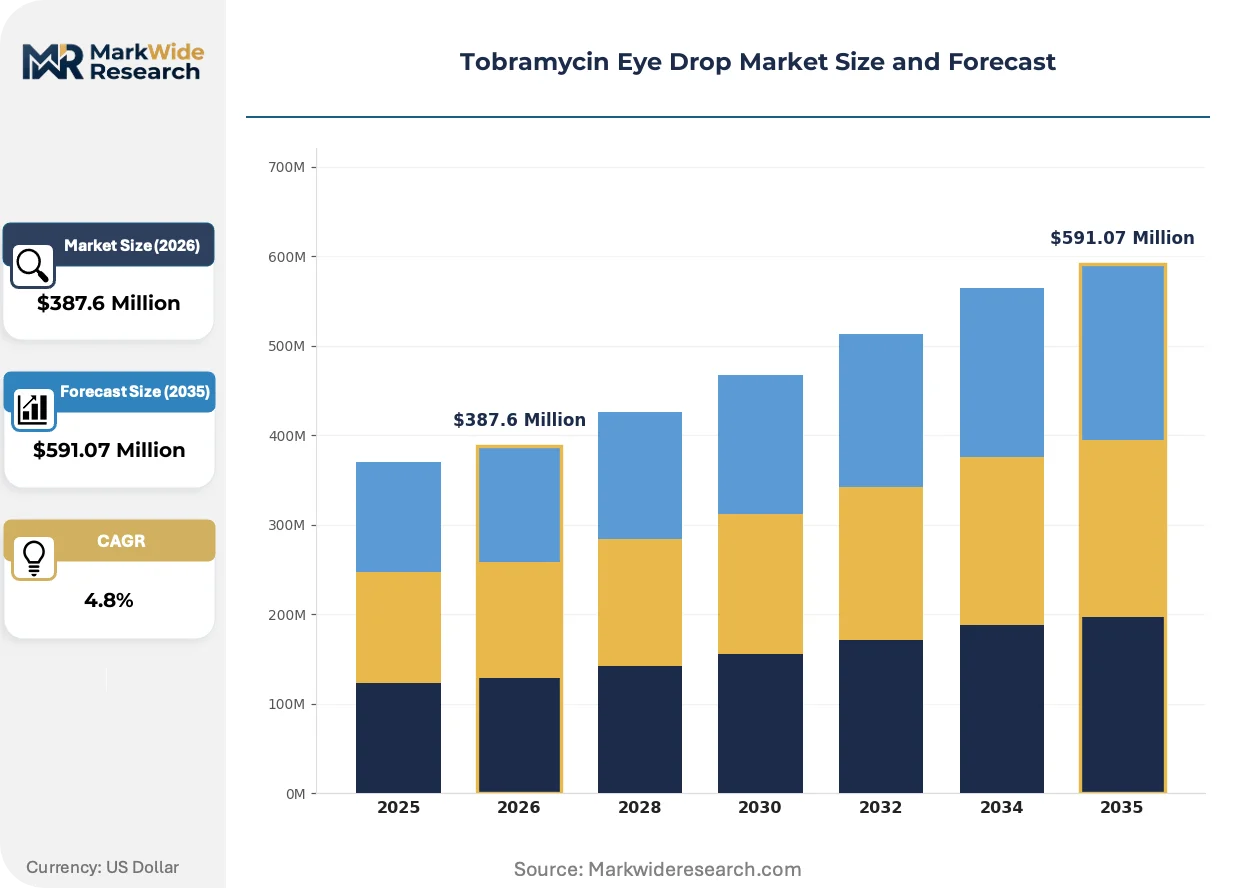
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $591.07 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Preservative-Free Drops, Multidose Bottles, Single-Dose Vials, Antibiotic Formulations End User: Ophthalmology Clinics, Hospitals, Retail Pharmacies, Home Care Settings Delivery Mode: Topical Application, Intravitreal Injection, Systemic Therapy, Device-Assisted Delivery Therapy Area: Infectious Diseases, Anti-Inflammatory Treatment, Allergic Conjunctivitis, Post-Operative Care |
| Companies Covered | Hikma Pharmaceuticals PLC, Bausch Health Companies Inc., Novartis AG, Akorn Operating Company LLC, Zydus Group, Incepta Pharmaceuticals Ltd., Grevis Pharmaceuticals Pvt Ltd., Hilbert Healthcare, Alembic Pharmaceuticals Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tobramycin Eye Drop Market Evolving Landscape
Blow-fill-seal automation is displacing conventional aseptic filling in ophthalmic manufacturing, while regulatory sterility guidance tightens across multiple geographies. Procurement concentration in hospital systems is compressing supplier margins and accelerating channel consolidation.
Robotic isolator technology is automating aseptic filling operations for preservative-free ophthalmic solutions. United States and European contract manufacturers are adopting closed-barrier systems at accelerated pace to meet FDA and EMA sterility expectations. This automation is compressing batch failure rates and enabling continuous processing that reduces human intervention contamination risk.
The US FDA's updated ophthalmic sterility guidance document imposes enhanced environmental monitoring and container-closure integrity testing. European manufacturers face parallel pressure from EMA Annex 1 revisions requiring isolator or restricted access barrier systems. Hospital procurement committees in Germany and France are now requiring documented compliance with these standards for formulary inclusion.
Buying concentration in United States integrated delivery networks is consolidating antibiotic procurement under centralized pharmacy and therapeutics committees. Specialty distributors serving ambulatory surgical centers are displacing traditional wholesale channels through direct-to-site logistics and inventory management services. This shift is most visible in Florida and Texas markets where ophthalmology clinic consolidation has proceeded fastest.
Tobramycin Eye Drop Market Segmentation
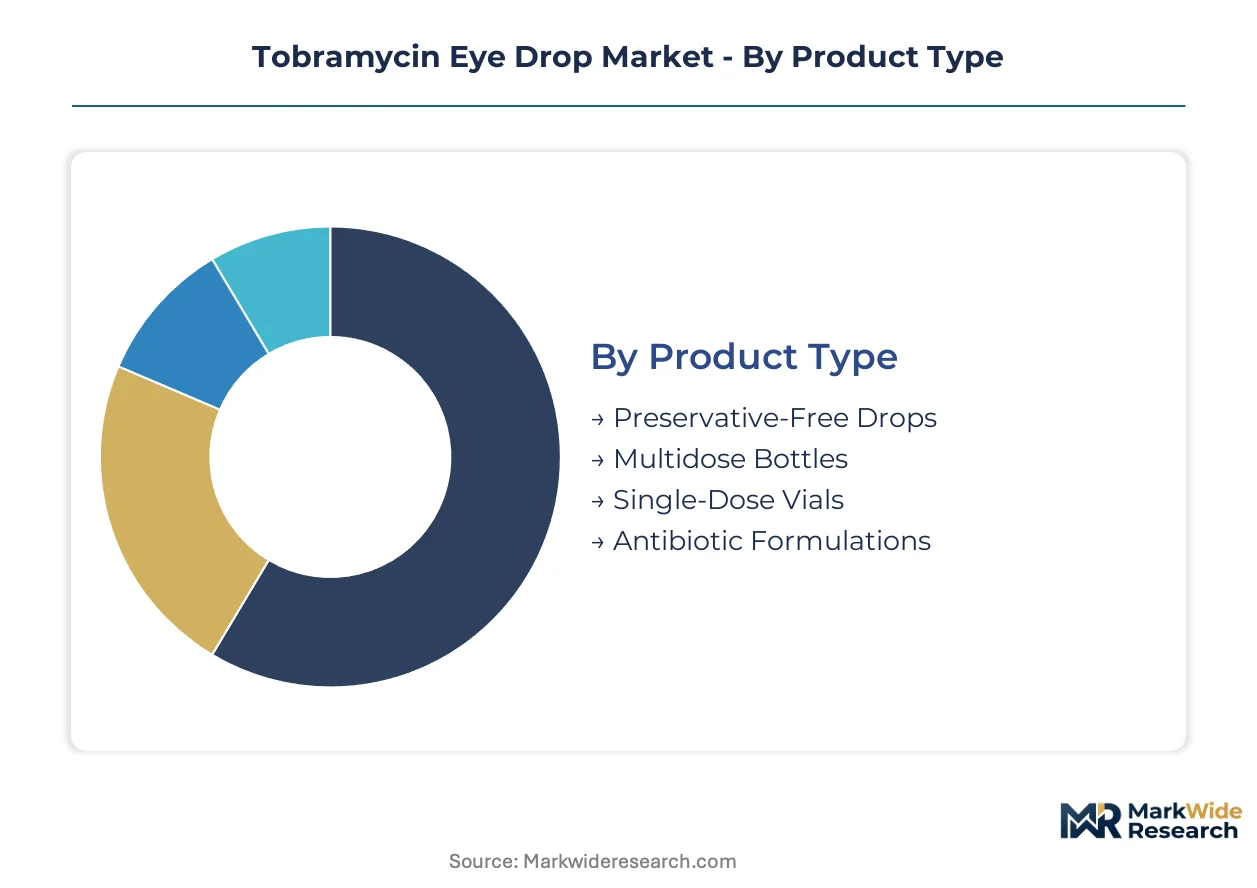
Tobramycin eye drop segmentation reveals divergent margin profiles across formulation technologies and procurement channels. Product type and end-user splits determine manufacturing investment priorities and regulatory compliance burdens.
Product Type:
Volume leadership sits with legacy multidose formats, while premium capture concentrates in sterile single-unit presentations demanded by surgical protocols.
- Preservative-Free Drops:Eliminate benzalkonium chloride and stabilizing agents to reduce corneal epithelium toxicity in repeat-dose regimens. United States tertiary eye care centers now mandate these formulations for post-operative prophylaxis, with FDA sterility guidance tightening manufacturing requirements. Today's leader: Multidose Bottles. Tomorrow's challenger: Preservative-Free Drops.
- Multidose Bottles:Retain cost advantage through conventional aseptic filling and plastic squeeze-container packaging. Retail pharmacy channels in price-sensitive markets continue procurement of these presentations despite hospital formulary restrictions.
- Single-Dose Vials:Blow-fill-seal manufactured units eliminate contamination risk between doses. Ambulatory surgical centers in Florida and Texas displace multidose alternatives through infection control committees.
- Antibiotic Formulations:Standard 0.3% tobramycin concentration solutions target gram-negative coverage including Pseudomonas aeruginosa.
Manufacturing capacity is reallocating toward aseptic barrier technology as procurement committees elevate sterility documentation requirements.
End User:
Channel concentration determines pricing leverage, with integrated delivery networks extracting volume discounts unavailable to fragmented retail accounts.
- Ophthalmology Clinics:Ambulatory surgical centers performing same-day cataract and refractive procedures drive antibiotic consumption through direct-to-site distribution arrangements. Same-day discharge protocols in United States outpatient settings concentrate procurement under specialty distributor contracts.
- Hospitals:Tertiary eye care centers maintain centralized pharmacy and therapeutics committees that mandate preservative-free formulary placement. Post-operative infection protocol tightening expands tobramycin utilization in surgical wards.
- Retail Pharmacies:Community dispensing channels retain multidose bottle preference where patient cost-sharing limits premium formulation uptake.
- Home Care Settings:Self-administered regimens for chronic blepharitis and recurrent conjunctivitis generate recurring prescription volume through mail-order pharmacy channels.
Procurement gravity is shifting toward clinic-based channels as inpatient ophthalmology volumes contract.
Delivery Mode:
Topical administration dominates commercial volume, while device-assisted formats capture development investment from precision dosing requirements.
- Topical Application:Standard dropper bottle and single-dose vial instillation delivers 0.3% solution to conjunctival sac. United States and European hospital formularies specify this route for prophylactic and therapeutic indications.
- Intravitreal Injection:Direct posterior segment delivery addresses severe endophthalmitis where topical penetration proves insufficient. Compounding pharmacies prepare these presentations under stricter USP 797 guidelines.
- Systemic Therapy:Oral or intravenous aminoglycoside administration complements topical regimens in orbital cellulitis and deep tissue infections.
- Device-Assisted Delivery:Punctal plug reservoirs and contact lens drug-eluting systems extend dosing intervals for chronic conditions.
Route selection pivots on infection severity and anatomical penetration requirements rather than patient convenience.
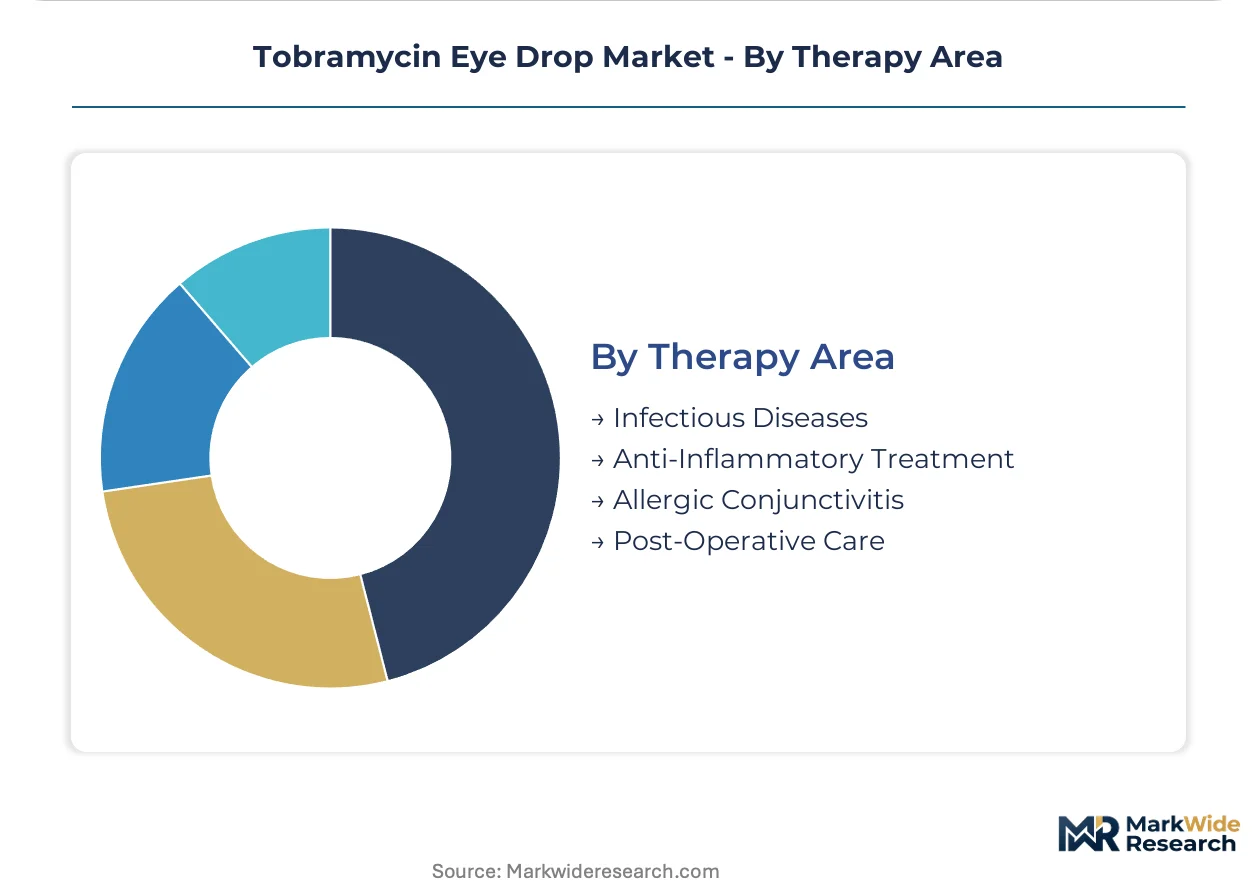
Therapy Area:
Post-surgical prophylaxis generates premium pricing tolerance, while infectious disease applications face generic substitution pressure.
- Post-Operative Care:Cataract and refractive surgery protocols mandate antibiotic prophylaxis against Pseudomonas and Staphylococcus colonization. United States ambulatory surgical centers specify preservative-free tobramycin in same-day discharge bundles.
- Infectious Diseases:Confirmed bacterial keratitis and corneal ulcer treatment requires gram-negative coverage where Pseudomonas resistance profiles favor aminoglycoside selection.
- Anti-Inflammatory Treatment:Combination tobramycin-dexamethasone formulations address concurrent infection and inflammation in surgical settings.
- Allergic Conjunctivitis:Off-label antibiotic use persists where bacterial superinfection complicates allergic presentations.
Revenue concentration aligns with surgical volume expansion rather than infectious disease incidence trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States tertiary eye care centers enforce stricter preservative-free mandates than Indian export-oriented manufacturers currently accommodate, creating divergent compliance timelines across manufacturing bases.
United States
Ambulatory surgical centers in Florida and Texas drive unit-dose vial demand through same-day discharge protocols. FDA ophthalmic sterility guidance tightens environmental monitoring requirements for aseptic filling operations. Boston and Baltimore clusters concentrate compounding pharmacy capacity for intravitreal preparations under USP 797.
Germany
Hospital procurement committees in Bavaria and Baden-Württemberg mandate EMA Annex 1 compliance for formulary inclusion. The country's national pharmaceutical regulator enforces isolator technology upgrades across sterile facilities. Frankfurt-Rhine-Main corridor hosts barrier technology equipment suppliers serving ophthalmic contract manufacturers.
India
Hyderabad and Ahmedabad sterile manufacturing zones expand aseptic ophthalmic capacity for WHO-prequalified export markets. CDSCO alignment with PIC/S guidelines determines regulated market access eligibility. Gujarat clusters concentrate API production subject to export qualification inspection backlogs.
Japan
Tokyo and Osaka metropolitan areas concentrate demand for combination tobramycin-dexamethasone formulations in refractive surgery bundles. PMDA manufacturing standards exceed baseline ICH requirements for preservative-free presentations. Nagoya-Chubu corridor hosts automated blow-fill-seal equipment installations serving domestic ophthalmic producers.
Switzerland
Basel pharmaceutical clusters specialize in high-value branded formulation science for European hospital tenders. Swissmedic standards for sterile ophthalmic manufacturing attract quality-sensitive procurement from neighboring EU markets. Geneva-Lausanne corridor concentrates precision dosing device development for chronic therapy applications.
Tobramycin Eye Drop Market Competitive Landscape
United States producers anchor one tier; Indian specialists hold cost-advantaged positions in API and finished dose supply. The market presents a bifurcated structure where regulated-market compliance separates premium positioning from volume-driven generic supply. Three archetypes dominate: vertically integrated sterile manufacturers, regional formulation specialists, and contract development organizations with barrier technology capabilities. Capacity expansion and portfolio diversification toward preservative-free presentations constitute the dominant competitive vectors.
Within the vertically integrated tier, Hikma Pharmaceuticals PLC and Bausch Health Companies Inc. exemplify manufacturers combining API control with sterile fill-finish infrastructure. Novartis AG occupies a position emphasizing branded formulation science across European procurement channels. These three entities represent contrasting geographic and strategic orientations within the competitive set.
| Leading Market Players |
|---|
| Hikma Pharmaceuticals PLC |
| Bausch Health Companies Inc. |
| Novartis AG |
| Akorn Operating Company LLC |
| Zydus Group |
| Incepta Pharmaceuticals Ltd. |
| Grevis Pharmaceuticals Pvt Ltd. |
| Hilbert Healthcare |
| Alembic Pharmaceuticals Limited |
| Others |
Value Network & Pricing Analysis
Captive sterile manufacturing networks in India and the United States anchor supply positions while simultaneously determining pricing power through API control and aseptic fill-finish capability. Hospital procurement committees exploit this concentration by demanding documented FDA sterility compliance as a condition of formulary placement, compressing margins for non-integrated suppliers.
Pricing Analysis
Capacity additions in Hyderabad and Ahmedabad sterile zones are reshaping price floors for preservative-free presentations as export qualification requirements tighten. Three-tier pricing structure across preservative-free premium, standard multidose, and economy generic levels stratifies according to EMA Annex 1 certification status and barrier technology documentation. Cost compression in the multidose segment is intensifying because retail pharmacy channels in price-sensitive markets resist premium formulation uptake. Ambulatory surgical centers exhibit least price sensitivity due to bundled reimbursement protocols, while independent ophthalmology clinics in emerging economies demonstrate highest elasticity.
Supply Chain Analysis
Dual-sourcing mandates from United States integrated delivery networks require qualified backup suppliers for tobramycin API and finished dose, extending qualification timelines. Supply concentrates in India for active pharmaceutical ingredient, the United States for sterile fill-finish, and Germany for barrier technology equipment. Raw material dependencies encompass pharmaceutical-grade plastic resins, blow-fill-seal machinery components, and sterile packaging films. Single-source vulnerability runs through Indian API clusters subject to CDSCO inspection backlogs. Distribution runs through specialty ophthalmic distributors serving ambulatory surgical centers, displacing traditional wholesale channels in Florida and Texas markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tobramycin eye drop market functions as a stable compounder anchored by irreversible surgical volume expansion in aging populations and tightening infection control protocols that mandate antibiotic prophylaxis.
For Market Incumbents: Deploy barrier technology certification as a competitive moat by accelerating isolator upgrades ahead of EMA Annex 1 enforcement deadlines. Consolidate formulary position through direct contracting with United States integrated delivery networks, capturing volume commitments that lock out fluoroquinolone substitutes. Deepen backward integration into API supply to insulate against Indian export qualification delays. For New Entrants and Emerging Players: The price-point gap between European hospital-grade preservative-free vials and emerging-market multidose bottles creates entry space for mid-tier certified alternatives. Target Indian CDSCO-aligned manufacturers seeking PIC/S qualification for WHO-prequalified export markets as the most penetrable supply-side entry point. Pursue toll manufacturing arrangements with established sterile facilities to bypass capital-intensive aseptic fill-finish investment. For Investors and Strategic Acquirers: Roll-up economics work for contract development organizations with barrier technology capabilities because hospital procurement consolidation is concentrating demand among compliant suppliers. Five-to-ten year viability rests on regulatory divergence between preservative-free mandates in Western markets and cost-driven multidose tolerance elsewhere. Monitor FDA adverse event surveillance data for sterility failures as the inflection indicator signaling accelerated market share shifts toward certified manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Technology Certification | EMA Annex 1 compliance unlocks European hospital formulary placement against non-compliant competitors. |
| API Backward Integration | In-house sterile aminoglycoside production insulates margin from Indian export inspection backlogs. |
| Hospital Direct Contracting | Integrated delivery network agreements capture volume commitments and displace wholesale intermediaries. |
| Combination Formulation Development | Tobramycin-dexamethasone fixed-dose products address surgical inflammation-infection protocols in single administration. |
| PIC/S Alignment Investment | CDSCO guideline adoption opens WHO-prequalified export access to regulated markets. |
Research Methodology
Direct dialogue with sterile manufacturing executives, hospital pharmacy and therapeutics committee members, ophthalmology clinic procurement managers, and regulatory affairs specialists grounded qualitative findings. Secondary validation drew from FDA ophthalmic sterility guidance documents, EMA Annex 1 revision drafts, CDSCO circulars, and hospital formulary databases. Bottom-up and top-down triangulation reconciled unit-dose vial demand projections with ambulatory surgical center volume data.
Bottom-up modeling segmented the market across formulation type, end-user channel, and regional regulatory cluster, while top-down analysis cross-checked aggregate value against tertiary eye care center expenditure patterns. CAGRs were derived from surgical volume trajectories and formulary placement timelines across the projection horizon. Forecast inputs incorporated FDA inspection enforcement intensity, EMA barrier technology upgrade compliance rates, and ambulatory surgical center same-day discharge protocol adoption curves.
Caveats apply where FDA sterility guidance enforcement delays, Indian API export qualification backlogs, or fluoroquinolone resistance profile shifts could materially shift the outlook. Deviation in hospital procurement committee preservative-free mandate timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Retinal Disorder Treatment Market
Ophthalmology
Global Optic Nerve Disorders Treatment Market
Ophthalmology
Blepharitis Treatment Market
Ophthalmology
Global Tonometer Market
Ophthalmology
Ophthalmic Viscosurgical Devices Market
Ophthalmology
USA Ophthalmic Devices Market
Ophthalmology
Japan Ophthalmic Devices and Drugs Market
Ophthalmology
Ocular Hypertension Treatment Market
Ophthalmology
CNV (Choroidal Neovascularization) Market
Ophthalmology
Global Aphakia Market
Ophthalmology
Canada Ophthalmology Drugs and Devices Market
Ophthalmology
Light Therapy Glasses Market
Ophthalmology
Cataract Treatment Market
Ophthalmology
Diabetes Associated Ophthalmic Treatment Market
Ophthalmology
Excimer and Femtosecond Ophthalmic Lasers Market
Ophthalmology
Intraocular Lymphoma Treatment Market