
 Bullous Keratopathy Market | 2026-2036
Bullous Keratopathy Market Size, Share, and Industry Trends Forecast 2026-2036
Bullous Keratopathy Market Outlook
Ophthalmology clinics are rebalancing toward combination therapy protocols that integrate pharmacological management with staged surgical intervention. Alcon Inc. leverages its intraocular portfolio to anchor corneal viscoelastic adjacencies, while Bausch + Lomb competes through sustained dominance in ophthalmic pharmaceutical distribution. Carl Zeiss Meditec AG differentiates via surgical visualization platforms that support endothelial keratoplasty precision.
Bullous keratopathy denotes corneal endothelial dysfunction with stromal edema and epithelial bullae formation, typically arising from postsurgical, traumatic, or Fuchs endothelial dystrophy etiologies. The condition disrupts corneal deturgescence, necessitating interventions ranging from hypertonic saline drops to Descemet stripping automated endothelial keratoplasty. Surgical implants command premium positioning due to tissue scarcity and graft survival dependencies, whereas pharmacological treatments serve as maintenance protocols for patients awaiting transplant or managing early-stage disease. Homecare settings represent an expanding channel for chronic topical therapy delivery, though hospitals retain procedural revenue concentration.
The FDA regulates corneal tissue and surgical devices under distinct premarket pathways, while the EMA's Advanced Therapy Medicinal Products framework shapes European cell therapy entry. ISO 14155 governs clinical investigation standards for ophthalmic device trials across multiple jurisdictions. Stakeholders must monitor regulatory convergence between tissue-based and synthetic implant classifications, as this boundary determines reimbursement tiers and manufacturing compliance burdens.
Market Dynamics
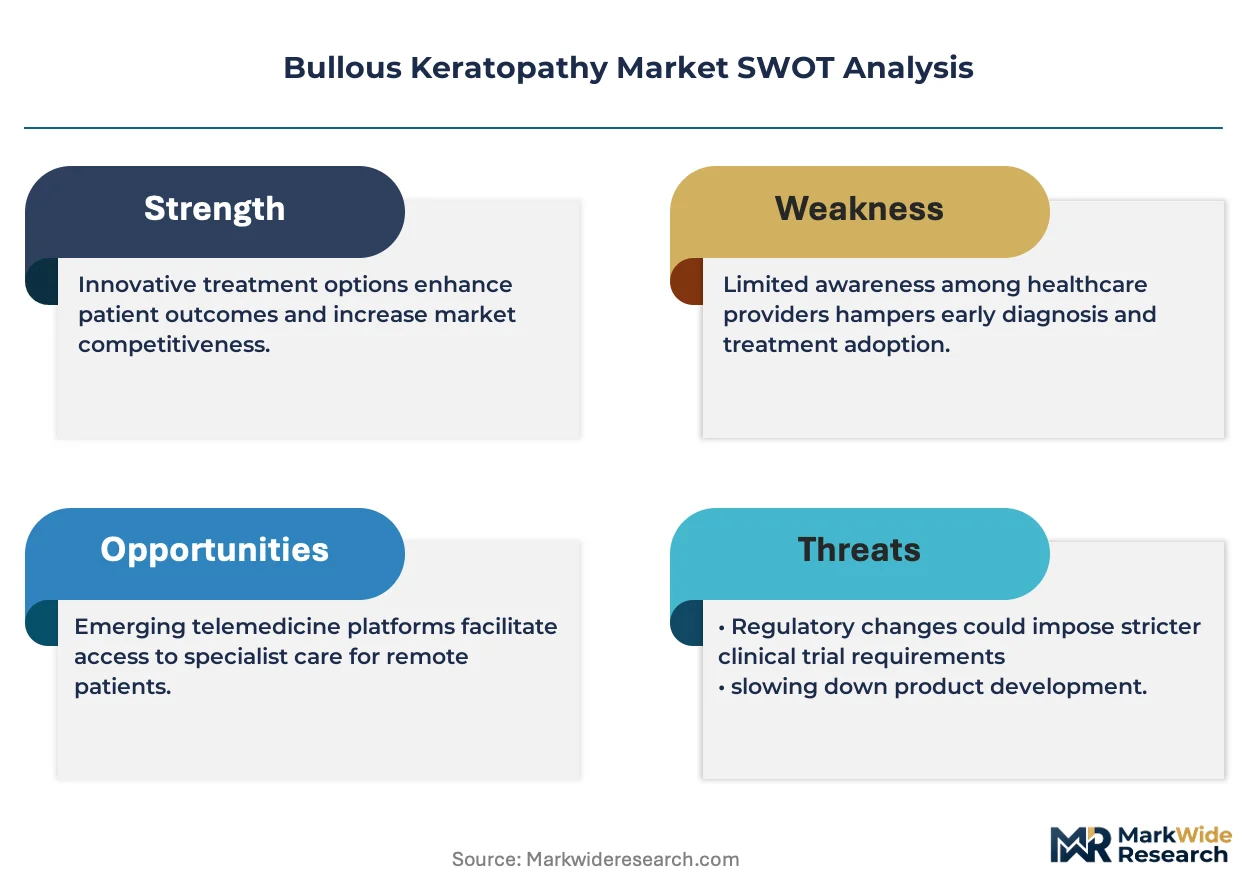
The bullous keratopathy market pivots on tissue scarcity dynamics that elevate surgical implant premiums while accelerating regenerative medicine alternatives. Corneal donor shortages concentrate procurement power among specialized eye banks, forcing clinicians toward staged intervention protocols.
Growth Catalysts
- Regenerative Medicine Frameworks:The FDA's evolving guidance for cell-based therapies compresses clinical validation timelines for endothelial replacement products.
- Descemet's Membrane Endothelial Keratoplasty:Surgical centers in the United States leverage matured Medicare reimbursement pathways to expand procedure volumes.
- Corneal Viscoelastic Adjacencies:Intraoperative pharmaceutical portfolios anchor combination therapy protocols that integrate pharmacological management with surgical staging.
Market Restraints
- Donor Tissue Volatility:Eye bank distribution networks face geographic concentration risk in the United States, where procurement shortfalls disrupt surgical scheduling.
- Graft Survival Dependencies:Endothelial cell density degradation limits long-term transplant efficacy, necessitating repeat interventions.
- EMA Advanced Therapy Classification:European cell therapy entry faces prolonged compliance burdens under the ATMP framework.
Strategic Opportunities
- Homecare Topical Delivery:Chronic maintenance therapy channels expand beyond hospital settings into patient-administered regimens.
- ISO 14155 Harmonization:Converging clinical investigation standards across jurisdictions reduce multi-site trial duplication costs.
- Endothelial Cell Culture:Laboratory-expanded donor cells promise decoupling from cadaveric tissue constraints.
Industry Challenges
- Microsurgical Skill Scarcity:Descemet stripping automated endothelial keratoplasty demands specialized training pipelines that academic medical centers struggle to scale.
- Tissue-Device Classification Boundaries:Regulatory ambiguity between synthetic implants and biological grafts creates reimbursement tier uncertainty.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bullous Keratopathy Market |
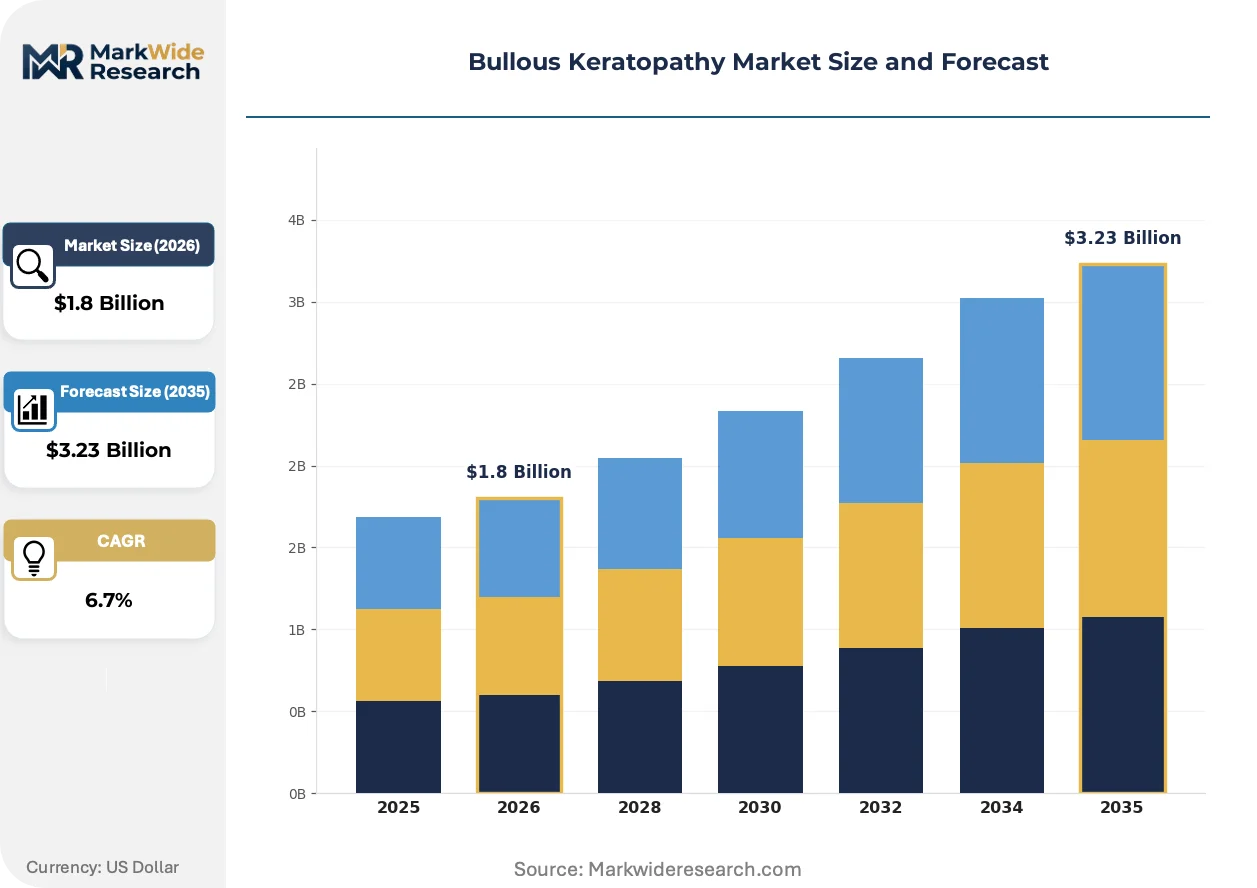
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Solutions, Surgical Implants, Patching Materials, Eye Drops End User: Ophthalmology Clinics, Hospitals, Research Institutions, Homecare Settings Distribution Channel: Direct Sales, Online Pharmacies, Retail Pharmacies, Wholesalers Treatment Type: Pharmacological, Surgical, Lasers, Combination Therapy |
| Companies Covered | Alcon Inc., Bausch + Lomb, Johnson & Johnson Vision, Carl Zeiss Meditec AG, CorneaGen Inc., Aurion Biotechnologies, Trefoil Therapeutics, Cellusion, Emmecell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bullous Keratopathy Market Strategic Shifts
Surgical visualization and cell-based interventions are compressing the boundary between pharmacological maintenance and definitive endothelial replacement. Three developments dominate this transition.
Femtosecond laser platforms are integrating with corneal surgical workflows to enhance graft preparation precision. Hospital-based corneal surgery departments adopt these systems to reduce endothelial cell loss during donor tissue manipulation. The technology is integrating endothelial keratoplasty outcomes with refractive surgery accuracy standards.
The EMA's Advanced Therapy Medicinal Products framework is reshaping European market entry for cell-based endothelial substitutes. Manufacturers must demonstrate comparability to donor tissue across extended follow-up periods. German and French regulatory submissions now dominate the pipeline for cultured endothelial cell products.
Academic medical centers are consolidating procurement authority for advanced keratoplasty platforms. Independent ophthalmology clinics lose access to premium surgical visualization equipment as hospital systems centralize capital expenditure. This concentration is most visible in the United States, where Medicare facility fees reinforce institutional control over complex endothelial procedures.
Bullous Keratopathy Market Segmentation
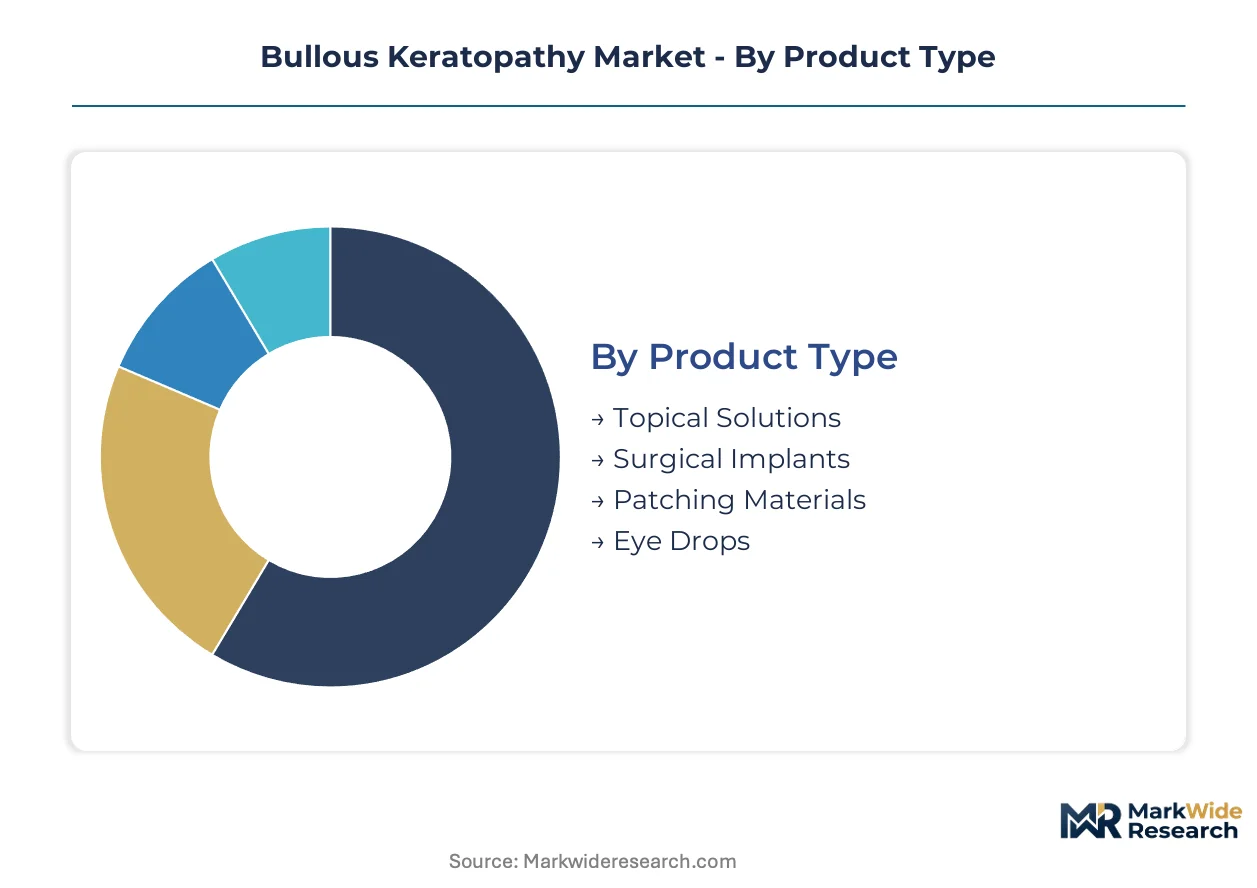
Bullous keratopathy treatment selection follows a staged escalation from maintenance pharmacology to definitive surgical replacement. Segmentation reveals how procurement authority, reimbursement pathways, and tissue availability reshape channel economics across intervention categories.
Product Type:
Upgrade cycles in endothelial replacement drive procurement decisions, with clinicians balancing graft survival rates against donor tissue lead times.
- Surgical Implants:Descemet stripping automated endothelial keratoplasty and Descemet's membrane endothelial keratoplasty grafts command premium positioning due to eye bank scarcity and Medicare facility fee structures in the United States. Academic medical centers in Boston, Baltimore, and San Francisco concentrate procurement authority for advanced keratoplasty platforms.
- Topical Solutions:Hypertonic saline and therapeutic contact lens protocols serve as bridge therapies for patients awaiting transplant or managing early-stage disease. Demand clusters in ophthalmology clinics across Germany and France where EMA reimbursement favors staged intervention over immediate surgical referral.
- Patching Materials:Bandage contact lenses and amniotic membrane grafts support epithelial defect healing in postoperative recovery.
- Eye Drops:Preservative-free artificial tears and hypertonic formulations dominate homecare maintenance regimens.
Volume placements concentrate in Surgical Implants; the faster expansion belongs to Topical Solutions.
End User:
Cost tier stratification separates high-acuity surgical centers from maintenance-focused outpatient settings, with reimbursement differentials determining capital allocation.
- Hospitals:Tertiary centers in the United States leverage matured Medicare reimbursement for endothelial keratoplasty facility fees, centralizing complex procedures away from independent clinics. Massachusetts Eye and Ear, Wilmer Eye Institute, and Bascom Palmer Eye Institute anchor national referral networks.
- Ophthalmology Clinics:Private practices in Germany and France manage chronic maintenance with pharmacological protocols, referring surgical candidates to university hospitals under EMA-mandated specialist concentration rules.
- Homecare Settings:Patient-administered topical regimens expand as teleophthalmology protocols reduce clinic visit frequency.
- Research Institutions:Academic centers in Japan and South Korea pilot cultured endothelial cell therapies under PMDA and MFDS accelerated approval frameworks.
Revenue concentration sits with Hospitals; Homecare Settings are climbing the fastest.
Distribution Channel:
Supply chain configuration separates cold-chain biological grafts from ambient pharmaceutical distribution, with regulatory custody requirements dictating channel selection.
- Direct Sales:Eye bank networks and specialized surgical device manufacturers maintain direct relationships with hospital procurement departments to ensure tissue viability windows and instrument sterilization protocols.
- Wholesalers:Regional distributors in the United States manage inventory pooling for high-cost keratoplasty consumables, absorbing demand volatility from donor tissue availability fluctuations.
- Retail Pharmacies:Community pharmacy chains dispense maintenance hypertonic drops and artificial tear formulations.
- Online Pharmacies:E-commerce platforms gain traction for chronic topical therapy refills in European markets with established remote prescription verification systems.
Transaction value concentrates in Direct Sales; Online Pharmacies show the steepest expansion trajectory.
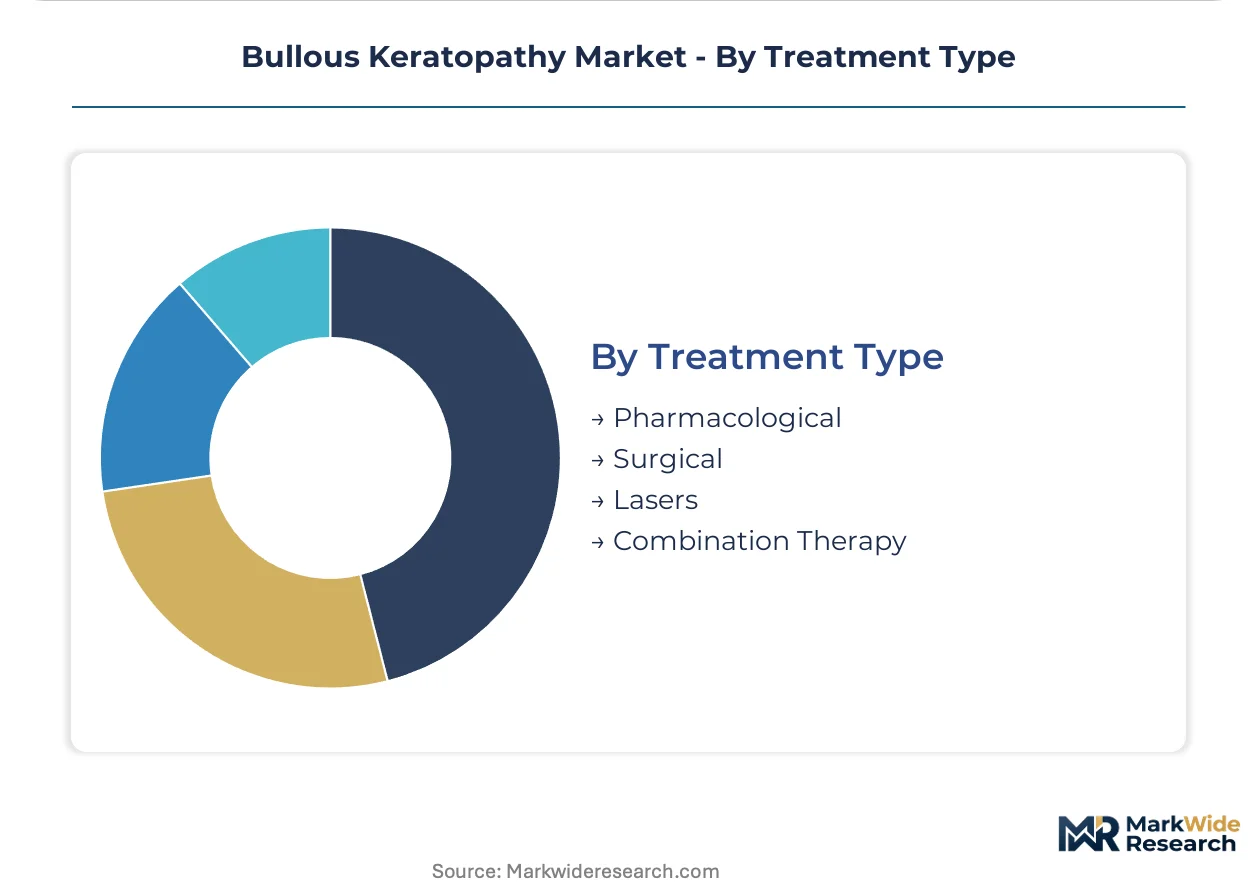
Treatment Type:
Application urgency separates emergency bullae management from elective visual rehabilitation, with clinical staging protocols determining reimbursement tier placement.
- Surgical:Endothelial keratoplasty procedures generate procedural revenue concentration in hospital-based corneal surgery departments, with graft survival dependencies limiting repeat intervention economics.
- Combination Therapy:Staged protocols integrating pharmacological maintenance with timed surgical intervention dominate clinical guidelines from the American Academy of Ophthalmology and European Society of Cataract and Refractive Surgeons.
- Pharmacological:Hypertonic saline and topical steroids manage acute edema episodes and suppress inflammation.
- Lasers:Femtosecond platforms assist graft preparation in high-volume tertiary centers.
Procedure volume concentrates in Surgical; Combination Therapy is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized ophthalmology hubs concentrate in designated medical innovation zones where tax incentives and research infrastructure accelerate endothelial therapy development. The United States anchors procedural volume through Medicare reimbursement maturation. Germany and Japan cultivate regenerative medicine pipelines under accelerated regulatory frameworks.
United States
Massachusetts Eye and Ear, Wilmer Eye Institute, and Bascom Palmer Eye Institute drive tertiary referral concentration for Descemet's membrane endothelial keratoplasty. The FDA's regenerative medicine guidance compresses clinical validation timelines for cell-based endothelial substitutes. Boston, Baltimore, and Miami surgical clusters absorb independent clinic referrals as hospital systems centralize capital expenditure for advanced keratoplasty platforms.
Germany
University hospitals in Heidelberg and Tübingen pilot cultured endothelial cell therapies under EMA Advanced Therapy Medicinal Products frameworks. The country's national pharmaceutical regulator mandates extended follow-up comparability studies for biological graft alternatives. The Baden-Württemberg medical technology corridor concentrates femtosecond laser platform adoption for graft preparation precision.
Japan
Academic centers in Tokyo and Osaka advance laboratory-expanded donor cell protocols through PMDA accelerated approval pathways. METI funding programs support endothelial cell culture commercialization to reduce cadaveric tissue dependency. The Kanto region's ophthalmology research institutes collaborate with South Korean counterparts on regional tissue banking standards.
France
Paris and Lyon university hospitals manage chronic maintenance therapy referrals under EMA-mandated specialist concentration rules. ANSM oversight shapes reimbursement tiers for staged intervention protocols versus immediate surgical referral. The Île-de-France region's eye bank networks face geographic distribution challenges that extend donor tissue lead times.
South Korea
Seoul-based research institutions pilot novel endothelial replacement modalities under MFDS streamlined review processes for regenerative ophthalmology products. The country's national pharmaceutical regulator aligns with Japanese counterparts on regional harmonization initiatives. Busan-Ulsan medical clusters develop intraoperative pharmaceutical portfolios for combination therapy protocols.
Bullous Keratopathy Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with surgical implant suppliers commanding premium positioning against pharmaceutical maintenance providers. The market structure concentrates procurement authority among eye bank networks and specialized device manufacturers with direct hospital relationships. Three archetypes dominate: integrated ophthalmology conglomerates anchoring intraoperative adjacencies, regenerative medicine ventures pursuing cell-culture alternatives, and regional surgical device specialists. Competitive moves center on portfolio diversification into combination therapy protocols and strategic partnerships to secure tissue supply chain stability.
Among integrated ophthalmology conglomerates, Alcon Inc. and Bausch + Lomb occupy positions exemplifying divergent strategic emphases—Alcon leveraging intraoperative portfolio breadth while Bausch + Lomb concentrates pharmaceutical distribution dominance. Carl Zeiss Meditec AG represents the precision surgical visualization archetype, with German engineering heritage supporting hospital-based procurement relationships for endothelial keratoplasty platforms.
| Leading Market Players |
|---|
| Alcon Inc. |
| Bausch + Lomb |
| Johnson & Johnson Vision |
| Carl Zeiss Meditec AG |
| CorneaGen Inc. |
| Aurion Biotechnologies |
| Trefoil Therapeutics |
| Cellusion |
| Emmecell |
| Others |
Value Chain & Pricing Dynamics
Donor tissue acquisition costs cascade through eye bank networks into surgical implant premiums, with cold-chain logistics and serological screening expenses concentrating procurement power among United States-based tissue distributors serving hospital-based corneal surgery departments.
Pricing Analysis
Lead-time-driven pricing angles dominate bullous keratopathy graft procurement, with premium surcharges attaching to expedited donor tissue delivery and spot inventory discounts emerging when eye bank surpluses align with surgical scheduling gaps. Three-tier pricing structure across premium, standard, and economy levels separates Descemet's membrane endothelial keratoplasty grafts with extended viability windows from standard Descemet stripping automated endothelial keratoplasty tissues and economy-grade amniotic membrane patching materials. Price differentiation hinges on endothelial cell density certification and geographic proximity to tissue processing centers. Cost compression in maintenance pharmacology is intensifying because of preservative-free generic formulation entry. Homecare settings exhibit highest price sensitivity; tertiary academic medical centers demonstrate lowest.
Supply Chain Analysis
Single-source vulnerability sits with United States eye bank networks for cadaveric donor tissue, forcing surgical centers toward multi-bank contracting strategies. Geographic supply concentration clusters in the United States, Germany, and Japan for processed corneal grafts. Raw material dependencies encompass donor cornea procurement, viscoelastic formulations, and amniotic membrane sourcing. Supply chain risk centers on regulatory restriction: FDA tissue eligibility criteria and EMA Advanced Therapy Medicinal Products classification create approval bottlenecks for cultured endothelial cell alternatives. Distribution runs through direct sales relationships between eye banks and hospital procurement departments, bypassing wholesale intermediaries for biological grafts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a vertical-integration race, with manufacturers pursuing backward integration into endothelial cell culture laboratories to decouple from cadaveric tissue constraints and secure supply chain control.
For Market Incumbents: To counter regenerative medicine ventures disrupting tissue-based revenue pools, Alcon Inc. and Bausch + Lomb should deepen upstream control over viscoelastic raw material suppliers and anchor hospital system partnerships through bundled intraoperative pharmaceutical portfolios. Capacity addition in Japanese and South Korean cell culture facilities offers geographic diversification against United States eye bank concentration risk. For New Entrants and Emerging Players: The price-point gap between premium DMEK grafts and economy maintenance pharmacology creates white-space entry for mid-tier combination therapy protocols targeting ophthalmology clinics in Germany and France. Teleophthalmology-enabled homecare delivery represents the most penetrable channel expansion vector. Go-to-market positioning should emphasize staged intervention cost containment versus immediate surgical referral. For Investors and Strategic Acquirers: FDA regenerative medicine guidance publication is the leading indicator that cultured endothelial cell therapy economics are approaching commercial viability. Long-term viability over the next decade rests on successful ATMP framework navigation in Europe and PMDA accelerated approval capture in Japan. Acquisition targets should profile as cell culture platform specialists with demonstrated comparability data to donor tissue. The signal to watch is Medicare reimbursement pathway expansion for laboratory-expanded endothelial products.| Strategic Initiative | Industry Significance |
|---|---|
| Endothelial Cell Culture Commercialization | Decouples supply from cadaveric tissue constraints under FDA regenerative medicine guidance. |
| Hospital System Partnership Consolidation | Centralizes procurement authority for advanced keratoplasty platforms at Massachusetts Eye and Ear and Wilmer Eye Institute. |
| EMA ATMP Framework Navigation | Unlocks European market entry for cultured cell therapies through extended comparability studies. |
| Teleophthalmology Platform Integration | Expands homecare channel capture for chronic topical therapy delivery beyond clinic settings. |
| Femtosecond Laser Platform Adoption | Enhances graft preparation precision at Bascom Palmer Eye Institute and Heidelberg University Hospital. |
Study Parameters
Document review covered FDA 510(k) filings, EMA Advanced Therapy Medicinal Products submissions, ClinicalTrials.gov endothelial keratoplasty protocols, and Medicare reimbursement databases, complemented by interviews with corneal surgeons, eye bank procurement directors, hospital purchasing committee members, and regenerative medicine venture executives. Secondary validation drew from hospital procurement databases, GPO contracts, CMS Medicare fee schedules, and ISO 14155 clinical investigation standards. Bottom-up procedure volume estimates and top-down market value triangulation anchored segmentation outputs.
Cross-reference between historical Medicare claims data and expert panel input shaped the analytical framework across the analysis window. Segmentation dimensions modeled encompass treatment type, product category, end-user setting, and regional regulatory cluster. CAGRs were derived from procedure volume trajectories and reimbursement rate evolution. Forecast inputs incorporated endothelial cell density degradation curves and eye bank donor availability trends.
Inputs from FDA guidance documents and EMA scientific advice procedures were available through the study window; gaps in real-time eye bank inventory data introduce uncertainty bands around surgical implant volume projections. Forecasts reflect assumptions about regulatory pathway maturation and reimbursement expansion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Global Ophthalmology Drugs and Devices Market
Ophthalmology
Retinal Disorder Treatment Market
Ophthalmology
North America Ophthalmic Devices and Drugs Market
Ophthalmology
Herpes Zoster Ophthalmicus Market
Ophthalmology
Keratitis Treatment Market
Ophthalmology
Europe Ophthalmology Drug and Device Market
Ophthalmology
Global Glaucoma Treatment Market
Ophthalmology
Ophthalmic Operating Room Microscope Market
Ophthalmology
Conjunctivitis Treatment Market
Ophthalmology
Macular Edema Market
Ophthalmology
Global Ophthalmology Market
Ophthalmology
Macular Edema and Macular Degeneration Market
Ophthalmology
United Kingdom Ophthalmology Devices Market
Ophthalmology
Retinal Vein Occlusion Treatment Market
Ophthalmology
Ptosis Treatment Market
Ophthalmology
Choroidal Neovascularization Market