
 Nystagmus Market | 2026-2036
Nystagmus Market Size, Share, and Industry Trends Forecast 2026-2036
Nystagmus Market Outlook
Gene therapy vector refinement is reconfiguring how congenital nystagmus interventions move from bench to bedside. Novartis AG leverages its cell and gene therapy infrastructure to anchor early-stage programs targeting hereditary ocular motility disorders. Teva Pharmaceutical Industries Ltd. competes through sustained generic formulation dominance across neurology and ophthalmology portfolios. F. Hoffmann-La Roche Ltd. differentiates via deep biologics expertise applied to rare disease indications with unmet diagnostic and therapeutic need.
Nystagmus comprises involuntary, rhythmic oscillations of the eyes arising from disruptions in the vestibulo-ocular reflex, neural integrator, or cerebellar gaze-holding networks, with waveforms classified by slow-phase velocity and foveation period duration. The condition demands precise measurement via infrared oculography or high-speed video eye tracking to guide surgical tenotomy, pharmacological dampening, or optical correction strategies. Congenital nystagmus and acquired nystagmus segments lead current therapeutic development, with the former attracting orphan drug investment and the latter expanding through neuro-ophthalmology service line growth in tertiary hospitals. Diagnostic Devices and Therapeutic Devices categories concentrate margin pools, while Visual Aids occupy a mature, price-sensitive channel serving pediatric and low-vision rehabilitation populations.
The FDA's orphan drug program and EMA's PRIME designation framework shape competitive entry timelines and exclusivity value for nystagmus drug developers. ISO 13485 quality management standards and MDR conformity requirements in Europe govern optical diagnostic device commercialization and post-market surveillance obligations. Stakeholders must monitor regulatory precedent for gene therapy ocular delivery systems, as first approvals will establish reimbursement benchmarks and manufacturing scalability requirements across major markets.
Market Dynamics
Gene therapy vector refinement is compressing development timelines for congenital nystagmus interventions, pulling investment toward ocular delivery platforms and reshaping how biologics manufacturers prioritize rare ophthalmology indications.
Growth Catalysts
- FDA Orphan Drug Exclusivity:The designation pathway accelerates clinical trial enrollment for hereditary ocular motility disorders, reducing regulatory friction for developers targeting pediatric populations with unmet diagnostic need.
- High-Speed Video Oculography:This diagnostic technology enables precise waveform classification in hospital-based ophthalmology departments, improving surgical planning accuracy for tenotomy procedures and expanding reimbursement eligibility.
- Academic Medical Center Concentration:Specialized tertiary hospitals in the United States drive clinical trial infrastructure and premium surgical volumes, creating anchored demand channels for device manufacturers.
Market Restraints
- Viral Vector Manufacturing Bottleneck:Scalable production of adeno-associated virus constructs for ocular gene therapy remains concentrated among contract development organizations, constraining program advancement.
- Reimbursement Complexity:Payer categorization of nystagmus surgeries as cosmetic versus functional creates claim denial risk in commercial insurance segments, particularly for adult acquired forms.
- Optical Device Price Compression:Visual aids for pediatric low-vision rehabilitation face margin erosion from standardized procurement in public health systems and educational institutions.
Strategic Opportunities
- Neuro-Ophthalmology Service Line Expansion:Tertiary hospitals are consolidating vestibular and oculomotor diagnostics, creating integrated capture opportunities for combined diagnostic-therapeutic device vendors.
- EMA PRIME Designation Leverage:Early access pathways for rare disease biologics in Europe enable accelerated market entry and conditional reimbursement frameworks for congenital nystagmus therapeutics.
- Digital Therapeutics Convergence:Eye-tracking software paired with adaptive optical correction is hybridizing hardware and software value propositions, opening recurring revenue models beyond device sales.
Industry Challenges
- Specialized Surgical Training Scarcity:Extraocular muscle tenotomy and recession procedures for nystagmus correction require fellowship-trained strabismus surgeons, limiting addressable procedure volume.
- Gene Therapy Cold Chain Complexity:Ocular vector products demand ultra-low temperature distribution infrastructure, complicating hospital pharmacy integration and wastage management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nystagmus Market |
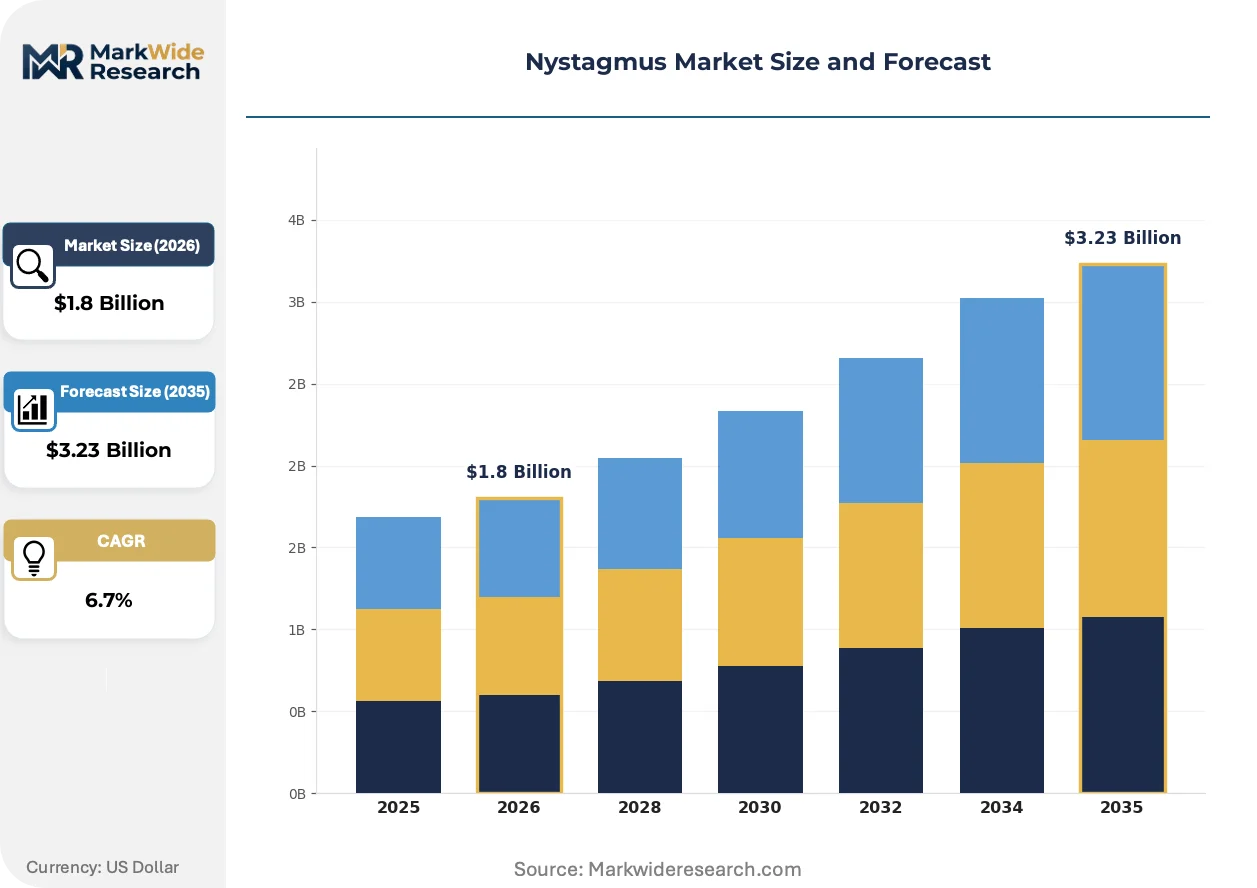
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Area: Congenital Nystagmus, Acquired Nystagmus, Vestibular Nystagmus, Optokinetic Nystagmus End User: Hospitals, Ophthalmology Clinics, Research Laboratories, Home Care Settings Product Type: Diagnostic Devices, Therapeutic Devices, Surgical Instruments, Visual Aids Distribution Channel: Direct Sales, Online Platforms, Medical Distributors, Hospital Stores |
| Companies Covered | Teva Pharmaceutical Industries Ltd., Johnson & Johnson Services, Inc., Novartis AG, F. Hoffmann-La Roche Ltd., Santen Pharmaceutical Co., Ltd., Pfizer Inc., Bausch Health Companies Inc., Genentech, Inc., Allergan (AbbVie Inc.), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nystagmus Market Strategic Shifts
Diagnostic precision requirements and vector delivery advances are simultaneously elevating measurement standards and therapeutic ambition in nystagmus care, compressing the gap between detection and intervention.
Infrared oculography systems are hybridizing with artificial intelligence-based waveform analysis to automate slow-phase velocity quantification. Hospital ophthalmology departments in Germany and Japan are piloting these integrated platforms for pre-surgical planning. The technology is compressing diagnostic interpretation time from hours to minutes, enabling higher patient throughput in high-volume academic centers.
The FDA's orphan drug program and EMA's PRIME designation framework are creating parallel accelerated pathways for rare ophthalmology indications. These regulatory structures compress Phase II-to-approval timelines by 12-18 months for qualifying programs. Gene therapy developers targeting hereditary nystagmus are prioritizing US-EU synchronized filings to maximize exclusivity value.
Academic medical centers are consolidating procurement for diagnostic and surgical devices under single-vendor framework agreements. This buyer concentration is displacing fragmented purchasing across individual departments. The shift is most visible in the United States, where integrated delivery networks now control ophthalmology capital equipment decisions for multiple affiliated hospitals.
Nystagmus Market Segmentation
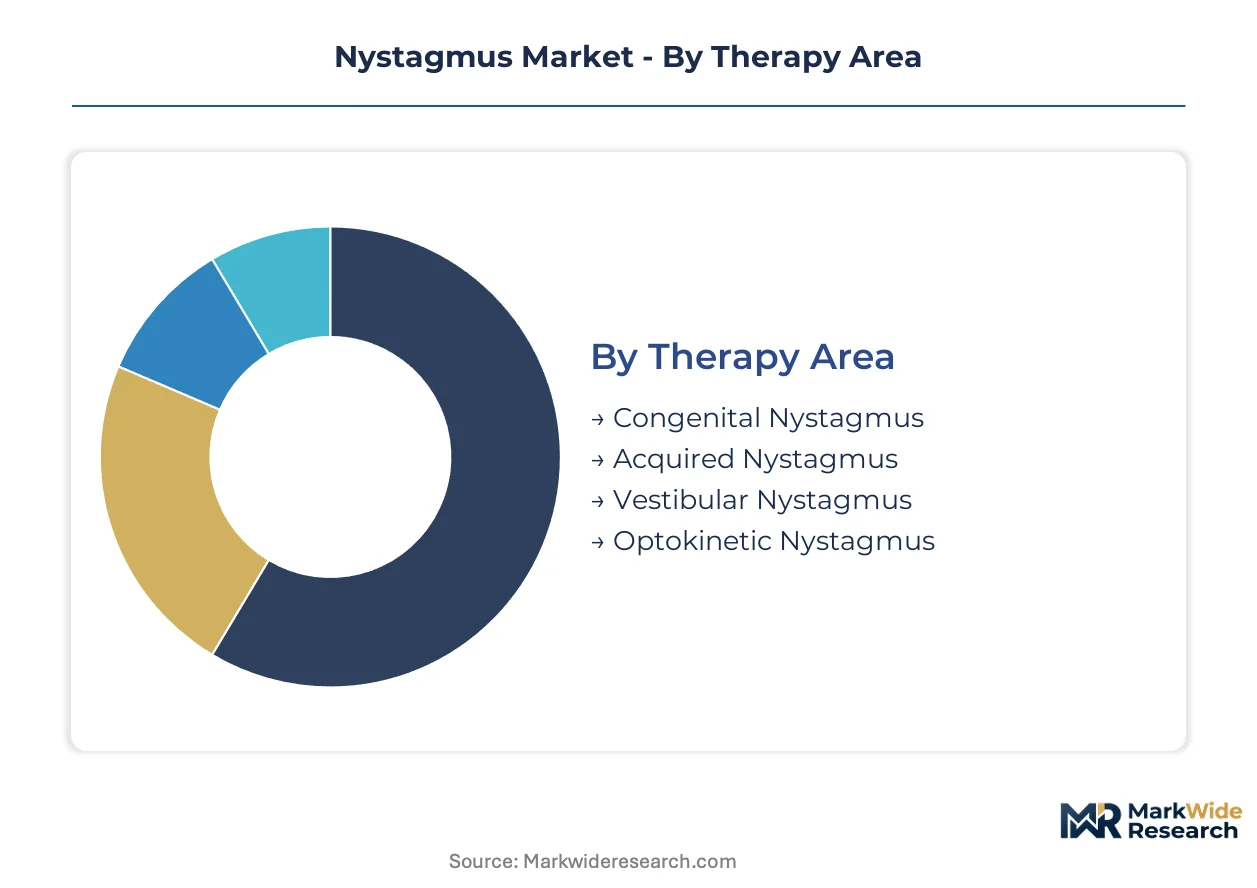
Nystagmus market segmentation reveals distinct service intensity patterns across therapeutic modalities and care delivery settings. Device manufacturers and pharmaceutical developers calibrate support infrastructure differently for congenital versus acquired patient populations, while distribution economics vary sharply between institutional procurement and direct-to-patient channels.
Therapy Area:
After-sales service intensity peaks in congenital nystagmus segments, where pediatric patients require longitudinal monitoring through academic medical centers and specialized strabismus surgery follow-up protocols.
- Congenital Nystagmus:Hereditary forms demand gene therapy vector stability monitoring and surgical tenotomy revision tracking. Service contracts in the United States bundle infrared oculography calibration with pediatric ophthalmology department partnerships, driven by FDA orphan drug program enrollment requirements and multi-year patient surveillance obligations.
- Acquired Nystagmus:Neuro-ophthalmology service lines in Germany and Japan manage post-stroke and demyelinating disease cases through integrated diagnostic-therapeutic platforms. Demand concentrates in tertiary hospitals where vestibular and oculomotor specialists coordinate pharmacological dampening with optical correction adjustments.
- Vestibular Nystagmus:Peripheral and central forms require otolaryngology-neurology co-management with specialized caloric testing equipment support.
- Optokinetic Nystagmus:Research applications in visual neuroscience laboratories drive precision eye-tracking device procurement with extended warranty terms.
By volume, Acquired Nystagmus leads due to neuro-ophthalmology service line expansion. By growth pace, Congenital Nystagmus is ahead on gene therapy pipeline acceleration.
End User:
Cost tier stratification separates capital-intensive hospital installations from reimbursable clinic procedures and out-of-pocket home care expenditures.
- Hospitals:Academic medical centers in the United States anchor demand for combined diagnostic-surgical platforms. Bundled procurement agreements across integrated delivery networks displace fragmented department-level purchasing, compressing vendor margins while locking in multi-year service revenues.
- Ophthalmology Clinics:Private practice settings in Germany prioritize portable high-speed video oculography for pre-surgical planning. Reimbursement eligibility for waveform classification procedures determines equipment acquisition timelines.
- Research Laboratories:Visual neuroscience and oculomotor physiology facilities require ultra-precise eye-tracking calibration services.
- Home Care Settings:Pediatric low-vision rehabilitation programs rely on standardized visual aids with limited technical support infrastructure.
By installed base, Hospitals dominate. By expansion trajectory, Ophthalmology Clinics are climbing the fastest on ambulatory surgery center growth.
Product Type:
Margin concentration varies across hardware categories, with diagnostic and therapeutic devices capturing premium pricing against commoditized visual aids.
- Diagnostic Devices:Infrared oculography systems with AI-integrated waveform analysis command premium pricing in Japan and German hospital installations. Post-market surveillance obligations under MDR conformity requirements extend manufacturer service commitments across European markets.
- Therapeutic Devices:Pharmacological dampening delivery systems and adaptive optical correction hardware require specialized training support. Demand clusters in tertiary hospitals where neuro-ophthalmology fellowship programs drive technology adoption.
- Surgical Instruments:Extraocular muscle tenotomy and recession tools demand fellowship-trained surgeon certification programs.
- Visual Aids:Pediatric low-vision rehabilitation products face procurement standardization in public health systems.
By revenue contribution, Diagnostic Devices lead. By technology refresh frequency, Therapeutic Devices are gaining share fastest on digital therapeutics convergence.
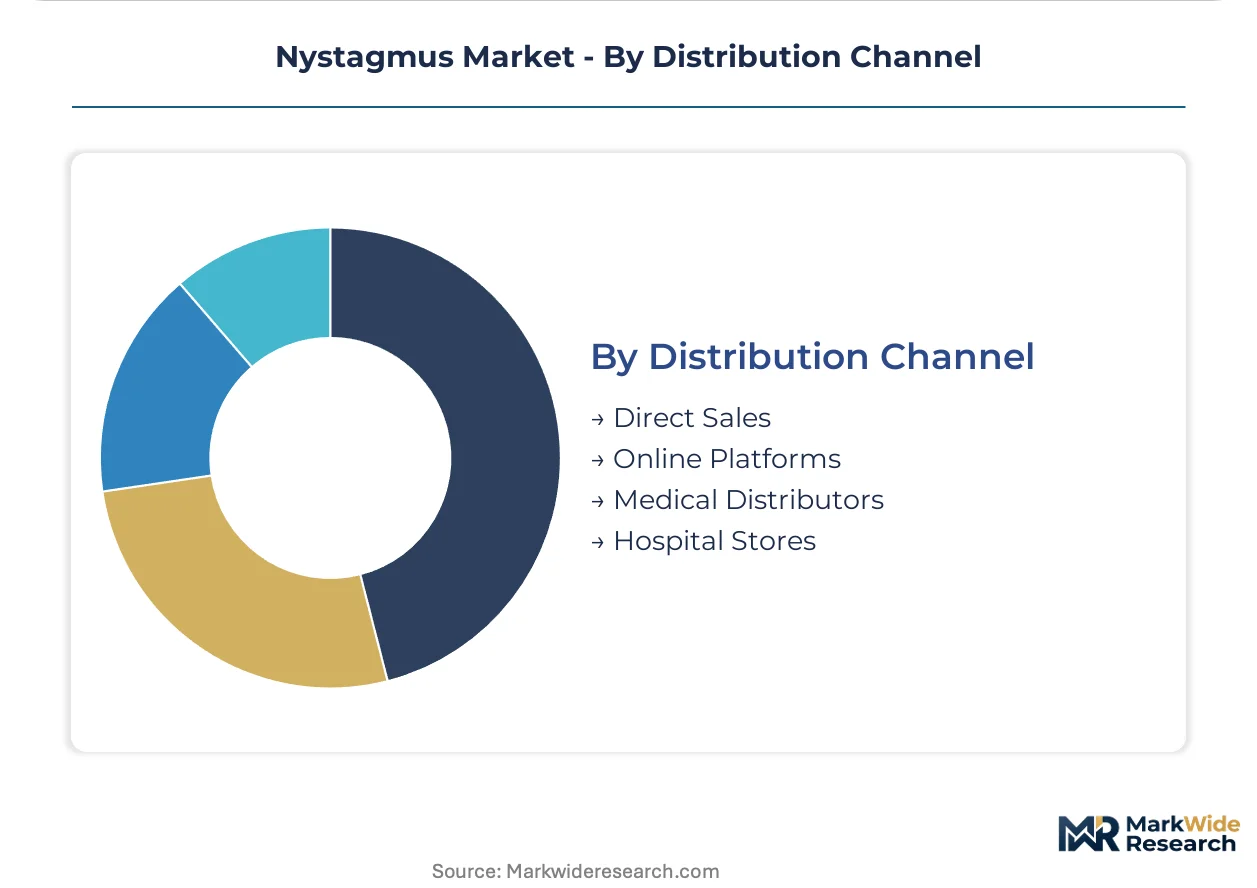
Distribution Channel:
Supply concentration shapes channel economics, with direct sales forces dominating high-value capital equipment while medical distributors fragment visual aid penetration.
- Direct Sales:Gene therapy developers and diagnostic device manufacturers deploy specialized clinical specialists to academic medical centers. The FDA's orphan drug program accelerates direct engagement with principal investigators, bypassing traditional distributor relationships for congenital nystagmus trials.
- Medical Distributors:Regional networks in Germany and Japan manage ophthalmology clinic procurement for portable diagnostic equipment. Inventory carrying costs and technical certification requirements limit distributor participation in high-complexity segments.
- Online Platforms:Standardized visual aids and consumable optical correction products migrate to digital procurement channels.
- Hospital Stores:Captive supply arrangements serve emergency and inpatient consultation needs.
By transaction value, Direct Sales leads. By coverage expansion, Medical Distributors are expanding most quickly into mid-tier ophthalmology clinic networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Academic medical centers in the United States concentrate procurement authority for nystagmus diagnostic and surgical platforms, while specialized ophthalmology clusters in Germany and Japan drive adoption of AI-integrated oculography systems.
United States
Integrated delivery networks in Massachusetts and California bundle capital equipment purchases across multiple hospital affiliates, compressing vendor margins while locking in multi-year service contracts. The FDA's orphan drug designation pathway accelerates clinical trial enrollment for congenital nystagmus gene therapy programs. The Bascom Palmer Eye Institute in Miami and the Wilmer Eye Institute in Baltimore anchor surgical volume and fellowship training for extraocular muscle tenotomy procedures.
Germany
University hospitals in Munich and Heidelberg prioritize portable high-speed video oculography for pre-surgical waveform classification in neuro-ophthalmology service lines. EMA PRIME designation frameworks enable accelerated market entry for rare disease biologics targeting hereditary ocular motility disorders. The Tübingen ophthalmology cluster coordinates reimbursement negotiations with statutory health insurers for diagnostic device procurement.
Japan
Metropolitan medical centers in Tokyo and Osaka deploy AI-integrated infrared oculography systems for automated slow-phase velocity quantification in pediatric ophthalmology departments. PMDA consultation pathways for regenerative medicine products streamline gene therapy development timelines for congenital forms. The Kobe biomedical innovation cluster hosts vector manufacturing partnerships targeting ocular delivery platforms.
United Kingdom
NHS England specialized commissioning frameworks concentrate nystagmus surgical referrals to Moorfields Eye Hospital and Birmingham Children's Hospital. The MHRA's early access to medicines scheme facilitates conditional approval for novel pharmacological dampening agents. London's academic health science centers coordinate multi-site clinical trials for vestibular nystagmus interventions.
Switzerland
University hospitals in Zurich and Geneva leverage Swissmedic's expedited review pathways for orphan ophthalmology indications. The Basel pharmaceutical manufacturing corridor supplies active ingredients for pharmacological dampening formulations. Cantonal health insurance frameworks create standardized reimbursement categories for diagnostic oculography procedures in pediatric populations.
Nystagmus Market Competitive Environment
Channel-controlling players compete with product-specialist players across the nystagmus market, with consolidated procurement authority in US academic medical centers favoring vendors with integrated diagnostic-surgical portfolios. The structure separates into three tiers: multinational pharmaceutical conglomerates with cell and gene therapy infrastructure, specialized ophthalmology device manufacturers with calibration service networks, and generic formulation specialists with neurology distribution reach. Dominant competitive moves include strategic partnerships for viral vector manufacturing capacity and geographic expansion into European neuro-ophthalmology service lines.
Within the multinational pharmaceutical tier, Novartis AG and F. Hoffmann-La Roche Ltd. exemplify archetypes leveraging rare disease biologics expertise and deep cell therapy infrastructure respectively. Teva Pharmaceutical Industries Ltd. occupies a position representing generic formulation dominance across neurology and ophthalmology portfolios. These three companies anchor the competitive landscape through distinct strategic postures: gene therapy vector refinement, biologics platform extension, and sustained generic market presence.
| Leading Market Players |
|---|
| Teva Pharmaceutical Industries Ltd. |
| Johnson & Johnson Services, Inc. |
| Novartis AG |
| F. Hoffmann-La Roche Ltd. |
| Santen Pharmaceutical Co., Ltd. |
| Pfizer Inc. |
| Bausch Health Companies Inc. |
| Genentech, Inc. |
| Allergan (AbbVie Inc.) |
| Others |
Value Chain & Pricing Dynamics
Viral vector manufacturing concentration in the United States and Switzerland anchors margin capture for gene therapy developers, while diagnostic device vendors absorb cost pressure from consolidated procurement by academic medical centers. The interplay between upstream biologics production scarcity and downstream hospital buyer concentration shapes where pricing power accrues across congenital and acquired nystagmus segments.
Pricing Analysis
Cost-plus contracts with raw material indexation dominate gene therapy supply agreements, insulating manufacturers against AAV plasmid cost volatility while capping upside. Pricing stratifies across premium gene therapy vectors, standard biologic dampening agents, and economy generic formulations, with differentiation resting on FDA orphan drug exclusivity and EMA PRIME designation tiers. Cost compression in visual aids intensifies because public health procurement standardization eliminates brand premiums. Pediatric academic medical centers exhibit lowest price sensitivity due to bundled service contracts, while ophthalmology clinics in Germany face highest sensitivity from reimbursement eligibility constraints.
Supply Chain Analysis
Tariff exposure between the United States and China disrupts optical component sourcing for infrared oculography systems, compelling manufacturers to qualify alternative suppliers. Supply concentrates in Germany for precision optical engineering, Japan for AI-integrated sensor fabrication, and the United States for viral vector bioproduction. Raw material dependencies span specialized glass substrates, semiconductor-grade photodetectors, and GMP-grade plasmid DNA. Single-source vulnerability in AAV contract development organizations constrains gene therapy program advancement. Distribution runs through direct sales forces for capital equipment and medical distributors for consumable visual aids.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nystagmus market sits in early-cycle expansion, with gene therapy pipeline maturation and neuro-ophthalmology service line consolidation creating multiple penetration vectors for aligned players.
For Market Incumbents: Pre-empt vector manufacturing bottlenecks by securing captive AAV production capacity in the Kobe biomedical cluster or Basel pharmaceutical corridor before contract development organization queues lengthen. Lock in multi-year framework agreements with integrated delivery networks in Massachusetts and California to defend against portable diagnostic entrants. The FDA's accelerating orphan drug enrollment timelines threaten to compress exclusivity windows for late-moving biologics. For New Entrants and Emerging Players: Pursue white-space opportunities in AI-integrated waveform analysis software paired with adaptive optical correction hardware, where digital therapeutics convergence remains underdeveloped. Target ophthalmology clinics in Germany and Japan for portable high-speed video oculography penetration, as ambulatory surgery center growth outpaces hospital capital budgets. A software-as-medical-device go-to-market angle bypasses viral vector manufacturing barriers while capturing recurring revenue. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed ophthalmology device manufacturers holding calibration service networks but lacking gene therapy adjacencies. The five-to-ten year viability window favors platforms with both diagnostic precision and therapeutic delivery capabilities. Acquisition target archetypes include AI-integrated oculography specialists and pediatric strabismus surgery tool vendors. The signal to watch is first FDA approval for ocular gene therapy, which will establish reimbursement benchmarks and trigger consolidation among vector manufacturing partnerships.| Strategic Initiative | Industry Significance |
|---|---|
| Gene Therapy Vector Manufacturing Scale-Up | Captive AAV production in Basel or Kobe clusters secures program timelines against CDO bottlenecks. |
| FDA Orphan Drug Designation Pathway | Accelerated clinical trial enrollment compresses Phase II-to-approval timelines for hereditary indications. |
| Hospital System Partnership | Framework agreements with integrated delivery networks lock in multi-year diagnostic-surgical platform revenues. |
| Software Companion Development | AI-integrated waveform analysis hybridizes hardware value propositions with recurring SaaS margins. |
| Reimbursement Strategy | EMA PRIME designation enables conditional frameworks for congenital nystagmus therapeutics in Germany. |
Study Parameters
Operator-level perspectives from strabismus surgeons, hospital procurement managers, gene therapy development executives, and neuro-ophthalmology service line directors anchored the qualitative base. These primary insights combined with secondary validation from FDA orphan drug filings, EMA PRIME designation records, ClinicalTrials.gov enrollment data, and hospital procurement databases. Bottom-up patient volume modeling and top-down therapeutic category sizing provided triangulation across the analysis window.
Scenario-bracketing framed the projection horizon, with segmentation across congenital versus acquired therapy areas, hospital versus clinic end users, and diagnostic versus therapeutic product types. CAGRs derived from fitted growth curves applied to gene therapy pipeline maturation timelines and neuro-ophthalmology service line expansion rates. Modeled inputs included orphan drug exclusivity value capture, AAV manufacturing capacity constraints, and reimbursement eligibility evolution in US and EU markets.
Macroeconomic conditions sit as an overlay; deviation in healthcare capital expenditure cycles or biologics reimbursement policy would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory pathway timelines and vector manufacturing scalability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Epidemic Keratoconjunctivitis Treatment Market
Ophthalmology
Vitrectomy Machines Market
Ophthalmology
Dacryocystitis Treatment Market
Ophthalmology
Uveal Melanoma Market
Ophthalmology
Ophthalmic Suspension Market
Ophthalmology
Bullous Keratopathy Market
Ophthalmology
Global Ophthalmic Perimeters Market
Ophthalmology
Retinal Disorder Treatment Market
Ophthalmology
Pediatric Vitrectomy Market
Ophthalmology
Extended and Continuous Wear Lenses Market
Ophthalmology
Global Posterior Segment Eye Disorders Market
Ophthalmology
Laser Vision Correction Market
Ophthalmology
Anterior Uveitis Market
Ophthalmology
Corneal Pachymetry Market
Ophthalmology
Personalized LASIK Surgery Market
Ophthalmology
North America Ophthalmic Devices and Drugs Market