
 Ophthalmic Photocoagulator Market | 2026-2036
Ophthalmic Photocoagulator Market Size, Share, and Industry Trends Forecast 2026-2036
Ophthalmic Photocoagulator Market Intelligence
Modular laser-delivery configurations with interchangeable slit-lamp adapters and indirect ophthalmoscope attachments is repositioning capital equipment purchasing toward flexible platform investments rather than single-modality systems. Lumenis Be Ltd. leverages its integrated laser-and-delivery architecture to sustain installed-base loyalty across academic medical centers. Alcon competes through proprietary fiber-optic handpiece ecosystems that anchor recurring consumable revenue streams.
An ophthalmic photocoagulator is a therapeutic laser system emitting coherent light at wavelengths between 532 nm and 810 nm to achieve thermal coagulation of retinal tissue, primarily employed to seal leaking vessels, ablate ischemic retina, or create chorioretinal adhesions in vitreoretinal disease management. Diode laser platforms now dominate new installations due to compact footprint, reduced cooling requirements, and compatibility with both slit-lamp and indirect delivery modes. Selective photocoagulation technology leads R&D investment as it minimizes collateral thermal damage to the neurosensory retina, while applications in diabetic retinopathy represent the deepest procedure volume pool among all clinical indications.
FDA 510(k) premarket notification requirements govern device clearance in the United States, while the EU Medical Device Regulation mandates clinical evaluation and post-market surveillance for CE-marked systems sold across European member states. Japan's PMDA enforces QMS conformity and country-specific biological safety testing that extends time-to-market for imported platforms. Stakeholders must monitor evolving reimbursement thresholds for office-based versus hospital-based retinal laser procedures as these determinations directly influence capital allocation across ambulatory surgical centers and specialized eye care networks.
Market Dynamics
Modular platform architectures are restructuring capital deployment patterns across eye care networks, forcing manufacturers to anchor recurring revenue through consumable ecosystems rather than upfront equipment sales alone.
Growth Catalysts
- Diabetic retinopathy prevalence:Rising diabetes incidence across aging populations in the United States and Germany is expanding the addressable patient pool for laser photocoagulation procedures.
- Medicare reimbursement stability:Consistent coverage determinations for hospital-based and office-based retinal laser treatments in the United States reduce procurement uncertainty for ambulatory surgical centers.
- Selective photocoagulation R&D:Next-generation wavelength-tunable systems minimize collateral thermal damage, accelerating replacement cycles at university hospitals in Germany.
Market Restraints
- Diode laser component concentration:Specialized semiconductor foundries in East Asia control critical 810 nm emitter supply, creating vulnerability for European and North American system integrators.
- EU MDR compliance costs:Enhanced clinical evaluation and post-market surveillance requirements under the Medical Device Regulation extend time-to-revenue for novel platform introductions.
- Pharmacologic substitution:Anti-VEGF intravitreal injections compete for diabetic macular edema cases, compressing addressable procedure volumes in some patient segments.
Strategic Opportunities
- India outpatient expansion:Tier-2 and tier-3 city eye hospital networks remain underpenetrated for selective photocoagulation platforms, offering first-mover positioning for adaptable system vendors.
- Tele-ophthalmology integration:Remote diagnostic workflows paired with centralized laser treatment hubs create new channel economics for equipment lessors.
- Japan PMDA QMS alignment:Early conformance to quality management system requirements opens streamlined market access relative to competitors facing extended biological safety testing timelines.
Industry Challenges
- Vitreoretinal surgeon training pipelines:Fellowship program capacity constraints in the United States and Germany limit qualified operator availability for advanced selective photocoagulation techniques.
- Legacy slit-lamp integration:Retrofitting existing delivery infrastructure with modular laser attachments requires field engineering resources that strain manufacturer service organizations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ophthalmic Photocoagulator Market |
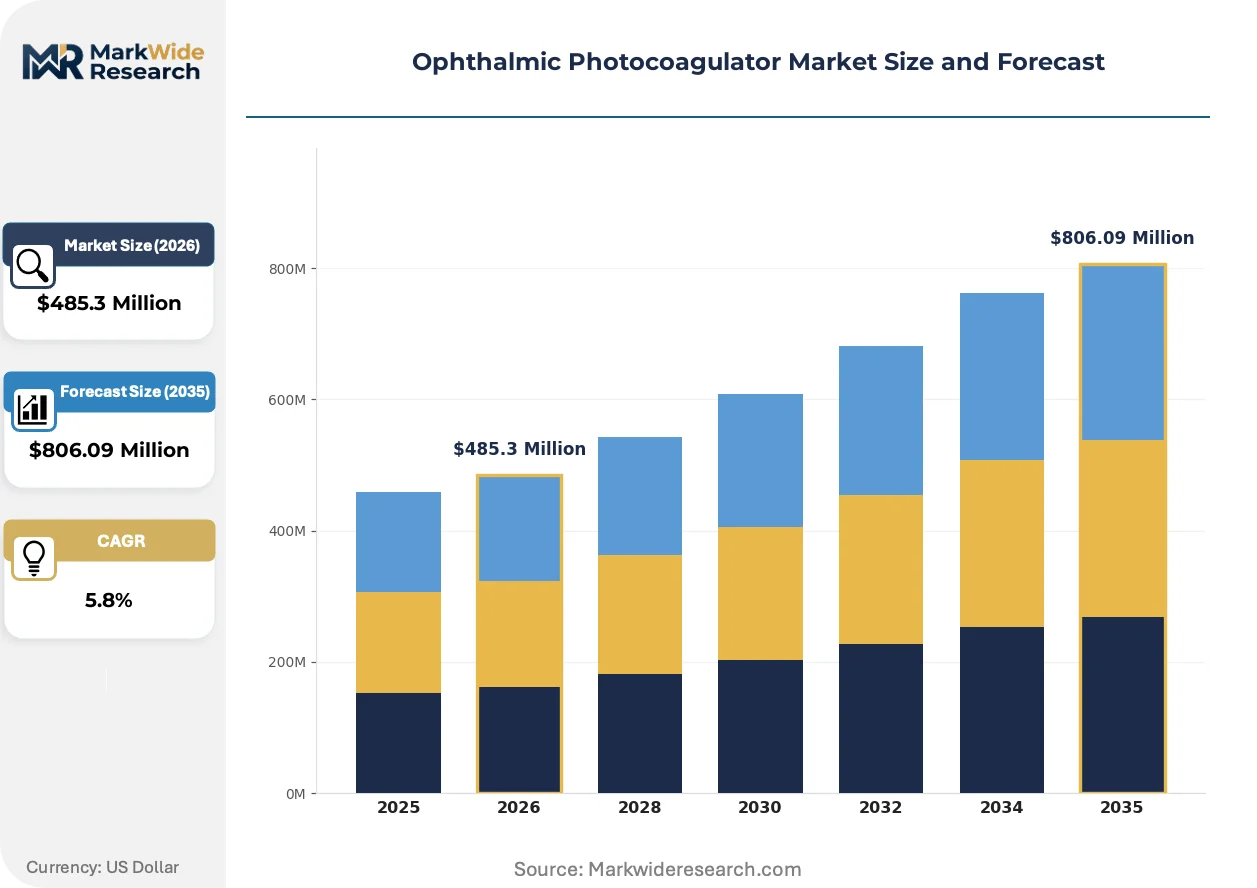
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $806.09 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
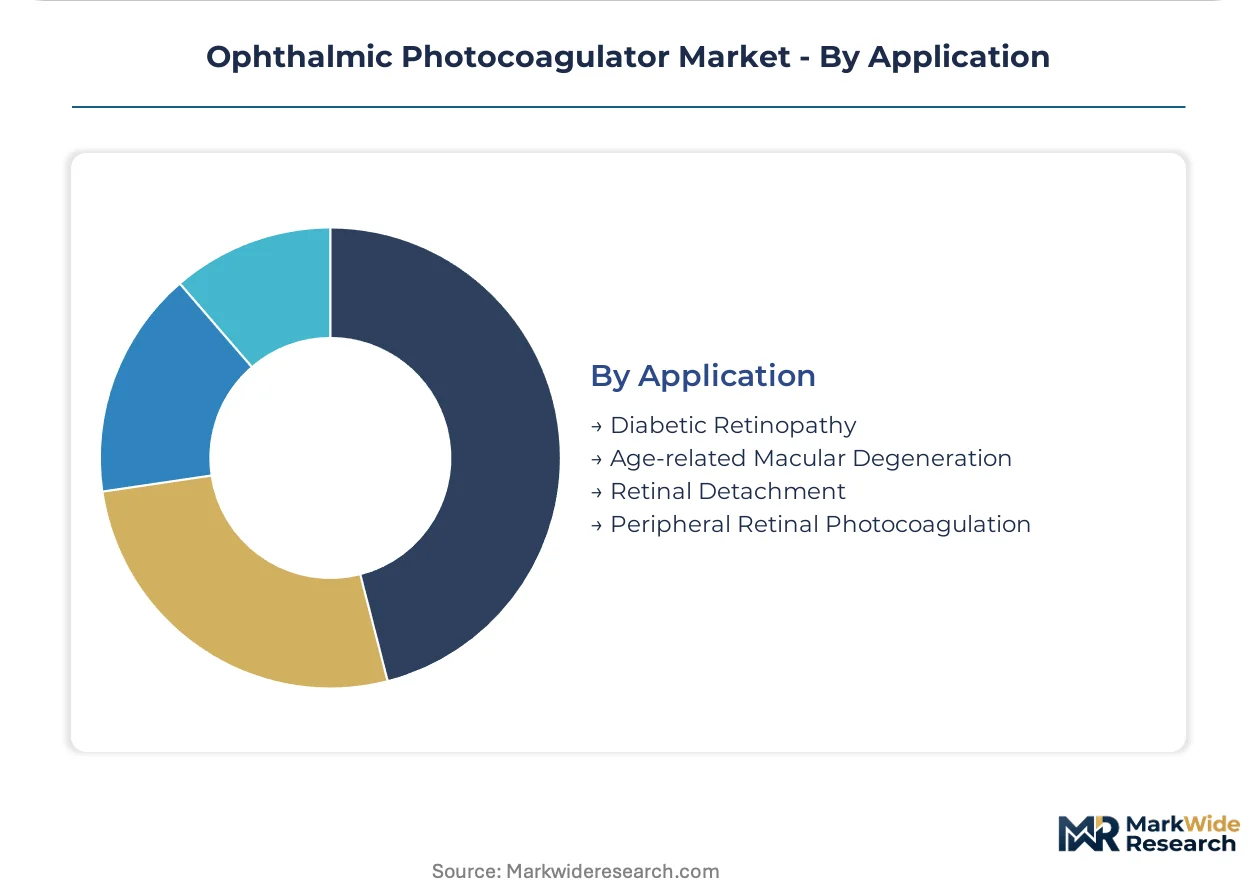
| Segmentation | Product Type: Pulsed Laser, Continuous Wave Laser, Diode Laser, Solid-State Laser Technology: Selective Photocoagulation, Laser Photocoagulation, Transscleral Photocoagulation, Retinal Laser Surgery End User: Hospitals, Eye Clinics, Ambulatory Surgical Centers, Specialized Eye Care Centers Application: Diabetic Retinopathy, Age-related Macular Degeneration, Retinal Detachment, Peripheral Retinal Photocoagulation |
| Companies Covered | Lumenis Be Ltd., Bausch + Lomb, Alcon, Carl Zeiss AG, Lumibird Medical, IRIDEX Corporation, Topcon Corporation, Johnson & Johnson Vision Care, Inc., NIDEK CO., LTD., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ophthalmic Photocoagulator Market Strategic Shifts & Innovations
Device miniaturization and software-defined wavelength control are converging to reshape how photocoagulation capabilities deploy across care settings, from academic medical centers to community-based practices.
Portable diode laser systems with battery-operated power supplies and tablet-based control interfaces are decentralizing treatment delivery beyond traditional hospital-based suites. Community eye clinics in the United States are adopting these platforms for same-day diabetic retinopathy management. This shift compresses capital requirements per treatment site while expanding manufacturer addressable market through volume-based consumable arrangements.
The EU Medical Device Regulation's enhanced post-market surveillance mandates are forcing system vendors to embed real-time usage telemetry and automated adverse event reporting into platform firmware. Manufacturers serving European university hospitals must now maintain continuous clinical evidence generation capabilities. German procurement committees are weighting MDR compliance documentation heavily in competitive tenders, favoring established suppliers with robust quality management infrastructure.
Subscription-based equipment access models are displacing outright purchase arrangements among United States ambulatory surgical centers facing capital constraint pressures. Laser system lessors bundle preventive maintenance, software updates, and consumable replenishment into per-procedure fees. This restructuring concentrates most visible in California and Texas eye care networks, where private equity-backed practice consolidation favors operational expenditure flexibility over balance sheet asset ownership.
Ophthalmic Photocoagulator Market Segmentation
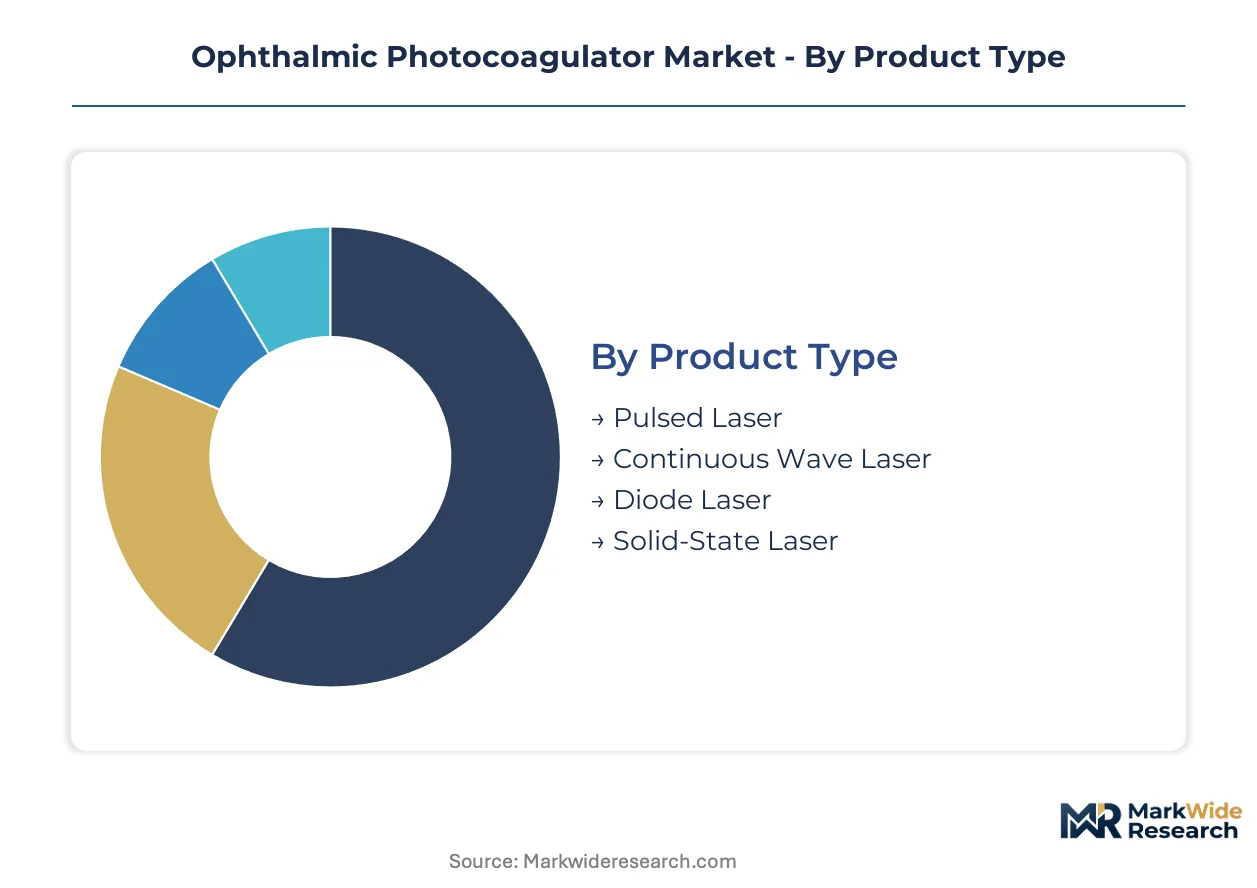
Laser wavelength architecture and delivery modality specifications determine capital allocation patterns across eye care networks. Procurement committees weight platform flexibility against procedure-specific performance thresholds when segmenting purchasing decisions.
Product Type:
Semiconductor foundry capacity for 810 nm emitters concentrates supply leverage among diode laser manufacturers.
- Diode Laser:Compact solid-state platforms operating at 810 nm with air-cooled thermal management. Demand clusters in United States ambulatory surgical centers seeking slit-lamp and indirect ophthalmoscope compatibility from single chassis configurations.
- Solid-State Laser:Frequency-doubled Nd:YAG systems emitting at 532 nm with superior beam quality for macular procedures. German university hospitals prioritize these platforms for selective photocoagulation research protocols requiring wavelength precision.
- Pulsed Laser:Q-switched or mode-locked architectures delivering energy in microsecond bursts for controlled thermal penetration.
- Continuous Wave Laser:Steady-state emission systems optimized for pan-retinal photocoagulation with uniform spot delivery.
Diode laser platforms absorb the bulk of installed capacity; solid-state laser configurations are expanding most quickly in academic medical center procurement.
Technology:
Clinical outcome differentiation now hinges on thermal damage zone control rather than raw power output specifications.
- Selective Photocoagulation:Microsecond-pulse architectures targeting retinal pigment epithelium while sparing neurosensory retina. United States diabetic retinopathy treatment protocols at specialized eye care centers are driving replacement cycles for legacy continuous-wave systems.
- Laser Photocoagulation:Conventional thermal coagulation across 532-810 nm wavelengths for sealing retinal breaks and ablating ischemic tissue. Eye clinics in Germany maintain substantial installed bases for standard procedural volumes.
- Transscleral Photocoagulation:External beam delivery through scleral tissue for ciliary body ablation in refractory glaucoma management.
- Retinal Laser Surgery:Integrated surgical laser systems combining photocoagulation with vitrectomy illumination platforms.
Selective photocoagulation commands premium pricing tiers; transscleral approaches are climbing the fastest as glaucoma drainage device alternatives face reimbursement compression.
End User:
Capital constraint severity and procedure volume predictability shape site-specific equipment configuration choices.
- Specialized Eye Care Centers:Dedicated retinal practices with fellowship-trained vitreoretinal surgeons operating multiple laser modalities. United States metropolitan markets concentrate demand for subscription-based equipment access with bundled consumable arrangements.
- Hospitals:Academic medical centers and community hospital ophthalmology departments with mixed subspecialty coverage. German university hospitals anchor selective photocoagulation platform validation studies.
- Eye Clinics:Independent optometric and ophthalmologic practices with limited procedural scope.
- Ambulatory Surgical Centers:Medicare-certified facilities focused on efficient throughput for standardized retinal laser protocols.
Specialized eye care centers absorb the bulk of installed capacity; ambulatory surgical centers are gaining share fastest under private equity consolidation strategies.
Application:
Disease prevalence trajectories and pharmacologic substitution risk determine addressable procedure volume stability.
- Diabetic Retinopathy:Pan-retinal and focal laser photocoagulation for proliferative and non-proliferative disease stages. United States Medicare reimbursement stability supports consistent procedure volumes despite anti-VEGF competition for macular edema cases.
- Age-related Macular Degeneration:Laser photocoagulation for extrafoveal choroidal neovascularization with limited applicability given pharmacologic standard-of-care dominance.
- Retinal Detachment:Demarcation laser around retinal breaks and horseshoe tears to prevent subretinal fluid progression.
- Peripheral Retinal Photocoagulation:Prophylactic treatment of lattice degeneration and peripheral retinal pathology in high-risk myopic patients.
Diabetic retinopathy applications absorb the bulk of installed capacity; peripheral retinal photocoagulation is expanding most quickly with myopia prevalence acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical device special economic zones in Malaysia and Puerto Rico concentrate ophthalmic laser assembly operations through tax-advantaged manufacturing status. These zones attract component suppliers and system integrators seeking duty-free import of semiconductor emitters from East Asian foundries.
United States
Medicare reimbursement stability for retinal laser procedures sustains hospital procurement cycles. FDA 510(k) clearance pathways shape product development timelines for diode laser platforms. Metropolitan eye care networks in California and Texas are consolidating under private equity ownership that favors subscription-based equipment access over capital purchases.
Germany
University hospital research budgets anchor demand for selective photocoagulation platforms with wavelength-tunable architectures. EU Medical Device Regulation compliance documentation carries heavy weight in competitive tenders issued by procurement committees. Bavarian medical technology clusters around Munich host validation studies for next-generation thermal damage control systems.
Japan
Aging demographics expand the diabetic retinopathy patient pool eligible for laser intervention. PMDA quality management system requirements extend time-to-market for imported platforms lacking prior QMS alignment. Tokyo-based academic medical centers serve as reference sites for clinical evidence generation supporting regulatory submissions.
India
Tier-2 and tier-3 city eye hospital networks remain underpenetrated for selective photocoagulation technology. Central Drugs Standard Control Organization registration timelines influence vendor market entry sequencing. Maharashtra and Gujarat host expanding outpatient chains seeking portable diode laser systems for decentralized diabetic retinopathy screening programs.
China
Domestic diabetes prevalence drives volume demand for pan-retinal photocoagulation procedures. National Medical Products Administration oversight of laser device classification affects import substitution strategies. Yangtze River Delta medical device manufacturing bases are developing localized diode emitter supply chains to reduce foreign component dependency.
Ophthalmic Photocoagulator Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the ophthalmic photocoagulator landscape, creating a tiered competitive structure. The vendor base clusters around three strategic archetypes: integrated laser-and-delivery platform architects, consumable-centric handpiece ecosystem builders, and modular attachment specialists. Consolidation pressures favor players with captive semiconductor supply relationships or established service organizations capable of supporting legacy slit-lamp retrofits.
Among Israel-based laser platform developers, Lumenis Be Ltd. exemplifies the integrated architecture archetype through its sustained installed-base loyalty across academic medical centers. Alcon and IRIDEX Corporation occupy positions within the consumable-anchored tier, with Alcon representing the proprietary handpiece ecosystem model that locks recurring revenue streams. These three companies illustrate how competitive positioning depends on whether revenue concentration sits at the initial capital sale or the ongoing consumable attachment.
| Leading Market Players |
|---|
| Lumenis Be Ltd. |
| Bausch + Lomb |
| Alcon |
| Carl Zeiss AG |
| Lumibird Medical |
| IRIDEX Corporation |
| Topcon Corporation |
| Johnson & Johnson Vision Care, Inc. |
| NIDEK CO., LTD. |
| Others |
Cost & Logistics Intelligence
EU MDR post-market surveillance mandates gate qualified supply access and premium-tier pricing power, forcing manufacturers to embed continuous clinical evidence generation capabilities that smaller competitors cannot fund. This regulatory moat stratifies pricing tiers between compliant incumbents and margin-constrained challengers.
Pricing Analysis
Margin tightening in the subscription-access tier reflects private equity-backed practice consolidation favoring operational expenditure flexibility over capital ownership. Three-tier pricing structure across premium selective photocoagulation, standard diode laser, and economy continuous-wave systems separates wavelength-tunable platforms from fixed-configuration alternatives. Price differentiation hinges on FDA 510(k) clearance tier and bundled consumable service levels. Ambulatory surgical centers exhibit highest price sensitivity; German university hospitals demonstrate lowest sensitivity due to research budget insulation.
Supply Chain Analysis
Regional distribution centers in Malaysia and Puerto Rico concentrate final assembly operations for tax-advantaged access to East Asian semiconductor inputs. Critical 810 nm diode emitters draw from specialized foundries in Taiwan and South Korea, while precision optics and fiber-optic handpieces source from German and Japanese suppliers. Single-source vulnerability around 810 nm emitter supply creates procurement risk for European and North American system integrators. Distribution runs through hospital procurement committees and GPO contracts in the United States, direct tender processes in Germany, and distributor networks in emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where EU MDR clinical evaluation requirements create a barrier-to-entry moat that rewards established players with robust quality management infrastructure.
For Market Incumbents: Acquire captive semiconductor supply relationships or exclusive foundry allocation agreements to secure 810 nm emitter access against East Asian supply concentration. Anchor recurring revenue through proprietary fiber-optic handpiece ecosystems that lock hospital procurement committees into consumable-dependent platforms, defending against modular attachment specialists eroding installed-base loyalty. For New Entrants and Emerging Players: Portable diode laser systems with battery-operated power supplies offer a technology-first wedge into United States community eye clinics and India tier-2 city networks where capital constraints favor decentralized deployment. Target subscription-based equipment access models in California and Texas metropolitan markets where private equity consolidation favors operational expenditure structures over balance sheet ownership. For Investors and Strategic Acquirers: FDA 510(k) clearance velocity for selective photocoagulation platforms is the leading indicator that wavelength-tunable R&D investment is converting to commercial traction. Long-term viability favors acquirers of modular platform architects with established service organizations capable of legacy slit-lamp retrofit support, as replacement cycle demand concentrates in academic medical center validation studies.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evaluation documentation accelerates competitive tender eligibility at German university hospitals. |
| Hospital System Partnership | Integrated delivery networks in the United States consolidate procurement leverage for subscription-based laser access. |
| Software Companion Development | Tablet-based control interfaces and real-time usage telemetry satisfy EU post-market surveillance mandates. |
| Reimbursement Strategy | Medicare coverage stability for office-based retinal laser procedures shapes ambulatory surgical center capital allocation. |
| Backward Integration into Emitters | Captive 810 nm diode supply reduces vulnerability to East Asian foundry concentration and tariff exposure. |
Research Approach
Multi-period observation of Medicare reimbursement determinations, FDA 510(k) clearance timelines, and EU MDR compliance documentation anchored the trend analysis, supplemented by interviews with vitreoretinal surgeons, hospital procurement committee members, biomedical engineers at academic medical centers, and GPO contracts managers. Secondary validation drew from FDA 510(k) premarket notification database, EUDAMED CE marking records, CMS Medicare physician fee schedules, and hospital capital expenditure disclosures. Bottom-up procedure volume modeling and top-down equipment replacement cycle analysis provided triangulation.
Segment-weighting across laser wavelength architecture, delivery modality, technology type, end-user facility category, and geographic regulatory cluster shaped the analytical framework. CAGRs were derived from installed base growth, replacement cycle acceleration, and procedure volume elasticity across the projection horizon. Industry-specific forecast inputs included diabetic retinopathy prevalence trajectories, anti-VEGF substitution rates for macular edema cases, and fellowship-trained surgeon pipeline capacity.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU MDR enforcement intensity shifts, East Asian semiconductor supply disruptions, or Medicare reimbursement compression for laser procedures relative to pharmacologic alternatives. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Ophthalmic Clinical Trials Market
Ophthalmology
Global Ophthalmic Knives Market
Ophthalmology
Retinal Detachment Market
Ophthalmology
Head Band Ophthalmoscopes Market
Ophthalmology
United States Dry Eye Syndrome Market
Ophthalmology
Laser Indirect Ophthalmoscope Market
Ophthalmology
Meibomian Gland Dysfunction Treatment Market
Ophthalmology
Retinal Detachment Diagnostic Market
Ophthalmology
Macular Edema and Macular Degeneration Market
Ophthalmology
Orthokeratology Market
Ophthalmology
Ophthalmic Drugs and Devices Market
Ophthalmology
Keratitis Treatment Market
Ophthalmology
Global Optic Nerve Disorders Treatment Market
Ophthalmology
Ptosis Treatment Market
Ophthalmology
Inherited Retinal Diseases Treatment Market
Ophthalmology
Amblyopia Treatment Market