
 Corneal Edema Treatment Market | 2026-2036
Corneal Edema Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Corneal Edema Treatment Market Outlook
EMA's updated advanced therapy medicinal products framework is decoupling European market access from traditional pharmaceutical approval timelines. Bausch + Lomb leverages its established ophthalmology infrastructure to sustain distribution reach across ambulatory surgical centers. Alcon dominates the surgical segment with proprietary phacoemulsification systems that reduce endothelial cell loss during cataract extraction. Johnson & Johnson Services Inc. anchors its position through integrated viscoelastic and intraocular lens portfolios that address post-surgical edema risk.
Corneal edema treatment encompasses pharmacological, optical, and surgical interventions designed to reduce stromal hydration and restore endothelial pump function, with hypertonic saline solutions operating at 5% sodium chloride concentration to draw fluid osmotically from the corneal stroma through topical application. The primary commercial purpose spans acute decompensation management, chronic endothelial dysfunction palliation, and post-operative visual rehabilitation following intraocular surgery. Hypertonic saline and contact lenses occupy the mature volume tier, while injectable therapies and surgical modalities capture expanding margin pools as endothelial keratoplasty techniques displace full-thickness transplantation. Delivery mode segmentation shows topical formulations retaining the largest patient touchpoint, though surgical intervention generates disproportionate value per procedure in hospital and ambulatory settings.
FDA premarket approval requirements, EMA ATMP classifications, and ISO 14155 clinical investigation standards collectively elevate the evidence threshold for novel corneal therapeutics entering commercial channels. The FDA's regenerative medicine advanced therapy designation creates accelerated pathways for cell-based interventions, while EMA's centralized procedure mandates pan-European efficacy data for biologic treatments. Stakeholders must monitor how payer coverage policies for Descemet membrane endothelial keratoplasty versus Descemet stripping automated endothelial keratoplasty reshape procedure economics and device purchasing patterns across hospital systems.
Market Dynamics
Descemet membrane endothelial keratoplasty is compressing full-thickness transplantation volumes as surgeons prioritize tissue-sparing techniques that accelerate visual recovery and reduce rejection risk.
Growth Catalysts
- FDA Regenerative Medicine Advanced Therapy designation:Cell-based corneal interventions receive expedited review timelines, compressing development cycles for endothelial cell therapies seeking commercial entry.
- Germany's specialized eye hospital expansion:Dedicated corneal service lines in Mannheim, Tübingen, and Berlin concentrate surgical expertise and drive procedure standardization across the country's tertiary care network.
- Phacoemulsification platform refinement:Reduced endothelial cell loss during cataract extraction cuts downstream edema incidence, expanding the addressable population for prophylactic and acute interventions.
Market Restraints
- Donor cornea supply volatility:Eye bank tissue availability fluctuates with seasonal donation patterns and screening rejection rates, constraining transplant procedure scheduling across ambulatory surgical centers.
- EMA centralized procedure timelines:Pan-European efficacy requirements for biologic treatments extend approval durations, delaying market entry for novel cell therapies relative to US pathways.
- Hypertonic saline commoditization:Generic 5% sodium chloride solutions capture pharmacy-tier pricing, compressing margin pools in the highest-volume treatment category.
Strategic Opportunities
- Injectable endothelial cell delivery:Intracameral injection protocols eliminate graft preparation complexity, opening access for community ophthalmologists lacking microsurgical keratoplasty training.
- US ambulatory surgical center penetration:Outpatient facility expansion creates dedicated procedure slots for elective endothelial keratoplasty outside hospital cost structures.
- ISO 14155 harmonization with FDA standards:Streamlined clinical investigation protocols reduce redundant trial design, accelerating multi-regional study execution for device and biologic developers.
Industry Challenges
- Microsurgical training pipeline constraints:DMEK adoption requires specialized fellowship exposure, limiting surgeon conversion rates from penetrating keratoplasty techniques.
- Endothelial cell density assessment standardization:Specular microscopy protocol variation across clinics complicates graft survival tracking and post-operative management algorithms.
- Viscoelastic product-trial integration:Intraoperative cohesive and dispersive agent selection impacts endothelial protection, demanding coordinated portfolio positioning across surgical suites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corneal Edema Treatment Market |
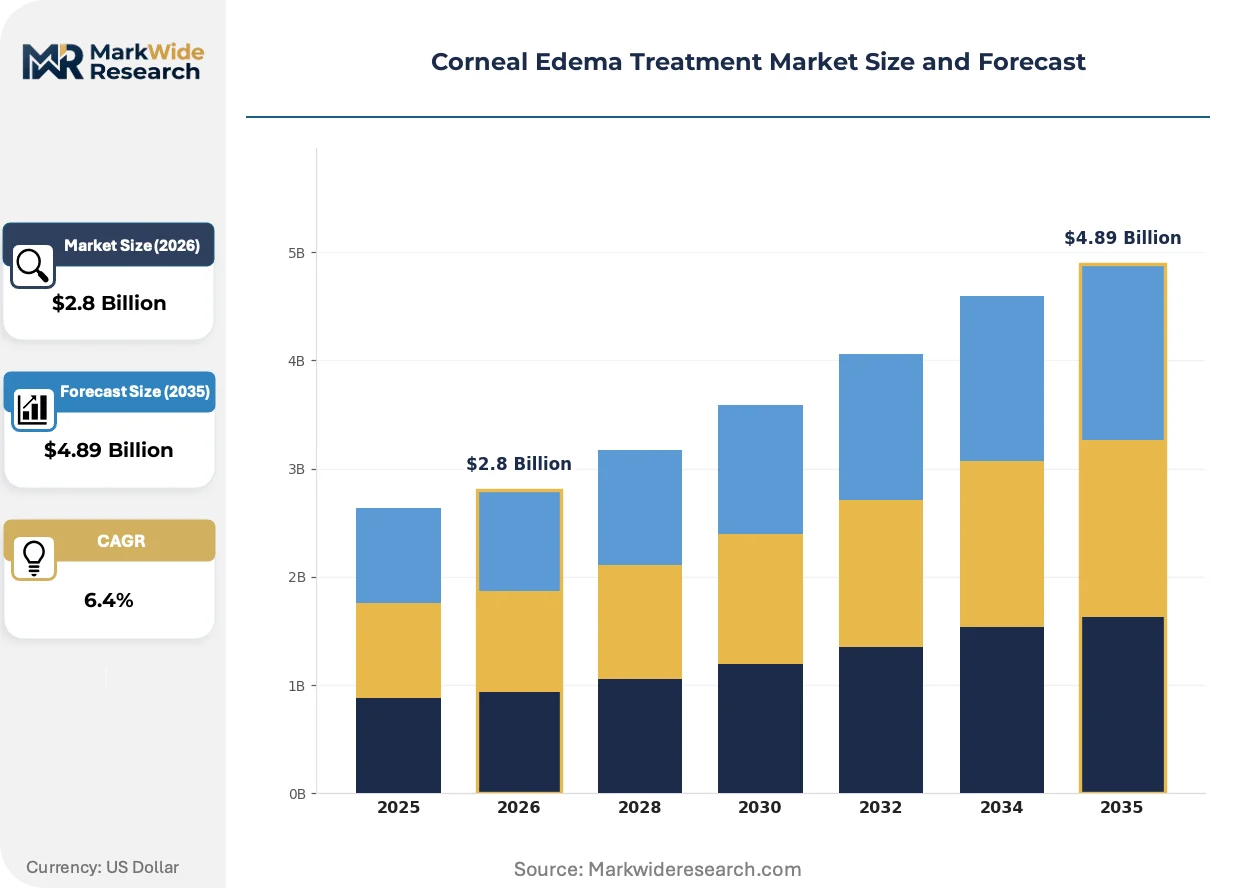
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hypertonic Saline, Dexamethasone, Mannitol, Contact Lenses Delivery Mode: Topical, Injectable, Oral, Surgical End User: Hospitals, Clinics, Ambulatory Surgical Centers, Homecare Treatment Stage: Acute, Chronic, Recurrent, Post-surgical |
| Companies Covered | Bausch + Lomb, Abbott, Alcon, Allergan, Johnson & Johnson Services Inc., Santen Pharmaceutical, Kowa Ltd., Aurion Biotech, Emmetrope Ophthalmics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corneal Edema Treatment Market Strategic Shifts
Femtosecond laser technology is reshaping endothelial keratoplasty preparation precision, while regulatory frameworks for advanced therapy medicinal products are decoupling approval timelines from traditional pharmaceutical pathways. Demand concentration in specialized corneal centers is redrawing referral network geography.
Femtosecond laser-assisted graft preparation is integrating into endothelial keratoplasty workflows, enabling automated Descemet membrane scoring and donor tissue customization. Academic medical centers in the United States and Germany are adopting these platforms to standardize graft thickness and reduce surgeon-dependent variability. The technology is integrating pre-operative planning software with intraoperative imaging, compressing procedure learning curves and expanding DMEK adoption beyond fellowship-trained specialists.
EMA's updated advanced therapy medicinal products framework is creating parallel approval tracks for cell-based corneal therapeutics, separating biologic classification from small-molecule timelines. European developers now pursue centralized procedures with distinct efficacy endpoints tailored to regenerative mechanisms. Germany and France are responding with national reimbursement pilot programs that align hospital payment with cell therapy outcomes rather than procedure volume.
Ambulatory surgical centers in the United States are consolidating elective endothelial keratoplasty volumes previously fragmented across hospital outpatient departments. Facility administrators negotiate device and viscoelastic bundles that prioritize inventory standardization over brand loyalty. Texas, Florida, and California markets exhibit the fastest site-of-service migration as certificate-of-need restrictions loosen and surgeon equity participation in ASCs expands.
Corneal Edema Treatment Market Segmentation
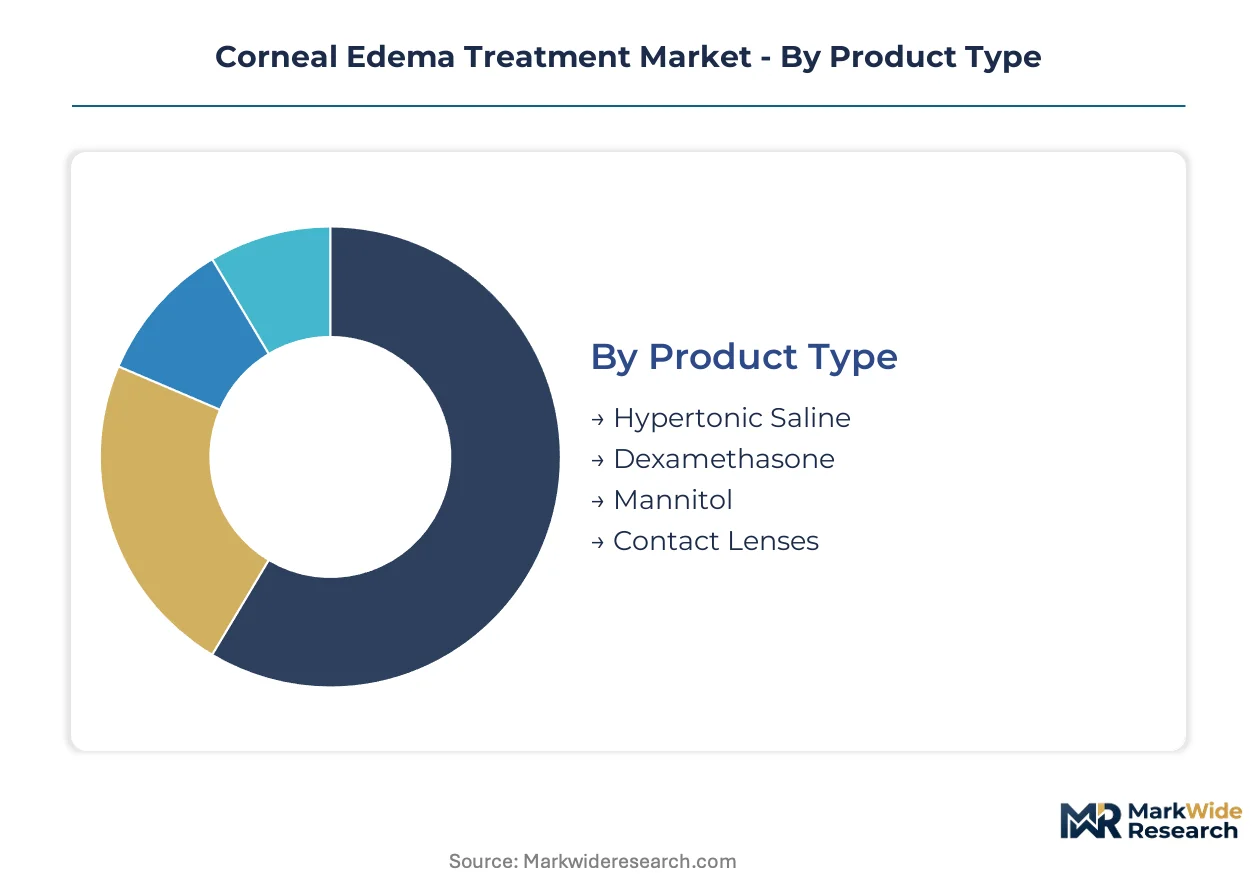
Corneal edema treatment modalities span standalone pharmaceutical interventions, embedded surgical protocols, and hybrid optical-pharmacological systems. Segment boundaries blur as endothelial keratoplasty techniques integrate viscoelastic delivery, cell therapy injection, and post-operative topical regimens into unified care pathways.
Product Type:
Integration depth varies sharply: hypertonic saline and contact lenses function as standalone patient-managed therapies, while dexamethasone and mannitol embed predominantly within surgical and acute care protocols.
- Hypertonic Saline:5% sodium chloride solutions draw fluid osmotically from the corneal stroma through topical application. Demand concentrates in US pharmacy-tier dispensing for acute decompensation episodes, though generic commoditization compresses margin pools in this highest-volume category.
- Dexamethasone:Corticosteroid formulations suppress inflammatory cascades driving endothelial dysfunction. Germany's specialized eye hospitals in Mannheim and Tübingen prioritize high-potency preparations for post-keratoplasty rejection prophylaxis, aligning procurement with cell therapy outcome tracking.
- Mannitol:Hyperosmolar intravenous agents reduce intraocular pressure in acute angle-closure scenarios with secondary corneal edema.
- Contact Lenses:Bandage and scleral lens designs mechanically protect epithelial barriers and normalize tear film osmolarity.
Volume placements concentrate in hypertonic saline; the faster expansion belongs to dexamethasone as surgical volumes climb.
Delivery Mode:
Cost tier stratification separates high-touch surgical and injectable interventions from self-administered topical and oral regimens, with reimbursement intensity tracking invasiveness.
- Topical:Eye drop formulations retain the largest patient touchpoint across all treatment stages. US ambulatory surgical centers bundle post-operative drops with procedure pricing, masking true pharmacy spend in consolidated billing.
- Surgical:Endothelial keratoplasty and full-thickness transplantation generate disproportionate value per procedure. Germany's national reimbursement pilots in Berlin and Heidelberg now align hospital payment with DMEK outcomes rather than procedure volume alone.
- Injectable:Intracameral cell delivery protocols eliminate graft preparation complexity for community ophthalmologists.
- Oral:Systemic carbonic anhydrase inhibitors and hyperosmotic agents address refractory cases with contraindications to topical therapy.
Topical formulations dominate patient encounters; surgical delivery captures expanding margin pools as DMEK displaces penetrating keratoplasty.
End User:
Customer type fragmentation reflects site-of-service migration trends, with procedure economics diverging between hospital cost structures and ambulatory facility efficiency.
- Ambulatory Surgical Centers:Outpatient facilities in Texas, Florida, and California consolidate elective endothelial keratoplasty volumes previously fragmented across hospital departments. Surgeons with equity participation drive inventory standardization through device and viscoelastic bundle negotiations.
- Hospitals:Tertiary centers retain complex re-operations and combined procedures requiring anesthesia support. Academic medical centers in the United States and Germany adopt femtosecond laser platforms to standardize graft preparation.
- Clinics:Ophthalmology clinics expand advanced surgical intervention adoption for post-cataract edema cases.
- Homecare:Self-administered hypertonic saline and contact lens protocols support chronic management outside reimbursed settings.
Procedure volume is concentrating fastest in ambulatory surgical centers; hospitals retain the highest-complexity tier.
Treatment Stage:
Maturity gradients separate established chronic palliation markets from emerging acute and post-surgical intervention categories with technology-linked pricing power.
- Post-surgical:Cataract extraction complications and endothelial keratoplasty rejection episodes drive technology-intensive intervention. Phacoemulsification platform refinement at Alcon and Johnson & Johnson reduces downstream edema incidence, expanding the addressable population for prophylactic protocols.
- Acute:Sudden endothelial decompensation from trauma or infection demands rapid osmotic and anti-inflammatory intervention. FDA's regenerative medicine advanced therapy designation creates expedited pathways for cell-based acute rescue therapies.
- Chronic:Long-term endothelial dysfunction management relies on hypertonic saline cycling and optical correction.
- Recurrent:Repeated decompensation episodes in Fuchs endothelial dystrophy patients prompt surgical candidacy evaluation.
Post-surgical cases command premium intervention intensity; acute stage therapies are gaining share fastest through regenerative medicine designations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized eye hospital zones in Germany concentrate surgical expertise and drive procedure standardization across tertiary care networks. FDA premarket pathways in the United States accelerate cell therapy commercialization timelines relative to European counterparts. EMA centralized procedures in France and the United Kingdom reshape how developers approach pan-European efficacy requirements.
United States
Texas, Florida, and California ambulatory surgical centers consolidate elective endothelial keratoplasty volumes as certificate-of-need restrictions loosen. FDA regenerative medicine advanced therapy designation creates expedited review timelines for cell-based interventions seeking commercial entry. Academic medical centers in Boston and Stanford adopt femtosecond laser platforms to standardize graft preparation precision.
Germany
Mannheim, Tübingen, and Berlin specialized eye hospitals build dedicated corneal service lines that concentrate surgical expertise. EMA advanced therapy medicinal products framework decouples approval timelines from traditional pharmaceutical pathways. National reimbursement pilots in Heidelberg now align hospital payment with DMEK outcomes rather than procedure volume alone.
Japan
PMDA streamlined review pathways for regenerative medical products accelerate endothelial cell therapy market entry timelines. METI funding programs support domestic ophthalmology device development and manufacturing scale-up. Tokyo and Osaka academic centers pioneer Descemet membrane endothelial keratoplasty training protocols for regional surgeon networks.
United Kingdom
NHS specialized commissioning frameworks concentrate complex corneal procedures within designated tertiary centers in London and Manchester. MHRA post-Brexit regulatory autonomy enables faster adaptive pathways for novel cell therapies relative to EMA centralized timelines. Moorfields Eye Hospital anchors national graft tissue distribution and surgeon training networks.
India
CDSCO accelerated approval pathways for ophthalmic devices expand access to phacoemulsification platforms in tier-1 cities. Tamil Nadu and Karnataka eye hospital chains build corneal subspecialty units to address post-cataract edema case volumes. Hyderabad and Chennai manufacturing clusters produce generic hypertonic saline formulations for domestic pharmacy-tier distribution.
Corneal Edema Treatment Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the corneal edema treatment landscape. Johnson & Johnson Services Inc. and Abbott anchor diversified healthcare portfolios spanning surgical devices, pharmaceuticals, and consumer eye care, while Aurion Biotech and Emmetrope Ophthalmics represent concentrated cell therapy development. Market structure stratifies into three archetypes: integrated ophthalmology conglomerates, specialized surgical device manufacturers, and regenerative medicine pure-plays. Dominant competitive moves include strategic partnerships between device makers and cell therapy developers, plus geographic expansion through ambulatory surgical center network penetration.
Among diversified ophthalmology conglomerates, Bausch + Lomb and Alcon occupy positions exemplifying integrated surgical and pharmaceutical portfolio strategies. Santen Pharmaceutical represents the specialized pharmaceutical archetype with concentrated ophthalmology therapeutic focus. These three entities anchor competitive dynamics through established distribution infrastructure and surgeon relationship networks.
| Leading Market Players |
|---|
| Bausch + Lomb |
| Abbott |
| Alcon |
| Allergan |
| Johnson & Johnson Services Inc. |
| Santen Pharmaceutical |
| Kowa Ltd. |
| Aurion Biotech |
| Emmetrope Ophthalmics |
| Others |
Value Chain & Pricing Dynamics
Commodity-grade hypertonic saline separates from premium surgical bundles through reimbursement tiering and inventory integration depth. Generic 5% sodium chloride solutions command pharmacy-tier pricing in US retail channels, while DMEK procedure packages bundle viscoelastic, donor tissue, and facility fees into consolidated hospital billing. Alcon and Johnson & Johnson negotiate device- pharmaceutical bundles with ambulatory surgical centers that mask true component pricing. Germany's national reimbursement pilots in Heidelberg and Berlin now tie hospital payment to cell therapy outcomes, decoupling pricing from procedure volume.
Pricing Analysis
Short lead-time premiums attach to expedited donor cornea tissue matching for acute decompensation cases. Three-tier pricing structure across premium, standard, and economy levels stratifies by graft preparation complexity and surgeon training certification. Price differentiation stems from ISO 14155 clinical investigation compliance tier and geographic delivery cost from eye bank to surgical facility. Pricing pressure stems from hypertonic saline commoditization as Indian manufacturers flood pharmacy channels with generic formulations. Community ophthalmologists exhibit highest price sensitivity; academic medical centers prioritize outcome-linked contracts over per-unit cost.
Supply Chain Analysis
Skilled microsurgical technician availability constrains graft preparation throughput in United States, Germany, and Japan manufacturing nodes. Donor cornea sourcing draws from eye bank networks in Tennessee, Florida, and California with seasonal donation volatility. Viscoelastic formulations, femtosecond laser platforms, and specular microscopy equipment feed into surgical workflow integration. Single-source vulnerability concentrates in approved donor tissue suppliers facing screening rejection rate fluctuations. Distribution runs through hospital procurement committees and ambulatory surgical center group purchasing organizations with standardized inventory mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Donor cornea supply constraints prop pricing power for approved tissue networks, compressing margin pressure on downstream device manufacturers. Capacity bottlenecks in eye bank screening infrastructure limit graft availability to match rising DMEK procedure demand.
For Market Incumbents: Deepen backward integration into donor tissue sourcing through eye bank partnership structures or captive tissue processing facilities. Alcon and Bausch + Lomb should lock in multi-year viscoelastic supply agreements with ambulatory surgical center networks before certificate-of-need deregulation accelerates site-of-service migration. Cell therapy developers face substitution threat from injectable endothelial delivery protocols that eliminate graft preparation complexity. For New Entrants and Emerging Players: Community ophthalmologists lacking fellowship-trained keratoplasty skills represent the most penetrable buyer archetype for simplified intracameral injection platforms. Target US ambulatory surgical centers in Texas and Florida with disposable delivery systems that bypass microsurgical training requirements. White-space exists in post-operative topical regimen standardization through pharmacy benefit manager partnerships. Go-to-market angle should emphasize inventory reduction and procedure slot efficiency over clinical outcomes messaging. For Investors and Strategic Acquirers: Re-rating potential sits with regenerative medicine pure-plays given FDA regenerative medicine advanced therapy designation acceleration timelines. Long-term viability over the next decade hinges on successful pivot from graft-based to cell-injection modalities. Acquisition target archetype: cell therapy developers with Phase II endothelial delivery data and existing eye bank distribution relationships. Signal to watch: EMA centralized procedure approval for first injectable corneal cell therapy as inflection indicator for platform validation.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Regenerative Medicine Advanced Therapy Designation | Expedited review timelines compress development cycles for Aurion Biotech and Emmetrope Ophthalmics cell-based interventions. |
| Eye Bank Network Partnership | Secured donor tissue access insulates against seasonal availability fluctuations and screening rejection rate volatility. |
| Ambulatory Surgical Center Bundle Negotiation | Device and viscoelastic standardization contracts lock in inventory slots ahead of site-of-service migration acceleration. |
| Fellowship Training Program Sponsorship | DMEK technique proliferation expands addressable surgeon base beyond academic medical center concentration. |
| Reimbursement Outcome Pilot Participation | Germany's Heidelberg and Berlin hospital payment alignment with cell therapy results creates first-mover advantage. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this corneal edema treatment analysis. Primary interviews with corneal surgeons, eye bank medical directors, ambulatory surgical center administrators, hospital procurement managers, and FDA regulatory affairs specialists validated demand assumptions. FDA 510(k) submissions, EMA centralized procedure documentation, ClinicalTrials.gov endothelial therapy entries, and CMS Medicare reimbursement databases supplied secondary validation. Bottom-up procedure volume modeling triangulated against top-down pharmaceutical and device revenue estimates.
Data-stream reconciliation across eye bank tissue distribution records, surgical device shipment data, and pharmaceutical dispensing databases generated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type tier, delivery mode invasiveness, end-user facility category, and treatment stage urgency. CAGRs derived from procedure volume trajectory analysis and pricing trend extrapolation. Forecast inputs incorporated phacoemulsification platform penetration rates and DMEK surgeon conversion curves.
Revisions become necessary when donor cornea supply shortages intensify, EMA centralized procedure timelines extend unexpectedly, or injectable cell therapy clinical data disrupts graft-based procedure economics. Forecasts reflect documented assumptions regarding reimbursement stability and surgeon training pipeline expansion. Regulatory pathway acceleration, eye bank consolidation, or ambulatory surgical center certificate-of-need deregulation could materially alter trajectory. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Ophthalmic Disease Therapeutics Market
Ophthalmology
Anterior Uveitis Market
Ophthalmology
Cataract Treatment Market
Ophthalmology
Optic Nerve Glioma Market
Ophthalmology
Ocular Pain Market
Ophthalmology
Ophthalmic Loupes Market
Ophthalmology
Tonometry Market
Ophthalmology
Macular Edema and Macular Degeneration Market
Ophthalmology
Presbyopia Treatment Market
Ophthalmology
Diabetic Macular Edema Treatment Market
Ophthalmology
Canada Ophthalmology Drugs and Devices Market
Ophthalmology
Personalized LASIK Surgery Market
Ophthalmology
Eye Infections Treatment Market
Ophthalmology
Asia-Pacific Conjunctivitis Treatment Market
Ophthalmology
Ophthalmic Photocoagulator Market
Ophthalmology
Superficial Punctate Keratitis Treatment Market