
 Germany Computed Tomography Market | 2026-2036
Germany Computed Tomography Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Computed Tomography Market Foresight
Silicon photomultiplier (SiPM) detector material is realigning CT scanner economics by replacing traditional photomultiplier tubes with solid-state alternatives that reduce energy consumption and improve spatial resolution. Siemens Healthineers leverages in-house semiconductor fabrication to control SiPM supply chains for its premium scanner lines. GE Healthcare competes through dual-source CT architectures that sustain throughput advantages in cardiac imaging workflows. Koninklijke Philips anchors its German position with spectral-detector CT platforms optimized for oncology quantification.
Computed tomography systems generate cross-sectional anatomical images through rotating X-ray tube-detector assemblies, with modern multi-slice configurations acquiring sub-millimeter isotropic voxels across 256 or more simultaneous slices for volumetric reconstruction. Multi-slice CT dominates German hospital procurement due to its integration into emergency trauma protocols and interventional planning. Portable CT represents the fastest-expanding product category as stroke networks deploy bedside units to reduce door-to-needle times. Cloud-enabled deployment models concentrate margin pools in software subscription architectures rather than hardware transactions alone.
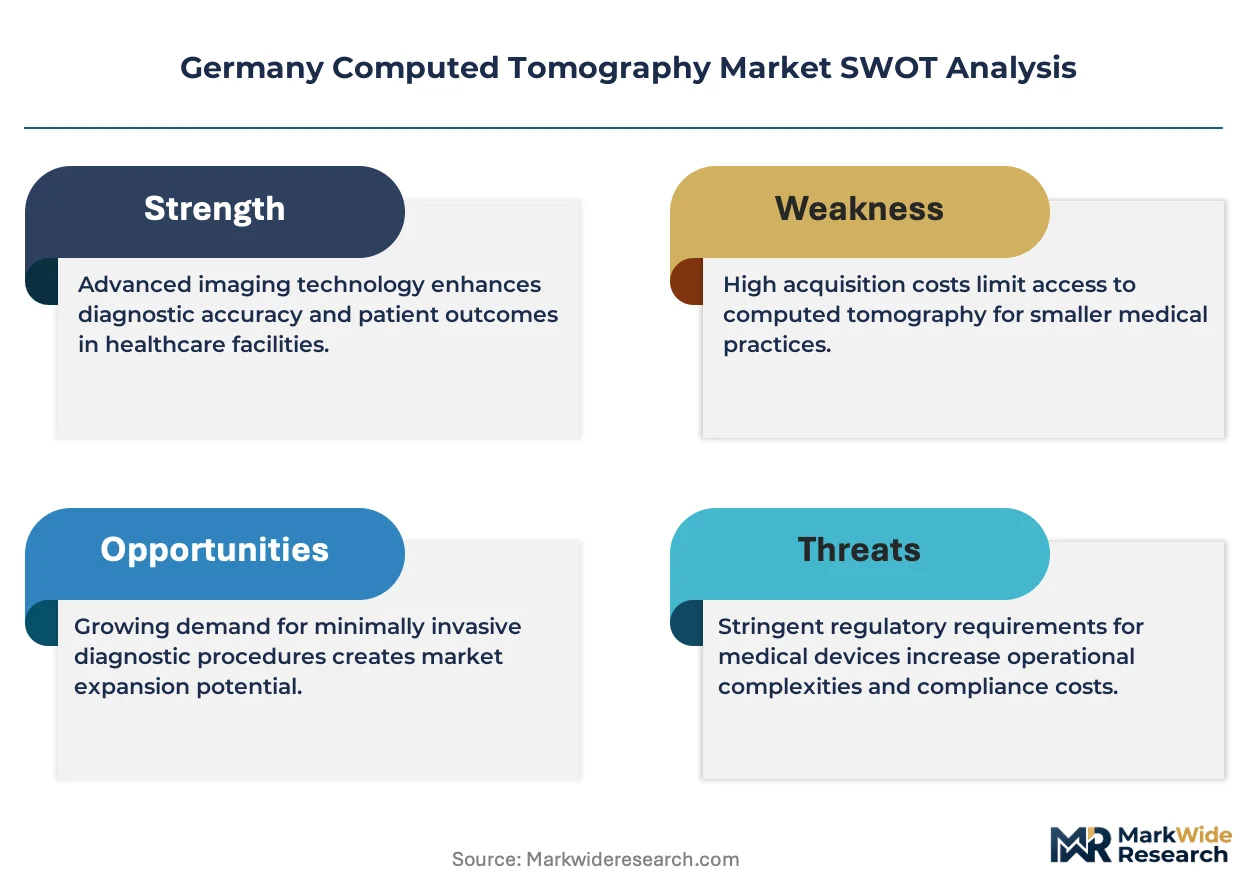
Germany's Federal Institute for Drugs and Medical Devices (BfArM) enforces EU MDR conformity procedures that extend certification timelines for new CT modalities, while the German Radiation Protection Act (StrlSchG) mandates dose reference levels that shape detector sensitivity requirements. KBA-equivalent medical device safety standards administered through DIN and VDE frameworks govern electromagnetic compatibility and electrical safety for installed base upgrades. Stakeholders must monitor how BfArM's evolving guidance on artificial-intelligence-enabled CT reconstruction algorithms reclassifies software as active medical devices subject to enhanced clinical evidence requirements.
Market Dynamics
Solid-state detector materials are compressing CT scanner energy profiles while EU MDR compliance timelines extend product certification cycles, creating a tension between performance advancement and market entry velocity.
Growth Catalysts
- Oncology staging protocols:German university hospitals are embedding spectral CT into precision tumor characterization workflows, expanding installed base utilization rates.
- EU MDR Article 10:Post-market surveillance requirements for imaging software are creating replacement demand for legacy systems lacking technical documentation.
- SiPM semiconductor yields:In-house fabrication capabilities at major manufacturers are stabilizing detector supply chains against photomultiplier tube discontinuation risks.
Market Restraints
- Helium-3 scarcity:Detector cooling dependencies on constrained noble gas supplies are elevating maintenance cost structures for superconducting magnet adjacent CT installations.
- BfArM conformity assessment:Extended technical documentation review periods are delaying new modality commercialization by twelve to eighteen months.
- Magnetic resonance substitution:Soft tissue imaging applications in neurology and musculoskeletal departments are migrating toward MRI for radiation-free alternatives.
Strategic Opportunities
- Stroke network bedside deployment:Portable CT units are penetrating emergency departments and intensive care units across Bavarian and North Rhine-Westphalian hospital clusters.
- Cloud-native reconstruction algorithms:AI-enabled image processing is shifting value capture toward software-as-a-service architectures with recurring revenue profiles.
- Interventional radiology integration:Hybrid operating suites are demanding real-time CT guidance for minimally invasive procedures, opening premium system configurations.
Industry Challenges
- Clinical engineering specialization:Detector calibration and SiPM module replacement require technicians with semiconductor fabrication familiarity scarce in hospital biomedical departments.
- Legacy PACS interoperability:Cloud-enabled CT platforms face integration friction with picture archiving systems predating DICOMweb standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Computed Tomography Market |
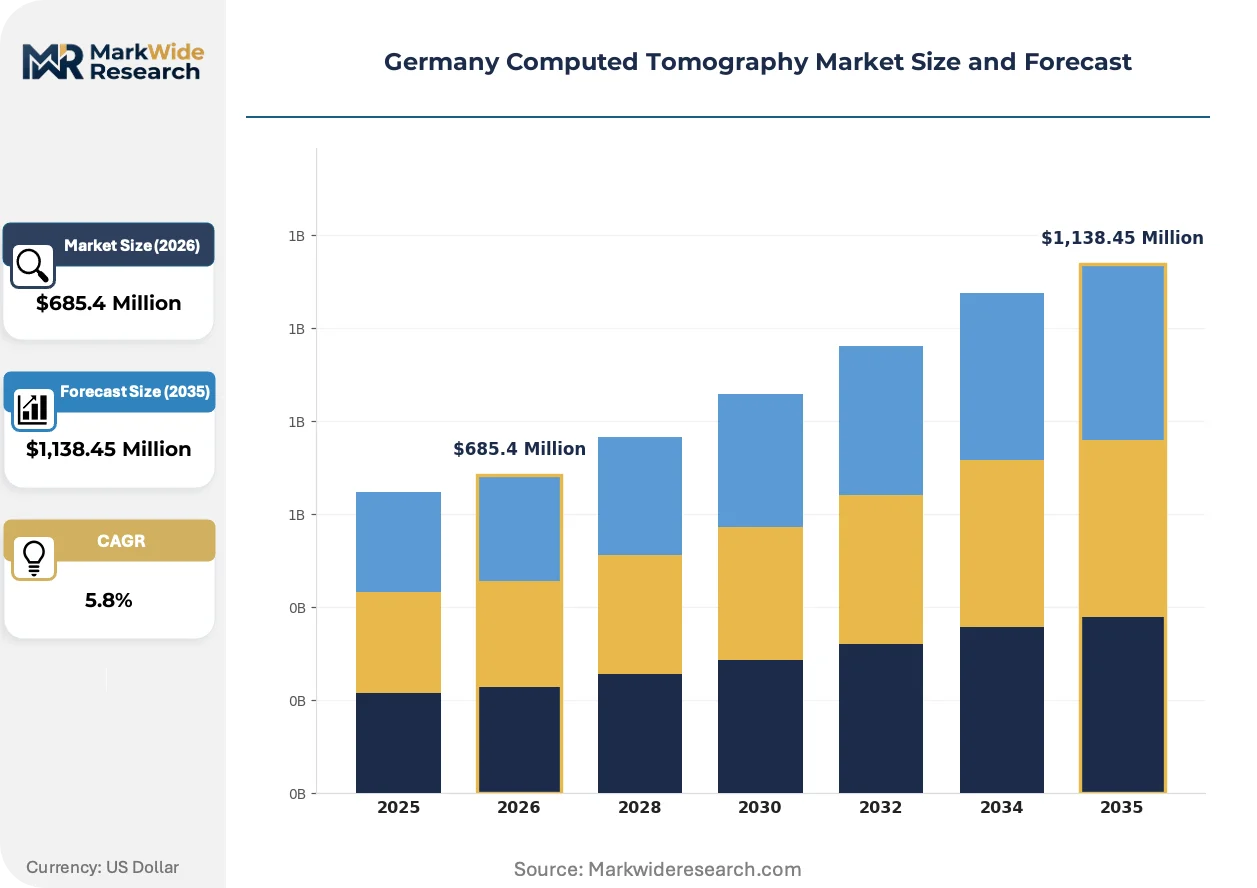
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Slice CT, Multi-Slice CT, Portable CT, Cone Beam CT, Electron Beam CT Application: Neurology, Oncology, Cardiology, Orthopedics, Pulmonology, Gastroenterology End User: Hospitals, Diagnostic Imaging Centers, Ambulatory Surgical Centers, Specialty Clinics, Research Institutes Deployment: Fixed Installation, Mobile Units, Remote Diagnostics, Cloud-Enabled Systems |
| Companies Covered | Siemens Healthineers, GE Healthcare, Koninklijke Philips, Canon Medical Systems, Fujifilm Holdings, Samsung, United Imaging Healthcare, Shimadzu, Carestream Health, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Computed Tomography Market Shifts & Advancements
Artificial intelligence is penetrating image reconstruction pipelines while regulatory frameworks reclassify software as active medical devices, and procurement patterns are migrating from capital expenditure cycles toward operational subscription models.
Photon-counting detector technology is automating spectral decomposition at the detector level, eliminating the need for dual-energy acquisition protocols. German oncology departments are adopting these systems for quantitative tissue characterization. The technology is automating material differentiation tasks previously requiring radiologist interpretation, compressing reporting turnaround times.
EU MDR Annex VIII reclassification rules are subjecting AI-enabled CT reconstruction algorithms to active medical device conformity procedures. Manufacturers must now compile clinical evidence packages demonstrating diagnostic performance equivalence. German notified bodies are experiencing backlog accumulation, delaying market authorization for software updates that previously qualified as maintenance releases.
After-sales service unbundling is fragmenting traditional bundled procurement contracts into separate hardware, software, and maintenance line items. University hospital purchasing consortia are negotiating component-level pricing transparency. This pattern is most visible in North Rhine-Westphalia, where centralized procurement entities are disaggregating multi-year service agreements into annual renewable software licenses.
Germany Computed Tomography Market Segmentation
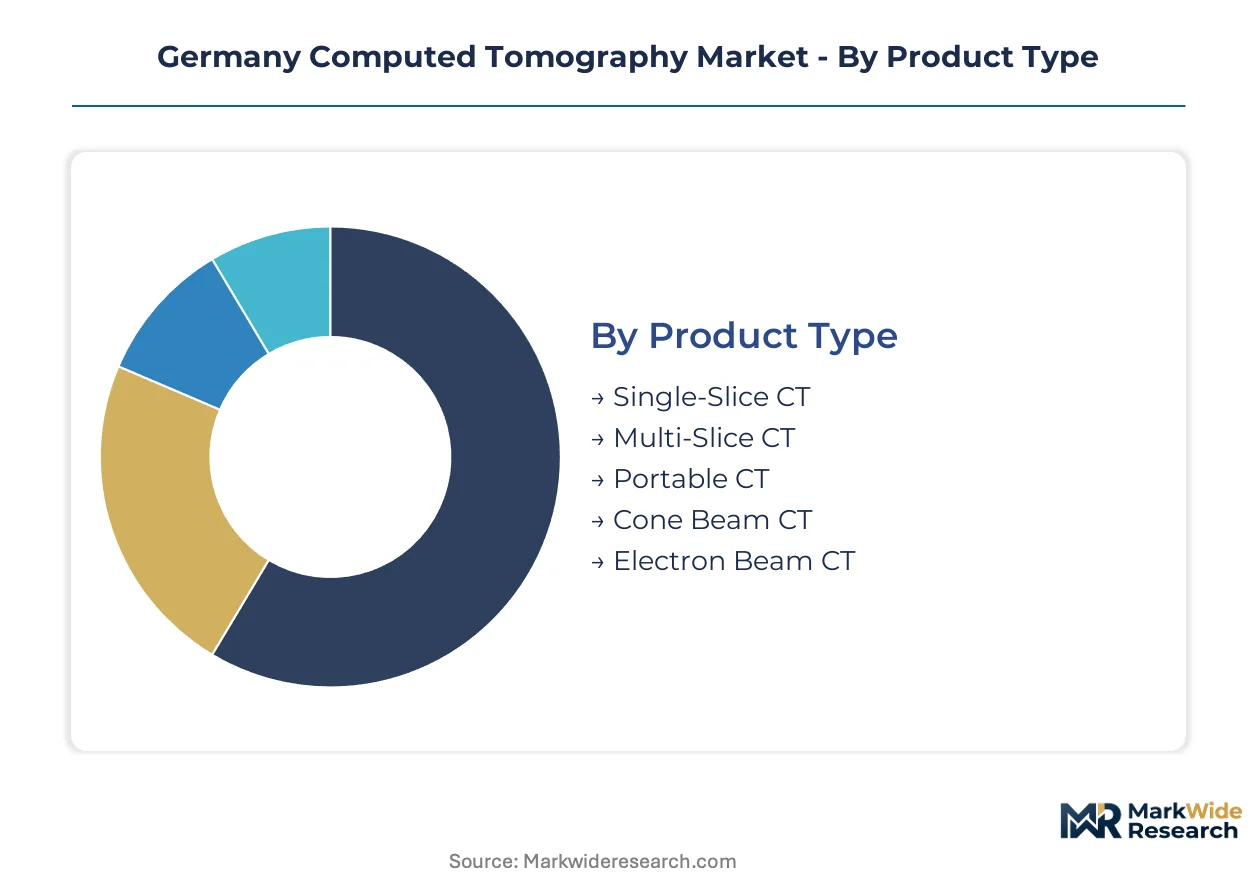
CT market segmentation in Germany tracks how hardware configurations, clinical applications, and deployment architectures distribute value across reimbursement tiers and procurement channels. Each dimension shapes capital allocation patterns and service revenue potential differently.
Product Type:
Standalone floor-mounted systems dominate hospital infrastructure planning, while portable and embedded configurations penetrate point-of-care networks and hybrid surgical environments.
- Multi-Slice CT:Rotating gantry systems acquire 256+ simultaneous slices through helical acquisition protocols, generating sub-millimeter isotropic voxels for volumetric reconstruction. Bavarian university hospitals anchor demand for premium configurations capable of spectral decomposition and cardiac gating. BfArM conformity timelines for software-upgradable systems extend replacement cycles toward decade-long intervals.
- Portable CT:Self-shielded wheeled units deploy at bedside for stroke network protocols and intensive care diagnostics, eliminating patient transport risks. North Rhine-Westphalian hospital clusters lead procurement for door-to-needle time reduction. KBA-equivalent DIN safety standards govern electromagnetic compatibility for corridor transit between departments.
- Single-Slice CT:Legacy helical scanners with 1-4 detector rows persist in rural diagnostic imaging centers with constrained capital budgets and lower patient throughput requirements.
- Cone Beam CT:Flat-panel detector systems optimized for dental maxillofacial and interventional radiology applications deliver lower dose profiles for focused anatomical regions.
- Electron Beam CT:Stationary ring-geometry scanners with electron-beam X-ray generation enable sub-second cardiac imaging without mechanical rotation, though installed base contraction reflects multi-slice substitution.
Volume placements concentrate in Multi-Slice CT; the faster expansion belongs to Portable CT.
Application:
Reimbursement intensity and procedure complexity determine how clinical departments prioritize CT capital allocation against MRI and nuclear medicine alternatives.
- Oncology:Spectral CT platforms enable quantitative iodine mapping for tumor perfusion assessment and treatment response monitoring. German university hospitals embed these workflows into precision staging protocols. EU MDR post-market surveillance requirements for AI-enabled lesion characterization are elevating documentation burdens.
- Cardiology:Dual-source architectures sustain coronary CT angiography throughput with sub-millisecond temporal resolution for motion-free imaging. Cardiac catheterization laboratories in Baden-Württemberg drive demand for hybrid interventional suites. StrlSchG dose reference levels shape detector sensitivity specifications.
- Neurology:Emergency stroke protocols prioritize non-contrast head CT for hemorrhage exclusion before thrombolysis administration.
- Orthopedics:Weight-bearing extremity CT and pre-surgical planning applications concentrate in specialized musculoskeletal centers.
- Pulmonology:Low-dose lung cancer screening and interstitial lung disease characterization utilize high-resolution acquisition protocols.
- Gastroenterology:CT enterography and virtual colonoscopy applications face substitution pressure from capsule endoscopy and MR enterography.
Revenue concentration sits with Oncology; Cardiology claims the steepest expansion trajectory from hybrid suite integration.
End User:
Procurement scale and service contracting sophistication separate institutional buyers from distributed outpatient networks.
- Hospitals:Maximum-slice configurations with spectral capability and interventional compatibility anchor capital budgets exceeding single-unit placements. Centralized purchasing consortia in North Rhine-Westphalia negotiate component-level pricing unbundling. BfArM technical documentation requirements favor established suppliers with regulatory affairs infrastructure.
- Diagnostic Imaging Centers:Outpatient-focused operators prioritize throughput-per-square-meter and rapid turnaround for referring physician relationships.
- Ambulatory Surgical Centers:Limited floor space and procedure-specific imaging needs favor compact single-room installations.
- Specialty Clinics:Orthopedic and dental practices deploy cone-beam systems for focused anatomical coverage at lower capital intensity.
- Research Institutes:Preclinical and clinical trial imaging demands drive phantom calibration protocols and quantitative biomarker validation.
Installed base dominance rests with Hospitals; Diagnostic Imaging Centers are gaining share fastest from outpatient migration.
Deployment:
Physical infrastructure requirements and data architecture decisions determine total cost of ownership across acquisition and operational phases.
- Fixed Installation:Shielded suite construction with integrated power conditioning and climate control supports maximum-performance gantry configurations. German hospital construction codes mandate radiation protection engineering for new radiology department builds.
- Cloud-Enabled Systems:Reconstruction algorithms and AI inference execute on remote infrastructure, shifting capital expenditure toward recurring software subscriptions. University hospital IT departments negotiate data residency requirements under GDPR and BfArM guidance.
- Mobile Units:Trailer-mounted or vehicle-integrated systems serve rural screening programs and temporary capacity expansion.
- Remote Diagnostics:Teleradiology integration enables specialist interpretation across distributed acquisition sites.
Procurement volume favors Fixed Installation; Cloud-Enabled Systems are climbing the fastest from subscription model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The German Research Incentive Act (Forschungszulagengesetz) channels R&D investment into medical imaging clusters across federal states, concentrating CT innovation in high-technology zones with tax-advantaged status.
Bavaria
University hospitals in Munich and Erlangen deploy spectral CT platforms for precision oncology staging. The Bavarian Ministry of Economic Affairs funds medical technology clusters through the High-Tech Agenda Bayern initiative. Siemens Healthineers anchors semiconductor fabrication for SiPM detectors in Forchheim, supplying premium scanner lines.
North Rhine-Westphalia
Hospital purchasing consortia in Cologne and Düsseldorf negotiate component-level pricing unbundling for multi-slice systems. BfArM conformity assessment timelines extend certification for AI-enabled reconstruction algorithms. Stroke networks across the Ruhr region deploy portable CT units to reduce door-to-needle times in emergency departments.
Baden-Württemberg
Cardiac catheterization laboratories in Stuttgart and Heidelberg drive demand for dual-source CT architectures with sub-millisecond temporal resolution. The German Radiation Protection Act (StrlSchG) mandates dose reference levels shaping detector sensitivity specifications. Hybrid interventional suites in Freiburg integrate real-time CT guidance for minimally invasive procedures.
Lower Saxony
Rural diagnostic imaging centers in Hanover and Braunschweig maintain legacy single-slice CT configurations with constrained capital budgets. DIN electromagnetic compatibility standards govern installed base upgrades for corridor-transit portable units. The state's medical device safety administration enforces VDE framework compliance for electrical safety certification.
Hesse
Frankfurt university medical centers prioritize cloud-enabled CT deployment with GDPR-compliant data residency requirements. BfArM guidance on AI reconstruction algorithms reclassifies software as active medical devices subject to enhanced clinical evidence. Research institutes in Darmstadt validate quantitative biomarker protocols for clinical trial imaging applications.
Germany Computed Tomography Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated control at the premium scanner tier and fragmented competition in portable and refurbished equipment. The vendor base organizes around three archetypes: integrated semiconductor fabricators capturing detector supply chains, dual-source architecture specialists defending cardiac throughput advantages, and spectral-platform operators targeting oncology quantification. Competitive moves concentrate on backward integration into detector materials and unbundled service contracting to capture recurring software revenue.
Among Germany-based integrated manufacturers, Siemens Healthineers exemplifies the captive-supply archetype through in-house SiPM fabrication. GE Healthcare and Koninklijke Philips occupy positions as multinational imaging platform operators with differentiated hardware architectures. These three entities represent the premium-tier concentration where regulatory affairs infrastructure and BfArM technical documentation capabilities create defensive moats.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GE Healthcare |
| Koninklijke Philips |
| Canon Medical Systems |
| Fujifilm Holdings |
| Samsung |
| United Imaging Healthcare |
| Shimadzu |
| Carestream Health |
| Others |
Supply & Pricing Matrix
Premium-economy scanner bifurcation separates university hospital spectral platforms from rural diagnostic centers' legacy configurations, manifesting in divergent procurement models where Bavarian institutions negotiate unbundled software subscriptions while Lower Saxony operators absorb bundled maintenance markups on depreciated hardware.
Pricing Analysis
Volume placements concentrate in mid-tier multi-slice configurations while margin pools concentrate in premium spectral platforms with AI-enabled reconstruction subscriptions. Pricing stratifies across premium, standard, and economy tiers based on detector row count and spectral capability certification. Cost compression in portable CT segments stems from Chinese and Korean manufacturer entry with simplified gantry architectures. Diagnostic imaging centers exhibit highest price sensitivity due to throughput-per-square-meter pressures, whereas university hospital purchasing consortia prioritize clinical performance over unit economics.
Supply Chain Analysis
Regional distribution centers in Forchheim and Hamburg coordinate hub-and-spoke logistics for detector module replacement across German hospital clusters. SiPM semiconductor fabrication concentrates in Germany, Japan, and the USA, while rare earth phosphor materials for scintillator crystals draw primarily from Chinese processing facilities. Single-source vulnerability in helium-3 cooling supplies elevates maintenance cost volatility for superconducting-adjacent installations. Distribution runs through manufacturer-direct service contracts with hospital biomedical engineering departments, bypassing traditional medical device distributors for premium-tier placements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into detector materials and cloud-native software stacks constitutes the dominant competitive race, with SiPM fabrication capabilities and AI reconstruction algorithm portfolios serving as the decisive upstream and downstream levers respectively.
For Market Incumbents: Deploy captive SiPM semiconductor fabrication to secure detector supply chains against photomultiplier tube discontinuation risks. Consolidate regulatory affairs infrastructure to compress BfArM conformity assessment timelines for AI-enabled reconstruction algorithms. Magnetic resonance substitution in neurology applications threatens CT utilization rates in musculoskeletal and soft tissue segments.
For New Entrants and Emerging Players: The premium-portable price gap between fixed spectral platforms and self-shielded bedside units creates entry space for simplified gantry architectures with cloud-tethered reconstruction. Stroke network deployments across North Rhine-Westphalian hospital clusters represent the most penetrable segment. Pursue hospital system partnership models with component-level pricing transparency to bypass incumbent service bundling.
For Investors and Strategic Acquirers: Re-rating potential sits with cloud-native reconstruction platform specialists given EU MDR software reclassification tailwinds. Long-term viability favors entities with recurring revenue profiles exceeding fifty percent of total sales. Monitor BfArM backlog accumulation rates as inflection indicator for regulatory capacity constraints affecting market authorization velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Detector Materials | Siemens Healthineers' Forchheim semiconductor fabrication secures SiPM supply chains against photomultiplier tube phase-outs. |
| Cloud-Native Reconstruction Platform Development | AI-enabled image processing shifts value capture toward subscription architectures with recurring revenue profiles under EU MDR. |
| Hospital System Partnership Structuring | North Rhine-Westphalian purchasing consortia negotiate component-level pricing unbundling for multi-slice system deployments. |
| Portable CT Stroke Network Penetration | Bavarian and Ruhr region emergency departments deploy bedside units to compress door-to-needle times for thrombolysis protocols. |
| EU MDR Regulatory Affairs Infrastructure Investment | BfArM technical documentation capabilities create defensive moats against twelve-to-eighteen month certification delays. |
Research Methodology
Document review covered EU MDR guidance documents, BfArM technical documentation requirements, and DIN electromagnetic compatibility standards, complemented by interviews with hospital biomedical engineers, radiology department heads, GPO contracts managers, and medical device regulatory affairs specialists. Secondary validation drew from hospital procurement databases, GPO contract filings, and CMS-equivalent German reimbursement schedules. Bottom-up installed base modeling and top-down market sizing triangulated volume and value estimates.
Historical shipment data cross-referenced against expert panel input on replacement cycle dynamics and spectral CT adoption curves across the projection horizon. Segmentation dimensions modeled include product type, clinical application, end-user institution scale, and deployment architecture. CAGRs derived from logistic diffusion curves fitted to technology substitution patterns and reimbursement tier evolution. Detector material cost trajectories and EU MDR compliance burden indices served as industry-specific forecast inputs.
Inputs from hospital purchasing committees and notified body representatives were available through the study window; gaps in real-time AI reconstruction algorithm clinical outcome data introduce uncertainty bands around software revenue projections. Forecasts reflect documented assumptions on EU MDR implementation timelines and SiPM semiconductor yield improvements. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Transesophageal Echocardiography (TEE) Market
Medical Imaging
Global Computed Tomography (CT) Market
Medical Imaging
United States Diagnostic Imaging Market
Medical Imaging
Global Elastography Imaging Market
Medical Imaging
South Africa Computed Tomography Market
Medical Imaging
Global Super Resolution Microscopes Market
Medical Imaging
Latin America Medical Imaging Software Market
Medical Imaging
Europe Open System MRI Market
Medical Imaging
Chile Diagnostic Imaging Equipment Market
Medical Imaging
North America Fluoroscopy Market
Medical Imaging
Smart X-Ray Detectors Market
Medical Imaging
United Kingdom Mammography Market
Medical Imaging
Japan Mammography Market
Medical Imaging
Radiographic Film Processor Market
Medical Imaging
Magnetic Resonance Imaging (MRI) Contrast Agents Market
Medical Imaging
Italy Digital Radiology Market