
 BRAF-MEK Inhibitors Market | 2026-2036
BRAF-MEK Inhibitors Market Size, Share, and Industry Trends Forecast 2026-2036
BRAF-MEK Inhibitors Market Analytics
EMA's oncology drug assessment framework is consolidating the cost-of-entry calculus for combination therapies across European markets. Pfizer Inc. leverages its manufacturing scale to sustain supply security for MEK inhibitor portfolios. Novartis AG anchors its position through deep specialization in targeted melanoma protocols. F. Hoffmann-La Roche Ltd. competes on clinical data breadth across dermatology and oncology indications.
BRAF-MEK inhibitors are small-molecule signal transduction modulators that interrupt the mitogen-activated protein kinase cascade by blocking mutated BRAF kinases and downstream MEK1/MEK2 enzymes, with oral bioavailability typically requiring once- or twice-daily dosing regimens. Their primary purpose is to arrest proliferation in tumors harboring BRAF V600 mutations, particularly metastatic melanoma where they have replaced cytotoxic chemotherapy as first-line intervention. Combination therapies lead the product landscape due to superior progression-free survival outcomes over monotherapy, while oncology dominates application demand fueled by protocol adoption in academic medical centers. The distribution channel structure tilts toward hospital and specialty pharmacy direct sales where cold-chain logistics and patient monitoring programs create margin pools that retail pharmacies struggle to capture.
FDA accelerated approval pathways and EMA conditional marketing authorization frameworks compress development timelines but impose rigorous post-market confirmatory trial obligations that reshape capital allocation. The EU AI Act and FDA's evolving guidance on real-world evidence integration are creating new compliance dimensions for adaptive trial designs. Japan's PMDA sakigake designation system adds a third regulatory speed lane that manufacturers must navigate for early market positioning. Stakeholders should monitor how payer evidence requirements evolve alongside regulatory flexibility, as reimbursement contracts increasingly determine commercial viability faster than approval status itself.
Market Dynamics
FDA accelerated approval pathways compress development timelines for combination therapies, forcing manufacturers to front-load capital into confirmatory trials while post-market obligations reshape portfolio risk calculations.
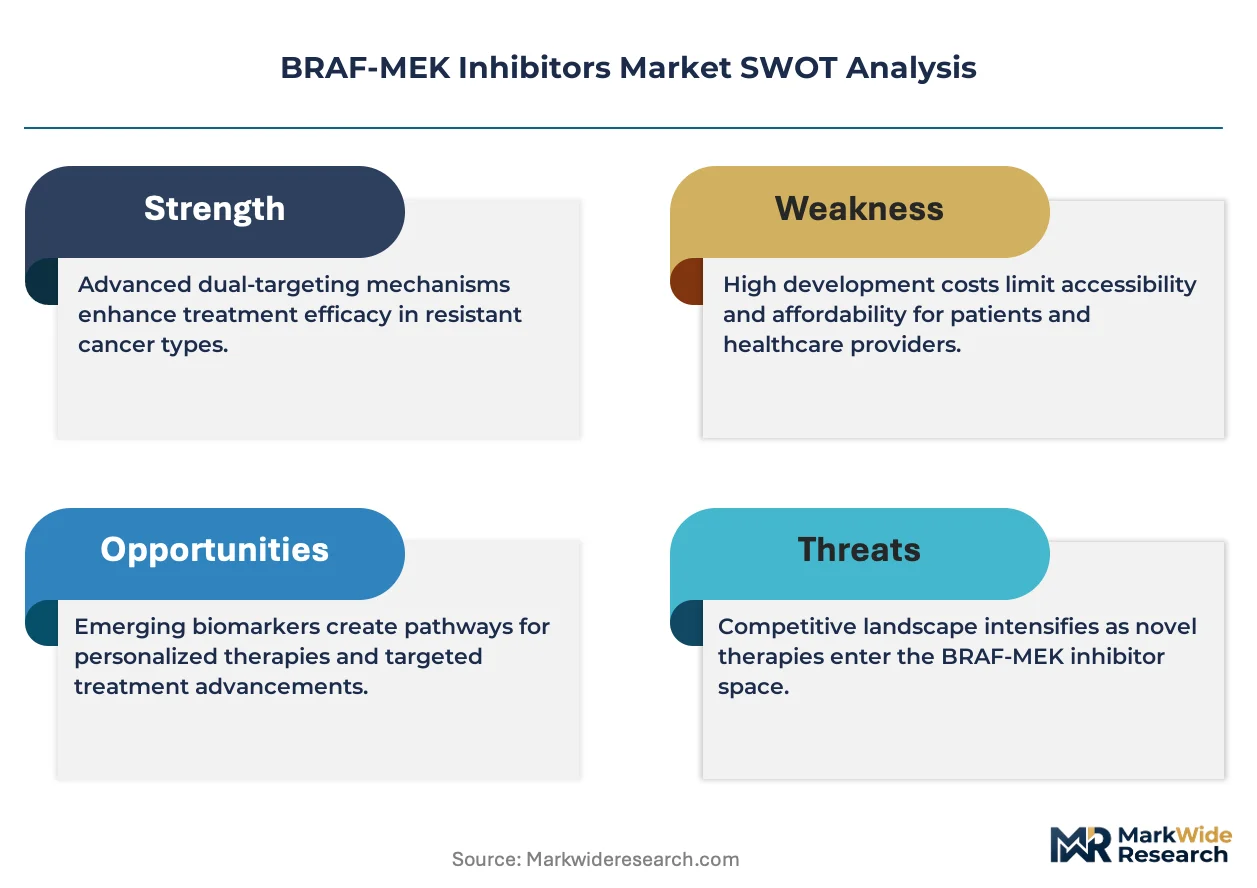
Growth Catalysts
- EMA Conditional Marketing Authorization:The framework compresses time-to-revenue for melanoma combination protocols, enabling earlier patient access while evidence generation continues.
- Academic Medical Center Adoption:Oncology departments at tertiary hospitals anchor demand through protocol standardization, creating pull-through for companion diagnostics.
- Real-World Evidence Integration:FDA guidance on RWE acceptance is unifying clinical and post-market data streams, reducing trial redundancy for targeted therapies.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:MEK inhibitor synthesis depends on specialized intermediate suppliers concentrated in China and India, creating single-source vulnerability.
- Reimbursement Contract Complexity:Payer evidence requirements for combination regimens exceed monotherapy thresholds, extending commercial access negotiations.
- Resistance Mechanism Substitution:BRAF-independent pathway activation limits durable response, pressuring development of next-generation sequencers.
Strategic Opportunities
- Japan PMDA Sakigake Designation:Early approval pathways for breakthrough therapies enable first-mover positioning in Asia-Pacific melanoma protocols.
- Colorectal Cancer Line Extension:BRAF V600E-mutated mCRC represents an underpenetrated indication with unmet need and distinct competitive dynamics.
- Specialty Pharmacy Direct Distribution:Cold-chain logistics and patient monitoring programs create margin pools that bypass retail pharmacy intermediation.
Industry Challenges
- Adaptive Trial Design Expertise:Biostatistical talent for seamless Phase II/III protocols remains scarce, constraining sponsor execution speed.
- Post-Market Confirmatory Trial Capital:FDA-mandated survival studies require sustained investment after approval, diverting resources from pipeline expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | BRAF-MEK Inhibitors Market |
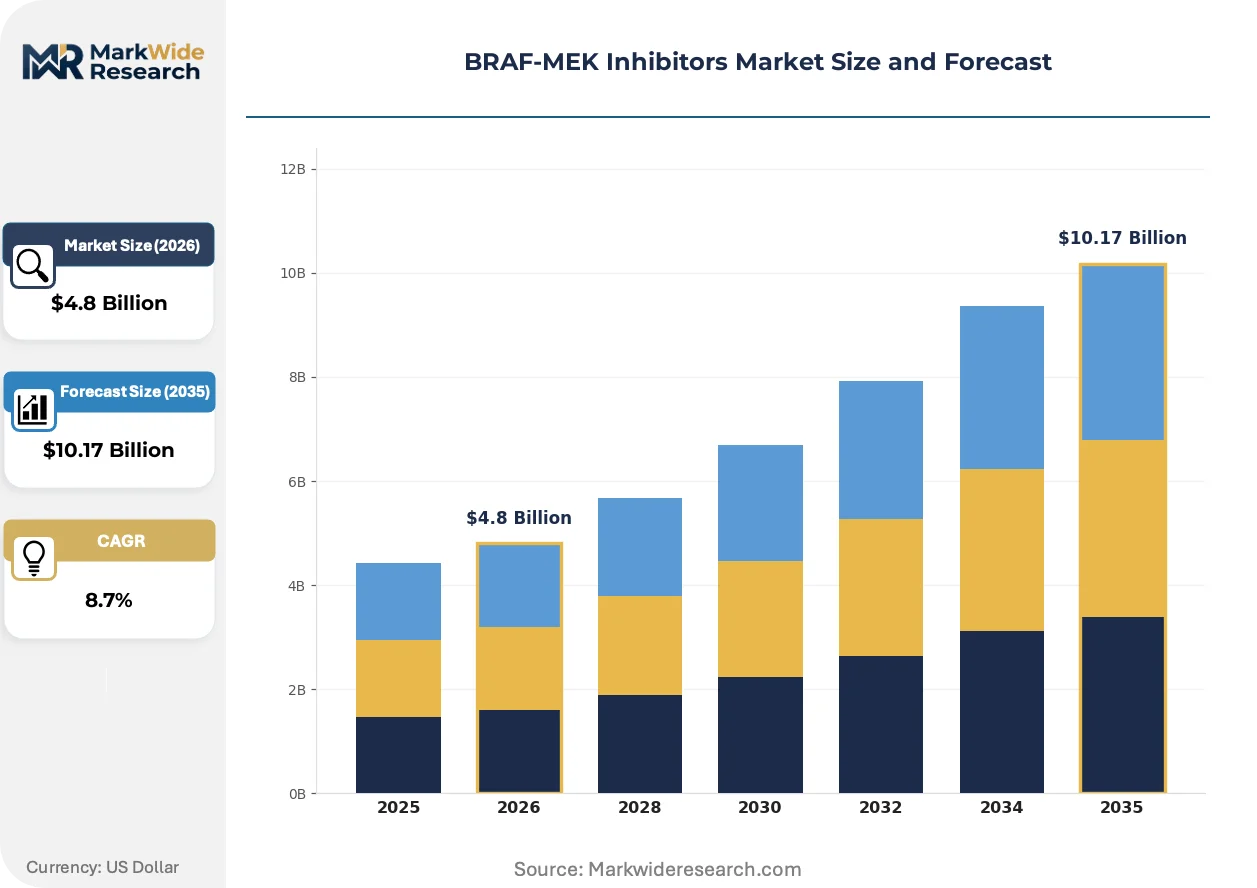
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: BRAF Inhibitors, MEK Inhibitors, Combination Therapies, Targeted Agents Application: Oncology, Dermatology, Clinical Trials, Personalized Medicine End User: Hospitals, Research Institutions, Oncology Centers, Specialty Clinics Distribution Channel: Retail Pharmacies, Online Pharmacies, Wholesalers, Direct Sales |
| Companies Covered | AstraZeneca, BeiGene Ltd., F. Hoffmann-La Roche Ltd., Jazz Pharmaceuticals Plc, Ono Pharmaceutical Co. Ltd., Pfizer Inc., Bayer AG, Merck KGaA, Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
BRAF-MEK Inhibitors Market Evolving Landscape
Clinical trial architecture and regulatory interaction models are undergoing structural revision as adaptive designs and real-world evidence frameworks mature.
Next-generation sequencing-based patient stratification is unifying biomarker identification with treatment selection. Oncology centers deploy comprehensive genomic profiling at diagnosis, compressing the interval between mutation detection and therapy initiation. This convergence is unifying diagnostic and therapeutic decision workflows into single-visit protocols.
The EU AI Act imposes algorithmic transparency requirements on clinical decision support tools used in adaptive trial monitoring. Sponsors must document training data provenance and performance metrics for AI-assisted endpoint adjudication. Dermatology-oncology crossover protocols face heightened documentation burdens as machine learning integrates into progression assessment.
Hospital procurement departments now negotiate indication-specific value frameworks rather than molecule-based contracts. Payers in Germany and Japan tie reimbursement to progression-free survival milestones, displacing traditional volume-based purchasing. Academic medical centers in the United States pilot outcomes-guarantee arrangements with manufacturers.
BRAF-MEK Inhibitors Market Segmentation
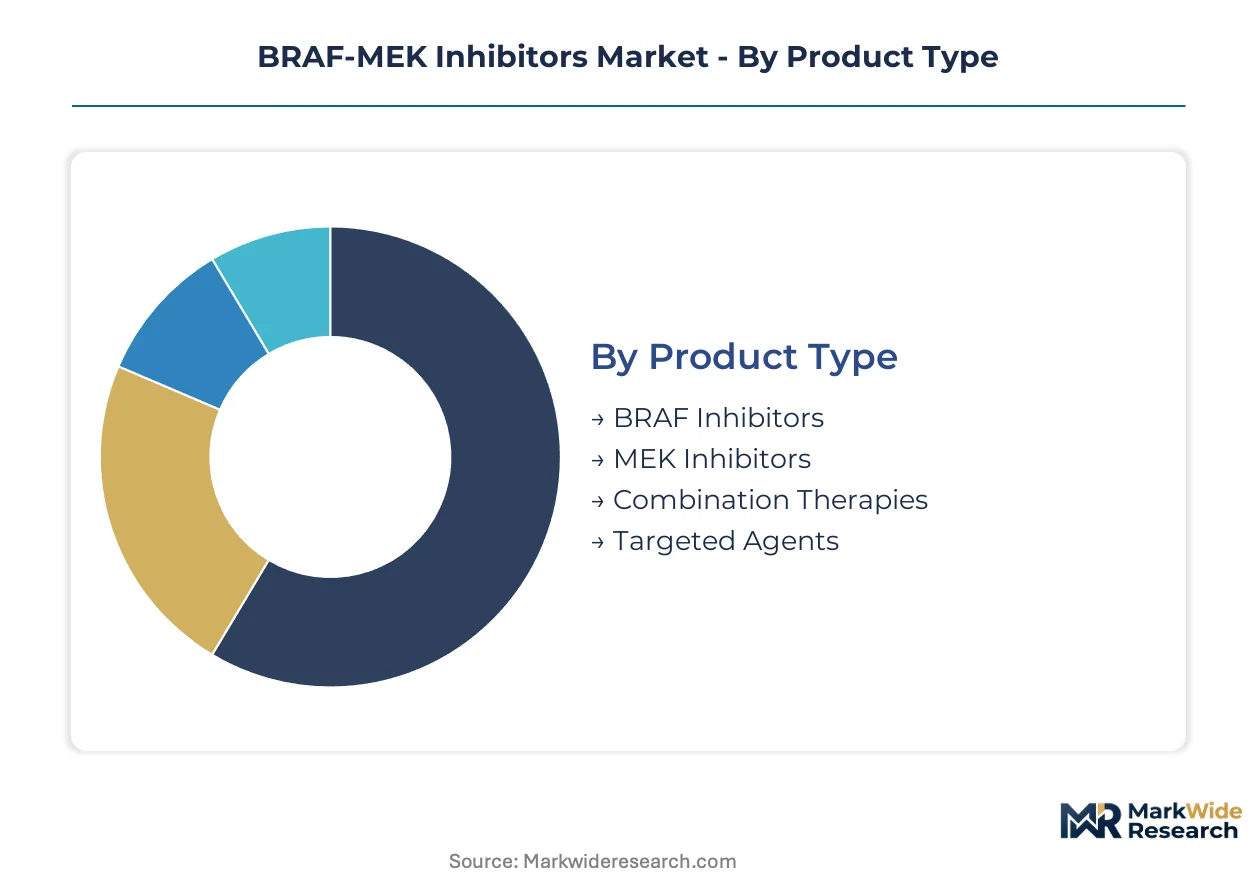
BRAF-MEK inhibitor commercialization demands precise alignment between molecular mechanism and clinical deployment setting. Segmentation reveals how formulation choices, care delivery sites, and channel structures jointly determine patient access and manufacturer margin capture.
Product Type:
Dual-target blockade defines the therapeutic frontier, with molecular architecture dictating efficacy duration and resistance profiles.
- Combination Therapies:Simultaneous BRAF and MEK inhibition delivers superior progression-free survival versus sequential monotherapy. Academic medical centers in the United States anchor demand through protocol standardization that elevates combination regimens to first-line status.
- BRAF Inhibitors:Selective V600E-mutant kinase blockers like vemurafenib and dabrafenib established the targeted therapy paradigm. Germany's dermatology-oncology crossover clinics concentrate prescription volume where companion diagnostic integration is most advanced.
- MEK Inhibitors:Downstream pathway interruption complements upstream BRAF blockade. Japan's PMDA sakigake designation pathway accelerates regulatory review for novel MEK agents.
- Targeted Agents:Next-generation molecules address acquired resistance mechanisms through alternative binding modes. Early-phase development concentrates in research institutions with NGS-enabled patient stratification capabilities.
Mature deployment sits with BRAF Inhibitors. Newer deployment is concentrated in Combination Therapies.
Application:
Clinical utility expands beyond melanoma as biomarker-driven protocols penetrate adjacent tumor types.
- Oncology:Metastatic melanoma remains the indication with deepest protocol penetration and reimbursement security. Hospital outpatient departments drive volume through integrated diagnostic-therapeutic workflows.
- Personalized Medicine:Comprehensive genomic profiling enables real-time treatment matching to mutation status. Specialty clinics in Japan and Germany lead adoption where liquid biopsy infrastructure is most mature.
- Dermatology:Cutaneous squamous cell carcinoma and other skin malignancies with BRAF alterations represent emerging addressable populations. Dermatology-oncology collaborative practices concentrate early utilization.
- Clinical Trials:Investigator-initiated studies and sponsor trials generate demand for comparator agents and novel combinations. Research institutions with NCI-designated cancer center status anchor enrollment.
Volume concentration rests with Oncology. Steepest expansion trajectory belongs to Personalized Medicine.
End User:
Site-of-care economics and patient complexity determine procurement authority and formulary placement.
- Oncology Centers:Dedicated cancer treatment facilities command purchasing leverage through concentrated patient volume and protocol influence. United States-based NCI-designated centers set standards that diffuse to community practice.
- Hospitals:Integrated health systems negotiate indication-specific value frameworks rather than molecule-based contracts. German hospital procurement coalitions extract price concessions through pooled tendering.
- Specialty Clinics:Focused dermatology and melanoma practices deliver high-touch patient monitoring required for adverse event management. Urban clusters in Japan concentrate this channel where physician density supports subspecialization.
- Research Institutions:Academic medical centers anchor early adoption and generate real-world evidence supporting label expansion. Investigator-initiated trial networks extend reach beyond commercial sales forces.
Procurement authority concentrates in Oncology Centers. Emerging influence is shifting toward Specialty Clinics.
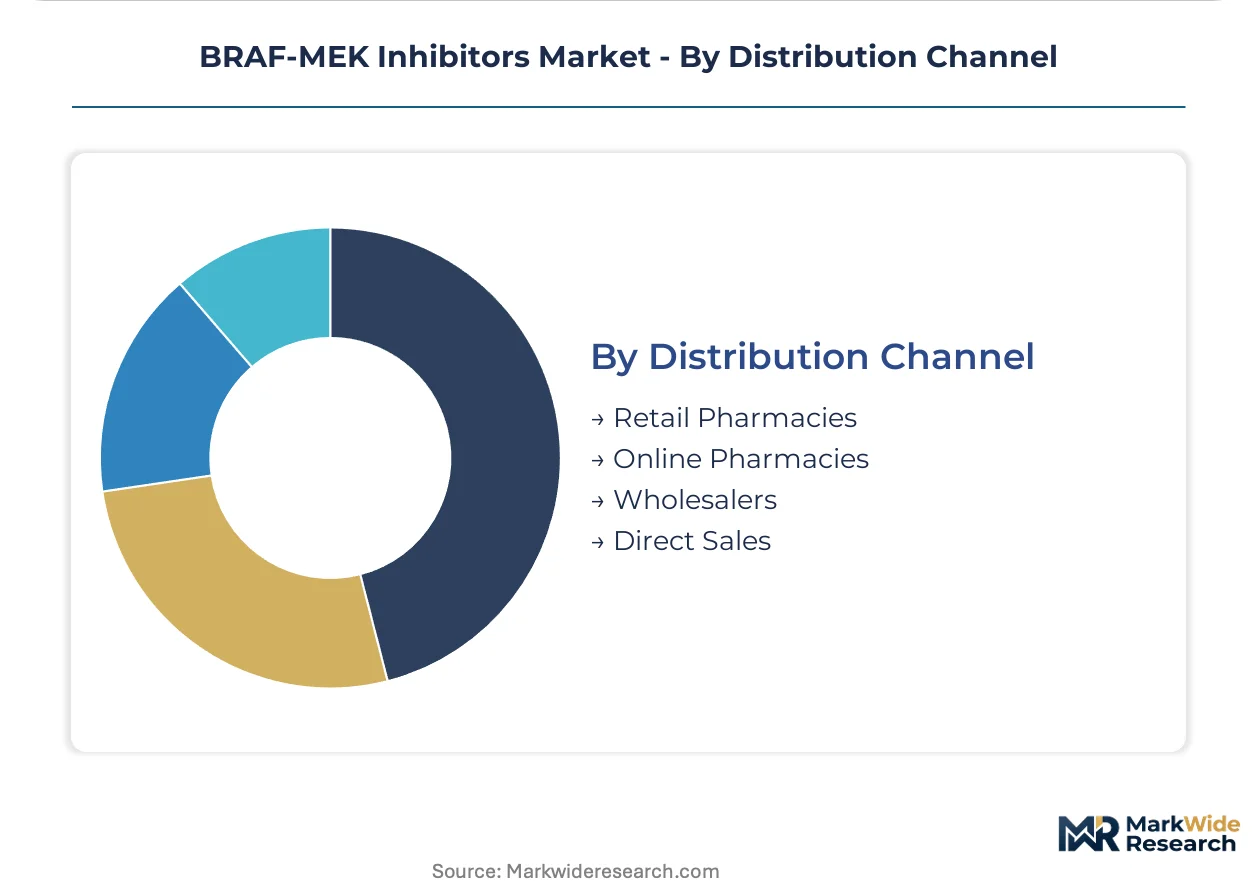
Distribution Channel:
Cold-chain requirements and patient monitoring obligations reshape channel economics away from traditional retail.
- Direct Sales:Manufacturer-to-provider distribution bypasses wholesale markups and enables patient support program integration. Hospital and specialty pharmacy direct purchasing dominates in the United States and Germany.
- Wholesalers:Three-tier distribution retains relevance for community oncology practices with limited cold-chain infrastructure. Regional wholesalers in Japan maintain position through relationships with smaller clinic networks.
- Retail Pharmacies:Generalist pharmacy channels capture limited share due to specialized handling requirements and prior authorization complexity. Retail participation concentrates in markets with relaxed specialty dispensing regulations.
- Online Pharmacies:Digital distribution models emerge for oral oncology agents with established safety profiles. Regulatory frameworks in select European markets permit limited direct-to-patient dispensing.
Established volume flows through Direct Sales. Channel development is accelerating in Online Pharmacies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Oncology biopharma clusters in the Research Triangle Park zone concentrate BRAF-MEK inhibitor development infrastructure, attracting FDA-tracked trials and specialized manufacturing investment.
United States
NCI-designated cancer centers in Boston and Houston drive protocol adoption for combination melanoma therapies. FDA accelerated approval pathways compress time-to-market for novel MEK inhibitors. The Research Triangle Park biopharma corridor anchors clinical trial operations with integrated genomic profiling laboratories.
Germany
Dermatology-oncology crossover clinics in Munich and Heidelberg concentrate prescription volume for targeted agents. EMA conditional marketing authorization frameworks enable earlier patient access while confirmatory trials continue. The Rhine-Main biotech cluster hosts specialized logistics providers for cold-chain distribution.
Japan
PMDA sakigake designation accelerates regulatory review for breakthrough melanoma therapies, compressing approval timelines. Tokyo and Osaka academic medical centers anchor demand through protocol standardization. The Kansai region concentrates specialty pharmacy networks with integrated patient monitoring capabilities.
United Kingdom
NHS England's Cancer Drugs Fund creates reimbursement security for combination regimens in metastatic melanoma. London and Manchester oncology centers drive adoption through genomic screening programs. The Golden Triangle biotech corridor connects academic research to early-phase clinical infrastructure.
Switzerland
Swissmedic's streamlined oncology review processes attract European headquarters for targeted therapy developers. Basel and Zurich concentrate pharmaceutical manufacturing with integrated quality control for small-molecule synthesis. The country's precision medicine initiatives align diagnostic and therapeutic decision workflows.
BRAF-MEK Inhibitors Market Competitive Landscape
United States-based pharmaceutical conglomerates anchor one tier; European oncology specialists hold differentiated positions in melanoma protocols. Market structure tilts toward consolidated control among integrated biopharma operators with existing immuno-oncology portfolios. Three archetypes dominate: large-cap diversified pharmas with manufacturing scale, mid-cap targeted therapy specialists, and emerging biotechs with next-generation resistance mechanisms. Competitive moves center on portfolio expansion through licensing arrangements and geographic positioning for regulatory speed lanes.
Within the large-cap tier, Pfizer Inc. and Novartis AG exemplify scale-driven operators with established MEK inhibitor portfolios, while F. Hoffmann-La Roche Ltd. occupies a position bridging diagnostic and therapeutic integration. These entities represent the consolidated core where manufacturing security and clinical data breadth determine formulary placement authority.
| Leading Market Players |
|---|
| AstraZeneca |
| BeiGene Ltd. |
| F. Hoffmann-La Roche Ltd. |
| Jazz Pharmaceuticals Plc |
| Ono Pharmaceutical Co. Ltd. |
| Pfizer Inc. |
| Bayer AG |
| Merck KGaA |
| Novartis AG |
| Others |
Value Network & Pricing Analysis
Hospital procurement coalitions in Germany demanding indication-specific value frameworks are forcing manufacturers to restructure contract terms and absorb post-market trial costs, compressing margins and privileging scaled operators with confirmatory study infrastructure.
Pricing Analysis
Short lead-time premiums for cold-chain MEK inhibitor shipments command pricing advantages over standard inventory cycles in the United States and Japan. Three-tier pricing structure across premium, standard, and economy levels reflects FDA approval status, companion diagnostic bundling, and volume commitment scale. Pricing pressure stems from payer evidence requirements for combination regimens that exceed monotherapy thresholds. Community oncology practices exhibit highest price sensitivity due to limited cold-chain infrastructure, while NCI-designated centers prioritize clinical data breadth over unit cost.
Supply Chain Analysis
Certification under EU Good Manufacturing Practice and FDA current Good Manufacturing Practice gates supplier qualification for BRAF-MEK inhibitor active pharmaceutical ingredients. Manufacturing concentrates in China, India, and Switzerland for specialized kinase inhibitor intermediates. Synthesis depends on pyridine derivatives, fluorinated building blocks, and chiral resolution agents. Single-source vulnerability in Chinese intermediate suppliers creates exposure to export restriction risk. Distribution runs through hospital and specialty pharmacy direct purchasing channels that bypass wholesale markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The BRAF-MEK inhibitor market operates as a cost-of-compliance arena where FDA-mandated post-market confirmatory trials erect capital barriers that filter out undercapitalized entrants and entrench scaled incumbents with survival study infrastructure.
For Market Incumbents: To counter resistance mechanism substitution eroding durable response rates, prioritize backward integration into next-generation sequencing diagnostic platforms and captive supply of MEK inhibitor intermediates. Anchor formulary placement through outcomes-guarantee arrangements with academic medical centers that shift reimbursement risk to manufacturers. For New Entrants and Emerging Players: PMDA sakigake designation in Japan opens a window for first-mover positioning in Asia-Pacific melanoma protocols before FDA approval cycles complete. Target colorectal cancer line extensions where BRAF V600E-mutated populations remain underpenetrated. Pursue specialty pharmacy direct distribution partnerships that bypass entrenched hospital procurement coalitions. For Investors and Strategic Acquirers: The window for entry favors mid-cap targeted therapy specialists with adaptive trial design capabilities and existing companion diagnostic relationships. Watch for inflection signals in real-world evidence integration frameworks that accelerate label expansion timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA accelerated approval compresses time-to-revenue while imposing confirmatory trial obligations. |
| Manufacturing Scale-Up | Pfizer and Novartis leverage production capacity to secure supply security for MEK inhibitor portfolios. |
| Pipeline Diversification | Next-generation resistance mechanism programs address BRAF-independent pathway activation limits. |
| Licensing Agreement | Companion diagnostic partnerships unify biomarker identification with treatment selection workflows. |
| Clinical Trial Advancement | Adaptive Phase II/III protocols reduce trial redundancy through seamless efficacy evaluation. |
Research Methodology
FDA filings, EMA assessment reports, and ClinicalTrials.gov records formed the secondary backbone, cross-referenced with formulary database audits and hospital procurement contract disclosures. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and payer access specialists validated quantitative assumptions. Bottom-up patient-flow modeling and top-down manufacturer revenue reconciliation enabled triangulation across data sources.
Historical trendline analysis of melanoma treatment protocol adoption and MEK inhibitor prescription volume established baseline growth trajectories across the projection horizon. Segmentation dimensions included product type, application, end user, distribution channel, and regional regulatory cluster. CAGRs were derived from weighted average of epidemiological projections, pricing elasticity estimates, and reimbursement access probability scoring.
The model assumes a particular technology adoption path for next-generation sequencing-based patient stratification; alternative pathways for liquid biopsy integration would alter the outlook. Forecasts reflect assumptions regarding FDA confirmatory trial completion rates and EMA conditional marketing authorization conversion patterns. A model refresh is warranted upon material change in payer evidence requirements for combination therapy reimbursement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Atrial Fibrillation Drugs Market
Pharmaceuticals
Africa Generic Pharmaceutical Market
Pharmaceuticals
Throat Sprays Market
Pharmaceuticals
North America SGLT2 Inhibitors Market
Pharmaceuticals
Ciclopirox Olamine Market
Pharmaceuticals
Global Self-Administered Drugs Market
Pharmaceuticals
Hospital Pharmaceuticals Market
Pharmaceuticals
Adapalene Products Market
Pharmaceuticals
Iodine Deficiency Drug Market
Pharmaceuticals
Marine Derived Pharmaceuticals Market
Pharmaceuticals
Loxoprofen Market
Pharmaceuticals
Focal Segmental Glomerulosclerosis (FSGS) Therapeutics Market
Pharmaceuticals
Global Vasopressin Market
Pharmaceuticals
Radiopharmaceutical (Oral Route) Market
Pharmaceuticals
Eperisone Hcl Market
Pharmaceuticals
Targeted Liposomes Drug Delivery Market