
 Global Diabetic Retinopathy Market | 2026-2036
Global Diabetic Retinopathy Market Size, Share, and Industry Trends Forecast 2026-2036
Global Diabetic Retinopathy Market Foresight
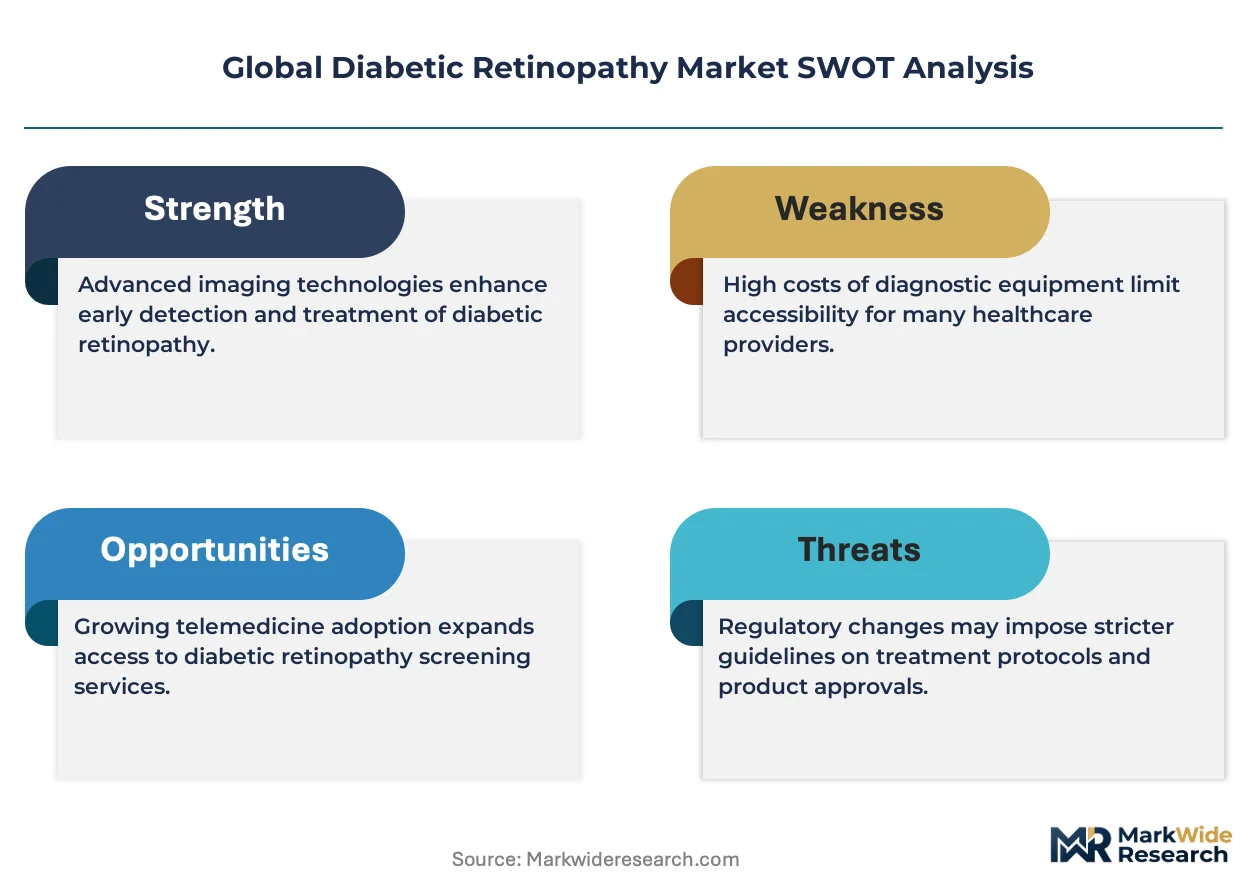
Retinal imaging specialist labor is rotating toward AI-augmented workflows as screening backlogs mount in diabetes-heavy populations. Regeneron Pharmaceuticals leverages its vascular endothelial growth factor franchise to sustain dominance in pharmacological intervention. Bayer AG anchors geographic reach through established ophthalmology distribution networks across Europe and Asia-Pacific. Novartis AG competes via integrated diagnostics-to-therapy platforms that streamline patient pathways from detection to treatment.
Diabetic retinopathy constitutes progressive microvascular damage to retinal tissue arising from chronic hyperglycemia, characterized by microaneurysms, hemorrhage, and neovascularization that degrades visual acuity; diagnostic protocols rely on non-mydriatic fundus photography with minimum 45-degree field capture and spectral-domain optical coherence tomography achieving 5-7 micron axial resolution to detect macular edema. Optical coherence tomography systems command premium positioning due to quantitative thickness mapping capabilities that guide anti-VEGF injection scheduling. Artificial intelligence technology segments attract capital allocation fastest as convolutional neural networks achieve diagnostic parity with fellowship-trained retina specialists in population screening settings. Fundus camera installations remain volume-dominant in emerging markets where cost barriers limit OCT penetration.
The FDA regulates AI diagnostic software as Class II medical devices requiring 510(k) premarket clearance with clinical validation datasets, while the EU AI Act imposes conformity assessment obligations on high-risk diagnostic algorithms deployed in member states. Japan's PMDA accelerates review timelines for AI-enabled screening devices through its Sakigake fast-track designation, reshaping competitive entry sequencing. Stakeholders must calibrate regulatory submission strategies across FDA, EMA, and PMDA jurisdictions while building real-world evidence repositories that satisfy evolving post-market surveillance requirements.
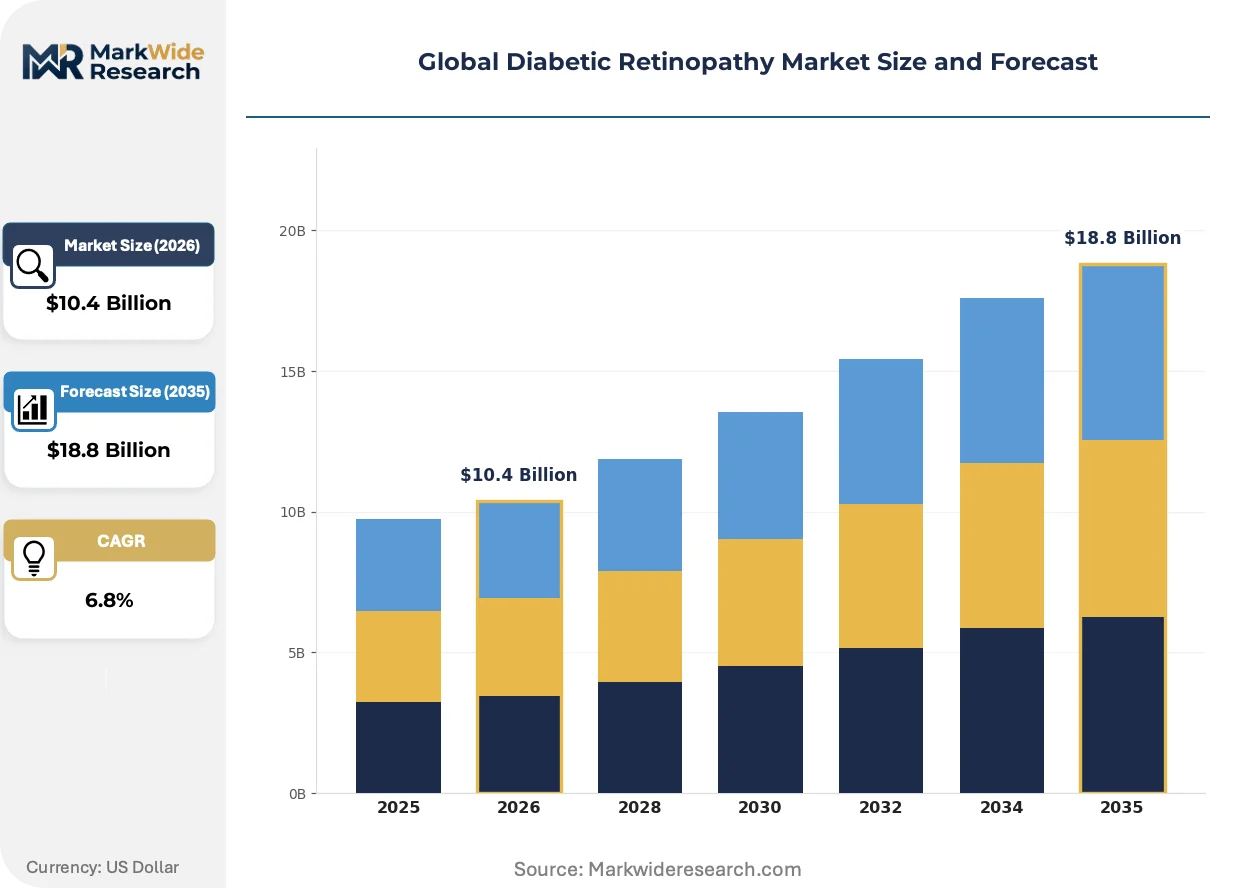
Market Dynamics
Artificial intelligence diagnostic software is fragmenting the traditional ophthalmologist-referral pathway by enabling point-of-care screening in primary care clinics and retail pharmacy settings, compressing the value chain between detection and specialist intervention.
Growth Catalysts
- Japan's Sakigake Fast-Track:PMDA's accelerated review designation for AI-enabled retinal devices compresses commercialization timelines from 24 months to under 12 months.
- Diabetes Prevalence Concentration:India and China's expanding diabetic populations generate screening backlogs that drive automated diagnostic adoption.
- Anti-VEGF Therapy Protocols:Spectral-domain OCT thickness mapping enables precision injection scheduling, expanding treatable patient volumes.
Market Restraints
- OCT Hardware Cost Structure:Spectral-domain systems require $75,000-$150,000 capital outlay, limiting penetration in Brazil and Mexico.
- Retina Specialist Supply Concentration:Fellowship-trained specialists cluster in metropolitan Germany and Japan, creating rural access deserts.
- EU AI Act Conformity Burden:High-risk diagnostic algorithm certification imposes 18-24 month validation timelines before member state deployment.
Strategic Opportunities
- India's Tier-2/Tier-3 Cities:Underpenetrated urban centers with rising diabetes incidence lack screening infrastructure, creating whitespace for mobile fundus camera units.
- Telemedicine Integration:Cloud-based image transmission from pharmacy clinics to centralized reading centers enables asynchronous specialist review.
- US Medicare Reimbursement Expansion:CPT code additions for AI-assisted screening in primary care settings create sustainable revenue models.
Industry Challenges
- Convolutional Neural Network Validation:FDA 510(k) submissions require multi-site clinical datasets exceeding 10,000 images per disease severity grade.
- Interoperability with PACS:Legacy hospital imaging archives use proprietary DICOM implementations that resist seamless AI integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Diabetic Retinopathy Market |
| Market Size in 2026 | $10.4 Billion |
| Market Size in 2035 | $18.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fundus Camera, Optical Coherence Tomography, Fluorescein Angiography, Ultrasound Imaging Technology: Telemedicine, Artificial Intelligence, Laser Therapy, Pharmacological Treatment, Surgical Intervention Application: Early Diagnosis, Disease Monitoring, Vision Restoration, Preventive Care End User: Ophthalmic Clinics, Eye Care Centers, Research Institutes, Diagnostic Laboratories |
| Companies Covered | Bayer AG, Novartis AG, Regeneron Pharmaceuticals, Roche Holding AG, Alimera Sciences, Allergan plc, Oxurion NV, Genentech, Kodiak Sciences Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Diabetic Retinopathy Market Shifts & Advancements
Diagnostic workflows are compressing from multi-visit specialist referrals toward single-encounter point-of-care decisions, enabled by hardware miniaturization and algorithmic accuracy gains that match human specialist performance.
Handheld fundus cameras are fragmenting the installed base of traditional tabletop systems by enabling non-mydriatic screening in primary care and endocrinology clinics. Family medicine practices across Germany and the United Kingdom are adopting these devices to capture 45-degree field images without pharmacologic dilation. The technology is fragmenting patient flow patterns by retaining screening volumes within generalist settings rather than routing through ophthalmology queues.
The EU AI Act's high-risk medical device classification imposes conformity assessment obligations on convolutional neural networks deployed for diagnostic decision support. Algorithm developers must maintain post-market surveillance repositories and explainability documentation for automated severity grading. European ophthalmology software vendors are responding by restructuring quality management systems to satisfy notified body audit requirements.
Pharmacy-based screening programs are emerging as an alternative channel to hospital outpatient departments, particularly in Japan's dense urban corridors. Retail health clinics equipped with automated fundus cameras capture images transmitted to centralized reading centers, unbundling the physical examination from specialist interpretation. This channel shift is most visible in Tokyo and Osaka prefectures where pharmacy chains compete on diabetes management service differentiation.
Global Diabetic Retinopathy Market Segmentation
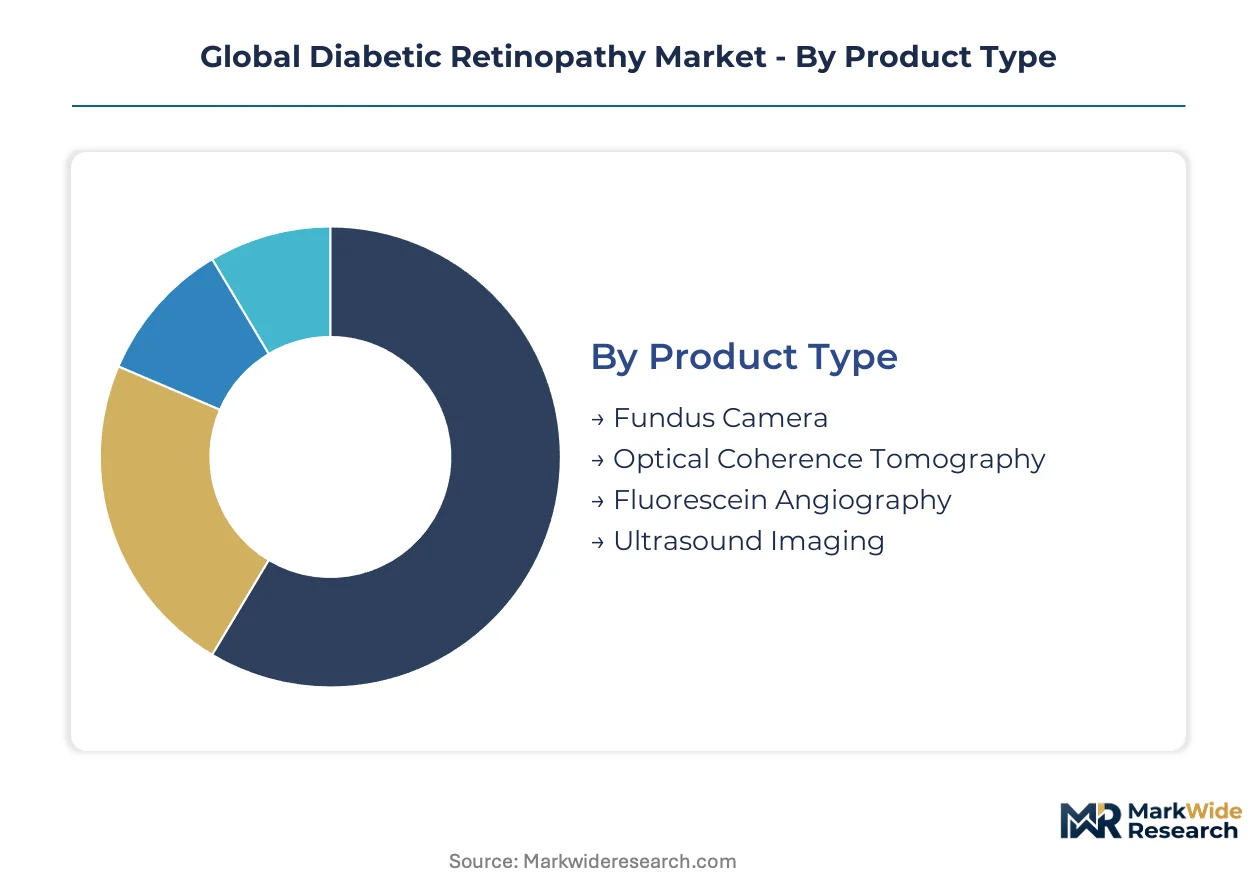
Segmentation in diabetic retinopathy markets reveals how diagnostic workflows fragment across care settings and technology interfaces. Product type and technology dimensions capture the core tension between hardware capital deployment and software-enabled automation reshaping screening economics.
Product Type:
Substitution pressure concentrates on imaging modalities where AI-augmented devices displace traditional equipment through comparable accuracy at lower operational cost.
- Fundus Camera:Non-mydriatic systems capture 45-degree retinal fields without pharmacologic dilation, enabling point-of-care deployment in primary care clinics across India and Brazil. Demand clusters in tier-2 cities where ophthalmologist density remains insufficient for referral-based screening.
- Optical Coherence Tomography:Spectral-domain platforms achieve 5-7 micron axial resolution for quantitative macular thickness mapping that guides anti-VEGF injection protocols. Japan's metropolitan hospital networks concentrate installed base due to reimbursement alignment with precision therapy scheduling.
- Fluorescein Angiography:Dye-based vascular imaging retains niche utility for neovascularization characterization in complex cases requiring dynamic perfusion assessment.
- Ultrasound Imaging:A-scan and B-scan modalities serve opaque media scenarios where optical techniques fail, particularly in advanced diabetic cataract cases.
Fundus cameras anchor the volume base while optical coherence tomography gains share at the steepest rate.
Technology:
Cost tier stratification separates capital-intensive surgical infrastructure from scalable software platforms with minimal marginal delivery cost.
- Telemedicine:Cloud-based image transmission architectures enable asynchronous specialist review from pharmacy clinics and rural health posts. Germany's statutory health insurance system reimburses remote screening consultations, accelerating channel adoption.
- Artificial Intelligence:Convolutional neural networks achieve diagnostic parity with fellowship-trained retina specialists in population screening settings. FDA 510(k) clearance requirements and EU AI Act conformity assessments create regulatory moats for validated algorithm developers.
- Laser Therapy:Photocoagulation systems address proliferative retinopathy through targeted thermal ablation of ischemic retina, retaining role in settings where pharmacologic therapy access remains constrained.
- Pharmacological Treatment:Intravitreal anti-VEGF injections dominate vision-threatening macular edema management through vascular permeability reduction protocols.
- Surgical Intervention:Vitrectomy platforms address tractional retinal detachment and vitreous hemorrhage complications requiring mechanical intervention.
Artificial intelligence platforms scale most rapidly across customer tiers while surgical intervention concentrates in tertiary referral centers with specialized anesthesia support.
Application:
Volume distribution across the care continuum reflects reimbursement incentives favoring intervention over prevention in most national health systems.
- Early Diagnosis:Asymptomatic screening programs target diabetic populations before visual acuity degradation, requiring workflow integration with endocrinology and primary care. Japan's compulsory employment health examination system incorporates retinal photography for working-age diabetic patients.
- Disease Monitoring:Serial imaging protocols track progression from non-proliferative to proliferative stages, with spectral-domain OCT interval scheduling driven by central subfield thickness trajectories.
- Vision Restoration:Therapeutic intervention applications address established visual impairment through pharmacologic or surgical modalities.
- Preventive Care:Glycemic control counseling and risk stratification programs operate at population health level with limited direct imaging content.
Disease monitoring generates the highest imaging frequency per patient while early diagnosis applications expand most quickly through screening automation.
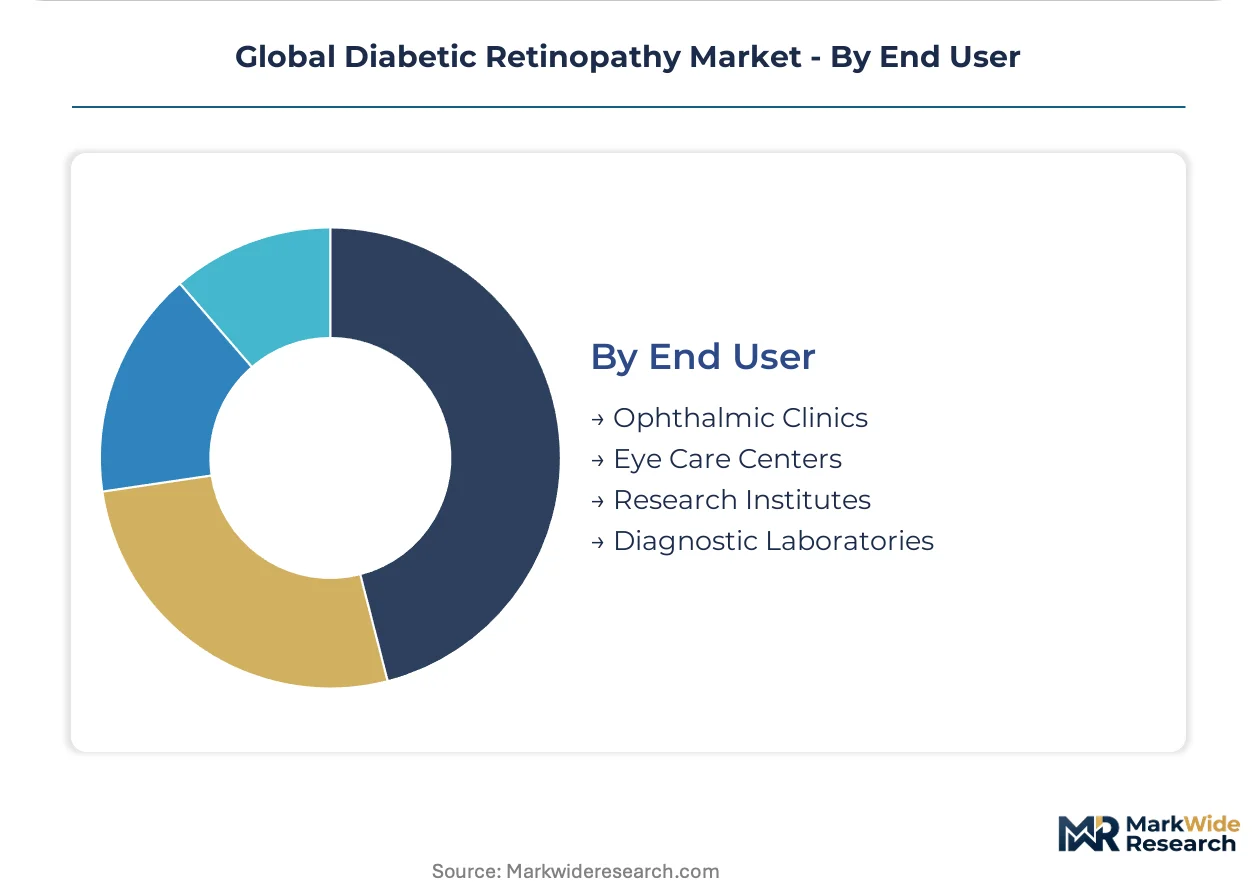
End User:
Customer type fragmentation accelerates as diagnostic capability migrates from specialist-controlled settings toward generalist and retail channels.
- Ophthalmic Clinics:Fellowship-trained retina specialists concentrate in urban Japan and Germany, performing advanced imaging interpretation and therapeutic intervention. These settings retain high-value procedural revenue but face screening volume leakage to automated alternatives.
- Eye Care Centers:Optometry-led facilities in the United Kingdom and Netherlands perform initial triage with delegated fundus photography, referring positive cases to medical retina services.
- Research Institutes:Academic medical centers conduct algorithm training and validation studies requiring annotated image repositories across disease severity grades.
- Diagnostic Laboratories:Centralized reading services aggregate images from distributed capture points, employing specialist interpreters for asynchronous report generation.
Ophthalmic clinics retain the highest revenue per encounter while eye care centers expand imaging volume most aggressively through workflow delegation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Screening infrastructure deployment diverges sharply across geographies: the United States and Japan concentrate spectral-domain OCT systems in metropolitan hospital networks, while India and Brazil rely on handheld fundus cameras in primary care settings where capital constraints dominate purchasing decisions.
United States
Medicare reimbursement expansion for AI-assisted screening in primary care clinics drives demand for automated diagnostic platforms. The FDA's 510(k) clearance pathway for convolutional neural network devices accelerates commercialization timelines for algorithm developers. Retinal imaging volumes concentrate in Medicare Advantage networks across Florida and Arizona where diabetic population density supports dedicated screening programs.
Japan
PMDA's Sakigake fast-track designation compresses regulatory review for AI-enabled devices from 24 months to under 12 months. Mandatory employment health examinations incorporate retinal photography for working-age diabetic patients, creating institutionalized screening demand. Tokyo and Osaka prefectures host pharmacy-based screening programs where retail chains compete on diabetes management service differentiation.
Germany
Statutory health insurance reimbursement for remote screening consultations accelerates telemedicine channel adoption. Fellowship-trained retina specialists cluster in metropolitan regions, creating rural access deserts that drive automated diagnostic demand. Bavaria and North Rhine-Westphalia anchor ophthalmic clinic networks performing advanced imaging interpretation and therapeutic intervention.
India
Tier-2 and tier-3 urban centers with rising diabetes incidence lack screening infrastructure, creating whitespace for mobile fundus camera units. The CDSCO regulates AI diagnostic software under medical device rules requiring clinical validation datasets. Maharashtra and Karnataka host expanding endocrinology clinics adopting non-mydriatic screening devices to capture 45-degree retinal fields without pharmacologic dilation.
Brazil
Cost barriers limit spectral-domain OCT penetration, preserving fundus camera dominance in public health screening programs. ANVISA's medical device registration requirements shape commercialization sequencing for foreign equipment manufacturers. São Paulo and Minas Gerais concentrate private ophthalmology practice networks where anti-VEGF therapy protocols drive precision imaging demand.
Global Diabetic Retinopathy Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with pharmaceutical conglomerates controlling therapeutic segments while diagnostic equipment vendors fragment across imaging modalities. The structure separates vascular endothelial growth factor franchise holders from AI software developers and hardware manufacturers. Two strategic archetypes dominate: integrated diagnostics-to-therapy platforms that streamline patient pathways, and focused algorithm developers seeking regulatory moats through multi-site clinical validation. Competitive moves concentrate on portfolio diversification into adjacent ophthalmology segments and strategic partnerships bridging hardware capture with cloud-based interpretation.
Among integrated pharmaceutical developers, Bayer AG anchors geographic reach through established distribution networks, while Novartis AG exemplifies the diagnostics-to-therapy platform archetype. Regeneron Pharmaceuticals occupies a position within the vascular endothelial growth factor therapeutic tier, sustaining dominance through injection protocol refinement. These three entities represent contrasting strategic postures: geographic breadth, vertical integration, and therapeutic focus respectively.
| Leading Market Players |
|---|
| Bayer AG |
| Novartis AG |
| Regeneron Pharmaceuticals |
| Roche Holding AG |
| Alimera Sciences |
| Allergan plc |
| Oxurion NV |
| Genentech |
| Kodiak Sciences Inc. |
| Others |
Supply & Pricing Matrix
FDA 510(k) clearance pathways and EU AI Act conformity assessments gate both supplier qualification and price differentiation simultaneously, as algorithm developers must absorb multi-site clinical validation costs that stratify market entry tiers. Hardware manufacturers face divergent capital requirements across spectral-domain OCT and handheld fundus camera segments, compressing margin structures in emerging markets while premium positioning endures in reimbursed settings.
Pricing Analysis
Long-term service contracts dominate AI diagnostic software revenue models, with subscription tiers scaling by patient volume throughput and algorithm update frequency. Three-tier pricing structure across premium, standard, and economy levels separates enterprise hospital networks from mid-sized ophthalmology groups and primary care pilot programs. Cost compression in handheld device segments is intensifying because Chinese and Indian manufacturers are scaling production of non-mydriatic cameras. Primary care clinics exhibit highest price sensitivity due to unfunded capital budgets, while metropolitan hospital networks accept premium positioning for OCT-guided injection protocols.
Supply Chain Analysis
Germany and Japan anchor precision optics manufacturing for spectral-domain OCT systems, while China and South Korea dominate CMOS sensor fabrication and handheld device assembly. Image sensor arrays, precision motion stages, and specialized optical coatings constitute critical input dependencies. Single-source vulnerability concentrates in high-resolution detector chips from Japanese suppliers subject to export licensing requirements. Distribution runs through ophthalmology equipment distributors with technical service capabilities, supplemented by direct-to-hospital contracting for large health system deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated hospital purchasing organizations and pharmacy chain procurement offices, fragmenting vendor pricing leverage as volume aggregates under fewer decision-makers.
For Market Incumbents: Secure regulatory moats through expanded FDA 510(k) submissions covering additional disease severity grades, while deepening backward integration into cloud-based image storage infrastructure. AI-native entrants threaten screening volume capture in primary care settings. Certification investment in EU AI Act conformity assessments represents the critical defensive lever. For New Entrants and Emerging Players: Differentiate on asynchronous telemedicine integration that unbundles image capture from specialist interpretation. India's tier-2 urban centers and Brazil's public health screening programs represent the most penetrable geographies. Pharmacy-based deployment partnerships offer the clearest go-to-market angle for hardware-light software platforms. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed AI diagnostic developers holding validated algorithms but limited commercial infrastructure. Long-term viability hinges on sustainable reimbursement pathways across Medicare, statutory health insurance, and private payer contracts. Algorithm developers with multi-regulatory clearance portfolios signal acquisition-ready maturity.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Regulatory Submission | Simultaneous FDA 510(k) and PMDA Sakigake filings compress commercialization timelines across the United States and Japan. |
| Cloud Platform Integration | Native DICOM interoperability with hospital PACS archives reduces deployment friction in German statutory health insurance networks. |
| Pharmacy Channel Partnership | Retail health clinic deployment in Tokyo and Osaka prefectures fragments traditional ophthalmology referral pathways. |
| Algorithm Training Expansion | Annotated image repository development across disease severity grades satisfies FDA validation dataset requirements for severity grading. |
| Reimbursement Strategy | Medicare CPT code expansion for AI-assisted primary care screening creates sustainable revenue models in United States markets. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with retina specialists, ophthalmology clinic administrators, and biomedical equipment procurement managers; and secondary validation against FDA 510(k) filings, PMDA approval databases, hospital procurement records, and GPO contract repositories. Bottom-up triangulation across equipment installation data and top-down reconciliation against pharmaceutical therapy volumes anchored market sizing.
Across the projection horizon, the analytical framework modeled segmentation by imaging modality, technology interface, care setting application, and end-user type. CAGRs derived from patient population growth, screening protocol penetration rates, and equipment replacement cycles. Anti-VEGF injection protocol expansion and AI diagnostic adoption curves served as primary demand-side forecast inputs.
Material uncertainties — regulatory timeline delays, reimbursement policy reversals, and algorithm performance degradation in real-world deployment — sit outside the modeled envelope. Forecasts reflect assumptions about sustained diabetes prevalence trajectories and stable medical device regulatory frameworks. Recalibration cycles align with material shifts in payer coverage determinations and breakthrough device designation awards.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Global Diabetes Pen Market
Diabetes Care
India Oral Anti-Diabetic Drug Market
Diabetes Care
Philippines Diabetes Drugs and Devices Market
Diabetes Care
Digital Diabetes Management Market
Diabetes Care
Type 2 Diabetes Market
Diabetes Care
Self-Monitoring Blood Glucose (SMBG) Market
Diabetes Care
Alternatives for Injectable Diabetes Care Market
Diabetes Care
Middle East and Africa Diabetes Pen Market
Diabetes Care
Insulin Resistance Market
Diabetes Care
North America Diabetes Care Devices Market
Diabetes Care
United Kingdom Blood Glucose Monitoring Market
Diabetes Care
Malaysia Insulin Infusion Pump Market
Diabetes Care
Wearable Glucometers Market
Diabetes Care
Russia Diabetes Care Devices Market
Diabetes Care
Mexico Oral Anti-Diabetic Drug Market
Diabetes Care
South Korea Oral Anti-Diabetic Drug Market