
 Global Uveitis Treatment Market | 2026-2036
Global Uveitis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Uveitis Treatment Market Foresight
Subscription-based outcomes monitoring and post-injection follow-up services is restructuring how uveitis care gets sold, shifting revenue from single-dose transactions to longitudinal patient management contracts. AbbVie Inc. leverages its immunology infrastructure to anchor biologic delivery networks across North American specialty hospitals. Novartis AG competes through sustained-release implant platforms that extend dosing intervals for posterior uveitis patients. Santen Pharmaceutical Co., Ltd. dominates Japanese ophthalmology clinics with localized corticosteroid formulations tailored to anterior segment disease patterns.
Uveitis treatment encompasses pharmacological interventions targeting intraocular inflammation, including corticosteroid suspensions with particle sizes below 10 microns for optimal trabecular meshwork penetration, immunosuppressive agents such as mycophenolate mofetil and cyclosporine, and biologic therapies engineered to neutralize tumor necrosis factor-alpha or interleukin pathways. The primary commercial purpose centers on preserving visual acuity by suppressing inflammatory cascades that damage the uveal tract, retina, and optic nerve while minimizing steroid-induced cataract and glaucoma complications. Biologic therapies command premium positioning due to refractory disease penetration and orphan drug economics, whereas corticosteroids retain volume leadership across anterior uveitis cases managed in ophthalmology clinics. Intravitreal injection delivery mode captures the fastest growth trajectory driven by sustained-release dexamethasone implants and anti-VEGF crossover applications in posterior disease.
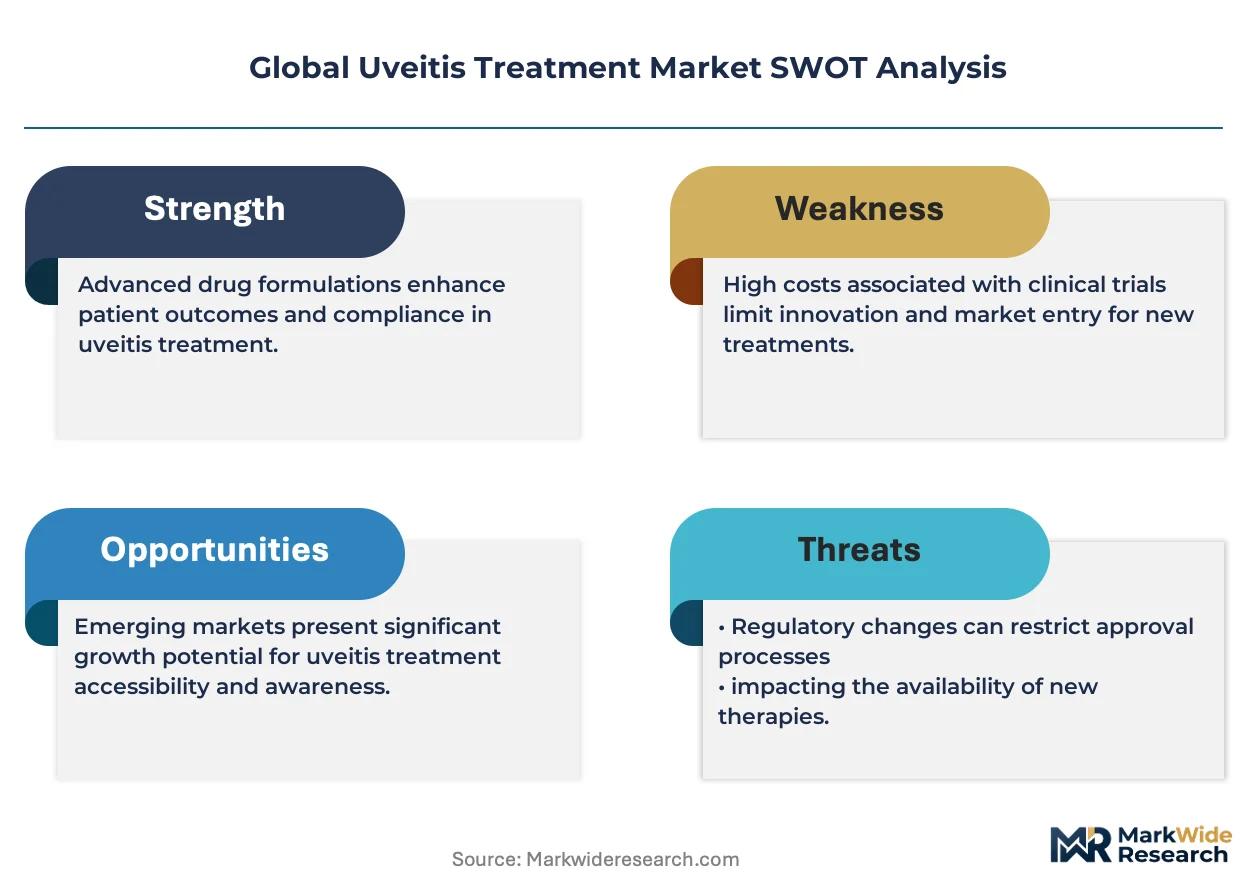
FDA orphan drug designations and EMA's priority medicines scheme accelerate biologic development timelines for non-infectious uveitis subtypes, while Japan's PMDA Sakigake pathway fast-tracks novel ocular delivery systems for domestic approval. These frameworks concentrate R&D investment toward sustained-release platforms and biosimilar entry strategies. Stakeholders must monitor how real-world evidence requirements from the FDA and EMA reshape post-market commitment burdens for long-acting intravitreal therapies.
Market Dynamics
Sustained-release intravitreal delivery platforms are compressing treatment intervals from monthly to quarterly or longer, forcing incumbent corticosteroid manufacturers to restructure around implantable depot formulations rather than conventional drops.
Growth Catalysts
- FDA Orphan Drug Designations:Accelerated review timelines for biologics targeting non-infectious posterior uveitis are pulling venture capital into rare disease ophthalmology pipelines. These designations reduce clinical trial burden and extend market exclusivity windows.
- Specialty Hospital Networks:Concentrated referral pathways in the United States and Japan are standardizing biologic administration protocols and creating predictable demand for long-acting therapies. This infrastructure supports premium pricing for refractory disease segments.
- IL-6 Pathway Inhibitors:Next-generation biologics targeting interleukin-6 receptors are expanding addressable populations beyond TNF-alpha refractory cases. These agents demonstrate superior steroid-sparing profiles in early-phase studies.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Corticosteroid raw material supply clusters in Indian and Chinese manufacturing hubs, exposing formulators to export restriction volatility and quality inspection backlogs.
- Intravitreal Administration Infrastructure:Limited availability of sterile compounding facilities and trained retina specialists in secondary markets constrains adoption of depot therapies outside major metropolitan clusters.
- Ocular Surface Substitutes:Topical cyclosporine and lifitegrast formulations for dry eye are capturing anterior segment inflammation cases that might otherwise progress to uveitis specialty care.
Strategic Opportunities
- German Outpatient Ophthalmology Chains:Underpenetrated ambulatory surgery centers in Bavaria and North Rhine-Westphalia lack sustained-release implant capabilities, creating first-mover advantage for platform licensors.
- EMA Priority Medicines Scheme:Accelerated assessment pathways for pediatric uveitis indications are opening development corridors for biologic sponsors willing to generate juvenile-specific safety databases.
- Tele-ophthalmology Monitoring Convergence:Remote anterior chamber cell grading via smartphone-mounted slit-lamp adapters is enabling rural patient retention in biologic regimens without monthly urban travel.
Industry Challenges
- Vitreoretinal Surgical Training Bottlenecks:Fellowship programs in the United States and Japan produce insufficient implant-trained specialists to match depot therapy expansion timelines.
- Multicenter Trial Harmonization:Divergent SUN classification criteria adoption across EU and Asian investigative sites complicates pooled efficacy analysis for global biologic submissions.
- Cold Chain Integrity at Last Mile:Temperature excursions during intravitreal kit transport to satellite clinics in Australia and Canada compromise biologic stability and trigger costly replacement protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Uveitis Treatment Market |
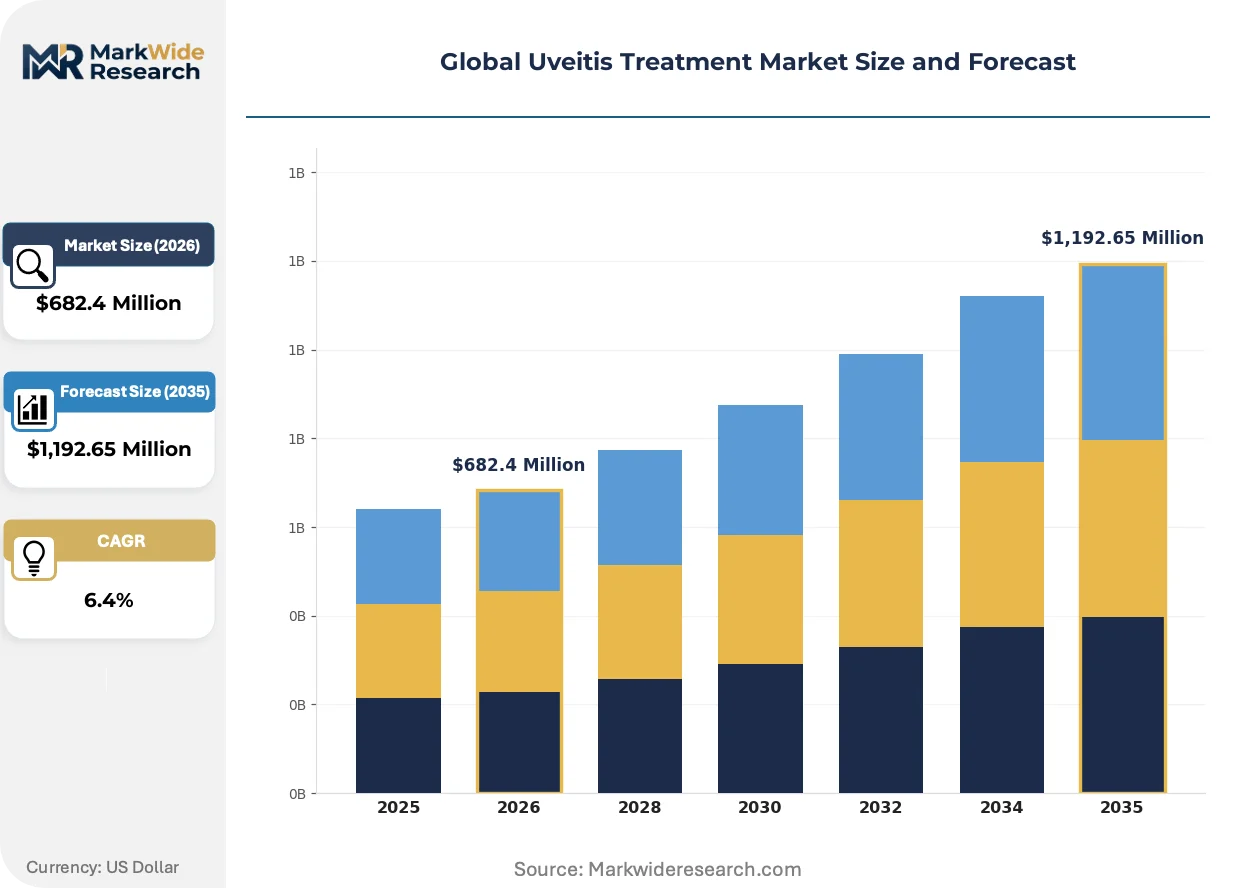
| Market Size in 2026 | $682.4 Million |
| Market Size in 2035 | $1,192.65 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunosuppressive Agents, Corticosteroids, Biologic Therapies, Antimetabolites, Tumor Necrosis Factor Inhibitors, Alkylating Agents Indication: Anterior Uveitis, Intermediate Uveitis, Posterior Uveitis, Panuveitis End User: Ophthalmology Clinics, Specialty Hospitals, Ambulatory Surgical Centers, Research Institutes Delivery Mode: Oral, Intravitreal Injection, Topical, Intravenous, Subcutaneous |
| Companies Covered | AbbVie Inc., Novartis AG, Bausch Health Companies Inc., EyePoint Pharmaceuticals, Inc., Santen Pharmaceutical Co., Ltd., Regeneron Pharmaceuticals Inc., Pfizer Inc., Clearside Biomedical Inc., Ocular Therapeutix, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Uveitis Treatment Market Shifts & Advancements
Biodegradable polymer matrices and port delivery systems are displacing permanent implants, enabling complete drug exhaustion without secondary surgical removal procedures. This material transition is compressing total cost-of-care calculations and reshaping physician preference.
Fluocinolone acetonide inserts in polyimide tube configurations are rewriting posterior segment treatment economics by eliminating the need for repeated intravitreal injections in chronic non-infectious uveitis. Retina specialists in United States academic medical centers are adopting these devices at rates exceeding prior depot technology launches. The technology is compressing practice overhead by reducing injection suite utilization and nursing labor allocation per patient-year.
Japan's PMDA Sakigake designation system is fast-tracking novel ocular delivery platforms through prioritized consultation and accelerated review timelines. Domestic sponsors gain conditional approval based on smaller Japanese trial cohorts before generating global datasets. This regulatory asymmetry is concentrating early-phase development investment in Tokyo-Osaka pharmaceutical clusters.
Subscription-based outcomes monitoring contracts are displacing per-injection reimbursement in German and United States specialty hospitals. Payers now demand visual acuity preservation guarantees over 24-month horizons, transferring outcome risk to provider networks. This shift is most visible in Medicare Advantage plans and statutory health insurance integrated care contracts.
Global Uveitis Treatment Market Segmentation
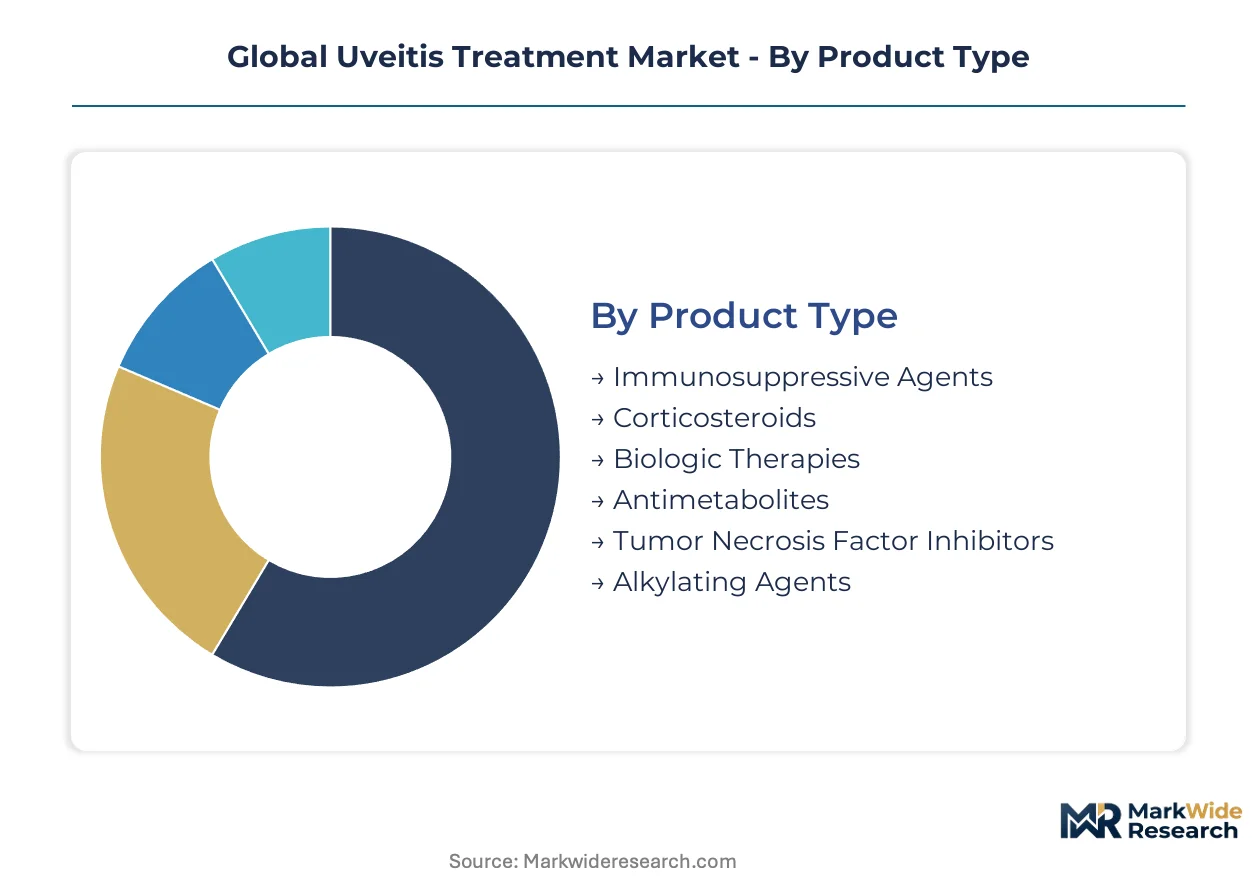
Uveitis treatment markets fragment sharply across pharmacological mechanisms and anatomical targets, with each segment demanding distinct manufacturing capabilities, regulatory pathways, and clinical infrastructure. Supply concentration in sustained-release platforms and biologic fermentation capacity creates divergent margin structures across categories.
Product Type:
Corticosteroid API supply clusters in Indian and Chinese manufacturing hubs, while biologic production concentrates in North American and European contract development organizations with mammalian cell culture expertise.
- Corticosteroids:Suspension formulations with particle sizes below 10 microns optimize trabecular meshwork penetration for anterior segment disease. Demand concentrates in ophthalmology clinics across the United States and Japan where first-line therapy protocols dominate, though steroid-induced cataract and glaucoma complications limit long-term use in chronic cases.
- Biologic Therapies:Engineered monoclonal antibodies neutralize tumor necrosis factor-alpha or interleukin pathways in refractory non-infectious disease. Specialty hospitals in Germany and the United States generate concentrated demand driven by FDA orphan drug economics and premium reimbursement for refractory posterior uveitis populations.
- Immunosuppressive Agents:Mycophenolate mofetil and cyclosporine formulations serve steroid-sparing protocols in bilateral chronic cases.
- Antimetabolites:Methotrexate and azathioprine address intermediate uveitis with systemic inflammatory associations.
- Tumor Necrosis Factor Inhibitors:Adalimumab and infliximab biosimilars are penetrating markets following originator patent expiries.
- Alkylating Agents:Cyclophosphamide reserves for severe sight-threatening panuveitis unresponsive to standard immunosuppression.
Today's leader: Corticosteroids. Tomorrow's challenger: Biologic Therapies.
Indication:
Anatomical classification by uveal tract involvement determines treatment intensity, with posterior and panuveitis cases requiring invasive delivery infrastructure that constrains addressable geography.
- Anterior Uveitis:Iris and ciliary body inflammation constitutes the highest-volume segment managed through topical drops and periocular injections. Community ophthalmology clinics in Japan and the United States handle the majority of cases, with corticosteroid suspensions capturing standard-of-care positioning.
- Posterior Uveitis:Retina and choroid involvement demands intravitreal or sustained-release depot therapies. Academic medical centers in Boston, Tokyo, and Heidelberg concentrate demand for fluocinolone acetonide implants and anti-VEGF crossover applications, with procedure volume limited by vitreoretinal specialist availability.
- Intermediate Uveitis:Pars planitis and vitritis variants require systemic immunosuppression or localized steroid delivery.
- Panuveitis:Diffuse inflammation involving all uveal layers presents the most complex management challenge with highest treatment costs.
Volume concentrates in anterior disease. Value concentrates in posterior and panuveitis.
End User:
Facility type determines reimbursement tier and therapy complexity, with specialty hospitals capturing biologic margins while clinics retain corticosteroid volume.
- Specialty Hospitals:Concentrated referral networks in the United States and Germany standardize biologic administration protocols and create predictable demand for long-acting therapies. These institutions command premium pricing for refractory disease segments through outcomes-based contracting with Medicare Advantage and statutory health insurers.
- Ophthalmology Clinics:Private practice and group settings manage anterior uveitis first-line therapy with topical and periocular corticosteroids. Japanese clinic networks under Santen's distribution infrastructure represent the most penetrated national market for localized corticosteroid formulations.
- Ambulatory Surgical Centers:Bavarian and North Rhine-Westphalian chains lack sustained-release implant capabilities, creating expansion opportunity for platform licensors.
- Research Institutes:Academic medical centers in Boston and Tokyo generate clinical trial demand for novel IL-6 pathway inhibitors.
Revenue per patient peaks in specialty hospitals. Patient throughput peaks in ophthalmology clinics.
Delivery Mode:
Route of administration separates chronic maintenance therapy from acute intervention, with invasive delivery modes requiring sterile infrastructure that fragments market geography.
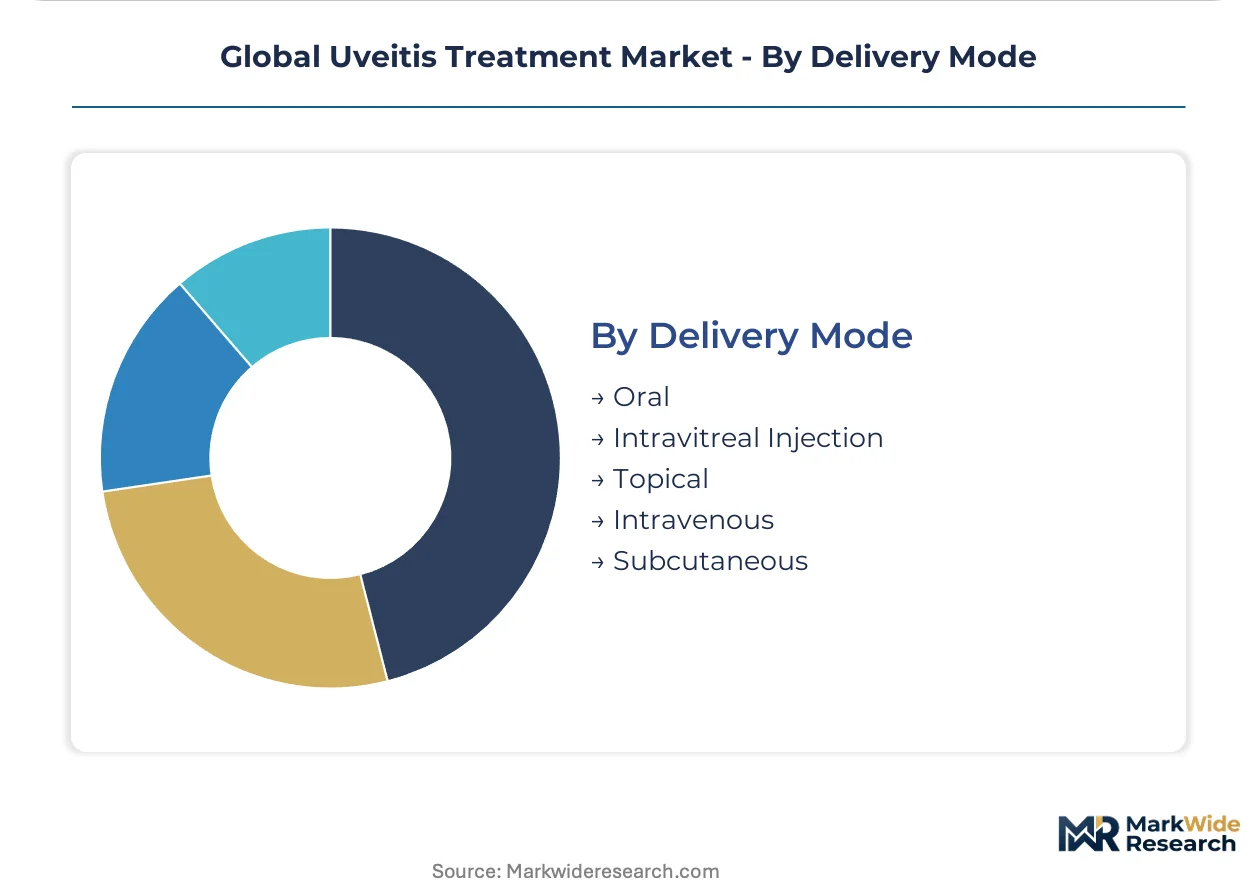
- Intravitreal Injection:Direct posterior segment access enables sustained-release dexamethasone implants and anti-VEGF applications. Retina specialists in United States academic centers are adopting biodegradable polymer matrices at rates exceeding prior depot technology launches, compressing practice overhead by reducing injection suite utilization.
- Oral:Systemic immunosuppression serves bilateral disease and cases with extraocular inflammatory associations.
- Topical:Eye drops and ointments retain volume leadership across anterior uveitis despite compliance challenges with frequent dosing regimens.
- Subcutaneous:Biologic self-administration protocols are expanding in Germany through integrated care contracts with outcomes monitoring.
- Intravenous:Hospital-based infusion for acute severe presentations and loading doses.
Injection frequency is compressing toward quarterly intervals. Oral and topical volumes face erosion from depot substitution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping where sustained-release ocular therapies undergo final formulation and sterile packaging. The FDA's orphan drug economics and Japan's PMDA Sakigake pathway create divergent cost-of-compliance profiles that concentrate biologic finishing in North American and Japanese facilities while corticosteroid API synthesis migrates toward Indian and Chinese chemical hubs.
United States
Academic medical centers in Boston and Philadelphia anchor demand for fluocinolone acetonide implants and IL-6 pathway inhibitors. Medicare Advantage plans are piloting 24-month visual acuity guarantee contracts that transfer outcome risk to specialty hospital networks. The FDA's accelerated approval pathways for rare disease biologics are compressing development timelines for non-infectious posterior uveitis candidates.
Germany
Statutory health insurance integrated care contracts are standardizing biologic administration protocols across Bavarian and North Rhine-Westphalian ophthalmology chains. The EMA's priority medicines scheme is accelerating pediatric uveitis indication assessments for sponsors generating juvenile-specific safety databases. Heidelberg and Berlin academic centers concentrate referral volume for refractory panuveitis cases requiring alkylating agent protocols.
Japan
Santen Pharmaceutical's distribution infrastructure dominates private ophthalmology clinics in Tokyo and Osaka with localized corticosteroid formulations. The PMDA Sakigake designation fast-tracks novel ocular delivery platforms through prioritized consultation, enabling conditional approval on smaller domestic trial cohorts. Domestic sponsors are concentrating early-phase development investment in the Tokyo-Osaka pharmaceutical corridor ahead of global dataset generation.
India
Corticosteroid API manufacturing clusters in Hyderabad and Mumbai supply suspension formulations with particle sizes below 10 microns to global formulators. CDSCO export inspections and quality certification backlogs are creating supply volatility that exposes Western formulators to raw material interruption risk. Domestic ophthalmology clinics in Delhi and Chennai manage anterior uveitis volume through topical and periocular corticosteroid protocols.
United Kingdom
NHS specialized commissioning frameworks are restricting biologic access to designated uveitis centers in London and Manchester, creating concentrated demand for adalimumab biosimilars. The MHRA's post-Brexit recognition pathways for EMA-approved ocular therapies are streamlining parallel import logistics. London academic centers are generating clinical trial demand for next-generation sustained-release polymer matrices.
Global Uveitis Treatment Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with immunology majors capturing biologic margins in specialty hospitals while regional formulators retain corticosteroid volume in ophthalmology clinics. The vendor base organizes into three strategic archetypes: diversified pharmaceutical conglomerates with immunology infrastructure, pure-play ophthalmology device-and-drug specialists, and contract development organizations with mammalian cell culture expertise. M&A activity concentrates on sustained-release platform acquisitions and biologic fermentation capacity expansion. Geographic licensing partnerships are accelerating market access for depot formulations in underpenetrated European ambulatory surgery centers.
Within the diversified pharmaceutical tier, AbbVie Inc. and Novartis AG exemplify contrasting strategic positions. AbbVie leverages North American immunology infrastructure to anchor biologic delivery networks across specialty hospital systems. Novartis occupies a position centered on sustained-release implant platforms that extend dosing intervals for posterior segment disease. Santen Pharmaceutical Co., Ltd. represents the regional specialist archetype, anchoring Japanese ophthalmology clinic distribution with localized anterior segment formulations.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Novartis AG |
| Bausch Health Companies Inc. |
| EyePoint Pharmaceuticals, Inc. |
| Santen Pharmaceutical Co., Ltd. |
| Regeneron Pharmaceuticals Inc. |
| Pfizer Inc. |
| Clearside Biomedical Inc. |
| Ocular Therapeutix, Inc. |
| Others |
Supply & Pricing Matrix
Vitreoretinal surgical specialists concentrated in Boston, Tokyo, and Heidelberg create labor-cost differentials that widen pricing spreads between academic medical centers and community ophthalmology clinics. Corticosteroid API manufacturing in Indian and Chinese chemical hubs feeds lower-cost anterior segment therapies, while biologic fermentation capacity in North American and European contract development organizations commands premium positioning for refractory posterior disease.
Pricing Analysis
Capacity additions in Indian and Chinese corticosteroid API manufacturing are reshaping price floors for anterior uveitis therapies, compressing margins on conventional suspension formulations. Three-tier pricing structure across premium, standard, and economy levels separates biologic therapies with orphan drug economics from sustained-release implants and generic corticosteroid drops. Price differentiation stems from FDA certification tier and sterile manufacturing complexity. Pricing pressure stems from biosimilar entry in TNF-inhibitor categories. Community ophthalmology clinics exhibit highest price sensitivity; academic specialty hospitals demonstrate lowest.
Supply Chain Analysis
FDA and EMA sterile manufacturing qualifications gate biologic finishing capacity, restricting depot therapy production to validated North American and European facilities. Corticosteroid API synthesis draws from Hyderabad and Mumbai chemical clusters, while biologic fermentation rests on mammalian cell culture expertise in Boston and Basel contract development organizations. Single-source vulnerability concentrates in Indian API export certification backlogs. Distribution runs through cold-chain logistics networks serving specialty hospital networks and ophthalmology clinic chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Demand is consolidating toward sustained-release platforms with demonstrated visual acuity preservation profiles over 24-month horizons.
For Market Incumbents: Anchor biologic delivery networks through exclusive specialty hospital partnerships in Boston and Heidelberg, locking out biosimilar entrants from high-volume referral pathways. Deepen upstream control over mammalian cell culture capacity to secure fermentation throughput for IL-6 pathway inhibitors. Defend against biodegradable polymer matrix substitutes by accelerating fluocinolone acetonide implant lifecycle extensions. For New Entrants and Emerging Players: Ambulatory surgical centers in Bavaria and North Rhine-Westphalia represent the most penetrable channel partner type for sustained-release platform licensing. Target German statutory health insurance integrated care contracts with tele-ophthalmology monitoring bundles that reduce patient travel burden. Pursue EMA priority medicines scheme acceleration for pediatric uveitis indications with juvenile-specific safety databases. For Investors and Strategic Acquirers: Diversified immunology majors are the most active acquirer in this space, seeking sustained-release platform technology to extend dosing interval advantages. Long-term viability centers on 5-10 year exclusivity windows for depot formulations with complete drug exhaustion profiles. Target acquisition archetype: contract development organizations with validated ocular sterile filling lines and PMDA Sakigake pathway experience. Watch for FDA real-world evidence requirement expansion as inflection indicator for post-market commitment burdens.| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Pathway | FDA accelerated review compresses development timelines for non-infectious posterior uveitis biologics. |
| Sustained-Release Platform Licensing | German ambulatory surgery center partnerships expand addressable geography for depot therapies. |
| Tele-Ophthalmology Monitoring Integration | Remote anterior chamber cell grading enables rural patient retention in biologic regimens. |
| Biosimilar Entry Strategy | Adalimumab and infliximab biosimilars penetrate NHS specialized commissioning frameworks in London. |
| Biodegradable Polymer Matrix Development | Complete drug exhaustion without secondary surgical removal compresses total cost-of-care calculations. |
Research Methodology
Multiple input streams — regulatory filing databases, hospital procurement records, and clinical trial registries — were reconciled with primary interviews across drug development executives, regulatory affairs leads, formulary directors, and vitreoretinal specialists. Secondary validation drew from FDA orphan drug designations, EMA priority medicines submissions, ClinicalTrials.gov protocols, and PMDA Sakigake approvals. Bottom-up patient-flow modeling and top-down pharmaceutical revenue triangulation anchored market sizing.
Data-stream reconciliation across treatment line, dosage form, administration route, and regional regulatory cluster dimensions shaped the analytical framework. CAGRs were derived from longitudinal patient volume projections and therapy switching patterns. Forecast inputs incorporated biologic penetration rates in refractory disease and sustained-release implant adoption curves in academic medical centers.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to biosimilar entry timing and real-world evidence requirement expansion. Forecasts reflect assumptions around sterile manufacturing capacity expansion and specialist training program throughput. A model refresh is warranted upon material change in FDA post-market commitment burdens for long-acting intravitreal therapies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Diabetic Retinopathy Treatment Market
Ophthalmology
United States Dry Eye Syndrome Market
Ophthalmology
Global Ophthalmic Viscoelastic Devices Market
Ophthalmology
Retinal Detachment Market
Ophthalmology
Keratitis Treatment Market
Ophthalmology
Global Diabetic Macular Edema Market
Ophthalmology
Ophthalmic Photocoagulator Market
Ophthalmology
India Ophthalmic Clinical Trials Market
Ophthalmology
Europe Ophthalmology Market
Ophthalmology
Optic Nerve Glioma Market
Ophthalmology
Ophthalmic Drugs and Devices Market
Ophthalmology
Blue Light Blocking Contact Lenses Market
Ophthalmology
Tobramycin Eye Drop Market
Ophthalmology
Macular Edema Treatment Market
Ophthalmology
Global Macular Degeneration Treatment Market
Ophthalmology
Ophthalmology Diagnostics Market