
 Ophthalmic Viscosurgical Devices Market | 2026-2036
Ophthalmic Viscosurgical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Ophthalmic Viscosurgical Devices Market Analysis
European sodium hyaluronate producers is restructuring supply chains to secure pharmaceutical-grade raw material streams amid tightening heparin-derivative sourcing constraints. Alcon leverages captive manufacturing of cohesive-dispersive viscoelastic formulations to sustain margin pools across premium surgical tiers. Johnson & Johnson Vision anchors its position through R&D intensity in pre-filled syringe delivery systems that reduce operating-room preparation time. Bausch + Lomb competes on geographic dominance in ambulatory surgical center channels across North American metropolitan markets.
Ophthalmic viscosurgical devices comprise sterile, viscoelastic formulations—principally sodium hyaluronate, chondroitin sulfate, or hydroxypropyl methylcellulose at concentrations of 1.0% to 3.0%—manufactured through aseptic fermentation and precision filtration processes to achieve defined molecular weights between 500,000 and 4,000,000 Daltons, with primary function to maintain anterior chamber depth, protect corneal endothelium, and manipulate tissue during intraocular microsurgery. Hyaluronic acid formulations dominate value capture due to superior cohesive properties and endothelial coating efficiency, while pre-filled syringe delivery modes represent the fastest-growing configuration as surgical workflows prioritize sterility assurance and dosing precision. The cataract surgery application segment occupies the deepest margin pool, though glaucoma surgery and vitrectomy applications are expanding as viscoelastic tamponade functions gain procedural acceptance.
The FDA's Class II 510(k) pathway governs device clearance for intraocular viscoelastic materials, while the EMA's Medical Device Regulation imposes strengthened biocompatibility and clinical follow-up requirements for European market access. ISO 15798 establishes international standards for ophthalmic viscosurgical device testing, with particular emphasis on endothelial cell protection metrics and viscosity retention under shear stress. Stakeholders must monitor evolving regulatory divergence between FDA streamlined review initiatives and EMA MDR implementation timelines, as this friction will determine which product configurations achieve multi-jurisdictional commercialization first.
Market Dynamics
The FDA's refinement of Class II 510(k) clearance pathways for intraocular materials is compressing product development timelines while elevating endothelial protection testing standards, forcing manufacturers to restructure clinical evidence packages before market entry.
Growth Catalysts
- Aging surgical demographics:The United States sustains premium viscoelastic consumption through high-volume cataract procedures performed on patients over 65 requiring anterior chamber maintenance.
- EMA MDR implementation:Strengthened biocompatibility requirements across European markets are accelerating adoption of pre-filled syringe configurations that reduce contamination risk during sterile field preparation.
- Sodium hyaluronate fermentation advances:Pharmaceutical-grade raw material streams from European producers now achieve molecular weight precision between 500,000 and 4,000,000 Daltons with tighter endothelial coating efficiency.
Market Restraints
- Heparin-derivative sourcing constraints:Tightening supply of pharmaceutical-grade precursors from traditional European extraction facilities is elevating input cost volatility for chondroitin sulfate formulations.
- EMA-FDA regulatory divergence:Misaligned clinical follow-up requirements between European Medical Device Regulation and FDA streamlined review initiatives are extending multi-jurisdictional commercialization timelines.
- Cohesive-dispersive formulation limitations:Current viscoelastic materials cannot simultaneously optimize anterior chamber depth maintenance and tissue manipulation across all intraocular microsurgery procedures.
Strategic Opportunities
- Glaucoma surgery expansion:Viscoelastic tamponade functions are gaining procedural acceptance beyond cataract applications, opening margin pools in trabeculectomy and minimally invasive glaucoma surgery.
- Ambulatory surgical center channel penetration:North American metropolitan markets show underpenetrated demand for pre-loaded delivery systems that reduce operating-room turnover time.
- ISO 15798 harmonization:International standardization of endothelial cell protection metrics is creating regulatory tailwinds for manufacturers with established shear-stress viscosity retention data.
Industry Challenges
- Aseptic fermentation talent scarcity:Precision filtration process expertise required for defined molecular weight achievement remains concentrated among limited specialist technician pools.
- 510(k) clinical evidence burden:FDA demands for endothelial protection validation are extending certification timelines and elevating documentation costs for novel viscoelastic formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ophthalmic Viscosurgical Devices Market |
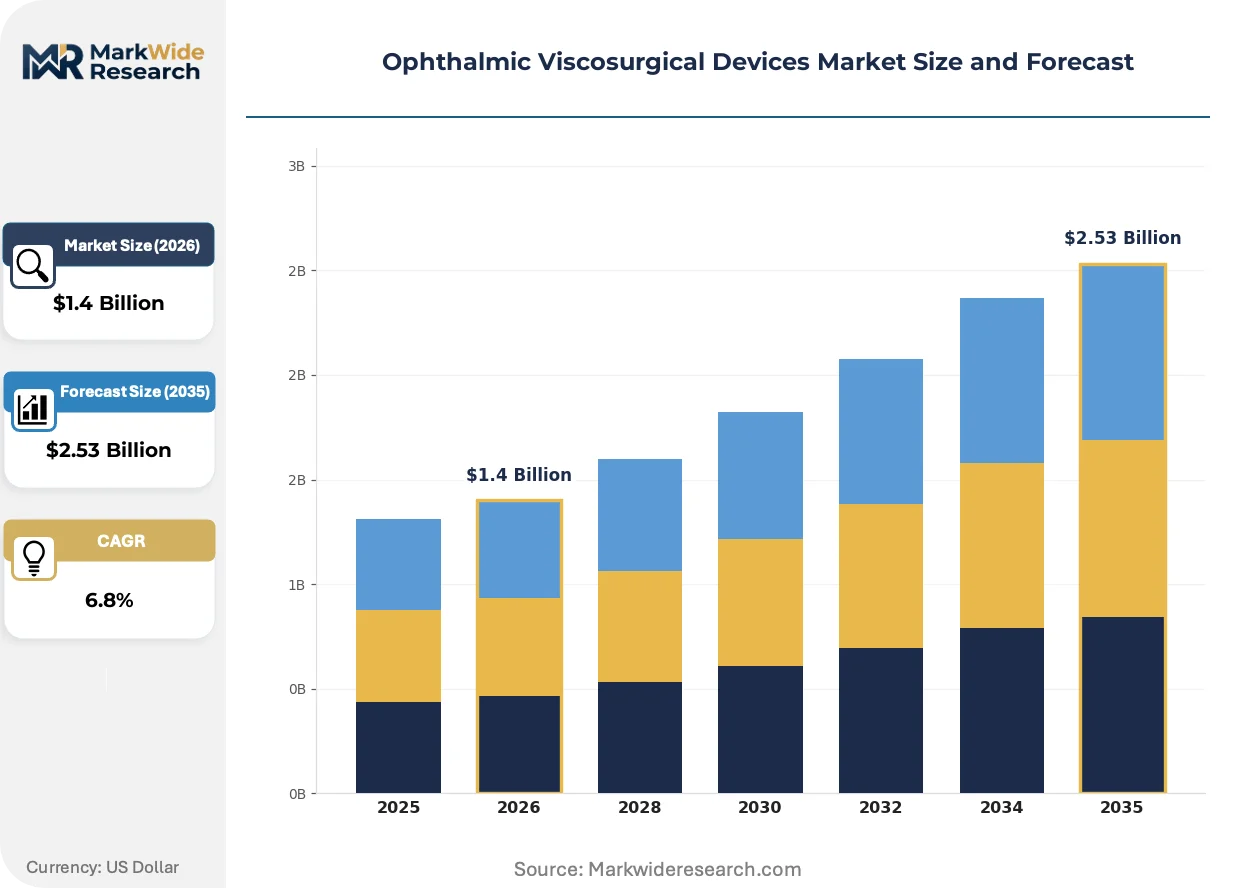
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hyaluronic Acid, Sodium Hyaluronate, Ocular Tamponade, Others End User: Hospitals, Eye Clinics, Ambulatory Surgical Centers, Research Labs Application: Cataract Surgery, Corneal Transplantation, Vitrectomy, Glaucoma Surgery Delivery Mode: Injectable, Pre-filled Syringes, Single-use Vials, Multi-dose Containers |
| Companies Covered | Carl Zeiss Meditec, Rayner Surgical, Alcon, Santen Pharmaceutical, Hoya Corporation, Johnson & Johnson Vision, Abbott Laboratories, Bohus Biotech, Bausch + Lomb, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ophthalmic Viscosurgical Devices Market Emerging Trajectories
Pre-filled syringe delivery configurations are displacing traditional vial-ampoule systems across surgical workflows, driven by sterility assurance priorities and operating-room efficiency mandates that reward reduced preparation protocols.
Dual-viscosity formulations combining cohesive and dispersive properties are absorbing market share from single-mechanism products as surgeons demand anterior chamber depth maintenance alongside tissue manipulation capability without device exchange. Academic medical centers in the United States are adopting these hybrid configurations fastest, with metropolitan surgical networks following within 18-24 month adoption cycles. The technology is absorbing R&D investment that previously flowed toward incremental molecular weight adjustments.
EMA Medical Device Regulation biocompatibility surveillance requirements are elevating post-market clinical follow-up obligations for intraocular viscoelastic materials across European markets. Manufacturers must now maintain patient outcome registries for extended periods, compressing margin structures for products lacking robust endothelial safety data. Premium-tier sodium hyaluronate formulations with established European clinical histories are capturing displaced volume from newer market entrants.
Surgical workflow unbundling is fragmenting traditional device-procurement relationships as ambulatory surgical centers negotiate direct supply agreements independent of hospital purchasing consortia. Independent ASC administrators in North American metropolitan markets now specify pre-filled syringe configurations with dosing precision features that reduce nursing staff preparation burden. This behavioral shift concentrates demand among logistics providers capable of just-in-time sterile field delivery.
Ophthalmic Viscosurgical Devices Market Segmentation
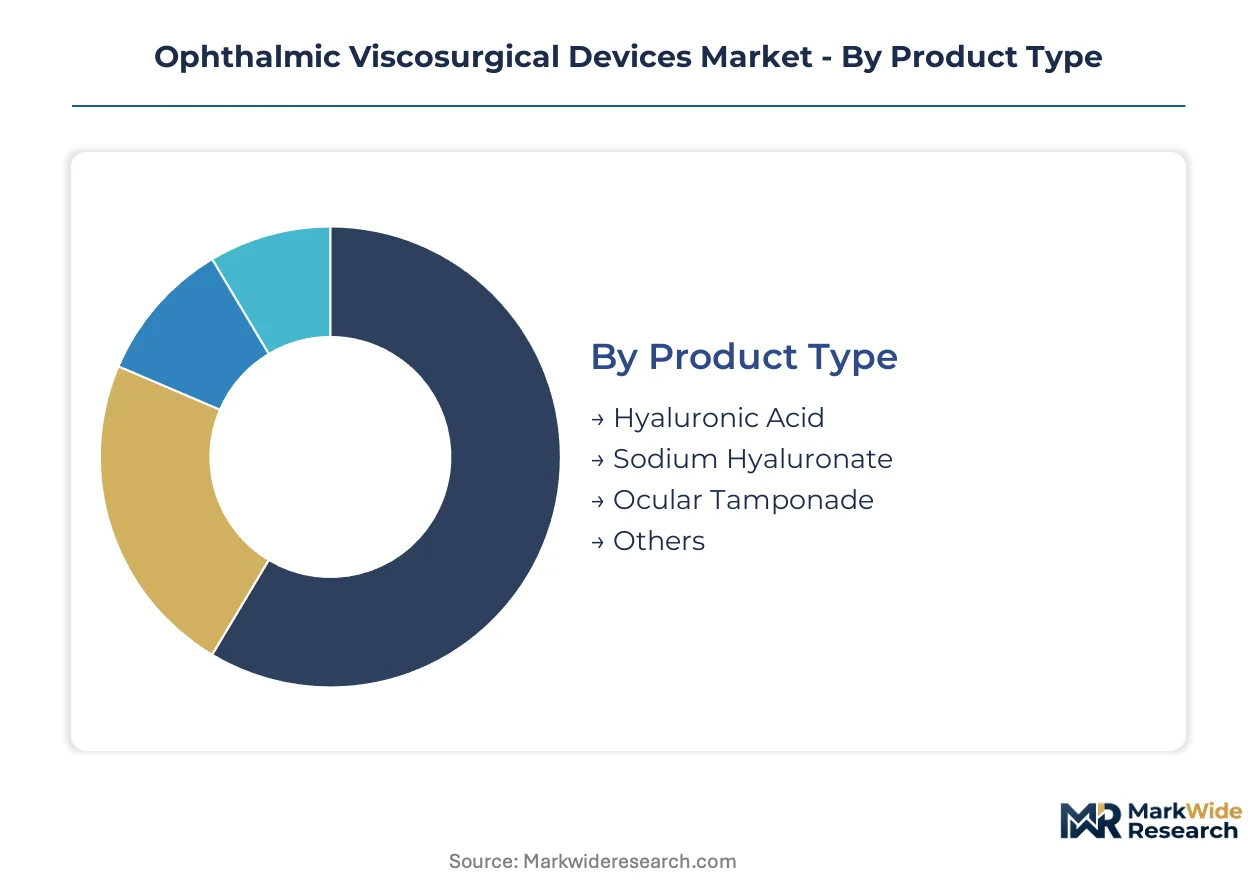
Ophthalmic viscosurgical devices segment across formulation chemistry, surgical setting, procedural application, and delivery configuration. Each axis shapes procurement decisions, regulatory pathways, and margin structures differently.
Product Type:
Formulation chemistry determines endothelial coating efficiency, molecular weight precision, and raw material sourcing requirements.
- Hyaluronic Acid:High-molecular-weight formulations between 500,000 and 4,000,000 Daltons deliver superior cohesive properties for anterior chamber maintenance. Demand concentrates in United States metropolitan surgical networks where premium-tier cataract procedures sustain pricing power.
- Sodium Hyaluronate:Pharmaceutical-grade fermentation outputs with defined viscosity retention under shear stress dominate European procurement flows. EMA MDR biocompatibility surveillance elevates entry barriers for newer molecular weight variants.
- Ocular Tamponade:Viscoelastic agents designed for retinal reattachment and intraocular tamponade functions.
- Others:Chondroitin sulfate and hydroxypropyl methylcellulose formulations at 1.0% to 3.0% concentrations.
Mature deployment sits with hyaluronic acid. Newer deployment is concentrated in ocular tamponade as vitrectomy volumes expand.
End User:
Surgical venue type dictates procurement scale, sterility protocols, and preparation workflow requirements.
- Hospitals:Academic medical centers and tertiary facilities manage high-complexity corneal transplantation and combined procedures requiring multiple viscoelastic formulations. United States hospital purchasing consortia negotiate volume-tiered supply agreements that compress margins for standard sodium hyaluronate configurations.
- Ambulatory Surgical Centers:Independent metropolitan ASC administrators specify pre-filled syringe delivery to reduce nursing staff burden and operating-room turnover. Direct procurement relationships outside hospital systems are fragmenting traditional distribution channels fastest here.
- Eye Clinics:Specialized ophthalmology practices with in-office surgical suites.
- Research Labs:Preclinical and clinical trial supply for novel formulation development.
Procurement consolidation is strongest in hospitals. Autonomous purchasing is expanding most quickly in ambulatory surgical centers.
Application:
Procedural indication determines functional requirements for tissue manipulation, endothelial protection, and chamber maintenance.
- Cataract Surgery:Phacoemulsification procedures require cohesive-dispersive balance for capsulorhexis and lens implantation. United States patients over 65 sustain the deepest volume concentration, with anterior chamber maintenance driving repeat viscoelastic dosing during single procedures.
- Glaucoma Surgery:Trabeculectomy and minimally invasive glaucoma surgery employ viscoelastic tamponade for bleb formation and filtration control. Procedural acceptance is climbing fastest as surgeons expand beyond cataract applications.
- Corneal Transplantation:Descemet's membrane endothelial keratoplasty and penetrating keratoplasty procedures.
- Vitrectomy:Posterior segment surgery requiring specialized tamponade agents.
Volume concentration remains with cataract surgery. Margin expansion is concentrating in glaucoma surgery as tamponade functions gain acceptance.
Delivery Mode:
Packaging configuration shapes sterility assurance, dosing precision, and preparation time in surgical workflows.
- Pre-filled Syringes:Sterile-field-ready configurations eliminate vial-ampoule transfer steps and reduce contamination risk. EMA MDR implementation across European markets is accelerating displacement of traditional systems as biocompatibility surveillance tightens.
- Injectable:Direct-to-tissue delivery systems for specialized intraocular microsurgery.
- Single-use Vials:Individual-dose packaging for lower-volume surgical settings.
- Multi-dose Containers:Cost-optimized configurations for high-throughput facilities with established aseptic handling protocols.
Workflow integration is deepest with injectable systems. Configuration transition is steepest in pre-filled syringes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical-grade sodium hyaluronate fermentation capacity concentrates in European and Asian manufacturing clusters. Surgical demand for viscoelastic materials distributes across aging populations in North America, Europe, and developed Asian economies. Regulatory divergence between FDA streamlined pathways and EMA MDR implementation is fragmenting product approval timelines across jurisdictions.
United States
Patients over 65 sustain high-volume cataract procedures requiring anterior chamber maintenance. FDA Class II 510(k) clearance pathways compress development timelines while elevating endothelial protection testing standards. Metropolitan surgical networks in New York, Los Angeles, and Chicago concentrate ambulatory surgical center demand for pre-filled syringe configurations.
Germany
Academic medical centers in Berlin and Munich drive adoption of dual-viscosity formulations for complex corneal transplantation. EMA Medical Device Regulation biocompatibility surveillance tightens post-market clinical follow-up obligations. The Baden-Württemberg industrial corridor anchors pharmaceutical-grade hyaluronic acid fermentation capacity serving European surgical networks.
Japan
PMDA oversight of intraocular materials maintains stringent endothelial cell protection validation requirements. Tokyo and Osaka metropolitan areas concentrate glaucoma surgery expansion where viscoelastic tamponade functions gain procedural acceptance. METI industrial policy supports precision fermentation technology development for defined molecular weight achievement.
India
CDSCO medical device registration pathways are streamlining for Class B and C intraocular materials amid surgical volume growth. Maharashtra and Gujarat host emerging ophthalmic device manufacturing clusters serving domestic and export markets. Tier-1 cities including Mumbai, Delhi, and Bangalore concentrate cataract surgical demand from aging urban populations.
Switzerland
Swissmedic maintains rigorous biocompatibility standards for intraocular viscoelastic materials that align with EMA MDR requirements. The Basel pharmaceutical cluster anchors specialized sodium hyaluronate raw material production for surgical applications. Zurich and Geneva academic medical centers participate in multi-center European clinical follow-up registries for endothelial safety validation.
Ophthalmic Viscosurgical Devices Market Vendor Landscape
Global majors compete with regional champions across formulation chemistry and delivery system innovation. Market structure shows consolidated leadership among diversified ophthalmic surgical device manufacturers alongside specialized viscoelastic material producers. Three archetypes dominate: integrated surgical platform providers, standalone viscoelastic specialists, and pharmaceutical-grade fermentation houses supplying raw materials. Capacity expansion in pre-filled syringe manufacturing and strategic partnerships for dual-viscosity formulation development represent the dominant competitive vectors.
Within the integrated surgical platform tier, Alcon and Johnson & Johnson Vision occupy positions spanning cohesive-dispersive formulation development through delivery system integration. Bausch + Lomb exemplifies geographic channel concentration, particularly across North American ambulatory surgical center networks. Carl Zeiss Meditec represents the precision optics-to-surgical workflow integration archetype, anchoring device-procurement relationships through combined visualization and viscoelastic platform offerings.
| Leading Market Players |
|---|
| Carl Zeiss Meditec |
| Rayner Surgical |
| Alcon |
| Santen Pharmaceutical |
| Hoya Corporation |
| Johnson & Johnson Vision |
| Abbott Laboratories |
| Bohus Biotech |
| Bausch + Lomb |
| Others |
Supply Flow & Price Mechanics
Pharmaceutical-grade sodium hyaluronate spot indices in European trading hubs cascade through three-tier pricing structures separating premium cohesive-dispersive formulations from standard single-mechanism products and economy-grade alternatives, with molecular weight certification tiers and endothelial protection testing outcomes determining contract premiums across hospital purchasing consortia and independent ambulatory surgical centers.
Pricing Analysis
Warranty and service bundling remains unbundled across most procurement relationships, with technical support and clinical training priced separately from viscoelastic material units. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 15798 endothelial cell protection certification grade and molecular weight precision, with FDA 510(k) clearance status commanding additional premiums in United States metropolitan surgical networks. Pricing pressure stems from EMA MDR compliance cost absorption as manufacturers maintain extended patient outcome registries. Independent ambulatory surgical centers exhibit highest price sensitivity due to direct procurement relationships outside volume-tiered hospital agreements, while academic medical centers prioritize performance metrics over unit economics.
Supply Chain Analysis
High-molecular-weight sodium hyaluronate supply rests on fermentation capacity concentrated in Germany, Switzerland, and Japan, with Baden-Württemberg and Basel pharmaceutical clusters anchoring European raw material output. Defined molecular weight achievement between 500,000 and 4,000,000 Daltons draws from aseptic fermentation expertise and precision filtration equipment, with pharmaceutical-grade chondroitin sulfate sourcing tethered to tightening heparin-derivative extraction from traditional European facilities. Single-source vulnerability concentrates in specialist technician pools capable of shear-stress viscosity retention validation. Distribution runs through diversified ophthalmic surgical device manufacturers with captive logistics networks serving hospital purchasing consortia and direct ambulatory surgical center agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from EMA MDR compliance cost burdens is forcing smaller viscoelastic material producers toward strategic exits or acquisition, compressing the vendor base toward integrated surgical platform providers with established European clinical histories.
For Market Incumbents: Deepen backward integration into pharmaceutical-grade sodium hyaluronate fermentation capacity to secure molecular weight precision and reduce exposure to European raw material volatility. Expand pre-filled syringe manufacturing footprints in North American metropolitan markets to capture ambulatory surgical center procurement fragmentation. Alcon and Johnson & Johnson Vision must defend against emerging standalone viscoelastic specialists by accelerating dual-viscosity formulation R&D intensity. For New Entrants and Emerging Players: Launch via direct distribution partnerships with independent ambulatory surgical center administrators in United States metropolitan markets, bypassing hospital purchasing consortia entirely. Target glaucoma surgery applications where viscoelastic tamponade functions remain underpenetrated relative to cataract procedures. Pursue ISO 15798 certification investment as the fastest pathway to credibility with academic medical center procurement committees. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap viscoelastic specialists with established EMA MDR compliance infrastructure in Germany and Switzerland. Long-term viability across the analysis window hinges on captive access to pharmaceutical-grade fermentation capacity and pre-filled syringe delivery system integration. Watch FDA 510(k) clearance timeline compression as the inflection signal for United States market entry acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EMA MDR biocompatibility surveillance elevates post-market registry requirements across European surgical networks. |
| Backward Integration into Fermentation | Captive sodium hyaluronate production secures molecular weight precision and reduces heparin-derivative sourcing exposure. |
| Pre-filled Syringe Manufacturing Scale-Up | Sterile-field-ready configurations capture ambulatory surgical center demand in New York and Los Angeles metropolitan markets. |
| Hospital System Partnership | Academic medical center alliances anchor dual-viscosity formulation adoption for complex corneal transplantation procedures. |
| Reimbursement Strategy | Cataract surgery coverage policies in United States Medicare frameworks sustain premium viscoelastic consumption volume. |
Methodological Framework
Independent corroboration across FDA 510(k) filing databases, EMA MDR submission records, and ISO 15798 certification registries underwrites the qualitative findings. Primary interviews with cataract surgeons, ambulatory surgical center administrators, hospital purchasing committee members, and ophthalmic device regulatory affairs specialists combined with secondary validation from hospital procurement databases, GPO contract disclosures, and customs trade data for pharmaceutical-grade sodium hyaluronate. Bottom-up surgical volume modeling and top-down manufacturer revenue triangulation anchored segmentation outputs.
Comparable-period anchoring to historical cataract procedure volumes and viscoelastic unit consumption patterns established the forecast framework across the projection horizon. Segmentation dimensions modeled include formulation chemistry, surgical venue type, procedural application, and delivery configuration, with molecular weight tier and endothelial protection certification grade as ophthalmic-specific stratifiers. CAGRs derived from surgical demographic trajectories and regulatory approval pathway timelines, incorporating EMA MDR implementation pace and FDA streamlined review initiative adoption as forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for dual-viscosity cohesive-dispersive formulations would alter the outlook if single-mechanism products retain procedural preference. Forecasts reflect assumptions around sodium hyaluronate fermentation capacity expansion and heparin-derivative supply stabilization. A small set of named triggers—EMA-FDA regulatory divergence acceleration, ambulatory surgical center procurement consolidation, and specialist technician pool scarcity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Lazy Eye Market
Ophthalmology
Ophthalmic Tonometers Market
Ophthalmology
Ophthalmic Devices Market
Ophthalmology
Europe Ophthalmology Drug and Device Market
Ophthalmology
Nystagmus Market
Ophthalmology
Uveal Melanoma Market
Ophthalmology
Anterior Uveitis Market
Ophthalmology
Non-Infectious Macular Edema Treatment Market
Ophthalmology
Laser Vision Correction Market
Ophthalmology
Global Retinal Detachment Treatment Market
Ophthalmology
Panuveitis Treatment Market
Ophthalmology
Pseudotumor Cerebri Market
Ophthalmology
Ophthalmology Diagnostics and Surgical Devices Market
Ophthalmology
Ophthalmic Lasers Therapeutic Market
Ophthalmology
Vernal Keratoconjunctivitis Treatment Market
Ophthalmology
Ophthalmology Devices Market