
 Retina Health Market | 2026-2036
Retina Health Market Size, Share, and Industry Trends Forecast 2026-2036
Retina Health Market Analytics
Aftermarket service revenue for diagnostic equipment is reconfiguring profit pools across the Retina Health Market. Carl Zeiss Meditec AG leverages its installed base of OCT systems to capture recurring service contracts. Regeneron Pharmaceuticals anchors its position through sustained R&D investment in anti-VEGF biologics. Novartis competes through gene therapy specialization in inherited retinal disease treatment.
Retina health encompasses the medical management of posterior segment ocular structures, including the macula, retinal pigment epithelium, and photoreceptor layers, where optical coherence tomography achieves axial resolutions below 10 micrometers for cross-sectional tissue visualization. Medications dominate current revenue, particularly intravitreal biologics for neovascular age-related macular degeneration, while gene therapy represents the fastest-expanding segment as regulatory pathways mature for single-administration interventions. Diagnostic equipment maintains stable replacement demand, though margin pools increasingly shift toward software-integrated platforms that enable longitudinal disease monitoring.
FDA, EMA, and the EU MDR collectively govern retinal device approvals, biologic licensing, and post-market surveillance, with the EU MDR's intensified clinical evidence requirements extending certification timelines for OCT and laser systems. The FDA's regenerative medicine advanced therapy designation accelerates gene therapy review, directly shaping pipeline prioritization among developers. Stakeholders must monitor reimbursement negotiations for gene therapies against anti-VEGF standards, as payor acceptance will determine whether premium pricing for one-time treatments displaces recurring injection models.
Market Dynamics
The Retina Health Market is experiencing a fundamental reconfiguration as one-time gene therapies threaten to displace recurring anti-VEGF injection models, forcing manufacturers to defend service revenue streams and restructure pricing architectures around durability rather than frequency.
Growth Catalysts
- Regenerative Medicine Advanced Therapy Designation:The FDA's accelerated review pathway compresses development timelines for inherited retinal disease treatments. Developers prioritize pipeline assets targeting Leber congenital amaurosis and retinitis pigmentosa.
- Japan's Super-Aged Society:METI reimbursement frameworks for OCT-guided monitoring expand diagnostic penetration among ophthalmology practices. Tokyo and Osaka medical districts drive per-capita imaging utilization rates.
- Artificial Intelligence Integration:Deep learning algorithms for automated drusen quantification and fluid segmentation reduce specialist interpretation burden. German university hospitals deploy these tools for population-scale screening programs.
Market Restraints
- EU MDR Clinical Evidence Requirements:Intensified post-market surveillance obligations extend recertification timelines for OCT and laser photocoagulation systems. Small device manufacturers face disproportionate compliance burdens.
- Single-Source Viral Vector Supply:Concentration of adeno-associated virus manufacturing in contract development organizations creates bottleneck risk for gene therapy commercialization. Yield variability affects batch release schedules.
- Anti-VEGF Biosimilar Price Compression:EMA-approved alternatives to reference biologics erode originator pricing power in European markets. German statutory health insurance funds mandate biosimilar prescribing quotas.
Strategic Opportunities
- Home-Based Monitoring Devices:Handheld microperimetry and smartphone-adaptable fundus cameras extend care access beyond clinic infrastructure. Rural prefectures in Japan pilot teleophthalmology reimbursement codes.
- Combination Gene-Editing Platforms:CRISPR-Cas9 convergence with AAV delivery vectors enables corrective interventions for dominant retinal disorders previously deemed untreatable. Academic medical centers in the United States establish dedicated manufacturing suites.
- Real-World Evidence Infrastructure:Longitudinal imaging registries support conditional reimbursement negotiations for novel therapies. NHS England pilots outcomes-based agreements leveraging hospital electronic health record integration.
Industry Challenges
- Vitreoretinal Surgical Subspecialist Scarcity:Fellowship training program capacity constraints limit gene therapy administration expertise. United States academic centers compete for qualified surgical talent.
- Cleanroom Manufacturing Scale-Up:Viral vector production facilities require capital-intensive containment infrastructure. Developers face facility qualification timelines extending commercialization schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retina Health Market |
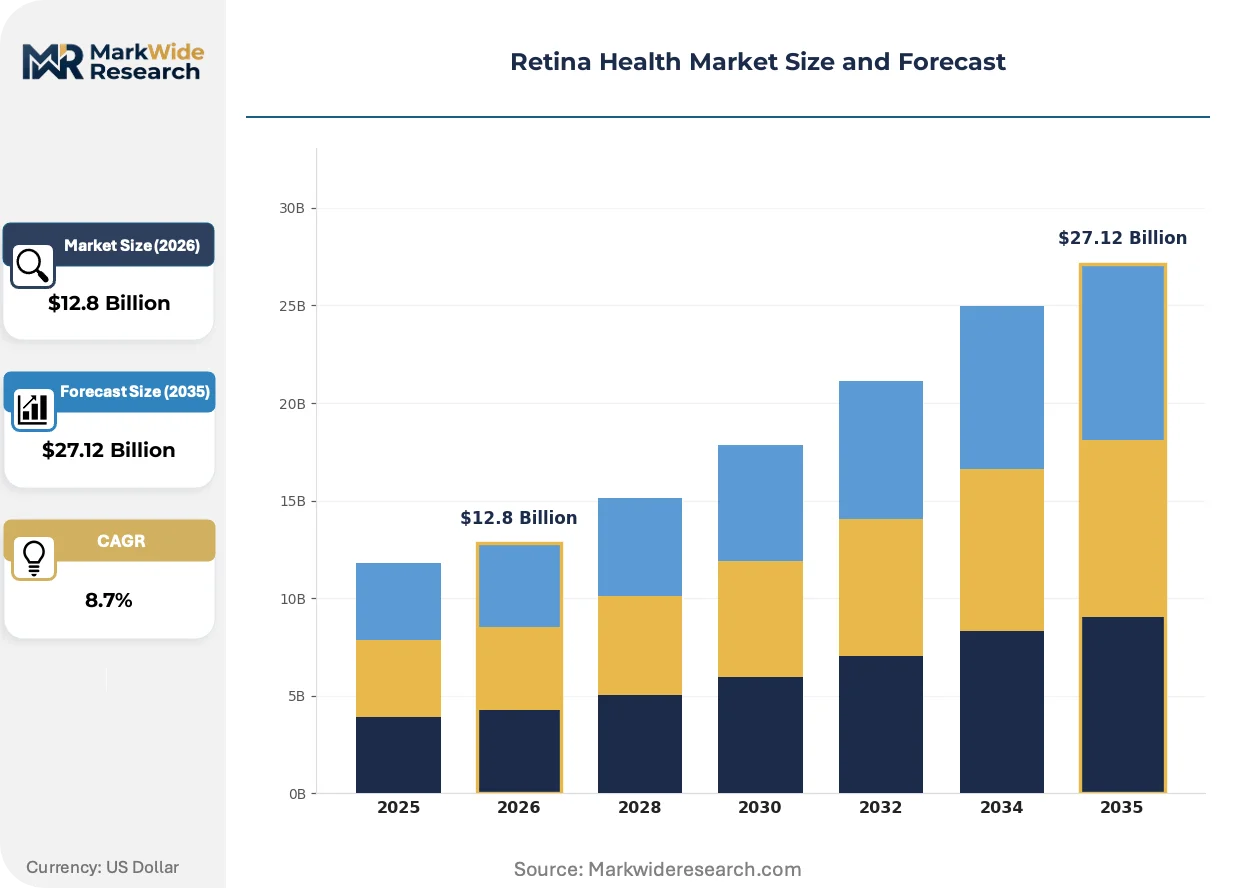
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $27.12 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Implants, Medications, Devices, Diagnostic Equipment Application: Retinal Detachment, Diabetic Retinopathy, Macular Degeneration, Inherited Retinal Disorders End User: Hospitals, Clinics, Research Labs, Ophthalmology Practices Technology: Laser Therapy, Gene Therapy, Surgical Procedures, OCT Imaging |
| Companies Covered | Regeneron Pharmaceuticals, Novartis, Bayer AG, Alcon, Carl Zeiss Meditec AG, Roche Holding AG, Bausch + Lomb, Topcon Corporation, IRIDEX Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retina Health Market Evolving Landscape
Technological convergence between imaging, genetic intervention, and digital health infrastructure is collapsing traditional boundaries between diagnosis and therapy in retinal care delivery models.
Swept-source OCT technology achieves imaging speeds exceeding 100,000 A-scans per second while penetrating through media opacities that previously obscured pathology. Academic medical centers in Germany and Japan deploy these systems for ultra-widefield angiography without dye injection. The technology is collapsing the distinction between structural assessment and functional prediction, enabling treatment decisions before visual acuity loss manifests.
The EU MDR's intensified clinical evidence requirements for Class III devices extend certification timelines for novel laser and imaging platforms. Manufacturers must generate post-market clinical follow-up data that previously sufficed with literature reviews. Retinal diagnostic equipment segments face compressed margins as small developers exit rather than absorb compliance costs, consolidating vendor landscapes in France and Italy.
Hospital procurement departments increasingly unbundle equipment acquisition from multi-year service contracts, demanding à la carte maintenance pricing transparency. German university hospital networks lead this shift, negotiating software upgrade rights separately from hardware warranty extensions. This behavioral change pressures device manufacturers to defend recurring revenue through predictive analytics subscriptions rather than captive service agreements.
Retina Health Market Segmentation
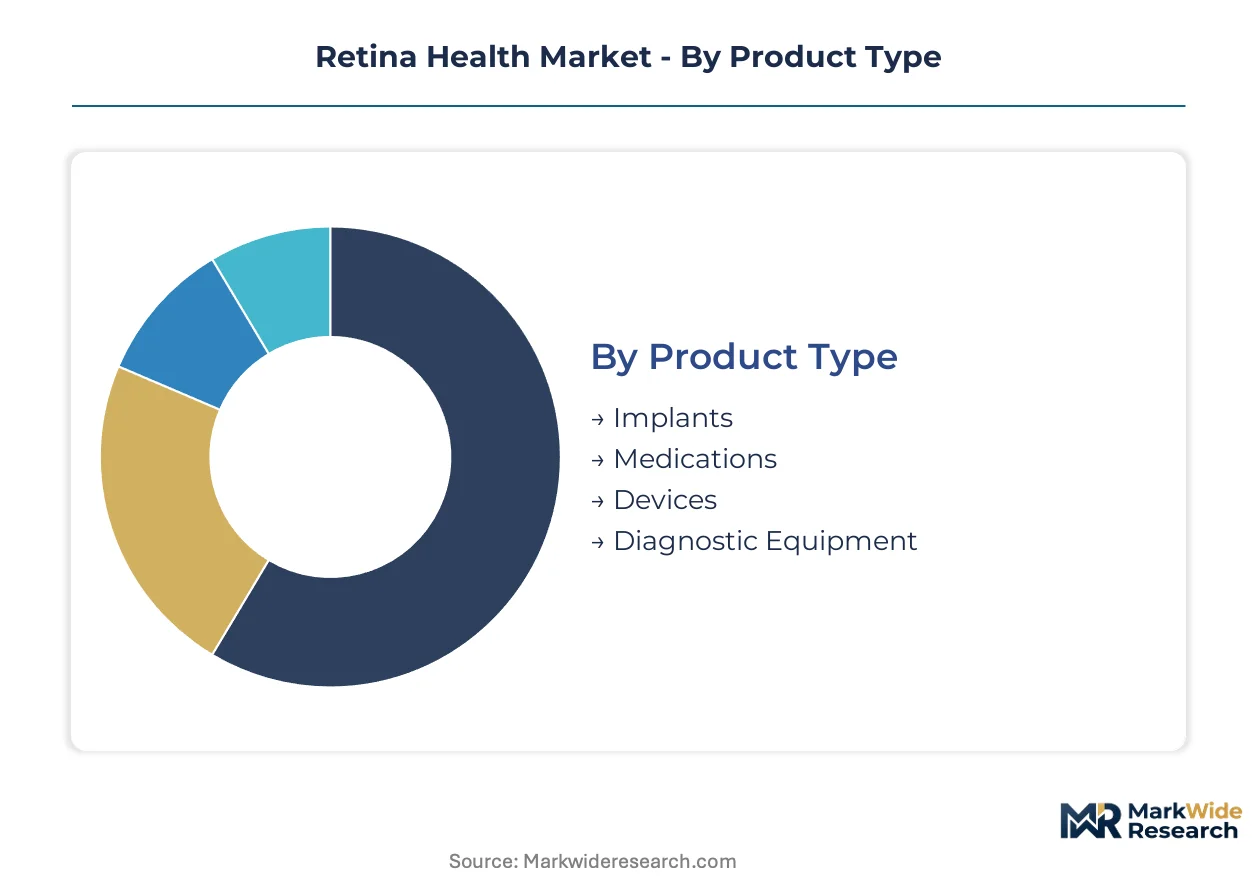
Retina health market segmentation reveals divergent investment cycles across therapeutic modalities. Replacement frequencies for capital equipment stretch across decades while biologic injection schedules compress revenue recognition into quarterly intervals. Understanding these temporal patterns enables resource allocation across development pipelines and commercial infrastructure.
Product Type:
Medications turn inventory fastest through monthly injection cycles, while implants and capital equipment lock capital into multi-year amortization schedules.
- Medications:Intravitreal biologics targeting vascular endothelial growth factor pathways require refrigerated supply chains and frequent administration. German statutory health insurance funds negotiate volume-based rebates for ranibizumab and aflibercept, compressing per-dose margins while expanding addressable patient populations.
- Diagnostic Equipment:Optical coherence tomography systems achieve axial resolutions below 10 micrometers for cross-sectional retinal visualization. Japan's METI reimbursement frameworks for OCT-guided monitoring expand diagnostic penetration among Tokyo and Osaka ophthalmology practices, driving per-capita imaging utilization.
- Implants:Sustained-release drug delivery devices reduce injection burden through biodegradable polymer matrices.
- Devices:Surgical instrumentation for vitreoretinal procedures includes microforceps, illuminators, and laser probes.
Medications dominate installed base. Diagnostic Equipment is where expansion concentrates.
Application:
Commercial maturity varies sharply across disease indications, with age-related conditions offering scale and inherited disorders promising pricing power.
- Macular Degeneration:Neovascular age-related macular degeneration generates the largest addressable population among retinal diseases. Anti-VEGF biologics from Regeneron Pharmaceuticals and Novartis anchor treatment protocols, though biosimilar erosion in European markets pressures originator pricing.
- Inherited Retinal Disorders:Leber congenital amaurosis and retinitis pigmentosa represent gene therapy's primary addressable population. FDA regenerative medicine advanced therapy designation accelerates review timelines, enabling single-administration interventions that threaten recurring injection models.
- Diabetic Retinopathy:Metabolic disease progression drives screening demand across primary care integration.
- Retinal Detachment:Acute surgical intervention requires immediate vitreoretinal specialist availability.
Macular Degeneration commands volume leadership. Inherited Retinal Disorders show the steepest expansion trajectory.
End User:
Procurement sophistication stratifies sharply, with hospital networks extracting service unbundling that smaller practices accept as packaged offerings.
- Hospitals:Academic medical centers concentrate gene therapy administration expertise and advanced surgical volume. German university hospital networks lead equipment procurement unbundling, negotiating software upgrade rights separately from hardware warranty extensions.
- Ophthalmology Practices:Private clinics drive OCT system installed base expansion through METI reimbursement frameworks in Japan's super-aged society. Rural prefectures pilot teleophthalmology reimbursement codes extending care access beyond urban infrastructure.
- Clinics:Ambulatory surgical centers optimize throughput for high-volume intravitreal injection procedures.
- Research Labs:Academic institutions host longitudinal imaging registries supporting conditional reimbursement negotiations.
Hospitals anchor complex intervention revenue. Ophthalmology Practices capture diagnostic volume growth.
Technology:
Development timelines stretch from decades-old laser platforms to emerging gene editing, with regulatory maturity determining commercial readiness.
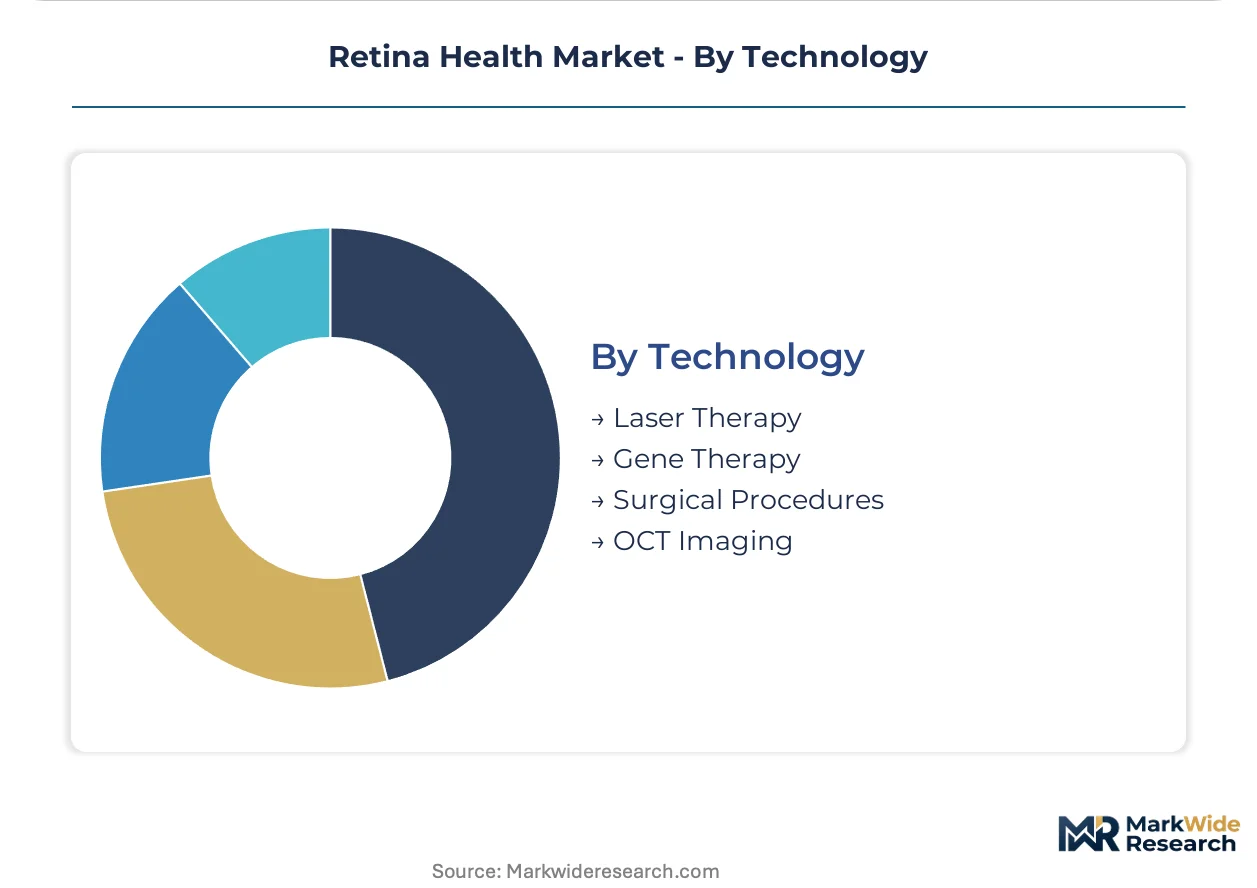
- Gene Therapy:Adeno-associated virus delivery vectors enable corrective interventions for previously untreatable dominant retinal disorders. Single-source viral vector manufacturing concentration in contract development organizations creates bottleneck risk affecting batch release schedules.
- OCT Imaging:Swept-source technology achieves imaging speeds exceeding 100,000 A-scans per second while penetrating media opacities. German and Japanese academic medical centers deploy these systems for ultra-widefield angiography without dye injection.
- Laser Therapy:Photocoagulation systems face EU MDR intensified clinical evidence requirements extending recertification timelines.
- Surgical Procedures:Vitreoretinal techniques require fellowship-trained subspecialist expertise concentrated in United States academic centers.
OCT Imaging dominates installed base. Gene Therapy is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity for retinal interventions varies sharply across geographies. German statutory health insurance funds extract volume-based rebates for anti-VEGF biologics, while Japanese METI frameworks sustain premium reimbursement for OCT-guided monitoring. United States commercial payers occupy the middle ground, negotiating outcomes-based agreements for gene therapies.
United States
Academic medical centers concentrate gene therapy administration expertise and vitreoretinal surgical volume. FDA regenerative medicine advanced therapy designation accelerates review timelines for inherited retinal disease treatments. Boston and Philadelphia medical districts anchor clinical trial infrastructure for Leber congenital amaurosis interventions.
Germany
Statutory health insurance funds mandate biosimilar prescribing quotas for anti-VEGF agents, compressing originator pricing. EU MDR intensified clinical evidence requirements extend recertification timelines for OCT and laser systems. Heidelberg and Munich university hospital networks lead equipment procurement unbundling, negotiating software upgrade rights separately from hardware warranties.
Japan
METI reimbursement frameworks for OCT-guided monitoring expand diagnostic penetration among ophthalmology practices. Tokyo and Osaka medical districts drive per-capita imaging utilization rates in the super-aged society. Rural prefectures pilot teleophthalmology reimbursement codes extending care access beyond urban infrastructure.
Switzerland
Swissmedic maintains streamlined pathways for breakthrough retinal therapies, attracting gene therapy developers seeking early market access. Premium pricing acceptance for single-administration interventions exceeds European averages. Basel and Zurich clusters concentrate pharmaceutical R&D investment in inherited retinal disorder pipelines.
Retina Health Market Competitive Landscape
Capability concentration sits with gene therapy developers possessing viral vector manufacturing expertise; scale advantage sits with established ophthalmic pharmaceutical houses commanding anti-VEGF installed bases. The market structures around three archetypes: biologic originators defending injection franchises, gene therapy specialists pursuing one-time intervention models, and diagnostic equipment vendors capturing recurring service contracts. Dominant competitive moves include strategic partnerships bridging manufacturing gaps and portfolio diversification into sustained-release delivery formats.
Within the biologic originator tier, Regeneron Pharmaceuticals and Novartis exemplify scale-driven positioning anchored by anti-VEGF market presence. Among precision diagnostic specialists, Carl Zeiss Meditec AG occupies a position leveraging installed base density for recurring service revenue capture. These three entities represent contrasting strategic postures: pharmaceutical scale defense, therapeutic modality transition, and equipment-services integration.
| Leading Market Players |
|---|
| Regeneron Pharmaceuticals |
| Novartis |
| Bayer AG |
| Alcon |
| Carl Zeiss Meditec AG |
| Roche Holding AG |
| Bausch + Lomb |
| Topcon Corporation |
| IRIDEX Corporation |
| Others |
Value Network & Pricing Analysis
Undercapacity in viral vector manufacturing facilities across North America and Europe simultaneously constrains gene therapy commercialization and inflates per-dose pricing premiums, compelling developers to secure captive production capacity while diagnostic equipment vendors exploit service contract bundling to offset hardware margin compression.
Pricing Analysis
Aftermarket service revenue tiers including predictive maintenance subscriptions and software upgrade rights now drive lifetime value capture for OCT system vendors. Three-tier pricing structure across premium, standard, and economy levels segments buyers by procedure volume and integration complexity. Cost compression in anti-VEGF biologics stems from EMA-mandated biosimilar quotas in Germany. Hospital procurement departments exhibit highest price sensitivity through unbundled negotiation tactics, while academic medical centers accept premium positioning for gene therapy administration capabilities.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk assessment for optical component sourcing. Manufacturing concentrates in Germany, Japan, and the United States for precision imaging systems. Active pharmaceutical ingredient production for intravitreal biologics draws from Switzerland, Ireland, and Singapore. Single-source vulnerability pervades adeno-associated virus vector production concentrated in contract development organizations. Distribution runs through specialized ophthalmology distributors and direct hospital system contracts for capital equipment.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from predictive analytics subscriptions and remote monitoring platforms is expanding faster than hardware replacement cycles, reconfiguring vendor economics toward recurring-revenue models.
For Market Incumbents: Harden installed base retention through predictive maintenance algorithms that reduce device downtime below competing service offerings. Secure backward integration into viral vector manufacturing to defend gene therapy margins against contract development organization bottlenecks. Deepen software companion development for longitudinal disease monitoring to lock in multi-year subscription renewals.
For New Entrants and Emerging Players: Establish a beachhead in home-based monitoring devices where regulatory pathways remain unsettled and reimbursement codes are piloting in Japan's rural prefectures. Target ophthalmology practices in secondary German cities where equipment procurement unbundling has not yet penetrated. Deploy teleophthalmology platforms with integrated AI diagnostic support as the primary go-to-market angle.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among diagnostic equipment vendors with dense installed bases and multi-year service contract penetration. Long-term viability across the analysis window favors entities controlling both therapeutic modality and monitoring infrastructure. Acquisition target archetype combines gene therapy pipeline assets with captive viral vector manufacturing capacity. Watch FDA regenerative medicine advanced therapy designation velocity as the signal for pipeline prioritization shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy | Outcomes-based agreements with CMS and German statutory funds determine gene therapy commercialization feasibility. |
| Manufacturing Scale-Up | Cleanroom facility qualification timelines directly compress commercialization schedules for AAV-based interventions. |
| Software Companion Development | AI-integrated OCT platforms enable longitudinal monitoring that supports conditional therapy reimbursement negotiations. |
| Hospital System Partnership | Academic medical center alliances concentrate gene therapy administration expertise and surgical volume capture. |
| Regulatory Approval Pathway | EU MDR clinical evidence requirements extend recertification timelines for novel laser and imaging platforms. |
Research Methodology
Initial hypotheses were tested against primary input from vitreoretinal surgeons, hospital procurement managers, regulatory affairs specialists, and gene therapy development executives and refined through secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up patient population estimates and top-down manufacturer revenue analysis were triangulated to converge on segment sizing.
Demand-supply balance dynamics across the projection horizon anchored the analytical framework, with segmentation modeled across therapeutic modality, disease indication, end-user procurement sophistication, and regional regulatory cluster. CAGRs were derived from fitted growth curves incorporating anti-VEGF injection frequency trends and gene therapy administration capacity buildout rates.
Sensitivities concentrate around FDA regenerative medicine advanced therapy designation velocity, EU MDR recertification timeline extensions, and viral vector manufacturing yield variability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Corneal Pachymetry Market
Ophthalmology
Global Posterior Segment Eye Disorders Market
Ophthalmology
Global Retinal Vein Occlusion Market
Ophthalmology
Global Photochromic Lenses Market
Ophthalmology
Ophthalmic Loupes Market
Ophthalmology
Global Tonometer Market
Ophthalmology
Vernal Keratoconjunctivitis Market
Ophthalmology
Ophthalmic Ultrasound Systems Market
Ophthalmology
Ptosis Treatment Market
Ophthalmology
Keratitis Treatment Market
Ophthalmology
Herpes Simplex Keratitis Treatment Market
Ophthalmology
Personalized LASIK Surgery Market
Ophthalmology
Head Band Ophthalmoscopes Market
Ophthalmology
Global Aphakia Market
Ophthalmology
South Africa Ophthalmic Devices Market
Ophthalmology
Global Ophthalmology Market