
 Meibomian Gland Dysfunction Treatment Market | 2026-2036
Meibomian Gland Dysfunction Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Meibomian Gland Dysfunction Treatment Market Outlook
Ophthalmology clinics is reorganizing purchasing patterns away from chronic pharmaceutical dependence toward procedural interventions. AbbVie (Allergan) leverages its established cyclosporine franchise to defend pharmacy-driven relationships while building device partnerships. Alcon anchors its position through integrated diagnostics-to-treatment platforms spanning meibomian gland imaging and thermal pulsation systems. Sight Sciences specializes in office-based procedural technologies that reduce patient reliance on ongoing topical regimens.
Meibomian Gland Dysfunction Treatment encompasses therapeutic interventions targeting obstructed or atrophied tarsal meibomian glands, whose lipid secretions stabilize the tear film's evaporative barrier; thermal pulsation systems apply controlled heat and pressure to express inspissated gland contents, while intense pulsed light therapy targets inflammatory mediators and Demodex overpopulation. Topical medications retain the largest installed base due to accessibility and payer familiarity, though device-assisted delivery modes capture expanding margin pools as clinic reimbursement per procedure exceeds chronic pharmaceutical costs. Intense pulsed light therapy represents the fastest-growing product type as practices seek differentiated cash-pay services beyond insurance-dependent workflows.
FDA 510(k) pathways govern device market entry for thermal and light-based systems, while the EU MDR imposes strengthened clinical evidence requirements on reusable ophthalmic instruments. The FDA's evolving dry eye device classification standards and Japan's PMDA reimbursement reviews for procedural ophthalmic therapies are reshaping geographic launch sequencing. Stakeholders must monitor whether CMS creates discrete procedural codes for meibomian gland expression or continues bundling into general ophthalmic visit reimbursement, as this determination will redirect capital between pharmaceutical and device development portfolios.
Market Dynamics
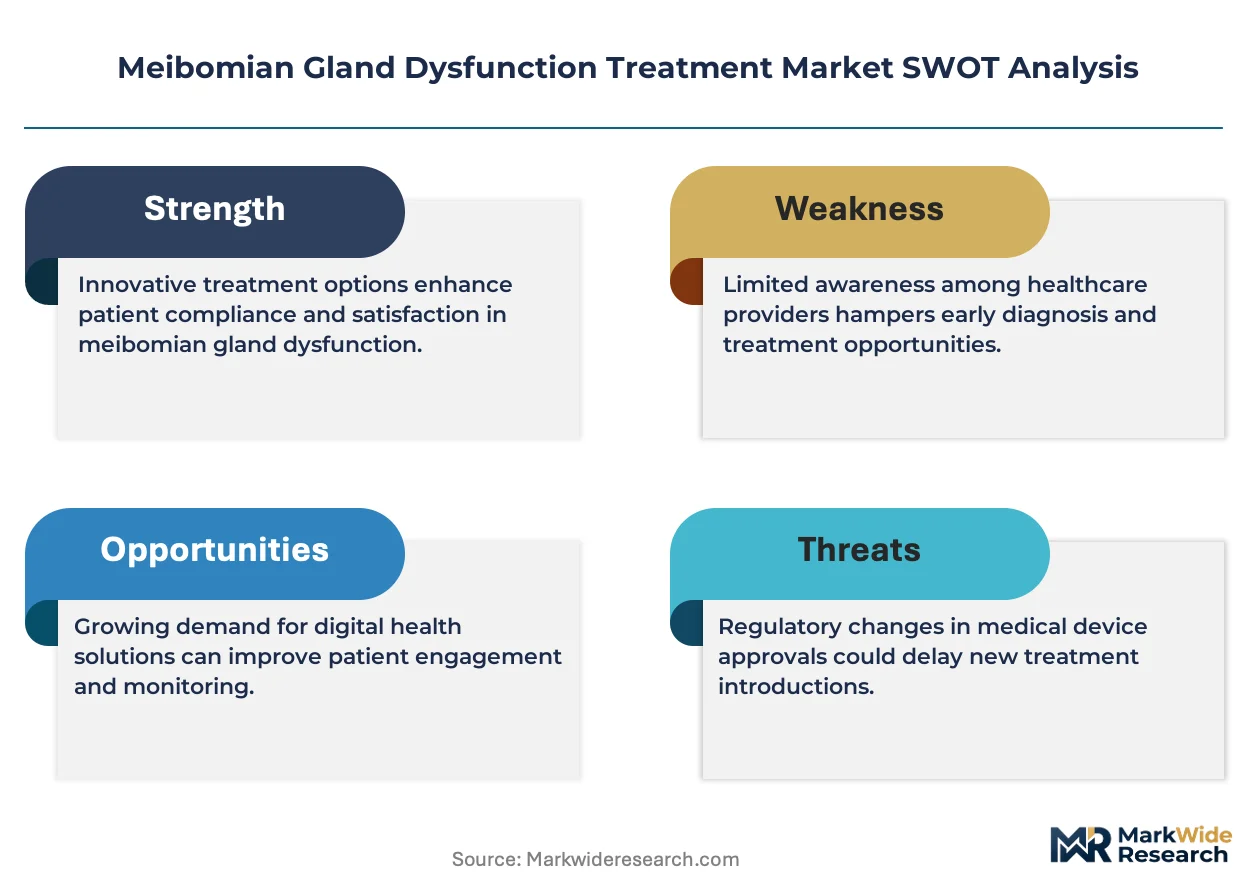
Thermal pulsation and intense pulsed light technologies are restructuring ophthalmology clinic economics by converting chronic pharmaceutical relationships into discrete procedural revenue streams with higher per-visit yields.
Growth Catalysts
- FDA 510(k) Pathway Efficiency:Streamlined device clearances for thermal and light-based systems accelerate commercial timelines for manufacturers targeting in-office procedural adoption.
- EU MDR Harmonization:Strengthened clinical evidence requirements create competitive moats for established device makers with robust quality management systems.
- Ophthalmology Clinic Consolidation:Larger practice groups deploy capital toward integrated diagnostic-treatment platforms that capture margin pools from fragmented topical medication dispensing.
Market Restraints
- Reimbursement Bundling Uncertainty:CMS continues grouping meibomian gland expression into general ophthalmic visit codes rather than discrete procedural reimbursement, compressing provider incentive for device investment.
- Supply Concentration in Optical Components:Precision thermal sensors and calibrated light sources concentrate among German and Japanese component suppliers, exposing device manufacturers to input bottlenecks.
- Topical Cyclosporine Substitution:Established chronic pharmaceutical regimens retain payer familiarity and patient accessibility, creating inertia against procedural conversion despite superior clinical outcomes.
Strategic Opportunities
- Japan PMDA Reimbursement Expansion:Procedural ophthalmic therapy coverage reviews create entry pathways for thermal pulsation systems in an aging population with high dry eye prevalence.
- Home-Use Thermal Device Convergence:Portable heating technologies combined with smartphone-guided treatment protocols open consumer-direct channels beyond clinic-dependent models.
- Demodex-Targeted IPL Protocols:Intense pulsed light applications addressing parasitic overpopulation expand treatable patient populations beyond traditional evaporative dry eye diagnoses.
Industry Challenges
- Cross-Trained Technician Scarcity:Device-assisted therapies require staff proficient in both gland imaging interpretation and thermal system operation, creating hiring bottlenecks for expanding clinic networks.
- EU MDR Technical Documentation Burden:Reusable ophthalmic instruments face extended conformity assessment timelines as notified bodies process strengthened clinical evidence requirements.
- Legacy EHR Integration Friction:Procedural documentation workflows for thermal pulsation and IPL treatments lack standardized interoperability with dominant electronic health record platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Meibomian Gland Dysfunction Treatment Market |
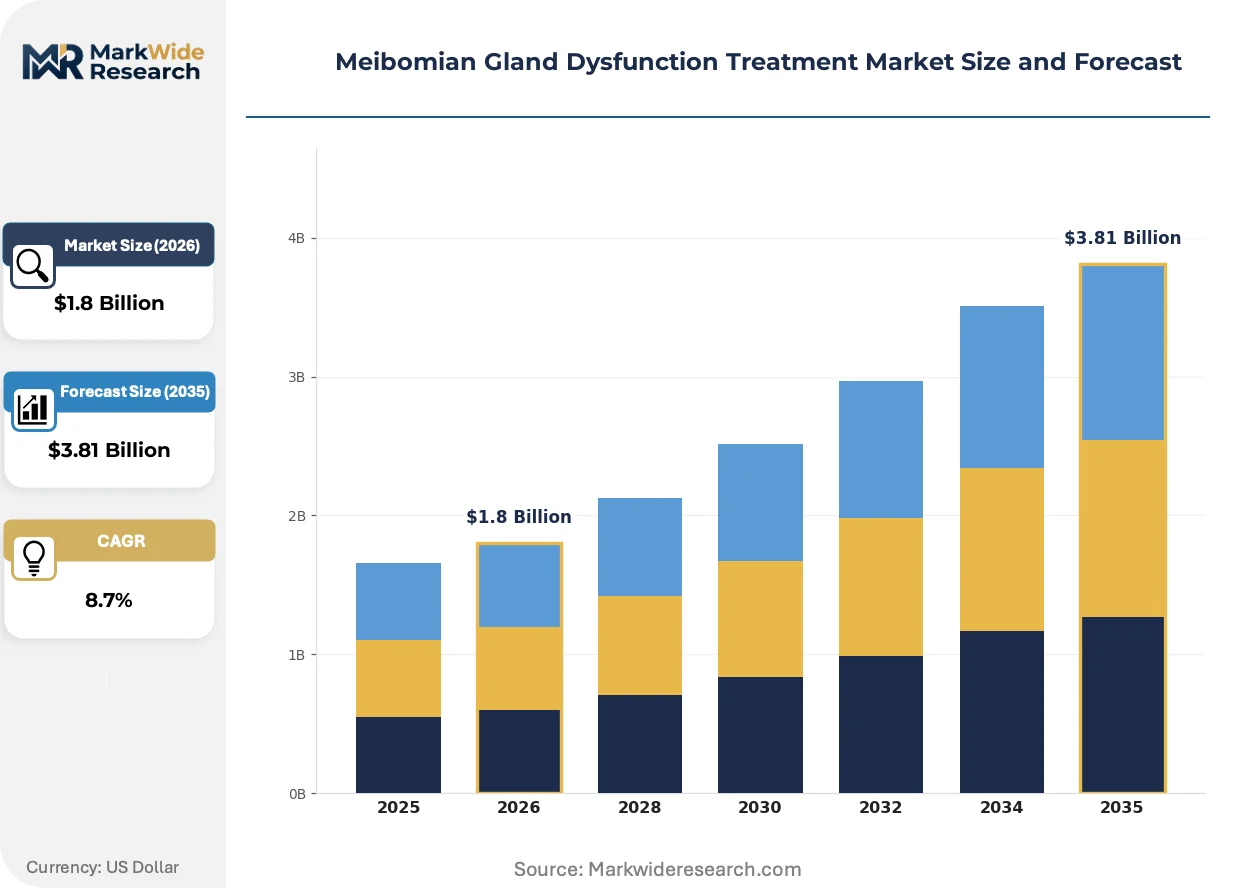
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Punctal Plugs, Lipiflow, Intense Pulsed Light Therapy, Topical Medications Application: Dry Eye Syndrome, Inflammation, Tear Film Stability, Ocular Surface Disease End User: Ophthalmology Clinics, Hospitals, Home Care Settings, Research Institutions Delivery Mode: Topical, Device-assisted, Surgical Procedures, Injections |
| Companies Covered | AbbVie (Allergan), Alcon, Bausch + Lomb, Johnson & Johnson Vision, Sight Sciences, Novaliq GmbH, Santen Pharmaceutical, Novartis, Azura Ophthalmics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Meibomian Gland Dysfunction Treatment Market Strategic Shifts
Device manufacturers and clinic operators are converging on integrated platforms that collapse diagnostic imaging, treatment delivery, and outcome tracking into unified workflows. This compression is reshaping capital deployment patterns across the sector.
Intense pulsed light therapy is fragmenting the traditional dry eye treatment hierarchy by creating cash-pay service categories outside insurance-dependent pharmaceutical workflows. Aesthetic dermatology clinics are cross-training staff to capture ophthalmic patient flows. The resulting channel expansion is compressing pricing power for standalone thermal pulsation device specialists.
The EU MDR's strengthened post-market surveillance requirements for reusable ophthalmic instruments are extending product lifecycle documentation obligations. Manufacturers must now maintain clinical evidence portfolios across extended device lifespans. Japanese and German notified bodies are prioritizing submissions with real-world performance registries, favoring established players with post-market infrastructure.
Patient acquisition patterns are rotating toward direct-to-consumer education channels that bypass traditional referral networks from optometry to ophthalmology. Social media platforms and condition-specific online communities now drive initial awareness of procedural alternatives to chronic drops. This disintermediation is most visible in United States metropolitan markets where aesthetic medicine marketing expertise transfers readily to dry eye service promotion.
Meibomian Gland Dysfunction Treatment Market Segmentation
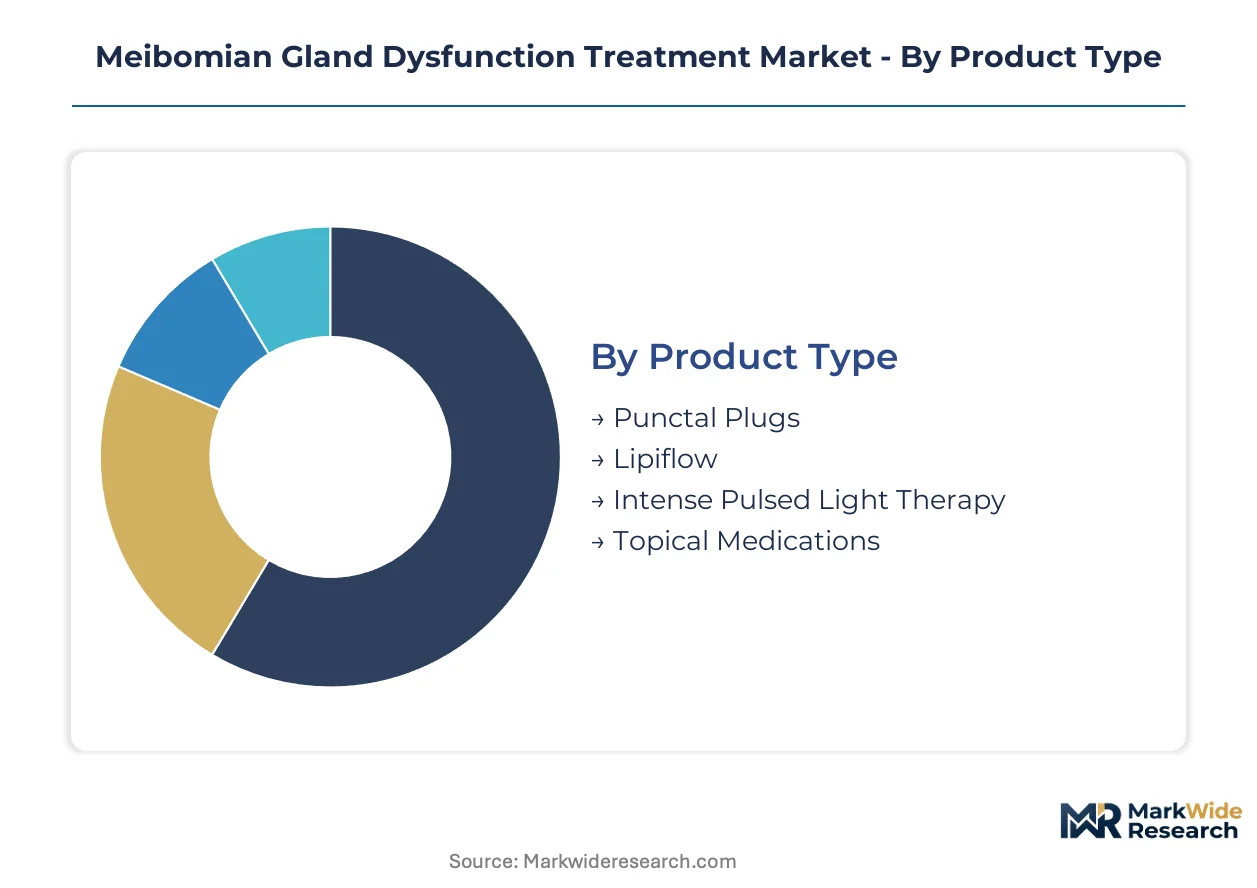
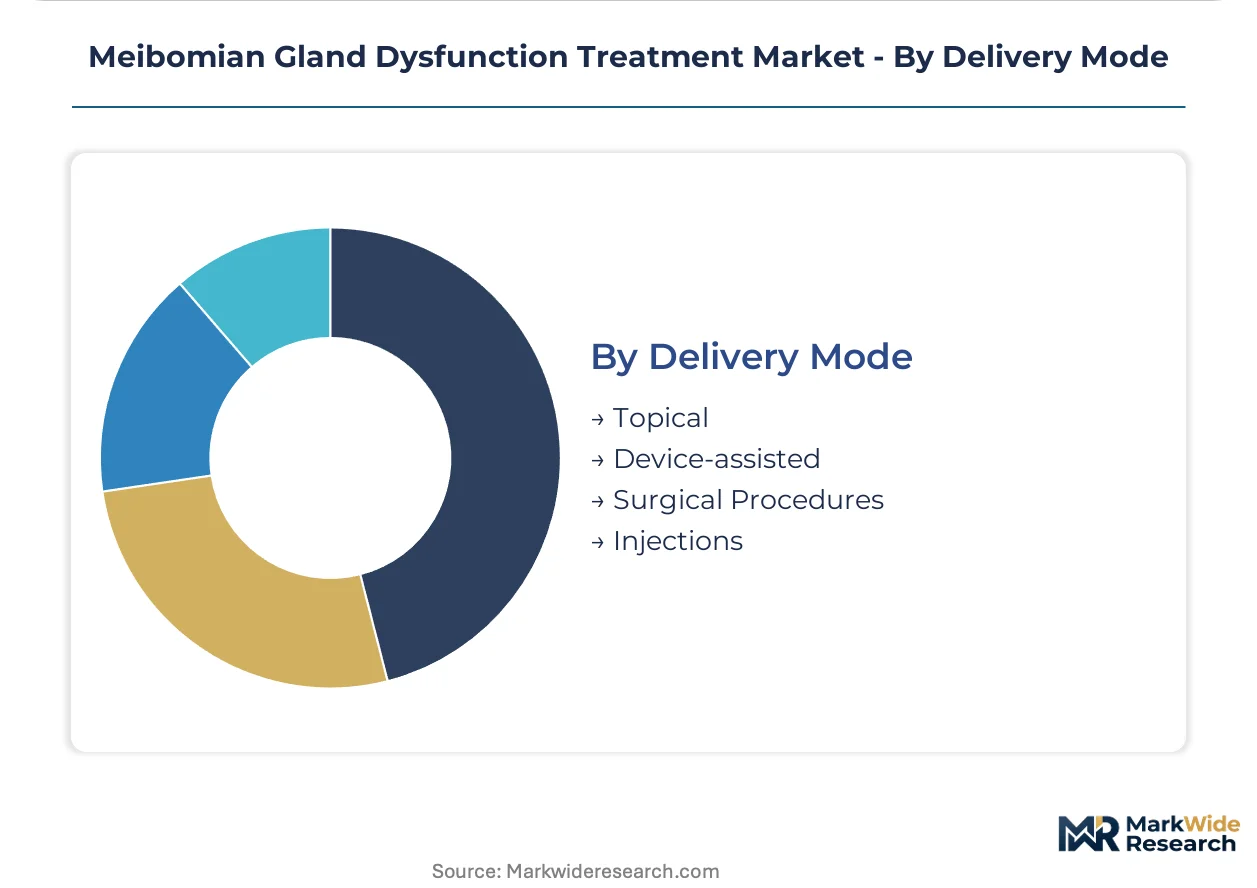
Segmentation in the Meibomian Gland Dysfunction Treatment Market reveals distinct procurement patterns across product types and care settings. Device-assisted therapies concentrate in high-margin clinic environments while pharmaceutical options retain broader accessibility.
Product Type:
Domestic demand for thermal and light-based systems concentrates in the United States, Germany, and Japan where reimbursement pathways have matured; export-led growth flows through portable heating technologies targeting home-use markets.
- Topical Medications:Cyclosporine and lifitegrast formulations constitute the accessible entry point for chronic management. Payer familiarity in United States commercial plans and German statutory insurance sustains volume despite clinical limitations in addressing gland obstruction directly.
- Intense Pulsed Light Therapy:Calibrated light delivery targets inflammatory mediators and Demodex overpopulation through melanin-absorbing wavelengths. Cash-pay adoption accelerates in United States metropolitan markets where aesthetic medicine marketing expertise transfers to dry eye service promotion.
- Lipiflow:Controlled thermal pulsation applies vectored heat and pressure to express inspissated gland contents.
- Punctal Plugs:Silicone or collagen inserts provide temporary tear retention through canalicular occlusion.
Topical Medications commands the established base. The steepest expansion runs through Intense Pulsed Light Therapy.
Application:
Cost tier differentiation separates insurance-reimbursed diagnostic categories from premium procedural interventions targeting refractory cases.
- Dry Eye Syndrome:Evaporative and aqueous-deficient subtypes drive distinct treatment selections; evaporative cases linked to MGD concentrate device demand in ophthalmology clinics while aqueous-deficient presentations retain pharmaceutical primacy.
- Ocular Surface Disease:Integrated diagnostic platforms collapse imaging and treatment workflows for complex presentations. Japan's aging population and high dry eye prevalence position PMDA reimbursement expansion as the critical volume catalyst.
- Inflammation:Cytokine-mediated pathways respond to immunomodulatory drops.
- Tear Film Stability:Lipid layer augmentation targets evaporative protection.
Dry Eye Syndrome anchors current procedure volumes. Ocular Surface Disease is climbing the fastest as diagnostic capabilities expand treatable identification.
End User:
Customer type fragmentation concentrates capital deployment toward integrated platforms in consolidated practice groups versus fragmented pharmaceutical dispensing.
- Ophthalmology Clinics:Office-based procedural technologies convert chronic pharmaceutical relationships into discrete revenue streams. Larger United States practice groups deploy thermal pulsation and IPL systems to capture margin pools from topical medication dispensing.
- Hospitals:Academic medical centers in Germany and Japan maintain research linkages to device clinical trials. EU MDR technical documentation burdens favor established manufacturers with post-market surveillance infrastructure for reusable instruments.
- Home Care Settings:Portable heating technologies with smartphone-guided protocols open consumer-direct channels.
- Research Institutions:Clinical evidence generation supports regulatory submissions.
Ophthalmology Clinics holds the dominant share. Home Care Settings is gaining share fastest through technology convergence.
Delivery Mode:
Supply concentration in precision thermal sensors and calibrated light sources shapes geographic manufacturing patterns for device-assisted segments.
- Device-assisted:Thermal pulsation and IPL systems require cross-trained technicians proficient in gland imaging interpretation. Supply bottlenecks in German and Japanese optical component suppliers expose manufacturers to input constraints.
- Topical:Drop formulations retain the largest installed base through pharmacy accessibility. CMS bundling of meibomian gland expression into general ophthalmic visit codes compresses provider incentive for procedural conversion.
- Surgical Procedures:Gland probing and expression address refractory obstruction.
- Injections:Intra-glandular delivery remains investigational.
Topical delivery maintains volume leadership. Device-assisted modalities show the steepest expansion trajectory as clinic economics restructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold chain infrastructure underwrites European distribution of temperature-sensitive ophthalmic biologics, while Japan's Shinkansen freight network enables same-day device delivery to clinics across the archipelago.
United States
CMS reimbursement bundling decisions for meibomian gland expression procedures concentrate provider investment in ophthalmology clinics across Texas and Florida. FDA 510(k) pathway efficiency accelerates commercial timelines for thermal pulsation manufacturers targeting in-office adoption. The Dallas-Fort Worth metroplex hosts consolidated practice groups deploying integrated diagnostic-treatment platforms.
Germany
Statutory insurance familiarity with chronic pharmaceutical regimens sustains cyclosporine volume despite procedural alternatives gaining traction in Bavarian university hospitals. EU MDR technical documentation burdens favor established device makers with post-market surveillance infrastructure. The Stuttgart region concentrates precision thermal sensor suppliers serving reusable ophthalmic instrument manufacturers.
Japan
PMDA reimbursement reviews for procedural ophthalmic therapies create entry pathways for thermal pulsation systems addressing an aging population with elevated dry eye prevalence. METI industrial standards for medical device software interoperability shape platform integration requirements. The Nagoya medical device cluster advances real-world performance registries supporting notified body submissions.
United Kingdom
NHS England commissioning frameworks for specialist ophthalmic services fragment procurement between acute trusts and community providers. MHRA post-Brexit regulatory alignment with EU MDR extends conformity assessment timelines for reusable instruments. London's Harley Street clinic district drives cash-pay adoption of intense pulsed light therapies outside insurance workflows.
Switzerland
Swissmedic's streamlined device authorization procedures attract manufacturers seeking rapid European market entry ahead of EU MDR harmonization. Private clinic networks in Zurich and Geneva deploy premium pricing for integrated diagnostic-treatment platforms. The Basel pharmaceutical corridor sustains R&D partnerships between device makers and topical formulation specialists.
Meibomian Gland Dysfunction Treatment Market Competitive Environment
Concentration sits with diversified ophthalmic conglomerates defending pharmacy-driven relationships while building device partnerships. The vendor base spans three tiers: established pharmaceutical franchises with cyclosporine infrastructure, integrated diagnostics-to-treatment platform specialists, and office-based procedural technology pure-plays. Competitive moves center on M&A activity capturing diagnostic imaging capabilities and strategic partnerships securing optical component supply.
Within the pharmaceutical-device hybrid tier, AbbVie (Allergan) and Alcon represent archetypes of divergent defensive strategies against procedural displacement. Among procedural technology specialists, Sight Sciences occupies a position exemplifying the pure-play model. Novaliq GmbH anchors the European contingent with GmbH-structured operations.
| Leading Market Players |
|---|
| AbbVie (Allergan) |
| Alcon |
| Bausch + Lomb |
| Johnson & Johnson Vision |
| Sight Sciences |
| Novaliq GmbH |
| Santen Pharmaceutical |
| Novartis |
| Azura Ophthalmics |
| Others |
Value Chain & Pricing Dynamics
Long-term capacity reservation agreements with German and Japanese optical component suppliers lock in thermal sensor and calibrated light source access while anchoring device manufacturers' cost visibility against input volatility. These contracts concentrate pricing power upstream, forcing downstream assembly operations to absorb margin compression or pass through to clinic buyers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared thermal pulsation systems from CE-marked equivalents and unregulated home-use heating devices. Brand premium and certification tier drive differentiation, with FDA 510(k) clearance commanding substantial markups over EU MDR-aligned alternatives. Cost compression in the home-use tier is intensifying because smartphone-guided protocols eliminate clinic overhead. Ophthalmology practice groups show least price sensitivity due to procedural reimbursement yields, while individual optometry clinics face acute budget constraints.
Supply Chain Analysis
Just-in-time inventory strategies dominate device assembly operations, though strategic stockpiling of precision thermal sensors from German suppliers buffers against semiconductor fabrication bottlenecks. Supply concentrates in Germany, Japan, and the United States for optical components, with raw material dependencies spanning rare-earth phosphors, medical-grade silicone, and calibrated LED arrays. Single-source vulnerability in melanin-targeting IPL wavelength modules exposes manufacturers to allocation risk. Distribution runs through specialized ophthalmic device distributors with GPO linkages to consolidated clinic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in post-treatment maintenance protocols and remote patient monitoring subscriptions are expanding faster than hardware sales, creating recurring revenue layers that justify premium platform pricing. This shift rewards vendors who bundle diagnostic imaging with ongoing outcome tracking.
For Market Incumbents: Fortify cyclosporine franchise relationships through integrated device partnerships that preserve pharmacy-driven workflows while capturing procedural margin pools. Invest in backward integration into precision thermal sensor production to reduce German supplier dependency. Prioritize EU MDR technical documentation infrastructure to extend conformity assessment timelines as competitive moats against emerging entrants lacking post-market surveillance capabilities. For New Entrants and Emerging Players: Anchor in home-use thermal device convergence where smartphone-guided protocols bypass clinic-dependent reimbursement complexity. Target cash-pay IPL services in United States metropolitan markets where aesthetic medicine marketing expertise transfers readily to dry eye patient acquisition. Pursue direct-to-consumer education channels that disintermediate traditional optometry-to-ophthalmology referral networks. For Investors and Strategic Acquirers: Capital is best deployed toward diagnostics-to-treatment platform specialists with integrated imaging and thermal pulsation capabilities that capture margin pools from fragmented topical dispensing. Long-term viability hinges on CMS reimbursement unbundling decisions that would restructure provider incentive toward procedural investment. Watch PMDA procedural therapy coverage expansion as the critical volume inflection signal for Japanese market entry.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Streamlined clearance pathways accelerate commercial timelines for thermal pulsation manufacturers targeting clinic adoption. |
| EU MDR Technical Documentation | Strengthened clinical evidence requirements favor established device makers with robust quality management systems. |
| Hospital System Partnership | Academic medical center alliances in Germany and Japan secure research linkages for reusable instrument clinical trials. |
| Software Companion Development | Smartphone-guided treatment protocols open consumer-direct channels beyond clinic-dependent reimbursement models. |
| Reimbursement Strategy | CMS procedural code unbundling would redirect capital between pharmaceutical and device development portfolios. |
Study Parameters
Cross-validation between ophthalmology clinic purchasing committee interviews and FDA 510(k) filing databases anchors the qualitative findings in documented regulatory pathways. Primary fieldwork encompassed device development executives, regulatory affairs leads, GPO contracts managers, and biomedical engineers across thermal pulsation and IPL system manufacturers. Secondary validation drew from FDA filings, EU MDR notified body submission records, CMS Medicare reimbursement databases, and hospital procurement data. Bottom-up segment sizing triangulated against top-down market aggregation.
Sensitivity analysis across reimbursement scenario variants tests forecast robustness over the projection horizon. Segmentation dimensions modeled include product type, delivery mode, end-user category, and regional regulatory cluster. CAGRs were derived from procedure volume trajectories and average selling price evolution. Industry-specific inputs incorporated PMDA reimbursement review timelines, EU MDR conformity assessment queue lengths, and optical component supplier allocation patterns.
Decision-makers should treat outputs as directional under assumptions of stable CMS bundling policy and sustained German-Japanese optical component supply; material deviation would warrant model refresh. Revision becomes warranted when FDA dry eye device classification standards or Japan PMDA procedural coverage decisions cross threshold inflection points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
North America Vision Care Market
Ophthalmology
Ophthalmic Tonometers Market
Ophthalmology
Laser Vision Correction Market
Ophthalmology
3D Printed Ophthalmic Implants Market
Ophthalmology
Ocular Inserts Market
Ophthalmology
Corneal Ulcer Treatment Market
Ophthalmology
Ophthalmic Eye Shield Market
Ophthalmology
Usher Syndrome Market
Ophthalmology
Ocular Pain Market
Ophthalmology
Amblyopia Treatment Market
Ophthalmology
Herpes Zoster Ophthalmicus Market
Ophthalmology
India Ophthalmic Clinical Trials Market
Ophthalmology
Laser Indirect Ophthalmoscope Market
Ophthalmology
Japan Ophthalmic Devices and Drugs Market
Ophthalmology
Ophthalmic Suspension Market
Ophthalmology
Eye Infections Treatment Market