
 Sterile Fill-Finish Process Simulation and Media Fill Test Equipment Market | 2026-2036
Sterile Fill-Finish Process Simulation and Media Fill Test Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Sterile Fill-Finish Process Simulation and Media Fill Test Equipment Market Insights
Annex 1 of the EU GMP is rotating the competitive landscape for media fill test equipment by mandating process simulation intervals that favor automated, validated systems. Syntegon Technology leverages its isolator-integrated platforms to anchor high-volume vaccine fill-finish lines across European CMOs. I.M.A. S.P.A. competes through modular equipment architectures that sustain flexible batch sizes for emerging biopharmaceutical pipelines. West Pharmaceutical Services differentiates via containment closure systems that extend process simulation fidelity from equipment into primary packaging.
Sterile fill-finish process simulation and media fill test equipment encompasses closed-system machinery that reproduces aseptic manufacturing conditions using microbial growth media rather than active pharmaceutical ingredients, typically operating within ISO 5 environments with HEPA-filtered unidirectional airflow exceeding 0.45 m/s at the work surface. Its primary purpose is to validate aseptic processing competency by demonstrating contamination rates below one positive unit per thousand filled. Automated systems now dominate capital expenditure as pharmaceutical companies prioritize continuous line integration over manual intervention points that introduce variability. Isolator technology represents the fastest-growing equipment category, displacing conventional laminar flow hoods where operator-mediated contamination risk conflicts with Annex 1's emphasis on closed barrier systems.
FDA, EMA, and WHO collectively shape equipment demand through harmonized but distinct aseptic processing guidelines that mandate periodic media fill validation for every commercial batch format. The FDA's 2004 Aseptic Processing Guidance and EMA's revised Annex 1 create dual compliance burdens for multinational manufacturers, directly driving replacement cycles for non-validated legacy equipment. Stakeholders must monitor divergence between FDA isolator guidance and EMA's stricter physical barrier requirements, as equipment purchased for one regulatory jurisdiction may demand costly retrofit for the other.
Market Dynamics
Annex 1's 2022 revision is compressing equipment replacement cycles by mandating closed barrier systems over open cleanroom configurations, forcing pharmaceutical manufacturers to retire laminar flow hoods ahead of depreciation schedules.
Growth Catalysts
- EMA barrier mandates:The revised Annex 1 requires physical separation between operators and critical zones, accelerating capital deployment into isolator-integrated media fill lines across European fill-finish facilities.
- Biologics capacity expansion:Contract manufacturing organizations are scaling aseptic processing footprints to accommodate monoclonal antibody and cell therapy volumes, directly lifting demand for process simulation validation.
- HEPA filtration upgrades:Unidirectional airflow specifications exceeding 0.45 m/s at work surfaces are driving replacement of legacy equipment in German and Swiss pharmaceutical clusters.
Market Restraints
- Stainless steel supply concentration:Equipment fabrication depends on specialized 316L stainless steel grades where European mill capacity constraints create 12-18 month lead times for isolator-grade components.
- FDA-EMA regulatory divergence:Isolator guidance differences between FDA's 2004 Aseptic Processing Guidance and EMA's stricter physical barrier definitions force dual-validation investments for multinational manufacturers.
- Skilled commissioning engineer scarcity:The specialized workforce required for isolator qualification and smoke pattern testing commands premium rates that extend project timelines.
Strategic Opportunities
- India biopharma infrastructure:CDSCO's alignment with PIC/S standards is opening validation service markets for equipment vendors as domestic biologics manufacturing scales.
- Continuous manufacturing integration:Convergence of isolator technology with real-time microbial detection systems enables closed-loop media fill processes that reduce batch release timelines.
- Single-use technology hybridization:Modular equipment architectures that accommodate both stainless steel and disposable flow paths capture flexible batch-size demand from emerging gene therapy pipelines.
Industry Challenges
- Isolator decontamination cycle validation:Vaporized hydrogen peroxide cycle development and biological indicator placement require specialized expertise that bottlenecks facility commissioning.
- Legacy line retrofit complexity:Integrating automated media fill systems with existing fill-finish infrastructure demands custom mechanical and software interfaces that extend qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sterile Fill-Finish Process Simulation and Media Fill Test Equipment Market |
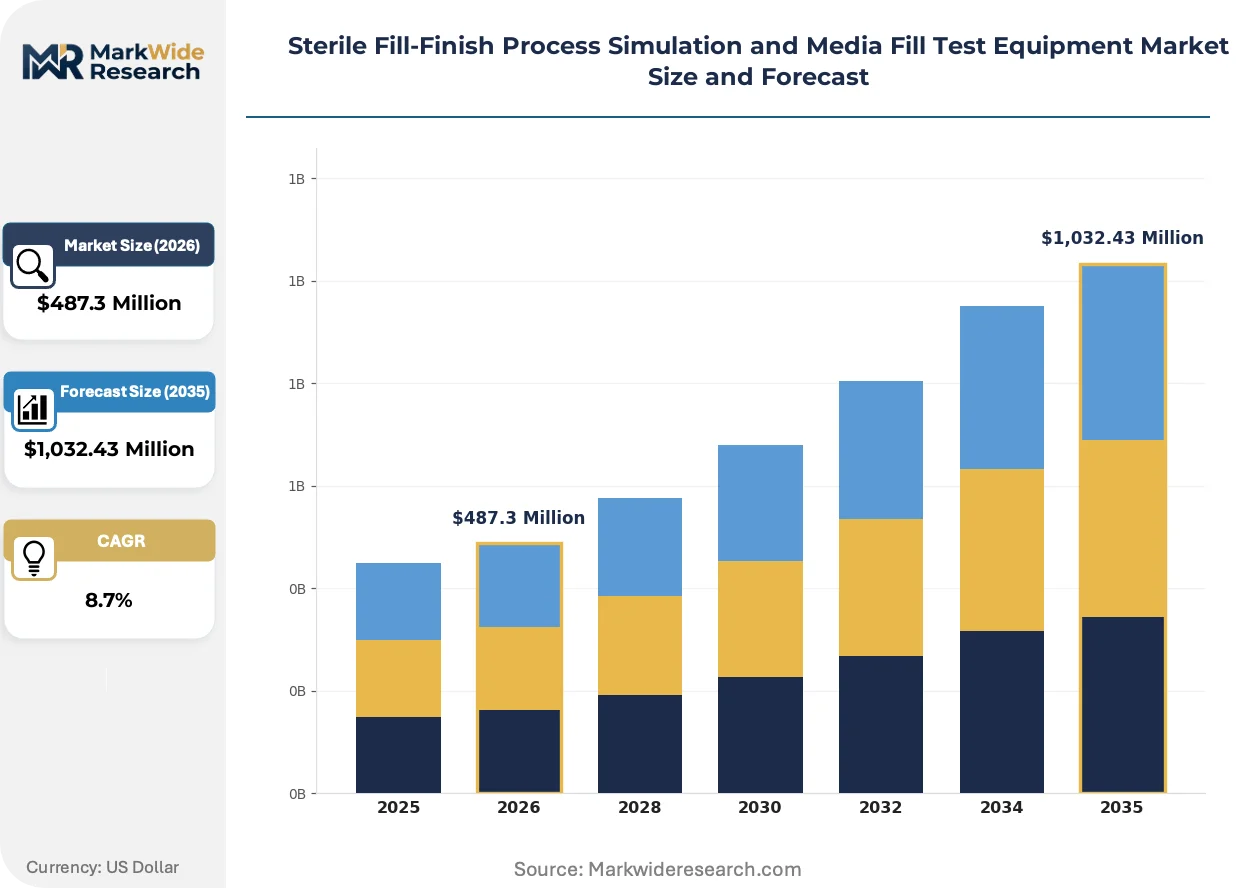
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Systems, Manual Units, Semi-Automated Equipment, Portable Devices Application: Vaccine Manufacturing, Biopharmaceuticals, Parenteral Drugs, Ophthalmic Products End User Type: Contract Manufacturing Organizations, Biotechnology Firms, Pharmaceutical Companies, Research Institutes Technology: Laminar Air Flow, Isolator Technology, Negative Pressure, HEPA Filtration |
| Companies Covered | Syntegon Technology, I.M.A. S.P.A., West Pharmaceutical Services, Gerresheimer AG, AptarGroup, BD, Dätwyler Holding, Bausch+Ströbel, Tofflon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sterile Fill-Finish Process Simulation and Media Fill Test Equipment Market Trends and Innovations
Equipment architectures are pivoting from operator-dependent cleanroom designs toward fully enclosed barrier systems that eliminate human intervention points during critical processing phases.
Isolator technology is displacing conventional laminar flow hoods as the dominant platform for media fill test execution. Vaccine manufacturers in Germany and Switzerland are prioritizing gloveless isolator configurations that enable robotic vial handling. This displacement is compressing the addressable market for open-system equipment and redirecting R&D investment toward containment integrity monitoring.
EMA's Annex 1 revision mandates process simulation intervals tied to batch format changes rather than fixed calendar schedules. Pharmaceutical manufacturers must now execute media fills for every new container closure configuration before commercial release. Fill-finish lines serving multi-product CMOs face the steepest compliance burden as format change frequency accelerates.
Buyers are unbundling equipment procurement from validation service contracts, treating media fill protocol development as a separate competitive tender. Large pharmaceutical manufacturers now source isolator hardware from specialized OEMs while engaging dedicated validation consultancies for smoke studies and environmental monitoring qualification. This bifurcation is most pronounced in the United States where FDA inspection intensity drives demand for independent third-party protocol execution.
Sterile Fill-Finish Process Simulation and Media Fill Test Equipment Market Segmentation
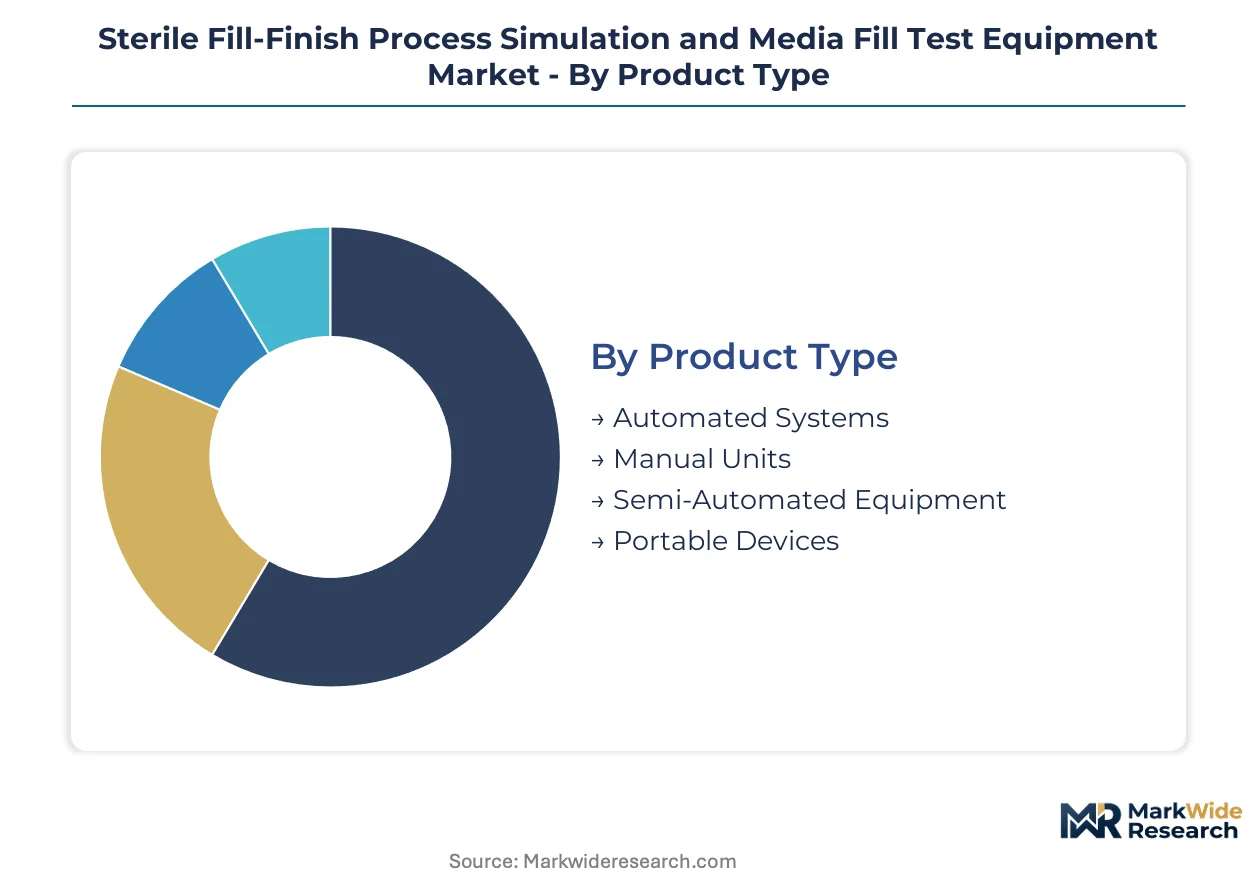
Segmentation in sterile fill-finish process simulation equipment reveals how regulatory pressure and biologics manufacturing scale reshape procurement patterns across hardware categories. Equipment buyers now prioritize technology platforms that compress validation timelines while satisfying divergent FDA and EMA barrier requirements.
Product Type:
Channel mix varies sharply by automation tier, with automated systems flowing through direct OEM relationships while manual units persist in distributor networks serving smaller research facilities.
- Automated Systems:These platforms integrate robotic vial handling, real-time environmental monitoring, and isolator-grade containment within single qualification protocols. German vaccine manufacturers and Swiss biologics CMOs concentrate procurement here, driven by Annex 1's closed-barrier mandates that eliminate operator intervention points.
- Manual Units:Benchtop configurations with glove ports and laminar flow hoods dominate academic and early-phase research settings. Demand concentrates in United States research institutes where budget constraints and lower throughput requirements sustain this tier despite regulatory pressure toward automation.
- Semi-Automated Equipment:Hybrid architectures blending operator-mediated steps with automated fill sequences capture mid-scale CMOs in emerging biopharma clusters.
- Portable Devices:Compact, wheeled units with rapid deployment capabilities serve validation service providers conducting multi-site media fill campaigns.
By volume, Manual Units leads. By growth pace, Automated Systems is ahead.
Application:
Cost tier stratification separates vaccine manufacturing's premium isolator investments from ophthalmic products' more standardized containment approaches.
- Vaccine Manufacturing:Large-scale parenteral fill-finish lines demand isolator-integrated process simulation systems with gloveless robotic interfaces. United States and German facilities anchor demand here, compelled by pandemic-era capacity expansion and WHO prequalification requirements for export-bound production.
- Biopharmaceuticals:Monoclonal antibody and cell therapy pipelines require flexible batch formats with rapid changeover capabilities. Swiss CMOs and United States biotechnology clusters concentrate procurement, driven by pipeline diversification that accelerates media fill frequency.
- Parenteral Drugs:Generic injectable manufacturers prioritize cost-efficient semi-automated platforms with validated cleaning protocols.
- Ophthalmic Products:Sterile eye drop and intraocular fill-finish lines employ compact isolator systems with specialized container closure handling.
Biopharmaceuticals commands the steepest equipment margins. Vaccine Manufacturing shows the steepest expansion trajectory.
End User Type:
Customer type determines procurement velocity, with contract manufacturing organizations executing rapid validation cycles while research institutes extend equipment lifecycles.
- Contract Manufacturing Organizations:Multi-product fill-finish facilities face the densest media fill schedules under Annex 1's format-change requirements. European and United States CMOs dominate capital deployment, compelled by customer audit intensity and regulatory inspection frequency that demand continuously qualified equipment.
- Biotechnology Firms:Emerging gene therapy and cell therapy developers prioritize modular platforms with single-use compatibility. United States coastal clusters concentrate demand, driven by venture-funded pipeline expansion and accelerated IND timelines.
- Pharmaceutical Companies:Integrated Big Pharma operations favor captive validation capabilities with standardized equipment fleets across manufacturing networks.
- Research Institutes:Academic and government laboratories sustain manual and semi-automated equipment demand for early-phase process development.
Pharmaceutical Companies deploy the largest individual orders. Biotechnology Firms are climbing the fastest.
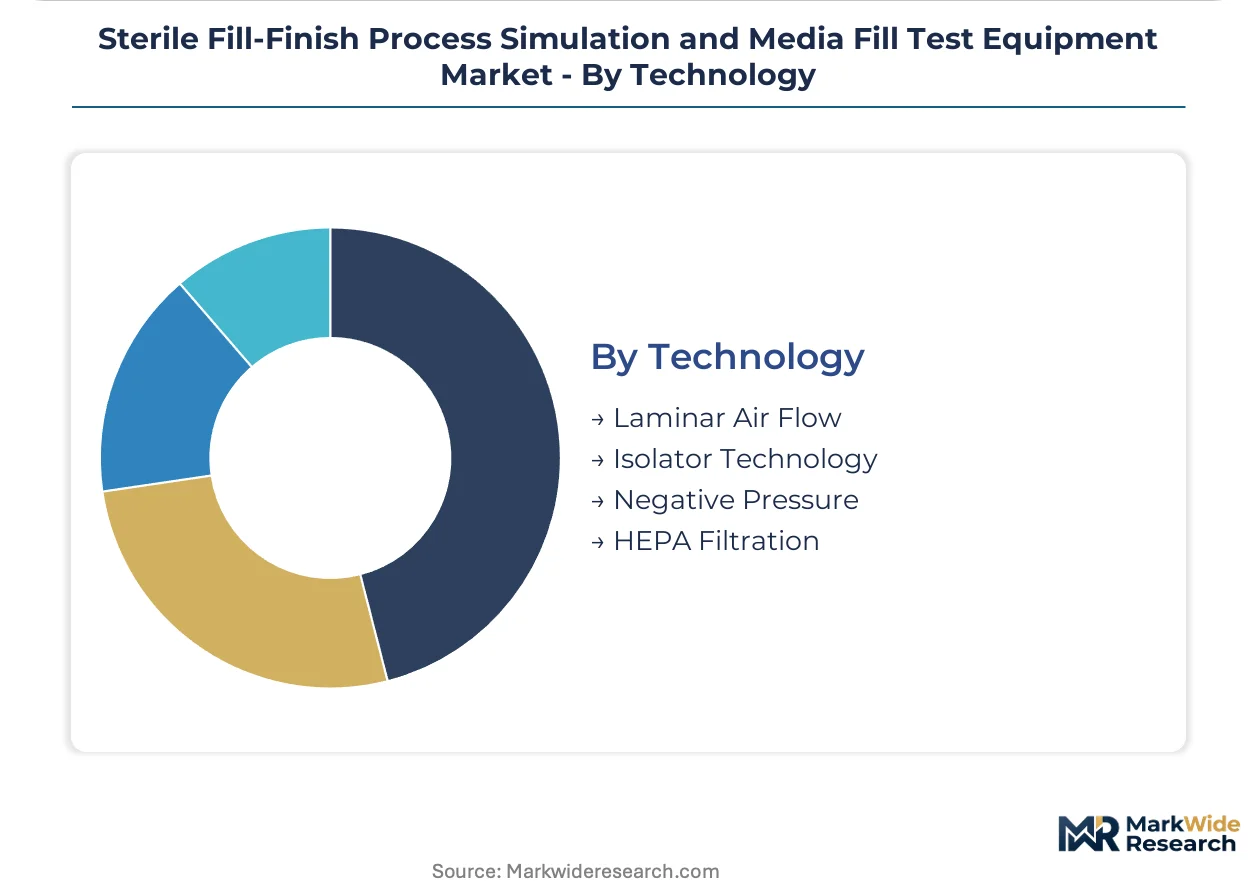
Technology:
Supply concentration in isolator fabrication creates procurement bottlenecks that favor early equipment commitments over spot purchasing.
- Isolator Technology:Fully enclosed rigid barrier systems with vaporized hydrogen peroxide decontamination cycles now dominate new capital allocation. German and Swiss fill-finish facilities prioritize gloveless configurations, compelled by EMA's stricter physical separation requirements that exceed FDA guidance.
- Laminar Air Flow:Open cleanroom configurations with unidirectional HEPA-filtered airflow face accelerated retirement schedules. Legacy installations persist in United States generic manufacturers where capital replacement cycles lag regulatory pressure.
- Negative Pressure:Containment systems for potent compound handling serve specialized cytotoxic and high-potency API fill-finish operations.
- HEPA Filtration:Filter housing and monitoring subsystems integrate across all platform tiers as upgrade components rather than standalone purchases.
Isolator Technology captures the dominant share of new capital. Negative Pressure is gaining share fastest in specialized applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EMA's 2022 Annex 1 revision is accelerating capital deployment into isolator-integrated media fill lines across European fill-finish facilities. German, Swiss, and United States pharmaceutical clusters concentrate procurement as regulatory pressure eliminates open cleanroom configurations ahead of depreciation schedules.
Germany
Bavaria and Baden-Württemberg anchor vaccine manufacturing capacity expansion with multi-billion euro biologics investments from CMOs. The country's national pharmaceutical regulator enforces EMA Annex 1 barrier mandates that exceed FDA guidance, compelling gloveless isolator adoption. Stuttgart and Munich pharmaceutical hubs are retiring laminar flow hoods in favor of vaporized hydrogen peroxide decontamination systems.
Switzerland
Basel and Zug biopharmaceutical clusters drive demand for flexible batch-format equipment serving monoclonal antibody pipelines. Swissmedic aligns with EMA's stricter physical separation requirements, accelerating validation service procurement. The Lake Geneva corridor concentrates gene therapy manufacturing where media fill frequency accelerates with pipeline diversification.
United States
Greater Boston and San Francisco Bay Area biotechnology firms prioritize modular platforms with single-use compatibility for accelerated IND timelines. FDA inspection intensity drives demand for independent third-party protocol execution and smoke study qualification. New Jersey and North Carolina fill-finish corridors sustain generic injectable manufacturing with semi-automated platform investments.
India
Maharashtra and Telangana biopharma infrastructure scales under CDSCO's alignment with PIC/S standards, opening validation service markets for equipment vendors. The country's national pharmaceutical regulator mandates periodic media fill validation for commercial batch release. Hyderabad and Mumbai pharmaceutical clusters are expanding aseptic processing footprints to accommodate export-bound biologics production.
United Kingdom
London and Southeast England CMOs execute rapid validation cycles under MHRA post-Brexit regulatory continuity agreements. The national pharmaceutical regulator maintains EMA-aligned barrier requirements while diverging on specific isolator guidance interpretations. Cambridge and Oxford biotech clusters sustain early-phase process development demand for manual and semi-automated equipment tiers.
Sterile Fill-Finish Process Simulation and Media Fill Test Equipment Market Competitive Landscape
Player mix skews toward integrated packaging specialists with captive fill-finish validation capabilities, creating tiered competition between full-line integrators and component-focused suppliers. European and North American fabricators dominate premium isolator-integrated platforms, while Asian manufacturers capture cost-sensitive semi-automated segments. Strategic archetypes include barrier system integrators, containment closure specialists, and modular equipment architects. Competitive moves center on technology licensing partnerships and geographic expansion through validation service networks.
Among European full-line integrators, Syntegon Technology and I.M.A. S.P.A. occupy positions within the isolator-integrated platform tier, representing archetypes of barrier system specialization and modular equipment architecture respectively. West Pharmaceutical Services exemplifies the containment closure specialist archetype, anchoring process simulation fidelity extension into primary packaging. These three entities sit within distinct competitive vectors—equipment integration, modularity, and packaging continuity—that collectively define the market's structural segmentation.
| Leading Market Players |
|---|
| Syntegon Technology |
| I.M.A. S.P.A. |
| West Pharmaceutical Services |
| Gerresheimer AG |
| AptarGroup |
| BD |
| Dätwyler Holding |
| Bausch+Ströbel |
| Tofflon |
| Others |
Pricing and Supply Chain Analysis
Isolator-grade 316L stainless steel displacing conventional fabrication materials is simultaneously concentrating procurement leverage among German and Swiss mill operators while compressing margin structures for equipment OEMs facing extended lead times. This substitution dynamic forces buyers into early commitment contracts that lock pricing before fabrication begins, creating tiered access based on volume scale and relationship tenure.
Pricing Analysis
Certification level (ISO/CE/FDA-grade) creates the primary spread between equipment tiers, with Annex 1-validated isolator platforms commanding substantial premiums over legacy laminar flow configurations. Pricing stratifies across premium isolator-integrated systems, standard semi-automated platforms, and economy manual units based on automation depth and validation bundle inclusion. Cost compression in the manual tier is intensifying because research institutes face budget constraints and extended replacement cycles. Contract manufacturing organizations exhibit the least price sensitivity due to customer audit intensity, while academic laboratories demonstrate acute sensitivity to capital expenditure thresholds.
Supply Chain Analysis
Inventory cycles for isolator-grade 316L stainless steel now stretch 12-18 months, compressing equipment delivery schedules and forcing buyers into speculative procurement positions. Supply concentrates in German, Swiss, and Italian specialty mills that serve pharmaceutical fabrication, with secondary sourcing from Japanese and South Korean producers for standard-grade components. Equipment fabrication draws from electropolished stainless steel, HEPA filtration media, and robotic handling subsystems as critical inputs. Single-source vulnerability in European mill capacity creates exposure to energy cost volatility and trade restriction scenarios. Distribution runs through direct OEM relationships for automated platforms and regional distributor networks for manual equipment tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is approaching a platform-economics inflection where interoperability between isolator hardware and real-time microbial detection software determines competitive positioning. EMA-FDA regulatory divergence is fragmenting validation protocols and creating ecosystem lock-in effects that favor early standard-setters.
For Market Incumbents: Consolidate validation service capabilities through acquisition of specialized smoke study and environmental monitoring consultancies to capture the unbundling trend in United States procurement. Annex 1's format-change requirements threaten margin compression for equipment-only vendors, making backward integration into protocol development a defensive necessity. Capacity addition in Indian validation service networks captures CDSCO-PIC/S alignment tailwinds before local competitors establish positions. For New Entrants and Emerging Players: Post-qualification support gaps where incumbents under-serve mid-scale CMOs represent the most penetrable white-space target, particularly for isolator decontamination cycle optimization and biological indicator placement services. India's emerging biopharma clusters offer the least contested geography for validation-centric market entry. A service-first go-to-market angle—contracting media fill protocol development before equipment sale—sidesteps capital intensity barriers while building captive equipment demand. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed CMOs that consolidated during pandemic-era capacity expansion and now face dense media fill schedules under Annex 1. Long-term viability hinges on isolator-integrated platform penetration rates in European vaccine manufacturing over a five-to-ten year horizon. Acquisition targets should display captive validation capabilities or modular equipment architectures compatible with single-use hybridization. The signal to watch is FDA-EMA regulatory convergence or divergence on physical barrier definitions, which would accelerate or delay replacement cycle compression.| Strategic Initiative | Industry Significance |
|---|---|
| Validation Service Network Expansion | Captures unbundled procurement trends among United States pharmaceutical manufacturers facing FDA inspection intensity. |
| Modular Equipment Architecture Development | Enables flexible batch formats for Swiss monoclonal antibody and cell therapy pipeline diversification. |
| Isolator-Integrated Platform Launch | Satisfies EMA Annex 1 closed-barrier mandates that eliminate open cleanroom configurations in German facilities. |
| Single-Use Technology Hybridization | Accommodates emerging gene therapy pipelines requiring rapid changeover capabilities in United States coastal clusters. |
| Geographic Expansion into India | Exploits CDSCO-PIC/S alignment opening validation service markets as domestic biologics manufacturing scales. |
Research Methodology
Initial hypotheses were tested against primary input from fill-finish operations directors, validation engineering leads, regulatory affairs specialists, and CMO procurement managers and refined through secondary validation against FDA guidance documents, EMA Annex 1 submissions, ISO 14644 cleanroom standards, and pharmaceutical trade association technical reports. Bottom-up triangulation across equipment shipment data and top-down cross-checks against capital expenditure disclosures anchored volume estimates. Primary fieldwork concentrated on German, Swiss, United States, and Indian pharmaceutical manufacturing clusters.
Variance decomposition across product type, application, end user category, technology platform, and regional regulatory cluster shaped the analytical framework. CAGRs were derived from segmented growth trajectory modeling rather than single-point extrapolation. Forecast inputs incorporated isolator adoption curves in European vaccine manufacturing, biologics capacity expansion timelines at contract manufacturing organizations, and regulatory inspection frequency trends affecting equipment replacement cycles. Outputs reflect constant-currency assumptions excluding inflation effects.
Forecasts assume regulatory continuity in EMA Annex 1 implementation and FDA aseptic processing guidance; material policy shifts around physical barrier definitions or media fill frequency requirements would necessitate re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
Pharmerging Contract Manufacturing Market
Pharmaceutical Equipment
Vials and Ampoules Market
Pharmaceutical Equipment
Pharmaceutical Glass Ampoules Market
Pharmaceutical Equipment
Europe Pharmacy Automation Market
Pharmaceutical Equipment
Pharmaceutical Equipment Testing Market
Pharmaceutical Equipment
Radiochemical Synthesizers Market
Pharmaceutical Equipment
Radiosynthesis Equipment Market
Pharmaceutical Equipment
Pharmaceutical CDMO Market
Pharmaceutical Equipment
Japan Contract Development and Manufacturing Organization Market
Pharmaceutical Equipment
US Depyrogenated Sterile Empty Vials Market
Pharmaceutical Equipment
India Contract Manufacturing Organization (CMO) Market
Pharmaceutical Equipment
Latin America Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
Global Pharmaceutical Membrane Filtration Market
Pharmaceutical Equipment
Pharmaceutical Continuous Manufacturing Market
Pharmaceutical Equipment
Pharmaceutical Cleaning Validation Market
Pharmaceutical Equipment
Asia-Pacific Pharmaceutical Isolator Market