
 Keratitis Treatment Market | 2026-2036
Keratitis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Keratitis Treatment Market Foresight
The EU MDR framework for ophthalmic medical devices is pivoting manufacturers toward enhanced clinical evidence requirements for sustained market access. Novartis International AG leverages its integrated eye care portfolio to anchor positions across both pharmaceutical and surgical keratitis interventions. Santen Pharmaceutical Co., Ltd. specializes in ophthalmology-exclusive R&D pipelines that differentiate its topical therapeutic offerings. Bausch Health Companies Inc. controls extensive distribution networks across North American and European eye care channels.
Keratitis treatment encompasses pharmacological and surgical interventions targeting corneal inflammation caused by bacterial, viral, fungal, or parasitic pathogens, with topical formulations typically requiring preserved or preservative-free compositions at specific pH ranges to maintain epithelial compatibility. The primary purpose centers on eliminating infectious agents, reducing inflammatory damage, and preserving visual acuity. Antibiotics and antiviral agents dominate current prescription volumes due to established efficacy against bacterial and herpetic keratitis, while artificial tears represent a mature, high-frequency segment driven by chronic dry eye comorbidities. Ophthalmic surgery as a delivery mode captures concentrated margin pools from severe ulcerative cases requiring therapeutic keratoplasty or amniotic membrane transplantation.
The FDA maintains stringent chemistry, manufacturing, and controls standards for ophthalmic solutions, while the EMA's MDR requirements impose additional post-market surveillance obligations on European suppliers. Health Canada and Japan's PMDA enforce comparable sterility and endotoxin thresholds that shape formulation development costs and timeline risk. Stakeholders must monitor regulatory divergence between major jurisdictions when prioritizing pipeline investments and manufacturing location strategies.
Market Dynamics
Hospital-based ophthalmology departments are expanding their adoption of advanced keratitis management protocols. The FDA's evolving guidance on ophthalmic drug formulations is reshaping product development pathways for manufacturers.
Growth Catalysts
- Specialized Corneal Care Centers:The United States concentrates demand through dedicated treatment facilities that drive premium therapy uptake and complex case referrals.
- EU MDR Framework:Enhanced clinical evidence requirements for ophthalmic medical devices are pivoting manufacturers toward sustained market access investments.
- Advanced Surgical Protocols:Therapeutic keratoplasty and amniotic membrane transplantation are capturing concentrated margin pools from severe ulcerative cases.
Market Restraints
- Formulation Development Costs:Stringent chemistry, manufacturing, and controls standards from the FDA, EMA, PMDA, and Health Canada inflate timeline risk and capital requirements.
- Preservative Compatibility Constraints:Topical formulations must maintain specific pH ranges for epithelial compatibility, limiting excipient options and manufacturing flexibility.
- Antibiotic Segment Maturity:Established efficacy of bacterial keratitis treatments creates pricing pressure and compresses innovation returns for new entrants.
Strategic Opportunities
- Preservative-Free Compositions:Chronic dry eye comorbidities are driving demand for artificial tears with advanced formulation architectures.
- Post-Market Surveillance Differentiation:European suppliers leveraging MDR compliance as a competitive moat against less prepared competitors.
- Distribution Network Control:North American and European eye care channels offer consolidation potential for integrated supply chain operators.
Industry Challenges
- Regulatory Divergence Monitoring:Stakeholders must track chemistry and sterility threshold variations between FDA, EMA, PMDA, and Health Canada when prioritizing pipeline investments.
- Manufacturing Location Strategy:Endotoxin and sterility requirements shape facility siting decisions and cross-border supply chain complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Keratitis Treatment Market |
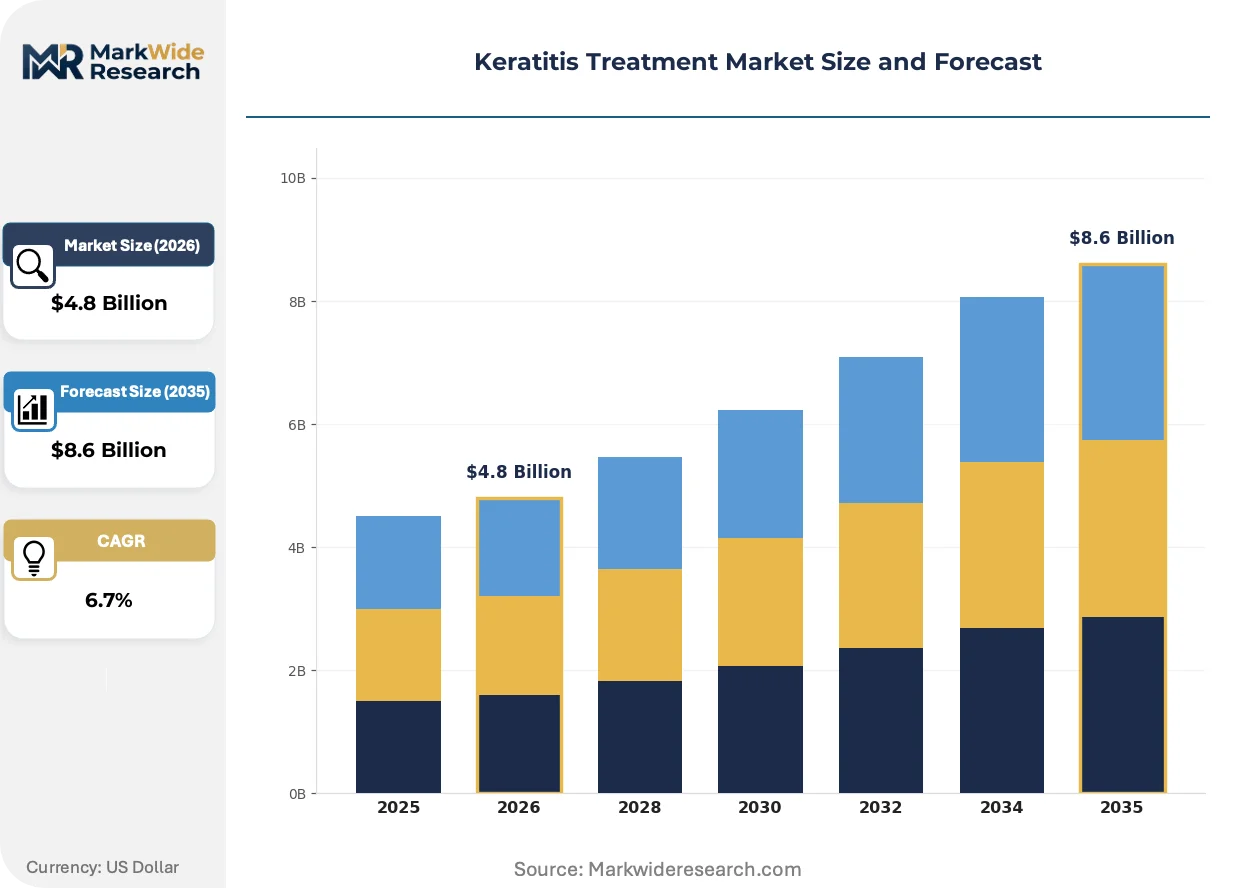
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Antiviral Agents, Corticosteroids, Artificial Tears Delivery Mode: Topical, Injectable, Oral, Ophthalmic Surgery End User: Hospitals, Clinics, Homecare, Ambulatory Surgical Centers Therapy Area: Infectious Keratitis, Acanthamoeba Keratitis, Viral Keratitis, Ulcerative Keratitis |
| Companies Covered | Novartis International AG, Allergan, Inc., Santen Pharmaceutical Co., Ltd., Akorn, Inc., Bausch Health Companies Inc., Johnson & Johnson Vision, Pfizer Inc., Merck & Co. Inc., Glenmark Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Keratitis Treatment Market Shifts & Advancements
Topical therapeutic architectures are undergoing fundamental reformulation as manufacturers respond to epithelial compatibility demands and preservative sensitivity profiles. Three intersecting developments are reconfiguring competitive positioning in corneal care.
Preservative-free ophthalmic solutions are consolidating market share among chronic dry eye populations and repeat-use patients. Hospital outpatient departments and specialized corneal clinics are accelerating adoption of these formulations to minimize epithelial toxicity. The technology is consolidating high-frequency artificial tear segments previously dominated by preserved alternatives.
EMA's Medical Device Regulation is tightening post-market surveillance obligations for European ophthalmic suppliers. Manufacturers must now maintain enhanced clinical evidence portfolios to sustain CE marking and market access. Surgical intervention categories including therapeutic keratoplasty face the steepest compliance cost escalations.
Integrated eye care portfolios are displacing standalone product strategies among major therapeutic developers. Procurement departments at academic medical centers are consolidating vendor relationships to secure bundled pharmaceutical and surgical supply agreements. This concentration is most visible across United States corneal care networks where volume commitments drive preferential pricing structures.
Keratitis Treatment Market Segmentation
Keratitis treatment segments diverge sharply by clinical setting and therapeutic intensity. Product formulations must balance efficacy against epithelial toxicity across acute and chronic use cases. Each category reflects distinct procurement patterns and margin structures.
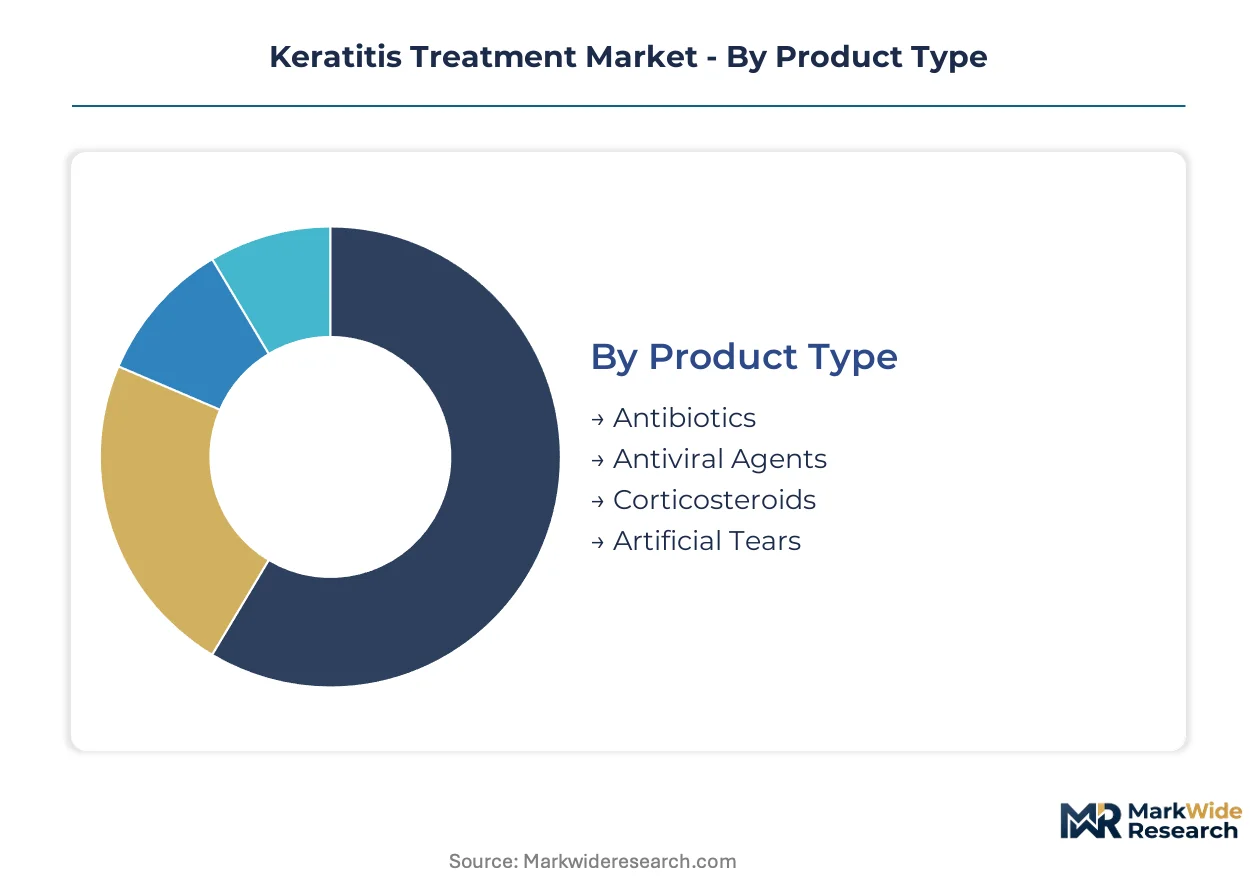
Product Type:
Standardization dominates antibiotics and antivirals with established clinical protocols, while artificial tears and corticosteroid formulations allow greater customization for chronic comorbidity management.
- Antibiotics:Fluoroquinolone and aminoglycoside formulations target bacterial pathogens with established minimum inhibitory concentration standards. Hospital pharmacies in the United States stock these as first-line therapy for contact lens-related infections, though generic substitution compresses margins.
- Antiviral Agents:Ganciclovir and trifluridine preparations address herpetic keratitis with specific corneal penetration requirements. Specialized corneal clinics drive prescription volume where recurrent epithelial disease necessitates long-term suppressive protocols.
- Corticosteroids:Post-infectious inflammation control requires tapered dosing regimens.
- Artificial Tears:Preservative-free architectures command premium positioning for dry eye overlap populations.
Most installed capacity flows through Antibiotics. Expansion is steepest in Artificial Tears.
Delivery Mode:
Cost tiering separates high-frequency topical replenishment from capital-intensive surgical intervention, with oral and injectable routes occupying intermediate reimbursement bands.
- Topical:Eye drops and ointments deliver localized drug concentrations with minimal systemic exposure. FDA sterility requirements for multidose containers shape manufacturing location decisions and endotoxin testing protocols.
- Ophthalmic Surgery:Therapeutic keratoplasty and amniotic membrane transplantation address perforated or non-healing ulcers. Academic medical centers in Boston and Baltimore concentrate case volume where bundled payments align surgical and pharmaceutical procurement.
- Injectable:Intravitreal or subconjunctival routes serve severe cases with poor topical penetration.
- Oral:Systemic agents supplement topical therapy for deep stromal involvement.
Topical formulations absorb the highest prescription frequency. Ophthalmic Surgery captures the steepest expansion trajectory as severe case referrals concentrate.
End User:
Customer type stratification places hospital purchasing coalitions against fragmented homecare channels, with ambulatory surgical centers occupying a hybrid reimbursement position.
- Hospitals:Inpatient and emergency departments manage severe infectious keratitis with 24-hour pharmacy coverage. The Joint Commission antimicrobial stewardship requirements influence formulary decisions and restrict empirical broad-spectrum use.
- Ambulatory Surgical Centers:Same-day surgical facilities perform therapeutic keratoplasty with lower overhead than hospital operating rooms. Medicare site-of-service differentials are accelerating case migration to these settings in Florida and Texas markets.
- Clinics:Private ophthalmology practices handle routine bacterial and viral cases.
- Homecare:Self-administered artificial tears and maintenance antibiotics extend therapy beyond clinical settings.
Hospitals retain the deepest installed capacity. Ambulatory Surgical Centers are gaining share fastest as site-of-service economics shift.
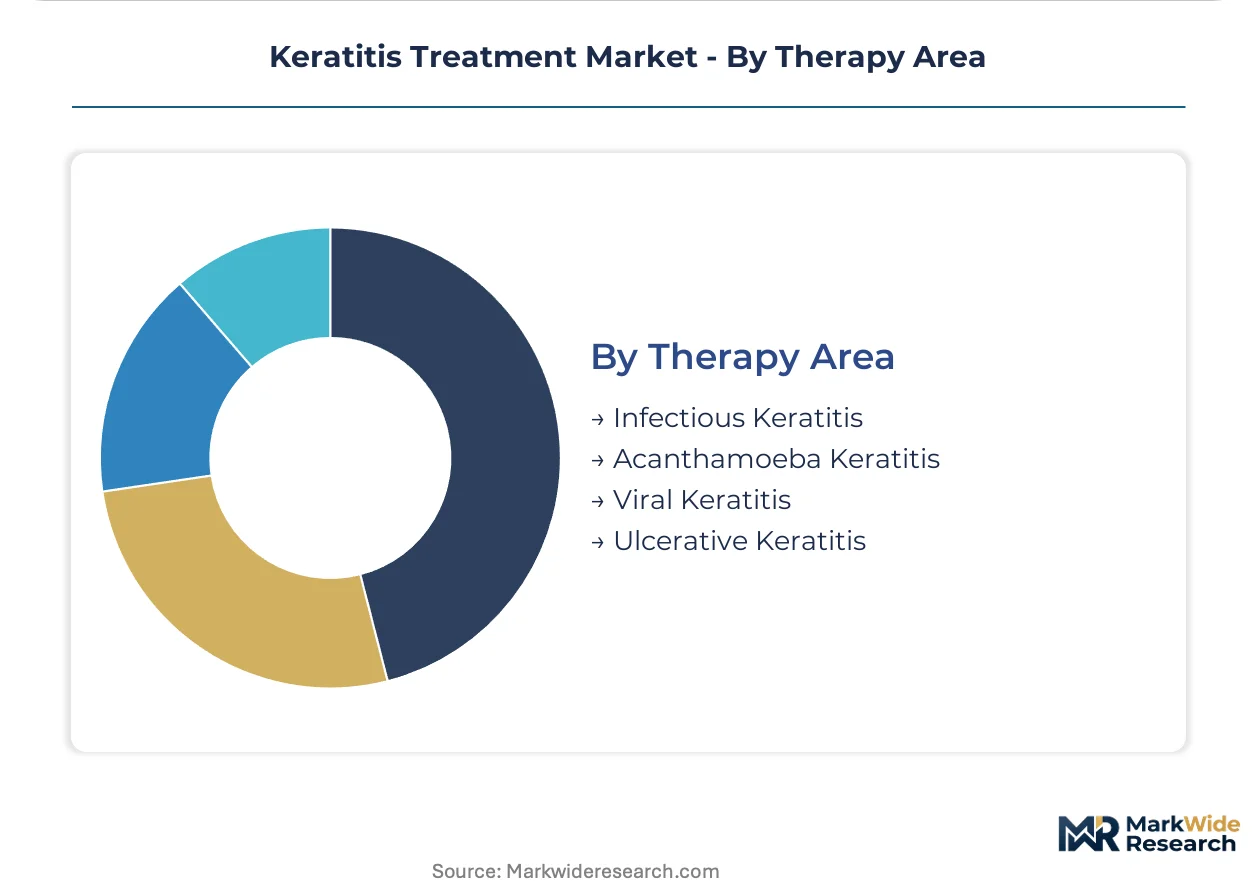
Therapy Area:
Maturity gradients separate well-characterized bacterial and viral indications from emerging protocol development in parasitic and severe ulcerative subtypes.
- Infectious Keratitis:Bacterial, fungal, and mixed microbial infections constitute the largest addressable population. CDC surveillance data tracks contact lens-associated Pseudomonas outbreaks, driving public health screening investments.
- Ulcerative Keratitis:Peripheral or central corneal thinning risks perforation and vision loss. Bascom Palmer Eye Institute and Wilmer Eye Center generate referral networks for complex medical and surgical management.
- Viral Keratitis:Herpes simplex and varicella-zoster reactivation requires chronic suppressive strategies.
- Acanthamoeba Keratitis:Contact lens hygiene failures propagate this difficult-to-diagnose parasitic infection.
Infectious Keratitis channels the highest patient volume. Ulcerative Keratitis shows the steepest expansion as advanced surgical protocols proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Keratitis treatment protocols first achieved systematic standardization in post-war United States academic medical centers, with subsequent diffusion to European and Asian ophthalmology networks establishing the current geographic footprint.
United States
Specialized corneal care centers in Boston, Baltimore, and Miami drive premium therapy uptake and complex case referrals. FDA chemistry, manufacturing, and controls standards for ophthalmic solutions shape formulation development timelines and capital requirements. Bascom Palmer Eye Institute and Wilmer Eye Center generate concentrated referral networks for severe ulcerative keratitis requiring therapeutic keratoplasty.
Germany
University hospital ophthalmology departments in Heidelberg and Tübingen anchor advanced surgical protocol adoption across Central Europe. EMA Medical Device Regulation post-market surveillance obligations impose enhanced clinical evidence requirements on European suppliers. The Rhine-Main cluster concentrates pharmaceutical manufacturing capacity serving both domestic and export markets.
Japan
PMDA sterility and endotoxin thresholds comparable to FDA standards shape domestic formulation development costs. Tokyo and Osaka metropolitan areas concentrate specialized corneal clinics managing herpetic keratitis with long-term suppressive protocols. Domestic manufacturers prioritize preservative-free architectures for chronic dry eye overlap populations.
India
Contact lens-associated Pseudomonas outbreaks drive public health screening investments and first-line antibiotic demand. CDSCO regulatory pathways for ophthalmic drugs create timeline considerations for multinational market entry. Mumbai and Hyderabad clusters concentrate generic antibiotic manufacturing serving price-sensitive domestic and export markets.
Switzerland
Swissmedic oversight of ophthalmic medical devices aligns with EU MDR frameworks while maintaining distinct approval pathways. Basel and Zurich host integrated eye care portfolio operations spanning pharmaceutical and surgical interventions. The country's precision manufacturing base supports preservative-free formulation technologies for European distribution.
Keratitis Treatment Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and surgical intervention intensity. The vendor base stratifies between integrated pharmaceutical-surgical portfolios and standalone topical therapeutic specialists. Three archetypes dominate: diversified eye care conglomerates with bundled procurement offerings, ophthalmology-exclusive developers with preservative-free specialization, and generic manufacturers capturing high-volume antibiotic substitution. Competitive moves concentrate on M&A for portfolio integration and geographic expansion into specialized corneal care networks.
Within the integrated portfolio tier, Novartis International AG and Bausch Health Companies Inc. exemplify the conglomerate archetype spanning both pharmaceutical and surgical keratitis interventions. Santen Pharmaceutical Co., Ltd. occupies a specialist position as an ophthalmology-exclusive developer with differentiated topical therapeutic offerings. These three companies represent the dominant strategic configurations in the current competitive structure.
| Leading Market Players |
|---|
| Novartis International AG |
| Allergan, Inc. |
| Santen Pharmaceutical Co., Ltd. |
| Akorn, Inc. |
| Bausch Health Companies Inc. |
| Johnson & Johnson Vision |
| Pfizer Inc. |
| Merck & Co. Inc. |
| Glenmark Pharmaceuticals |
| Others |
Supply & Pricing Matrix
Captive manufacturing of preservative-free formulations in Switzerland and Germany anchors supply positioning and pricing power for European ophthalmic suppliers facing EMA MDR compliance costs. This integration choice insulates premium-tier players from generic substitution pressure while concentrating margin capture among vertically integrated portfolios.
Pricing Analysis
Three-tier pricing structure across premium preservative-free, standard preserved, and economy generic tiers separates patient populations by chronicity and reimbursement access. Price differentiation rests on FDA certification tier and volume scale through hospital purchasing coalitions. Cost compression in the antibiotic segment is intensifying because generic substitution runs through United States hospital formularies. Homecare channels show highest price sensitivity; academic medical centers demonstrate lowest sensitivity due to bundled procurement agreements.
Supply Chain Analysis
Dual-sourcing requirements from United States hospital purchasing coalitions mandate multi-supplier qualification for critical topical formulations. Manufacturing concentrates in Switzerland, Germany, and the United States for preservative-free architectures. Raw material dependencies include pharmaceutical-grade hyaluronic acid, boric acid buffers, and endotoxin-tested packaging components. Single-source vulnerability sits with specialized filter membrane suppliers for sterile filling operations. Distribution runs through integrated eye care distributors and direct hospital contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in preservative-free formulation segments where chronic dry eye comorbidities justify premium positioning and manufacturing scale economies reduce unit costs.
For Market Incumbents: To counter generic substitution pressure in fluoroquinolone antibiotics, deepen backward integration into active pharmaceutical ingredient sourcing and secure exclusive formulary placement through therapeutic keratoplasty bundling at Bascom Palmer and Wilmer referral networks. For New Entrants and Emerging Players: Capture white-space in preservative-free artificial tears for contact lens wearers and Acanthamoeba keratitis diagnostics where protocol standardization remains incomplete. Prioritize direct-to-specialist-corneal-clinic distribution to bypass consolidated hospital purchasing. For Investors and Strategic Acquirers: Roll-up economics work for ophthalmology-exclusive developers because EMA MDR compliance costs are displacing standalone European suppliers. Five-to-ten-year viability favors preservative-free formulation specialists with Swissmedic-aligned manufacturing. Watch FDA guidance evolution on ophthalmic drug-device combinations as inflection signal for surgical intervention valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Preservative-Free Formulation Development | EMA MDR compliance creates competitive moat for early movers in chronic dry eye segments. |
| Hospital System Partnership | Bascom Palmer and Wilmer referral networks concentrate severe case volume and bundled procurement leverage. |
| CE Marking Pathway Investment | Enhanced clinical evidence portfolios sustain market access under tightened post-market surveillance obligations. |
| Backward Integration into API Supply | Captive sourcing of pharmaceutical-grade excipients insulates margin from commodity volatility and qualification delays. |
| Reimbursement Strategy Development | Medicare site-of-service differentials accelerate case migration to ambulatory surgical centers in Florida and Texas. |
Research Methodology
Bottom-up hospital and clinic modeling reconciled against top-down pharmaceutical and surgical supply tracking forms the analytical core of this study. Primary interviews with formulary directors, corneal specialists, regulatory affairs leads, and GPO contracts managers combined with secondary validation from FDA 510(k) filings, EMA CE marking databases, ClinicalTrials.gov, and hospital procurement records. Triangulation across these sources anchors volume and value estimates.
Input-output matrices connect patient population incidence, treatment protocol penetration, and pricing tier adoption across product type, delivery mode, end user, and therapy area dimensions. CAGRs derive from segmented growth rate reconciliation against macro healthcare expenditure trends. Forecast inputs include FDA guidance trajectory on ophthalmic formulations and EMA MDR implementation pace.
Regulatory approval delays, reimbursement policy shifts, and infectious disease outbreak patterns are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions about protocol adoption curves and manufacturing capacity expansion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Japan Ophthalmic Devices and Drugs Market
Ophthalmology
Global Automated Ophthalmic Perimeters Market
Ophthalmology
Optic Nerve Glioma Market
Ophthalmology
India Ophthalmology Devices Market
Ophthalmology
Ophthalmic Eye Drops Market
Ophthalmology
Conjunctivitis Market
Ophthalmology
Ophthalmic Suspension Market
Ophthalmology
Global Ophthalmic Sutures Market
Ophthalmology
Nystagmus Market
Ophthalmology
Global Uveitis Treatment Market
Ophthalmology
Global Advanced Ophthalmology Technologies Market
Ophthalmology
Neovascular Age-Related Macular Degeneration Treatment Market
Ophthalmology
UAE Ophthalmic Devices Market
Ophthalmology
Ptosis Treatment Market
Ophthalmology
United Kingdom Ophthalmology Devices Market
Ophthalmology
North America Vision Care Market