
 Epidemic Keratoconjunctivitis Treatment Market | 2026-2036
Epidemic Keratoconjunctivitis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Epidemic Keratoconjunctivitis Treatment Market Foresight
FDA guidance on adenoviral conjunctivitis endpoints is shifting the cost-of-entry calculus for developers seeking ophthalmic anti-infective approvals. Bausch + Lomb Corp leverages its established ophthalmic manufacturing infrastructure to sustain formulary positioning across retail and institutional channels. Alcon AG competes through specialized ophthalmic drop formulations that anchor its presence in acute viral eye infection protocols. Novartis AG differentiates via R&D intensity in antiviral ophthalmology, extending its pipeline into next-generation topical interventions.
Epidemic keratoconjunctivitis treatment encompasses pharmaceutical and therapeutic interventions targeting acute adenoviral conjunctivitis, a highly contagious ocular surface infection transmitted through direct contact, respiratory droplets, or contaminated fomites, with primary agents including topical antivirals, corticosteroids, and supportive lubricants formulated at pH-balanced osmolarity compatible with corneal epithelial integrity. The primary purpose centers on reducing viral shedding duration, mitigating pseudomembrane formation, and preventing corneal subepithelial infiltrates that threaten visual acuity in outbreak settings. Antiviral drugs occupy the leading therapeutic position given their direct mechanism against adenoviral replication, while ophthalmic drops dominate delivery mode preference due to targeted anterior segment bioavailability and patient compliance advantages in self-administration protocols. Home healthcare represents the fastest-growing end-user segment as post-acute monitoring and teleophthalmology integration reduce institutional dependency for non-complicated cases.
FDA ophthalmic anti-infective guidance, EMA MDR requirements for diagnostic-adjacent devices, and WHO outbreak response frameworks collectively shape product standards, trial design, and market access pathways across developed and emerging health systems. These regulatory layers elevate documentation burdens for novel entrants while reinforcing incumbent advantages among firms with established pharmacovigilance and quality management systems. Stakeholders must monitor evolving adenovirus typing protocols and point-of-care diagnostic reimbursement decisions that will determine whether treatment expansion outpaces the current forecast trajectory.
Market Dynamics
FDA's evolving guidance on adenoviral conjunctivitis trial endpoints is compressing development timelines while elevating documentation burdens, forcing developers to restructure clinical protocols around point-of-care diagnostic integration and viral shedding duration metrics rather than traditional symptom resolution benchmarks.
Growth Catalysts
- Point-of-Care Diagnostic Expansion:Rapid adenovirus typing protocols in ophthalmology clinics are shortening time-to-treatment decisions and expanding addressable patient volumes beyond traditional referral networks.
- Teleophthalmology Integration:Remote monitoring platforms for post-acute EKC cases are reducing institutional dependency and enabling home healthcare segment penetration.
- WHO Outbreak Response Frameworks:Standardized surveillance protocols in high-density infection zones are accelerating treatment protocol adoption across national health systems.
Market Restraints
- Antiviral Manufacturing Concentration:Active pharmaceutical ingredient supply for topical ophthalmic antivirals clusters among limited contract manufacturers in India and China, creating single-source vulnerability.
- EMA MDR Compliance Burden:Diagnostic-adjacent device classification for rapid adenovirus tests extends certification timelines and elevates quality management system costs for European market entry.
- Corticosteroid Substitution Risk:Off-label use of generic topical steroids for symptom management displaces branded antiviral prescriptions in cost-constrained payer environments.
Strategic Opportunities
- Home Healthcare Channel Development:Direct-to-patient delivery models for lubricant and antiviral combination therapies bypass traditional pharmacy intermediaries in United States metropolitan markets.
- Next-Generation Topical Formulations:pH-balanced osmolarity delivery systems compatible with corneal epithelial integrity represent unmet need in pediatric and contact lens-wearing populations.
- Dual Carbon Goals Alignment:China's NMPA incentive structures for sustainable manufacturing processes favor domestic producers investing in reduced-packaging ophthalmic drop presentations.
Industry Challenges
- Ocular Pharmacology Talent Scarcity:Specialized formulators with anterior segment bioavailability expertise command premium compensation, constraining mid-tier developer pipeline velocity.
- Legacy Diagnostic Integration Friction:Electronic health record compatibility gaps between rapid adenovirus testing platforms and hospital information systems delay point-of-care deployment in integrated delivery networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Epidemic Keratoconjunctivitis Treatment Market |
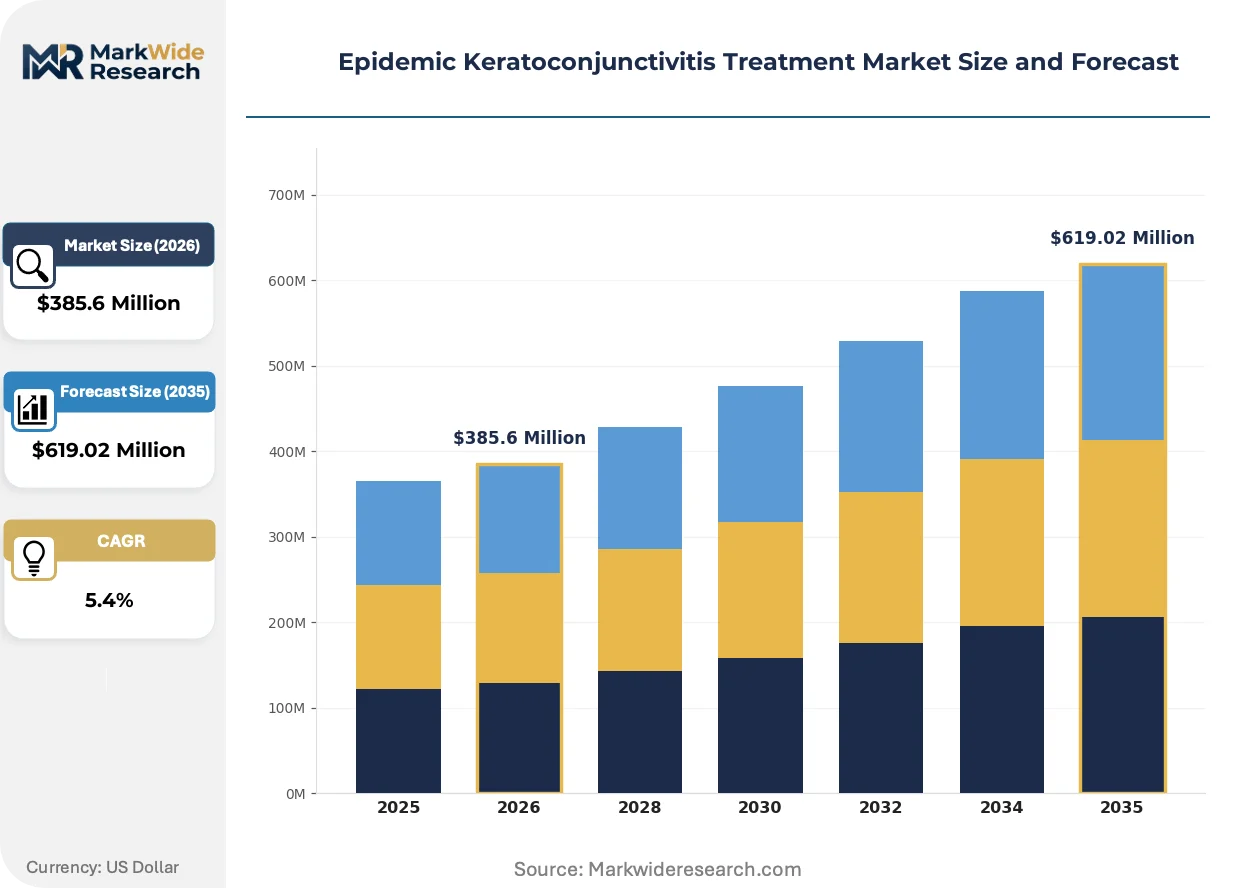
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $619.02 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antiviral Drugs, Antihistamines, Steroids, Antibiotics Delivery Mode: Topical Applications, Oral Solutions, Injectable, Ophthalmic Drops End User: Hospitals, Ophthalmology Clinics, Specialty Practices, Home Healthcare Distribution Channel: Pharmacies, Online Platforms, Hospital Pharmacies, Retail Clinics |
| Companies Covered | Bausch + Lomb Corp, Sandoz Group AG, Xenon Pharmaceuticals Inc, Rayner Group, Alcon AG, AbbVie Inc., Viatris Inc., Santen Pharmaceutical Co., Ltd, Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Epidemic Keratoconjunctivitis Treatment Market Shifts & Advancements
Adenoviral detection technology is compressing diagnostic latency from days to hours, while regulatory frameworks restructure trial endpoints and care delivery models shift toward decentralized monitoring protocols.
Multiplex PCR-based adenovirus typing is consolidating laboratory and near-patient testing workflows into unified platforms. Ophthalmology clinics in United States urban centers are adopting these systems at accelerated replacement cycles for legacy culture-based methods. This consolidation is collapsing the separate revenue streams for reference laboratories and enabling same-day treatment initiation in outbreak settings.
EMA's Medical Device Regulation requirements for diagnostic-adjacent ophthalmic devices are elevating clinical evidence standards for rapid viral detection platforms. Manufacturers must now submit prospective validation studies against composite reference standards rather than retrospective laboratory correlations. European ophthalmology networks are responding by consolidating procurement around pre-certified platform vendors with established quality management systems.
Post-acute monitoring responsibilities are migrating from institutional settings to home-based teleophthalmology protocols. Patients with resolving EKC receive automated symptom tracking applications that trigger specialist escalation based on corneal infiltrate progression algorithms. This behavioral shift is most pronounced in United States markets with established remote reimbursement codes and integrated payer-provider structures.
Epidemic Keratoconjunctivitis Treatment Market Segmentation
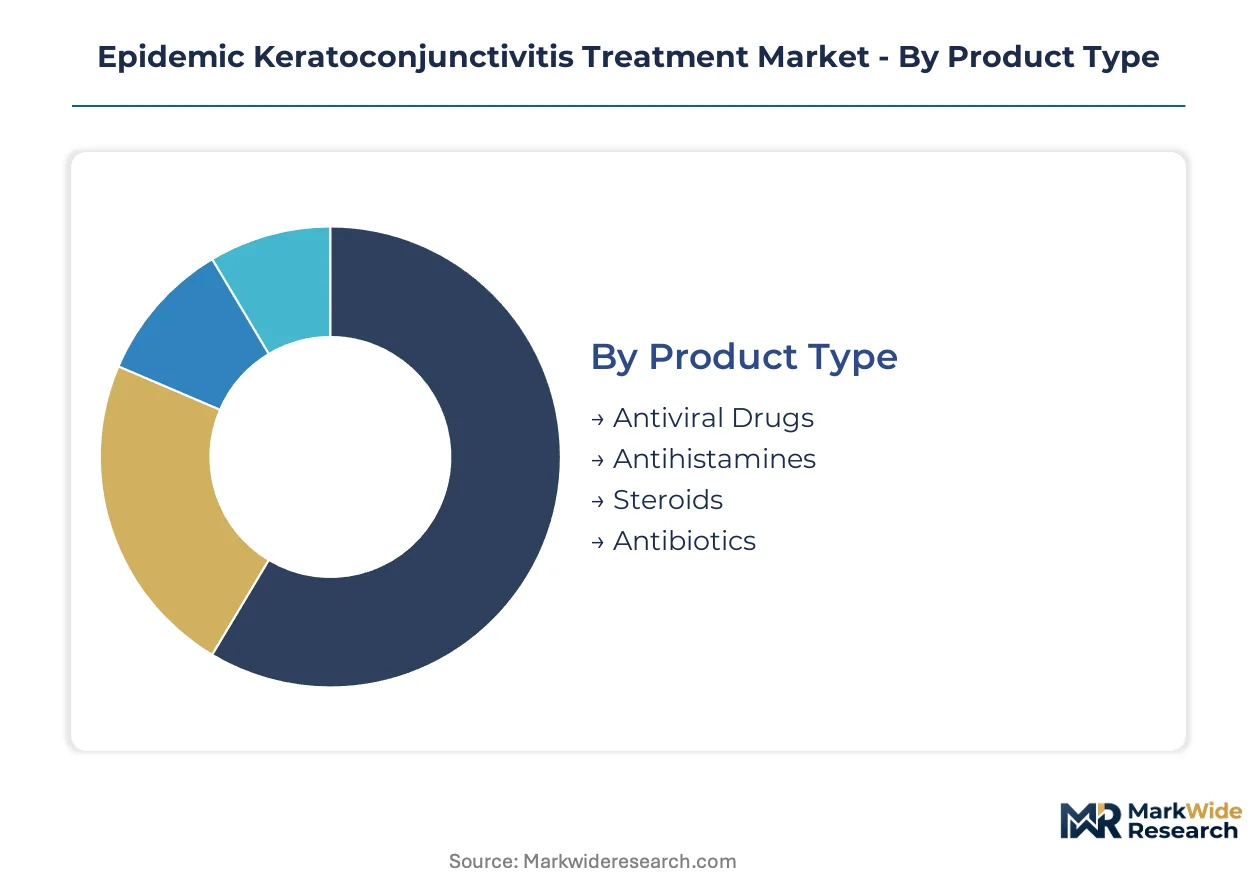
Treatment modality selection in epidemic keratoconjunctivitis follows distinct clinical pathways shaped by infection severity, corneal involvement risk, and patient self-administration capacity. Segmentation reveals how pharmaceutical formulators, delivery system engineers, and care delivery architects compete across differentiated value chains rather than undifferentiated commodity markets.
Product Type:
Clinician preference for mechanism-of-action specificity drives prescribing patterns across acute viral conjunctivitis protocols, with corneal preservation outcomes outweighing cost considerations in institutional settings.
- Antiviral Drugs:Direct-acting agents targeting adenoviral DNA polymerase replication machinery, formulated at concentrations balancing viral load suppression with epithelial toxicity thresholds. Demand concentrates in United States ophthalmology clinics where FDA-cleared protocols prioritize shedding duration reduction over symptom palliation alone. Point-of-care diagnostic reimbursement expansion accelerates same-day antiviral initiation.
- Steroids:Topical corticosteroid suspensions managing pseudomembrane inflammation and subepithelial infiltrate formation, requiring precise tapering regimens to avoid viral rebound. United States academic medical centers anchor volume given subspecialist oversight requirements for safe deployment. Off-label generic substitution threatens branded positioning in Medicaid-dominant markets.
- Antihistamines:H1-receptor antagonists providing symptomatic relief for concurrent allergic conjunctivitis presentations complicating adenoviral diagnosis.
- Antibiotics:Prophylactic bacterial coverage agents prescribed when corneal epithelial defects create secondary infection risk.
Antiviral drugs lead on scale; steroids lead on momentum given expanding subspecialist network penetration.
Delivery Mode:
Patient compliance mechanics and anterior segment bioavailability requirements shape formulation R&D investment allocation across ophthalmic delivery platforms.
- Ophthalmic Drops:Unit-dose preservative-free vials and multi-dose bottles delivering precise microliter volumes to the tear film, with pH-buffered osmolarity matching physiological ranges. United States home healthcare expansion drives volume as teleophthalmology protocols enable remote monitoring of self-administered regimens. Pediatric formulation gaps represent unmet need.
- Topical Applications:Ointment-based vehicles providing prolonged contact time for overnight corneal surface protection, particularly in contact lens-wearing populations experiencing mechanical irritation.
- Oral Solutions:Systemic antiviral agents reserved for severe bilateral presentations or immunocompromised patients with disseminated adenoviral infection.
- Injectable:Subconjunctival or intravitreal depot formulations for recalcitrant cases threatening visual acuity, restricted to hospital-based administration.
Ophthalmic drops dominate patient volume; home healthcare channel expansion accelerates self-administration platform adoption fastest.
End User:
Care setting selection follows disease severity stratification, with diagnostic capability and specialist availability determining patient routing across the acute-to-chronic continuum.
- Ophthalmology Clinics:Dedicated anterior segment practices equipped with slit-lamp biomicroscopy and rapid adenovirus typing platforms, enabling definitive diagnosis and targeted therapy initiation. United States metropolitan markets concentrate volume given subspecialist density and integrated payer-provider structures rewarding episode-of-care efficiency. Point-of-care diagnostic procurement cycles are compressing from five-year to three-year replacement intervals.
- Home Healthcare:Post-acute monitoring and medication adherence support for resolving cases, leveraging teleophthalmology platforms with automated symptom tracking algorithms. United States reimbursement code expansion for remote evaluation drives segment expansion. Lubricant and antiviral combination therapy direct delivery models bypass traditional pharmacy intermediaries.
- Hospitals:Emergency department and inpatient consultation services for severe presentations with pseudomembrane formation or visual acuity compromise.
- Specialty Practices:Optometry and urgent care settings with limited subspecialist backup, relying on clinical algorithms for presumptive treatment initiation.
Ophthalmology clinics lead on procedural revenue capture; home healthcare leads on volume growth trajectory given telehealth infrastructure maturation.
Distribution Channel:
Patient access convenience and formulary positioning power determine channel share allocation, with pharmacy benefit design steering behavioral patterns.
- Pharmacies:Community-based dispensing of generic antihistamines and lubricants, with branded antiviral access constrained by prior authorization requirements in commercial insurance plans.
- Hospital Pharmacies:Captive distribution for injectable and high-cost topical agents within integrated delivery networks, with 340B pricing advantages in United States safety-net institutions.
- Online Platforms:Direct-to-consumer lubricant and supplement sales, with prescription antiviral distribution limited to telehealth-integrated pharmacy services.
- Retail Clinics:Co-located dispensing within urgent care and big-box health settings, capturing convenience-driven demand for over-the-counter symptom management.
Hospital pharmacies lead on specialty agent margin capture; online platforms lead on consumer-directed volume expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized ophthalmology talent concentrates in metropolitan medical centers across five countries where diagnostic infrastructure and reimbursement frameworks determine treatment protocol adoption. Workforce density in anterior segment subspecialists shapes regional market penetration rates more than raw infection incidence.
United States
Ophthalmology clinic consolidation in urban corridors accelerates point-of-care diagnostic procurement cycles from five-year to three-year replacement intervals. FDA reimbursement code expansion for remote evaluation drives home healthcare segment penetration. The Boston-Cambridge cluster anchors teleophthalmology platform development for post-acute monitoring protocols.
Germany
Academic medical center networks in Baden-Württemberg and Bavaria standardize pseudomembrane management protocols across integrated delivery systems. EMA MDR compliance requirements for diagnostic-adjacent devices extend certification timelines for rapid adenovirus testing platforms. The Heidelberg-Mannheim corridor concentrates slit-lamp biomicroscopy manufacturing for anterior segment practices.
Japan
PMDA streamlined review pathways for ophthalmic anti-infectives compress regulatory timelines for topical antiviral submissions. Tokyo-Osaka metropolitan corridors concentrate subspecialist density and drive formulary positioning for preservative-free unit-dose formulations. Santen Pharmaceutical's domestic manufacturing infrastructure anchors regional supply security.
China
NMPA incentive structures for sustainable manufacturing processes favor reduced-packaging ophthalmic drop presentations in domestic production. Yangtze River Delta ophthalmology networks adopt rapid adenovirus typing protocols at accelerated replacement cycles. Shanghai's medical device registration consulting cluster facilitates dual carbon goals alignment for multinational entrants.
India
Contract manufacturing concentration for active pharmaceutical ingredients creates single-source vulnerability in topical ophthalmic antiviral supply. CDSCO harmonization with ICH guidelines accelerates clinical trial approval timelines for multinational sponsors. Hyderabad's bulk drug manufacturing cluster supplies generic corticosteroid intermediates for regional formulation.
Epidemic Keratoconjunctivitis Treatment Market Competitive Landscape
The competitive structure tilts toward diversified pharmaceutical conglomerates with established ophthalmic divisions rather than standalone eye care specialists. Incumbents leverage pharmacovigilance infrastructure and quality management systems to absorb FDA documentation burdens that constrain novel entrants. Two archetypes dominate: integrated eye care platforms with captive manufacturing and research-intensive pharmacos with antiviral pipelines. Competitive moves concentrate on point-of-care diagnostic integration partnerships and teleophthalmology platform licensing.
Among Swiss-headquartered research-intensive pharmacos, Novartis AG and its former eye care spin-off Alcon AG exemplify divergent strategic positioning within the same therapeutic domain. Bausch + Lomb Corp represents the integrated eye care platform archetype with manufacturing infrastructure spanning retail and institutional channels. These three anchors demonstrate how conglomerate origin shapes competitive capability allocation across the acute-to-chronic treatment continuum.
| Leading Market Players |
|---|
| Bausch + Lomb Corp |
| Sandoz Group AG |
| Xenon Pharmaceuticals Inc |
| Rayner Group |
| Alcon AG |
| AbbVie Inc. |
| Viatris Inc. |
| Santen Pharmaceutical Co., Ltd |
| Novartis AG |
| Others |
Supply & Pricing Matrix
United States ophthalmology clinic networks concentrate procurement power through consolidated group purchasing organizations, anchoring a contract-based pricing model where formulary positioning determines net realized prices across institutional and retail channels. FDA reimbursement code expansion for point-of-care diagnostics reinforces bundled service pricing, while generic corticosteroid substitution exerts downward pressure on branded antiviral margins in Medicaid-dominant markets.
Pricing Analysis
Bundled diagnostic-plus-therapy protocols command premium positioning against unbundled symptom-management alternatives in United States integrated delivery networks. Three-tier pricing structure across preservative-free unit-dose premium, multi-dose standard, and generic economy levels reflects formulation complexity and brand heritage. Cost compression in the steroid segment intensifies because off-label generic prescribing displaces branded antiviral initiation in cost-constrained payer environments. Hospital pharmacy buyers exhibit lowest price sensitivity given 340B pricing advantages and episode-of-care bundling, while retail clinic channels face highest sensitivity due to direct consumer out-of-pocket exposure.
Supply Chain Analysis
China's NMPA domestic-content incentives for sustainable manufacturing processes reshape active pharmaceutical ingredient sourcing toward Yangtze River Delta producers. Topical ophthalmic antiviral supply draws from contract manufacturing clusters in India and China, with corneal epithelium-compatible pH-buffer excipients sourced from Japanese and German specialty chemical producers. Single-source vulnerability concentrates in Indian API intermediates for adenoviral polymerase inhibitors. Distribution runs through hospital pharmacy captives for injectable and high-cost topical agents, while direct-to-patient models bypass traditional pharmacy intermediaries in home healthcare channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FDA guidance evolution on adenoviral conjunctivitis trial endpoints creates sustained demand for documentation-capable incumbents with established pharmacovigilance infrastructure.
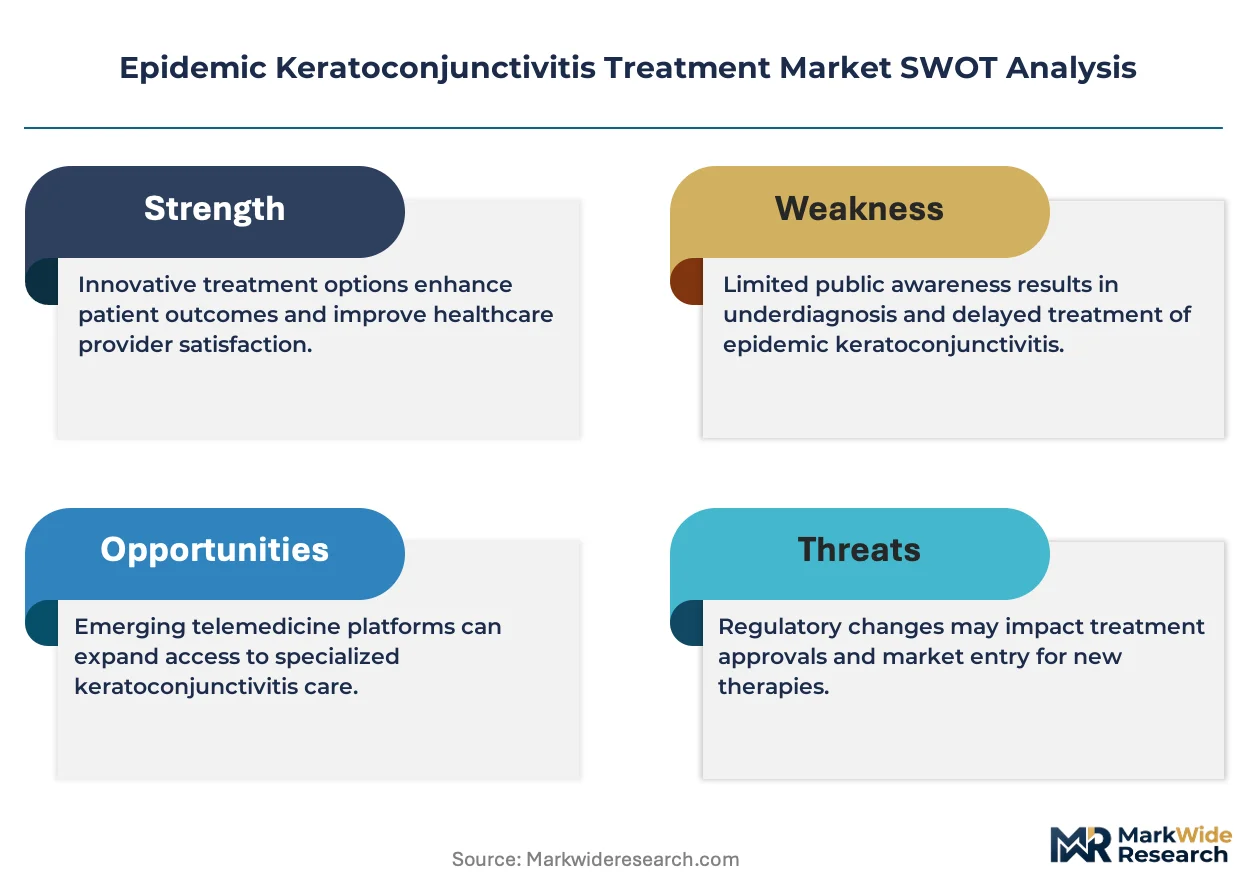
For Market Incumbents: Anticipate generic corticosteroid substitution threats by deepening backward integration into preservative-free formulation capacity and securing point-of-care diagnostic platform partnerships that lock in bundled protocol positioning. Prioritize quality management system investments that absorb EMA MDR compliance burdens constraining European market entry for mid-tier competitors. Channel control through teleophthalmology platform licensing represents the critical defensive lever against direct-to-patient disintermediation. For New Entrants and Emerging Players: Teleophthalmology platform providers offer the most accessible channel partnership avenue for bypassing entrenched hospital pharmacy gatekeepers. Pediatric formulation gaps in pH-balanced osmolarity delivery systems represent the most penetrable white-space target, given corneal epithelial toxicity concerns limiting adult antiviral repurposing. Home healthcare direct delivery models in United States metropolitan markets provide the specific go-to-market angle for lubricant-antiviral combination therapies. For Investors and Strategic Acquirers: Diversified pharmaceutical conglomerates with ophthalmic divisions are the most active acquirer in this space, seeking point-of-care diagnostic integration capabilities to complete acute-to-chronic treatment continuums. Long-term viability rests on regulatory documentation capacity rather than pipeline novelty alone, favoring targets with established FDA pharmacovigilance infrastructure over pre-revenue platform technologies. Reimbursement code expansion velocity for remote evaluation serves as the specific signal to watch for inflection in home healthcare segment economics.| Strategic Initiative | Industry Significance |
|---|---|
| Point-of-Care Diagnostic Integration | Bundled protocol positioning with Bausch + Lomb and Alcon formulary networks secures institutional channel lock-in. |
| Preservative-Free Formulation Scale-Up | Santen Pharmaceutical's domestic Japanese manufacturing anchors regional supply security against API concentration risk. |
| Teleophthalmology Platform Licensing | Boston-Cambridge cluster development enables remote monitoring reimbursement capture in United States metropolitan markets. |
| EMA MDR Quality System Investment | Pre-certified diagnostic platform vendors consolidate European procurement around established quality management systems. |
| Pediatric pH-Balanced Formulation R&D | Corneal epithelial integrity compatibility addresses unmet need in contact lens-wearing and pediatric populations. |
Research Methodology
Bottom-up ophthalmology clinic and home healthcare demand modeling reconciled against top-down API manufacturing and diagnostic platform supply tracking forms the analytical core of this study. Primary interviews with drug development executives, regulatory affairs leads, formulary directors at United States academic medical centers, and payer access specialists combined with secondary validation against FDA filings, ClinicalTrials.gov records, EMA submission databases, and hospital procurement contract repositories. Cross-referencing bottom-up patient volume estimates with top-down manufacturer shipment data enables triangulation across independent data streams.
Historical trendline analysis across antiviral prescription volumes, diagnostic platform replacement cycles, and teleophthalmology reimbursement code expansions establishes baseline growth patterns. Segmentation modeling spans treatment modality, delivery mode, end-user setting, and distribution channel dimensions across the projection horizon. CAGRs derive from regression-adjusted trend extrapolation incorporating regulatory milestone timing and point-of-care diagnostic procurement cycle compression. Industry-specific forecast inputs include adenovirus typing protocol adoption curves and remote evaluation reimbursement velocity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA guidance evolution on trial endpoints, EMA MDR implementation timelines, and API supply concentration disruptions. Analytical boundaries exclude systemic antiviral therapies for non-ocular adenoviral manifestations and surgical intervention for corneal sequelae. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Tobramycin Eye Drop Market
Ophthalmology
Global Optic Nerve Disorders Treatment Market
Ophthalmology
Ophthalmology Diagnostics and Surgical Devices Market
Ophthalmology
Global Macular Degeneration Treatment Market
Ophthalmology
Vernal Keratoconjunctivitis Market
Ophthalmology
Ophthalmology Devices Market
Ophthalmology
Aesthetic Ophthalmology Device Market
Ophthalmology
Global Aphakia Market
Ophthalmology
Europe Ophthalmology Market
Ophthalmology
Allergy Relieving Eye Drops Market
Ophthalmology
Ptosis Treatment Market
Ophthalmology
Global Ophthalmology Drugs and Devices Market
Ophthalmology
Eye Allergy Treatment Market
Ophthalmology
Uveal Melanoma Treatment Market
Ophthalmology
Artificial Iris Market
Ophthalmology
Trachoma Treatment Market