
 Diabetic Gastroparesis Treatment Market | 2026-2036
Diabetic Gastroparesis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Diabetic Gastroparesis Treatment Market Intelligence
Multi-source procurement for established antiemetic and prokinetic agents is shifting the competitive landscape for hospital pharmacies. In this environment, Eli Lilly and Company leverages its extensive background in diabetes management to develop integrated care solutions. Medtronic plc dominates the gastric electrical stimulation device segment through its technological leadership. Salix Pharmaceuticals Inc. specializes in gastroenterology-focused therapies, competing on clinical efficacy and relationships with specialist prescribers.
Diabetic gastroparesis treatment encompasses medical interventions designed to manage delayed gastric emptying, a complication of diabetes confirmed through methods like gastric emptying scintigraphy. The primary goal is to alleviate symptoms such as nausea, vomiting, and abdominal pain, thereby improving patient quality of life. Prokinetic agents constitute the foundational treatment type, though their use is often limited by side effects. The oral route of administration remains dominant for most drug-based therapies, while gastric electrical stimulation represents a key device-based intervention.
Regulatory pathways defined by the US Food and Drug Administration (FDA) and the European Medicines Agency (EMA) heavily influence drug development timelines and costs. Approval standards set by Japan's Pharmaceuticals and Medical Devices Agency (PMDA) also create specific market access requirements for novel therapies. Consequently, navigating the distinct clinical trial endpoints required by these bodies is critical for market participants. Stakeholders must monitor the progression of next-generation prokinetics and neuromodulation devices through these regulatory gates.
Market Dynamics
The central dynamic in the diabetic gastroparesis treatment market is the clinical tension between the high prevalence of debilitating symptoms and the limited efficacy and poor safety profiles of foundational prokinetic agents. This gap is compelling investment into novel drug mechanisms and non-pharmacological devices to meet urgent patient needs.
Growth Catalysts
- Novel Prokinetics:The development pipeline for agents with selective receptor targets, aiming to improve gastric motility without the cardiovascular or neurological side effects of older drugs, is a primary catalyst.
- Rising Diabetes Incidence:Increasing prevalence of Type 1 and Type 2 diabetes, particularly in developed nations like the United States and Germany, expands the underlying patient pool requiring gastroparesis management.
- Regulatory Incentives:Pathways like the FDA's Fast Track designation and the EMA's PRIME scheme can accelerate the review process for drugs that demonstrate potential to address significant unmet medical needs in gastroparesis.
Market Restraints
- Restrictive Drug Labels:Many prokinetic agents carry black box warnings or are limited to short-term use due to significant safety concerns, constraining their clinical utility and prescriber confidence.
- Diagnostic Challenges:Underutilization and limited access to definitive tests like gastric emptying scintigraphy result in frequent underdiagnosis or misdiagnosis, restricting the addressable patient population.
- High Off-Label Use:The widespread practice of using antiemetics and other symptomatic treatments off-label erodes the market for specifically approved, and often more expensive, gastroparesis therapies.
Strategic Opportunities
- Digital Health Integration:Combining gastric electrical stimulation devices with smartphone apps and wearable sensors presents an opportunity to provide real-time patient feedback and enable remote therapy optimization by clinicians.
- Pediatric Formulation Development:There is a distinct unmet need for developing safe and effective gastroparesis treatments specifically formulated and approved for the pediatric and adolescent diabetic populations.
- Biomarker Discovery:Identifying reliable biomarkers to predict treatment response would enable a personalized medicine approach, allowing clinicians to select the most effective therapy for individual patient profiles.
Industry Challenges
- Subjective Clinical Endpoints:Reliance on patient-reported symptom diaries in clinical trials introduces variability and complexity, making it difficult to demonstrate statistically significant efficacy to regulators like the FDA and PMDA.
- Payer Reimbursement Hurdles:Gaining favorable reimbursement status for new, high-cost device interventions and novel pharmaceuticals requires demonstrating substantial long-term value and quality-of-life improvements over existing standards of care.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diabetic Gastroparesis Treatment Market |
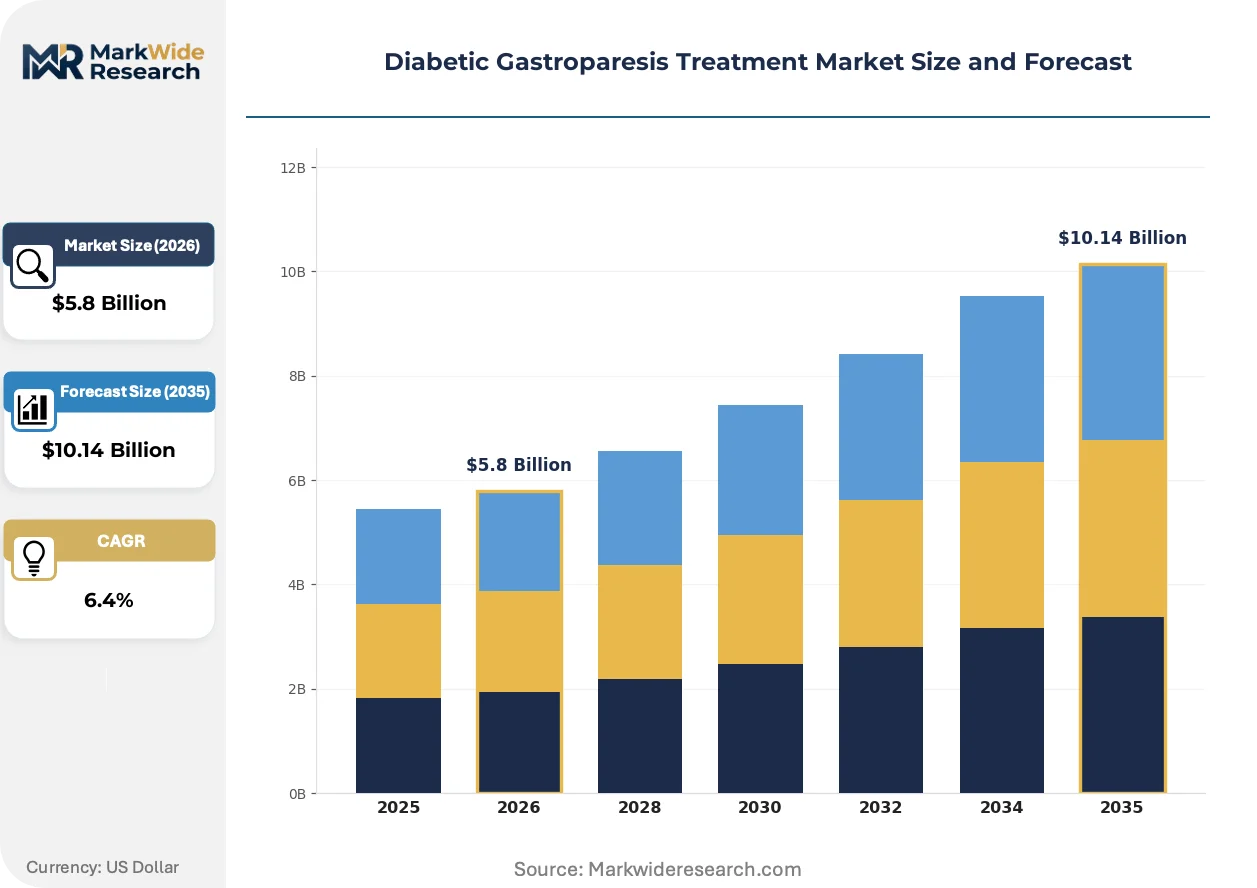
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Prokinetic Agents, Antiemetics, Gastric Electrical Stimulation, Botulinum Toxin, Nutritional Therapy Route of Administration: Oral, Intravenous, Subcutaneous Injection, Transdermal, Endoscopic Delivery End User: Specialty Clinics, Gastroenterologists, Ambulatory Surgery Centers, Long-term Care Facilities Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Direct Sales, Contract Manufacturing |
| Companies Covered | Salix Pharmaceuticals Inc., Medtronic plc, Abbott Laboratories, Eli Lilly and Company, Takeda Pharmaceutical Company Limited, AstraZeneca plc, Boston Scientific Corporation, Vanda Pharmaceuticals Inc., Evoke Pharma Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diabetic Gastroparesis Treatment Market Strategic Shifts & Innovations
The evolution of treatment is defined by a shift from broad-acting systemic drugs toward more targeted interventions. This includes advancements in neuromodulation and a refined regulatory focus on patient-centric outcomes, altering how therapeutic value is measured and developed.
Technology and Product Evolution
Gastric Electrical Stimulation (GES) provides targeted neuromodulation to the stomach via an implanted device. Specialty gastroenterology centers and hospital systems are adopting this technology for patients with severe, refractory symptoms. Originally a last-resort intervention, GES is expanding into a more established role within the therapeutic algorithm, offering a non-pharmacological alternative for managing intractable nausea and vomiting.
Regulatory and Policy Shifts
The US Food and Drug Administration's increasing emphasis on Patient-Reported Outcomes (PROs) as valid primary endpoints is a significant regulatory shift. This forces manufacturers to design clinical trials that measure improvements in symptoms and quality of life, rather than relying solely on objective metrics like gastric emptying speed. Consequently, developers of new therapies must now invest in validating and incorporating PRO instruments to meet approval requirements.
Demand and Behavioral Shifts
A notable behavioral shift is the move toward integrated diabetes care within large healthcare systems. Instead of isolated treatment by a gastroenterologist, endocrinology and primary care teams are becoming more involved in screening for and co-managing gastroparesis as a recognized diabetic complication. This trend is most prominent in the United States, where it aligns with value-based care models that incentivize holistic and preventative patient management.
Diabetic Gastroparesis Treatment Market Segmentation
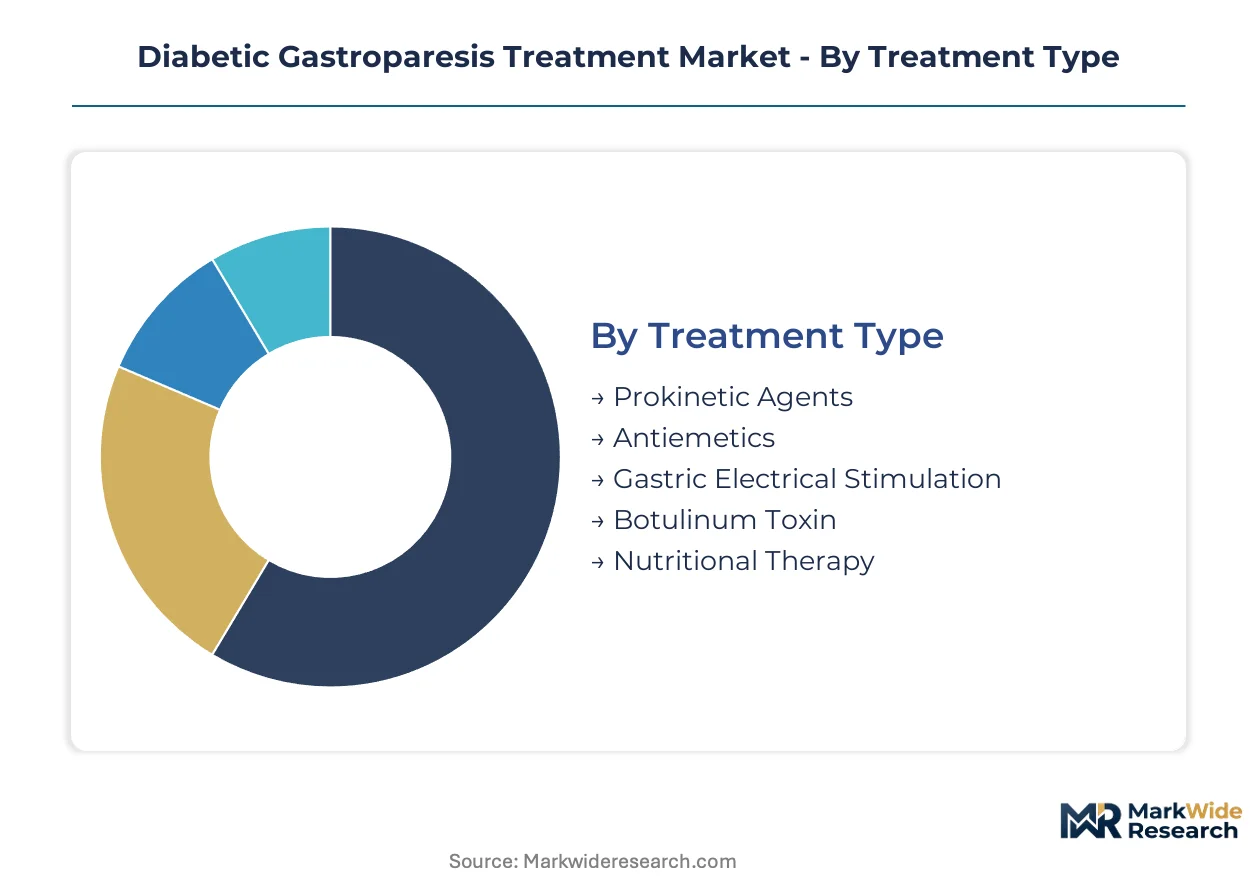
The diabetic gastroparesis treatment market segments reflect diverse therapeutic approaches and patient care settings. Understanding these distinct categories provides insight into where innovation is concentrating and how treatment modalities reach patients. Each segment addresses specific clinical needs or operational aspects within the broader gastroparesis management landscape.
Treatment Type:
The capital intensity of various treatment types significantly influences market investment and adoption. Device-based interventions typically require higher upfront costs for development and implementation compared to pharmaceutical agents.
- Gastric Electrical Stimulation:This device-based intervention involves surgically implanting electrodes to deliver electrical impulses to the stomach. Demand is concentrating in specialized gastroenterology centers in the United States and Germany, driven by the need for non-pharmacological options for refractory symptoms.
- Prokinetic Agents:These pharmaceutical compounds enhance gastrointestinal motility by targeting specific receptors in the digestive system. The development pipeline for novel prokinetics is active, aiming to address the limitations of existing drugs, particularly in regions with high diabetes prevalence like the United States.
- Antiemetics:These medications primarily alleviate symptoms such as nausea and vomiting, often used as symptomatic relief. These agents are widely available and frequently prescribed off-label for gastroparesis management.
- Botulinum Toxin:Administered endoscopically, botulinum toxin temporarily paralyzes the pyloric sphincter to improve gastric emptying. This treatment is typically reserved for patients unresponsive to other therapies.
- Nutritional Therapy:Dietary modifications and specialized feeding regimens, such as enteral or parenteral nutrition, manage severe gastroparesis symptoms and nutritional deficiencies. This therapy is fundamental for comprehensive patient care.
Most installed capacity flows through Prokinetic Agents. Expansion is steepest in Gastric Electrical Stimulation.
Route of Administration:
The method of therapeutic delivery profoundly impacts patient convenience, adherence, and the speed of symptom relief. Oral formulations remain the most common, balancing efficacy with ease of use for long-term management.
- Oral:This route involves medications taken by mouth, offering convenience and suitability for chronic disease management. Oral administration remains the primary choice for most drug-based gastroparesis therapies globally.
- Intravenous:Administered directly into the bloodstream, intravenous therapies provide rapid onset of action for acute symptom management in hospital settings. These are critical for patients experiencing severe nausea and vomiting.
- Subcutaneous Injection:Medications delivered under the skin offer an alternative for agents that cannot be absorbed orally or require sustained release. This route provides flexibility for home administration.
- Transdermal:Patches applied to the skin allow for continuous drug delivery, bypassing the digestive system and offering steady therapeutic levels. This method is gaining traction for certain antiemetics.
- Endoscopic Delivery:Therapies administered directly to the gastrointestinal tract using an endoscope, such as botulinum toxin injections, enable targeted treatment. This specialized approach is utilized in specific clinical scenarios.
Oral administration dominates patient preference, while intravenous routes remain critical for acute interventions.
End User:
The diverse patient care settings influence treatment protocols and procurement strategies for gastroparesis therapies. Each end-user type caters to different stages of the patient journey, from diagnosis to long-term management.
- Specialty Clinics:These facilities, including gastroenterology and endocrinology clinics, provide advanced diagnostic services and specialized treatment plans. Specialty clinics drive the adoption of novel therapies and devices.
- Gastroenterologists:As primary prescribers for gastroparesis, gastroenterologists manage diagnosis, treatment selection, and ongoing patient care. Their expertise is central to clinical decision-making.
- Ambulatory Surgery Centers:These outpatient facilities perform procedures like gastric electrical stimulator implantation or endoscopic interventions. They offer a cost-effective alternative to inpatient hospital stays for certain procedures.
- Long-term Care Facilities:These institutions manage chronic conditions and nutritional support for elderly or severely ill gastroparesis patients. They focus on symptom management and quality of life.
Specialty clinics constitute a significant point of care, with gastroenterologists driving much of the prescription volume.
Distribution Channel:
The pathway for therapeutic delivery shapes market access and pricing dynamics for diabetic gastroparesis treatments. Channels range from traditional pharmacies to specialized direct sales models for complex devices.
- Hospital Pharmacies:These pharmacies procure and dispense medications for inpatient use and manage specialized drugs and devices for hospital-based procedures. They play a significant role in initial treatment phases.
- Retail Pharmacies:Community-based pharmacies dispense oral medications and antiemetics for outpatient use. They provide broad accessibility for patients managing chronic gastroparesis.
- Online Pharmacies:E-commerce platforms offer convenient access to prescription refills and over-the-counter symptomatic relief. This channel is expanding, particularly for chronic medication management.
- Direct Sales:Manufacturers often use direct sales forces to market and distribute high-value medical devices like gastric electrical stimulators to hospitals and specialty clinics. This ensures specialized training and support.
- Contract Manufacturing:Third-party manufacturers produce pharmaceutical agents or device components for market participants. This model supports scalability and specialized production capabilities.
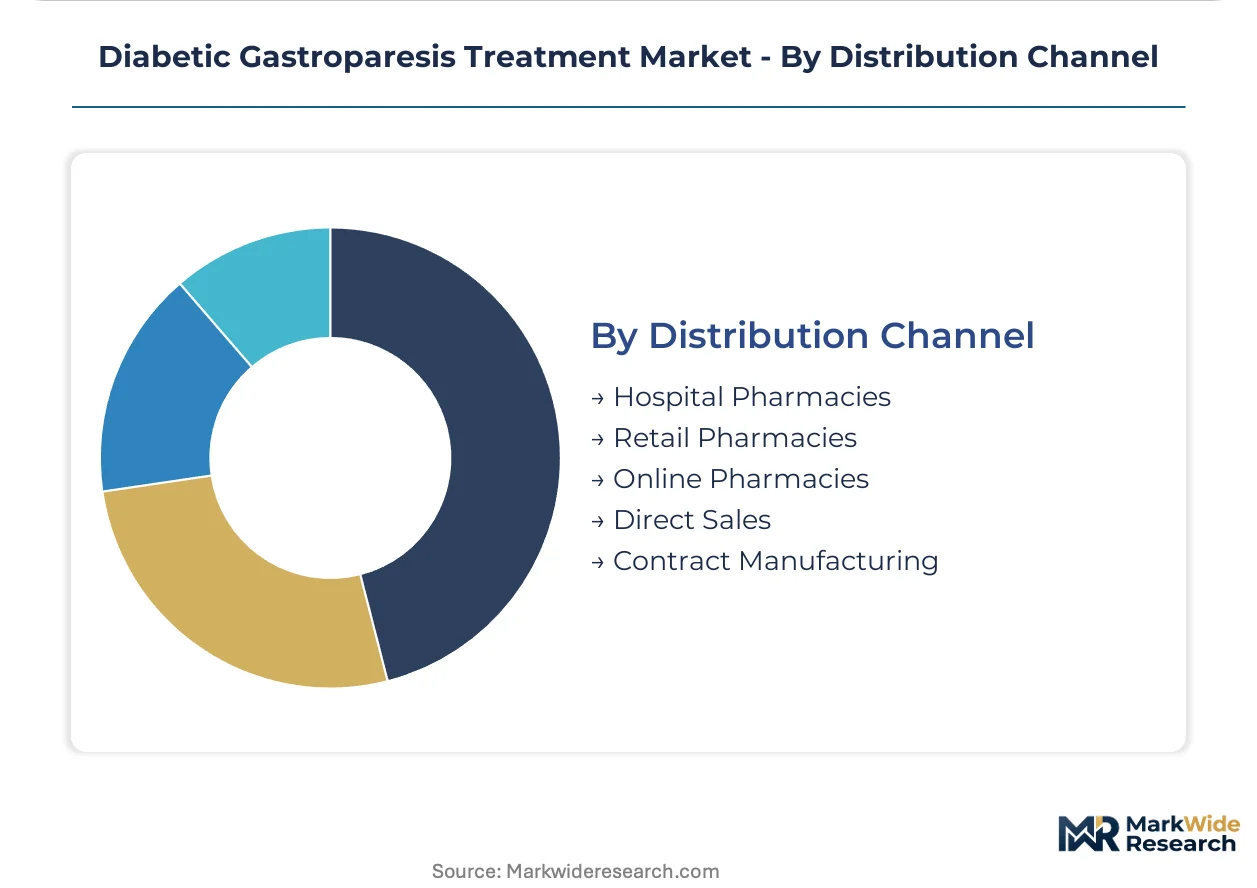
Hospital pharmacies manage complex procurement for both drugs and devices, as retail pharmacies ensure widespread access for patients.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States' advanced healthcare infrastructure and high diabetes prevalence drive significant demand for diabetic gastroparesis treatments. This market benefits from targeted regulatory support for novel therapies addressing unmet needs. Specialized centers across major cities are key to adopting advanced treatment modalities.
United States
The United States exhibits robust demand for diabetic gastroparesis therapies due to its high diabetes incidence and sophisticated medical facilities. The FDA's increasing emphasis on Patient-Reported Outcomes influences clinical trial design for new drug approvals. Boston's biotech hub actively develops next-generation prokinetics and neuromodulation devices.
Germany
Germany's well-developed healthcare system and aging population contribute to a steady demand for effective gastroparesis management. The European Medicines Agency's PRIME scheme accelerates review for novel treatments addressing high unmet medical needs. Munich's life science corridor sees significant investment in advanced gastroenterology research.
Japan
Japan presents unique market access requirements for diabetic gastroparesis therapies, driven by its distinct regulatory environment. The PMDA's rigorous approval standards shape drug development timelines for market entry. Tokyo's medical technology sector focuses on innovative device-based interventions.
India
Rising diabetes incidence across India fuels an expanding patient pool requiring gastroparesis management, particularly in urban centers. The CDSCO's evolving guidelines for drug approval and manufacturing impact local and international pharmaceutical companies. Hyderabad's pharmaceutical ecosystem is a growing hub for developing affordable therapeutic options.
France
France demonstrates a strong emphasis on improving patient quality of life for chronic conditions, impacting gastroparesis treatment adoption. The Agence Nationale de Sécurité du Médicament et des produits de santé (ANSM) oversight ensures high standards for drug safety and efficacy. The Paris-Saclay innovation cluster actively researches novel mechanisms for gastric motility regulation.
Diabetic Gastroparesis Treatment Market Key Industry Players
Global majors compete with regional champions across therapeutic modalities and device innovation within the diabetic gastroparesis treatment market. The landscape exhibits a tiered structure, with established pharmaceutical companies alongside specialized medical device manufacturers. Strategic archetypes include integrated diabetes solution providers, dedicated gastroenterology specialists, and neuromodulation device innovators. Companies primarily engage in strategic partnerships for pipeline development and targeted geographic expansion to broaden patient access.
Integrated diabetes solution providers, such as Eli Lilly and Company, leverage their extensive background in metabolic disorders to offer comprehensive care. Medtronic plc, a global medical technology company, exemplifies leadership in the gastric electrical stimulation device segment. Salix Pharmaceuticals Inc., focused on gastroenterology, represents a specialized player competing on clinical efficacy and prescriber relationships for targeted therapies. These companies anchor distinct segments of the market, from broad pharmaceutical portfolios to niche device-based interventions.
| Leading Market Players |
|---|
| Salix Pharmaceuticals Inc. |
| Medtronic plc |
| Abbott Laboratories |
| Eli Lilly and Company |
| Takeda Pharmaceutical Company Limited |
| AstraZeneca plc |
| Boston Scientific Corporation |
| Vanda Pharmaceuticals Inc. |
| Evoke Pharma Inc. |
| Others |
Cost & Logistics Intelligence
Family-owned mid-caps and specialized device manufacturers influence both supply behavior and pricing discipline within the diabetic gastroparesis treatment market, particularly for niche interventions.
Pricing Analysis
Input-cost pass-through mechanisms significantly impact pricing for both pharmaceutical agents and medical devices. Value-based pricing models are emerging for novel therapies demonstrating superior clinical outcomes. Price differentiation drivers include advanced clinical efficacy, improved safety profiles, and specialized after-sales support for complex devices. Pricing softness stems from the widespread off-label use of generic antiemetics. Hospital systems and payers exhibit the highest price sensitivity, while patients seeking relief from debilitating symptoms may be less sensitive for highly effective treatments.
Supply Chain Analysis
Workforce availability in specialized manufacturing geographies like the United States and Germany affects the production of advanced medical devices. Geographic supply concentration for pharmaceutical APIs primarily centers in India and China. Raw material dependencies include specialized chemical precursors for prokinetic agents and precision components for gastric electrical stimulators. Single-source vulnerability for critical device components represents a structural supply chain risk. Distribution runs through a dual model, with hospital pharmacies managing complex procurements and retail pharmacies ensuring broad access for oral medications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a clear margin-expansion story, driven by the shift towards premium-tier novel prokinetics and advanced neuromodulation devices.
For Market Incumbents: Acquire specialized R&D capabilities in next-generation prokinetics or neuromodulation devices. This defends against emerging entrant archetypes focused on targeted therapies. Consolidate market share through strategic partnerships in key geographies like the United States to leverage established distribution channels. Invest in clinical trial design that incorporates Patient-Reported Outcomes to meet evolving regulatory standards and secure premium pricing.
For New Entrants and Emerging Players: Biomarker discovery platforms represent a technology-first wedge into personalized medicine for diabetic gastroparesis. Target the underpenetrated pediatric and adolescent diabetic populations with specifically formulated treatments. Develop digital health integration solutions that combine device-based interventions with remote monitoring capabilities. A direct-to-specialist go-to-market angle, emphasizing clinical efficacy data, can build early prescriber confidence.
For Investors and Strategic Acquirers: Medical device conglomerates are the most active acquirers in this space, seeking to expand their neuromodulation portfolios. Long-term viability hinges on investments in therapies addressing the significant unmet needs for improved safety and efficacy. Focus on companies with strong intellectual property in novel drug mechanisms or device technologies. The signal to watch is successful Phase 3 clinical trial readouts for next-generation prokinetics or FDA approval for new device indications.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement for Novel Prokinetics | Accelerates market entry for agents with improved safety profiles, addressing a critical patient need. |
| Regulatory Approval Pathway Optimization | Streamlines access to key markets like the United States and Europe for innovative therapies. |
| Strategic Partnership for Device Distribution | Expands market reach for gastric electrical stimulators into specialized gastroenterology centers. |
| Biomarker Discovery Investment | Enables personalized medicine approaches, enhancing treatment selection for individual patients. |
| Digital Health Integration Development | Improves patient adherence and remote monitoring capabilities for device-based interventions. |
Research Approach
Multiple input streams — primary interviews with industry stakeholders, extensive secondary data analysis, and proprietary database screening — were reconciled to build a comprehensive market view. This involved engaging with gastroenterologists, regulatory affairs specialists, device engineers, and hospital administrators. Secondary sources included FDA filings, EMA submissions, clinical trial registries, and medical journals, all triangulated through both bottom-up and top-down approaches.
Data-stream reconciliation formed the basis of the analytical framework, projecting market trends across the analysis window. Segmentation dimensions modeled included treatment type, route of administration, end user, and geographic region, alongside patient population demographics. Compound annual growth rates were derived from historical data analysis and future trend projections, incorporating inputs like diabetes prevalence rates and the progression of the drug development pipeline.
The model holds under current regulatory landscapes and established clinical practice patterns; deviation in novel prokinetic approval timelines or significant shifts in payer reimbursement policies would shift forecast trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Point of Care Glucose Testing Market
Diabetes Care
Japan Insulin Drugs and Delivery Devices Market
Diabetes Care
India Self-Monitoring Blood Glucose Devices Market
Diabetes Care
South Africa Self-Monitoring Blood Glucose Devices Market
Diabetes Care
South Africa Oral Antidiabetic Drug Market
Diabetes Care
South Korea Insulin Infusion Pump Market
Diabetes Care
Global Pet Diabetes Care Market
Diabetes Care
Iran Diabetes Care Devices Market
Diabetes Care
Middle East and Africa Diabetes Market
Diabetes Care
South Korea Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Global Diabetes Pen Market
Diabetes Care
India Continuous Glucose Monitoring (CGM) Market
Diabetes Care
China Continuous Glucose Monitoring Devices Market
Diabetes Care
Thailand Oral Antidiabetic Drug Market
Diabetes Care
Diabetes Care Devices and Drugs Market
Diabetes Care
Hyperglycemia Treatment Market