
 Gastric Cancer Drugs Market | 2026-2036
Gastric Cancer Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Gastric Cancer Drugs Market Intelligence
Biopharma manufacturing clusters in Massachusetts and Switzerland are pivoting toward antibody-drug conjugate capacity to serve gastric cancer pipelines. Bristol-Myers Squibb leverages its immuno-oncology infrastructure across checkpoint inhibitor development. Daiichi Sankyo anchors its position through HER2-targeted ADC technology leadership. F. Hoffmann-La Roche sustains competitive depth in companion diagnostic-linked therapeutic protocols.
Gastric cancer drugs comprise systemic therapeutic agents designed to inhibit tumor proliferation, angiogenesis, or immune evasion in adenocarcinomas of the stomach and gastroesophageal junction, typically formulated as monoclonal antibodies, small-molecule kinase inhibitors, or cytotoxic chemotherapeutics requiring parenteral or oral delivery. Their primary purpose is to extend progression-free survival and overall survival in unresectable or metastatic disease settings. Immunotherapy segments command premium positioning as PD-1 and CTLA-4 inhibitors displace earlier-line chemotherapy in combination protocols across major markets. Targeted therapy segments concentrate margin pools where HER2, FGFR2, or CLDN18.2 biomarker testing identifies addressable subpopulations. Oral administration routes gain traction in maintenance settings where intravenous infusion logistics burden hospital capacity.
The FDA, EMA, and Japan's PMDA govern clinical trial design, accelerated approval criteria, and post-market pharmacovigilance requirements that shape development investment and commercial access timelines for gastric cancer therapeutics. China's NMPA implements national reimbursement list negotiations that directly determine volume accessibility for imported and domestic oncology agents. Stakeholders must monitor biomarker-driven trial enrichment strategies and evolving combination therapy standards of care to align portfolio priorities with regulatory and clinical trajectory.
Market Dynamics
Checkpoint inhibitor combination protocols are displacing first-line chemotherapy standards across major oncology markets, compressing development timelines and forcing portfolio realignments toward immuno-oncology assets.
Growth Catalysts
- Biomarker-driven trial enrichment:HER2, FGFR2, and CLDN18.2 testing protocols expand addressable patient subpopulations. Companion diagnostic linkages accelerate regulatory pathways at the FDA and EMA.
- Japan's PMDA adaptive licensing:Conditional early approval frameworks compress commercialization timelines for novel antibody-drug conjugates. Japanese screening programs broaden eligible patient pools.
- China's NMPA national reimbursement negotiations:Volume-based procurement agreements improve accessibility for imported oncology agents. Domestic manufacturing clusters expand capacity for biologic therapeutics.
Market Restraints
- Platinum-based chemotherapy input costs:Active pharmaceutical ingredient supply concentrates in Indian and Chinese contract manufacturing organizations. Price volatility constrains margin stability for generic cytotoxic formulations.
- Biomarker testing infrastructure gaps:Community oncology settings lack standardized immunohistochemistry and next-generation sequencing capabilities. Diagnostic fragmentation limits therapeutic matching.
- EMA pharmacovigilance requirements:Post-market safety monitoring obligations extend development investment horizons. Risk management plans impose ongoing compliance burdens.
Strategic Opportunities
- Maintenance therapy oral formulations:Small-molecule kinase inhibitors enable outpatient administration models. Hospital capacity constraints in the United States and Japan favor non-infusion delivery routes.
- Swissmedic adaptive pathway pilot programs:Switzerland's progressive regulatory framework attracts early-stage clinical trial investment. Basel-Zurich biopharma clusters support accelerated development timelines.
- Real-world evidence integration:EHR-derived outcome data complements traditional randomized controlled trials. Payers in Germany and France increasingly accept pragmatic study designs for coverage decisions.
Industry Challenges
- Immuno-oncology talent scarcity:Translational medicine and biomarker strategy functions face recruitment bottlenecks. Competition for experienced clinical development leadership intensifies across Boston and Basel clusters.
- Multi-regional trial coordination complexity:Divergent FDA, EMA, PMDA, and NMPA endpoint requirements fragment study designs. Harmonization efforts remain incomplete for progression-free survival definitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gastric Cancer Drugs Market |
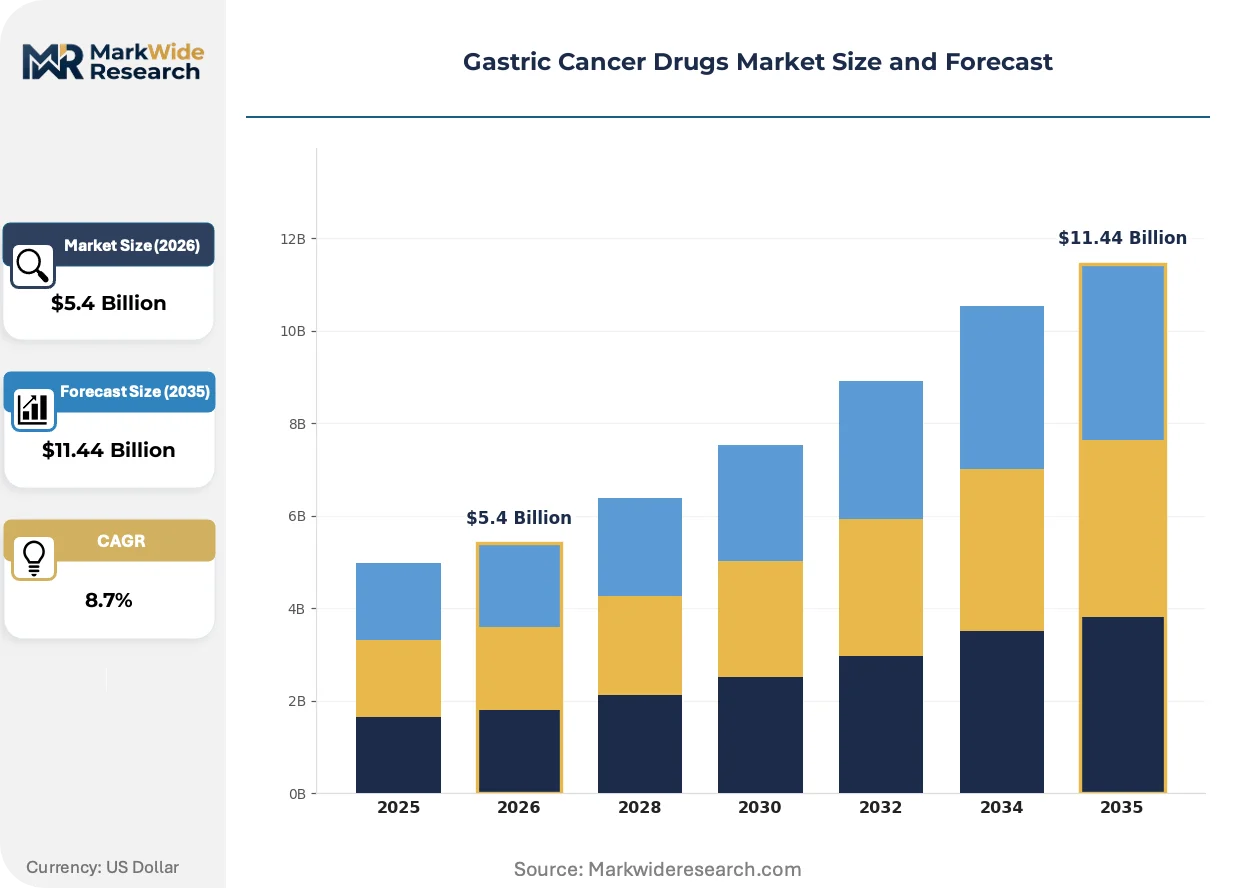
| Market Size in 2026 | $5.4 Billion |
| Market Size in 2035 | $11.44 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: Chemotherapy, Targeted Therapy, Immunotherapy, Hormonal Therapy Administration Route: Oral, Intravenous, Subcutaneous, Topical End User: Hospitals, Oncology Clinics, Homecare, Research Institutions Distribution Channel: Retail Pharmacies, Hospital Pharmacies, Online Pharmacies, Direct Sales |
| Companies Covered | Bristol-Myers Squibb, Daiichi Sankyo, F. Hoffmann-La Roche, BeiGene, Astellas Pharma, Eli Lilly and Company, Merck & Co. Inc., Novartis, AstraZeneca, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gastric Cancer Drugs Market Strategic Shifts & Innovations
Antibody-drug conjugate engineering is redefining therapeutic index expectations in solid tumor oncology, with payload-linker optimization emerging as the critical differentiator in competitive positioning.
Next-generation ADC platforms is modularizing payload delivery across diverse tumor antigen targets. Massachusetts-based contract development organizations are expanding conjugation capacity to serve pipeline demand from emerging biopharma sponsors. This architectural flexibility is compressing preclinical-to-clinic timelines for novel gastric cancer assets.
REACH registration requirements for novel chemical entities are tightening environmental release controls across European manufacturing networks. ECHA substance evaluation processes now extend to antibody-drug conjugate intermediate compounds. Swiss and German production facilities are investing in closed-system bioprocessing to preempt compliance disruptions.
Hospital pharmacy committees are consolidating formulary decisions through centralized oncology pathway committees. Community infusion centers in the United States are losing access to novel immuno-oncology agents as academic medical centers capture referral flows. This concentration is visible most acutely in Texas and California metropolitan markets where vertically integrated health systems dominate.
Gastric Cancer Drugs Market Segmentation
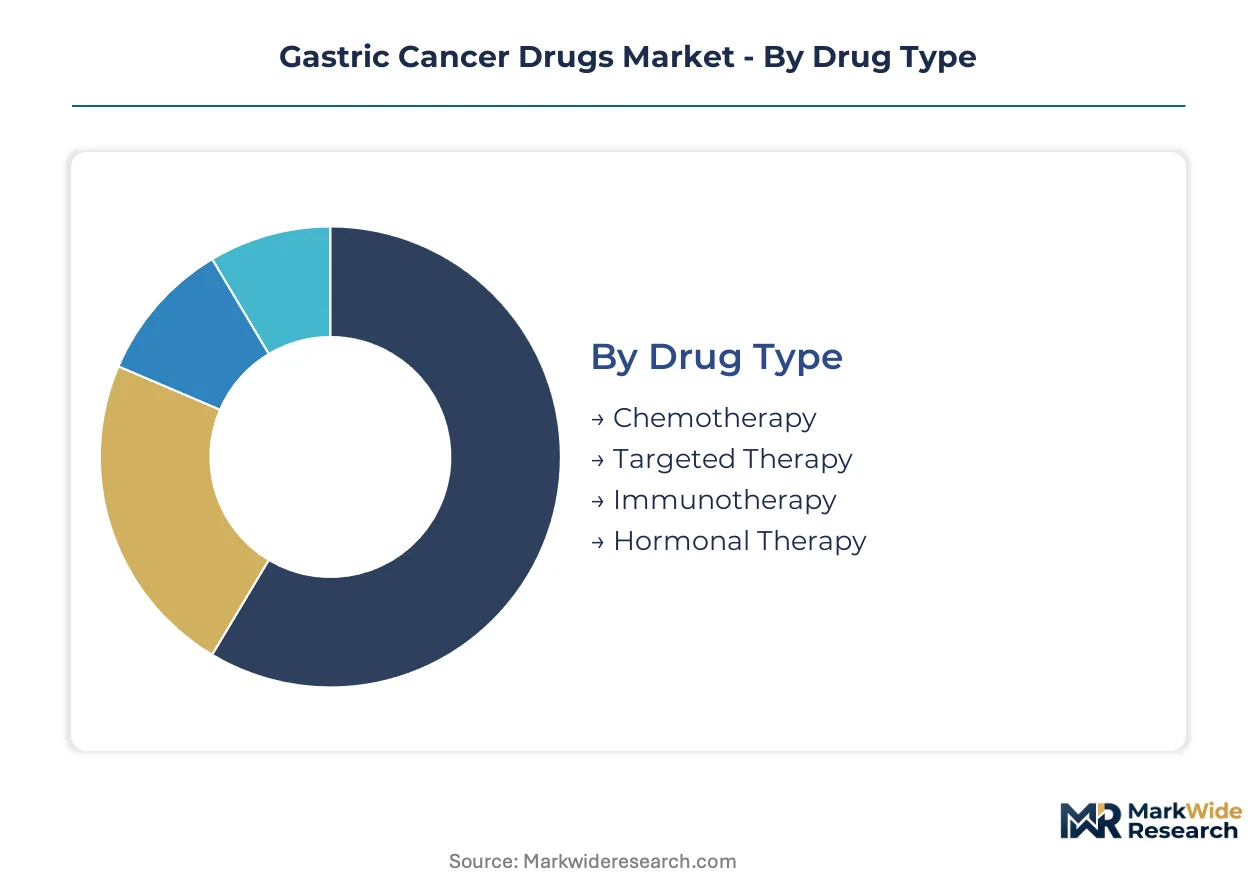
Gastric cancer therapeutics fragment across multiple decision axes where biomarker status, infusion logistics, and reimbursement pathways determine prescribing patterns. Treatment selection hinges on HER2 expression, PD-L1 scores, and hospital formulary positioning rather than clinical efficacy alone.
Drug Type:
Prescribers anchor first-line decisions on biomarker-driven efficacy profiles and companion diagnostic availability, with reimbursement tiers reinforcing these clinical hierarchies.
- Immunotherapy:PD-1 and CTLA-4 inhibitors command premium positioning through checkpoint blockade mechanisms. Demand concentrates in academic medical centers across the United States and Japan where centralized pathway committees control formulary access. Regulatory compression at the FDA and PMDA accelerates label expansions into earlier treatment lines.
- Targeted Therapy:HER2-directed monoclonal antibodies and emerging CLDN18.2 inhibitors require diagnostic infrastructure investment. Japanese and Chinese screening programs expand eligible patient pools where biomarker prevalence aligns with addressable subpopulations. Companion diagnostic linkages at Roche and Daiichi Sankyo portfolios reinforce prescribing loyalty.
- Chemotherapy:Platinum-fluoropyrimidine backbones persist in resource-constrained settings lacking molecular testing infrastructure.
- Hormonal Therapy:Limited applicability restricts deployment to rare neuroendocrine gastric subtypes with hormone receptor positivity.
Volume sits with chemotherapy due to infrastructure ubiquity; growth tilts toward immunotherapy as checkpoint combinations displace earlier-line standards.
Administration Route:
Hospital capacity constraints and patient convenience preferences are redistributing market share across delivery modalities, with outpatient administration models gaining reimbursement traction.
- Intravenous:Infusion-dependent biologics dominate immuno-oncology and ADC protocols requiring controlled delivery environments. Academic medical centers in Texas and California metropolitan markets capture referral flows as community infusion centers lose access to novel agents. Cold chain logistics and compounding pharmacy investment create barrier thresholds.
- Oral:Small-molecule kinase inhibitors enable maintenance therapy models that reduce hospital burden. Japanese and United States payers favor non-infusion routes where total cost of care calculations include nursing time and facility fees. Tyrosine kinase inhibitors in FGFR2-altered populations exemplify this shift.
- Subcutaneous:Emerging delivery platforms for monoclonal antibodies promise reduced administration time and patient preference advantages.
- Topical:Negligible relevance given gastric cancer's internal tumor location and systemic disease progression patterns.
Revenue concentrates in intravenous delivery; patient preference and total cost pressures are accelerating oral formulation development pipelines.
End User:
Site-of-care economics and clinical trial access determine where novel agents achieve initial penetration before community diffusion.
- Hospitals:Comprehensive cancer centers anchor immuno-oncology adoption through clinical trial infrastructure and multidisciplinary tumor boards. Vertical integration in United States metropolitan markets concentrates novel agent access within academic medical center networks. Pharmacy and therapeutics committees gate formulary inclusion.
- Oncology Clinics:Community-based practices handle stable maintenance populations and chemotherapy backbones where infusion logistics remain manageable. Diagnostic fragmentation limits therapeutic matching in settings lacking next-generation sequencing capabilities.
- Homecare:Oral kinase inhibitors and subcutaneous delivery platforms expand administration beyond facility walls where reimbursement supports remote monitoring.
- Research Institutions:Early-phase clinical trial sites generate real-world evidence that supports regulatory submissions and payer negotiations.
Prescription volume clusters in hospital outpatient departments; oncology clinics represent the expansion frontier for maintenance therapy protocols.
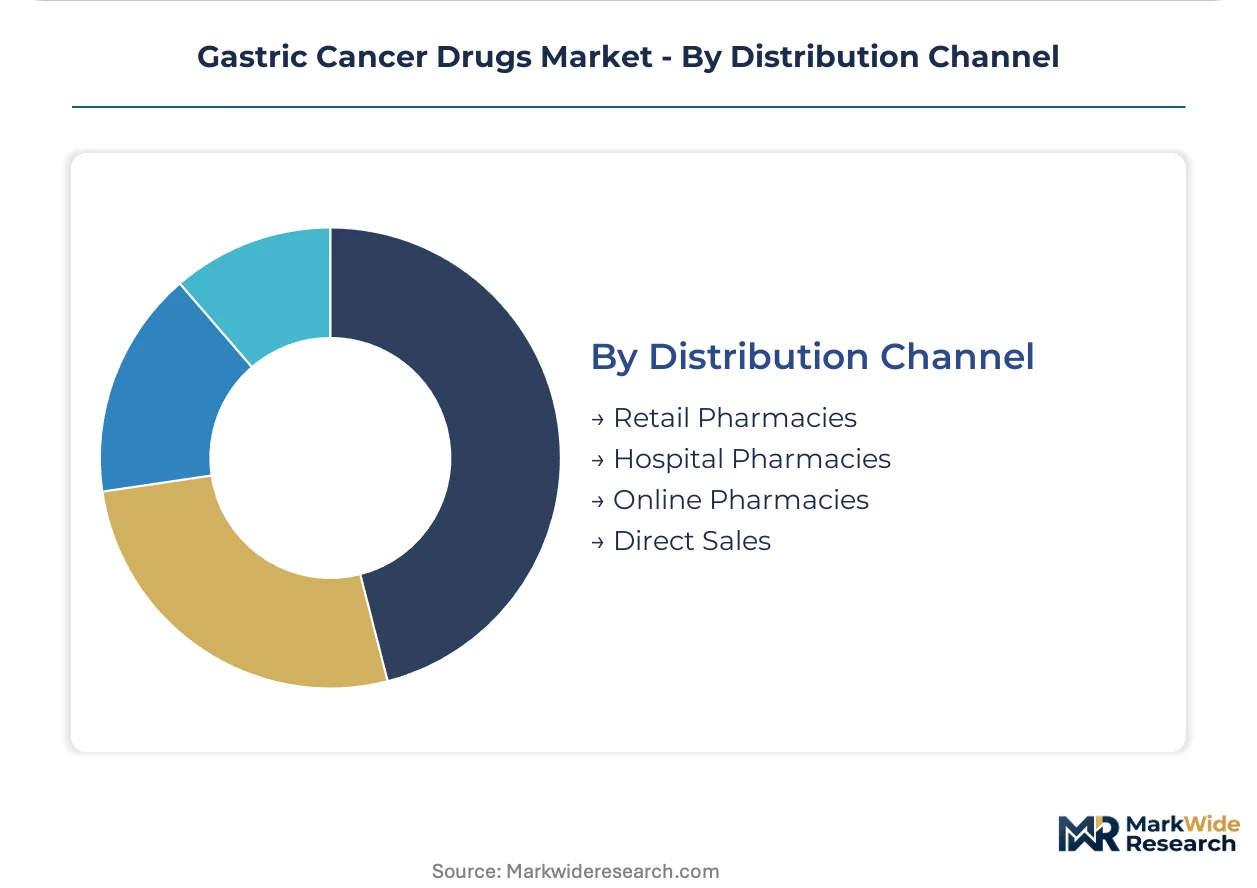
Distribution Channel:
Channel selection follows drug temperature requirements, reimbursement complexity, and patient support program integration needs.
- Hospital Pharmacies:Captures infused biologics and 340B-discounted oncology agents where integrated delivery networks control purchasing. Formulary consolidation through centralized oncology pathway committees reduces vendor fragmentation. Cold chain custody requirements favor captive pharmacy operations.
- Retail Pharmacies:Oral oncology specialty pharmacies manage prior authorization complexity and patient assistance program enrollment. Limited distribution networks for high-cost agents restrict independent pharmacy participation.
- Online Pharmacies:Emerging channel for oral maintenance therapies in markets with established telehealth infrastructure and remote monitoring capabilities.
- Direct Sales:Manufacturer-controlled distribution for clinical trial supplies and compassionate use programs.
Hospital pharmacies command infused agent volume; retail specialty pharmacy networks are climbing fastest for oral oncology portfolios.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Active pharmaceutical ingredient supply clusters in Indian and Chinese contract manufacturing organizations anchor geographic production patterns for cytotoxic backbones, while biologic manufacturing concentrates in Massachusetts and Swiss corridor facilities.
United States
FDA accelerated approval pathways compress development timelines for novel antibody-drug conjugates. The agency's breakthrough therapy designation attracts early-phase clinical trial investment to Boston-Cambridge and San Francisco biopharma clusters. Massachusetts-based CDMOs expand conjugation capacity to serve pipeline demand from emerging sponsors.
Japan
PMDA adaptive licensing frameworks enable conditional early approval for HER2-targeted regimens. National screening programs broaden eligible patient pools for biomarker-driven therapies. Tokyo-Osaka pharmaceutical corridors anchor immuno-oncology infrastructure development.
China
NMPA national reimbursement list negotiations determine volume accessibility for imported oncology agents. Domestic manufacturing clusters expand biologic production capacity in Shanghai and Suzhou. Volume-based procurement agreements reshape pricing dynamics for checkpoint inhibitors.
Germany
EMA pharmacovigilance requirements extend post-market safety monitoring obligations for gastric cancer therapeutics. ECHA REACH registration tightens environmental release controls for ADC intermediate compounds. Basel-Zurich corridor facilities invest in closed-system bioprocessing to preempt compliance disruptions.
Switzerland
Swissmedic adaptive pathway pilot programs attract early-stage clinical trial investment through progressive regulatory frameworks. Basel-Zurich biopharma clusters support accelerated development timelines for novel agents. Companion diagnostic-linked therapeutic protocols reinforce competitive positioning.
Gastric Cancer Drugs Market Key Industry Players
Global majors compete with regional champions across biomarker-driven therapeutic categories, with portfolio depth in checkpoint inhibitors and antibody-drug conjugates determining tier placement. The vendor base organizes around three archetypes: immuno-oncology platform holders, HER2-directed ADC specialists, and emerging biopharma sponsors with modular payload technologies. Strategic moves concentrate on capacity expansion for conjugation manufacturing and geographic licensing partnerships for Asia-Pacific market access.
Within the immuno-oncology platform tier, Bristol-Myers Squibb and Merck & Co. Inc. occupy positions defined by checkpoint inhibitor infrastructure scale. Among HER2-directed ADC specialists, Daiichi Sankyo and F. Hoffmann-La Roche exemplify companion diagnostic-linked therapeutic development. BeiGene represents the emerging biopharma archetype with Asia-Pacific market development capabilities.
| Leading Market Players |
|---|
| Bristol-Myers Squibb |
| Daiichi Sankyo |
| F. Hoffmann-La Roche |
| BeiGene |
| Astellas Pharma |
| Eli Lilly and Company |
| Merck & Co. Inc. |
| Novartis |
| AstraZeneca |
| Others |
Cost & Logistics Intelligence
Antibody-drug conjugate manufacturing transitions from batch conjugation to continuous processing, compressing cost per gram while concentrating technical capacity in Massachusetts and Swiss corridor facilities. This dual shift simultaneously reduces unit economics for emerging sponsors and raises barrier thresholds for new manufacturing entrants.
Pricing Analysis
Companion diagnostic bundling separates reimbursed premium regimens from unbundled testing costs that shift to patients. Three-tier pricing structure across premium immuno-oncology combinations, standard targeted therapy protocols, and economy chemotherapy backbones reflects biomarker infrastructure investment levels. Cost compression in platinum-based generic cytotoxics stems from Indian and Chinese API oversupply. Community oncology clinics exhibit highest price sensitivity due to formulary committee gatekeeping and 340B discount capture by academic medical centers.
Supply Chain Analysis
Single-source vulnerability sits with Chinese contract manufacturing organizations for platinum salt active pharmaceutical ingredients. Biologic drug substance production draws from Switzerland, Massachusetts, and Singapore facilities. Payload-linker chemistries hinge on specialized intermediate suppliers in Basel-Zurich and Boston-Cambridge clusters. Tariff exposure on Chinese-sourced cytotoxic inputs threatens margin stability for generic formulations. Distribution runs through hospital captive pharmacies for infused biologics and limited specialty pharmacy networks for oral kinase inhibitors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gastric cancer therapeutics represent a consolidation play as biomarker-driven trial complexity and companion diagnostic infrastructure requirements force subscale developers toward partnership or exit. Checkpoint inhibitor standard-of-care displacement eliminates single-agent chemotherapy sponsors without combination assets.
For Market Incumbents: Cement formulary positioning through PBM and GPO contracting depth ahead of biosimilar entry. Lock in diagnostic partnerships with Roche and Daiichi Sankyo to preserve prescribing loyalty. Capacity addition in Singapore and Swiss corridor facilities secures ADC conjugation supply against Massachusetts bottlenecks. Vertical integration into payload-linker chemistry reduces dependency on Basel-Zurich intermediate suppliers.
For New Entrants and Emerging Players: Capture maintenance therapy oral formulations where hospital capacity constraints favor non-infusion delivery. White-space sits with FGFR2-altered populations and CLDN18.2-negative subsegments lacking approved targeted options. Community oncology clinic partnerships enable formulary access outside academic medical center gatekeeping. Licensing Asian-Pacific rights to BeiGene or Astellas accelerates NMPA reimbursement pathway navigation.
For Investors and Strategic Acquirers: Exit pathways concentrate in mid-cap biopharma with Phase II-ready ADC assets and established CDMO relationships. Long-term viability favors platforms with modular payload technologies applicable across solid tumor indications. Acquisition target archetype: emerging sponsors with Japanese PMDA conditional approval experience and Asian manufacturing partnerships. Watch FDA breakthrough therapy designation velocity as inflection indicator for portfolio prioritization.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Phase III enrollment in biomarker-enriched populations accelerates FDA breakthrough therapy designation timelines. |
| Manufacturing Scale-Up | ADC conjugation capacity expansion in Massachusetts CDMOs reduces sponsor queue times for emerging biopharma. |
| Regulatory Approval Pathway | PMDA adaptive licensing submission compresses Japanese commercialization timelines for HER2-directed regimens. |
| Licensing Agreement | Asian-Pacific rights partnerships with BeiGene or Astellas unlock NMPA national reimbursement list access. |
| Pipeline Diversification | CLDN18.2 and FGFR2 program additions reduce dependency on crowded PD-1 combination development. |
Research Approach
Independent corroboration across drug development executives, regulatory affairs leads, formulary directors, and payer access specialists underwrites the qualitative findings. Primary interviews with hospital procurement managers and oncology pathway committee members informed site-of-care dynamics. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary database audits. Bottom-up patient-flow modeling and top-down revenue reconciliation triangulate market sizing across the analysis window.
Rate-of-change decomposition isolates volume effects from price-mix shifts across treatment line, administration route, biomarker status, and regional regulatory cluster dimensions. CAGRs derive from segmented growth trajectory blending rather than single-point extrapolation. Forecast inputs incorporate checkpoint inhibitor label expansion velocity, companion diagnostic penetration curves, and NMPA reimbursement negotiation outcomes.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to biomarker testing infrastructure buildout rates and immuno-oncology combination toxicity profiles. Deviation in FDA accelerated approval conversion rates or EMA pharmacovigilance enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Nasal Antihistamines Market
Pharmaceuticals
Global Blood Plasma Derivatives Market
Pharmaceuticals
Ophthalmic Drug Delivery Systems Market
Pharmaceuticals
United States Over the Counter (OTC) Drugs Market
Pharmaceuticals
Europe Oral Anti-Diabetic Drug Market
Pharmaceuticals
Bendamustin Market
Pharmaceuticals
North America Over the Counter Drugs Market
Pharmaceuticals
Cough and Cold Preparations Market
Pharmaceuticals
Global Alteplase Market
Pharmaceuticals
Toxoid Vaccines Market
Pharmaceuticals
Europe Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Dyslipidemia Therapeutics Market
Pharmaceuticals
Global HPMC Capsules Market
Pharmaceuticals
Placental Protein Market
Pharmaceuticals
Contract Pharmaceutical Fermentation Services Market
Pharmaceuticals
Calcineurin Inhibitor Drugs Market