
 India Continuous Glucose Monitoring (CGM) Market | 2026-2036
India Continuous Glucose Monitoring (CGM) Market Size, Share, and Industry Trends Forecast 2026-2036
India Continuous Glucose Monitoring (CGM) Market Foresight
Market Context with Strategic Players
Modular sensor-transmitter bundles is repositioning buyer choice in India's CGM landscape, allowing patients to upgrade components without replacing full systems. Abbott Laboratories leverages its FreeStyle Libre ecosystem to dominate pharmacy and e-pharmacy channels across Mumbai and Delhi. Dexcom Inc. differentiates through G7 platform compatibility with third-party insulin pumps. Medtronic plc anchors the premium integrated-pump segment through its long-standing endocrinology hospital relationships.
Technical Definition and Structural Segments
Continuous Glucose Monitoring comprises a subcutaneous electrochemical sensor measuring interstitial glucose concentrations every 1-15 minutes, a transmitter relaying data via Bluetooth or NFC, and a receiver or smartphone app displaying real-time trends and predictive alerts for glycemic excursions. The technology serves Type 1 and insulin-dependent Type 2 diabetes patients seeking to reduce HbA1c variability and hypoglycemic episodes between fingerstick measurements. Sensor components command the dominant margin pool due to recurring replacement cycles every 10-14 days, while home care settings represent the fastest-expanding end-user channel as reimbursement frameworks evolve. Bluetooth-enabled systems lead technology adoption, though NFC-based options sustain growth among cost-sensitive patient segments in government hospital procurement.
Regulatory Frame and Forward Outlook
CDSCO's Medical Device Rules 2017, BIS certification requirements for wireless medical devices, and the Digital Information Security in Healthcare Act framework collectively shape product registration timelines and data localization obligations for CGM manufacturers entering India. The PLI scheme for medical electronics creates fiscal incentives for domestic assembly of transmitters and receivers, though sensor manufacturing remains import-dependent. Stakeholders must monitor whether CDSCO harmonizes with EU MDR or FDA 510(k) pathways to accelerate approval timelines for next-generation optical glucose sensing technologies.
Market Dynamics
CDSCO's streamlined approval pathway for digital health technologies is compressing market access timelines and enabling faster commercialization of next-generation glucose sensing platforms across Indian healthcare networks.
Growth Catalysts
- PLI scheme for medical electronics:Fiscal incentives for domestic assembly of transmitters and receivers reduce landed costs for manufacturers establishing Indian production facilities.
- Home care channel expansion:Type 2 diabetes patients in Maharashtra and Tamil Nadu are accelerating adoption of Bluetooth-enabled systems as reimbursement frameworks evolve for outpatient monitoring.
- Endocrinology infrastructure depth:Tier-1 cities with established private hospital networks and deeper insurance penetration concentrate demand for integrated pump-sensor systems.
Market Restraints
- Sensor import dependency:Domestic manufacturing capabilities remain limited for electrochemical sensor substrates, exposing supply chains to freight cost volatility and currency fluctuation risks.
- Wireless device certification friction:BIS certification requirements for Bluetooth and NFC medical devices extend pre-market timelines by 4-8 months compared to non-connected glucose meters.
- Reimbursement fragmentation:Central government health schemes and state-level insurance programs maintain inconsistent coverage criteria for CGM versus traditional fingerstick monitoring.
Strategic Opportunities
- Tier-2 city penetration:Underpenetrated markets in Gujarat and Karnataka present whitespace as diagnostic infrastructure expands beyond Mumbai and Delhi metropolitan clusters.
- NFC-based cost positioning:Government hospital procurement channels favor lower-cost, non-Bluetooth systems for mass screening programs in rural districts.
- Optical glucose sensing convergence:CDSCO harmonization with EU MDR or FDA 510(k) pathways would accelerate approval timelines for non-invasive monitoring technologies.
Industry Challenges
- Data localization compliance:Digital Information Security in Healthcare Act obligations require domestic server infrastructure for patient glucose data, increasing operational complexity for foreign platform providers.
- Integration with legacy hospital IT:Electronic health record systems at established endocrinology centers use non-standard APIs, forcing custom middleware development for real-time glucose data feeds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Continuous Glucose Monitoring (CGM) Market |
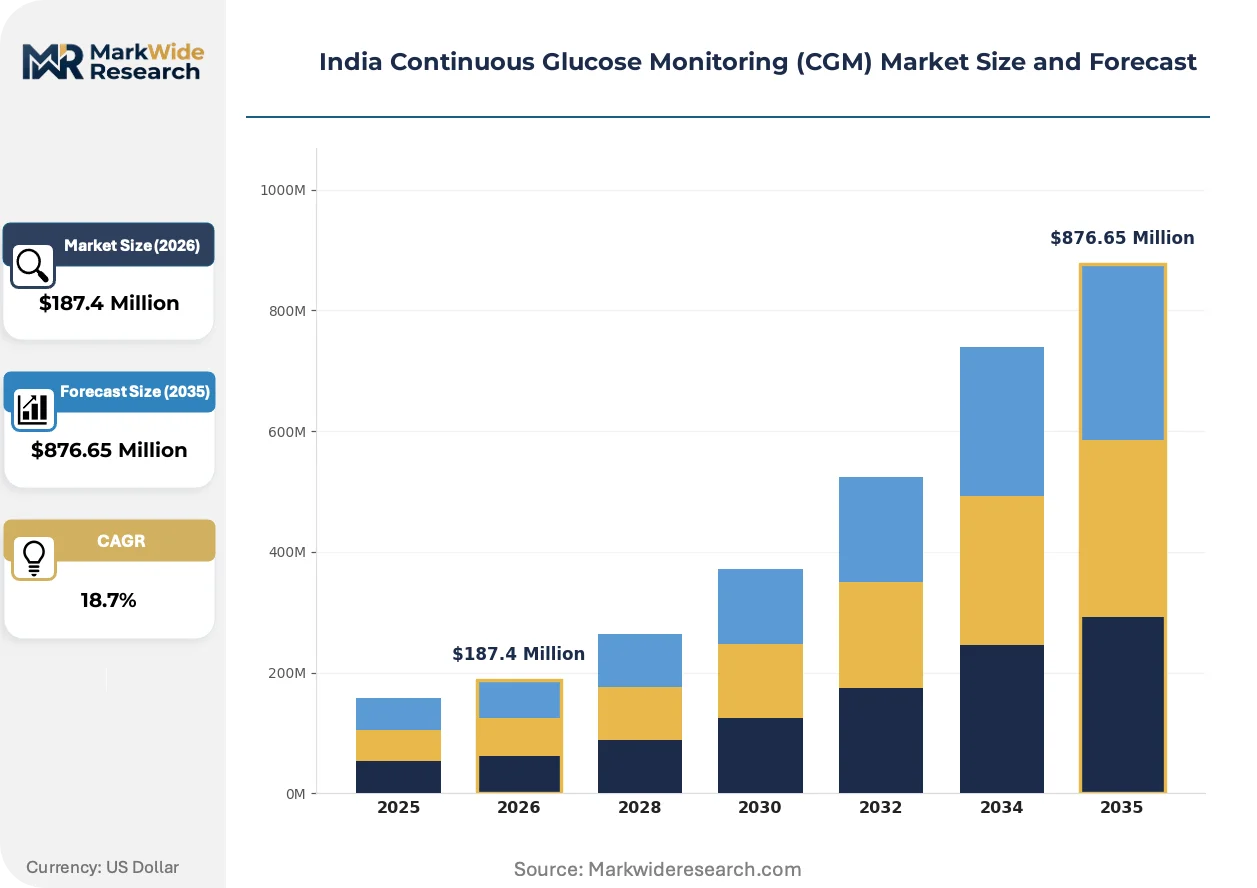
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $876.65 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sensor, Transmitter, Receiver, Smartphone App End User: Hospitals, Diabetes Clinics, Home Care, Research Institutions Technology: Wireless, NFC, Bluetooth, Optical Application: Type 1 Diabetes, Type 2 Diabetes, Gestational Diabetes, Others |
| Companies Covered | Abbott Laboratories, Dexcom Inc., Medtronic plc, F. Hoffmann-La Roche Ltd, Ascensia Diabetes Care, Senseonics Holdings Inc., Ypsomed AG, i-SENS Inc., Zhejiang POCTech Co. Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Continuous Glucose Monitoring (CGM) Market Shifts & Advancements
Modular hardware architectures and algorithmic personalization are redefining competitive differentiation in India's glucose monitoring landscape, shifting value capture from device sales toward recurring sensor subscriptions and data analytics services.
Non-invasive optical glucose sensing is converging with machine learning-based predictive algorithms to enable calibration-free monitoring. Research institutions in Bangalore and Hyderabad are piloting spectroscopic approaches that eliminate fingerstick validation requirements. This technology convergence is compressing the addressable market for traditional electrochemical sensors among pre-diabetic populations seeking preventive monitoring solutions.
CDSCO's Medical Device Rules 2017 amendments are mandating post-market surveillance reporting for Class C and D devices including CGM transmitters. Manufacturers must now submit periodic safety updates and adverse event data through the Sugam portal. The integrated-pump segment faces the steepest compliance burden as dual-classification devices trigger both pharmaceutical and medical device oversight pathways.
Subscription-based sensor replenishment models are displacing upfront hardware purchases in private pharmacy channels. Patients in Chennai and Pune increasingly prefer monthly payment plans bundled with teleconsultation access over single-transaction device acquisition. This behavioral shift concentrates recurring revenue with platform operators controlling end-to-end patient data flows rather than distributors managing inventory-heavy logistics networks.
India Continuous Glucose Monitoring (CGM) Market Segmentation
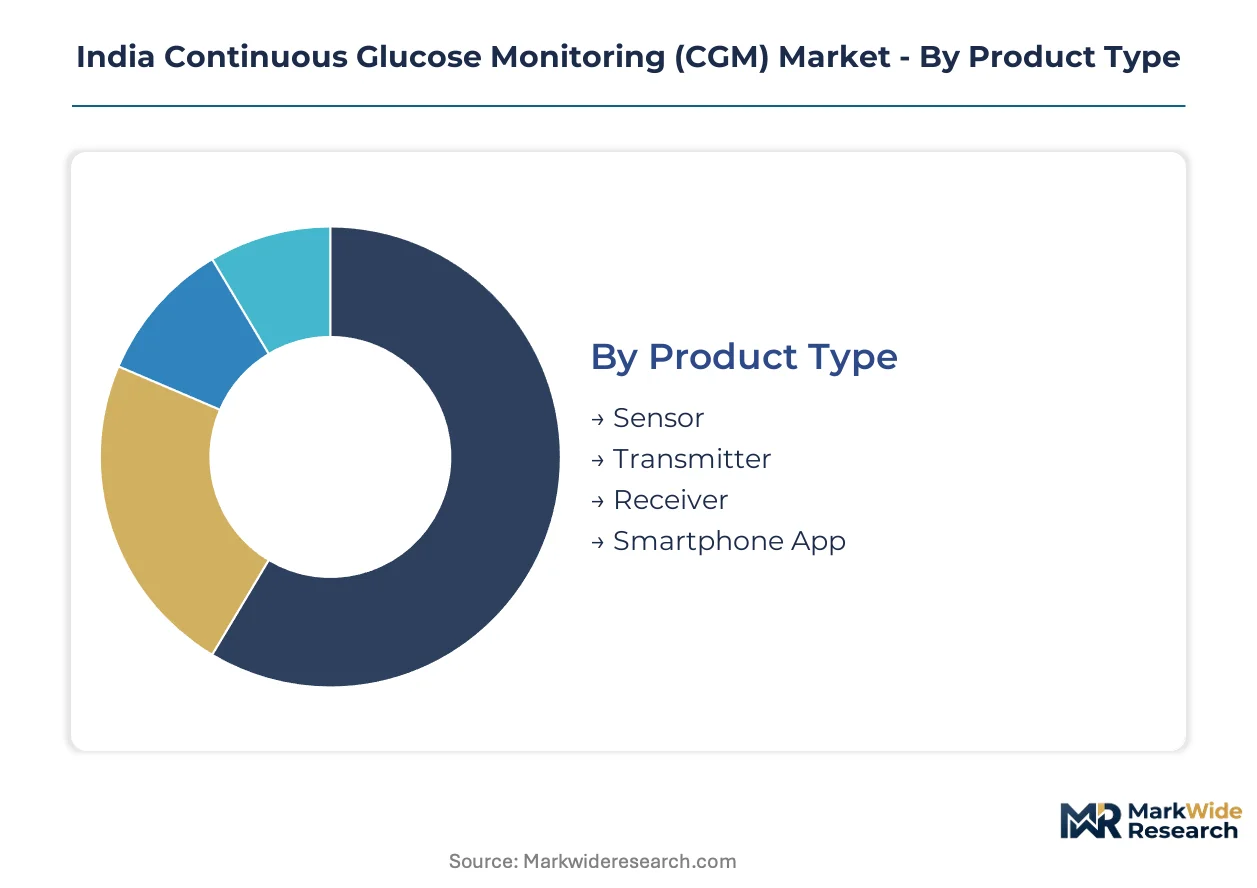
CGM segmentation in India reflects divergent technology readiness across patient populations and care settings. Component-level analysis reveals where margin pools concentrate versus where volume expansion is occurring.
Product Type:
Sensor-transmitter-receiver architectures define the hardware stack, with software layers increasingly determining patient retention and clinical utility.
- Sensor:Subcutaneous electrochemical filaments measuring interstitial glucose through enzymatic reaction with glucose oxidase. Maharashtra and Tamil Nadu home care patients drive replacement demand through 10-14 day wear cycles, though import dependency constrains supply security.
- Transmitter:Miniaturized Bluetooth or NFC radios relaying glucose data to receivers or smartphones. Domestic assembly incentives under PLI scheme for medical electronics are compressing landed costs for manufacturers establishing Bangalore or Hyderabad production facilities.
- Receiver:Dedicated display units for patients without smartphone access. Government hospital procurement in rural districts sustains demand for standalone hardware as primary data visualization endpoints.
- Smartphone App:Software platforms processing raw sensor signals into trend graphs and predictive alerts. CDSCO's Digital Information Security in Healthcare Act mandates domestic server infrastructure for glucose data storage, elevating operational complexity for foreign platform operators.
Mature deployment sits with Sensor. Newer deployment is concentrated in Smartphone App.
End User:
Channel economics diverge sharply between institutional procurement and direct-to-patient subscription models.
- Hospitals:Integrated pump-sensor systems anchor premium tier demand at established endocrinology centers in Mumbai and Delhi. Custom middleware development for electronic health record integration creates friction for real-time glucose data feeds.
- Diabetes Clinics:Specialized outpatient facilities prescribing CGM for insulin optimization. Tier-1 city concentration reflects deeper private insurance penetration and specialist physician density.
- Home Care:Direct patient-managed monitoring outside clinical settings. Bluetooth-enabled systems are climbing the fastest among Type 2 diabetes patients as reimbursement frameworks evolve for outpatient monitoring in Maharashtra and Tamil Nadu.
- Research Institutions:Academic medical centers and clinical trial sites utilizing CGM for glycemic pattern analysis. Bangalore and Hyderabad research pilots on spectroscopic non-invasive approaches are compressing addressable market potential for traditional electrochemical sensors among pre-diabetic screening populations.
Institutional volume concentrates in Hospitals. Patient-directed expansion is shifting toward Home Care.
Technology:
Connectivity specifications determine regulatory pathway complexity and cost positioning across patient segments.
- Wireless:Encompasses both Bluetooth and NFC transmission protocols under unified regulatory classification. BIS certification requirements for wireless medical devices extend pre-market timelines by 4-8 months compared to non-connected glucose meters.
- NFC:Near-field communication enabling data transfer through smartphone tap. Government hospital procurement channels in rural districts favor lower-cost, non-Bluetooth systems for mass screening programs.
- Bluetooth:Continuous low-energy broadcast enabling real-time alerts and cloud synchronization. Tier-1 city patients in Chennai and Pune increasingly prefer subscription-based sensor replenishment bundled with teleconsultation access.
- Optical:Spectroscopic glucose measurement eliminating subcutaneous insertion. CDSCO harmonization with EU MDR or FDA 510(k) pathways would accelerate approval timelines for calibration-free monitoring technologies entering Indian preventive care markets.
Established penetration rests with Bluetooth. Experimental deployment is gathering in Optical.
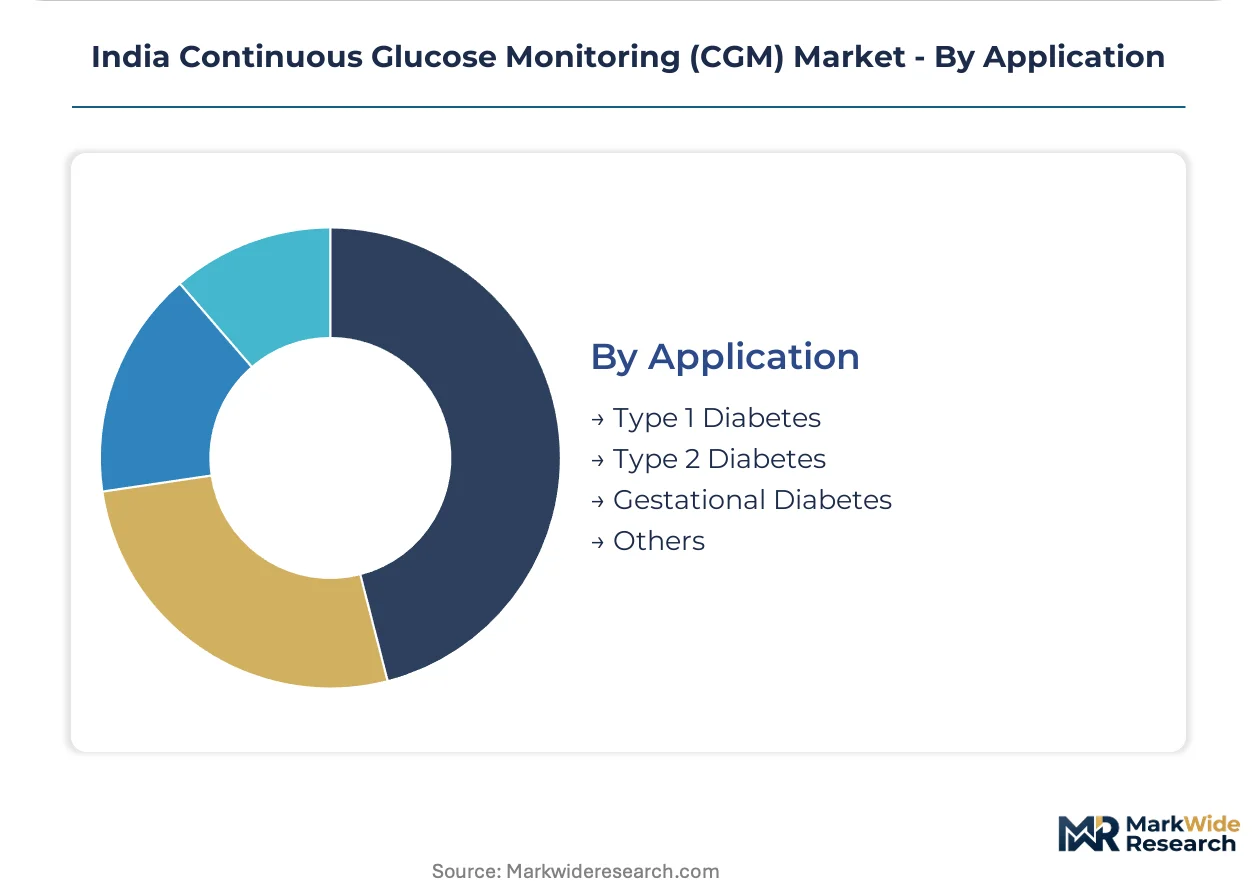
Application:
Disease severity and insulin dependency shape patient willingness to absorb out-of-pocket costs for continuous monitoring.
- Type 1 Diabetes:Absolute insulin deficiency requiring intensive glucose monitoring. Pediatric and adolescent patients in Delhi and Mumbai metropolitan clusters anchor premium integrated-pump system demand.
- Type 2 Diabetes:Insulin-resistant and insulin-dependent populations seeking HbA1c variability reduction. Home care adoption is gaining share fastest among this segment as diagnostic infrastructure expands beyond tier-1 cities into Gujarat and Karnataka.
- Gestational Diabetes:Pregnancy-related glucose intolerance requiring temporary monitoring. Limited reimbursement coverage under central government health schemes constrains addressable market depth.
- Others:Pre-diabetic screening, critical care glycemic control, and sports performance optimization. Inconsistent coverage criteria across state-level insurance programs fragment commercialization pathways.
Clinical standard-of-care resides with Type 1 Diabetes. Volume expansion is redirecting toward Type 2 Diabetes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical Device Parks and Special Economic Zones in Andhra Pradesh and Telangana are concentrating domestic assembly capacity for transmitters and receivers, drawing PLI scheme beneficiaries away from traditional Mumbai-Delhi distribution corridors.
Maharashtra
Mumbai and Pune metropolitan clusters anchor premium-tier demand for integrated pump-sensor systems through established endocrinology hospital networks. CDSCO's streamlined digital health approval pathway accelerates commercialization timelines for manufacturers registering Class C transmitters. Thane-Belapur industrial corridor hosts emerging domestic assembly facilities leveraging PLI incentives for medical electronics.
Tamil Nadu
Chennai's diagnostic infrastructure depth supports accelerating home care adoption among Type 2 diabetes patients seeking Bluetooth-enabled outpatient monitoring. State-level insurance program expansions are broadening reimbursement coverage beyond central government schemes. Coimbatore-Salem manufacturing belt is attracting component suppliers for NFC-based systems targeting government hospital procurement.
Karnataka
Bangalore's research institutions pilot spectroscopic non-invasive glucose sensing approaches that threaten traditional electrochemical sensor addressable markets. BIS certification requirements for wireless medical devices extend pre-market timelines for Bluetooth-enabled platforms. Mysuru-Mandya corridor is emerging as a secondary distribution hub bypassing Chennai congestion for southern peninsula reach.
Delhi-NCR
Private insurance penetration depth in Gurugram and Noida concentrates demand for subscription-based sensor replenishment bundled with teleconsultation. Digital Information Security in Healthcare Act compliance obligations force domestic server infrastructure investments for patient glucose data localization. Faridabad assembly units are repurposing consumer electronics lines toward transmitter manufacturing under PLI scheme coverage.
Gujarat
Ahmedabad-Surat pharmaceutical manufacturing ecosystem creates adjacency opportunities for CGM sensor packaging and sterilization services. Underpenetrated diagnostic infrastructure relative to Maharashtra presents whitespace for tier-2 city expansion as endocrinology networks mature. Mundra port proximity reduces landed costs for imported electrochemical sensor substrates facing freight volatility.
India Continuous Glucose Monitoring (CGM) Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across India's CGM landscape, creating a tiered structure where scale advantages in regulatory navigation clash with agility in algorithmic personalization. The market exhibits moderate consolidation at the premium integrated-pump segment while fragmenting across pharmacy and e-pharmacy channels for standalone sensor-transmitter bundles. Three archetypes dominate: multinational medical device majors with established hospital relationships, Asian electronics manufacturers leveraging component cost advantages, and domestic assemblers exploiting PLI scheme fiscal incentives. Competitive moves center on modular hardware architectures enabling patient upgrade flexibility and subscription-based revenue models displacing upfront hardware purchases.
Among multinational medical device majors, Abbott Laboratories and Dexcom Inc. exemplify the hospital-relationship archetype, while Medtronic plc occupies a position bridging premium integrated systems with long-standing endocrinology center affiliations. Asian electronics manufacturers including Zhejiang POCTech Co. Ltd. represent the component-cost positioning tier, and Senseonics Holdings Inc. sits within the implantable long-term sensor specialization niche. These named entities anchor industry-level commentary on strategic positioning without constraining competitive dynamics to specific corporate actions.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Dexcom Inc. |
| Medtronic plc |
| F. Hoffmann-La Roche Ltd |
| Ascensia Diabetes Care |
| Senseonics Holdings Inc. |
| Ypsomed AG |
| i-SENS Inc. |
| Zhejiang POCTech Co. Ltd. |
| Others |
Supply & Pricing Matrix
Captive sensor manufacturing concentration in electrochemical substrate production anchors both supply security vulnerabilities and pricing power asymmetries across India's CGM landscape. CDSCO's import-dependent approval pathways for foreign-manufactured sensors compress margin flexibility for domestic assemblers while PLI scheme incentives for transmitters and receivers shift cost structures toward locally assembled components.
Pricing Analysis
Lead-time-driven pricing stratification separates subscription-based sensor replenishment models from spot inventory transactions in pharmacy channels. Three-tier pricing structure across premium integrated-pump systems, standard Bluetooth-enabled bundles, and economy NFC-based options reflects certification grade differentiation and after-sales teleconsultation bundling. Cost compression in the economy tier intensifies because government hospital procurement favors lowest-qualified bids for mass screening programs. Price sensitivity concentrates among Type 2 diabetes patients in tier-2 cities seeking first-time CGM adoption, while Type 1 pediatric populations in Mumbai and Delhi absorb premium pricing for integrated systems.
Supply Chain Analysis
Single-source vulnerability sits with electrochemical sensor substrate manufacturing concentrated in the United States, Germany, and Japan. Domestic assembly draws from imported enzymatic filaments, Bluetooth radio modules, and medical-grade polymers for transmitter housings. Tariff exposure on wireless medical device components under BIS certification requirements extends pre-market timelines and inflates landed costs. Distribution runs through Mumbai-Delhi pharmaceutical corridors for institutional procurement and direct-to-patient e-pharmacy channels for subscription replenishment models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's CGM market is consolidating around platform operators controlling end-to-end patient data flows, with CDSCO's data localization mandates forcing smaller foreign competitors toward exit or partnership. Sensor import dependency and reimbursement fragmentation are squeezing margin-poor hardware distributors out of viable economics.
For Market Incumbents:Acquire domestic server infrastructure assets to satisfy Digital Information Security in Healthcare Act compliance obligations without operational disruption. Backward integration into transmitter assembly through PLI scheme facilities in Bangalore or Hyderabad reduces exposure to currency fluctuation on imported radio modules. Optical glucose sensing research at Indian Institutes of Technology threatens electrochemical sensor incumbents within a decade-long technology transition window.
For New Entrants and Emerging Players:Launch via government hospital procurement channels for NFC-based systems targeting mass screening programs in Gujarat and Karnataka rural districts. Tier-2 city diagnostic infrastructure expansion presents whitespace for cost-positioned entrants before endocrinology network maturation. Partnership with state-level insurance programs in Tamil Nadu offers faster reimbursement pathway establishment than central government scheme navigation.
For Investors and Strategic Acquirers:Exit pathways concentrate in acquisition by multinational medical device majors seeking hospital relationship assets and CDSCO registration expertise. Long-term viability favors platform operators with recurring sensor subscription revenue and captive patient data flows over inventory-heavy distribution plays. CDSCO harmonization announcements with EU MDR or FDA 510(k) pathways signal inflection timing for optical sensing technology bets.
| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO Registration Pathway Optimization | Streamlined Class C device approvals compress commercialization timelines for next-generation transmitters. |
| Domestic Assembly Facility Establishment | PLI scheme medical electronics incentives reduce landed costs for Bluetooth and NFC transmitter production. |
| State Insurance Program Partnership | Tamil Nadu and Maharashtra reimbursement expansions broaden addressable patient populations beyond central schemes. |
| Optical Sensing R&D Investment | Spectroscopic calibration-free monitoring threatens electrochemical sensor incumbents in pre-diabetic screening segments. |
| Data Localization Infrastructure Buildout | Domestic server compliance with Digital Information Security in Healthcare Act enables foreign platform market access. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with endocrinologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers validated demand-side assumptions. CDSCO Sugam portal submissions, BIS wireless device certifications, and PLI scheme beneficiary disclosures supplied regulatory and supply-side data. Bottom-up patient population modeling and top-down medical device import value triangulation cross-checked volume estimates.
Granularity-level modeling disaggregated projections across sensor, transmitter, receiver, and smartphone app components with separate treatment of Bluetooth, NFC, and optical technology pathways. End-user segmentation distinguished hospitals, diabetes clinics, home care, and research institutions with distinct pricing and replacement cycle assumptions. CAGRs derived from fitted growth curves incorporating reimbursement policy evolution and diagnostic infrastructure expansion rates across Maharashtra, Tamil Nadu, Karnataka, Delhi-NCR, and Gujarat sub-regions.
PLI scheme incentive revisions, CDSCO-EU MDR harmonization delays, and optical sensing technology breakthroughs are the dominant revision risks to modeled trajectories. Forecasts reflect assumptions on reimbursement framework evolution and sensor substrate import cost stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
France Continuous Glucose Monitoring Market
Diabetes Care
Mexico Continuous Glucose Monitoring Market
Diabetes Care
Global Pet Diabetes Care Market
Diabetes Care
Continuous Glucose Monitoring Market
Diabetes Care
Global Type 2 Diabetes Treatment Market
Diabetes Care
North America Insulin Infusion Pumps Market
Diabetes Care
Brazil Continuous Glucose Monitoring Market
Diabetes Care
Saudi Arabia Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Glycated Albumin Market
Diabetes Care
BRIC Diabetes Care Devices Market
Diabetes Care
North America Insulin Market
Diabetes Care
Australia Self-Monitoring Blood Glucose Market
Diabetes Care
Germany Digital Diabetes Management Market
Diabetes Care
Global Non-Invasive Blood Glucose Monitoring Devices Market
Diabetes Care
Global Continuous Subcutaneous Insulin Infusion Market
Diabetes Care
Oman Insulin Drugs and Delivery Devices Market