
 Peripheral Nerve Stimulators Market | 2026-2036
Peripheral Nerve Stimulators Market Size, Share, and Industry Trends Forecast 2026-2036
Peripheral Nerve Stimulators Market Outlook
The capital-intensity divergence between implantable device manufacturers and external stimulator producers is collapsing as miniaturization costs fall across both categories. Medtronic leverages vertically integrated component fabrication to sustain margin advantages in rechargeable implantable systems. Abbott differentiates through wireless communication platforms that reduce surgical revision rates. Boston Scientific Corporation anchors its position in pain management via broad therapy area coverage across hospital and homecare channels.
Peripheral nerve stimulators are electrotherapeutic devices that deliver targeted electrical impulses to specific neural pathways, with implantable variants typically featuring lithium-ion power cells and biocompatible titanium or polymer housings designed for multi-year residence. These systems modulate afferent pain signaling to treat refractory chronic conditions including complex regional pain syndrome and diabetic neuropathy. Implantable stimulators command the highest value per unit within product type segmentation, while wearable devices represent the fastest-expanding category as homecare settings gain reimbursement traction. Transcutaneous electrical nerve stimulation technology dominates volume flows, though wireless communication capabilities are capturing premium positioning across technology tiers.
FDA premarket approval requirements and the EU Medical Device Regulation shape product development timelines, with both frameworks mandating clinical evidence thresholds that favor established manufacturers with trial infrastructure. The FDA breakthrough device program offers expedited review for neuromodulation therapies addressing opioid-resistant pain, directly influencing R&D allocation across the competitive set. Stakeholders must monitor evolving reimbursement decisions by CMS and Germany's Federal Joint Committee, as coverage determinations for peripheral nerve stimulation procedures will dictate commercial scalability faster than regulatory clearance alone.
Market Dynamics
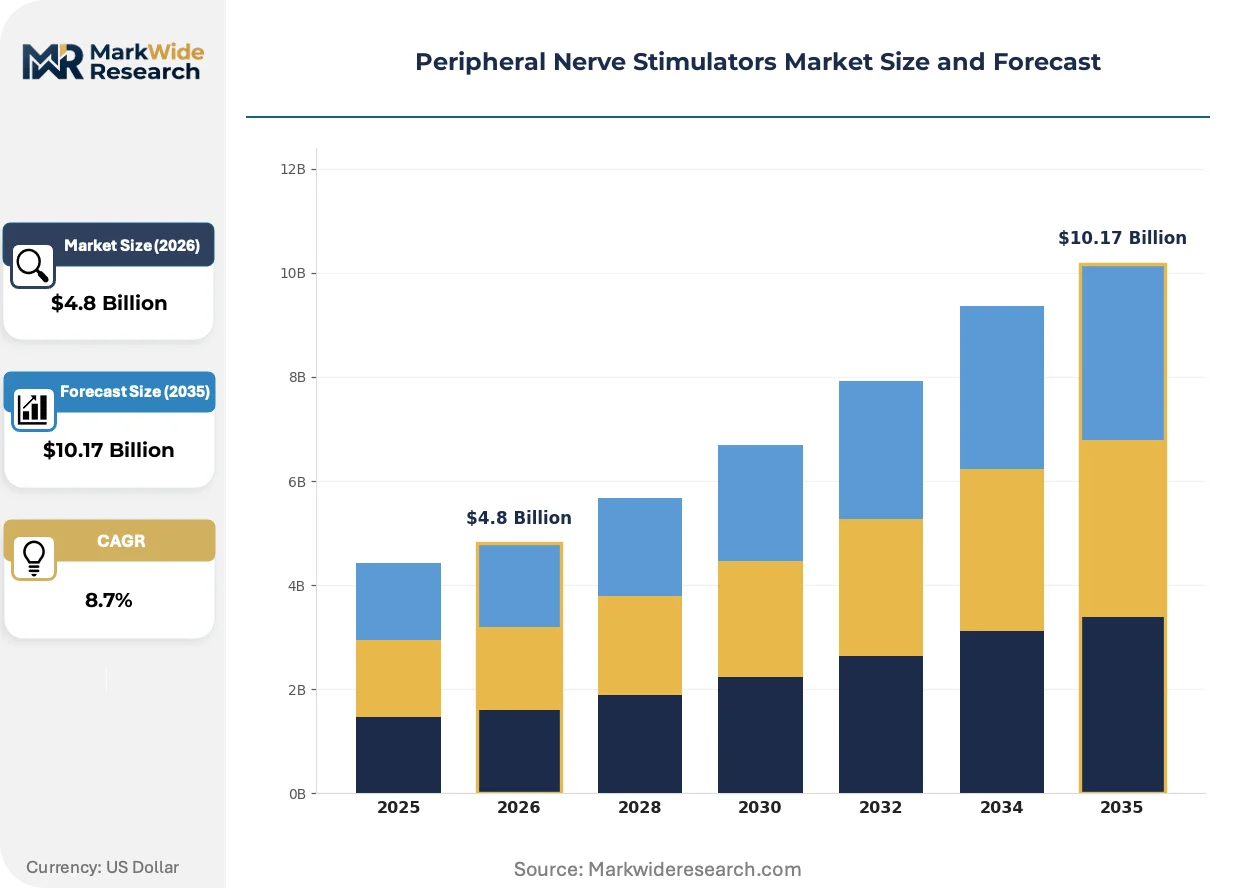
The Peripheral Nerve Stimulators Market is experiencing a structural compression between implantable and external device categories as lithium-ion miniaturization collapses cost barriers that historically separated capital-intensive surgical systems from wearable alternatives.
Growth Catalysts
- FDA Breakthrough Device Designation:Expedited premarket review pathways for neuromodulation therapies addressing opioid-resistant pain are compressing time-to-market for novel systems targeting refractory neuropathy cases.
- Germany's Statutory Reimbursement Frameworks:Mature Federal Joint Committee coverage determinations for peripheral nerve stimulation procedures are establishing predictable payment pathways that accelerate hospital adoption.
- Homecare Channel Expansion:Wearable transcutaneous electrical nerve stimulation devices are capturing new patient populations previously excluded from implantable surgical candidacy due to comorbidity thresholds.
Market Restraints
- Lithium-Ion Supply Concentration:Dependence on East Asian battery cell manufacturers creates input cost volatility and geopolitical exposure for rechargeable implantable system producers.
- EU Medical Device Regulation Clinical Evidence Thresholds:MDR-mandated trial infrastructure requirements favor established manufacturers with dedicated research budgets, raising competitive barriers for emerging entrants.
- Pharmacological Substitution:Extended-release gabapentin formulations and sodium channel blockers retain first-line status in primary care settings, limiting neuromodulation to refractory case escalation.
Strategic Opportunities
- Underpenetrated Ambulatory Surgical Centers:United States outpatient facilities currently lack dedicated neuromodulation programs, creating white space for procedure volume capture outside traditional hospital settings.
- Wireless-Telemetry Convergence:Integration of Bluetooth Low Energy with implantable pulse generators enables remote programming that reduces surgical revision rates and extends device lifecycle value.
- India's CDSCO Accelerated Approval Pathway:Streamlined regulatory channels for medical devices addressing chronic pain are opening market access ahead of full harmonization with international standards.
Industry Challenges
- Biocompatibility Certification Timelines:ISO 10993 testing protocols for novel polymer housings extend development cycles by 18-24 months, compressing effective patent protection windows.
- Electrophysiologist Training Bottlenecks:Specialized surgical placement techniques for lead positioning require fellowship-level expertise that remains concentrated in academic medical centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peripheral Nerve Stimulators Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Implantable Stimulators, External Stimulators, Wearable Devices, Rechargeable Units Therapy Area: Pain Management, Neuromodulation, Rehabilitation, Sleep Disorders End User: Hospitals, Clinics, Rehabilitation Centers, Homecare Settings Technology: Electrical Stimulation, Transcutaneous Electrical Nerve Stimulation, Ultrasound, Wireless Communication |
| Companies Covered | Boston Scientific Corporation, Medtronic, Abbott, B. Braun SE, Bioventus, Avanos Medical, Inc., Nevro Corp., Curonix LLC, SPR Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peripheral Nerve Stimulators Market Strategic Shifts
Neuromodulation hardware is undergoing a platform shift toward closed-loop adaptive systems that respond to real-time neural feedback rather than delivering fixed stimulation patterns.
Implantable pulse generator architecture is miniaturizing through advanced application-specific integrated circuit design and high-density battery packaging. Pain management clinics in the United States are adopting these compact systems for same-day surgical procedures that previously required overnight admission. This compression of form factor is collapsing the historical distinction between implantable and external therapeutic categories.
EU Medical Device Regulation implementation is enforcing stricter clinical evidence requirements for legacy device families previously grandfathered under prior directives. Manufacturers must now conduct post-market clinical follow-up studies for existing implantable neuromodulation systems to maintain CE marking validity. High-value rechargeable segments face the most significant compliance burden as notified bodies prioritize active implantable reviews.
Hospital procurement departments are consolidating vendor relationships through single-source contracts that bundle device supply with technical support and revision surgery coverage. This concentration is displacing traditional multi-vendor purchasing arrangements in German and United States health systems. Academic medical centers with established neuromodulation programs are leading this consolidation, leveraging procedure volume for preferential pricing terms.
Peripheral Nerve Stimulators Market Segmentation
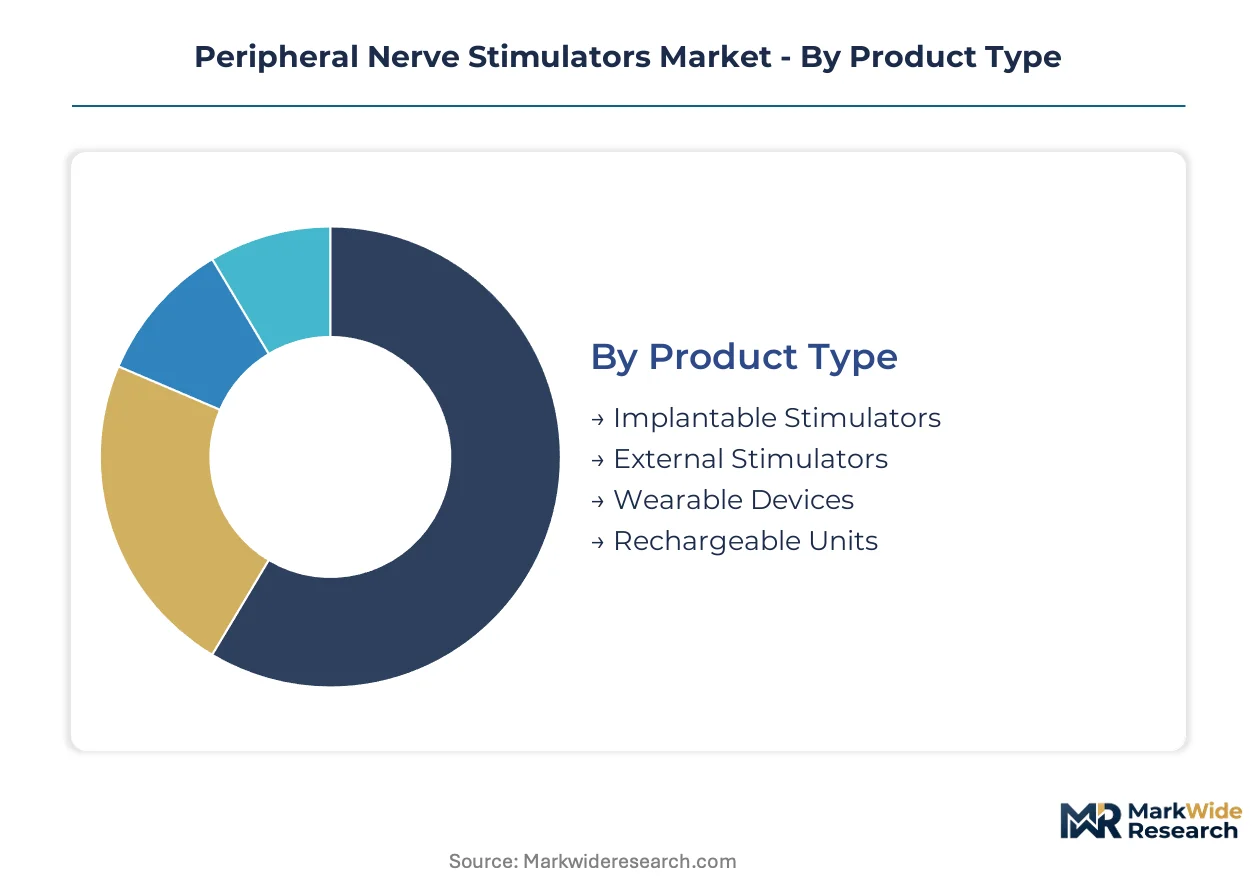
Segmentation in peripheral nerve stimulators determines reimbursement pathways, regulatory requirements, and channel economics. Product form factor dictates whether systems flow through hospital surgical suites or direct-to-consumer retail channels.
Product Type:
Implantable systems generate recurring revenue through battery replacement cycles, while external devices capture volume through pharmacy and durable medical equipment channels.
- Implantable Stimulators:These systems incorporate lithium-ion power cells within biocompatible titanium housings designed for multi-year residence. Pain management clinics in the United States concentrate demand for these devices in refractory neuropathy cases where pharmacological intervention has failed.
- Wearable Devices:Compact form factors with adhesive electrode arrays enable patient-administered therapy without surgical candidacy screening. Homecare settings in Germany drive expansion here as statutory reimbursement frameworks mature for ambulatory treatment.
- External Stimulators:Tabletop or handheld units deliver transcutaneous electrical nerve stimulation through reusable electrode pairs. Rehabilitation centers represent the primary procurement channel for these systems.
- Rechargeable Units:Inductive charging coils eliminate surgical battery replacement, extending device lifecycle value. Hospital procurement departments favor these for total cost-of-ownership reduction in high-volume implant programs.
Implantable stimulators dominate installed base. Wearable devices are where expansion concentrates.
Therapy Area:
Cost tier separation is pronounced across therapeutic applications, with surgical implantation reserved for highest-acuity indications.
- Pain Management:Complex regional pain syndrome and diabetic neuropathy represent the primary addressable populations. FDA breakthrough device designation pathways accelerate premarket review for opioid-resistant pain indications.
- Neuromodulation:Targeted electrical impulse delivery modulates afferent signaling in peripheral neural pathways. Academic medical centers with fellowship-trained electrophysiologists concentrate procedural volume for these advanced applications.
- Rehabilitation:Post-surgical muscle re-education and motor function recovery drive demand for temporary external stimulation protocols. Rehabilitation centers in Germany leverage mature reimbursement frameworks for extended therapy courses.
- Sleep Disorders:Hypoglossal nerve stimulation and related applications address obstructive sleep apnea through nocturnal electrical modulation. Sleep medicine clinics represent an emerging channel with limited current penetration.
Pain management commands premium pricing. Neuromodulation is climbing the fastest.
End User:
Customer type determines purchasing authority, with hospital value analysis committees controlling capital-intensive implantable procurement.
- Hospitals:Inpatient surgical suites and dedicated pain management centers handle complex lead placement procedures. United States health systems are consolidating vendor relationships through single-source contracts bundling device supply with revision surgery coverage.
- Homecare Settings:Patients self-administer external stimulation therapy with remote clinician oversight. Germany's Federal Joint Committee reimbursement determinations enable direct-to-patient distribution for qualified wearable systems.
- Clinics:Outpatient facilities provide trial stimulation and programming services without overnight admission. Ambulatory surgical centers in the United States currently lack dedicated neuromodulation programs, creating white space for volume capture.
- Rehabilitation Centers:Physical therapy protocols incorporate electrical stimulation for muscle strengthening and pain modulation. These facilities prioritize external devices with simplified user interfaces for therapist-operated treatment sessions.
Hospitals dominate implantable system procurement. Homecare settings are gaining share fastest.
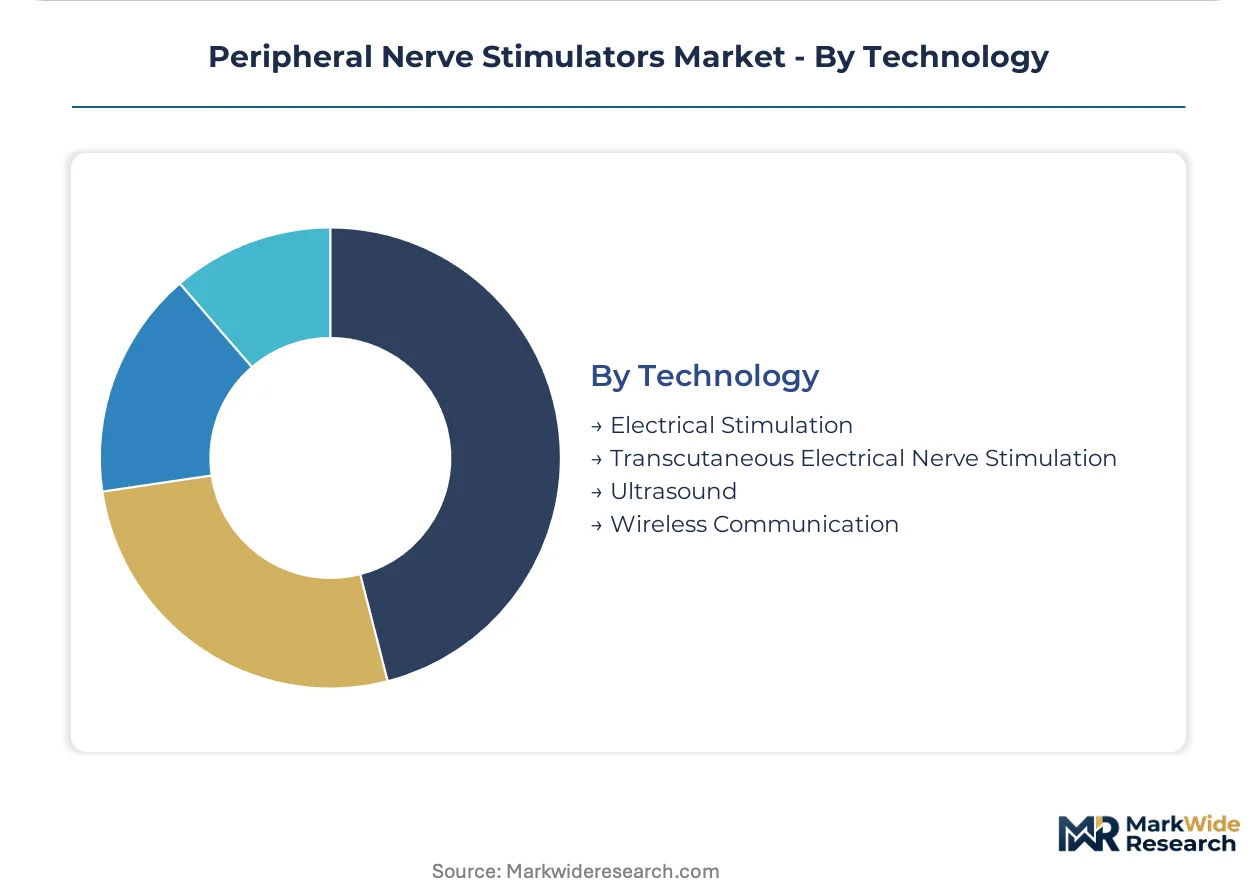
Technology:
Maturity curves diverge sharply, with established electrical stimulation platforms facing displacement from wireless-enabled next-generation systems.
- Transcutaneous Electrical Nerve Stimulation:Surface electrode delivery of pulsed electrical currents for temporary pain relief. This technology saturates volume flows across retail pharmacy and durable medical equipment channels.
- Wireless Communication:Bluetooth Low Energy integration enables remote programming and real-time therapy adjustment. Pain management clinics adopt these capabilities to reduce surgical revision rates and extend device lifecycle value.
- Electrical Stimulation:Percutaneous or implanted lead delivery of targeted impulses to specific neural pathways. Implantable pulse generator architecture miniaturization is collapsing cost barriers historically separating surgical and external categories.
- Ultrasound:Therapeutic sound wave delivery for tissue penetration without electrode contact. This modality remains confined to specialized rehabilitation applications with limited neuromodulation penetration.
Transcutaneous electrical nerve stimulation dominates volume. Wireless communication is where technology investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity in peripheral nerve stimulators varies sharply by reimbursement maturity. Germany's statutory frameworks insulate buyers from device costs, while out-of-pocket markets in India and Brazil force acute price discipline on manufacturers.
United States
Chronic pain clinics drive implantable device adoption for refractory neuropathy cases. FDA breakthrough device designation pathways compress premarket review timelines for opioid-resistant pain therapies. Minneapolis and Boston anchor the highest concentration of neuromodulation procedure volume.
Germany
Federal Joint Committee reimbursement determinations establish predictable payment pathways for peripheral nerve stimulation. EU Medical Device Regulation mandates clinical evidence thresholds that favor established manufacturers with trial infrastructure. North Rhine-Westphalia hospitals lead consolidation of vendor relationships through single-source contracts.
China
NMPA regulatory harmonization accelerates market access for neuromodulation systems addressing diabetic neuropathy prevalence. Domestic battery cell manufacturers reduce input cost volatility for rechargeable implantable producers. Shanghai medical device clusters concentrate R&D investment in miniaturized pulse generator architecture.
India
CDSCO accelerated approval pathways open market access ahead of full international standard harmonization. Out-of-pocket payment structures compress pricing for external stimulators in homecare settings. Maharashtra's Mumbai-Pune corridor attracts contract manufacturing for transcutaneous electrical nerve stimulation devices.
Japan
PMDA regulatory frameworks maintain stringent clinical evidence requirements for active implantable medical devices. Aging demographics expand the addressable population for chronic pain management interventions. Tokyo academic medical centers concentrate fellowship-trained electrophysiologist expertise for complex lead placement procedures.
Peripheral Nerve Stimulators Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. The vendor base concentrates around diversified medical device conglomerates with vertically integrated component fabrication and specialized neuromodulation pure-plays with focused therapy portfolios. Three archetypes dominate: integrated device manufacturers with captive battery supply, wireless-communication platform specialists, and external stimulator mass-market producers. Competitive moves center on M&A for regulatory trial infrastructure and strategic partnerships for ambulatory surgical center channel access.
Among diversified conglomerates, Boston Scientific Corporation, Medtronic, and Abbott exemplify distinct strategic positioning. Boston Scientific Corporation anchors pain management coverage across hospital and homecare channels. Medtronic occupies a position sustained by in-house production of rechargeable implantable system components. Abbott represents the wireless-telemetry convergence archetype through communication platform differentiation. These three entities sit within the premium-tier implantable segment where regulatory clearance timelines and reimbursement relationships determine commercial scalability.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Medtronic |
| Abbott |
| B. Braun SE |
| Bioventus |
| Avanos Medical, Inc. |
| Nevro Corp. |
| Curonix LLC |
| SPR Therapeutics |
| Others |
Value Chain & Pricing Dynamics
Capacity reservation agreements with East Asian battery cell manufacturers lock in lithium-ion supply access while anchoring price visibility for rechargeable implantable system producers. These contractual structures insulate vertically integrated device manufacturers from spot market volatility in raw material inputs.
Pricing Analysis
Battery replacement service contracts generate lifetime value that exceeds initial hardware margins across implantable neuromodulation portfolios. Pricing stratifies across premium, standard, and economy tiers based on wireless telemetry capability and biocompatibility certification grade. Cost compression in wearable transcutaneous segments is intensifying because pharmacy channel distributors consolidate procurement volumes. Homecare settings in Germany exhibit lowest price sensitivity due to Federal Joint Committee reimbursement coverage, while out-of-pocket markets in India force acute price discipline on external stimulator producers.
Supply Chain Analysis
Inventory buffers for titanium housings and polymer electrode arrays stretch lead times by six to eight weeks across implantable device assembly operations. Component sourcing concentrates in China, South Korea, and Japan for lithium-ion cells, application-specific integrated circuits, and biocompatible polymer substrates. Single-source vulnerability in inductive charging coil manufacturing creates exposure to logistics chokepoints at Shanghai port facilities. Distribution runs through hospital value analysis committees for implantable systems and durable medical equipment distributors for external devices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Remote programming and battery replacement services represent a recurring-revenue layer expanding faster than hardware sales across peripheral nerve stimulation portfolios. This service-attach dynamic repositions commercial viability toward lifecycle value capture rather than transactional device margins.
For Market Incumbents: Secure exclusive supplier status within consolidating United States hospital systems through bundled contracts covering device supply, technical support, and revision surgery coverage. Deepen in-house production of lithium-ion power management components to reduce exposure to East Asian battery cell price volatility. Lock in electrophysiologist training partnerships at academic medical centers to defend procedural volume against emerging wireless-telemetry competitors.
For New Entrants and Emerging Players: Differentiate on closed-loop adaptive stimulation algorithms that respond to real-time neural feedback rather than fixed output patterns. Target ambulatory surgical centers in the United States where dedicated neuromodulation programs remain underdeveloped. Pursue CDSCO accelerated approval pathways in India to establish market presence ahead of full international standard harmonization.
For Investors and Strategic Acquirers: Wireless-communication platform specialists with FDA breakthrough device designations represent the most defensible acquisition targets within the neuromodulation value chain. Long-term viability hinges on reimbursement relationship depth rather than regulatory clearance velocity alone. Watch CMS coverage determinations for peripheral nerve stimulation procedures as the primary inflection signal for commercial scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Single-source contracts with United States health systems bundle device supply with revision surgery coverage. |
| FDA Breakthrough Device Pathway | Expedited premarket review for opioid-resistant pain therapies compresses time-to-market for novel systems. |
| Software Companion Development | Bluetooth Low Energy integration enables remote programming that reduces surgical revision rates. |
| Reimbursement Strategy | Federal Joint Committee coverage determinations in Germany establish predictable payment pathways. |
| CE Marking Pathway | EU Medical Device Regulation compliance maintains market access across statutory health insurance frameworks. |
Study Parameters
Cross-validation between primary interviews with pain management clinicians, hospital purchasing committee members, biomedical engineers, and GPO contracts managers anchors the qualitative findings against secondary validation from FDA premarket approval filings, CMS Medicare reimbursement databases, hospital procurement records, and EU Medical Device Regulation notified body documentation. Bottom-up installed base modeling and top-down therapy area penetration estimates triangulate volume and value outputs.
Sensitivity analysis around lithium-ion cell cost trajectories and Federal Joint Committee reimbursement decision timing frames the analytical approach across the projection horizon. Segmentation dimensions include product form factor, therapy area acuity, end-user channel type, and wireless communication capability tier. CAGRs derive from procedure volume growth rates, device replacement cycles, and service revenue attachment coefficients.
The analysis sits within stated boundaries; outcomes outside FDA breakthrough designation velocity or CMS coverage expansion would require recalibration. Forecasts reflect assumptions around electrophysiologist training pipeline throughput and biocompatibility certification timeline stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Intra-Cranial Pressure (ICP) Monitor Market
Medical Devices
Wearable ECG Sensor Market
Medical Devices
Mucus Clearance Devices Market
Medical Devices
Global Gynecology Robotic Surgery Market
Medical Devices
Intervertebral Implants Market
Medical Devices
Airway Clearance Systems Market
Medical Devices
India Spinal Fusion Devices Market
Medical Devices
Global Wearable Injectors Market
Medical Devices
Nasal Atomizer Devices Market
Medical Devices
Endodontic Devices Market
Medical Devices
China Ultrasound Devices Market
Medical Devices
Australia Aesthetic Devices Market
Medical Devices
Struts Implants Market
Medical Devices
Anterior Cervical Plating Market
Medical Devices
Rechargeable Medical Battery Market
Medical Devices
Global Medical Laser Systems Market