
 Bipolar Disorders Treatment Market | 2026-2036
Bipolar Disorders Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Bipolar Disorders Treatment Market Analysis
Maintenance and adherence monitoring services are decoupling from pure drug dispensing, creating recurring revenue streams that reshape pharmaceutical economics. Johnson & Johnson leverages its digital health infrastructure to embed patient-tracking tools alongside its therapeutic portfolio. Eli Lilly and Company anchors its bipolar franchise through intensive R&D investment in next-generation mood stabilizers. Alkermes plc differentiates via its long-acting injectable platforms that reduce relapse frequency in outpatient settings.
Bipolar disorders treatment encompasses pharmacological and psychosocial interventions targeting manic, depressive, and mixed episodes through neurotransmitter modulation and behavioral stabilization; lithium carbonate remains the reference-standard mood stabilizer with narrow therapeutic windows requiring routine serum monitoring. Antipsychotics command the largest revenue pool among product types due to their expanded labeling across bipolar I maintenance and acute mania, while psychotherapy grows fastest as payers integrate coordinated specialty care models. Injectable delivery modes capture premium positioning through compliance advantages, though oral formulations still dominate prescription volumes across outpatient facilities and home care channels.
The FDA's Risk Evaluation and Mitigation Strategies shape antipsychotic market access through mandatory prescriber certifications and patient registries, while the DEA controls scheduled compounds used in acute agitation management. EMA's centralized marketing authorization procedures govern European commercialization, with national health technology assessment bodies determining reimbursement eligibility country-by-country. Stakeholders must monitor evolving FDA digital therapeutics guidance, as software-based adjunctive interventions for bipolar disorder advance through pilot programs and seek formal classification pathways.
Market Dynamics
The FDA's accelerated approval pathways for novel antipsychotic therapies are compressing commercialization timelines and forcing incumbents to accelerate digital health integration alongside traditional drug development.
Growth Catalysts
- Reimbursement Expansion:Recent federal legislation in the United States has broadened mental health service coverage, expanding patient access to specialty clinic outpatient psychiatric services.
- Long-Acting Injectable Platforms:These delivery technologies reduce relapse frequency in outpatient settings, creating premium positioning through compliance advantages over oral formulations.
- Digital Therapeutics Guidance:Evolving FDA frameworks for software-based adjunctive interventions are advancing pilot programs toward formal classification pathways.
Market Restraints
- Narrow Therapeutic Windows:Lithium carbonate requires routine serum monitoring, creating infrastructure burdens for outpatient facilities and home care channels.
- DEA Scheduling Controls:Acute agitation management compounds face strict distribution limitations, constraining prescriber flexibility in emergency settings.
- Risk Evaluation and Mitigation Strategies:Mandatory prescriber certifications and patient registries create administrative friction for antipsychotic market access.
Strategic Opportunities
- Maintenance Service Decoupling:Adherence monitoring services are separating from pure drug dispensing, enabling recurring revenue streams that reshape pharmaceutical economics.
- EMA Centralized Authorization:European marketing authorization procedures create pathway efficiencies for products seeking multi-country commercialization.
- Coordinated Specialty Care Models:Psychotherapy integration with pharmacological treatment is accelerating as payers demand bundled care outcomes.
Industry Challenges
- Prescriber Certification Bottlenecks:Mandatory training requirements under REMS programs constrain prescriber pool expansion and delay therapy initiation.
- Cross-Border Reimbursement Fragmentation:National health technology assessment bodies in Europe determine eligibility country-by-country, complicating commercial planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bipolar Disorders Treatment Market |
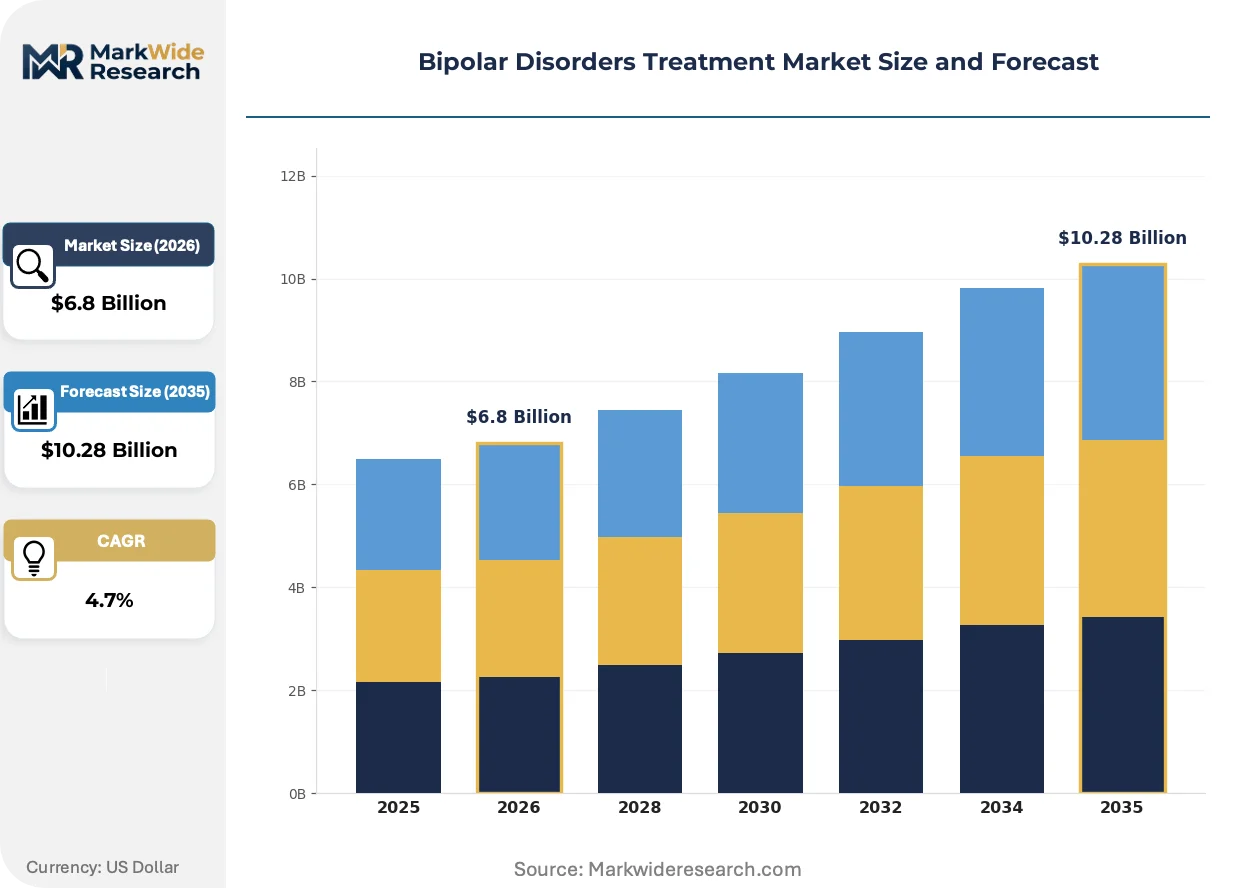
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antidepressants, Mood Stabilizers, Antipsychotics, Psychotherapy Delivery Mode: Oral, Injectable, Transdermal, Combination Therapy End User: Hospitals, Specialty Clinics, Outpatient Facilities, Home Care Age Group: Children, Adolescents, Adults, Elderly |
| Companies Covered | AstraZeneca plc, Eli Lilly and Company, GlaxoSmithKline plc, Johnson & Johnson, AbbVie Inc., H. Lundbeck A/S, Alkermes plc, Intra-Cellular Therapies Inc., Otsuka Holdings Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bipolar Disorders Treatment Market Emerging Trajectories
Digital health infrastructure is embedding directly into therapeutic portfolios, creating hybrid care models that extend pharmaceutical value propositions beyond molecule delivery.
Patient-tracking tools are modularizing how pharmaceutical companies engage with bipolar disorder management. Johnson & Johnson embeds these digital health components alongside its therapeutic offerings. Specialty clinics adopt these platforms to monitor outpatient adherence between visits. This technology convergence is modularizing the traditional prescriber-pharmacist-patient relationship into continuous data-driven care loops.
EMA's centralized marketing authorization procedures are harmonizing European commercialization pathways for novel mood stabilizers. National health technology assessment bodies retain country-by-country reimbursement control, creating a two-tier access system. Products seeking European market entry must navigate both centralized safety approval and fragmented payer negotiations.
After-sales service unbundling is reshaping how pharmaceutical economics capture value from bipolar disorder treatment. Maintenance and adherence monitoring now generate standalone revenue rather than subsidizing drug margins. This shift concentrates in the United States where reimbursement frameworks accommodate service-based billing codes. Specialty clinics lead adoption of these unbundled models, integrating them into outpatient psychiatric service expansion.
Bipolar Disorders Treatment Market Segmentation
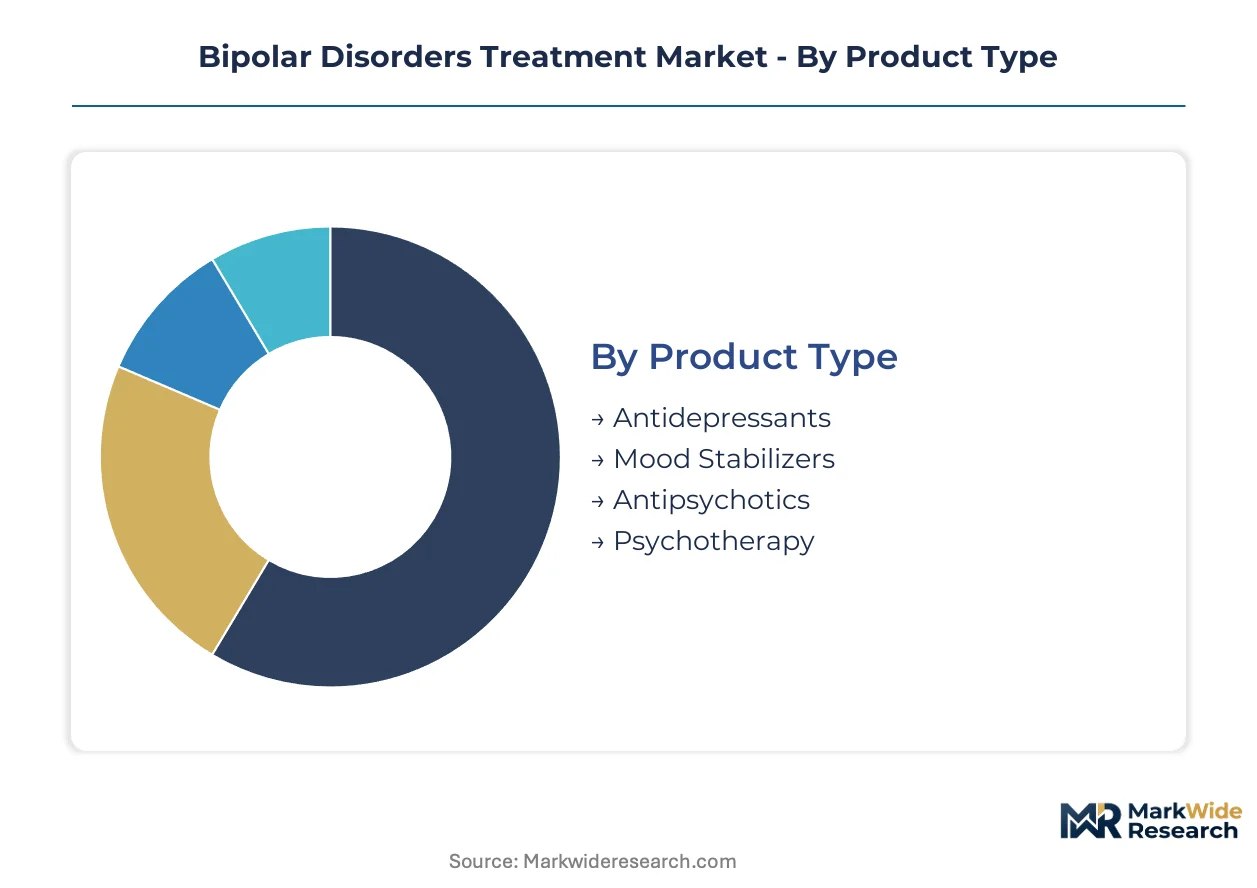
Treatment modality selection in bipolar disorder management hinges on episode severity, compliance history, and care setting infrastructure. Segmentation reveals how pharmaceutical supply chains align with prescriber certification requirements and reimbursement coding structures across delivery environments.
Product Type:
Supply concentration clusters around antipsychotic manufacturing capacity, with API sourcing networks favoring established GMP-certified facilities.
- Antipsychotics:These agents modulate dopamine and serotonin pathways to manage acute mania and maintenance phases. Demand concentrates in United States specialty clinics where FDA Risk Evaluation and Mitigation Strategies mandate prescriber certifications, creating administrative barriers that favor incumbent suppliers with established REMS infrastructure.
- Mood Stabilizers:Lithium carbonate and valproate derivatives require routine serum monitoring due to narrow therapeutic windows. Outpatient facilities in Germany and France absorb significant volumes where national health technology assessment bodies have codified monitoring reimbursement.
- Antidepressants:Selective serotonin reuptake inhibitors and related compounds address depressive episodes with broader prescriber eligibility.
- Psychotherapy:Cognitive behavioral and interpersonal therapy protocols are gaining integrated care model adoption.
Antipsychotics absorb the bulk of installed capacity; psychotherapy is expanding most quickly.
Delivery Mode:
Cost tier differentiation separates premium injectable formulations from commodity oral generics, with reimbursement rates determining facility adoption thresholds.
- Injectable:Long-acting formulations reduce relapse frequency through guaranteed bioavailability over weeks or months. Specialty clinics in the United Kingdom and Netherlands prioritize these platforms where bundled payment models reward reduced hospitalization rates.
- Oral:Immediate and extended-release tablets dominate prescription volumes across outpatient facilities due to lower per-dose costs and prescriber familiarity. Home care channels in Japan favor oral regimens where METI guidelines support remote monitoring technologies.
- Transdermal:Patch-based delivery offers steady plasma concentration profiles for select mood stabilizers.
- Combination Therapy:Multi-modal regimens integrate pharmacological and psychosocial interventions under single care plans.
Oral formulations retain volume leadership; injectable platforms are climbing the fastest.
End User:
Customer type fragmentation reflects divergent infrastructure requirements for serum monitoring, REMS compliance, and digital health integration.
- Specialty Clinics:These facilities combine psychiatric expertise with laboratory capacity for lithium monitoring and REMS program administration. Expansion concentrates in United States metropolitan areas where recent federal legislation broadened mental health service reimbursement.
- Hospitals:Acute care settings manage severe manic episodes and medication stabilization prior to discharge.
- Outpatient Facilities:Community-based centers handle maintenance therapy with varying monitoring capabilities.
- Home Care:Remote monitoring platforms enable lithium therapy outside institutional settings where digital infrastructure permits.
Specialty clinics absorb the bulk of installed capacity; home care is gaining share fastest.
Age Group:
Application requirements vary sharply across developmental stages, with pediatric indications carrying distinct FDA labeling constraints and adult populations driving volume economics.
- Adults:Patients aged 18-64 constitute the primary addressable population with established diagnostic criteria and broad formulary coverage. Prescription volumes concentrate in United States and German outpatient networks where maintenance therapy protocols are most mature.
- Adolescents:Bipolar I diagnosis in patients 13-17 requires careful antipsychotic selection given metabolic side effect profiles.
- Elderly:Age-related pharmacokinetic changes necessitate dose adjustments and enhanced monitoring for drug interactions.
- Children:Pediatric bipolar spectrum presentations below age 12 involve complex differential diagnosis and limited approved therapies.
Adults absorb the bulk of installed capacity; adolescents represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of antipsychotic APIs clusters in India and China, while consumption concentrates in the United States and Western Europe where specialty clinic infrastructure supports complex therapy management.
United States
Specialty clinic expansion in metropolitan corridors drives outpatient psychiatric service growth. The FDA's Risk Evaluation and Mitigation Strategies mandate prescriber certifications for antipsychotic dispensing, creating administrative barriers that favor established suppliers. Boston and New York Metro anchor the highest concentration of REMS-compliant facilities with integrated lithium monitoring laboratories.
Germany
National health technology assessment bodies codify reimbursement for mood stabilizer serum monitoring, expanding outpatient facility adoption. The country's pharmaceutical regulator maintains stringent GMP certification requirements for API importation. North Rhine-Westphalia hosts the densest cluster of psychiatric day clinics with embedded laboratory capacity.
Japan
METI guidelines support remote monitoring technologies that enable lithium therapy in home care channels. The PMDA accelerates review pathways for novel antipsychotic formulations targeting treatment-resistant populations. Tokyo and Osaka metropolitan areas concentrate the nation's psychiatric specialist workforce and digital health infrastructure deployment.
United Kingdom
Bundled payment models reward reduced hospitalization rates, prioritizing long-acting injectable platforms in specialty clinics. NICE technology appraisals determine formulary access for new mood stabilizer entrants. London and the Southeast concentrate prescriber training capacity for complex bipolar disorder management protocols.
India
API manufacturing for generic antipsychotics and mood stabilizers supplies global formulation networks. CDSCO manufacturing facility inspections determine export eligibility to regulated markets. Hyderabad and Ahmedabad anchor contract manufacturing clusters serving European and North American pharmaceutical companies.
Bipolar Disorders Treatment Market Vendor Landscape
Top-tier vendors anchor the antipsychotic maintenance segment, while mid-cap specialists concentrate on long-acting injectable platforms and digital adherence tools. The vendor base stratifies across three archetypes: diversified pharmaceutical conglomerates with psychiatric franchises, pure-play CNS-focused developers, and specialty formulation companies with depot delivery expertise. Consolidation pressure intensifies as FDA accelerated approval pathways compress commercialization timelines for novel mechanisms. Competitive moves center on digital health infrastructure integration and specialty clinic partnership networks that secure REMS-compliant prescriber access.
Among diversified pharmaceutical conglomerates, Johnson & Johnson and Eli Lilly and Company exemplify the integrated-care archetype combining therapeutic portfolios with patient-tracking platforms. Alkermes plc occupies a distinct position within the specialty formulation tier, representing long-acting injectable expertise that reduces relapse frequency in outpatient settings. These three anchors illustrate how competitive positioning increasingly depends on service unbundling rather than molecule differentiation alone.
| Leading Market Players |
|---|
| AstraZeneca plc |
| Eli Lilly and Company |
| GlaxoSmithKline plc |
| Johnson & Johnson |
| AbbVie Inc. |
| H. Lundbeck A/S |
| Alkermes plc |
| Intra-Cellular Therapies Inc. |
| Otsuka Holdings Co. Ltd. |
| Others |
Supply Flow & Price Mechanics
Specialty clinic procurement concentration in United States metropolitan corridors anchors contract-based pricing for long-acting injectable platforms, with bundled reimbursement codes creating three-tier pricing structure across premium, standard, and economy levels based on REMS compliance infrastructure and digital health integration depth.
Pricing Analysis
Margin tightening in oral generic mood stabilizers reflects API oversupply from Indian contract manufacturers and prescriber price sensitivity in outpatient facilities. Price differentiation hinges on FDA REMS certification tier and after-sales adherence monitoring bundling. Cost-down pressure on lithium carbonate formulations accelerates because narrow therapeutic window monitoring requirements shift reimbursement risk to providers. Government payers exhibit highest price sensitivity; specialty clinics with bundled payment contracts demonstrate lowest.
Supply Chain Analysis
Domestic-content mandates in India's pharmaceutical sector reshape API sourcing for generic antipsychotics serving European and North American formulation networks. Active pharmaceutical ingredient manufacturing concentrates in India, China, and the United States. Raw material dependencies include lithium carbonate from South American brine operations, specialty chemical intermediates from Chinese manufacturers, and packaging materials from regional converters. Single-source vulnerability persists for certain dopamine receptor ligand precursors. Distribution runs through GMP-certified depots to REMS-registered specialty clinics and hospital pharmacies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where FDA accelerated approval pathways compress commercialization timelines and force subscale developers toward strategic exits.
For Market Incumbents: Anticipate digital therapeutic classification pathways by embedding patient-tracking tools alongside therapeutic portfolios before formal FDA guidance solidifies. Secure REMS-compliant prescriber networks through specialty clinic partnerships to defend against emerging pure-play CNS developers with streamlined certification infrastructure. Prioritize backward integration into long-acting injectable formulation capacity. For New Entrants and Emerging Players: Digital adherence monitoring platforms offer technology-first wedge into service-unbundled revenue streams where pharmaceutical economics now capture standalone value beyond molecule delivery. Target home care channels in Japan where METI guidelines support remote lithium monitoring and prescriber density remains lowest. Pursue EMA centralized authorization pathways to bypass fragmented national reimbursement negotiations. For Investors and Strategic Acquirers: The window for entry favors specialty formulation companies with depot delivery expertise and existing REMS infrastructure. Long-term viability hinges on regulatory compliance capabilities rather than pipeline depth alone. Watch FDA digital therapeutics guidance finalization as inflection indicator for software-based adjunctive intervention valuations.| Strategic Initiative | Industry Significance |
|---|---|
| REMS Infrastructure Investment | Specialty clinic partnerships secure prescriber certification bottlenecks before competitors consolidate access. |
| Digital Therapeutics Pathway | FDA software classification positions pharmaceutical portfolios for recurring service revenue beyond drug margins. |
| Long-Acting Injectable Scale-Up | Depot formulation capacity captures bundled payment rewards for reduced hospitalization rates in United Kingdom markets. |
| EMA Centralized Authorization | Harmonized European marketing approval creates pathway efficiencies for multi-country commercialization of novel mood stabilizers. |
| API Manufacturing Backward Integration | In-house lithium carbonate production mitigates South American supply concentration and quality variability risks. |
Methodological Framework
FDA filings, EMA centralized procedure documentation, and ClinicalTrials.gov registries formed the secondary backbone, supplemented by SEC 10-K pharmaceutical segment disclosures and national health technology assessment body reimbursement determinations. Primary interviews with drug development executives, regulatory affairs leads, formulary directors at United States payers, and hospital procurement managers validated demand assumptions and pricing dynamics. Bottom-up prescription volume modeling and top-down therapeutic class expenditure analysis enabled triangulation across data sources.
Historical trendline analysis of antipsychotic and mood stabilizer revenue trajectories informed baseline calibration across the projection horizon. Segmentation dimensions modeled include product type, delivery mode, end-user facility category, and regional regulatory cluster. CAGRs derived from curve-fitting approaches applied to approved therapy launch curves and generic erosion patterns. Forecast inputs incorporated FDA review timeline distributions and EMA national reimbursement negotiation lag structures.
Several conditions sit outside the modeled scope, including pipeline discontinuations before regulatory submission, unforeseen REMS program modifications, and macroeconomic shifts affecting mental health service reimbursement prioritization. Forecasts reflect documented assumptions regarding prescriber certification expansion rates and digital health infrastructure adoption curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Musculoskeletal System Disorders Market
Specialty Medicine
Esophageal Atresia Treatment Market
Specialty Medicine
Multiple Sclerosis Market
Specialty Medicine
Urinary Retention Market
Specialty Medicine
Global Plasma Therapeutics Market
Specialty Medicine
Anaplastic Astrocytoma Market
Specialty Medicine
North America Cancer Therapy Market
Specialty Medicine
Global Glaucoma Therapeutics Market
Specialty Medicine
Global Hammertoe Market
Specialty Medicine
Generalized Anxiety Disorder Treatment Market
Specialty Medicine
Megalencephaly-Polymicrogyria-Polydactyly-Hydrocephalus Syndrome Market
Specialty Medicine
Piriformis Syndrome Treatment Market
Specialty Medicine
Global Huntingtons Disease Treatment Market
Specialty Medicine
Nasal Polyposis Treatment Market
Specialty Medicine
Axial Spondyloarthritis Treatment Market
Specialty Medicine
Global Amyotrophic Lateral Sclerosis (ALS) Treatment Market