
 Thailand Oral Antidiabetic Drug Market | 2026-2036
Thailand Oral Antidiabetic Drug Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Oral Antidiabetic Drug Market Insights
Thai pharmaceutical manufacturing capacity is expanding through government-backed production incentives under the Board of Investment's medical hub strategy. Novo Nordisk leverages its insulin portfolio to anchor hospital formulary presence across public and private channels. Takeda competes through DPP-4 inhibitor specialization and deep ties with endocrinology departments in Bangkok's teaching hospitals. Pfizer sustains commercial momentum via broad distribution reach into provincial clinics beyond the capital region.
Oral antidiabetic drugs comprise chemically synthesized or biologically derived pharmaceutical agents administered perorally to lower blood glucose through mechanisms including hepatic glucose suppression, insulin sensitization, or renal glucose excretion inhibition. These formulations typically require bioavailability thresholds above 50 percent and standardized dissolution profiles to ensure therapeutic consistency across patient populations. SGLT2 inhibitors command expanding prescription share among cardiometabolic specialists seeking renal protective outcomes beyond glycemic control. Metformin occupies the dominant volume position as first-line monotherapy across Thailand's universal coverage, social security, and civil servant benefit schemes. Extended-release tablet formulations capture growing preference among elderly patients managing polypharmacy regimens in homecare settings.
Thai FDA registration requirements govern bioequivalence standards for generic substitutions within the National List of Essential Medicines. The Ministry of Public Health's procurement policies shape demand through centralized tender mechanisms that prioritize cost-containment for sulfonylureas and metformin. Stakeholders must monitor how Thailand's pending pharmaceutical benefit management reforms alter reimbursement tiers for novel drug classes versus established therapies.
Market Dynamics
Thailand's universal health coverage scheme is accelerating prescription volume migration toward second-line oral antidiabetic therapies, compressing the historical dominance of sulfonylureas and metformin monotherapy in public hospital formularies.
Growth Catalysts
- Thai FDA's Accelerated Biosimilar Pathway:The streamlined approval framework is expanding therapeutic options within the National List of Essential Medicines, enabling faster formulary inclusion of cost-competitive alternatives.
- Cardiometabolic Specialist Demand:Endocrinology departments in Bangkok's teaching hospitals are prioritizing SGLT2 inhibitors for renal protective outcomes beyond glycemic control, driving prescription share shifts.
- Provincial Network Expansion:Thailand's Ministry of Public Health is extending centralized procurement mechanisms to affiliated regional medical centers, broadening patient access to reimbursed oral therapies.
Market Restraints
- Active Pharmaceutical Ingredient Import Dependence:Thai manufacturers rely on imported metformin and DPP-4 inhibitor raw materials, exposing margins to currency volatility and supply disruptions.
- Cost-Containment Procurement Policies:The Ministry of Public Health's tender mechanisms prioritize lowest-cost sulfonylureas and generic metformin, constraining premium pricing for novel drug classes.
- Bioequivalence Certification Bottlenecks:Thai FDA bioequivalence study requirements for generic substitutions create extended registration timelines that delay market entry.
Strategic Opportunities
- Extended-Release Formulation Development:Elderly polypharmacy patients in homecare settings are driving preference for once-daily dosing regimens that reduce pill burden.
- Provincial Clinic Channel Penetration:Distribution networks beyond Bangkok's tertiary hospital cluster remain underdeveloped, offering first-mover advantages in secondary city medical centers.
- Board of Investment Production Incentives:Thailand's medical hub strategy provides tax privileges and infrastructure support for domestic manufacturing capacity expansion.
Industry Challenges
- Clinical Pharmacist Training Shortfalls:Thailand's endocrinology workforce lacks sufficient specialized personnel to manage complex multi-drug regimens in rapidly expanding patient populations.
- Legacy Formulary Integration Complexity:Hospital pharmacy information systems require substantial reconfiguration to accommodate real-time reimbursement verification for tiered therapy protocols.
- Cross-Scheme Reimbursement Harmonization:Disparities between universal coverage, social security, and civil servant benefit schemes create administrative friction for multi-payer prescribing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Oral Antidiabetic Drug Market |
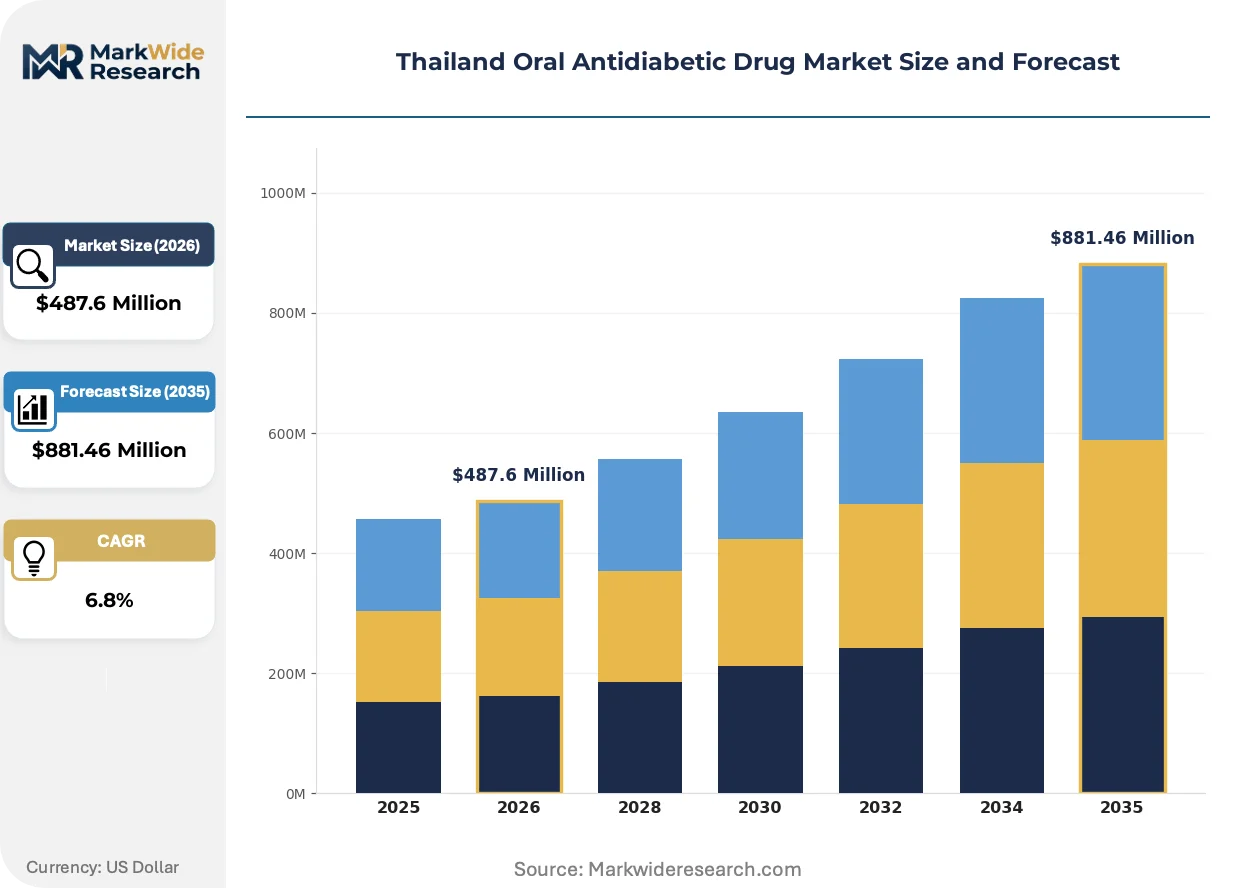
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metformin, DPP-4 Inhibitors, SGLT2 Inhibitors, Sulfonylureas End User: Clinics, Hospitals, Pharmacies, Homecare Form: Tablets, Oral Solutions, Extended Release, Granules Disease Type: Type 1 Diabetes, Type 2 Diabetes, Pre-diabetes, Gestational Diabetes |
| Companies Covered | Takeda, Novo Nordisk, Pfizer, Eli Lilly, Janssen Pharmaceuticals, Astellas Pharma, Boehringer Ingelheim, Merck, AstraZeneca, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Oral Antidiabetic Drug Market Trends and Innovations
Fixed-dose combination therapies are compressing Thailand's oral antidiabetic market structure, enabling single-pill regimens that simplify adherence monitoring and reduce pharmacy dispensing costs across public hospital networks.
SGLT2 inhibitor technology is electrifying treatment protocols in Bangkok's cardiometabolic specialty centers. These agents lower blood glucose through renal glucose excretion inhibition while delivering cardiovascular protective effects. Endocrinology departments at Siriraj and Ramathibodi hospitals are adopting SGLT2 inhibitors at accelerating velocity for patients with comorbid heart failure. This technology is electrifying competitive positioning among manufacturers seeking formulary placement beyond glycemic endpoints.
Thai FDA's bioequivalence guidance revision is tightening generic substitution standards for narrow-therapeutic-index oral antidiabetic drugs. The policy mandates expanded pharmacokinetic study parameters for certain drug classes. Domestic manufacturers and multinational subsidiaries operating in Thailand are responding by expanding in-house clinical trial capabilities to accelerate registration timelines.
Centralized hospital procurement through Thailand's Government Pharmaceutical Organization is consolidating purchasing authority away from individual facility pharmacy committees. Bangkok's tertiary network and provincial medical centers are migrating toward framework agreements that specify volume commitments in exchange for price concessions. This consolidation is most visible in the universal coverage scheme's metformin and sulfonylurea tenders, where single-source awards now dominate previously fragmented purchasing.
Thailand Oral Antidiabetic Drug Market Segmentation
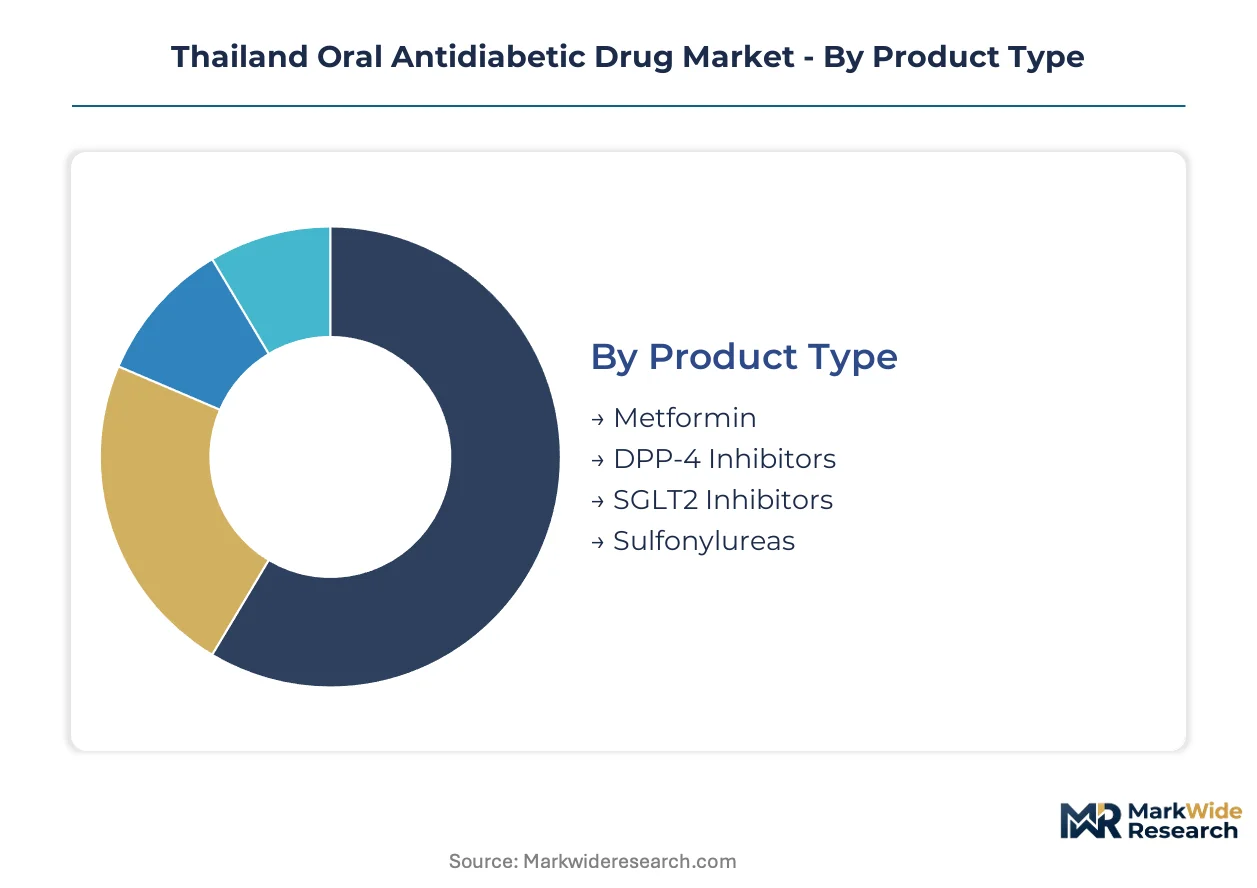
Thailand's oral antidiabetic market fragments along therapeutic mechanism, care setting, formulation technology, and disease severity. Each dimension shapes procurement pathways, reimbursement tiers, and prescriber behavior differently across the universal coverage scheme's three beneficiary populations.
Product Type:
Prescriber familiarity and formulary positioning drive product selection more than price sensitivity alone.
- Metformin:Biguanide-class first-line therapy dominates prescription volumes through established bioequivalence standards and lowest-tier reimbursement across all three national health schemes. Bangkok's tertiary hospitals and provincial medical centers alike prioritize immediate-release and extended-release formulations for treatment-naive patients.
- DPP-4 Inhibitors:Dipeptidyl peptidase-4 inhibitors such as sitagliptin and vildagliptin occupy second-line positioning where metformin monotherapy fails. Endocrinology departments at Siriraj and Ramathibodi teaching hospitals favor these agents for their weight-neutral profile and low hypoglycemia risk in elderly polypharmacy patients.
- SGLT2 Inhibitors:Sodium-glucose cotransporter-2 inhibitors are gaining share fastest among cardiometabolic specialists seeking renal protective outcomes beyond glycemic control.
- Sulfonylureas:Glipizide and glimepiride remain entrenched in cost-containment procurement tiers despite declining preference among academic medical centers.
Volume sits with metformin; growth tilts toward SGLT2 inhibitors.
End User:
Care setting determines reimbursement verification complexity and prescribing authority constraints.
- Hospitals:Tertiary centers in Bangkok and affiliated provincial medical centers concentrate specialist prescribing, formulary committee decisions, and centralized Government Pharmaceutical Organization procurement. These facilities manage complex multi-drug regimens and generate the bulk of second-line therapy initiations.
- Clinics:Primary care clinics under the universal coverage scheme handle stable patient maintenance and first-line therapy titration. Provincial clinic networks beyond Bangkok remain underdeveloped for novel drug class distribution.
- Pharmacies:Community pharmacies dispense chronic refills for established regimens with minimal clinical oversight.
- Homecare:Elderly patients managing polypharmacy in home settings drive demand for extended-release formulations and blister-pack compliance aids.
Prescription authority concentrates in hospitals; patient touchpoints are expanding fastest in clinics.
Form:
Manufacturing capability and bioavailability requirements shape formulation availability.
- Tablets:Immediate-release compressed tablets remain the default dosage form for metformin and sulfonylureas across all procurement tiers. Thai manufacturers maintain substantial domestic capacity for these high-volume products.
- Extended Release:Matrix and osmotic pump technologies enable once-daily dosing that reduces pill burden for elderly patients managing multiple chronic conditions in homecare settings.
- Oral Solutions:Liquid formulations serve pediatric populations and adults with swallowing difficulties, though volumes remain limited by stability and packaging costs.
- Granules:Sachet-dosed granules occupy niche positioning for dose-flexibility requirements in geriatric titration protocols.
Standard tablets capture volume share; extended-release formats are climbing fastest on adherence benefits.
Disease Type:
Treatment intensity and therapeutic goals vary sharply across diabetes progression stages.
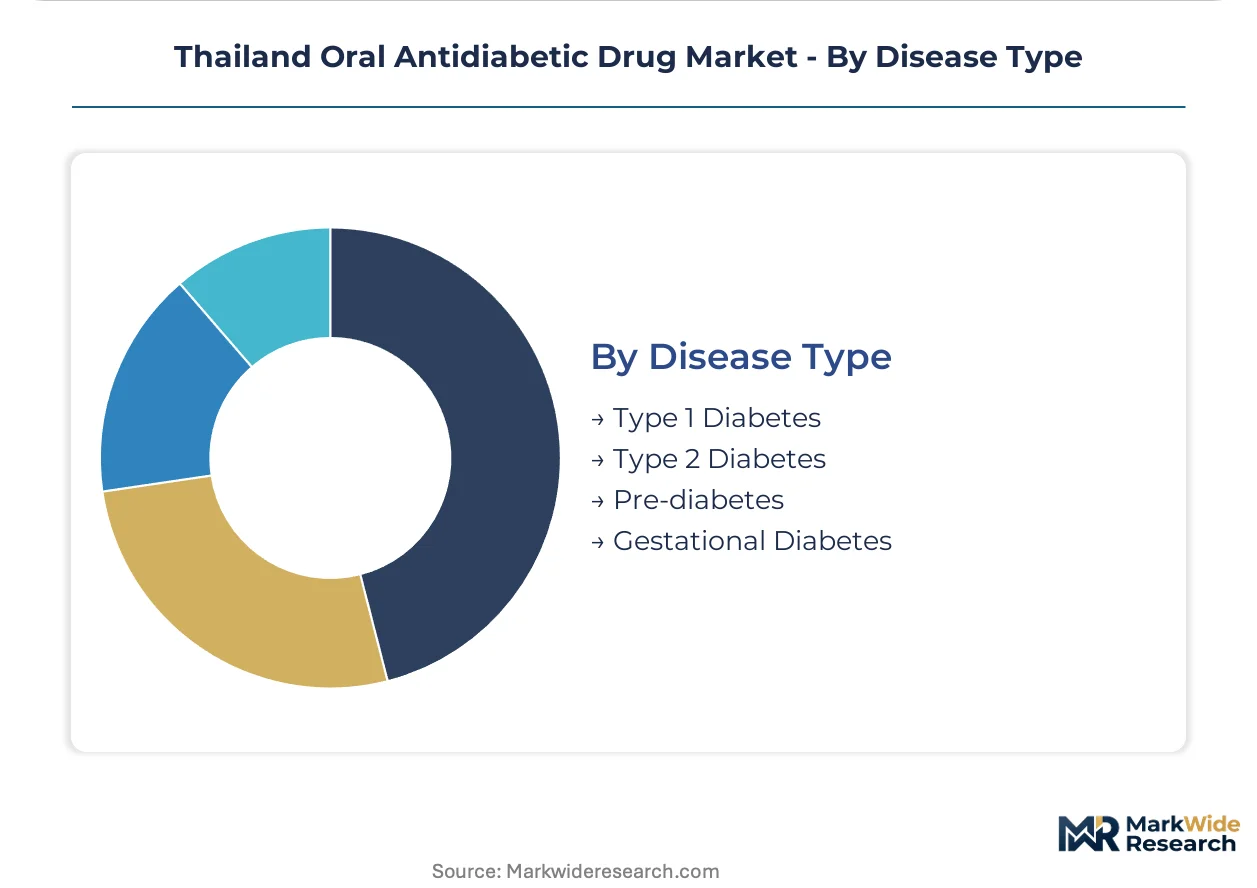
- Type 2 Diabetes:The overwhelming majority of oral antidiabetic prescribing addresses this progressive metabolic disorder. Thailand's aging population and rising obesity prevalence expand the addressable patient pool across universal coverage, social security, and civil servant benefit schemes.
- Type 1 Diabetes:Insulin-dependent patients require minimal oral adjunct therapy, though metformin occasionally features in combination regimens for overweight adolescents.
- Pre-diabetes:Lifestyle intervention dominates, with pharmacotherapy reserved for high-risk progression cases in specialized prevention programs.
- Gestational Diabetes:Insulin remains first-line for glycemic control in pregnancy; oral agents see restricted off-label use in select cases.
Type 2 diabetes commands absolute volume; pre-diabetes pharmacotherapy represents the steepest expansion trajectory as screening intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Active pharmaceutical ingredient sourcing for metformin and DPP-4 inhibitors concentrates in eastern China's chemical manufacturing belt and western India's specialty chemical corridors, with Thai formulators dependent on these feedstock channels.
Greater Bangkok Metropolitan Region
Siriraj Hospital and Ramathibodi Hospital generate concentrated demand for SGLT2 inhibitors and fixed-dose combination therapies. Thailand's universal health coverage scheme processes the majority of second-line therapy reimbursements through this cluster. The Board of Investment's medical hub incentives are attracting multinational packaging operations to Pathum Thani industrial zones.
Central Plains Provinces
Ayutthaya and Saraburi host government pharmaceutical manufacturing facilities supplying metformin to the universal coverage scheme. The Ministry of Public Health's centralized tender mechanisms prioritize lowest-cost sulfonylureas from these state-owned production sites. Provincial medical centers in Nakhon Pathom and Ratchaburi are expanding endocrinology referral capacity.
Eastern Economic Corridor
Chonburi and Rayong provinces are developing pharmaceutical logistics infrastructure under the Eastern Economic Corridor initiative. The Thai FDA maintains regional inspection offices in Laem Chabang to accelerate biosimilar registration for export-oriented manufacturers. Cold-chain distribution networks serving oral antidiabetic formulations are consolidating around this deep-sea port hub.
Northern Thailand
Chiang Mai University Hospital anchors specialist diabetes care for the upper northern region. The social security scheme's reimbursement verification systems face administrative friction when processing cross-regional referrals from Mae Hong Son and Chiang Rai. Domestic manufacturers are testing extended-release tablet stability in high-humidity monsoon conditions at pilot facilities in Lampang.
Southern Peninsula
Hat Yai Hospital in Songkhla Province manages complex multi-drug regimens for Malay-Muslim populations with distinct dietary compliance patterns. The civil servant benefit scheme maintains separate procurement protocols for this region's government hospital network. Cross-border pharmaceutical trade with Malaysia's Kelantan state creates informal distribution channels for unregistered oral antidiabetic products.
Thailand Oral Antidiabetic Drug Market Competitive Landscape
Global majors compete with regional champions across hospital formulary access and procurement channel penetration. The market structure tilts toward multinational pharmaceutical corporations with established insulin portfolios that anchor broader metabolic disorder presence. Three archetypes dominate: integrated diabetes care specialists leveraging endocrinology department relationships, diversified pharmaceutical conglomerates with broad distribution infrastructure, and biosimilar-focused manufacturers exploiting Thai FDA accelerated pathways. Competitive moves concentrate on securing Government Pharmaceutical Organization tender awards and expanding provincial clinic channel coverage.
Among the integrated specialists, Novo Nordisk and Takeda exemplify contrasting positioning archetypes. Novo Nordisk occupies the hospital-centric tier through its insulin portfolio's formulary anchoring effect. Takeda represents the DPP-4 inhibitor specialization model with concentrated presence in Bangkok's teaching hospital network. Pfizer sits within the diversified infrastructure tier, leveraging distribution reach into provincial clinics beyond the capital region.
| Leading Market Players |
|---|
| Takeda |
| Novo Nordisk |
| Pfizer |
| Eli Lilly |
| Janssen Pharmaceuticals |
| Astellas Pharma |
| Boehringer Ingelheim |
| Merck |
| AstraZeneca |
| Others |
Pricing and Supply Chain Analysis
Thailand's medical hub sustainability certification gates qualified supplier status and premium-tier pricing access for oral antidiabetic manufacturers seeking Government Pharmaceutical Organization tender participation. Board of Investment green manufacturing incentives tether pricing power to demonstrable environmental compliance across production facilities.
Pricing Analysis
Service bundling separates tender-winning bids from commodity suppliers, with bioequivalence certification support and pharmacist training programs included in premium offerings. Three-tier pricing structure across originator, qualified generic, and unbranded commodity levels reflects Thai FDA registration tier and bioequivalence study depth. Cost compression in the universal coverage scheme's sulfonylurea tenders intensifies as centralized procurement consolidates volume. Provincial clinic networks exhibit highest price sensitivity; Bangkok's teaching hospitals prioritize clinical service bundles over per-unit cost.
Supply Chain Analysis
Direct-to-hospital channels handle Government Pharmaceutical Organization centralized demand, while distributor networks serve private pharmacy and provincial clinic segments. Active pharmaceutical ingredient sourcing concentrates in eastern China's chemical manufacturing belt and western India's specialty chemical corridors. Thai formulators draw from imported metformin, DPP-4 inhibitor intermediates, and SGLT2 inhibitor raw materials. Single-source vulnerability in Chinese API feedstock exposes margins to currency volatility and logistics disruption. Cold-chain distribution runs through the Eastern Economic Corridor's Laem Chabang port infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thailand's oral antidiabetic market is becoming a vertical-integration race as manufacturers pursue backward control over API supply to defend margins against import cost volatility.
For Market Incumbents: Extend formulation development capabilities into extended-release technologies that reduce dosing frequency for elderly polypharmacy patients. Secure captive supply of DPP-4 inhibitor intermediates through joint ventures with Indian specialty chemical manufacturers to offset raw material cost pressure. Novo Nordisk's insulin portfolio anchoring effect demonstrates how metabolic disorder breadth protects formulary position against single-product competitors.
For New Entrants and Emerging Players: Enter via the provincial clinic channel beyond Bangkok's tertiary hospital cluster, where distribution infrastructure remains underdeveloped and first-mover advantages await. Target the social security scheme's reimbursement tier for second-line therapies, where prescriber familiarity with novel drug classes is building fastest. Partner with domestic manufacturers holding Board of Investment incentives to accelerate Thai FDA registration through existing bioequivalence study infrastructure.
For Investors and Strategic Acquirers: Thai FDA accelerated biosimilar pathway approvals crossing ten registrations annually is the leading indicator that manufacturing capacity expansion will outpace demand absorption. Mid-scale domestic producers with established Government Pharmaceutical Organization relationships and in-house clinical trial capabilities represent the most defensible acquisition profile. Monitor Board of Investment incentive utilization rates as the signal for sustainable cost-competitive positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Bioequivalence Study Infrastructure Expansion | Thai FDA registration timelines compress for manufacturers with in-house clinical pharmacology capabilities. |
| Extended-Release Formulation Development | Once-daily dosing regimens capture elderly patient preference in homecare settings. |
| Provincial Clinic Distribution Partnership | Secondary city medical centers outside Bangkok offer underpenetrated channel access. |
| API Supply Joint Venture | Backward integration into Indian and Chinese feedstock hedges currency and logistics risk. |
| Medical Hub Sustainability Certification | Board of Investment green manufacturing incentives unlock tax privileges and tender preference. |
Research Methodology
Independent corroboration across hospital pharmacy directors, Government Pharmaceutical Organization procurement officers, Thai FDA regulatory affairs leads, and endocrinology department heads underwrites the qualitative findings in this study. Primary interviews with formulary committee members at Siriraj and Ramathibodi hospitals combined with secondary validation from Thai FDA registration databases, National List of Essential Medicines revision records, and Ministry of Public Health tender announcements. Bottom-up prescription volume modeling and top-down scheme expenditure analysis triangulate market size estimates.
Comparable historical period anchoring to universal coverage scheme expansion phases and social security benefit revisions structured the forecast window across the projection horizon. Segmentation modeling incorporated therapeutic mechanism, care setting, formulation technology, and disease severity dimensions. CAGRs derived from volume trend extrapolation adjusted for reimbursement tier migration patterns and prescriber behavior shifts. Thai FDA approval velocity and Board of Investment incentive uptake served as industry-specific forecast sensitivity inputs.
Revisions become necessary when pharmaceutical benefit management reforms alter reimbursement tiers, bioequivalence certification bottlenecks extend registration timelines, or API supply disruptions materialize from geopolitical friction. Forecasts reflect documented assumptions regarding scheme expansion continuity and prescriber adoption curves for novel drug classes. Periodic stress-testing of base assumptions against tender award patterns and provincial clinic network development is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
New Zealand Self-Monitoring Blood Glucose Market
Diabetes Care
Diabetes Care Devices Market
Diabetes Care
Smart Glucose Monitors Market
Diabetes Care
Type 2 Diabetes Market
Diabetes Care
Vietnam Oral Anti-Diabetic Drug Market
Diabetes Care
India Oral Anti-Diabetic Drug Market
Diabetes Care
Middle-East and Africa Blood Glucose Monitoring Market
Diabetes Care
Continuous Glucose Monitoring in Philippines Market
Diabetes Care
Global Continuous Glucose Monitoring Systems Market
Diabetes Care
Japan Insulin Infusion Pump Market
Diabetes Care
New Zealand Continuous Glucose Monitoring Devices Market
Diabetes Care
Global Pet Diabetes Care Market
Diabetes Care
Self-Monitoring Blood Glucose Devices Market
Diabetes Care
United States Self-Monitoring Blood Glucose Market
Diabetes Care
Oman Insulin Drugs and Delivery Devices Market
Diabetes Care
Middle East and Africa Continuous Glucose Monitoring Market