
 Hyperglycemia Treatment Market | 2026-2036
Hyperglycemia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Hyperglycemia Treatment Market Foresight
Market Context with Strategic Players
CE marking under the EU Medical Device Regulation is collapsing the window for unapproved continuous glucose monitors and automated insulin delivery systems in European markets. Novo Nordisk A/S leverages its integrated insulin and GLP-1 portfolio to dominate Nordic and North American prescribing patterns. Eli Lilly and Company anchors its position through manufacturing scale in injectable and oral antidiabetic formulations. Sanofi competes aggressively in basal insulin analogs across hospital and retail pharmacy channels.
Technical Definition and Structural Segments
Hyperglycemia treatment encompasses pharmacological and device-based interventions that reduce elevated blood glucose through insulin supplementation, insulin sensitization, or enhanced glucose-dependent insulin secretion, with formulations ranging from recombinant human insulin to dipeptidyl peptidase-4 inhibitors and sodium-glucose cotransporter-2 modulators. Injectable delivery modes, particularly insulin and GLP-1 receptor agonists, command the deepest margin pools due to cold-chain logistics barriers and biosimilar lag, while oral DPP-4 inhibitors and metformin sustain volume leadership in outpatient diabetes management. Homecare end users represent the fastest-growing channel as remote patient monitoring and mail-order pharmacy fulfillment displace traditional clinic-based titration protocols.
Regulatory Frame and Forward-Looking Close
FDA, EMA, and WHO prequalification standards govern clinical trial endpoints, manufacturing quality, and post-market safety reporting for antihyperglycemic agents and delivery devices. These frameworks shape demand by mandating cardiovascular outcome trials for novel drug classes and restricting market access for devices lacking interoperability certification. Stakeholders must monitor evolving pharmacovigilance requirements and reimbursement criteria for automated insulin delivery systems as payer evidence thresholds tighten.
Market Dynamics
Hospital systems in the United States, Germany, and Japan are collapsing traditional glucose monitoring workflows through mandatory continuous glucose monitoring protocols that bypass manual point-of-care testing. This shift compresses reimbursement timelines and forces device interoperability certification as a baseline market entry requirement.
Growth Catalysts
- EMA cardiovascular outcome trial mandates:Novel SGLT2 inhibitors and GLP-1 receptor agonists must demonstrate heart failure and renal benefit endpoints, accelerating clinical differentiation for agents with positive data.
- Mail-order pharmacy fulfillment:Remote patient monitoring platforms integrate automated insulin delivery prescriptions with direct-to-home cold-chain logistics, bypassing traditional retail pharmacy bottlenecks.
- Japanese PMDA reimbursement expansion:METI-directed national health insurance now covers real-time continuous glucose monitors for Type 2 diabetes patients, opening volume pools previously restricted to Type 1 indications.
Market Restraints
- Biosimilar insulin lag:Cold-chain distribution complexity and immunogenicity surveillance requirements delay interchangeable biosimilar entry, preserving originator pricing power in basal analog segments.
- FDA pharmacovigilance tightening:Post-market safety reporting for novel antidiabetic agents now requires real-world evidence collection through mandated patient registries, elevating compliance costs for new market entrants.
- Interoperability certification gaps:Automated insulin delivery systems lacking IEEE 11073 or ISO 15197 standard compliance face restricted payer coverage in German statutory insurance frameworks.
Strategic Opportunities
- India's CDSCO fast-track pathway:The country's national pharmaceutical regulator accelerates review for indigenous continuous glucose monitor manufacturing, creating local production white space for cost-optimized sensors.
- Dual-hormone artificial pancreas convergence:Integration of glucagon-stable formulations with insulin pump algorithms enables closed-loop systems for hypoglycemia-unaware patient subsets.
- EU MDR notified body capacity expansion:CE marking backlog reduction under the Medical Device Regulation creates regulatory tailwind for automated insulin delivery submissions in Nordic markets.
Industry Challenges
- Digital therapeutics integration complexity:FDA Software as a Medical Device classification for algorithm-driven insulin dosing requires dual expertise in endocrinology clinical protocols and agile software validation workflows.
- GLP-1 manufacturing scale-up bottlenecks:Peptide synthesis capacity constraints and fill-finish automation shortages delay supply response to prescribing surges in North American obesity-expanded indications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hyperglycemia Treatment Market |
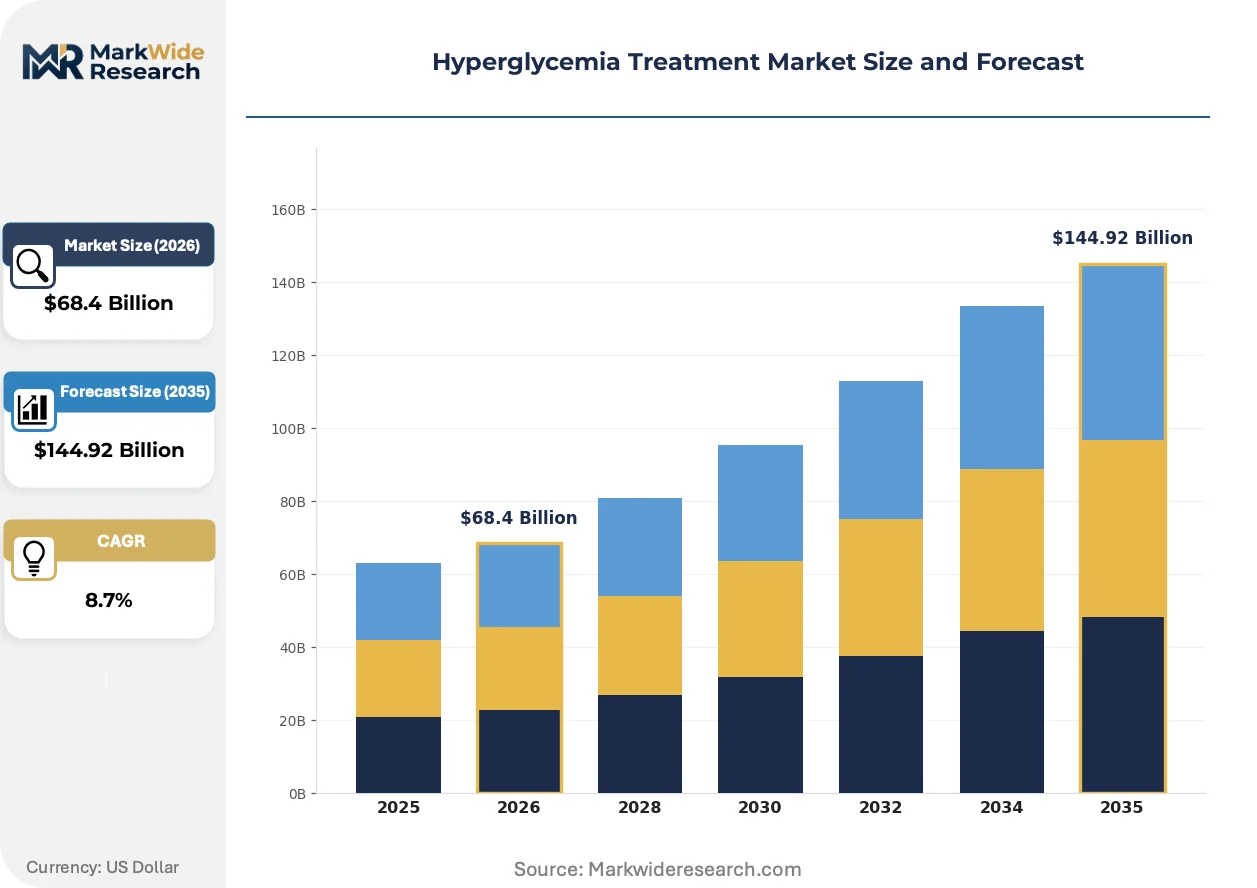
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $144.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin, Sulfonylureas, Metformin, DPP-4 Inhibitors End User: Hospitals, Clinics, Homecare, Long-term Care Facilities Delivery Mode: Injectable, Oral, Transdermal, Inhalable Application: Diabetes Management, Critical Care, Hospitalization, Outpatient Care |
| Companies Covered | Merck & Company Inc., Bristol-Myers Squibb Company, Novo Nordisk A/S, Medtronic plc, Teva Pharmaceutical Industries Ltd., Sanofi, AstraZeneca, Boehringer Ingelheim, Eli Lilly and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hyperglycemia Treatment Market Shifts & Advancements
Algorithm-driven insulin dosing is collapsing the traditional patient self-management model by embedding predictive glucose control into wearable hardware. This convergence of software and delivery mechanism redefines competitive advantage around data infrastructure rather than molecule patent life.
Factory-calibrated continuous glucose monitors eliminate fingerstick calibration requirements through novel fluoropolymer membrane chemistry. Endocrinology practices in the United States are adopting these systems at pace sufficient to compress traditional self-monitoring blood glucose device volumes. The technology is supplanting manual logging workflows in hospital discharge planning and retail pharmacy chronic care management programs.
EMA's tightened post-authorization safety study requirements for sodium-glucose cotransporter-2 inhibitors mandate renal and cardiovascular event tracking across diverse European populations. This regulatory friction elevates trial costs for follow-on molecules while advantaging incumbents with existing real-world evidence databases. German and French prescribing guidelines now incorporate these outcome data as formulary tiering criteria.
Subscription-based insulin delivery models bundle hardware, sensors, and algorithm updates into per-patient monthly fees. This unbundles traditional device purchase from consumable replenishment in United States employer-sponsored insurance channels. Large self-insured employers in Texas and California pilot these arrangements to cap diabetes-related medical cost trend.
Hyperglycemia Treatment Market Segmentation
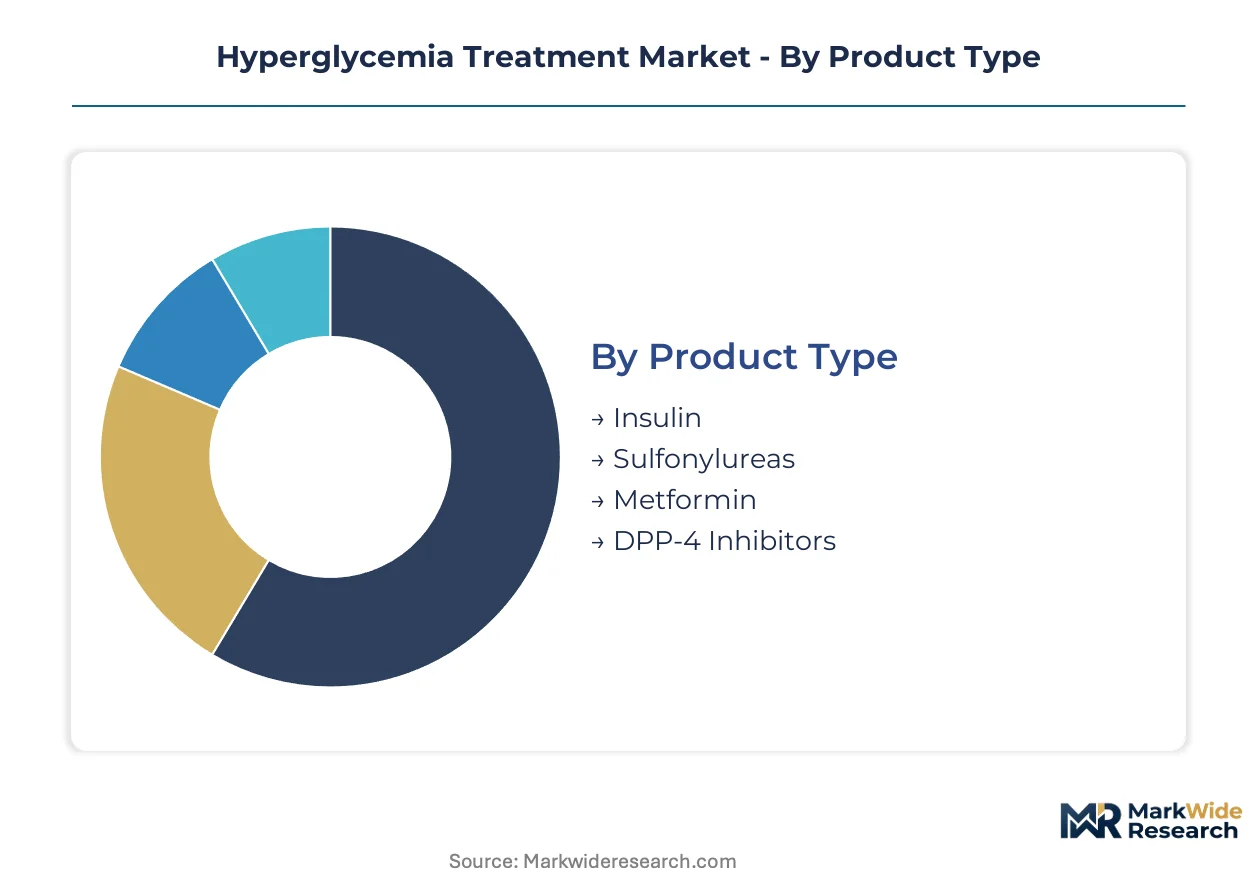
Hyperglycemia treatment segmentation reflects divergent reimbursement pathways and clinical settings that shape prescribing economics. Each dimension—molecule class, care site, delivery mechanism, and therapeutic use—carries distinct margin profiles and regulatory surveillance obligations.
Product Type:
EMA cardiovascular outcome mandates and FDA pharmacovigilance requirements create tiered compliance burdens across molecular classes, directly affecting market access timelines and post-market surveillance costs.
- Insulin:Recombinant human and analog formulations requiring cold-chain distribution and immunogenicity monitoring. Demand concentrates in United States hospital systems and German statutory insurance channels where automated insulin delivery reimbursement is deepening.
- Sulfonylureas:Oral insulin secretaries with established hypoglycemia risk profiles. Prescribing persists in India's CDSCO-regulated outpatient settings and Japanese community health centers where cost containment overrides cardiovascular outcome considerations.
- Metformin:First-line biguanide therapy dominating volume in outpatient diabetes management across all major markets.
- DPP-4 Inhibitors:Oral incretin enhancers with weight-neutral profiles preferred in polypharmacy elderly populations.
Established volume favors Metformin; emerging adoption favors Insulin.
End User:
Care site selection determines device interoperability requirements and reimbursement coding complexity, with homecare channels escaping hospital purchasing consortium price compression.
- Hospitals:Acute care settings with mandatory continuous glucose monitoring protocols and automated insulin delivery integration. United States health systems and German university hospitals lead capital deployment for closed-loop systems.
- Clinics:Outpatient endocrinology practices in Japan's PMDA reimbursement framework and United States Medicare Advantage networks where factory-calibrated sensors displace manual logging.
- Homecare:Remote patient monitoring with mail-order pharmacy fulfillment. This channel climbs the fastest as algorithm-driven dosing platforms bypass traditional retail pharmacy bottlenecks.
- Long-term Care Facilities:Skilled nursing settings with staff-mediated insulin administration and simplified glucose target protocols.
Capital intensity favors Hospitals; margin expansion favors Homecare.
Delivery Mode:
Route of administration governs manufacturing complexity, cold-chain infrastructure requirements, and biosimilar substitution vulnerability.
- Injectable:Insulin and GLP-1 receptor agonists delivered via pen devices or pumps. Cold-chain logistics barriers and peptide synthesis capacity constraints protect margin pools in North American and Nordic markets.
- Oral:Small-molecule agents including metformin, sulfonylureas, and DPP-4 inhibitors. Volume leadership persists in outpatient diabetes management across all geographies due to patient self-administration convenience.
- Transdermal:Patch-based delivery systems with limited commercial penetration pending adhesion reliability validation.
- Inhalable:Pulmonary insulin formulations constrained by pulmonary function testing requirements and restricted payer coverage.
Volume concentration favors Oral; technical differentiation favors Injectable.
Application:
Therapeutic use case determines clinical endpoint requirements, monitoring intensity, and episode-based reimbursement structures.
- Diabetes Management:Chronic glycemic control with HbA1c targets and complication prevention. Japanese PMDA reimbursement expansion for Type 2 continuous glucose monitors and United States employer-sponsored subscription models reshape chronic care economics.
- Critical Care:Intensive insulin protocols in surgical and medical ICUs. German statutory insurance frameworks and United States hospital systems mandate interoperable device certification for automated glycemic control.
- Hospitalization:Inpatient glucose management with sliding-scale or basal-bolus protocols.
- Outpatient Care:Community-based titration and monitoring with remote patient monitoring platform integration.
Reimbursement stability favors Diabetes Management; technology integration favors Critical Care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement consortia in the United States, Germany, and Japan concentrate demand for advanced insulin delivery systems and continuous glucose monitors. These buyers anchor volume for automated glycemic control technologies. Reimbursement depth and regulatory stringency vary sharply across national frameworks.
United States
Large self-insured employers in Texas and California pilot subscription-based insulin delivery models that bundle hardware, sensors, and algorithm updates. FDA pharmacovigilance tightening mandates real-world evidence collection through patient registries for novel antidiabetic agents. The Boston-Cambridge corridor hosts device interoperability certification clusters for closed-loop system development.
Germany
University hospitals in Bavaria and North Rhine-Westphalia deploy capital for interoperable automated insulin delivery systems. EMA cardiovascular outcome trial mandates for SGLT2 inhibitors and GLP-1 receptor agonists shape formulary tiering in statutory insurance frameworks. The Munich-Stuttgart axis concentrates manufacturing scale for factory-calibrated continuous glucose monitors.
Japan
METI-directed national health insurance expansion covers real-time continuous glucose monitors for Type 2 diabetes patients, opening volume pools previously restricted to Type 1 indications. PMDA reimbursement protocols accelerate adoption in Kanto region endocrinology practices. The Osaka-Kobe corridor anchors peptide synthesis capacity for GLP-1 receptor agonist manufacturing.
India
CDSCO fast-track pathways accelerate review for indigenous continuous glucose monitor manufacturing, creating local production white space for cost-optimized sensors. Outpatient diabetes management in Maharashtra and Gujarat sustains volume demand for oral metformin and sulfonylurea formulations. The Mumbai-Pune corridor concentrates contract research organization capacity for antidiabetic clinical trials.
Switzerland
Swissmedic certification requirements for automated insulin delivery systems attract device manufacturers seeking European market entry through regulatory excellence. Basel-Zurich corridor anchors pharmaceutical quality control infrastructure for insulin analog production. Geneva-based health technology assessment bodies influence EU-wide reimbursement criteria for dual-hormone artificial pancreas systems.
Hyperglycemia Treatment Market Competitive Landscape
Player mix skews toward integrated pharmaceutical-device conglomerates with cold-chain logistics capabilities and biosimilar defense positions. The structure concentrates around insulin and GLP-1 manufacturing scale, with secondary tiers of regional generic manufacturers and emerging sensor specialists. Three archetypes dominate: vertically integrated insulin-originators with pump partnerships, GLP-1 peptide synthesis specialists, and factory-calibrated sensor platform builders. Competitive moves center on manufacturing capacity expansion for peptide fill-finish automation and strategic device interoperability certification.
Among integrated pharmaceutical-originators, Novo Nordisk A/S, Eli Lilly and Company, and Sanofi occupy positions defined by insulin portfolio breadth and GLP-1 manufacturing scale. Novo Nordisk A/S represents the Nordic-anchored archetype with integrated insulin and incretin capabilities. Eli Lilly and Company exemplifies North American manufacturing scale in injectable and oral antidiabetic formulations. Sanofi anchors the European-originator position in basal insulin analog distribution across hospital and retail channels.
| Leading Market Players |
|---|
| Merck & Company Inc. |
| Bristol-Myers Squibb Company |
| Novo Nordisk A/S |
| Medtronic plc |
| Teva Pharmaceutical Industries Ltd. |
| Sanofi |
| AstraZeneca |
| Boehringer Ingelheim |
| Eli Lilly and Company |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements for insulin analogs lock in cold-chain logistics capacity and stabilize unit cost visibility for United States hospital systems and German statutory insurance purchasers. These contracts bundle peptide synthesis output with fill-finish automation slots, anchoring price predictability against GLP-1 manufacturing bottlenecks.
Pricing Analysis
Cost-plus contracts with API indexation govern insulin procurement for large United States health systems and Japanese PMDA-reimbursed clinics. Three-tier pricing structure across originator analogs, biosimilar equivalents, and human insulin formulations reflects immunogenicity surveillance burden and cold-chain certification grade. Pricing pressure stems from biosimilar lag in interchangeable basal segments, compressing margins in German outpatient channels. Price-sensitive buyers cluster in India's CDSCO-regulated retail pharmacy tier, while least-sensitive demand concentrates in United States employer-sponsored subscription bundles.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg port congestion elevate landed costs for Danish and Irish insulin fill-finish facilities serving European markets. Peptide synthesis capacity concentrates in Denmark, the United States, and Japan, drawing from recombinant DNA fermentation inputs, fluoropolymer sensor membranes, and glucagon-stable formulation excipients. Single-source vulnerability in GLP-1 receptor agonist fill-finish automation threatens supply continuity for North American obesity-expanded indications. Distribution runs through cold-chain logistics specialists with hospital direct-delivery contracts and mail-order pharmacy fulfillment platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Algorithm update subscriptions and sensor consumable replenishment generate recurring revenue expanding faster than insulin pump hardware sales in United States employer channels. Service-attach depth now determines lifetime customer value more than device placement volume.
For Market Incumbents: Consolidate peptide synthesis capacity in the Osaka-Kobe corridor and Bavaria to defend against GLP-1 manufacturing scale-up bottlenecks. Deepen backward integration into factory-calibrated sensor membrane chemistry to capture margin migrating from hardware to consumable attach rates. Lock hospital system purchasing consortia into multi-year algorithm licensing agreements before interoperability certification requirements harden in German statutory frameworks. For New Entrants and Emerging Players: Remote patient monitoring platform integration for Type 2 diabetes populations in Japan's Kanto region offers the most penetrable white space, as METI reimbursement expansion outpaces incumbent sensor supply response. Target CDSCO fast-track indigenous manufacturing in Maharashtra and Gujarat for cost-optimized continuous glucose monitors. Lead with direct-to-home cold-chain logistics partnerships rather than retail pharmacy channel contests. For Investors and Strategic Acquirers: Capital is best deployed toward dual-hormone artificial pancreas algorithm developers with FDA Software as a Medical Device clearance pathways and existing glucagon-stable formulation partnerships. Long-term viability hinges on five-to-ten-year reimbursement durability for closed-loop systems in United States Medicare Advantage and German statutory insurance. Watch Japanese PMDA expansion of continuous glucose monitor coverage to additional Type 2 subpopulations as the demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software as a Medical Device Submission | Algorithm-driven insulin dosing requires dual validation in endocrinology protocols and agile software workflows. |
| CE Marking Pathway under EU MDR | Notified body capacity expansion in Nordic markets accelerates automated insulin delivery system market entry. |
| Hospital System Partnership | United States health system consortia anchor volume for interoperable closed-loop glycemic control capital deployment. |
| Software Companion Development | Subscription-based algorithm updates bundle with sensor replenishment in Texas and California employer pilots. |
| Reimbursement Strategy | German statutory insurance tiering criteria now incorporate EMA cardiovascular outcome trial data for formulary placement. |
Research Methodology
A spread of perspectives from drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists converged on the working assumptions for insulin and GLP-1 demand trajectories. Primary interview findings combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up patient population modeling and top-down pharmaceutical revenue triangulation anchored volume and value estimates.
Segmentation dimensions modeled span molecule class, care site, delivery mechanism, and therapeutic application across the analysis window. Analytical framework projections reflect patient population epidemiology, reimbursement expansion patterns, and regulatory approval timelines. CAGRs derived from fitted growth curves applied to baseline prevalence data and adoption rate assumptions. Forecast inputs incorporated PMDA coverage expansion scenarios and CDSCO manufacturing pathway acceleration.
Underlying assumptions cover cardiovascular outcome trial success rates and biosimilar interchangeability designations, with deviation risk concentrated in FDA pharmacovigilance tightening and GLP-1 peptide synthesis capacity constraints. Practitioners should keep alternative scenarios live as METI reimbursement criteria and EU MDR notified body capacity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Global Type 1 Diabetes (T1D) Market
Diabetes Care
OTC Glucose Monitors Market
Diabetes Care
Russia Diabetes Care Devices Market
Diabetes Care
Mexico Diabetes Medication Market
Diabetes Care
Middle East and Africa Continuous Glucose Monitoring Market
Diabetes Care
Diabetes Injection Pens Market
Diabetes Care
Global Continuous Glucose Monitoring Systems Market
Diabetes Care
South Africa Continuous Glucose Monitoring Market
Diabetes Care
Global Type 2 Diabetes Treatment Market
Diabetes Care
Insulin Resistance Market
Diabetes Care
Global Smart Diabetes Management Market
Diabetes Care
Diabetes Care Devices and Drugs Market
Diabetes Care
South Korea Oral Anti-Diabetic Drug Market
Diabetes Care
Brazil Blood Glucose Monitoring Market
Diabetes Care
Internet of Things for Diabetes Market
Diabetes Care
Japan Oral Anti-Diabetic Drug Market